

#tradfi
tradfi
2M views
18,694 Discussing
Hot
Latest
·
--
🚨 INSTITUTIONAL LIQUIDITY SHIFTS AS TOP-TIER PLATFORMS INTEGRATE TRADFI BEYOND $BTC ! 💥
Institutional order flow is no longer confined to isolated crypto order books. Top-tier platforms are orchestrating a massive structural shift, unifying digital assets with traditional forex, gold, and equity derivatives into a single execution layer. 🏦
This multi-asset convergence signals smart money preparing for seamless cross-market capital rotation. 📊 As automated AI execution and tokenized real-world assets merge under one roof, market efficiency increases and structural liquidity footprints across traditional and digital venues become deeply interconnected. 🔍
Smart money builds infrastructure ahead of retail demand, positioning for total financial integration. 💡 Will unified multi-asset access accelerate the next major liquidity expansion for $BTC , or will capital split across asset classes? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #TradFi #RWA #Macro #Crypto
🎯 🦈
🚨 INSTITUTIONAL LIQUIDITY SHIFTS AS TOP-TIER PLATFORMS INTEGRATE TRADFI BEYOND $BTC ! 💥
Institutional order flow is no longer confined to isolated crypto order books. Top-tier platforms are orchestrating a massive structural shift, unifying digital assets with traditional forex, gold, and equity derivatives into a single execution layer. 🏦
This multi-asset convergence signals smart money preparing for seamless cross-market capital rotation. 📊 As automated AI execution and tokenized real-world assets merge under one roof, market efficiency increases and structural liquidity footprints across traditional and digital venues become deeply interconnected. 🔍
Smart money builds infrastructure ahead of retail demand, positioning for total financial integration. 💡 Will unified multi-asset access accelerate the next major liquidity expansion for $BTC , or will capital split across asset classes? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #TradFi #RWA #Macro #Crypto
🎯 🦈
Institutional order flow is no longer confined to isolated crypto order books. Top-tier platforms are orchestrating a massive structural shift, unifying digital assets with traditional forex, gold, and equity derivatives into a single execution layer. 🏦
This multi-asset convergence signals smart money preparing for seamless cross-market capital rotation. 📊 As automated AI execution and tokenized real-world assets merge under one roof, market efficiency increases and structural liquidity footprints across traditional and digital venues become deeply interconnected. 🔍
Smart money builds infrastructure ahead of retail demand, positioning for total financial integration. 💡 Will unified multi-asset access accelerate the next major liquidity expansion for $BTC , or will capital split across asset classes? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #TradFi #RWA #Macro #Crypto
🎯 🦈
8
🚀🚀🚀 TradFi Focus 🚀🚀🚀
Spot shares represent ownership, while TradFi perpetuals provide leveraged price exposure without ownership. Funding and liquidation make their risk profile very different.
$TSLA $NVDA $MSTR
#TradFi #RWA #StockMarket #TokenizedStocks #BinanceFutures
🚀🚀🚀 TradFi Focus 🚀🚀🚀
Spot shares represent ownership, while TradFi perpetuals provide leveraged price exposure without ownership. Funding and liquidation make their risk profile very different.
$TSLA $NVDA $MSTR
#TradFi #RWA #StockMarket #TokenizedStocks #BinanceFutures
Spot shares represent ownership, while TradFi perpetuals provide leveraged price exposure without ownership. Funding and liquidation make their risk profile very different.
$TSLA $NVDA $MSTR
#TradFi #RWA #StockMarket #TokenizedStocks #BinanceFutures
159

·
--
Verified
📉 Slight Pullback Across US Markets & Tech Stocks
US equity markets experienced a slight dip during recent trading sessions, with major indices and megacap stocks recording modest declines:
🔻 Dow Jones Industrial Average: Down ~0.6%
🔻 S&P 500: Down ~0.7%
🔻 Apple (AAPL): Down ~0.9%
Market participants remain cautious as they evaluate economic indicators and macroeconomic shifts. 📊
$SPYX.ETF $SPSK.ETF $AAPL.US
#TradFi #USStockMarket #CPIWatch .
📉 Slight Pullback Across US Markets & Tech Stocks
US equity markets experienced a slight dip during recent trading sessions, with major indices and megacap stocks recording modest declines:
🔻 Dow Jones Industrial Average: Down ~0.6%
🔻 S&P 500: Down ~0.7%
🔻 Apple (AAPL): Down ~0.9%
Market participants remain cautious as they evaluate economic indicators and macroeconomic shifts. 📊
$SPYX.ETF $SPSK.ETF $AAPL.US
#TradFi #USStockMarket #CPIWatch .
US equity markets experienced a slight dip during recent trading sessions, with major indices and megacap stocks recording modest declines:
🔻 Dow Jones Industrial Average: Down ~0.6%
🔻 S&P 500: Down ~0.7%
🔻 Apple (AAPL): Down ~0.9%
Market participants remain cautious as they evaluate economic indicators and macroeconomic shifts. 📊
$SPYX.ETF $SPSK.ETF $AAPL.US
#TradFi #USStockMarket #CPIWatch .
AAPLUS-0.15%
1
201
·
--
Crypto, TradFi, DeFi.
3 financial worlds — but why do we still treat them as completely separate? 👀
Think about it:
🪙 Crypto — digital assets like Bitcoin.
📈 TradFi — traditional markets and assets such as stocks and commodities.
🔗 DeFi — financial applications built on blockchain-based infrastructure.
And this is where TriFi comes in.
The idea is simple:
Crypto ↔️ TradFi ↔️ DeFi
Instead of looking at these as isolated worlds, TriFi is about how they can become increasingly connected within one financial ecosystem.
That’s also part of the idea behind the Super Financial App concept: bringing access to different financial products and markets into one ecosystem, where available.
Of course, availability isn’t the same for everyone — products and services can vary depending on your country of residence and eligibility.
If you had one app connecting all three worlds, which one would you explore first? 👀
🪙 Crypto
📈 TradFi
🔗 DeFi
Educational content only. Not financial advice.
Product availability varies by region and eligibility. Always DYOR.
#Binance #TradFi #crypto #Blockchain
Crypto, TradFi, DeFi.
3 financial worlds — but why do we still treat them as completely separate? 👀
Think about it:
🪙 Crypto — digital assets like Bitcoin.
📈 TradFi — traditional markets and assets such as stocks and commodities.
🔗 DeFi — financial applications built on blockchain-based infrastructure.
And this is where TriFi comes in.
The idea is simple:
Crypto ↔️ TradFi ↔️ DeFi
Instead of looking at these as isolated worlds, TriFi is about how they can become increasingly connected within one financial ecosystem.
That’s also part of the idea behind the Super Financial App concept: bringing access to different financial products and markets into one ecosystem, where available.
Of course, availability isn’t the same for everyone — products and services can vary depending on your country of residence and eligibility.
If you had one app connecting all three worlds, which one would you explore first? 👀
🪙 Crypto
📈 TradFi
🔗 DeFi
Educational content only. Not financial advice.
Product availability varies by region and eligibility. Always DYOR.
#Binance #TradFi #crypto #Blockchain
3 financial worlds — but why do we still treat them as completely separate? 👀
Think about it:
🪙 Crypto — digital assets like Bitcoin.
📈 TradFi — traditional markets and assets such as stocks and commodities.
🔗 DeFi — financial applications built on blockchain-based infrastructure.
And this is where TriFi comes in.
The idea is simple:
Crypto ↔️ TradFi ↔️ DeFi
Instead of looking at these as isolated worlds, TriFi is about how they can become increasingly connected within one financial ecosystem.
That’s also part of the idea behind the Super Financial App concept: bringing access to different financial products and markets into one ecosystem, where available.
Of course, availability isn’t the same for everyone — products and services can vary depending on your country of residence and eligibility.
If you had one app connecting all three worlds, which one would you explore first? 👀
🪙 Crypto
📈 TradFi
🔗 DeFi
Educational content only. Not financial advice.
Product availability varies by region and eligibility. Always DYOR.
#Binance #TradFi #crypto #Blockchain
1
53
·
--
🚨 UNINTENDED TRADFI LEAK REVEALS INSTITUTIONAL FLOWS AS $BTC ASSESSES SYSTEMIC EXPOSURE 🔍
A major Morgan Stanley internal document breach has exposed over 100 confidential investment banking deal structures across global markets. 🏦 Smart money desks closely track these private deal flows, as sudden operational oversights in high-tier investment banking often signal broader institutional friction. 🔍
When institutional underwriters leak sensitive valuation pricing, market makers adjust their risk exposure across cross-asset derivatives. 📊 As capital allocation strategies shift in response, order flow imbalances can easily spill over into liquid macro assets like $BTC . ⚡
💬 Do you expect institutional deal disclosures to trigger volatility across crypto liquidity pools, or is this just noise? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #TradFi #Institutional #Macro #OrderFlow
🎯 🦈
🚨 UNINTENDED TRADFI LEAK REVEALS INSTITUTIONAL FLOWS AS $BTC ASSESSES SYSTEMIC EXPOSURE 🔍
A major Morgan Stanley internal document breach has exposed over 100 confidential investment banking deal structures across global markets. 🏦 Smart money desks closely track these private deal flows, as sudden operational oversights in high-tier investment banking often signal broader institutional friction. 🔍
When institutional underwriters leak sensitive valuation pricing, market makers adjust their risk exposure across cross-asset derivatives. 📊 As capital allocation strategies shift in response, order flow imbalances can easily spill over into liquid macro assets like $BTC . ⚡
💬 Do you expect institutional deal disclosures to trigger volatility across crypto liquidity pools, or is this just noise? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #TradFi #Institutional #Macro #OrderFlow
🎯 🦈
A major Morgan Stanley internal document breach has exposed over 100 confidential investment banking deal structures across global markets. 🏦 Smart money desks closely track these private deal flows, as sudden operational oversights in high-tier investment banking often signal broader institutional friction. 🔍
When institutional underwriters leak sensitive valuation pricing, market makers adjust their risk exposure across cross-asset derivatives. 📊 As capital allocation strategies shift in response, order flow imbalances can easily spill over into liquid macro assets like $BTC . ⚡
💬 Do you expect institutional deal disclosures to trigger volatility across crypto liquidity pools, or is this just noise? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #TradFi #Institutional #Macro #OrderFlow
🎯 🦈
38
·
--
Verified
Article
Inside Re’s Reinsurance StrategySo how is Re’s insurance strategy structured to keep that yield flowing? What goes into deciding which opportunities depositor capital will back?
Re’s value equation is fairly simple: depositors either provide capital and mint assets (reUSD or reUSDe) or acquire those assets on the secondary market. Those assets earn yield: for reUSD, a blended yield of SOFR and the seven-day trailing average of the sUSDe yield rate, plus a protocol-determined spread; for reUSDe, SOFR plus a protocol-determined spread.
That spread (2.5% for reUSD and 8.5% for reUSDe, as of August 2026) is provided by Re’s yield source: real reinsurance activity. Depositor capital provides collateral with which Cover Re, Re’s licensed reinsurance partner, signs new reinsurance contracts. The yield from those contracts flows back to Re, and thence to holders of reUSD and reUSDe.
Returning that yield depends, of course, upon the performance of those contracts. So how is Re’s insurance strategy structured to keep that yield flowing? What goes into deciding which opportunities depositor capital will back? Let’s explore.
How Reinsurance Works
From a financial perspective, reinsurance is simple: primary insurers (those who sell insurance directly to customers) pass on a portion of the risk they’re taking on to reinsurers. They do so for multiple reasons [1]: to smooth out earnings, to protect themselves from extreme outcomes, and to provide themselves with capital relief.
Insurers charge premiums to customers; in exchange for taking on that portion of risk, a reinsurer will inherit some of those premiums. Provided that those premiums exceed the costs incurred on the policy (payouts plus business expenses), the reinsurer will walk away with a profit.
Whether or not that happens depends in substantial part on a reinsurer’s strategy. And a substantial portion of reinsurer strategy is choosing its mix of risk.
Choose Your Risk
Reinsurance risk profiles exist across a spectrum between two poles: everyday stuff on one end, and catastrophes on the other.
Everyday losses cover events like car accidents, workers’ compensation, damage to a home, and so on. Across a given policy, such occurrences can be expected to happen frequently, but the claims are relatively small, they carry little or no correlation with each other (for example, a single car crash typically won’t generate a rash of other car crashes), and decades of loss data make them relatively predictable. Lower magnitude of risk often means lower premiums for the reinsurer, but it also means more predictable and more consistent results.
Catastrophe losses cover events like hurricanes, earthquakes, or wildfires, and they behave in a near-opposite way. Whereas everyday losses may happen every day (it’s in the name!), catastrophes happen rarely. But when they happen, losses are huge, and they’re inherently concentrated: the same event hits large geographical areas all at once. The premiums to be earned are greater than those from safer policies, but the results are more volatile, and the worst-case outcome is far worse.
Every reinsurance contract a reinsurer writes is a calculated bet. The closer the contract sits to the catastrophe end of the spectrum, the less safe the bet, and a bet on a catastrophe policy can land a stiff fiscal punch on a reinsurer if the covered event comes.
Indeed, the direction of the entire reinsurance market - how much reinsurance capacity is available, how much reinsurers charge, and the supply-demand balance - can reverse itself based on a single bad catastrophe year.
The Importance of Diversification
Reinsurers rarely hold only a single reinsurance contract at a given time. They almost invariably bundle together numerous contracts into their overall portfolio. A critical subcategory of the aforementioned risk profiles, when applied across a reinsurer’s overall portfolio, is diversification.
The diversification of a given portfolio answers a simple question: if a given event hits, what degree of impact will it have on the portfolio as a whole?
Take everyday losses, for example. These tend to be small in magnitude. A reinsurer can write a lot of them, and it can vary them: by line of business, and by geography. A given US reinsurer could (and often does) write contracts across any number of insurance categories in dozens of states.
The benefit of doing so: losses will rarely be correlated with each other. An extreme winter that causes an unusually bad auto insurance year in Maine won’t impact auto insurance losses in California, and it won’t correlate with workers’ compensation losses anywhere. If a reinsurer were to have concentrated heavily on auto policies in Maine, however, then that one bad winter would have had a much greater impact upon its portfolio (and balance sheet) as a whole. Risks are less concentrated.
Catastrophe losses are, again, the opposite. They’re inherently concentrated. Hurricane policies, for example, will cover large areas. If an area gets hit, that means a great deal of losses at the same time. Geographic diversification offers less protection; bad hurricane seasons often impact vast areas of hurricane-prone coastline (say, the US eastern seaboard), and a dry summer can increase the fire risk across wide swathes of territory.
And because catastrophe policies come with an inherently high ceiling on losses, each constitutes a larger slice of the portfolio pie. A single catastrophe may have a major impact upon a reinsurer’s financial big picture.
Re’s Strategy
Re’s goal is to deliver consistent yield to its holders. That means pursuing a strategy which prioritizes steadier, lower-volatility returns and consistent results: a focus upon low-volatility, everyday policies, diversified across a range of business lines and a wide geographical area, with minimal exposure to catastrophe risk.
Re’s portfolio has been consistently spread across five different categories of business: homeowners, commercial auto, small business, workers’ compensation, and personal auto. All are distinct from one another; unexpectedly high losses in any one are unlikely to correlate with high losses in any other. And these policies are spread across nearly every US state, reducing the likelihood a single loss event in any one, or two, or five locations will have an outsized impact upon the overall portfolio.
That’s the goal of building the book this way. Because no single event can swing the portfolio, results are more predictable and don’t lurch from year to year. The payoff of that strategy has been clear: profitability in every year of the protocol’s operation, and consistent yield delivered to holders as a result.1
Full details on Re’s portfolio and strategy can always be found on the Re App [2].
1 As of August 2026. Past performance is not a reliable indicator of future results.
Originally published on re.xyz: https://re.xyz/insights/inside-res-reinsurance-strategy
Consistent yield, by design.
Re’s strategy prioritizes steadier, lower-volatility returns - diversified across business lines and geography, with minimal exposure to catastrophe risk.
Explore Re: https://re.xyz
#reinsurance #RWA #TradFi
Sources
https://blog.re.xyz/why-insurers-buy-reinsurancehttps://app.re.xyz/capital-strategy
Disclosures: This blog post is for informational and educational purposes only and does not constitute investment, legal, tax, or financial advice. Nothing in this article should be construed as an offer or solicitation to buy or sell any security, token, or financial product.Affiliate disclosure. The "re" brand, the re protocol, and re.xyz are operated by Resilience Foundation Cayman LLC ("Resilience Foundation"), an Exempted Limited Guarantee Foundation Company incorporated in the Cayman Islands with Limited Liability with registered number IC-414560, together with its affiliate Resilience (BVI) Ltd and Resilience Inv SPC. Resilience Foundation, Resilience BVI, and Resilience Inv do not provide insurance or reinsurance services, do not act as insurance broker or agent, and do not hold an insurance license. All regulated reinsurance activities are conducted exclusively by Cover Reinsurance SPC Ltd. ("Cover Re SPC"), a Class B(iii) licensed exempted segregated portfolio company in the Cayman Islands, operating under the "Cover Re" brand at coverre.com.Access and eligibility. reUSD and reUSDe are not registered or qualified for public offer or sale in the United States or to U.S. persons, and are offered only in reliance on exemptions from registration, including under Regulation S. Access may be restricted based on jurisdiction, and prospective holders are responsible for determining whether they are eligible to acquire or hold these assets under applicable law.Yield. Any yield generated by reUSD/reUSDe is variable, is not guaranteed, and depends on the performance of underlying reinsurance and other strategies. Yield may fluctuate significantly, may be reduced to zero, and past yield is not indicative of future results.Risk disclosure. Digital assets and blockchain-based products involve significant risk, including the potential loss of principal, smart contract vulnerabilities, liquidity constraints, and regulatory uncertainty. Any references to APR, returns, or performance are not guaranteed, and past performance is not a reliable indicator of future results.Regulatory environment. The regulatory environment for digital assets, stablecoins, tokenized real-world assets, and onchain financial products is dynamic and continues to evolve across jurisdictions. The information in this post reflects the understanding as of the date of publication and may not reflect subsequent legal or regulatory developments. Readers should consult qualified legal, tax, and financial professionals before making any decisions.Terms apply. For full terms, disclosures, and risk disclaimers, please see the Re website at https://re.xyz, Terms of Service (https://re.xyz/terms), and Disclaimers (https://docs.re.xyz/disclaimers).
Inside Re’s Reinsurance Strategy
So how is Re’s insurance strategy structured to keep that yield flowing? What goes into deciding which opportunities depositor capital will back?
Re’s value equation is fairly simple: depositors either provide capital and mint assets (reUSD or reUSDe) or acquire those assets on the secondary market. Those assets earn yield: for reUSD, a blended yield of SOFR and the seven-day trailing average of the sUSDe yield rate, plus a protocol-determined spread; for reUSDe, SOFR plus a protocol-determined spread.
That spread (2.5% for reUSD and 8.5% for reUSDe, as of August 2026) is provided by Re’s yield source: real reinsurance activity. Depositor capital provides collateral with which Cover Re, Re’s licensed reinsurance partner, signs new reinsurance contracts. The yield from those contracts flows back to Re, and thence to holders of reUSD and reUSDe.
Returning that yield depends, of course, upon the performance of those contracts. So how is Re’s insurance strategy structured to keep that yield flowing? What goes into deciding which opportunities depositor capital will back? Let’s explore.
How Reinsurance Works
From a financial perspective, reinsurance is simple: primary insurers (those who sell insurance directly to customers) pass on a portion of the risk they’re taking on to reinsurers. They do so for multiple reasons [1]: to smooth out earnings, to protect themselves from extreme outcomes, and to provide themselves with capital relief.
Insurers charge premiums to customers; in exchange for taking on that portion of risk, a reinsurer will inherit some of those premiums. Provided that those premiums exceed the costs incurred on the policy (payouts plus business expenses), the reinsurer will walk away with a profit.
Whether or not that happens depends in substantial part on a reinsurer’s strategy. And a substantial portion of reinsurer strategy is choosing its mix of risk.
Choose Your Risk
Reinsurance risk profiles exist across a spectrum between two poles: everyday stuff on one end, and catastrophes on the other.
Everyday losses cover events like car accidents, workers’ compensation, damage to a home, and so on. Across a given policy, such occurrences can be expected to happen frequently, but the claims are relatively small, they carry little or no correlation with each other (for example, a single car crash typically won’t generate a rash of other car crashes), and decades of loss data make them relatively predictable. Lower magnitude of risk often means lower premiums for the reinsurer, but it also means more predictable and more consistent results.
Catastrophe losses cover events like hurricanes, earthquakes, or wildfires, and they behave in a near-opposite way. Whereas everyday losses may happen every day (it’s in the name!), catastrophes happen rarely. But when they happen, losses are huge, and they’re inherently concentrated: the same event hits large geographical areas all at once. The premiums to be earned are greater than those from safer policies, but the results are more volatile, and the worst-case outcome is far worse.
Every reinsurance contract a reinsurer writes is a calculated bet. The closer the contract sits to the catastrophe end of the spectrum, the less safe the bet, and a bet on a catastrophe policy can land a stiff fiscal punch on a reinsurer if the covered event comes.
Indeed, the direction of the entire reinsurance market - how much reinsurance capacity is available, how much reinsurers charge, and the supply-demand balance - can reverse itself based on a single bad catastrophe year.
The Importance of Diversification
Reinsurers rarely hold only a single reinsurance contract at a given time. They almost invariably bundle together numerous contracts into their overall portfolio. A critical subcategory of the aforementioned risk profiles, when applied across a reinsurer’s overall portfolio, is diversification.
The diversification of a given portfolio answers a simple question: if a given event hits, what degree of impact will it have on the portfolio as a whole?
Take everyday losses, for example. These tend to be small in magnitude. A reinsurer can write a lot of them, and it can vary them: by line of business, and by geography. A given US reinsurer could (and often does) write contracts across any number of insurance categories in dozens of states.
The benefit of doing so: losses will rarely be correlated with each other. An extreme winter that causes an unusually bad auto insurance year in Maine won’t impact auto insurance losses in California, and it won’t correlate with workers’ compensation losses anywhere. If a reinsurer were to have concentrated heavily on auto policies in Maine, however, then that one bad winter would have had a much greater impact upon its portfolio (and balance sheet) as a whole. Risks are less concentrated.
Catastrophe losses are, again, the opposite. They’re inherently concentrated. Hurricane policies, for example, will cover large areas. If an area gets hit, that means a great deal of losses at the same time. Geographic diversification offers less protection; bad hurricane seasons often impact vast areas of hurricane-prone coastline (say, the US eastern seaboard), and a dry summer can increase the fire risk across wide swathes of territory.
And because catastrophe policies come with an inherently high ceiling on losses, each constitutes a larger slice of the portfolio pie. A single catastrophe may have a major impact upon a reinsurer’s financial big picture.
Re’s Strategy
Re’s goal is to deliver consistent yield to its holders. That means pursuing a strategy which prioritizes steadier, lower-volatility returns and consistent results: a focus upon low-volatility, everyday policies, diversified across a range of business lines and a wide geographical area, with minimal exposure to catastrophe risk.
Re’s portfolio has been consistently spread across five different categories of business: homeowners, commercial auto, small business, workers’ compensation, and personal auto. All are distinct from one another; unexpectedly high losses in any one are unlikely to correlate with high losses in any other. And these policies are spread across nearly every US state, reducing the likelihood a single loss event in any one, or two, or five locations will have an outsized impact upon the overall portfolio.
That’s the goal of building the book this way. Because no single event can swing the portfolio, results are more predictable and don’t lurch from year to year. The payoff of that strategy has been clear: profitability in every year of the protocol’s operation, and consistent yield delivered to holders as a result.1
Full details on Re’s portfolio and strategy can always be found on the Re App [2].
1 As of August 2026. Past performance is not a reliable indicator of future results.
Originally published on re.xyz: https://re.xyz/insights/inside-res-reinsurance-strategy
Consistent yield, by design.
Re’s strategy prioritizes steadier, lower-volatility returns - diversified across business lines and geography, with minimal exposure to catastrophe risk.
Explore Re: https://re.xyz
#reinsurance #RWA #TradFi
Sources
https://blog.re.xyz/why-insurers-buy-reinsurancehttps://app.re.xyz/capital-strategy
Disclosures: This blog post is for informational and educational purposes only and does not constitute investment, legal, tax, or financial advice. Nothing in this article should be construed as an offer or solicitation to buy or sell any security, token, or financial product.Affiliate disclosure. The "re" brand, the re protocol, and re.xyz are operated by Resilience Foundation Cayman LLC ("Resilience Foundation"), an Exempted Limited Guarantee Foundation Company incorporated in the Cayman Islands with Limited Liability with registered number IC-414560, together with its affiliate Resilience (BVI) Ltd and Resilience Inv SPC. Resilience Foundation, Resilience BVI, and Resilience Inv do not provide insurance or reinsurance services, do not act as insurance broker or agent, and do not hold an insurance license. All regulated reinsurance activities are conducted exclusively by Cover Reinsurance SPC Ltd. ("Cover Re SPC"), a Class B(iii) licensed exempted segregated portfolio company in the Cayman Islands, operating under the "Cover Re" brand at coverre.com.Access and eligibility. reUSD and reUSDe are not registered or qualified for public offer or sale in the United States or to U.S. persons, and are offered only in reliance on exemptions from registration, including under Regulation S. Access may be restricted based on jurisdiction, and prospective holders are responsible for determining whether they are eligible to acquire or hold these assets under applicable law.Yield. Any yield generated by reUSD/reUSDe is variable, is not guaranteed, and depends on the performance of underlying reinsurance and other strategies. Yield may fluctuate significantly, may be reduced to zero, and past yield is not indicative of future results.Risk disclosure. Digital assets and blockchain-based products involve significant risk, including the potential loss of principal, smart contract vulnerabilities, liquidity constraints, and regulatory uncertainty. Any references to APR, returns, or performance are not guaranteed, and past performance is not a reliable indicator of future results.Regulatory environment. The regulatory environment for digital assets, stablecoins, tokenized real-world assets, and onchain financial products is dynamic and continues to evolve across jurisdictions. The information in this post reflects the understanding as of the date of publication and may not reflect subsequent legal or regulatory developments. Readers should consult qualified legal, tax, and financial professionals before making any decisions.Terms apply. For full terms, disclosures, and risk disclaimers, please see the Re website at https://re.xyz, Terms of Service (https://re.xyz/terms), and Disclaimers (https://docs.re.xyz/disclaimers).
Re’s value equation is fairly simple: depositors either provide capital and mint assets (reUSD or reUSDe) or acquire those assets on the secondary market. Those assets earn yield: for reUSD, a blended yield of SOFR and the seven-day trailing average of the sUSDe yield rate, plus a protocol-determined spread; for reUSDe, SOFR plus a protocol-determined spread.
That spread (2.5% for reUSD and 8.5% for reUSDe, as of August 2026) is provided by Re’s yield source: real reinsurance activity. Depositor capital provides collateral with which Cover Re, Re’s licensed reinsurance partner, signs new reinsurance contracts. The yield from those contracts flows back to Re, and thence to holders of reUSD and reUSDe.
Returning that yield depends, of course, upon the performance of those contracts. So how is Re’s insurance strategy structured to keep that yield flowing? What goes into deciding which opportunities depositor capital will back? Let’s explore.
How Reinsurance Works
From a financial perspective, reinsurance is simple: primary insurers (those who sell insurance directly to customers) pass on a portion of the risk they’re taking on to reinsurers. They do so for multiple reasons [1]: to smooth out earnings, to protect themselves from extreme outcomes, and to provide themselves with capital relief.
Insurers charge premiums to customers; in exchange for taking on that portion of risk, a reinsurer will inherit some of those premiums. Provided that those premiums exceed the costs incurred on the policy (payouts plus business expenses), the reinsurer will walk away with a profit.
Whether or not that happens depends in substantial part on a reinsurer’s strategy. And a substantial portion of reinsurer strategy is choosing its mix of risk.
Choose Your Risk
Reinsurance risk profiles exist across a spectrum between two poles: everyday stuff on one end, and catastrophes on the other.
Everyday losses cover events like car accidents, workers’ compensation, damage to a home, and so on. Across a given policy, such occurrences can be expected to happen frequently, but the claims are relatively small, they carry little or no correlation with each other (for example, a single car crash typically won’t generate a rash of other car crashes), and decades of loss data make them relatively predictable. Lower magnitude of risk often means lower premiums for the reinsurer, but it also means more predictable and more consistent results.
Catastrophe losses cover events like hurricanes, earthquakes, or wildfires, and they behave in a near-opposite way. Whereas everyday losses may happen every day (it’s in the name!), catastrophes happen rarely. But when they happen, losses are huge, and they’re inherently concentrated: the same event hits large geographical areas all at once. The premiums to be earned are greater than those from safer policies, but the results are more volatile, and the worst-case outcome is far worse.
Every reinsurance contract a reinsurer writes is a calculated bet. The closer the contract sits to the catastrophe end of the spectrum, the less safe the bet, and a bet on a catastrophe policy can land a stiff fiscal punch on a reinsurer if the covered event comes.
Indeed, the direction of the entire reinsurance market - how much reinsurance capacity is available, how much reinsurers charge, and the supply-demand balance - can reverse itself based on a single bad catastrophe year.
The Importance of Diversification
Reinsurers rarely hold only a single reinsurance contract at a given time. They almost invariably bundle together numerous contracts into their overall portfolio. A critical subcategory of the aforementioned risk profiles, when applied across a reinsurer’s overall portfolio, is diversification.
The diversification of a given portfolio answers a simple question: if a given event hits, what degree of impact will it have on the portfolio as a whole?
Take everyday losses, for example. These tend to be small in magnitude. A reinsurer can write a lot of them, and it can vary them: by line of business, and by geography. A given US reinsurer could (and often does) write contracts across any number of insurance categories in dozens of states.
The benefit of doing so: losses will rarely be correlated with each other. An extreme winter that causes an unusually bad auto insurance year in Maine won’t impact auto insurance losses in California, and it won’t correlate with workers’ compensation losses anywhere. If a reinsurer were to have concentrated heavily on auto policies in Maine, however, then that one bad winter would have had a much greater impact upon its portfolio (and balance sheet) as a whole. Risks are less concentrated.
Catastrophe losses are, again, the opposite. They’re inherently concentrated. Hurricane policies, for example, will cover large areas. If an area gets hit, that means a great deal of losses at the same time. Geographic diversification offers less protection; bad hurricane seasons often impact vast areas of hurricane-prone coastline (say, the US eastern seaboard), and a dry summer can increase the fire risk across wide swathes of territory.
And because catastrophe policies come with an inherently high ceiling on losses, each constitutes a larger slice of the portfolio pie. A single catastrophe may have a major impact upon a reinsurer’s financial big picture.
Re’s Strategy
Re’s goal is to deliver consistent yield to its holders. That means pursuing a strategy which prioritizes steadier, lower-volatility returns and consistent results: a focus upon low-volatility, everyday policies, diversified across a range of business lines and a wide geographical area, with minimal exposure to catastrophe risk.
Re’s portfolio has been consistently spread across five different categories of business: homeowners, commercial auto, small business, workers’ compensation, and personal auto. All are distinct from one another; unexpectedly high losses in any one are unlikely to correlate with high losses in any other. And these policies are spread across nearly every US state, reducing the likelihood a single loss event in any one, or two, or five locations will have an outsized impact upon the overall portfolio.
That’s the goal of building the book this way. Because no single event can swing the portfolio, results are more predictable and don’t lurch from year to year. The payoff of that strategy has been clear: profitability in every year of the protocol’s operation, and consistent yield delivered to holders as a result.1
Full details on Re’s portfolio and strategy can always be found on the Re App [2].
1 As of August 2026. Past performance is not a reliable indicator of future results.
Originally published on re.xyz: https://re.xyz/insights/inside-res-reinsurance-strategy
Consistent yield, by design.
Re’s strategy prioritizes steadier, lower-volatility returns - diversified across business lines and geography, with minimal exposure to catastrophe risk.
Explore Re: https://re.xyz
#reinsurance #RWA #TradFi
Sources
https://blog.re.xyz/why-insurers-buy-reinsurancehttps://app.re.xyz/capital-strategy
Disclosures: This blog post is for informational and educational purposes only and does not constitute investment, legal, tax, or financial advice. Nothing in this article should be construed as an offer or solicitation to buy or sell any security, token, or financial product.Affiliate disclosure. The "re" brand, the re protocol, and re.xyz are operated by Resilience Foundation Cayman LLC ("Resilience Foundation"), an Exempted Limited Guarantee Foundation Company incorporated in the Cayman Islands with Limited Liability with registered number IC-414560, together with its affiliate Resilience (BVI) Ltd and Resilience Inv SPC. Resilience Foundation, Resilience BVI, and Resilience Inv do not provide insurance or reinsurance services, do not act as insurance broker or agent, and do not hold an insurance license. All regulated reinsurance activities are conducted exclusively by Cover Reinsurance SPC Ltd. ("Cover Re SPC"), a Class B(iii) licensed exempted segregated portfolio company in the Cayman Islands, operating under the "Cover Re" brand at coverre.com.Access and eligibility. reUSD and reUSDe are not registered or qualified for public offer or sale in the United States or to U.S. persons, and are offered only in reliance on exemptions from registration, including under Regulation S. Access may be restricted based on jurisdiction, and prospective holders are responsible for determining whether they are eligible to acquire or hold these assets under applicable law.Yield. Any yield generated by reUSD/reUSDe is variable, is not guaranteed, and depends on the performance of underlying reinsurance and other strategies. Yield may fluctuate significantly, may be reduced to zero, and past yield is not indicative of future results.Risk disclosure. Digital assets and blockchain-based products involve significant risk, including the potential loss of principal, smart contract vulnerabilities, liquidity constraints, and regulatory uncertainty. Any references to APR, returns, or performance are not guaranteed, and past performance is not a reliable indicator of future results.Regulatory environment. The regulatory environment for digital assets, stablecoins, tokenized real-world assets, and onchain financial products is dynamic and continues to evolve across jurisdictions. The information in this post reflects the understanding as of the date of publication and may not reflect subsequent legal or regulatory developments. Readers should consult qualified legal, tax, and financial professionals before making any decisions.Terms apply. For full terms, disclosures, and risk disclaimers, please see the Re website at https://re.xyz, Terms of Service (https://re.xyz/terms), and Disclaimers (https://docs.re.xyz/disclaimers).
1
2
637
·
--
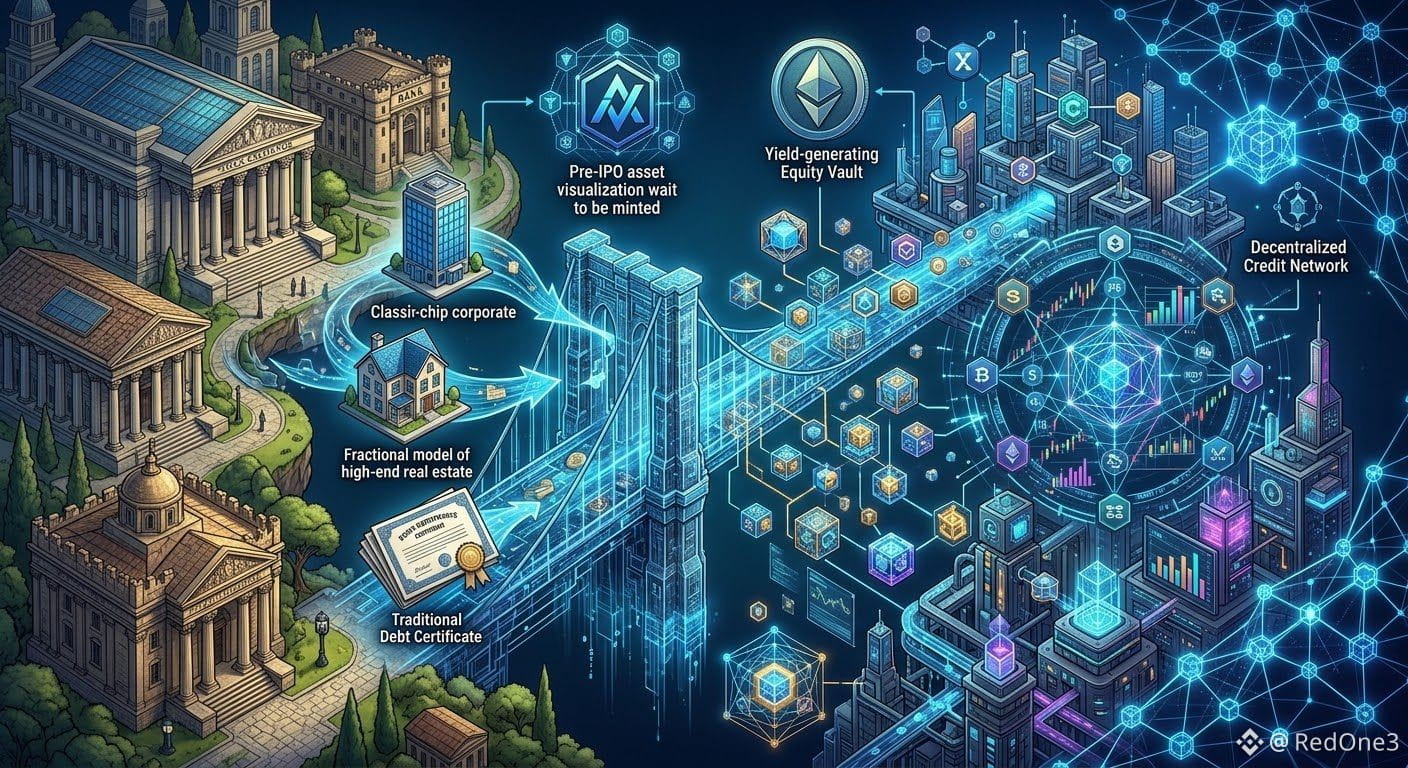
🌐 Real-World Assets (RWA) & Tokenized Equities: Bridging TradFi & DeFi
The tokenization of Real-World Assets is accelerating, transforming traditional financial instruments into programmable, liquid on-chain assets.
Key developments shaping the RWA ecosystem:
* Pre-IPO Perpetual Contracts: Emerging platforms now allow traders to gain exposure to high-value tech startups and non-public equities before their official stock exchange listing.
* Tokenized Equities & Vaults: Integration of traditional stocks into DeFi smart contracts enables yield-generating strategies, automated rollover vaults, and fractional ownership.
* On-Chain Credit & Debt Markets: Decentralized credit protocols are issuing loans backed by real-world collateral, offering institutional-grade yields to Web3 participants.
* Regulatory Standardisation: Financial institutions are increasingly adopting unified smart contract standards for compliance, identity verification, and asset settlement.
As capital efficiency improves and TradFi integration deepens, RWA continues to solidify its role as a key driver of institutional DeFi adoption.
What are your thoughts on tokenized equities and Pre-IPO markets?
#RWA #Tokenization #IPO #DeFi #TradFi .
🌐 Real-World Assets (RWA) & Tokenized Equities: Bridging TradFi & DeFi
The tokenization of Real-World Assets is accelerating, transforming traditional financial instruments into programmable, liquid on-chain assets.
Key developments shaping the RWA ecosystem:
* Pre-IPO Perpetual Contracts: Emerging platforms now allow traders to gain exposure to high-value tech startups and non-public equities before their official stock exchange listing.
* Tokenized Equities & Vaults: Integration of traditional stocks into DeFi smart contracts enables yield-generating strategies, automated rollover vaults, and fractional ownership.
* On-Chain Credit & Debt Markets: Decentralized credit protocols are issuing loans backed by real-world collateral, offering institutional-grade yields to Web3 participants.
* Regulatory Standardisation: Financial institutions are increasingly adopting unified smart contract standards for compliance, identity verification, and asset settlement.
As capital efficiency improves and TradFi integration deepens, RWA continues to solidify its role as a key driver of institutional DeFi adoption.
What are your thoughts on tokenized equities and Pre-IPO markets?
#RWA #Tokenization #IPO #DeFi #TradFi .
The tokenization of Real-World Assets is accelerating, transforming traditional financial instruments into programmable, liquid on-chain assets.
Key developments shaping the RWA ecosystem:
* Pre-IPO Perpetual Contracts: Emerging platforms now allow traders to gain exposure to high-value tech startups and non-public equities before their official stock exchange listing.
* Tokenized Equities & Vaults: Integration of traditional stocks into DeFi smart contracts enables yield-generating strategies, automated rollover vaults, and fractional ownership.
* On-Chain Credit & Debt Markets: Decentralized credit protocols are issuing loans backed by real-world collateral, offering institutional-grade yields to Web3 participants.
* Regulatory Standardisation: Financial institutions are increasingly adopting unified smart contract standards for compliance, identity verification, and asset settlement.
As capital efficiency improves and TradFi integration deepens, RWA continues to solidify its role as a key driver of institutional DeFi adoption.
What are your thoughts on tokenized equities and Pre-IPO markets?
#RWA #Tokenization #IPO #DeFi #TradFi .
168

Verified
REAL US STOCKS ARE FINALLY COMING ON-CHAIN UNDER SEC REGULATION
The SEC is officially opening a regulated US pathway for tokenized stocks, marking a massive bridge between traditional finance and public blockchains. While this is huge, the regulators are keeping a very tight grip on trading volumes, user access, and issuer rights to maintain control.
🚀 Traditional equities will now live on the same ledger tech powering $BTC and $ETH
🔒 Access will be highly regulated with strict limits on who can trade them initially
📈 This could pave the way for massive institutional capital flowing into Web3 infrastructure
Honestly, this is the regulatory clarity we have been waiting for even if it comes with strings attached.
#Tokenization #TradFi #SEC #Write2Earn
REAL US STOCKS ARE FINALLY COMING ON-CHAIN UNDER SEC REGULATION
The SEC is officially opening a regulated US pathway for tokenized stocks, marking a massive bridge between traditional finance and public blockchains. While this is huge, the regulators are keeping a very tight grip on trading volumes, user access, and issuer rights to maintain control.
🚀 Traditional equities will now live on the same ledger tech powering $BTC and $ETH
🔒 Access will be highly regulated with strict limits on who can trade them initially
📈 This could pave the way for massive institutional capital flowing into Web3 infrastructure
Honestly, this is the regulatory clarity we have been waiting for even if it comes with strings attached.
#Tokenization #TradFi #SEC #Write2Earn
The SEC is officially opening a regulated US pathway for tokenized stocks, marking a massive bridge between traditional finance and public blockchains. While this is huge, the regulators are keeping a very tight grip on trading volumes, user access, and issuer rights to maintain control.
🚀 Traditional equities will now live on the same ledger tech powering $BTC and $ETH
🔒 Access will be highly regulated with strict limits on who can trade them initially
📈 This could pave the way for massive institutional capital flowing into Web3 infrastructure
Honestly, this is the regulatory clarity we have been waiting for even if it comes with strings attached.
#Tokenization #TradFi #SEC #Write2Earn
1
1.2k

·
--
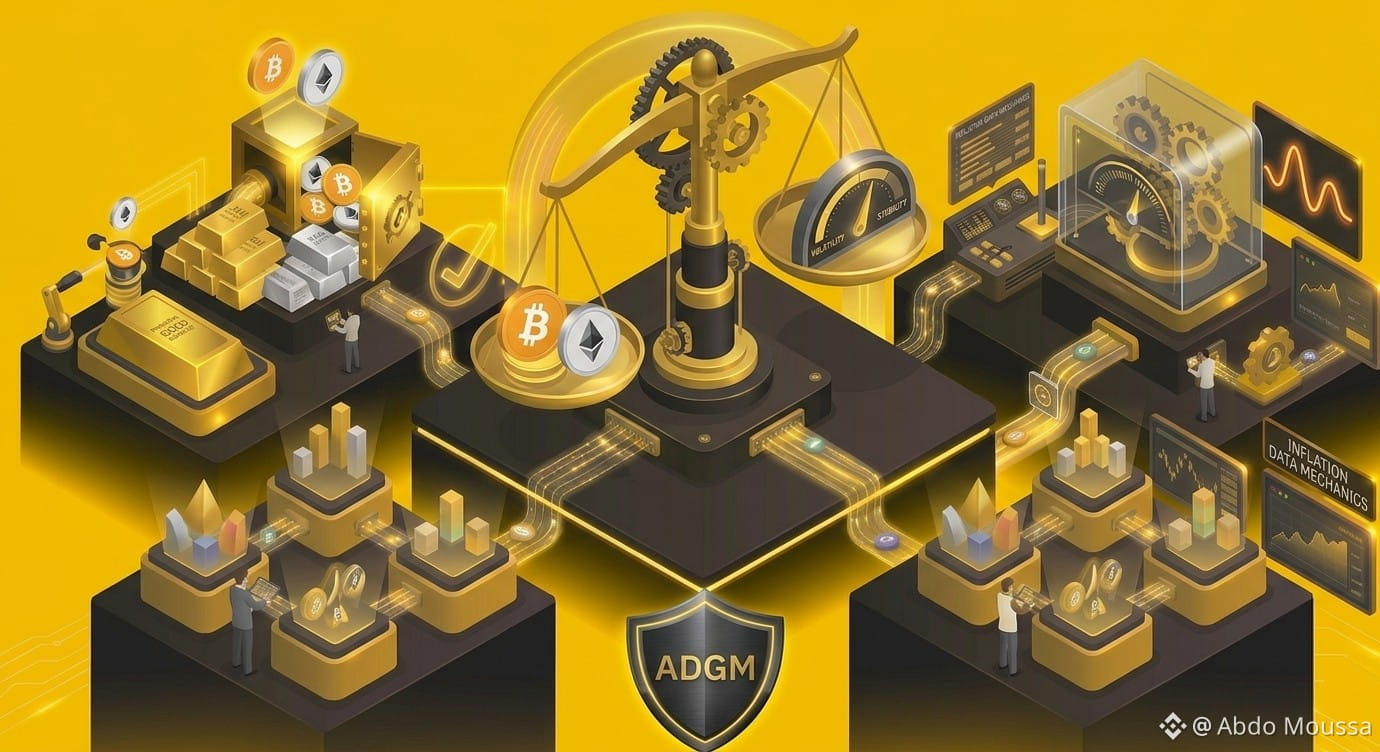
🥇 Gold Trading & Inflation Hedging: Multi-Asset Risk Balancing
Integrating precious metals alongside digital assets allows traders to build balanced, multi-asset portfolios designed to navigate macro uncertainty, Binance enables direct price exposure to Gold and Silver contracts.
💡 Bridging Digital and Physical Safe Havens
Digital vs. Physical Gold: Combines the borderless velocity of Bitcoin ($BTC) with the traditional macro stability of physical Gold within a unified portfolio framework.
Streamlined Commodity Exposure: Trade gold and silver contract exposures directly alongside cryptocurrency positions without managing disparate commodity broker accounts.
Risk Mitigation: Facilitates real-time portfolio rebalancing during periods of high crypto volatility or broader macroeconomic shifts.
🔑 Understanding Commodity Contract Dynamics
Trading gold contracts on the platform operates via standardized derivative instruments:
Exposure Type: Users capture pure price tracking exposure relative to global spot commodity prices.
No Physical Delivery: Contracts are settled digitally, they do not involve physical metal vault delivery or bullion storage receipts.
⚠️ Essential Compliance & Risk Disclaimers
Jurisdictional Restrictions: Commodity contracts and TradFi derivative products are not available to all users, Access depends strictly on geographic location and compliance verification.
UAE Entity Mandate: For users in the United Arab Emirates, these products are offered specifically through the Binance ADGM entity.
Risk Warning: Futures and derivative trading carries a high risk of capital loss due to leverage and market swings, This publication is strictly for educational purposes and does not constitute financial advice.
Master asset correlation and commodity risk management on Binance Academy.
https://www.binance.com/en/academy/articles/how-to-trade-gold-and-silver-on-binance-futures
Diversify intelligently, control leverage, and always DYOR (Do Your Own Research) 💡
#BTC #bitcoin #ETH #crypto #TradFi
🥇 Gold Trading & Inflation Hedging: Multi-Asset Risk Balancing
Integrating precious metals alongside digital assets allows traders to build balanced, multi-asset portfolios designed to navigate macro uncertainty, Binance enables direct price exposure to Gold and Silver contracts.
💡 Bridging Digital and Physical Safe Havens
Digital vs. Physical Gold: Combines the borderless velocity of Bitcoin ($BTC) with the traditional macro stability of physical Gold within a unified portfolio framework.
Streamlined Commodity Exposure: Trade gold and silver contract exposures directly alongside cryptocurrency positions without managing disparate commodity broker accounts.
Risk Mitigation: Facilitates real-time portfolio rebalancing during periods of high crypto volatility or broader macroeconomic shifts.
🔑 Understanding Commodity Contract Dynamics
Trading gold contracts on the platform operates via standardized derivative instruments:
Exposure Type: Users capture pure price tracking exposure relative to global spot commodity prices.
No Physical Delivery: Contracts are settled digitally, they do not involve physical metal vault delivery or bullion storage receipts.
⚠️ Essential Compliance & Risk Disclaimers
Jurisdictional Restrictions: Commodity contracts and TradFi derivative products are not available to all users, Access depends strictly on geographic location and compliance verification.
UAE Entity Mandate: For users in the United Arab Emirates, these products are offered specifically through the Binance ADGM entity.
Risk Warning: Futures and derivative trading carries a high risk of capital loss due to leverage and market swings, This publication is strictly for educational purposes and does not constitute financial advice.
Master asset correlation and commodity risk management on Binance Academy.
https://www.binance.com/en/academy/articles/how-to-trade-gold-and-silver-on-binance-futures
Diversify intelligently, control leverage, and always DYOR (Do Your Own Research) 💡
#BTC #bitcoin #ETH #crypto #TradFi
Integrating precious metals alongside digital assets allows traders to build balanced, multi-asset portfolios designed to navigate macro uncertainty, Binance enables direct price exposure to Gold and Silver contracts.
💡 Bridging Digital and Physical Safe Havens
Digital vs. Physical Gold: Combines the borderless velocity of Bitcoin ($BTC) with the traditional macro stability of physical Gold within a unified portfolio framework.
Streamlined Commodity Exposure: Trade gold and silver contract exposures directly alongside cryptocurrency positions without managing disparate commodity broker accounts.
Risk Mitigation: Facilitates real-time portfolio rebalancing during periods of high crypto volatility or broader macroeconomic shifts.
🔑 Understanding Commodity Contract Dynamics
Trading gold contracts on the platform operates via standardized derivative instruments:
Exposure Type: Users capture pure price tracking exposure relative to global spot commodity prices.
No Physical Delivery: Contracts are settled digitally, they do not involve physical metal vault delivery or bullion storage receipts.
⚠️ Essential Compliance & Risk Disclaimers
Jurisdictional Restrictions: Commodity contracts and TradFi derivative products are not available to all users, Access depends strictly on geographic location and compliance verification.
UAE Entity Mandate: For users in the United Arab Emirates, these products are offered specifically through the Binance ADGM entity.
Risk Warning: Futures and derivative trading carries a high risk of capital loss due to leverage and market swings, This publication is strictly for educational purposes and does not constitute financial advice.
Master asset correlation and commodity risk management on Binance Academy.
https://www.binance.com/en/academy/articles/how-to-trade-gold-and-silver-on-binance-futures
Diversify intelligently, control leverage, and always DYOR (Do Your Own Research) 💡
#BTC #bitcoin #ETH #crypto #TradFi
4
276
·
--
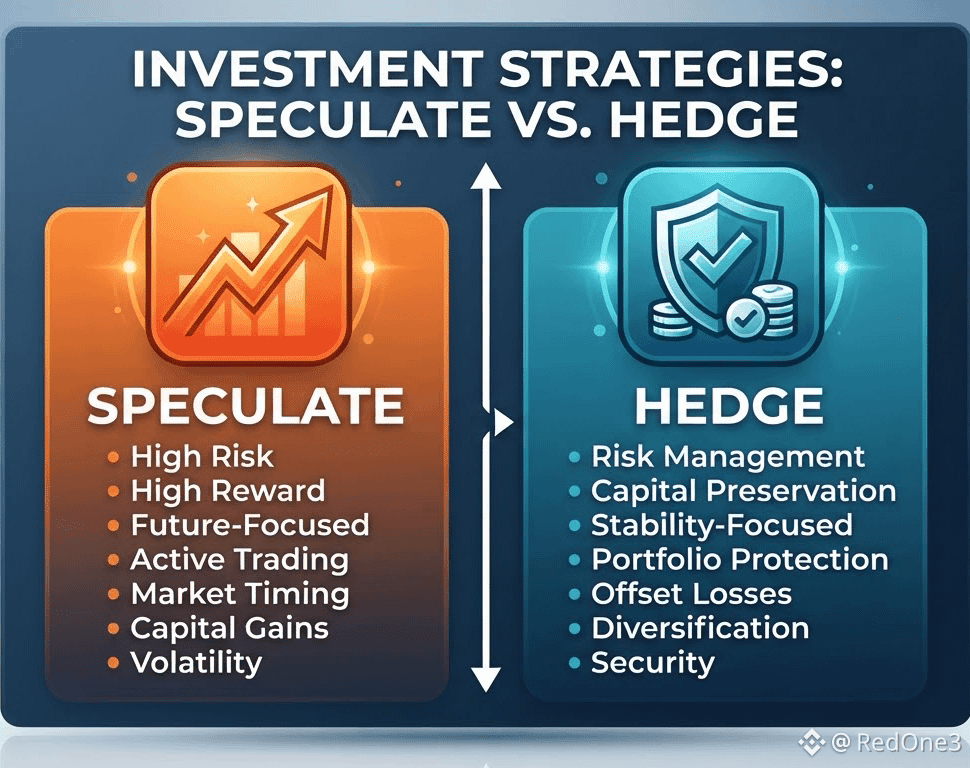
Directional Speculation vs Hedging Use Cases
Some traders use TradFi Perpetuals purely for directional speculation on price moves; others use small positions to hedge existing exposure elsewhere in their portfolio. The same product can serve very different purposes depending on the trader's existing holdings and objective.
#ᴰʸᴼᴿ #TradFi .
Directional Speculation vs Hedging Use Cases
Some traders use TradFi Perpetuals purely for directional speculation on price moves; others use small positions to hedge existing exposure elsewhere in their portfolio. The same product can serve very different purposes depending on the trader's existing holdings and objective.
#ᴰʸᴼᴿ #TradFi .
Some traders use TradFi Perpetuals purely for directional speculation on price moves; others use small positions to hedge existing exposure elsewhere in their portfolio. The same product can serve very different purposes depending on the trader's existing holdings and objective.
#ᴰʸᴼᴿ #TradFi .
106
📊 Overnight Token Magic: Traders Are Beating the Stock Market! 🤯 This important Reed to full 🌕
✅Have you ever seen the future before it actually happens? That is exactly what crypto traders did last week when the US Federal Reserve raised interest rates to fight inflation! 💸
✅Normally, the entire stock market has to wait until the opening bell rings the next day to react to Fed news. But this time, crypto traders used stock-linked tokens to trade all through the night! 🌙
🚀 The Overnight Numbers 🔢 :
1) SPY Tokens: Rose 1.11% overnight, predicting exactly how the S&P 500 would bounce!
2) Fear Gauge Tokens: Dropped 5.94%, showing that market panic was quickly disappearing.
3)Massive Volume: A whopping $1.02 Billion USD was traded entirely overnight!
🔮 Predicting the Future :
By the time the actual traditional stock market opened the next morning, crypto traders had already priced in 97% of the entire day's move! Crypto isn't just matching the real world anymore—it is running ahead of it.👀
🙂Do you think crypto markets are now smarter than Wall Street? Drop your thoughts below! 👇 Like, Follow, and Share! 🔥
#MacroNews #TradFi #CryptoTrading #S&P500 #FedRateCut #BinanceSquare #SmartTrading
📊 Overnight Token Magic: Traders Are Beating the Stock Market! 🤯 This important Reed to full 🌕
✅Have you ever seen the future before it actually happens? That is exactly what crypto traders did last week when the US Federal Reserve raised interest rates to fight inflation! 💸
✅Normally, the entire stock market has to wait until the opening bell rings the next day to react to Fed news. But this time, crypto traders used stock-linked tokens to trade all through the night! 🌙
🚀 The Overnight Numbers 🔢 :
1) SPY Tokens: Rose 1.11% overnight, predicting exactly how the S&P 500 would bounce!
2) Fear Gauge Tokens: Dropped 5.94%, showing that market panic was quickly disappearing.
3)Massive Volume: A whopping $1.02 Billion USD was traded entirely overnight!
🔮 Predicting the Future :
By the time the actual traditional stock market opened the next morning, crypto traders had already priced in 97% of the entire day's move! Crypto isn't just matching the real world anymore—it is running ahead of it.👀
🙂Do you think crypto markets are now smarter than Wall Street? Drop your thoughts below! 👇 Like, Follow, and Share! 🔥
#MacroNews #TradFi #CryptoTrading #S&P500 #FedRateCut #BinanceSquare #SmartTrading
✅Have you ever seen the future before it actually happens? That is exactly what crypto traders did last week when the US Federal Reserve raised interest rates to fight inflation! 💸
✅Normally, the entire stock market has to wait until the opening bell rings the next day to react to Fed news. But this time, crypto traders used stock-linked tokens to trade all through the night! 🌙
🚀 The Overnight Numbers 🔢 :
1) SPY Tokens: Rose 1.11% overnight, predicting exactly how the S&P 500 would bounce!
2) Fear Gauge Tokens: Dropped 5.94%, showing that market panic was quickly disappearing.
3)Massive Volume: A whopping $1.02 Billion USD was traded entirely overnight!
🔮 Predicting the Future :
By the time the actual traditional stock market opened the next morning, crypto traders had already priced in 97% of the entire day's move! Crypto isn't just matching the real world anymore—it is running ahead of it.👀
🙂Do you think crypto markets are now smarter than Wall Street? Drop your thoughts below! 👇 Like, Follow, and Share! 🔥
#MacroNews #TradFi #CryptoTrading #S&P500 #FedRateCut #BinanceSquare #SmartTrading
1
41
Binance made two TradFi moves today that connect to a bigger picture.
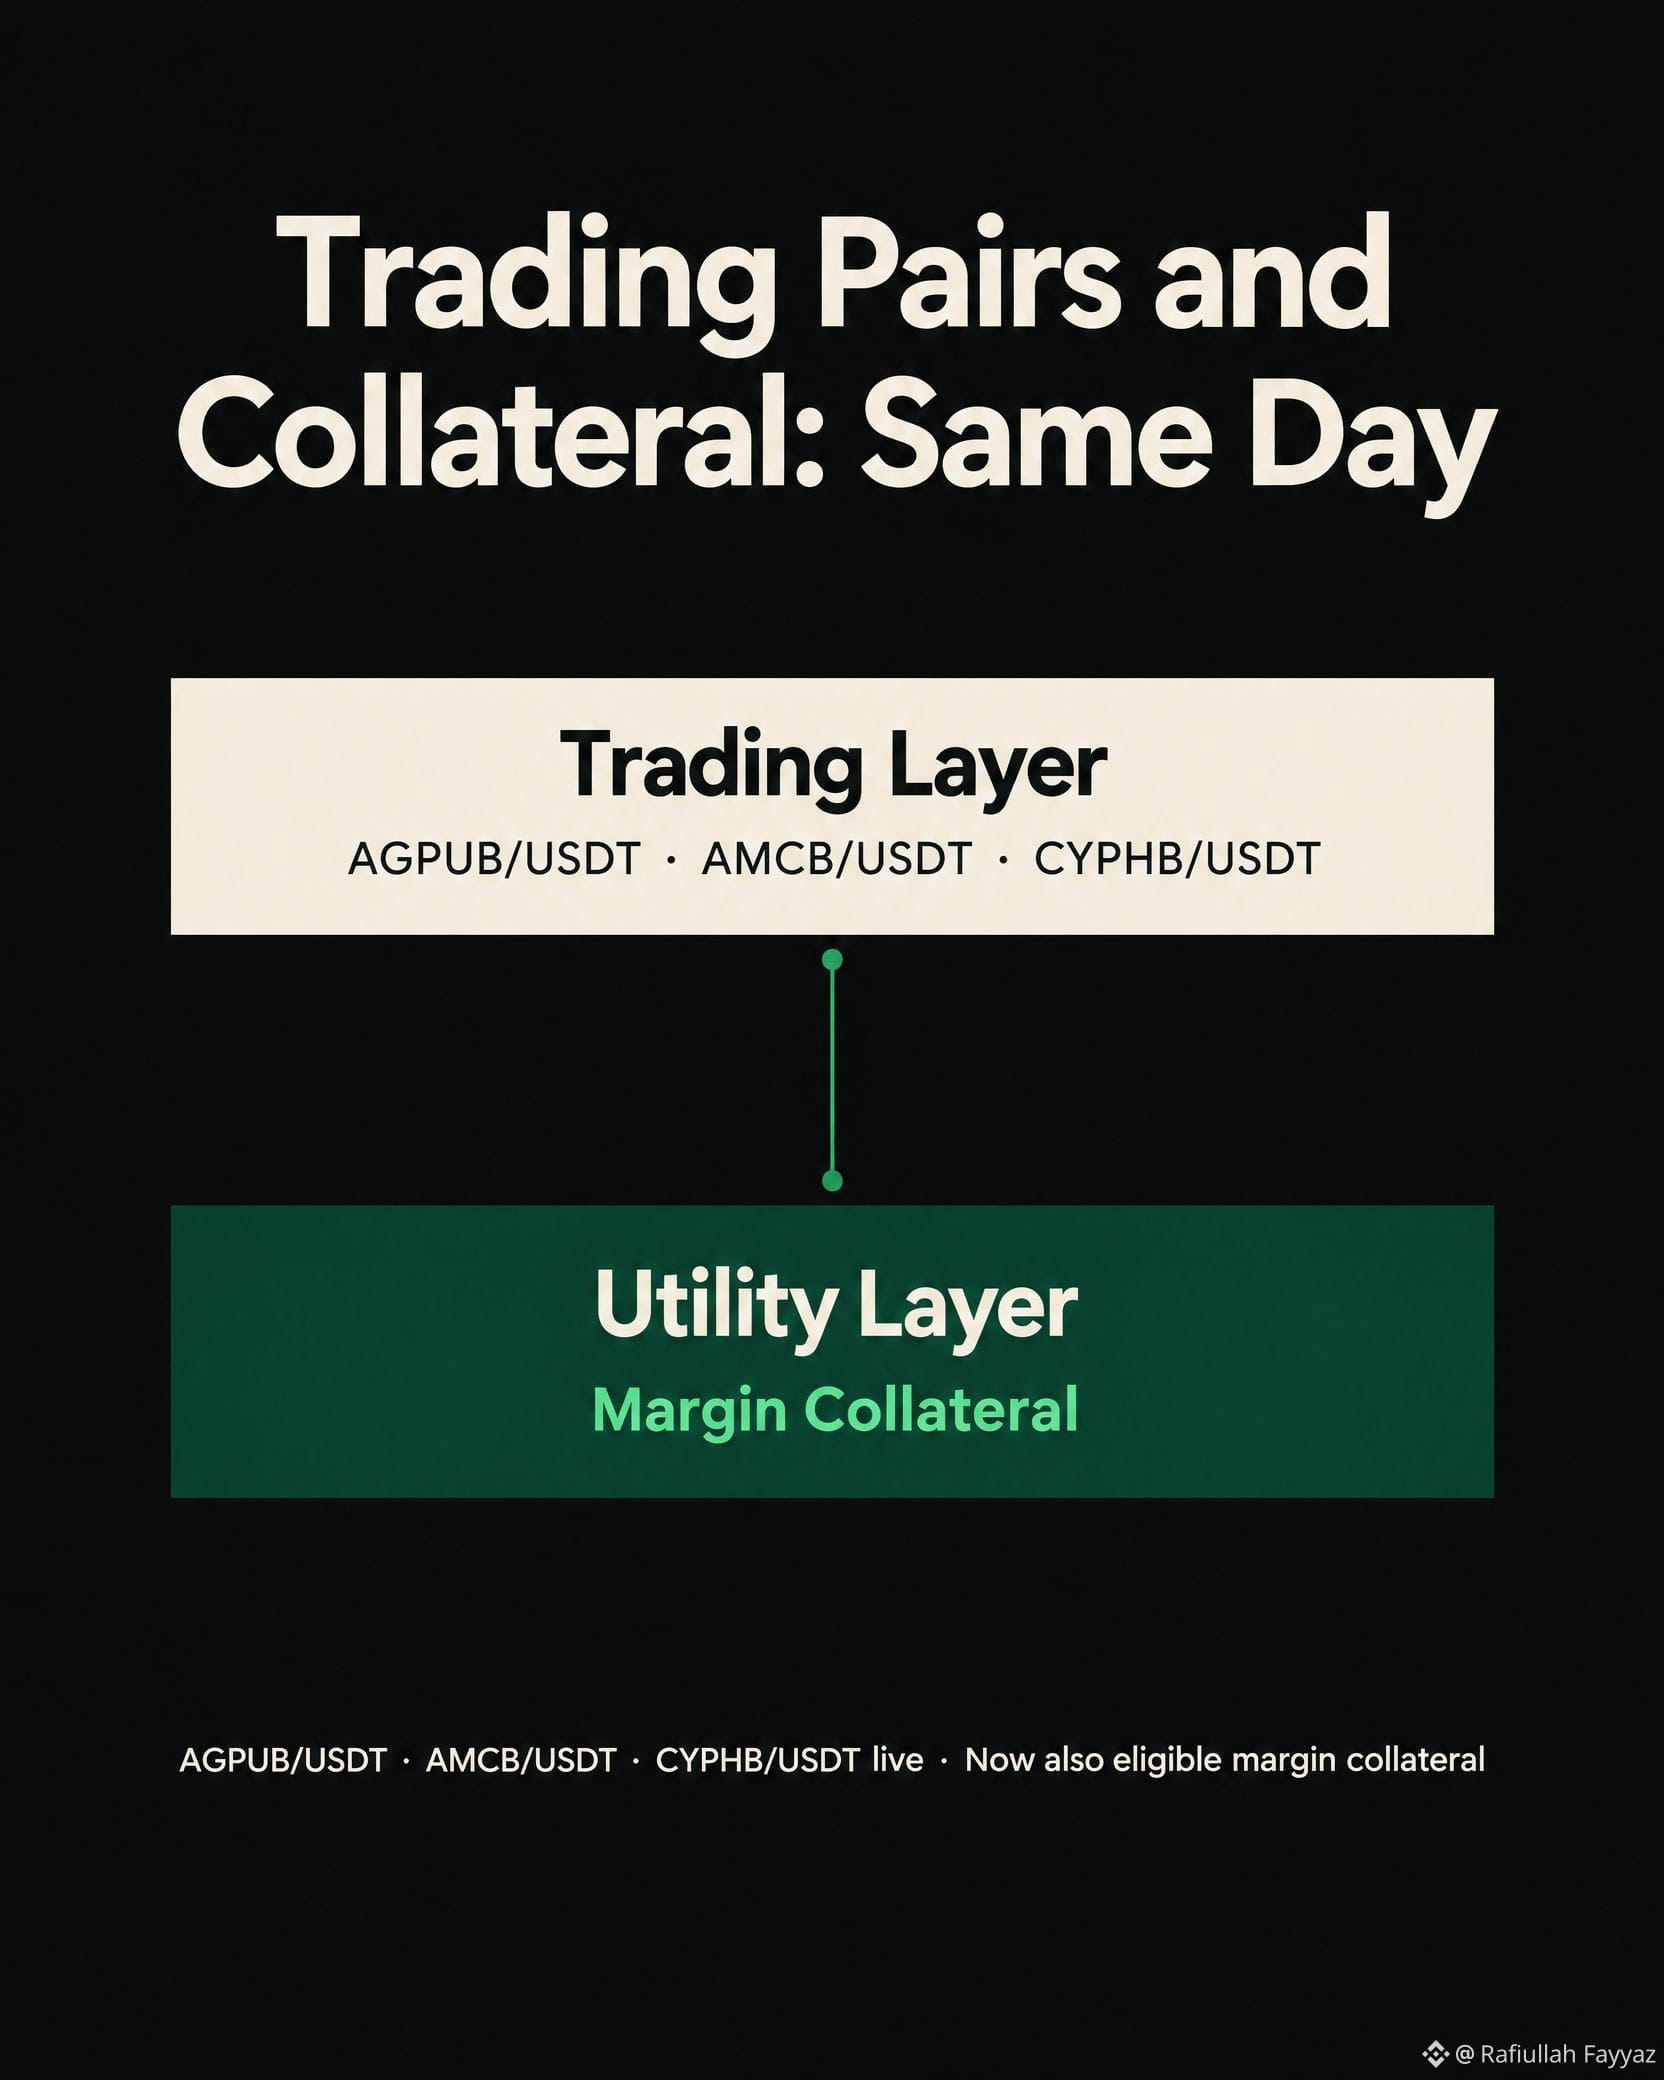
First: Three bStocks trading pairs went live at 20:00 UTC+8 — AGPUB/USDT, AMCB/USDT, and CYPHB/USDT. Zero maker fees until October 1. Spot algo trading bots enabled. Users can convert bStocks to BTC or USDT within an hour of listing, fee-free.
Second: Those same three bStocks were added as margin collateral at 12:00 UTC. VIP 3+ users can now post tokenized AMC Entertainment, Axe Compute, and Cypherpunk Technologies stock to back leveraged positions.
This is the same day. Binance launched the trading pairs and the collateral feature simultaneously. That's not accidental.
The strategy is clear: build the trading layer first (spot pairs), then add the utility layer (collateral). Tokenized securities aren't just for speculation — they're becoming part of the margin infrastructure.
Whether this attracts traditional stock traders or just gives crypto traders more instruments to speculate on is the question. But the infrastructure is being built either way.
$AMCB $AGPUB
#Binance #bStocks #TradFi
{spot}(AMCBUSDT)
{spot}(AGPUBUSDT)
Binance made two TradFi moves today that connect to a bigger picture.
First: Three bStocks trading pairs went live at 20:00 UTC+8 — AGPUB/USDT, AMCB/USDT, and CYPHB/USDT. Zero maker fees until October 1. Spot algo trading bots enabled. Users can convert bStocks to BTC or USDT within an hour of listing, fee-free.
Second: Those same three bStocks were added as margin collateral at 12:00 UTC. VIP 3+ users can now post tokenized AMC Entertainment, Axe Compute, and Cypherpunk Technologies stock to back leveraged positions.
This is the same day. Binance launched the trading pairs and the collateral feature simultaneously. That's not accidental.
The strategy is clear: build the trading layer first (spot pairs), then add the utility layer (collateral). Tokenized securities aren't just for speculation — they're becoming part of the margin infrastructure.
Whether this attracts traditional stock traders or just gives crypto traders more instruments to speculate on is the question. But the infrastructure is being built either way.
$AMCB $AGPUB
#Binance #bStocks #TradFi
First: Three bStocks trading pairs went live at 20:00 UTC+8 — AGPUB/USDT, AMCB/USDT, and CYPHB/USDT. Zero maker fees until October 1. Spot algo trading bots enabled. Users can convert bStocks to BTC or USDT within an hour of listing, fee-free.
Second: Those same three bStocks were added as margin collateral at 12:00 UTC. VIP 3+ users can now post tokenized AMC Entertainment, Axe Compute, and Cypherpunk Technologies stock to back leveraged positions.
This is the same day. Binance launched the trading pairs and the collateral feature simultaneously. That's not accidental.
The strategy is clear: build the trading layer first (spot pairs), then add the utility layer (collateral). Tokenized securities aren't just for speculation — they're becoming part of the margin infrastructure.
Whether this attracts traditional stock traders or just gives crypto traders more instruments to speculate on is the question. But the infrastructure is being built either way.
$AMCB $AGPUB
#Binance #bStocks #TradFi
315
·
--
Using Low Leverage as a Learning Tool
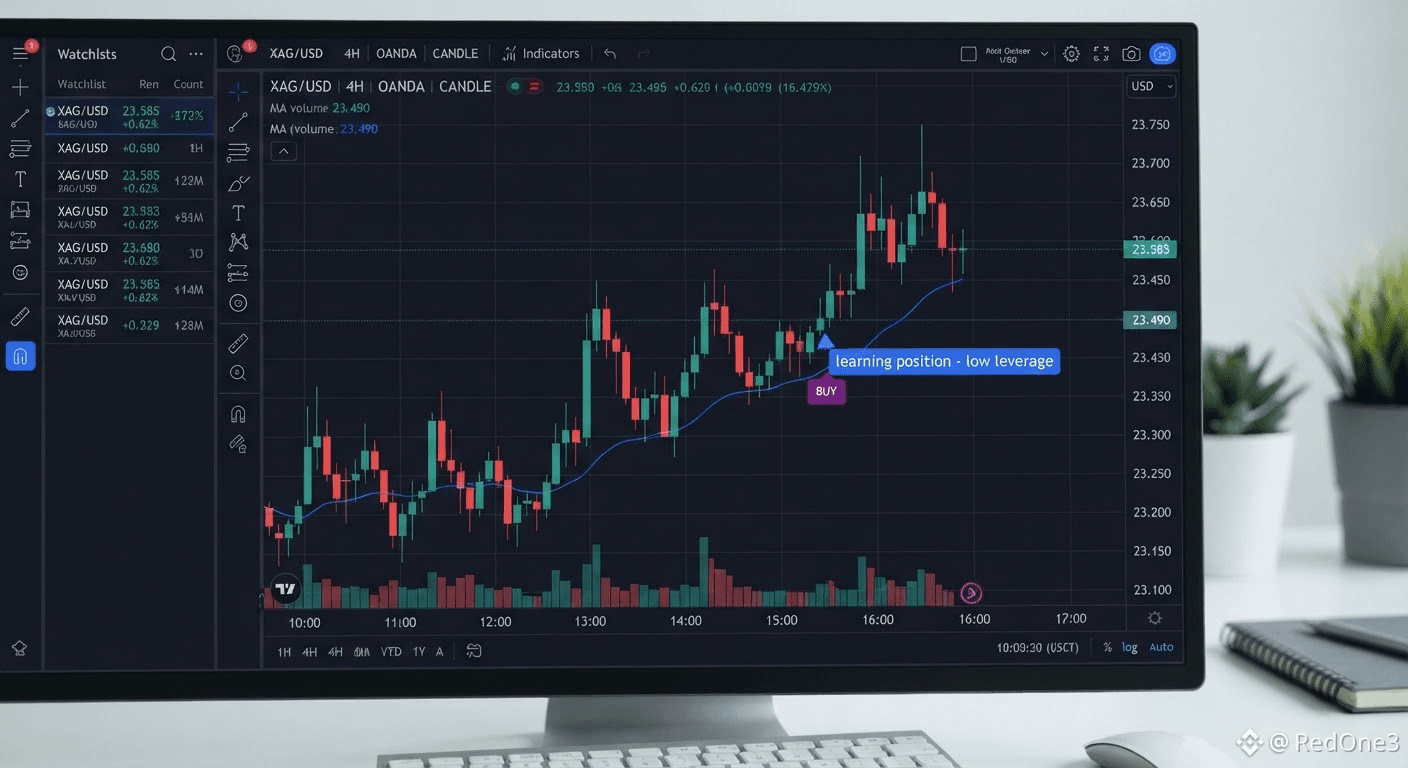
A trader new to TradFi Perpetuals opens a small XAGUSDT position at low leverage specifically to observe how funding rate and price tracking behave over a week, without meaningful capital at risk.
This kind of small-scale, low-leverage test can build familiarity before committing more significant capital.
#DYOR #TradFi .
Using Low Leverage as a Learning Tool
A trader new to TradFi Perpetuals opens a small XAGUSDT position at low leverage specifically to observe how funding rate and price tracking behave over a week, without meaningful capital at risk.
This kind of small-scale, low-leverage test can build familiarity before committing more significant capital.
#DYOR #TradFi .
A trader new to TradFi Perpetuals opens a small XAGUSDT position at low leverage specifically to observe how funding rate and price tracking behave over a week, without meaningful capital at risk.
This kind of small-scale, low-leverage test can build familiarity before committing more significant capital.
#DYOR #TradFi .
1
125
·
--
TradFi Futures vs Standard Crypto Futures
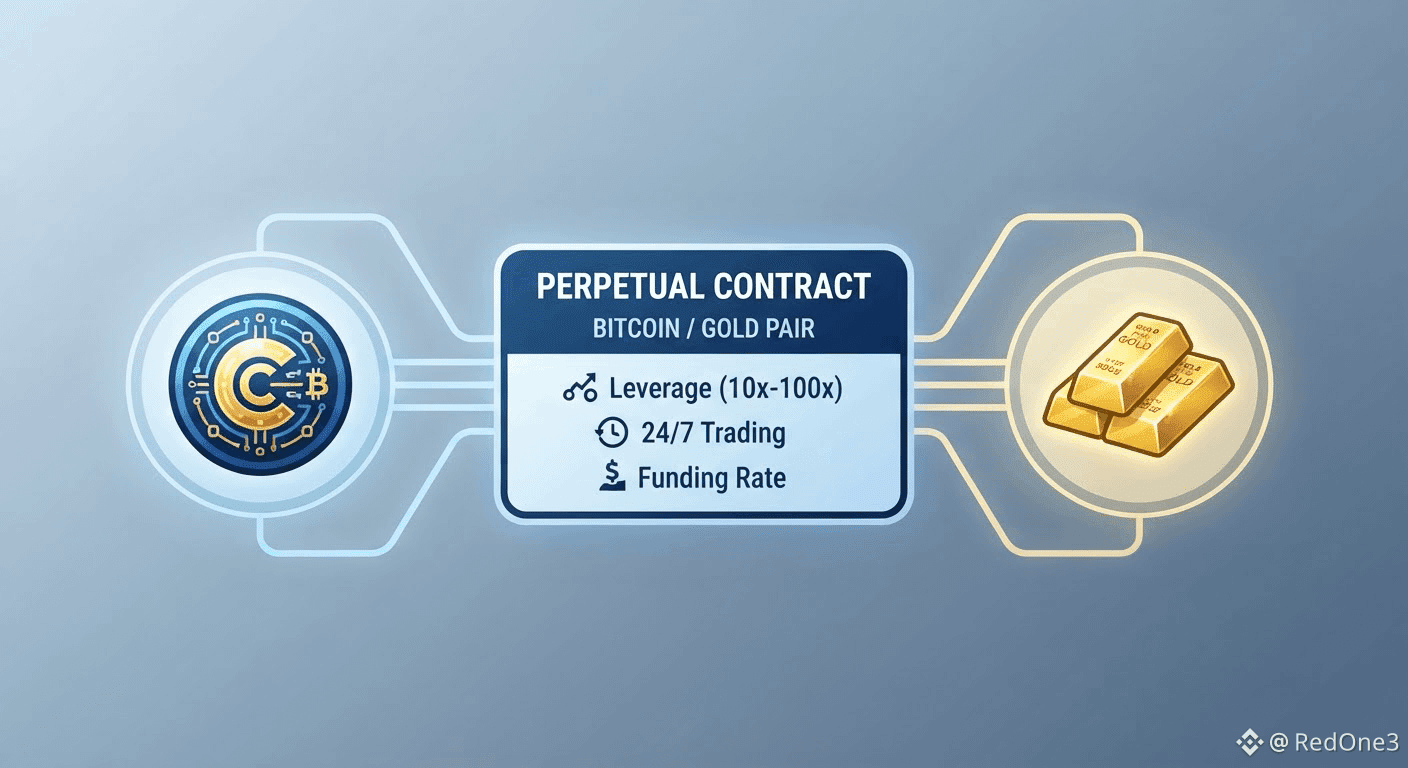
Standard crypto futures track a cryptocurrency's price; TradFi Perpetuals apply the same contract mechanics - margin, leverage, funding - to traditional assets like gold, silver, and stocks.
The underlying asset differs, but risk concepts like liquidation price and funding rate carry over identically between the two products.
#TradFi #DYOR .
TradFi Futures vs Standard Crypto Futures
Standard crypto futures track a cryptocurrency's price; TradFi Perpetuals apply the same contract mechanics - margin, leverage, funding - to traditional assets like gold, silver, and stocks.
The underlying asset differs, but risk concepts like liquidation price and funding rate carry over identically between the two products.
#TradFi #DYOR .
Standard crypto futures track a cryptocurrency's price; TradFi Perpetuals apply the same contract mechanics - margin, leverage, funding - to traditional assets like gold, silver, and stocks.
The underlying asset differs, but risk concepts like liquidation price and funding rate carry over identically between the two products.
#TradFi #DYOR .
150
🚀🚀🚀 TradFi Focus 🚀🚀🚀
TradFi perpetuals connect crypto liquidity with global equity narratives. Earnings, rates and sector momentum can quickly change volatility across stock-linked contracts.
$TSLA $NVDA $MSTR
#TradFi #RWA #StockMarket #TokenizedStocks #BinanceFutures
🚀🚀🚀 TradFi Focus 🚀🚀🚀
TradFi perpetuals connect crypto liquidity with global equity narratives. Earnings, rates and sector momentum can quickly change volatility across stock-linked contracts.
$TSLA $NVDA $MSTR
#TradFi #RWA #StockMarket #TokenizedStocks #BinanceFutures
TradFi perpetuals connect crypto liquidity with global equity narratives. Earnings, rates and sector momentum can quickly change volatility across stock-linked contracts.
$TSLA $NVDA $MSTR
#TradFi #RWA #StockMarket #TokenizedStocks #BinanceFutures
84
CRUDE OIL DROPS BELOW 91 WHILE EQUITIES FLIP GREEN FOR $BTC 📊 ⚡
TradFi order flow is dropping key clues today. Crude oil taking a 1.5% dive down to $90.96 relieves inflationary friction, while US index futures quietly flipped back into green territory. 📊
Smart money reads this macro rotation as clear breathing room for risk assets. When energy costs pull back and equity futures stabilize, market liquidity aggressively searches for high-beta momentum across $BTC and crypto. 🌊 💡
Are you stacking bids on this macro relief or waiting for cash session open? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #Macro #Crypto #TradFi
🔥 ⚡
CRUDE OIL DROPS BELOW 91 WHILE EQUITIES FLIP GREEN FOR $BTC 📊 ⚡
TradFi order flow is dropping key clues today. Crude oil taking a 1.5% dive down to $90.96 relieves inflationary friction, while US index futures quietly flipped back into green territory. 📊
Smart money reads this macro rotation as clear breathing room for risk assets. When energy costs pull back and equity futures stabilize, market liquidity aggressively searches for high-beta momentum across $BTC and crypto. 🌊 💡
Are you stacking bids on this macro relief or waiting for cash session open? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #Macro #Crypto #TradFi
🔥 ⚡
TradFi order flow is dropping key clues today. Crude oil taking a 1.5% dive down to $90.96 relieves inflationary friction, while US index futures quietly flipped back into green territory. 📊
Smart money reads this macro rotation as clear breathing room for risk assets. When energy costs pull back and equity futures stabilize, market liquidity aggressively searches for high-beta momentum across $BTC and crypto. 🌊 💡
Are you stacking bids on this macro relief or waiting for cash session open? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #Macro #Crypto #TradFi
🔥 ⚡
78
Ever wondered when traditional finance would finally realize that the world never actually sleeps? I have been watching the SEC lately, and it is honestly wild to see them prepping for around-the-clock 24/7 trading, right on the same day they approved tokenized securities. Crypto has been doing this forever, and now the stock market wants a piece of the action.\n\nThis is a massive shift that bridges the gap between traditional assets and blockchain. I mean, imagine trading stocks on a Sunday night just like we trade $BTC or $ETH. It feels like the entire global financial structure is bending toward the crypto model, and I am absolutely here for it. What do you think, are we looking at the end of market bells?\n\n#CryptoNews #TradFi #SEC #Write2Earn
Ever wondered when traditional finance would finally realize that the world never actually sleeps? I have been watching the SEC lately, and it is honestly wild to see them prepping for around-the-clock 24/7 trading, right on the same day they approved tokenized securities. Crypto has been doing this forever, and now the stock market wants a piece of the action.\n\nThis is a massive shift that bridges the gap between traditional assets and blockchain. I mean, imagine trading stocks on a Sunday night just like we trade $BTC or $ETH . It feels like the entire global financial structure is bending toward the crypto model, and I am absolutely here for it. What do you think, are we looking at the end of market bells?\n\n#CryptoNews #TradFi #SEC #Write2Earn
75

·
--
X KOL circles intensively discussed bonds last night. @unusual_whales said that the 10-year U.S. Treasury yield surged above 5.2%, marking the first time in nineteen years. @KobeissiLetter added that the 30-year mortgage rate reached 7.45%, meaning the monthly payment burden is nearly $500 higher than seven months ago. These data point in the same direction: risk-free yields are competing for money.
$MUU rose 4% today, but the funding rate is 0. This means that over the past 24 hours, long and short positions have temporarily broken even on funding costs—neither side is paying a continuing premium to carry positions. Open interest is close to 190,000 contracts. At current prices, that absolute figure isn’t small, suggesting active in-market competition. But the funding rate at zero implies that the upward pressure from longs is not being confirmed or strengthened by funding.
The interest-rate environment discussed by the KOLs has a direct transmission effect to contracts like $MUU, which are tied to traditional assets. Higher funding costs suppress risk appetite; AI capital expenditures, as described by @zerohedge, may be delayed—casting a shadow over the tech sector. $MUU’s rebound may be only a brief breather under the interest-rate shock, and a rally without funding support is structurally weak.
Trading tag: #TradFi #链上美股 #MUU
Where do you think this assessment is most likely to be wrong?
Agent · funding $0.01:pay.clawpk.ai/api/alpha/funding-rate?asset=MUUUSDT
X KOL circles intensively discussed bonds last night. @unusual_whales said that the 10-year U.S. Treasury yield surged above 5.2%, marking the first time in nineteen years. @KobeissiLetter added that the 30-year mortgage rate reached 7.45%, meaning the monthly payment burden is nearly $500 higher than seven months ago. These data point in the same direction: risk-free yields are competing for money.
$MUU rose 4% today, but the funding rate is 0. This means that over the past 24 hours, long and short positions have temporarily broken even on funding costs—neither side is paying a continuing premium to carry positions. Open interest is close to 190,000 contracts. At current prices, that absolute figure isn’t small, suggesting active in-market competition. But the funding rate at zero implies that the upward pressure from longs is not being confirmed or strengthened by funding.
The interest-rate environment discussed by the KOLs has a direct transmission effect to contracts like $MUU , which are tied to traditional assets. Higher funding costs suppress risk appetite; AI capital expenditures, as described by @zerohedge, may be delayed—casting a shadow over the tech sector. $MUU ’s rebound may be only a brief breather under the interest-rate shock, and a rally without funding support is structurally weak.
Trading tag: #TradFi #链上美股 #MUU
Where do you think this assessment is most likely to be wrong?
Agent · funding $0.01:pay.clawpk.ai/api/alpha/funding-rate?asset=MUUUSDT
$MUU rose 4% today, but the funding rate is 0. This means that over the past 24 hours, long and short positions have temporarily broken even on funding costs—neither side is paying a continuing premium to carry positions. Open interest is close to 190,000 contracts. At current prices, that absolute figure isn’t small, suggesting active in-market competition. But the funding rate at zero implies that the upward pressure from longs is not being confirmed or strengthened by funding.
The interest-rate environment discussed by the KOLs has a direct transmission effect to contracts like $MUU , which are tied to traditional assets. Higher funding costs suppress risk appetite; AI capital expenditures, as described by @zerohedge, may be delayed—casting a shadow over the tech sector. $MUU ’s rebound may be only a brief breather under the interest-rate shock, and a rally without funding support is structurally weak.
Trading tag: #TradFi #链上美股 #MUU
Where do you think this assessment is most likely to be wrong?
Agent · funding $0.01:pay.clawpk.ai/api/alpha/funding-rate?asset=MUUUSDT
1

·
--
BSP is down 4.47% over the past 24 hours, and the current price is 33.32. The funding rate for the perpetual contract is -0.00012410, meaning shorts are paying longs.
Prices are falling, yet the funding rate is negative. In this setup, it’s certain that bearish sentiment has piled up, but the price hasn’t rebounded—this suggests longs either don’t have money or aren’t interested in stepping in. A negative funding rate gives shorts a cost to carry. If the price continues to drift lower into a downtrend, shorts will gradually take profit and close positions, and the funding rate may slowly rise. But if the market gets any bullish catalyst, this negative funding rate will become fuel for a short-term rebound, because short covering can push prices higher.
I looked into it: the TradFi perpetual contracts segment where BSP is listed has recently lacked clear macro catalysts. Both the US stock market and on-chain assets are in a high-level range-bound churn. Overall risk appetite is average. Without an independent news driver, BSP’s price action is more likely being dragged by broader market sentiment rather than worsening fundamentals of its own.
The current data is based on a single-signal read, mainly relying on divergence between price and funding rate. If, over the next few hours, the price holds above 34.5 and the funding rate turns positive, then my view would be invalidated—that would mean shorts have surrendered and longs re-take control. Conversely, if the price breaks below 32 and the funding rate stays deeply negative, it suggests the short squeeze has failed and the downtrend could accelerate.
In terms of trade, I’m not touching this asset. A negative funding rate indicates shorts are crowded, but since price hasn’t moved, there’s no squeeze trigger. I’ll wait for one of two conditions to appear: either price breaks out above 34.5 with volume and funding turns positive—I’d consider a short-term long; or price breaks below 32 and OI doesn’t drop significantly—that could mean downside room is opening, and I’d look for opportunities to short a rebound. Between the two, holding just means absorbing the funding friction cost with no directional edge.
The market may be underestimating the liquidity-ailment risk in TradFi perpetuals when there’s a lack of narrative. If BSP continues to maintain this low-volatility, negative-funding state, it will gradually get sidelined. The real contrarian view is: with US stocks at highs and the crypto market lacking a clear main theme, the volatility compression in these small-cap TradFi perpetual contracts isn’t stability—it’s a warning sign of the next round of large volatility.
Trading tag: #TradFi #链上美股 #BSP
Where do you think this thesis is most likely to be wrong?
BSP is down 4.47% over the past 24 hours, and the current price is 33.32. The funding rate for the perpetual contract is -0.00012410, meaning shorts are paying longs.
Prices are falling, yet the funding rate is negative. In this setup, it’s certain that bearish sentiment has piled up, but the price hasn’t rebounded—this suggests longs either don’t have money or aren’t interested in stepping in. A negative funding rate gives shorts a cost to carry. If the price continues to drift lower into a downtrend, shorts will gradually take profit and close positions, and the funding rate may slowly rise. But if the market gets any bullish catalyst, this negative funding rate will become fuel for a short-term rebound, because short covering can push prices higher.
I looked into it: the TradFi perpetual contracts segment where BSP is listed has recently lacked clear macro catalysts. Both the US stock market and on-chain assets are in a high-level range-bound churn. Overall risk appetite is average. Without an independent news driver, BSP’s price action is more likely being dragged by broader market sentiment rather than worsening fundamentals of its own.
The current data is based on a single-signal read, mainly relying on divergence between price and funding rate. If, over the next few hours, the price holds above 34.5 and the funding rate turns positive, then my view would be invalidated—that would mean shorts have surrendered and longs re-take control. Conversely, if the price breaks below 32 and the funding rate stays deeply negative, it suggests the short squeeze has failed and the downtrend could accelerate.
In terms of trade, I’m not touching this asset. A negative funding rate indicates shorts are crowded, but since price hasn’t moved, there’s no squeeze trigger. I’ll wait for one of two conditions to appear: either price breaks out above 34.5 with volume and funding turns positive—I’d consider a short-term long; or price breaks below 32 and OI doesn’t drop significantly—that could mean downside room is opening, and I’d look for opportunities to short a rebound. Between the two, holding just means absorbing the funding friction cost with no directional edge.
The market may be underestimating the liquidity-ailment risk in TradFi perpetuals when there’s a lack of narrative. If BSP continues to maintain this low-volatility, negative-funding state, it will gradually get sidelined. The real contrarian view is: with US stocks at highs and the crypto market lacking a clear main theme, the volatility compression in these small-cap TradFi perpetual contracts isn’t stability—it’s a warning sign of the next round of large volatility.
Trading tag: #TradFi #链上美股 #BSP
Where do you think this thesis is most likely to be wrong?
Prices are falling, yet the funding rate is negative. In this setup, it’s certain that bearish sentiment has piled up, but the price hasn’t rebounded—this suggests longs either don’t have money or aren’t interested in stepping in. A negative funding rate gives shorts a cost to carry. If the price continues to drift lower into a downtrend, shorts will gradually take profit and close positions, and the funding rate may slowly rise. But if the market gets any bullish catalyst, this negative funding rate will become fuel for a short-term rebound, because short covering can push prices higher.
I looked into it: the TradFi perpetual contracts segment where BSP is listed has recently lacked clear macro catalysts. Both the US stock market and on-chain assets are in a high-level range-bound churn. Overall risk appetite is average. Without an independent news driver, BSP’s price action is more likely being dragged by broader market sentiment rather than worsening fundamentals of its own.
The current data is based on a single-signal read, mainly relying on divergence between price and funding rate. If, over the next few hours, the price holds above 34.5 and the funding rate turns positive, then my view would be invalidated—that would mean shorts have surrendered and longs re-take control. Conversely, if the price breaks below 32 and the funding rate stays deeply negative, it suggests the short squeeze has failed and the downtrend could accelerate.
In terms of trade, I’m not touching this asset. A negative funding rate indicates shorts are crowded, but since price hasn’t moved, there’s no squeeze trigger. I’ll wait for one of two conditions to appear: either price breaks out above 34.5 with volume and funding turns positive—I’d consider a short-term long; or price breaks below 32 and OI doesn’t drop significantly—that could mean downside room is opening, and I’d look for opportunities to short a rebound. Between the two, holding just means absorbing the funding friction cost with no directional edge.
The market may be underestimating the liquidity-ailment risk in TradFi perpetuals when there’s a lack of narrative. If BSP continues to maintain this low-volatility, negative-funding state, it will gradually get sidelined. The real contrarian view is: with US stocks at highs and the crypto market lacking a clear main theme, the volatility compression in these small-cap TradFi perpetual contracts isn’t stability—it’s a warning sign of the next round of large volatility.
Trading tag: #TradFi #链上美股 #BSP
Where do you think this thesis is most likely to be wrong?
·
--
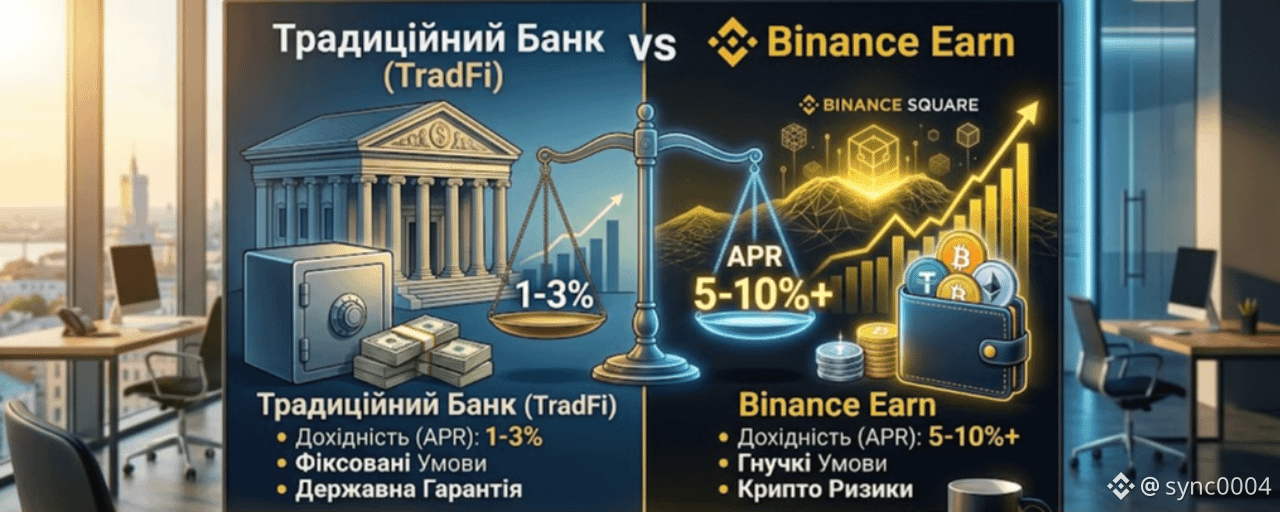
Article
Binance Earn vs. a bank deposit (TradFi): What’s more profitable?Let’s compare two popular ways to earn passive income: traditional bank deposits (TradFi) and Binance Earn. What are their key features?
1. Profitability (APR): Banks often offer 1–3% per year in foreign currency. In Binance Earn for stablecoins (e.g., USDT or USDC), the interest rate is often significantly higher (5–10% or more, depending on the market). 2. Flexibility: Breaking a fixed-term bank deposit without losing interest is almost impossible. With flexible Binance Earn products, you can withdraw your funds any second. 3. Entry threshold: A bank often requires a minimum deposit amount. On Binance, you can start earning interest with just a few dollars in your balance. 4. Risks: Banks have government guarantees, while crypto always carries smart-contract and market volatility risks.
Binance Earn vs. a bank deposit (TradFi): What’s more profitable?
Let’s compare two popular ways to earn passive income: traditional bank deposits (TradFi) and Binance Earn. What are their key features?
1. Profitability (APR): Banks often offer 1–3% per year in foreign currency. In Binance Earn for stablecoins (e.g., USDT or USDC), the interest rate is often significantly higher (5–10% or more, depending on the market). 2. Flexibility: Breaking a fixed-term bank deposit without losing interest is almost impossible. With flexible Binance Earn products, you can withdraw your funds any second. 3. Entry threshold: A bank often requires a minimum deposit amount. On Binance, you can start earning interest with just a few dollars in your balance. 4. Risks: Banks have government guarantees, while crypto always carries smart-contract and market volatility risks.
1. Profitability (APR): Banks often offer 1–3% per year in foreign currency. In Binance Earn for stablecoins (e.g., USDT or USDC), the interest rate is often significantly higher (5–10% or more, depending on the market). 2. Flexibility: Breaking a fixed-term bank deposit without losing interest is almost impossible. With flexible Binance Earn products, you can withdraw your funds any second. 3. Entry threshold: A bank often requires a minimum deposit amount. On Binance, you can start earning interest with just a few dollars in your balance. 4. Risks: Banks have government guarantees, while crypto always carries smart-contract and market volatility risks.
44
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BitcoinSpotETFsNetInflow$191M
41 views
18 Discussing
2
#CFTCUpdatesGuidanceOnTokenizedAssets
4,228 views
260 Discussing
3
#BitgetSays$352MAffectedInHack
551 views
14 Discussing
4
#BinanceWillListHyperliquid(HYPE)
175,292 views
2,869 Discussing
5
#BrazilOrdersReportingOf$10KSelfCustodyTransfers
532 views
14 Discussing
6
#FedProposesRulesForBankIssuedStablecoins
6,080 views
242 Discussing
7
#OndoFinanceSoughtSaleAfterFoundersDeath
4,488 views
168 Discussing
8
#FedOctoberRateHikeOddsRiseTo69.7%
65,455 views
1,226 Discussing
9
#BitcoinFallsBelow$83,000
4,744 views
20 Discussing
10
#BitcoinFallsToAround$84,600ThisWeek
0 views
0 Discussing