
#stocks
stocks
4.9M views
12,461 Discussing
Hot
Latest

·
--
Bullish
Verified
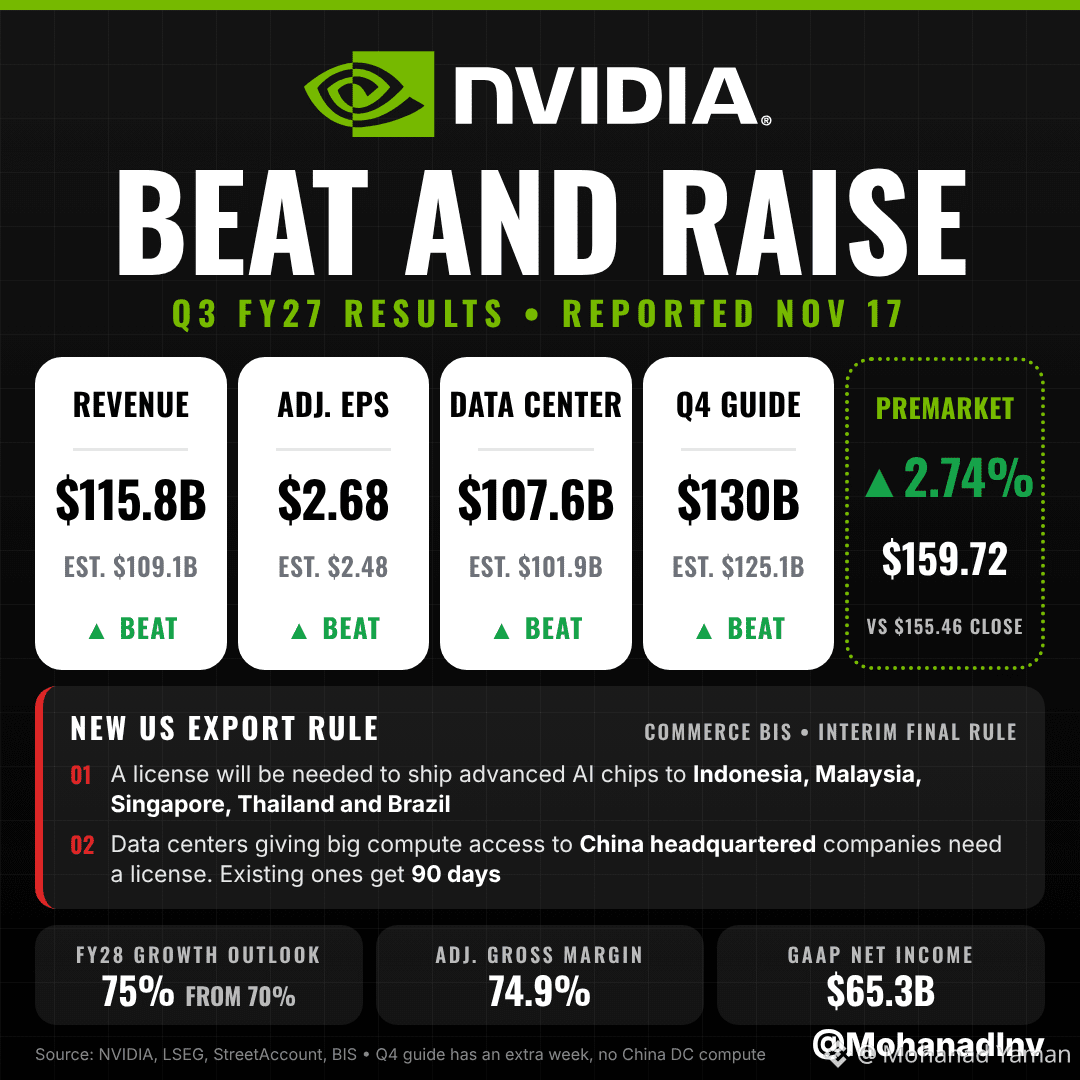
$NVDA beat on every line and raised, and it's up 2.74% premarket 👀
🔹 Revenue $115.8B vs $109.1B expected, ▲103% YoY
🔹 Adjusted EPS $2.68 vs $2.48 expected
🔹 Data Center $107.6B vs $101.9B expected, ▲110%
🔹 Q4 guide $130B vs $125.1B expected, with an extra week and no China data center compute
🔹 FY28 growth outlook raised to about 75% from 70%
🔹 Board says it won't reinstate Jensen Huang
The catch: a new US rule will require licenses to ship advanced AI chips to Indonesia, Malaysia, Singapore, Thailand and Brazil, and to data centers giving big compute to China headquartered firms. Existing ones get 90 days
Premarket it's at $159.72 vs Tuesday's $155.46 close. Wednesday's close settles it
Does the beat outweigh the new export rule? 👇
#stocks
{spot}(NVDABUSDT)
$NVDA beat on every line and raised, and it's up 2.74% premarket 👀
🔹 Revenue $115.8B vs $109.1B expected, ▲103% YoY
🔹 Adjusted EPS $2.68 vs $2.48 expected
🔹 Data Center $107.6B vs $101.9B expected, ▲110%
🔹 Q4 guide $130B vs $125.1B expected, with an extra week and no China data center compute
🔹 FY28 growth outlook raised to about 75% from 70%
🔹 Board says it won't reinstate Jensen Huang
The catch: a new US rule will require licenses to ship advanced AI chips to Indonesia, Malaysia, Singapore, Thailand and Brazil, and to data centers giving big compute to China headquartered firms. Existing ones get 90 days
Premarket it's at $159.72 vs Tuesday's $155.46 close. Wednesday's close settles it
Does the beat outweigh the new export rule? 👇
#stocks
🔹 Revenue $115.8B vs $109.1B expected, ▲103% YoY
🔹 Adjusted EPS $2.68 vs $2.48 expected
🔹 Data Center $107.6B vs $101.9B expected, ▲110%
🔹 Q4 guide $130B vs $125.1B expected, with an extra week and no China data center compute
🔹 FY28 growth outlook raised to about 75% from 70%
🔹 Board says it won't reinstate Jensen Huang
The catch: a new US rule will require licenses to ship advanced AI chips to Indonesia, Malaysia, Singapore, Thailand and Brazil, and to data centers giving big compute to China headquartered firms. Existing ones get 90 days
Premarket it's at $159.72 vs Tuesday's $155.46 close. Wednesday's close settles it
Does the beat outweigh the new export rule? 👇
#stocks
2
1.2k


Verified
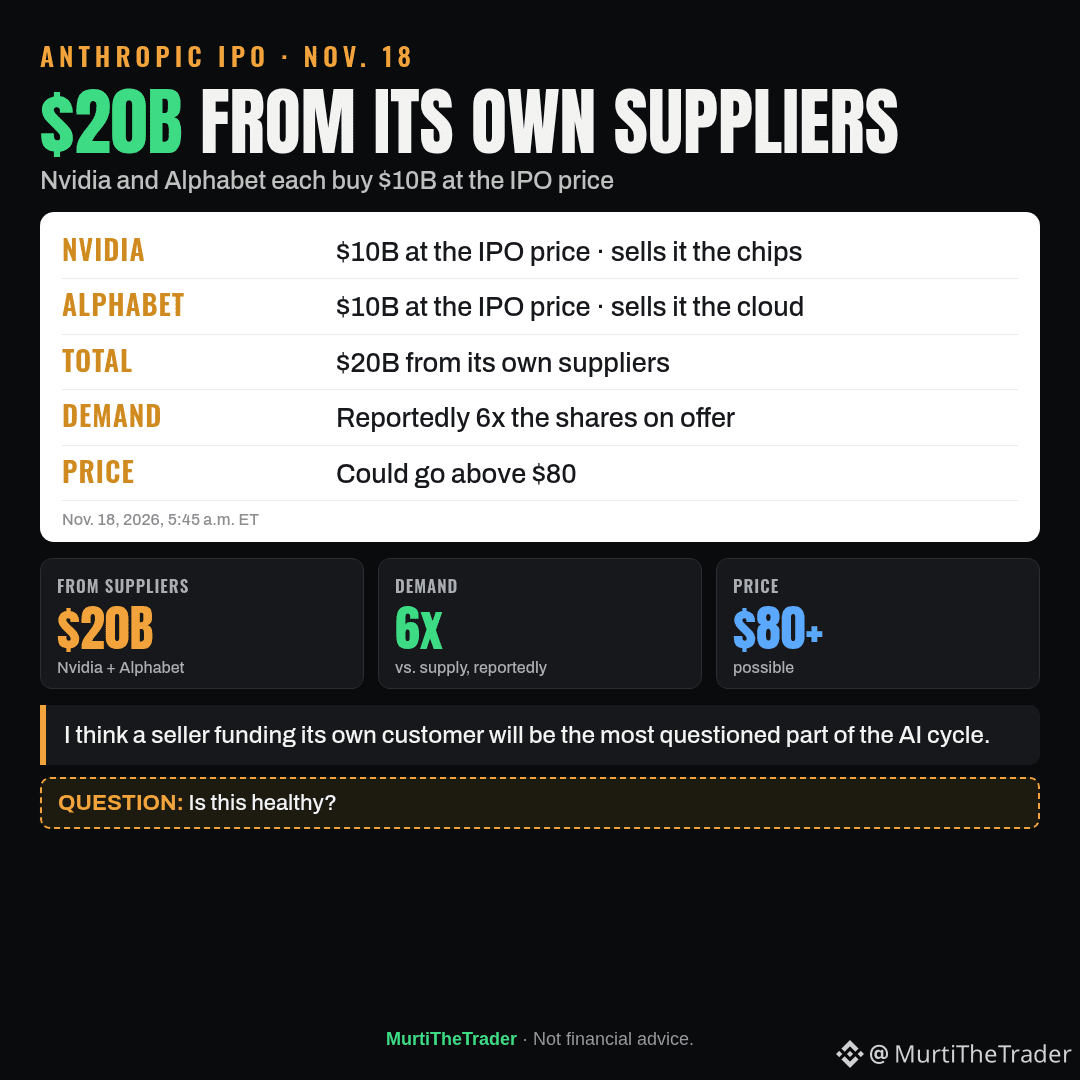
In Anthropic's IPO, $20B of the shares are going to its own suppliers.
Nvidia and Alphabet will each buy $10B at the IPO price; one sells it the chips, the other the cloud. Demand is reportedly 6 times the shares on offer, and the price could go above $80.
I think a seller funding its own customer will be the most questioned part of the AI cycle. Do you think this is healthy?
#AI #Stocks
Watching: $NVDA $GOOGL $QQQ
In Anthropic's IPO, $20B of the shares are going to its own suppliers.
Nvidia and Alphabet will each buy $10B at the IPO price; one sells it the chips, the other the cloud. Demand is reportedly 6 times the shares on offer, and the price could go above $80.
I think a seller funding its own customer will be the most questioned part of the AI cycle. Do you think this is healthy?
#AI #Stocks
Watching: $NVDA $GOOGL $QQQ
Nvidia and Alphabet will each buy $10B at the IPO price; one sells it the chips, the other the cloud. Demand is reportedly 6 times the shares on offer, and the price could go above $80.
I think a seller funding its own customer will be the most questioned part of the AI cycle. Do you think this is healthy?
#AI #Stocks
Watching: $NVDA $GOOGL $QQQ
851
·
--
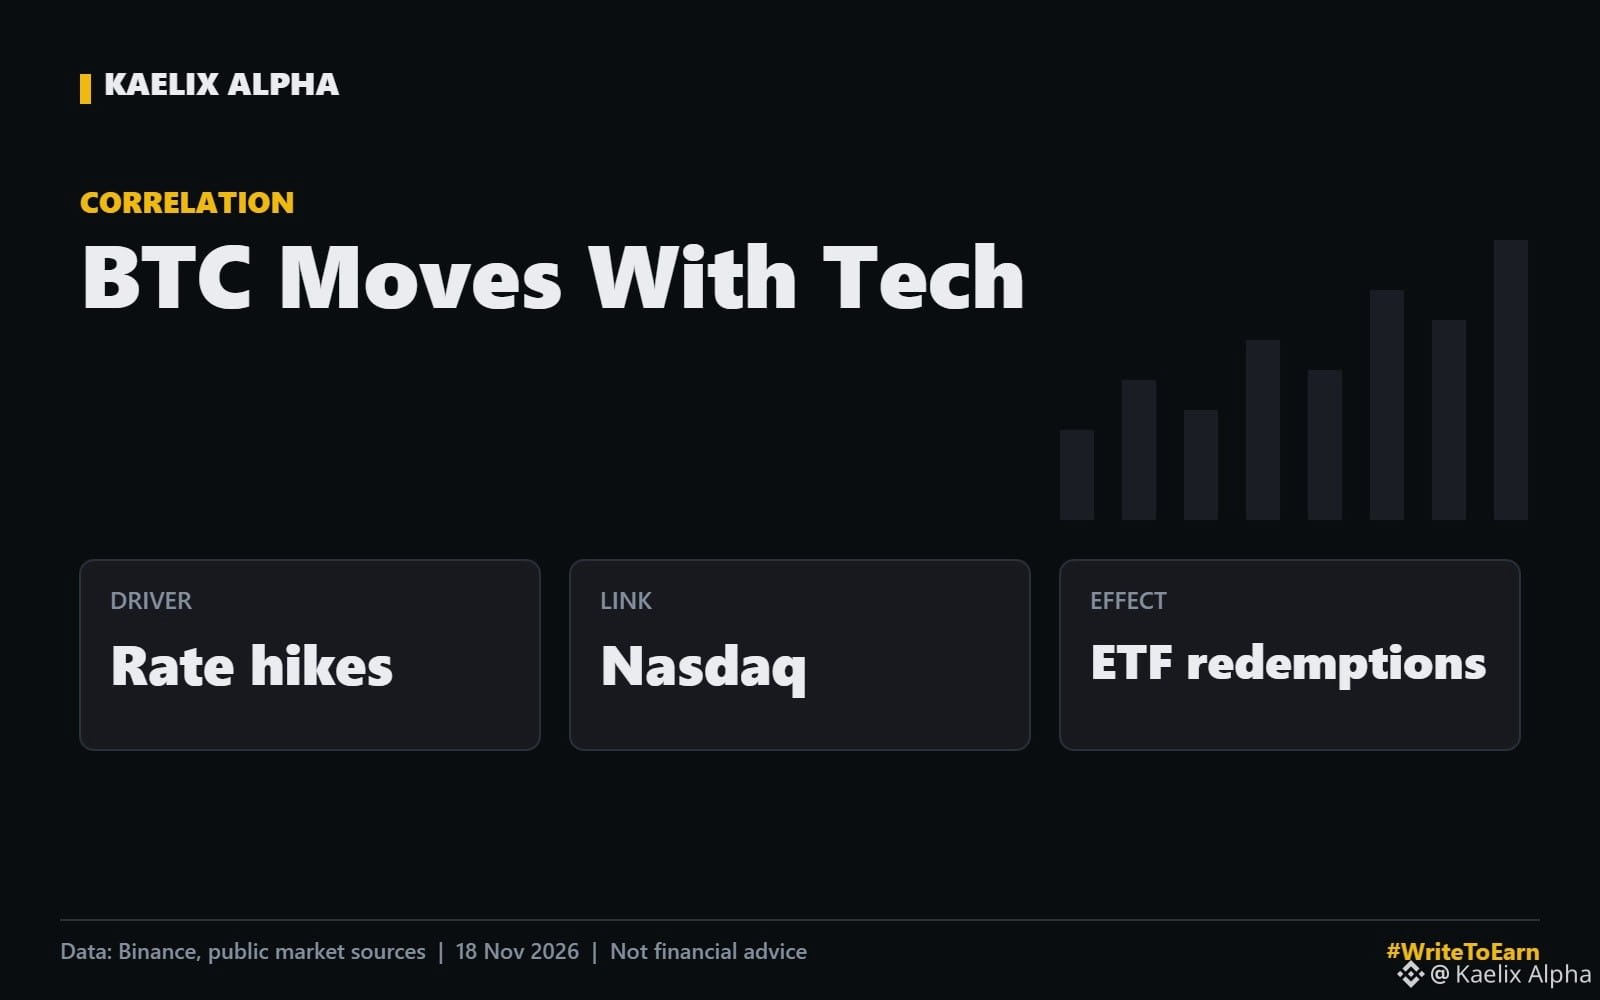
𝗕𝗜𝗧𝗖𝗢𝗜𝗡 𝗜𝗦 𝗧𝗥𝗔𝗗𝗜𝗡𝗚 𝗟𝗜𝗞𝗘 𝗔 𝗧𝗘𝗖𝗛 𝗦𝗧𝗢𝗖𝗞. 𝗛𝗘𝗥𝗘 𝗜𝗦 𝗧𝗛𝗘 𝗣𝗥𝗢𝗢𝗙.
"Digital gold" is not how the market is treating Bitcoin this month.
𝗧𝗵𝗲 𝗲𝘃𝗶𝗱𝗲𝗻𝗰𝗲
Bitcoin's correlation with tech stocks has been high in November. On 5 November, a sharp Nasdaq 100 drop lined up with about $430 million of Bitcoin ETF outflows (TradingNEWS). When tech sells off, allocators cut risk across the board, and BTC is on that list.
𝗪𝗵𝗮𝘁 𝗶𝘁 𝗺𝗲𝗮𝗻𝘀 𝗳𝗼𝗿 𝘁𝗿𝗮𝗱𝗲𝗿𝘀
Big tech earnings and rate expectations now matter for crypto. You cannot read the BTC chart in isolation.
𝗪𝗵𝗮𝘁 𝗯𝗿𝗲𝗮𝗸𝘀 𝘁𝗵𝗲 𝗹𝗶𝗻𝗸
A crypto-specific catalyst, like strong ETF inflows or a policy win, can decouple Bitcoin. Until then, keep one eye on the Nasdaq.
Do you check stock markets before trading crypto?
$BTC
#WriteToEarn #Write2Earn #Bitcoin #Macro #Stocks
Not financial advice. Do your own research.
𝗕𝗜𝗧𝗖𝗢𝗜𝗡 𝗜𝗦 𝗧𝗥𝗔𝗗𝗜𝗡𝗚 𝗟𝗜𝗞𝗘 𝗔 𝗧𝗘𝗖𝗛 𝗦𝗧𝗢𝗖𝗞. 𝗛𝗘𝗥𝗘 𝗜𝗦 𝗧𝗛𝗘 𝗣𝗥𝗢𝗢𝗙.
"Digital gold" is not how the market is treating Bitcoin this month.
𝗧𝗵𝗲 𝗲𝘃𝗶𝗱𝗲𝗻𝗰𝗲
Bitcoin's correlation with tech stocks has been high in November. On 5 November, a sharp Nasdaq 100 drop lined up with about $430 million of Bitcoin ETF outflows (TradingNEWS). When tech sells off, allocators cut risk across the board, and BTC is on that list.
𝗪𝗵𝗮𝘁 𝗶𝘁 𝗺𝗲𝗮𝗻𝘀 𝗳𝗼𝗿 𝘁𝗿𝗮𝗱𝗲𝗿𝘀
Big tech earnings and rate expectations now matter for crypto. You cannot read the BTC chart in isolation.
𝗪𝗵𝗮𝘁 𝗯𝗿𝗲𝗮𝗸𝘀 𝘁𝗵𝗲 𝗹𝗶𝗻𝗸
A crypto-specific catalyst, like strong ETF inflows or a policy win, can decouple Bitcoin. Until then, keep one eye on the Nasdaq.
Do you check stock markets before trading crypto?
$BTC
#WriteToEarn #Write2Earn #Bitcoin #Macro #Stocks
Not financial advice. Do your own research.
"Digital gold" is not how the market is treating Bitcoin this month.
𝗧𝗵𝗲 𝗲𝘃𝗶𝗱𝗲𝗻𝗰𝗲
Bitcoin's correlation with tech stocks has been high in November. On 5 November, a sharp Nasdaq 100 drop lined up with about $430 million of Bitcoin ETF outflows (TradingNEWS). When tech sells off, allocators cut risk across the board, and BTC is on that list.
𝗪𝗵𝗮𝘁 𝗶𝘁 𝗺𝗲𝗮𝗻𝘀 𝗳𝗼𝗿 𝘁𝗿𝗮𝗱𝗲𝗿𝘀
Big tech earnings and rate expectations now matter for crypto. You cannot read the BTC chart in isolation.
𝗪𝗵𝗮𝘁 𝗯𝗿𝗲𝗮𝗸𝘀 𝘁𝗵𝗲 𝗹𝗶𝗻𝗸
A crypto-specific catalyst, like strong ETF inflows or a policy win, can decouple Bitcoin. Until then, keep one eye on the Nasdaq.
Do you check stock markets before trading crypto?
$BTC
#WriteToEarn #Write2Earn #Bitcoin #Macro #Stocks
Not financial advice. Do your own research.
29
·
--
Bullish
🚀 I'M HOLDING $SOXL — MY TARGET IS $100!
I'm staying LONG on $SOXL because I believe the semiconductor sector still has room for a bigger recovery.
Current price: $51.98
The chart is showing a recovery attempt after bouncing from the $43–$46 support area. Now I'm watching whether price can reclaim $56 and build momentum toward the $65 zone.
My bigger target remains $100. 🎯
I'm holding my LONG position with that target in mind. This is my personal market view, not a guaranteed outcome. SOXL is highly volatile, so the journey could be rough.
Who's holding SOXL for the bigger move?
{future}(SOXLUSDT)
#SOXL #Semiconductor #Stocks #Long
🚀 I'M HOLDING $SOXL — MY TARGET IS $100!
I'm staying LONG on $SOXL because I believe the semiconductor sector still has room for a bigger recovery.
Current price: $51.98
The chart is showing a recovery attempt after bouncing from the $43–$46 support area. Now I'm watching whether price can reclaim $56 and build momentum toward the $65 zone.
My bigger target remains $100. 🎯
I'm holding my LONG position with that target in mind. This is my personal market view, not a guaranteed outcome. SOXL is highly volatile, so the journey could be rough.
Who's holding SOXL for the bigger move?
#SOXL #Semiconductor #Stocks #Long
I'm staying LONG on $SOXL because I believe the semiconductor sector still has room for a bigger recovery.
Current price: $51.98
The chart is showing a recovery attempt after bouncing from the $43–$46 support area. Now I'm watching whether price can reclaim $56 and build momentum toward the $65 zone.
My bigger target remains $100. 🎯
I'm holding my LONG position with that target in mind. This is my personal market view, not a guaranteed outcome. SOXL is highly volatile, so the journey could be rough.
Who's holding SOXL for the bigger move?
#SOXL #Semiconductor #Stocks #Long
牛批plus:
整体趋势好像往下走唉
2
1
568

·
--
📰 Siebert pegs MSCI-driven selling of Strategy at 13 million shares
The MSCI exclusion may reduce passive investment demand, impacting Strategy's stock liquidity and potentially influencing Bitcoin sentiment. The post Siebert pegs MSCI-driven selling of Strategy at 13 million shares appeared first on Crypto Briefing.
Source : Crypto Briefing
Time : 2026-11-17 20:26:31
Credit : vivian nguyen
#stocks
$BTC
Share your opinion in the comment section below
📰 Siebert pegs MSCI-driven selling of Strategy at 13 million shares
The MSCI exclusion may reduce passive investment demand, impacting Strategy's stock liquidity and potentially influencing Bitcoin sentiment. The post Siebert pegs MSCI-driven selling of Strategy at 13 million shares appeared first on Crypto Briefing.
Source : Crypto Briefing
Time : 2026-11-17 20:26:31
Credit : vivian nguyen
#stocks
$BTC
Share your opinion in the comment section below
The MSCI exclusion may reduce passive investment demand, impacting Strategy's stock liquidity and potentially influencing Bitcoin sentiment. The post Siebert pegs MSCI-driven selling of Strategy at 13 million shares appeared first on Crypto Briefing.
Source : Crypto Briefing
Time : 2026-11-17 20:26:31
Credit : vivian nguyen
#stocks
$BTC
Share your opinion in the comment section below

·
--
Verified
NVIDIA's Earnings Repriced AI Risk. They Didn't Remove It.
Asian chip stocks rebounded after NVIDIA reported $115.8B in quarterly revenue and guided for $130B next quarter.
SK hynix gained over 6% in early Korean trading, Samsung Electronics around 4.6%. Tokyo Electron and SoftBank also opened higher.
The cross-market signal is interesting: the Dow, S&P 500 and Nasdaq all closed lower overnight, while the Philadelphia Semiconductor Index managed a 0.34% gain.
Capital is returning selectively to the AI supply chain, not indiscriminately to equities.
But the rally answers only one question: near-term accelerator demand remains strong.
It does not settle the harder questions around HBM supply growth, GPU financing economics, neocloud cash conversion or Rubin margins.
The next phase of the AI trade will depend less on whether hyperscalers keep spending, and more on whether that spending produces sustainable returns across the supply chain.
#stocks
$NVDA.US
{stock_us}(NVDA.US)
NVIDIA's Earnings Repriced AI Risk. They Didn't Remove It.
Asian chip stocks rebounded after NVIDIA reported $115.8B in quarterly revenue and guided for $130B next quarter.
SK hynix gained over 6% in early Korean trading, Samsung Electronics around 4.6%. Tokyo Electron and SoftBank also opened higher.
The cross-market signal is interesting: the Dow, S&P 500 and Nasdaq all closed lower overnight, while the Philadelphia Semiconductor Index managed a 0.34% gain.
Capital is returning selectively to the AI supply chain, not indiscriminately to equities.
But the rally answers only one question: near-term accelerator demand remains strong.
It does not settle the harder questions around HBM supply growth, GPU financing economics, neocloud cash conversion or Rubin margins.
The next phase of the AI trade will depend less on whether hyperscalers keep spending, and more on whether that spending produces sustainable returns across the supply chain.
#stocks
$NVDA.US
Asian chip stocks rebounded after NVIDIA reported $115.8B in quarterly revenue and guided for $130B next quarter.
SK hynix gained over 6% in early Korean trading, Samsung Electronics around 4.6%. Tokyo Electron and SoftBank also opened higher.
The cross-market signal is interesting: the Dow, S&P 500 and Nasdaq all closed lower overnight, while the Philadelphia Semiconductor Index managed a 0.34% gain.
Capital is returning selectively to the AI supply chain, not indiscriminately to equities.
But the rally answers only one question: near-term accelerator demand remains strong.
It does not settle the harder questions around HBM supply growth, GPU financing economics, neocloud cash conversion or Rubin margins.
The next phase of the AI trade will depend less on whether hyperscalers keep spending, and more on whether that spending produces sustainable returns across the supply chain.
#stocks
$NVDA.US
NVDAUS+2.79%
1.1k
·
--
Verified
IREN: The Real Advantage Isn't 5GW of Power. It's Who Funds the GPUs.
$IREN reported $200M in quarterly AI Cloud revenue, up 182% sequentially, with $20.3B in contracted revenue backlog.
Its secured power exceeds 5GW. But power alone doesn't make the stock cheap.
The more important question is who funds the expansion.
IREN says its roughly 300MW deployment, targeting over $4B in annualized revenue, is fully contracted and funded. One five-year contract generates approximately $22M per IT-MW annually, with customer prepayments covering 90% of associated GPU capex.
Yet the company still faces $15B in planned FY27 capex, including $6B dependent on additional financing and other sources.
Dilution is already substantial: IREN raised approximately $3.7B through its current ATM program by October 30, issuing 76.8M shares.
And its reported 86% AI Cloud segment gross margin excludes depreciation and site-level costs.
My thesis: IREN's real advantage isn't the power it controls, but how much customer-funded cash flow it can generate per diluted share after capital costs.
Watch commissioned MW, recognized revenue, financing costs and share count.
Power creates capacity. Capital allocation determines shareholder returns.
#stocks
$IREN.US
{stock_us}(IREN.US)
IREN: The Real Advantage Isn't 5GW of Power. It's Who Funds the GPUs.
$IREN reported $200M in quarterly AI Cloud revenue, up 182% sequentially, with $20.3B in contracted revenue backlog.
Its secured power exceeds 5GW. But power alone doesn't make the stock cheap.
The more important question is who funds the expansion.
IREN says its roughly 300MW deployment, targeting over $4B in annualized revenue, is fully contracted and funded. One five-year contract generates approximately $22M per IT-MW annually, with customer prepayments covering 90% of associated GPU capex.
Yet the company still faces $15B in planned FY27 capex, including $6B dependent on additional financing and other sources.
Dilution is already substantial: IREN raised approximately $3.7B through its current ATM program by October 30, issuing 76.8M shares.
And its reported 86% AI Cloud segment gross margin excludes depreciation and site-level costs.
My thesis: IREN's real advantage isn't the power it controls, but how much customer-funded cash flow it can generate per diluted share after capital costs.
Watch commissioned MW, recognized revenue, financing costs and share count.
Power creates capacity. Capital allocation determines shareholder returns.
#stocks
$IREN.US
$IREN reported $200M in quarterly AI Cloud revenue, up 182% sequentially, with $20.3B in contracted revenue backlog.
Its secured power exceeds 5GW. But power alone doesn't make the stock cheap.
The more important question is who funds the expansion.
IREN says its roughly 300MW deployment, targeting over $4B in annualized revenue, is fully contracted and funded. One five-year contract generates approximately $22M per IT-MW annually, with customer prepayments covering 90% of associated GPU capex.
Yet the company still faces $15B in planned FY27 capex, including $6B dependent on additional financing and other sources.
Dilution is already substantial: IREN raised approximately $3.7B through its current ATM program by October 30, issuing 76.8M shares.
And its reported 86% AI Cloud segment gross margin excludes depreciation and site-level costs.
My thesis: IREN's real advantage isn't the power it controls, but how much customer-funded cash flow it can generate per diluted share after capital costs.
Watch commissioned MW, recognized revenue, financing costs and share count.
Power creates capacity. Capital allocation determines shareholder returns.
#stocks
$IREN.US
IRENUS+4.02%
973
·
--
📰 CoinShares Valkyrie Bitcoin Fund (NASDAQ:BRRR) Stock Short Interest Report for October
CoinShares Valkyrie Bitcoin Fund (NASDAQ:BRRR – Get Free Report) was the recipient of a large drop in short interest during the month of October. As of October 30th, there was short interest totaling 67,728 shares, a drop of 45.2% from the October 15th total of 123,543 shares. Currently, 0.3% of the shares of the company […]
Source : The Lincolnian Online
Time : 2026-11-17 19:43:22
Credit : anthony miller
#options_articles #stocks
$BTC
Share your opinion in the comment section below
📰 CoinShares Valkyrie Bitcoin Fund (NASDAQ:BRRR) Stock Short Interest Report for October
CoinShares Valkyrie Bitcoin Fund (NASDAQ:BRRR – Get Free Report) was the recipient of a large drop in short interest during the month of October. As of October 30th, there was short interest totaling 67,728 shares, a drop of 45.2% from the October 15th total of 123,543 shares. Currently, 0.3% of the shares of the company […]
Source : The Lincolnian Online
Time : 2026-11-17 19:43:22
Credit : anthony miller
#options_articles #stocks
$BTC
Share your opinion in the comment section below
CoinShares Valkyrie Bitcoin Fund (NASDAQ:BRRR – Get Free Report) was the recipient of a large drop in short interest during the month of October. As of October 30th, there was short interest totaling 67,728 shares, a drop of 45.2% from the October 15th total of 123,543 shares. Currently, 0.3% of the shares of the company […]
Source : The Lincolnian Online
Time : 2026-11-17 19:43:22
Credit : anthony miller
#options_articles #stocks
$BTC
Share your opinion in the comment section below
·
--
📰 CoinShares Valkyrie Bitcoin Fund (NASDAQ:BRRR) Stock Short Interest Report for October
CoinShares Valkyrie Bitcoin Fund (NASDAQ:BRRR – Get Free Report) was the recipient of a large drop in short interest during the month of October. As of October 30th, there was short interest totaling 67,728 shares, a drop of 45.2% from the October 15th total of 123,543 shares. Currently, 0.3% of the shares of the company […]
Source : The Lincolnian Online
Time : 2026-11-17 19:43:22
Credit : anthony miller
#options_articles #stocks
$BTC
Share your opinion in the comment section below
📰 CoinShares Valkyrie Bitcoin Fund (NASDAQ:BRRR) Stock Short Interest Report for October
CoinShares Valkyrie Bitcoin Fund (NASDAQ:BRRR – Get Free Report) was the recipient of a large drop in short interest during the month of October. As of October 30th, there was short interest totaling 67,728 shares, a drop of 45.2% from the October 15th total of 123,543 shares. Currently, 0.3% of the shares of the company […]
Source : The Lincolnian Online
Time : 2026-11-17 19:43:22
Credit : anthony miller
#options_articles #stocks
$BTC
Share your opinion in the comment section below
CoinShares Valkyrie Bitcoin Fund (NASDAQ:BRRR – Get Free Report) was the recipient of a large drop in short interest during the month of October. As of October 30th, there was short interest totaling 67,728 shares, a drop of 45.2% from the October 15th total of 123,543 shares. Currently, 0.3% of the shares of the company […]
Source : The Lincolnian Online
Time : 2026-11-17 19:43:22
Credit : anthony miller
#options_articles #stocks
$BTC
Share your opinion in the comment section below
·
--
AI Is Changing Big Tech's Capital Allocation Model
For years, the largest technology companies could fund growth while returning substantial cash to shareholders.
AI infrastructure is changing that equation.
Alphabet spent $132B on cash capex in the first nine months of 2026, exceeding its $127B in operating cash flow. It repurchased no shares.
Meta's buybacks fell from $26.2B in the first nine months of 2025 to zero in 2026, while cash purchases of property and equipment rose from $48.3B to $83.1B.
Oracle raised $19.9B through an equity offering in its August quarter.
These are not signs that AI demand has collapsed. They show how much capital is required to supply it.
My thesis: AI could generate enormous industry revenue while delivering a much smaller increase in free cash flow per share for the companies funding the buildout.
NVIDIA captures revenue as infrastructure is purchased. Its customers must earn returns over years, while absorbing depreciation, financing costs and hardware replacement.
The next test isn't another capex increase.
It's whether incremental AI revenue can restore free cash flow per share without continued external financing.
AI growth and shareholder value creation are not the same metric.
#stocks
$ANTHROPIC $NVDA.US
$META.US
{stock_us}(META.US)
AI Is Changing Big Tech's Capital Allocation Model
For years, the largest technology companies could fund growth while returning substantial cash to shareholders.
AI infrastructure is changing that equation.
Alphabet spent $132B on cash capex in the first nine months of 2026, exceeding its $127B in operating cash flow. It repurchased no shares.
Meta's buybacks fell from $26.2B in the first nine months of 2025 to zero in 2026, while cash purchases of property and equipment rose from $48.3B to $83.1B.
Oracle raised $19.9B through an equity offering in its August quarter.
These are not signs that AI demand has collapsed. They show how much capital is required to supply it.
My thesis: AI could generate enormous industry revenue while delivering a much smaller increase in free cash flow per share for the companies funding the buildout.
NVIDIA captures revenue as infrastructure is purchased. Its customers must earn returns over years, while absorbing depreciation, financing costs and hardware replacement.
The next test isn't another capex increase.
It's whether incremental AI revenue can restore free cash flow per share without continued external financing.
AI growth and shareholder value creation are not the same metric.
#stocks
$ANTHROPIC $NVDA.US
$META.US
For years, the largest technology companies could fund growth while returning substantial cash to shareholders.
AI infrastructure is changing that equation.
Alphabet spent $132B on cash capex in the first nine months of 2026, exceeding its $127B in operating cash flow. It repurchased no shares.
Meta's buybacks fell from $26.2B in the first nine months of 2025 to zero in 2026, while cash purchases of property and equipment rose from $48.3B to $83.1B.
Oracle raised $19.9B through an equity offering in its August quarter.
These are not signs that AI demand has collapsed. They show how much capital is required to supply it.
My thesis: AI could generate enormous industry revenue while delivering a much smaller increase in free cash flow per share for the companies funding the buildout.
NVIDIA captures revenue as infrastructure is purchased. Its customers must earn returns over years, while absorbing depreciation, financing costs and hardware replacement.
The next test isn't another capex increase.
It's whether incremental AI revenue can restore free cash flow per share without continued external financing.
AI growth and shareholder value creation are not the same metric.
#stocks
$ANTHROPIC $NVDA.US
$META.US
296
·
--
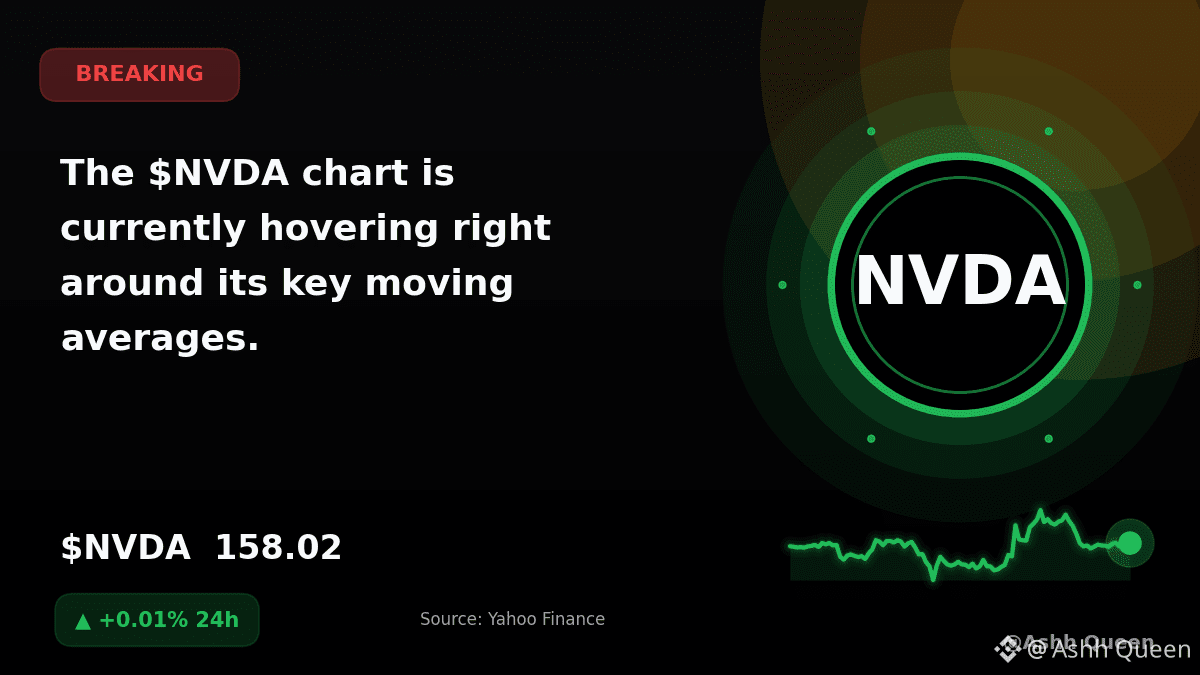
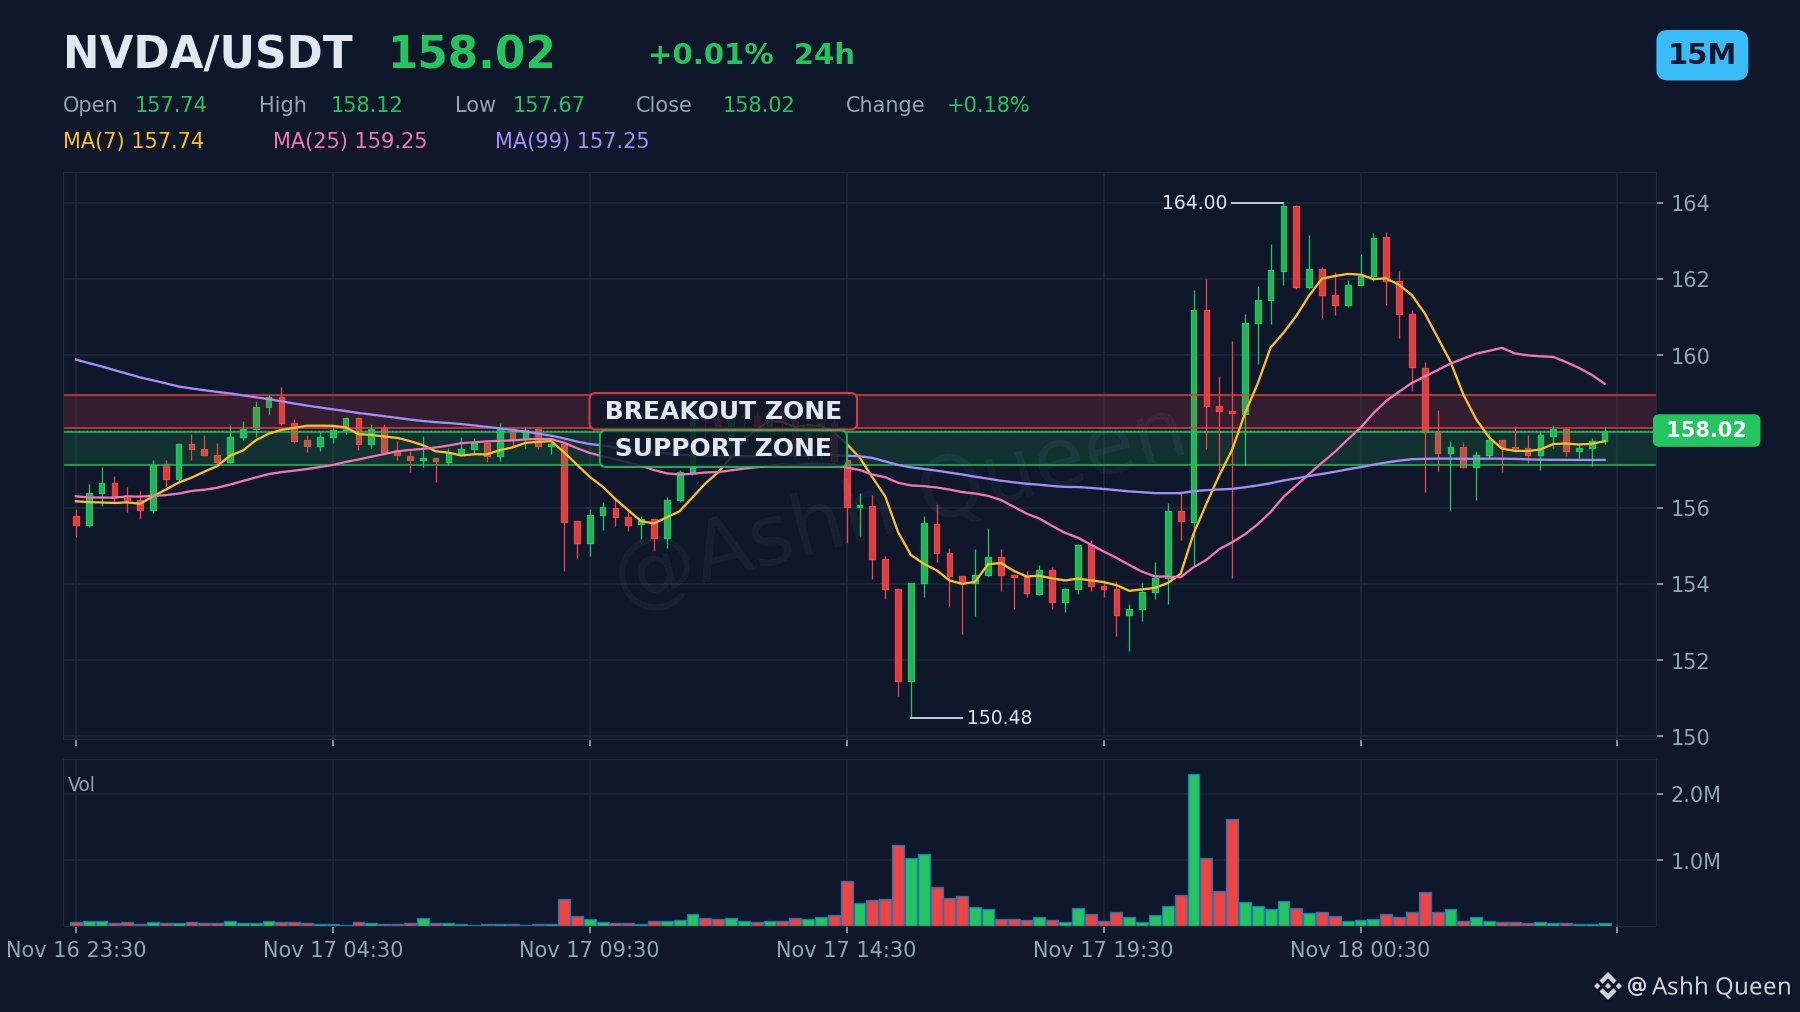
The $NVDA chart is currently hovering right around its key moving averages.
Yahoo Finance reports that the company’s recent earnings performance carries a significant risk for retirement portfolios due to potential volatility. Markets remain focused on the broader technology sector's movement following these results.
The $NVDA perpetual contract is priced at 158.02 with a 24h change of +0.01%. It is currently testing support at 157.54.
How do you interpret this volatility in the context of wider market trends and why? ⚠️ 🛡️ 🧐
#NVDA #Stocks #HuangExitNvidiaStrategyInFocus #NVDAStock
⚠️ Perpetual contracts are leveraged derivatives, not the stock or commodity itself.
DYOR. Size positions carefully and never trade with money you cannot afford to lose.
The $NVDA chart is currently hovering right around its key moving averages.
Yahoo Finance reports that the company’s recent earnings performance carries a significant risk for retirement portfolios due to potential volatility. Markets remain focused on the broader technology sector's movement following these results.
The $NVDA perpetual contract is priced at 158.02 with a 24h change of +0.01%. It is currently testing support at 157.54.
How do you interpret this volatility in the context of wider market trends and why? ⚠️ 🛡️ 🧐
#NVDA #Stocks #HuangExitNvidiaStrategyInFocus #NVDAStock
⚠️ Perpetual contracts are leveraged derivatives, not the stock or commodity itself.
DYOR. Size positions carefully and never trade with money you cannot afford to lose.
Yahoo Finance reports that the company’s recent earnings performance carries a significant risk for retirement portfolios due to potential volatility. Markets remain focused on the broader technology sector's movement following these results.
The $NVDA perpetual contract is priced at 158.02 with a 24h change of +0.01%. It is currently testing support at 157.54.
How do you interpret this volatility in the context of wider market trends and why? ⚠️ 🛡️ 🧐
#NVDA #Stocks #HuangExitNvidiaStrategyInFocus #NVDAStock
⚠️ Perpetual contracts are leveraged derivatives, not the stock or commodity itself.
DYOR. Size positions carefully and never trade with money you cannot afford to lose.
3
·
--
Bullish
Verified
Before tonight, you pay less per dollar of profit for $NVDA than for Walmart 🛒
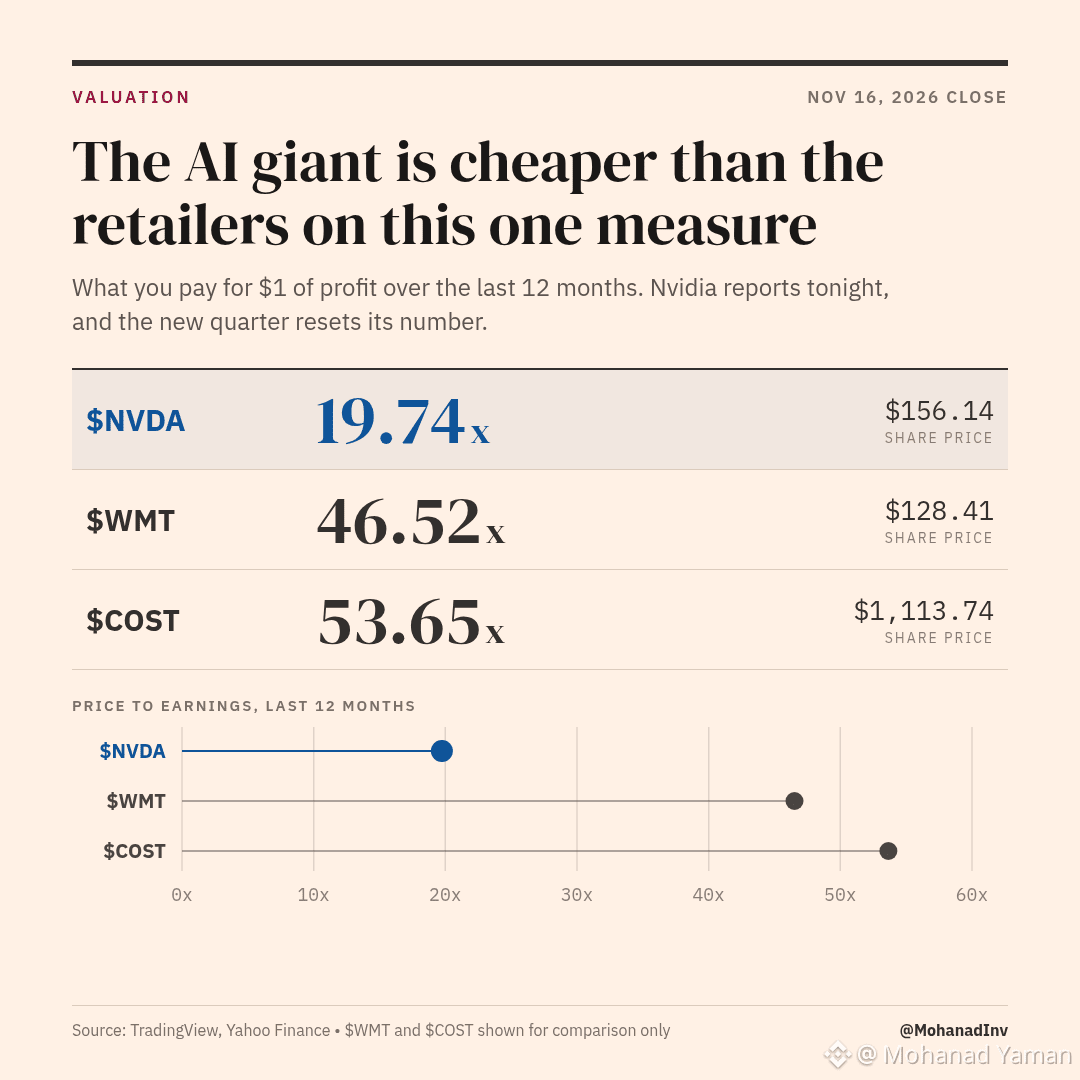
Price to earnings, last 12 months:
🔹 $NVDA 19.74x at $156.14
🔹 $WMT 46.52x at $128.41
🔹 $COST 53.65x at $1,113.74
The AI giant is cheaper than the retailers on this one measure. Tonight's report resets Nvidia's number
Will it stay this cheap in 2027?
#stocks
{spot}(NVDABUSDT)
Before tonight, you pay less per dollar of profit for $NVDA than for Walmart 🛒
Price to earnings, last 12 months:
🔹 $NVDA 19.74x at $156.14
🔹 $WMT 46.52x at $128.41
🔹 $COST 53.65x at $1,113.74
The AI giant is cheaper than the retailers on this one measure. Tonight's report resets Nvidia's number
Will it stay this cheap in 2027?
#stocks
Price to earnings, last 12 months:
🔹 $NVDA 19.74x at $156.14
🔹 $WMT 46.52x at $128.41
🔹 $COST 53.65x at $1,113.74
The AI giant is cheaper than the retailers on this one measure. Tonight's report resets Nvidia's number
Will it stay this cheap in 2027?
#stocks
1
2.6k
·
--
Bullish
Verified
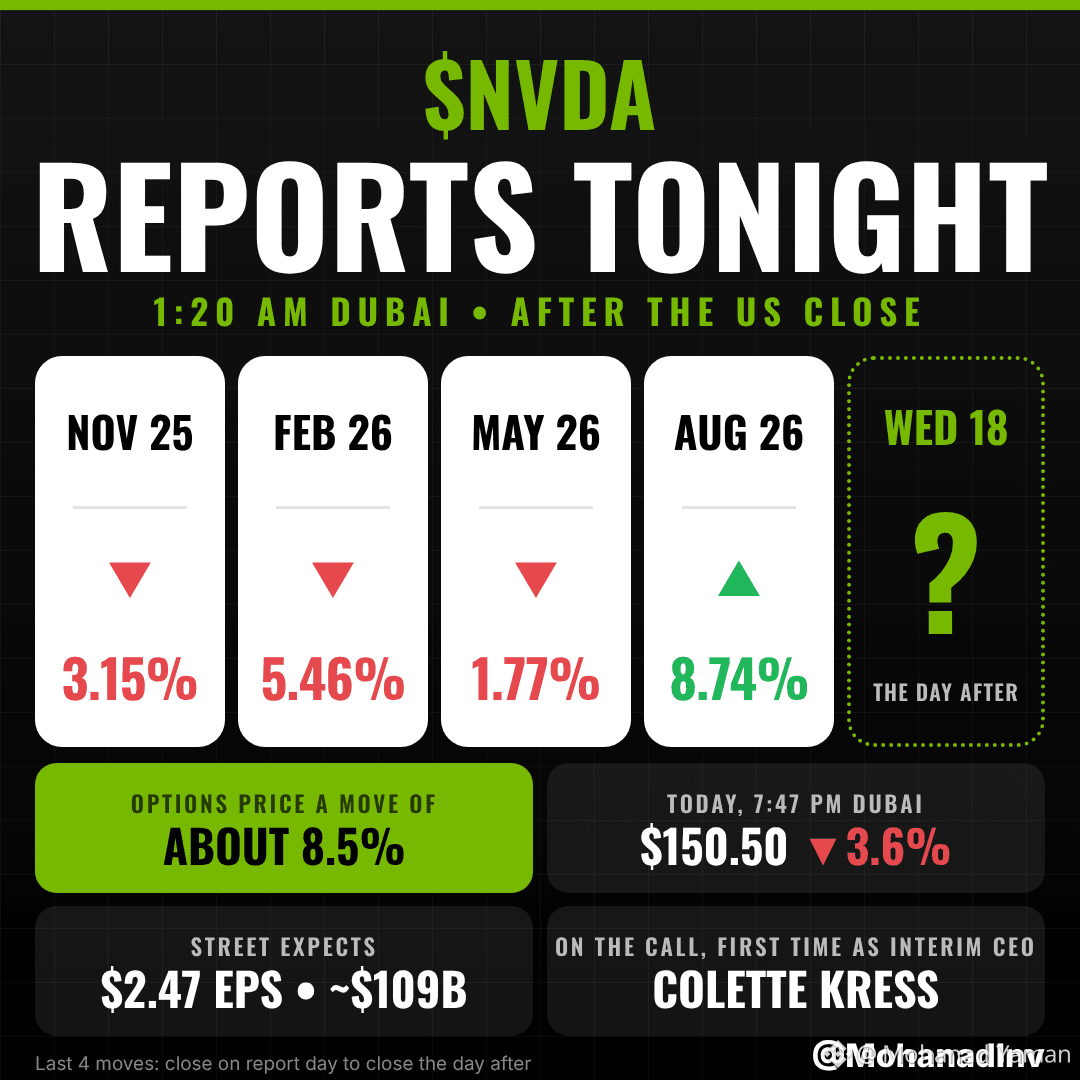
A few hours to go. $NVDA reports after the US close, and it's sliding into it ⏳
🔹 Options price a move of about 8.5% either way
🔹 The Street wants $2.47 EPS on about $109B, vs Nvidia's own $108B guide
🔹 Colette Kress leads the call for the first time as interim CEO
🔹 $NVDA ▼3.6% today at $150.50, about 37% under its $239.24 record close from Oct 6
🔹 The AI trade is red too: $TSM ▼4.8%, $AMD ▼3.6%
Wednesday's close settles it
Beat and bounce, or another sell the news? 👇
⚠️ Past performance is not an indication of future results. Not investment advice, your capital is at risk
#stocks
{spot}(NVDABUSDT)
A few hours to go. $NVDA reports after the US close, and it's sliding into it ⏳
🔹 Options price a move of about 8.5% either way
🔹 The Street wants $2.47 EPS on about $109B, vs Nvidia's own $108B guide
🔹 Colette Kress leads the call for the first time as interim CEO
🔹 $NVDA ▼3.6% today at $150.50, about 37% under its $239.24 record close from Oct 6
🔹 The AI trade is red too: $TSM ▼4.8%, $AMD ▼3.6%
Wednesday's close settles it
Beat and bounce, or another sell the news? 👇
⚠️ Past performance is not an indication of future results. Not investment advice, your capital is at risk
#stocks
🔹 Options price a move of about 8.5% either way
🔹 The Street wants $2.47 EPS on about $109B, vs Nvidia's own $108B guide
🔹 Colette Kress leads the call for the first time as interim CEO
🔹 $NVDA ▼3.6% today at $150.50, about 37% under its $239.24 record close from Oct 6
🔹 The AI trade is red too: $TSM ▼4.8%, $AMD ▼3.6%
Wednesday's close settles it
Beat and bounce, or another sell the news? 👇
⚠️ Past performance is not an indication of future results. Not investment advice, your capital is at risk
#stocks
Palpatine:
ya lo presento =)
1
3
3.3k
·
--
Partly True
NVIDIA's $130B Guidance Has Two Important Constraints
NVIDIA reported $115.8B in Q3 revenue, up 103% year over year. Data center revenue reached $107.6B, up 110%.
Its Q4 revenue outlook is $130B, plus or minus 3%, despite assuming zero data center compute revenue from China.
That exclusion matters. NVIDIA shipped $2.4B of Hopper data center products to China in Q3, but its next-quarter forecast does not assume a repeat.
The more interesting tension is profitability.
Q3 GAAP gross margin was 74.8%, down from 75.0% sequentially. NVIDIA attributed the slight decline partly to the initial Vera Rubin ramp.
For Q4, both GAAP and non-GAAP gross margins are guided to 71–72%.
At $130B in revenue, each percentage point of gross margin represents $1.3B in quarterly gross profit. A decline from 74.8% to the 71.5% midpoint would mean roughly $4.3B less gross profit than maintaining the Q3 margin on the same revenue base.
That is a margin sensitivity calculation, not a forecast of declining absolute gross profit.
NVIDIA's next test isn't simply whether customers keep buying. It's whether Rubin's rapid volume ramp can restore the economics of the previous platform generation.
The demand signal remains powerful. The margin recovery path is now equally important.
Q4 includes an extra week, another reason not to confuse reported growth with underlying demand acceleration.
#stocks
$NVDA.US
{stock_us}(NVDA.US)
NVIDIA's $130B Guidance Has Two Important Constraints
NVIDIA reported $115.8B in Q3 revenue, up 103% year over year. Data center revenue reached $107.6B, up 110%.
Its Q4 revenue outlook is $130B, plus or minus 3%, despite assuming zero data center compute revenue from China.
That exclusion matters. NVIDIA shipped $2.4B of Hopper data center products to China in Q3, but its next-quarter forecast does not assume a repeat.
The more interesting tension is profitability.
Q3 GAAP gross margin was 74.8%, down from 75.0% sequentially. NVIDIA attributed the slight decline partly to the initial Vera Rubin ramp.
For Q4, both GAAP and non-GAAP gross margins are guided to 71–72%.
At $130B in revenue, each percentage point of gross margin represents $1.3B in quarterly gross profit. A decline from 74.8% to the 71.5% midpoint would mean roughly $4.3B less gross profit than maintaining the Q3 margin on the same revenue base.
That is a margin sensitivity calculation, not a forecast of declining absolute gross profit.
NVIDIA's next test isn't simply whether customers keep buying. It's whether Rubin's rapid volume ramp can restore the economics of the previous platform generation.
The demand signal remains powerful. The margin recovery path is now equally important.
Q4 includes an extra week, another reason not to confuse reported growth with underlying demand acceleration.
#stocks
$NVDA.US
NVIDIA reported $115.8B in Q3 revenue, up 103% year over year. Data center revenue reached $107.6B, up 110%.
Its Q4 revenue outlook is $130B, plus or minus 3%, despite assuming zero data center compute revenue from China.
That exclusion matters. NVIDIA shipped $2.4B of Hopper data center products to China in Q3, but its next-quarter forecast does not assume a repeat.
The more interesting tension is profitability.
Q3 GAAP gross margin was 74.8%, down from 75.0% sequentially. NVIDIA attributed the slight decline partly to the initial Vera Rubin ramp.
For Q4, both GAAP and non-GAAP gross margins are guided to 71–72%.
At $130B in revenue, each percentage point of gross margin represents $1.3B in quarterly gross profit. A decline from 74.8% to the 71.5% midpoint would mean roughly $4.3B less gross profit than maintaining the Q3 margin on the same revenue base.
That is a margin sensitivity calculation, not a forecast of declining absolute gross profit.
NVIDIA's next test isn't simply whether customers keep buying. It's whether Rubin's rapid volume ramp can restore the economics of the previous platform generation.
The demand signal remains powerful. The margin recovery path is now equally important.
Q4 includes an extra week, another reason not to confuse reported growth with underlying demand acceleration.
#stocks
$NVDA.US
NVDAUS+2.79%
965

Kalshi is making moves into equities, but Robinhood isn't sweating the competition. Mizuho remains super bullish on HOOD, projecting an impressive 86 percent upside. Traditional brokerages and prediction markets are starting to blur lines, yet HOOD's robust ecosystem gives it a massive moat. Retail trading is evolving fast, but established giants seem ready to defend their turf against new entrants. Will this bullish Wall Street thesis play out? #Robinhood #Stocks #Trading
Kalshi is making moves into equities, but Robinhood isn't sweating the competition. Mizuho remains super bullish on HOOD, projecting an impressive 86 percent upside. Traditional brokerages and prediction markets are starting to blur lines, yet HOOD's robust ecosystem gives it a massive moat. Retail trading is evolving fast, but established giants seem ready to defend their turf against new entrants. Will this bullish Wall Street thesis play out? #Robinhood #Stocks #Trading
10
·
--
Bullish
🚀 Intel is waking up — and $57.00 is the line that matters
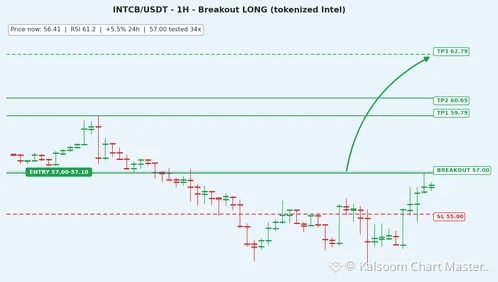
INTCB (tokenized Intel stock on Binance) is +5.5% today at $56.41, riding the chip rally after Nvidia's earnings beat. Hourly closes have climbed all day — $53.51 → $56.41 — and it's above both EMAs with RSI 61.2.
Why $57.00 matters: it's the 24h high, tested 34 times in 48 hours. A break above it opens $59.79, then $60.65.
Roadmap:
$55.00 support → $56.41 → $57.00 breakout → $59.79 → $60.65 → $62.79
🟢 LONG — $INTCB (on breakout)
Entry: $57.00 – $57.10
SL: $55.00
TP1: $59.79 | TP2: $60.65 | TP3: $62.79
⚠️ Don't buy at $56.41 — wait for the break of $57.00. If it rejects $57.00 again, the breakout fails.
Receipts: our calls overnight — SOL TP2 $75, BREV TP2 $0.1200, MMT full TP3, ZEC TP1.
Is Intel the next chip stock to run? 🤔
#intcb #Intel #Stocks
NFA — This is not financial advice, DYOR.
🚀 Intel is waking up — and $57.00 is the line that matters
INTCB (tokenized Intel stock on Binance) is +5.5% today at $56.41, riding the chip rally after Nvidia's earnings beat. Hourly closes have climbed all day — $53.51 → $56.41 — and it's above both EMAs with RSI 61.2.
Why $57.00 matters: it's the 24h high, tested 34 times in 48 hours. A break above it opens $59.79, then $60.65.
Roadmap:
$55.00 support → $56.41 → $57.00 breakout → $59.79 → $60.65 → $62.79
🟢 LONG — $INTCB (on breakout)
Entry: $57.00 – $57.10
SL: $55.00
TP1: $59.79 | TP2: $60.65 | TP3: $62.79
⚠️ Don't buy at $56.41 — wait for the break of $57.00. If it rejects $57.00 again, the breakout fails.
Receipts: our calls overnight — SOL TP2 $75, BREV TP2 $0.1200, MMT full TP3, ZEC TP1.
Is Intel the next chip stock to run? 🤔
#intcb #Intel #Stocks
NFA — This is not financial advice, DYOR.
INTCB (tokenized Intel stock on Binance) is +5.5% today at $56.41, riding the chip rally after Nvidia's earnings beat. Hourly closes have climbed all day — $53.51 → $56.41 — and it's above both EMAs with RSI 61.2.
Why $57.00 matters: it's the 24h high, tested 34 times in 48 hours. A break above it opens $59.79, then $60.65.
Roadmap:
$55.00 support → $56.41 → $57.00 breakout → $59.79 → $60.65 → $62.79
🟢 LONG — $INTCB (on breakout)
Entry: $57.00 – $57.10
SL: $55.00
TP1: $59.79 | TP2: $60.65 | TP3: $62.79
⚠️ Don't buy at $56.41 — wait for the break of $57.00. If it rejects $57.00 again, the breakout fails.
Receipts: our calls overnight — SOL TP2 $75, BREV TP2 $0.1200, MMT full TP3, ZEC TP1.
Is Intel the next chip stock to run? 🤔
#intcb #Intel #Stocks
NFA — This is not financial advice, DYOR.
68
·
--
NAND Equipment Could Boom Before NAND Prices Weaken
Bernstein now forecasts $217B in global wafer-fab equipment spending for 2027, including 58% growth in NAND equipment investment.
The beneficiaries are not necessarily the companies selling NAND chips.
$LRCX has direct exposure to 3D NAND layer transitions through etch and deposition. $AMAT supplies a broader range of memory manufacturing tools, while $KLAC benefits from rising process-control complexity.
Tokyo Electron (8035.T) and Kokusai Electric (6525.T) also have exposure to memory equipment spending.
But equipment orders and NAND pricing operate on different clocks.
Much of the near-term investment is aimed at converting existing NAND lines to higher-layer architectures, not simply adding new wafer capacity.
Those conversions can increase bit output per wafer. Equipment suppliers may recognize revenue before the resulting supply reaches the storage market.
For NAND producers such as $SNDK and Kioxia (285A.T), that creates a different risk: stronger manufacturing productivity could eventually pressure pricing if bit supply outruns demand.
My thesis: NAND equipment makers could enjoy an earnings upcycle even as the investments they supply begin weakening NAND producers' pricing power.
The key indicators are equipment orders, NAND bit output and enterprise SSD contract prices. They won't necessarily turn at the same time.
#stocks
NAND Equipment Could Boom Before NAND Prices Weaken
Bernstein now forecasts $217B in global wafer-fab equipment spending for 2027, including 58% growth in NAND equipment investment.
The beneficiaries are not necessarily the companies selling NAND chips.
$LRCX has direct exposure to 3D NAND layer transitions through etch and deposition. $AMAT supplies a broader range of memory manufacturing tools, while $KLAC benefits from rising process-control complexity.
Tokyo Electron (8035.T) and Kokusai Electric (6525.T) also have exposure to memory equipment spending.
But equipment orders and NAND pricing operate on different clocks.
Much of the near-term investment is aimed at converting existing NAND lines to higher-layer architectures, not simply adding new wafer capacity.
Those conversions can increase bit output per wafer. Equipment suppliers may recognize revenue before the resulting supply reaches the storage market.
For NAND producers such as $SNDK and Kioxia (285A.T), that creates a different risk: stronger manufacturing productivity could eventually pressure pricing if bit supply outruns demand.
My thesis: NAND equipment makers could enjoy an earnings upcycle even as the investments they supply begin weakening NAND producers' pricing power.
The key indicators are equipment orders, NAND bit output and enterprise SSD contract prices. They won't necessarily turn at the same time.
#stocks
Bernstein now forecasts $217B in global wafer-fab equipment spending for 2027, including 58% growth in NAND equipment investment.
The beneficiaries are not necessarily the companies selling NAND chips.
$LRCX has direct exposure to 3D NAND layer transitions through etch and deposition. $AMAT supplies a broader range of memory manufacturing tools, while $KLAC benefits from rising process-control complexity.
Tokyo Electron (8035.T) and Kokusai Electric (6525.T) also have exposure to memory equipment spending.
But equipment orders and NAND pricing operate on different clocks.
Much of the near-term investment is aimed at converting existing NAND lines to higher-layer architectures, not simply adding new wafer capacity.
Those conversions can increase bit output per wafer. Equipment suppliers may recognize revenue before the resulting supply reaches the storage market.
For NAND producers such as $SNDK and Kioxia (285A.T), that creates a different risk: stronger manufacturing productivity could eventually pressure pricing if bit supply outruns demand.
My thesis: NAND equipment makers could enjoy an earnings upcycle even as the investments they supply begin weakening NAND producers' pricing power.
The key indicators are equipment orders, NAND bit output and enterprise SSD contract prices. They won't necessarily turn at the same time.
#stocks
84
·
--
Article
Will Anthropic and OpenAI Trigger the Next AI Bubble? I Don't Think So. Not Yet.Everyone is talking about an AI bubble. With companies like Anthropic and OpenAI pushing the boundaries of artificial intelligence, many investors are beginning to question whether we're approaching another dot-com moment.
But I have a different perspective.
I don't think the AI bubble is ready to happen yet. In fact, I believe we're still in the early stages of something much bigger. Here's why.
1. AI Will Become a Strategic Asset for Every Nation 🌍
AI companies won't simply be technology businesses. They could become the backbone of national economies, industrial productivity, military capabilities, and geopolitical power.
Think about oil and natural gas. Nations have spent decades competing for energy resources because economic and national security depend on them.
AI could become the next strategic resource.
No country will want to fall behind. Governments will compete to develop domestic AI infrastructure, secure computing power, build semiconductor supply chains, and support their own AI champions.
And when governments, corporations, and investors all compete for the same technology, the result could be an extraordinary wave of capital and euphoria.
2. The Dot-Com Bubble Might Look Small Compared to What's Coming 📈
During the dot-com era, some internet-related companies reached extraordinary valuations, with P/E ratios approaching or exceeding 200x.
But here's what makes AI different.
AI isn't just another internet business model. It has the potential to transform almost every industry, from finance and healthcare to manufacturing, logistics, defense, and software.
If an AI-driven speculative bubble eventually emerges, I wouldn't be surprised to see extreme valuations across semiconductor and AI-related stocks.
We're talking about a hypothetical scenario where some companies could reach P/E ratios of 300x, 500x, or even 2,000x.
Of course, these aren't price targets or guaranteed outcomes. They're illustrations of how extreme market euphoria could become.
3. The Real AI Bubble Begins When AI Becomes a Market Participant 🤖
This is perhaps my most controversial point.
What if the biggest AI bubble doesn't happen when humans invest in AI companies, but when AI itself becomes an active participant in the economy?
Imagine millions of AI agents conducting business, managing capital, developing software, negotiating contracts, optimizing supply chains, and competing against one another.
AI won't just be a tool used by humans.
It could become an economic participant.
And isn't that process already beginning?
AI is already automating tasks that once required human workers. Entire workflows are being transformed, and some traditional jobs are becoming increasingly replaceable.
Now imagine what happens when AI systems become significantly more capable, autonomous, and interconnected.
The economic activity generated by AI could become a catalyst for another enormous investment cycle.
My Conclusion:
I don't believe the AI story is over, and I don't think we've necessarily reached peak euphoria.
The dot-com bubble was driven by expectations of an internet-powered future.
The potential AI bubble could be driven by something even bigger: a global race for intelligence, computing power, automation, and economic dominance.
And perhaps the most important question isn't whether AI is overvalued today.
It's how far the world will go when every nation, corporation, investor, and eventually AI itself competes for dominance.
The biggest AI bubble in history might still be ahead of us.
What do you think? Are we already in an AI bubble, or are we still in the early innings?
{future}(SNDKUSDT)
{future}(SOXLUSDT)
{future}(NVDAUSDT)
#Aİ #Anthropic #OpenAI #stocks #NVDA
Will Anthropic and OpenAI Trigger the Next AI Bubble? I Don't Think So. Not Yet.
Everyone is talking about an AI bubble. With companies like Anthropic and OpenAI pushing the boundaries of artificial intelligence, many investors are beginning to question whether we're approaching another dot-com moment.
But I have a different perspective.
I don't think the AI bubble is ready to happen yet. In fact, I believe we're still in the early stages of something much bigger. Here's why.
1. AI Will Become a Strategic Asset for Every Nation 🌍
AI companies won't simply be technology businesses. They could become the backbone of national economies, industrial productivity, military capabilities, and geopolitical power.
Think about oil and natural gas. Nations have spent decades competing for energy resources because economic and national security depend on them.
AI could become the next strategic resource.
No country will want to fall behind. Governments will compete to develop domestic AI infrastructure, secure computing power, build semiconductor supply chains, and support their own AI champions.
And when governments, corporations, and investors all compete for the same technology, the result could be an extraordinary wave of capital and euphoria.
2. The Dot-Com Bubble Might Look Small Compared to What's Coming 📈
During the dot-com era, some internet-related companies reached extraordinary valuations, with P/E ratios approaching or exceeding 200x.
But here's what makes AI different.
AI isn't just another internet business model. It has the potential to transform almost every industry, from finance and healthcare to manufacturing, logistics, defense, and software.
If an AI-driven speculative bubble eventually emerges, I wouldn't be surprised to see extreme valuations across semiconductor and AI-related stocks.
We're talking about a hypothetical scenario where some companies could reach P/E ratios of 300x, 500x, or even 2,000x.
Of course, these aren't price targets or guaranteed outcomes. They're illustrations of how extreme market euphoria could become.
3. The Real AI Bubble Begins When AI Becomes a Market Participant 🤖
This is perhaps my most controversial point.
What if the biggest AI bubble doesn't happen when humans invest in AI companies, but when AI itself becomes an active participant in the economy?
Imagine millions of AI agents conducting business, managing capital, developing software, negotiating contracts, optimizing supply chains, and competing against one another.
AI won't just be a tool used by humans.
It could become an economic participant.
And isn't that process already beginning?
AI is already automating tasks that once required human workers. Entire workflows are being transformed, and some traditional jobs are becoming increasingly replaceable.
Now imagine what happens when AI systems become significantly more capable, autonomous, and interconnected.
The economic activity generated by AI could become a catalyst for another enormous investment cycle.
My Conclusion:
I don't believe the AI story is over, and I don't think we've necessarily reached peak euphoria.
The dot-com bubble was driven by expectations of an internet-powered future.
The potential AI bubble could be driven by something even bigger: a global race for intelligence, computing power, automation, and economic dominance.
And perhaps the most important question isn't whether AI is overvalued today.
It's how far the world will go when every nation, corporation, investor, and eventually AI itself competes for dominance.
The biggest AI bubble in history might still be ahead of us.
What do you think? Are we already in an AI bubble, or are we still in the early innings?
#Aİ #Anthropic #OpenAI #stocks #NVDA
But I have a different perspective.
I don't think the AI bubble is ready to happen yet. In fact, I believe we're still in the early stages of something much bigger. Here's why.
1. AI Will Become a Strategic Asset for Every Nation 🌍
AI companies won't simply be technology businesses. They could become the backbone of national economies, industrial productivity, military capabilities, and geopolitical power.
Think about oil and natural gas. Nations have spent decades competing for energy resources because economic and national security depend on them.
AI could become the next strategic resource.
No country will want to fall behind. Governments will compete to develop domestic AI infrastructure, secure computing power, build semiconductor supply chains, and support their own AI champions.
And when governments, corporations, and investors all compete for the same technology, the result could be an extraordinary wave of capital and euphoria.
2. The Dot-Com Bubble Might Look Small Compared to What's Coming 📈
During the dot-com era, some internet-related companies reached extraordinary valuations, with P/E ratios approaching or exceeding 200x.
But here's what makes AI different.
AI isn't just another internet business model. It has the potential to transform almost every industry, from finance and healthcare to manufacturing, logistics, defense, and software.
If an AI-driven speculative bubble eventually emerges, I wouldn't be surprised to see extreme valuations across semiconductor and AI-related stocks.
We're talking about a hypothetical scenario where some companies could reach P/E ratios of 300x, 500x, or even 2,000x.
Of course, these aren't price targets or guaranteed outcomes. They're illustrations of how extreme market euphoria could become.
3. The Real AI Bubble Begins When AI Becomes a Market Participant 🤖
This is perhaps my most controversial point.
What if the biggest AI bubble doesn't happen when humans invest in AI companies, but when AI itself becomes an active participant in the economy?
Imagine millions of AI agents conducting business, managing capital, developing software, negotiating contracts, optimizing supply chains, and competing against one another.
AI won't just be a tool used by humans.
It could become an economic participant.
And isn't that process already beginning?
AI is already automating tasks that once required human workers. Entire workflows are being transformed, and some traditional jobs are becoming increasingly replaceable.
Now imagine what happens when AI systems become significantly more capable, autonomous, and interconnected.
The economic activity generated by AI could become a catalyst for another enormous investment cycle.
My Conclusion:
I don't believe the AI story is over, and I don't think we've necessarily reached peak euphoria.
The dot-com bubble was driven by expectations of an internet-powered future.
The potential AI bubble could be driven by something even bigger: a global race for intelligence, computing power, automation, and economic dominance.
And perhaps the most important question isn't whether AI is overvalued today.
It's how far the world will go when every nation, corporation, investor, and eventually AI itself competes for dominance.
The biggest AI bubble in history might still be ahead of us.
What do you think? Are we already in an AI bubble, or are we still in the early innings?
#Aİ #Anthropic #OpenAI #stocks #NVDA
1
743
Partly True
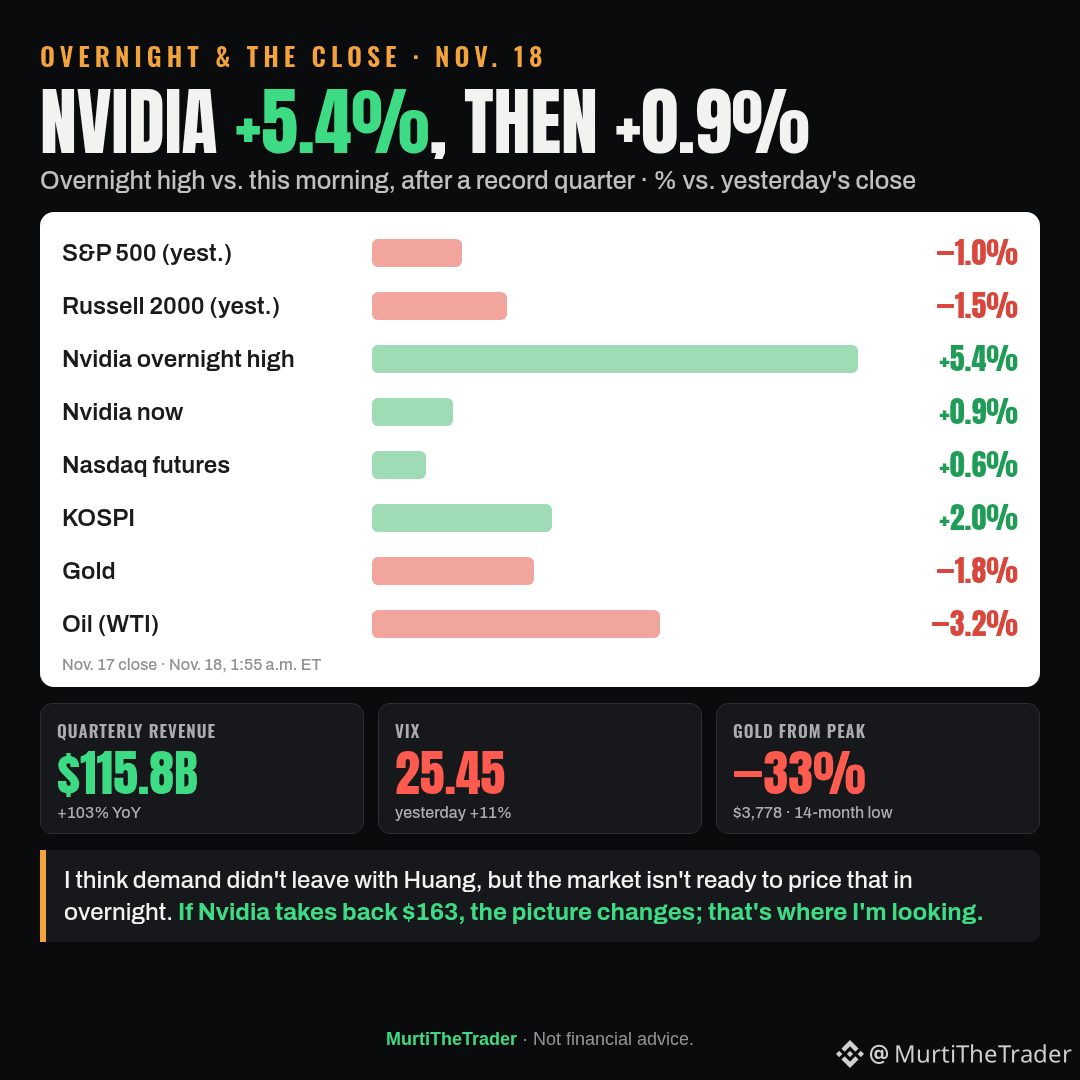
Overnight and the close: Nvidia rose as much as 5.4% overnight, but this morning it's up only 0.9%.
→ Yesterday the S&P fell 1.0%, the Russell 1.5%, and the VIX closed at 25.45 (+11%)
→ After the close, a record quarter: revenue of $115.8 billion (+103% year over year), with $130 billion guided for this quarter
→ This morning KOSPI is up 2.0% and Nasdaq futures 0.6%; gold is at $3,778, a 14-month low (−33% from its peak), and oil is down 3.2%
I think demand didn't leave with Huang, but the market isn't ready to price that in overnight. If Nvidia takes back $163, the picture changes; that's where I'm looking.
#Stocks #Nvidia
Watching: $NVDA $QQQ $SPY
Overnight and the close: Nvidia rose as much as 5.4% overnight, but this morning it's up only 0.9%.
→ Yesterday the S&P fell 1.0%, the Russell 1.5%, and the VIX closed at 25.45 (+11%)
→ After the close, a record quarter: revenue of $115.8 billion (+103% year over year), with $130 billion guided for this quarter
→ This morning KOSPI is up 2.0% and Nasdaq futures 0.6%; gold is at $3,778, a 14-month low (−33% from its peak), and oil is down 3.2%
I think demand didn't leave with Huang, but the market isn't ready to price that in overnight. If Nvidia takes back $163, the picture changes; that's where I'm looking.
#Stocks #Nvidia
Watching: $NVDA $QQQ $SPY
→ Yesterday the S&P fell 1.0%, the Russell 1.5%, and the VIX closed at 25.45 (+11%)
→ After the close, a record quarter: revenue of $115.8 billion (+103% year over year), with $130 billion guided for this quarter
→ This morning KOSPI is up 2.0% and Nasdaq futures 0.6%; gold is at $3,778, a 14-month low (−33% from its peak), and oil is down 3.2%
I think demand didn't leave with Huang, but the market isn't ready to price that in overnight. If Nvidia takes back $163, the picture changes; that's where I'm looking.
#Stocks #Nvidia
Watching: $NVDA $QQQ $SPY
990
Partly True
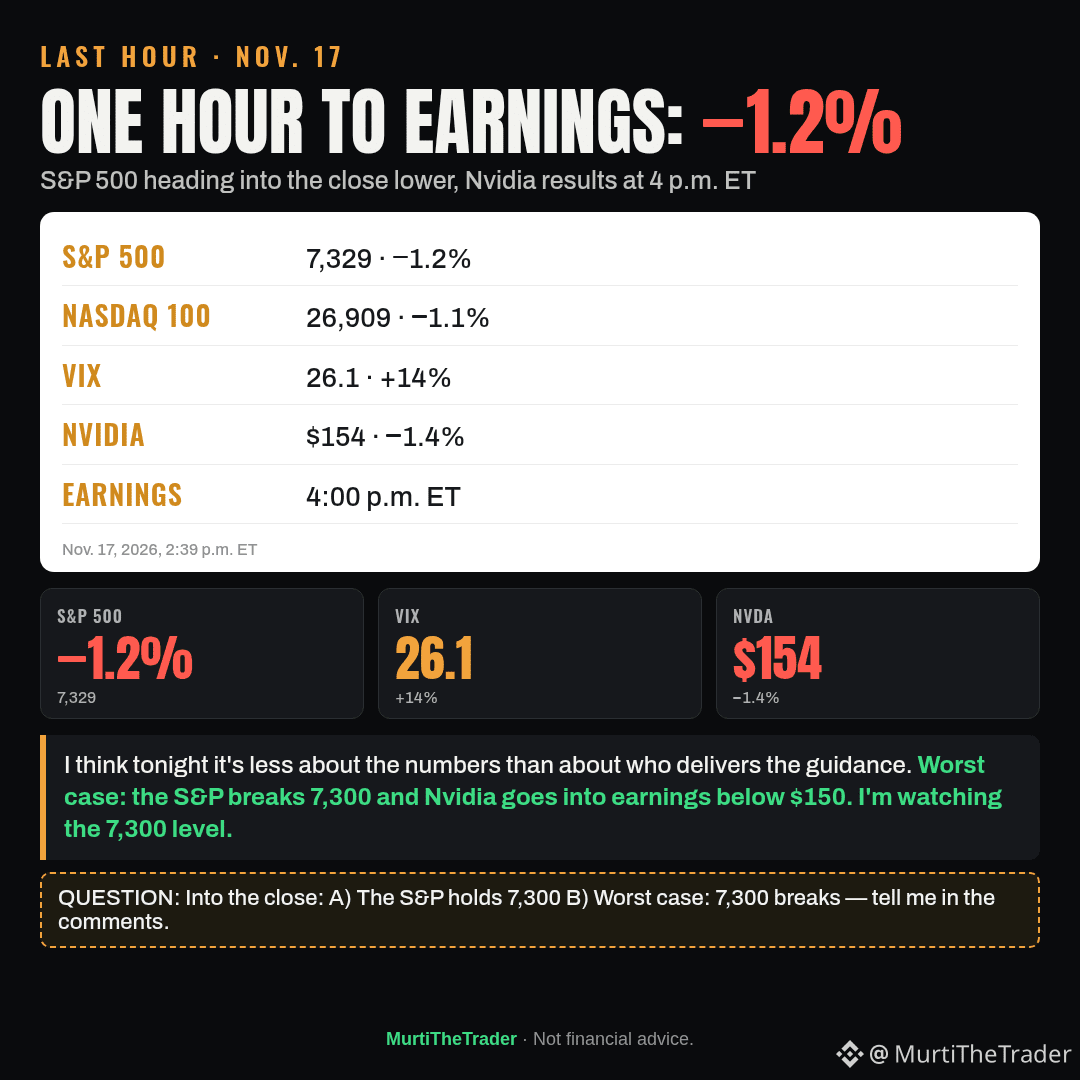
Last hour: the S&P 500 is down 1.2% at 7,329, and the VIX jumped 14% to 26.1.
→ Nvidia hired a search firm to find a new CEO; the stock is at $154 (−1.4%)
→ Earnings are at 4:00 p.m. ET; options are pricing a move of around ±7%
I think tonight it's less about the numbers than about who delivers the guidance.
Into the close: A) The S&P holds 7,300 B) Worst case: 7,300 breaks and Nvidia goes into earnings below $150 — tell me in the comments.
#Stocks #AI
Watching: $SPY $QQQ $NVDA
Last hour: the S&P 500 is down 1.2% at 7,329, and the VIX jumped 14% to 26.1.
→ Nvidia hired a search firm to find a new CEO; the stock is at $154 (−1.4%)
→ Earnings are at 4:00 p.m. ET; options are pricing a move of around ±7%
I think tonight it's less about the numbers than about who delivers the guidance.
Into the close: A) The S&P holds 7,300 B) Worst case: 7,300 breaks and Nvidia goes into earnings below $150 — tell me in the comments.
#Stocks #AI
Watching: $SPY $QQQ $NVDA
→ Nvidia hired a search firm to find a new CEO; the stock is at $154 (−1.4%)
→ Earnings are at 4:00 p.m. ET; options are pricing a move of around ±7%
I think tonight it's less about the numbers than about who delivers the guidance.
Into the close: A) The S&P holds 7,300 B) Worst case: 7,300 breaks and Nvidia goes into earnings below $150 — tell me in the comments.
#Stocks #AI
Watching: $SPY $QQQ $NVDA
546
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#NvidiaBeatsEstimatesWith$130BQ4Outlook
17,261 views
207 Discussing
2
#AnthropicIPOPriceCouldExceed$80
22,019 views
178 Discussing
3
#RussiaCentralBankAddsAlfaBankToCryptoExchangeRegister
0 views
11 Discussing
4
#RussianCentralBankPlansToAllowFundsToHoldCryptoIn2027
0 views
6 Discussing
5
#VisaPlansStablecoinPrefundingForAPACCrossBorderPayments
0 views
9 Discussing
6
#CanNvidia’sDataCenterGrowthContinue?
65,350 views
987 Discussing
7
#CanadaAndUSLaunchOperationNiagaraAgainstApprovalPhishing
5,807 views
47 Discussing
8
#BankOfEnglandUnveilsClearingHousePathwayCoveringDLTFirms
2,628 views
55 Discussing
9
#DBSAndCirclePartnerToExpandAsianInstitutionsUSDCAccess
3,856 views
60 Discussing
10
#LedgerHardwareImplantReportsExtendToDubai
31,123 views
491 Discussing