
#remittances
remittances
11,537 views
121 Discussing
Hot
Latest

·
--
Sending $200 abroad for 2.18%? That's the new IMF number for stablecoin remittances.
An IMF study (via COINOTAG) puts the cost of a $200 stablecoin remittance at 2.18%, well below what traditional money-transfer channels typically charge on small transfers.
While the market argues over hacks and ETF outflows, this is the quiet use case that keeps growing: cheap, fast cross-border payments on $USDT and $USDC rails.
My take: the real test is the last mile. Cheap on-chain transfer means little if cashing out locally is costly.
Would you use stablecoins to send money home, and what would convince you: lower fees, speed, or easy cash-out?
#Stablecoins #Remittances #IMF #Crypto
Sending $200 abroad for 2.18%? That's the new IMF number for stablecoin remittances.
An IMF study (via COINOTAG) puts the cost of a $200 stablecoin remittance at 2.18%, well below what traditional money-transfer channels typically charge on small transfers.
While the market argues over hacks and ETF outflows, this is the quiet use case that keeps growing: cheap, fast cross-border payments on $USDT and $USDC rails.
My take: the real test is the last mile. Cheap on-chain transfer means little if cashing out locally is costly.
Would you use stablecoins to send money home, and what would convince you: lower fees, speed, or easy cash-out?
#Stablecoins #Remittances #IMF #Crypto
An IMF study (via COINOTAG) puts the cost of a $200 stablecoin remittance at 2.18%, well below what traditional money-transfer channels typically charge on small transfers.
While the market argues over hacks and ETF outflows, this is the quiet use case that keeps growing: cheap, fast cross-border payments on $USDT and $USDC rails.
My take: the real test is the last mile. Cheap on-chain transfer means little if cashing out locally is costly.
Would you use stablecoins to send money home, and what would convince you: lower fees, speed, or easy cash-out?
#Stablecoins #Remittances #IMF #Crypto
1

·
--
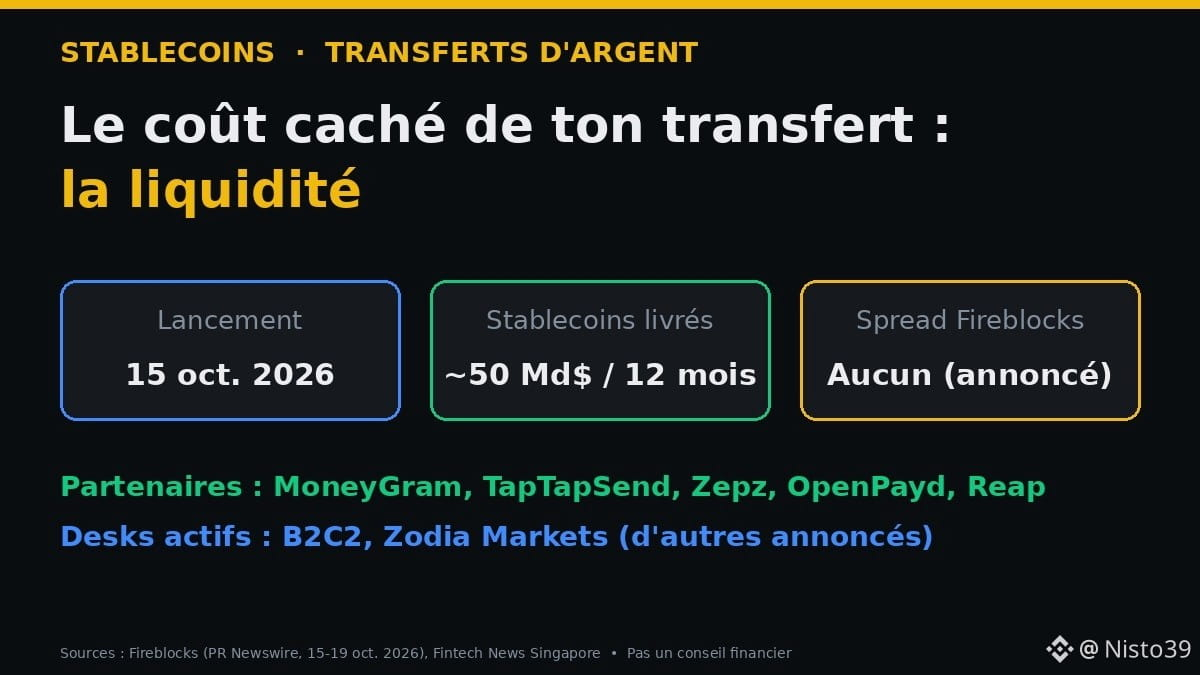
💸 When you send money to Dakar or Bamako, the visible fee is only part of the cost. The other part happens behind the scenes: liquidity.
📌 The facts (Fireblocks, Oct. 15, 2026)
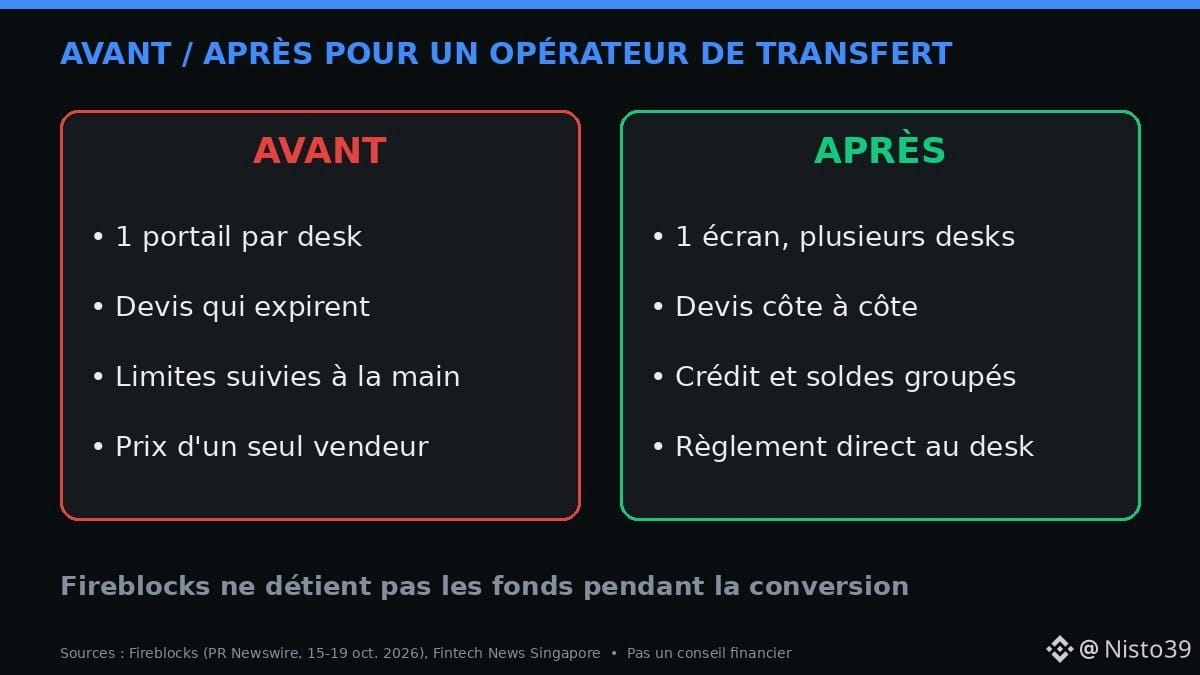
• Launch of “Liquidity Market”: payment companies can compare prices from several OTC desks (large stablecoin sellers) on a single screen
• Design partners: MoneyGram, TapTapSend, Zepz, OpenPayd, Reap
• Active desks: B2C2 and Zodia Markets; Wintermute, FalconX, GSR and others announced
• Nearly $50B in stablecoins delivered to payment companies over 12 months through the Fireblocks network
• Fireblocks says it takes no spread and does not custody funds
🧠 How it works
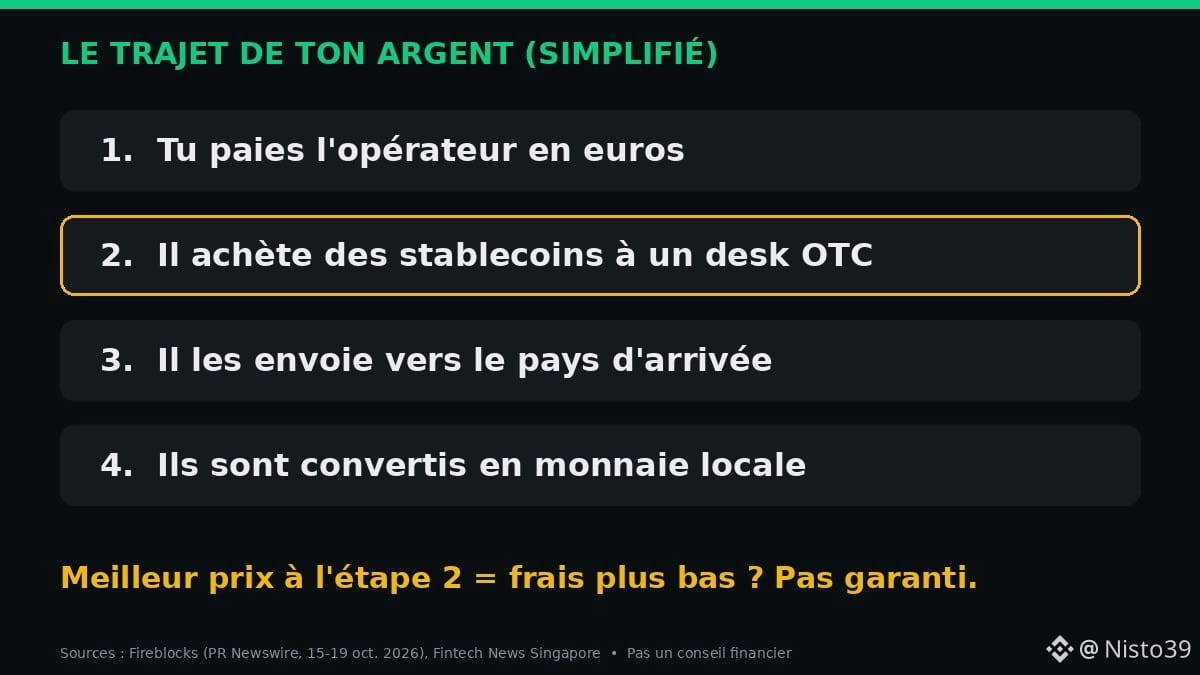
To pay in $USDT or $USDC, the operator first has to buy them. With a single provider, they have to accept its price. Comparing several quotes can narrow the gap, especially on “difficult” corridors.
👤 Imagine Mariam (a fictional character), a healthcare assistant in Paris who sends €100 a month to her mother in Kayes. If the operator buys at a lower price, some of the savings could go to her… or stay in its margin.
⚖️ Caveat: the tool is only available to Fireblocks clients, and no public figures are available on fee reductions.
✅ Cheaper for you 🟢 / mainly for operators 🔴 / remains to be seen 🟡? 👇
Not financial advice. DYOR.
Sources: Fireblocks (PR Newswire), Fintech News Singapore.
#Stablecoins #Remittances #CryptoNews
💸 When you send money to Dakar or Bamako, the visible fee is only part of the cost. The other part happens behind the scenes: liquidity.
📌 The facts (Fireblocks, Oct. 15, 2026)
• Launch of “Liquidity Market”: payment companies can compare prices from several OTC desks (large stablecoin sellers) on a single screen
• Design partners: MoneyGram, TapTapSend, Zepz, OpenPayd, Reap
• Active desks: B2C2 and Zodia Markets; Wintermute, FalconX, GSR and others announced
• Nearly $50B in stablecoins delivered to payment companies over 12 months through the Fireblocks network
• Fireblocks says it takes no spread and does not custody funds
🧠 How it works
To pay in $USDT or $USDC , the operator first has to buy them. With a single provider, they have to accept its price. Comparing several quotes can narrow the gap, especially on “difficult” corridors.
👤 Imagine Mariam (a fictional character), a healthcare assistant in Paris who sends €100 a month to her mother in Kayes. If the operator buys at a lower price, some of the savings could go to her… or stay in its margin.
⚖️ Caveat: the tool is only available to Fireblocks clients, and no public figures are available on fee reductions.
✅ Cheaper for you 🟢 / mainly for operators 🔴 / remains to be seen 🟡? 👇
Not financial advice. DYOR.
Sources: Fireblocks (PR Newswire), Fintech News Singapore.
#Stablecoins #Remittances #CryptoNews
📌 The facts (Fireblocks, Oct. 15, 2026)
• Launch of “Liquidity Market”: payment companies can compare prices from several OTC desks (large stablecoin sellers) on a single screen
• Design partners: MoneyGram, TapTapSend, Zepz, OpenPayd, Reap
• Active desks: B2C2 and Zodia Markets; Wintermute, FalconX, GSR and others announced
• Nearly $50B in stablecoins delivered to payment companies over 12 months through the Fireblocks network
• Fireblocks says it takes no spread and does not custody funds
🧠 How it works
To pay in $USDT or $USDC , the operator first has to buy them. With a single provider, they have to accept its price. Comparing several quotes can narrow the gap, especially on “difficult” corridors.
👤 Imagine Mariam (a fictional character), a healthcare assistant in Paris who sends €100 a month to her mother in Kayes. If the operator buys at a lower price, some of the savings could go to her… or stay in its margin.
⚖️ Caveat: the tool is only available to Fireblocks clients, and no public figures are available on fee reductions.
✅ Cheaper for you 🟢 / mainly for operators 🔴 / remains to be seen 🟡? 👇
Not financial advice. DYOR.
Sources: Fireblocks (PR Newswire), Fintech News Singapore.
#Stablecoins #Remittances #CryptoNews
5
·
--
🚨 CROSS-BORDER CAPITAL FLOWS: UNPACKING THE $250B REMITTANCE ENGINE 🇺🇸🇲🇽🇵🇭🇨🇴🇨🇳 🚀
🔥 Headline figures highlighting $250 Billion+ in annual cross-border remittances outbound from the United States reflect one of the most critical structural payment corridors globally.
For developing economies—including Mexico, Colombia, the Philippines, India, and China—these personal capital flows serve as vital balance-of-payments support, funding household healthcare, food security, educational access, and local capital projects.
$XRP 🌐
Ripple ($XRP) sits directly at the center of the cross-border liquidity thesis via its On-Demand Liquidity (ODL) networks. Utilizing digital assets as a bridge asset eliminates pre-funding bank accounts in recipient nations—watch major institutional corridor volume metrics and horizontal support levels for structural signals.
$PHA ⚙️
Phala Network ($PHA) targets confidential compute and privacy-preserving execution layers for Web3 architectures. In an era of increasing cross-border transaction monitoring, decentralized data privacy frameworks remain a key technological focal point.
$PUMP ⚡
Pump.fun ($PUMP) tracks speculative meme launchpad liquidity on Solana. Unlike cross-border infrastructure assets, is driven strictly by retail volume momentum and token creation metrics—manage capital tightly around local lower-timeframe support layers.
🛑 Trader Risk Warning:
Trading macro news flows and payment infrastructure tokens during high-volatility cycles carries elevated execution, slippage, and liquidation risks! Protect your trading portfolio: enforce strict Stop-Loss (SL) parameters, cap perpetual leverage conservatively (2x–5x max), and practice disciplined risk management! 🛡️⚡
💬 Do you expect cross-border payment volume to shift rapidly onto stablecoin and bridge-asset rails over this cycle, or will traditional money transfer operators hold their market share? Share your setups below! 👇
#Binance #Remittances #PUMP
#CrossBorderPayments
🚨 CROSS-BORDER CAPITAL FLOWS: UNPACKING THE $250B REMITTANCE ENGINE 🇺🇸🇲🇽🇵🇭🇨🇴🇨🇳 🚀
🔥 Headline figures highlighting $250 Billion+ in annual cross-border remittances outbound from the United States reflect one of the most critical structural payment corridors globally.
For developing economies—including Mexico, Colombia, the Philippines, India, and China—these personal capital flows serve as vital balance-of-payments support, funding household healthcare, food security, educational access, and local capital projects.
$XRP 🌐
Ripple ($XRP ) sits directly at the center of the cross-border liquidity thesis via its On-Demand Liquidity (ODL) networks. Utilizing digital assets as a bridge asset eliminates pre-funding bank accounts in recipient nations—watch major institutional corridor volume metrics and horizontal support levels for structural signals.
$PHA ⚙️
Phala Network ($PHA ) targets confidential compute and privacy-preserving execution layers for Web3 architectures. In an era of increasing cross-border transaction monitoring, decentralized data privacy frameworks remain a key technological focal point.
$PUMP ⚡
Pump.fun ($PUMP ) tracks speculative meme launchpad liquidity on Solana. Unlike cross-border infrastructure assets, is driven strictly by retail volume momentum and token creation metrics—manage capital tightly around local lower-timeframe support layers.
🛑 Trader Risk Warning:
Trading macro news flows and payment infrastructure tokens during high-volatility cycles carries elevated execution, slippage, and liquidation risks! Protect your trading portfolio: enforce strict Stop-Loss (SL) parameters, cap perpetual leverage conservatively (2x–5x max), and practice disciplined risk management! 🛡️⚡
💬 Do you expect cross-border payment volume to shift rapidly onto stablecoin and bridge-asset rails over this cycle, or will traditional money transfer operators hold their market share? Share your setups below! 👇
#Binance #Remittances #PUMP
#CrossBorderPayments
🔥 Headline figures highlighting $250 Billion+ in annual cross-border remittances outbound from the United States reflect one of the most critical structural payment corridors globally.
For developing economies—including Mexico, Colombia, the Philippines, India, and China—these personal capital flows serve as vital balance-of-payments support, funding household healthcare, food security, educational access, and local capital projects.
$XRP 🌐
Ripple ($XRP ) sits directly at the center of the cross-border liquidity thesis via its On-Demand Liquidity (ODL) networks. Utilizing digital assets as a bridge asset eliminates pre-funding bank accounts in recipient nations—watch major institutional corridor volume metrics and horizontal support levels for structural signals.
$PHA ⚙️
Phala Network ($PHA ) targets confidential compute and privacy-preserving execution layers for Web3 architectures. In an era of increasing cross-border transaction monitoring, decentralized data privacy frameworks remain a key technological focal point.
$PUMP ⚡
Pump.fun ($PUMP ) tracks speculative meme launchpad liquidity on Solana. Unlike cross-border infrastructure assets, is driven strictly by retail volume momentum and token creation metrics—manage capital tightly around local lower-timeframe support layers.
🛑 Trader Risk Warning:
Trading macro news flows and payment infrastructure tokens during high-volatility cycles carries elevated execution, slippage, and liquidation risks! Protect your trading portfolio: enforce strict Stop-Loss (SL) parameters, cap perpetual leverage conservatively (2x–5x max), and practice disciplined risk management! 🛡️⚡
💬 Do you expect cross-border payment volume to shift rapidly onto stablecoin and bridge-asset rails over this cycle, or will traditional money transfer operators hold their market share? Share your setups below! 👇
#Binance #Remittances #PUMP
#CrossBorderPayments
1
397
·
--
In sub-Saharan Africa, remittances from the diaspora
represent more than $50 billion per year.
And Western Union, MoneyGram, correspondent banks
take between 6 and 12% as they pass through.
These are billions stolen from families. Legally.
Crypto, and especially stablecoins on Lightning or Stellar,
brings these fees down to less than 0.1%.
This isn’t technology for technology’s sake.
It’s money returned to those it belongs to.
GoldenBridge educates on these use cases because they really matter.
#Remittances
#AfriqueFintech
#Stablecoins
#FinancialInclusion
In sub-Saharan Africa, remittances from the diaspora
represent more than $50 billion per year.
And Western Union, MoneyGram, correspondent banks
take between 6 and 12% as they pass through.
These are billions stolen from families. Legally.
Crypto, and especially stablecoins on Lightning or Stellar,
brings these fees down to less than 0.1%.
This isn’t technology for technology’s sake.
It’s money returned to those it belongs to.
GoldenBridge educates on these use cases because they really matter.
#Remittances
#AfriqueFintech
#Stablecoins
#FinancialInclusion
represent more than $50 billion per year.
And Western Union, MoneyGram, correspondent banks
take between 6 and 12% as they pass through.
These are billions stolen from families. Legally.
Crypto, and especially stablecoins on Lightning or Stellar,
brings these fees down to less than 0.1%.
This isn’t technology for technology’s sake.
It’s money returned to those it belongs to.
GoldenBridge educates on these use cases because they really matter.
#Remittances
#AfriqueFintech
#Stablecoins
#FinancialInclusion
166
People underestimate TRON because it is not flashy. It does not have NFT hype or meme coin mania. What it has is utility that actually matters. Cross-border remittances cost fractions of a cent on TRON. Compare that to Western Union charging 7-10 percent. For someone sending 200 dollars home to their family, that difference is life-changing. TRON is financial inclusion without the marketing budget. The network processes over 2 billion dollars in daily USDT transfers. That volume speaks louder than any Twitter thread. Real adoption is quiet but relentless. #TRON #Remittances
People underestimate TRON because it is not flashy. It does not have NFT hype or meme coin mania. What it has is utility that actually matters. Cross-border remittances cost fractions of a cent on TRON. Compare that to Western Union charging 7-10 percent. For someone sending 200 dollars home to their family, that difference is life-changing. TRON is financial inclusion without the marketing budget. The network processes over 2 billion dollars in daily USDT transfers. That volume speaks louder than any Twitter thread. Real adoption is quiet but relentless. #TRON #Remittances
1
38
·
--
Remittances just got a major upgrade with $XRP. Bitso, a major crypto exchange, is bringing a new stablecoin called MXNB to the XRP Ledger. This stablecoin is backed by the Mexican peso, meaning one MXNB will always be worth one Mexican peso. This partnership with Ripple aims to make sending money between the US and Mexico much faster and cheaper, especially for large institutions. It's all about making cross-border payments more efficient globally. This move highlights the growing adoption of stablecoins for real-world use cases, particularly in countries with large remittance flows. It shows that crypto isn't just about trading; it's providing tangible solutions for everyday financial challenges. We could see more similar partnerships in other regions. This could make $XRP a key player in global remittances. What do you think? Keep an eye on $STG, today's top gainer at +46.13%! #Stablecoins #XRPL #Remittances
Remittances just got a major upgrade with $XRP . Bitso, a major crypto exchange, is bringing a new stablecoin called MXNB to the XRP Ledger. This stablecoin is backed by the Mexican peso, meaning one MXNB will always be worth one Mexican peso. This partnership with Ripple aims to make sending money between the US and Mexico much faster and cheaper, especially for large institutions. It's all about making cross-border payments more efficient globally. This move highlights the growing adoption of stablecoins for real-world use cases, particularly in countries with large remittance flows. It shows that crypto isn't just about trading; it's providing tangible solutions for everyday financial challenges. We could see more similar partnerships in other regions. This could make $XRP a key player in global remittances. What do you think? Keep an eye on $STG, today's top gainer at +46.13%! #Stablecoins #XRPL #Remittances
236

·
--
Article
TripleA CEO Says Stablecoins Could Replace Traditional RemittancesEric Barbier, CEO of TripleA, expressed a forward-looking view on remittances, suggesting that in the future, traditional remittance methods might become obsolete. Speaking to ChainCatcher, Barbier said he does not believe in the common model of fiat-to-stablecoin-to-fiat remittances, which is currently prevalent in many cross-border transfer services.
Instead, Barbier emphasized that stablecoins could provide people in emerging markets with a way to hold stronger currencies directly, bypassing the need for converting to weaker local currencies or relying on traditional financial intermediaries. He argued that stablecoins offer a more efficient, accessible alternative for remittance flows, especially in regions with limited banking infrastructure.
Barbier pointed out that remittances typically involve moving from a stronger currency into a weaker one, which can lead to loss of value and increased costs. He believes stablecoins, by offering a stable store of value that is pegged to stronger currencies, could fundamentally change how money is transferred across borders, reducing costs and increasing speed.
This perspective reflects a growing interest in the potential of stablecoins to revolutionize international money transfers, particularly in emerging markets where access to banking services is limited. Barbier’s comments highlight the evolving understanding of digital currencies not just as investment assets, but as practical tools for financial inclusion.
More details are available in the official Binance Square post. #Stablecoins #Remittances #FinancialInclusion
TripleA CEO Says Stablecoins Could Replace Traditional Remittances
Eric Barbier, CEO of TripleA, expressed a forward-looking view on remittances, suggesting that in the future, traditional remittance methods might become obsolete. Speaking to ChainCatcher, Barbier said he does not believe in the common model of fiat-to-stablecoin-to-fiat remittances, which is currently prevalent in many cross-border transfer services.
Instead, Barbier emphasized that stablecoins could provide people in emerging markets with a way to hold stronger currencies directly, bypassing the need for converting to weaker local currencies or relying on traditional financial intermediaries. He argued that stablecoins offer a more efficient, accessible alternative for remittance flows, especially in regions with limited banking infrastructure.
Barbier pointed out that remittances typically involve moving from a stronger currency into a weaker one, which can lead to loss of value and increased costs. He believes stablecoins, by offering a stable store of value that is pegged to stronger currencies, could fundamentally change how money is transferred across borders, reducing costs and increasing speed.
This perspective reflects a growing interest in the potential of stablecoins to revolutionize international money transfers, particularly in emerging markets where access to banking services is limited. Barbier’s comments highlight the evolving understanding of digital currencies not just as investment assets, but as practical tools for financial inclusion.
More details are available in the official Binance Square post. #Stablecoins #Remittances #FinancialInclusion
Instead, Barbier emphasized that stablecoins could provide people in emerging markets with a way to hold stronger currencies directly, bypassing the need for converting to weaker local currencies or relying on traditional financial intermediaries. He argued that stablecoins offer a more efficient, accessible alternative for remittance flows, especially in regions with limited banking infrastructure.
Barbier pointed out that remittances typically involve moving from a stronger currency into a weaker one, which can lead to loss of value and increased costs. He believes stablecoins, by offering a stable store of value that is pegged to stronger currencies, could fundamentally change how money is transferred across borders, reducing costs and increasing speed.
This perspective reflects a growing interest in the potential of stablecoins to revolutionize international money transfers, particularly in emerging markets where access to banking services is limited. Barbier’s comments highlight the evolving understanding of digital currencies not just as investment assets, but as practical tools for financial inclusion.
More details are available in the official Binance Square post. #Stablecoins #Remittances #FinancialInclusion
65
·
--
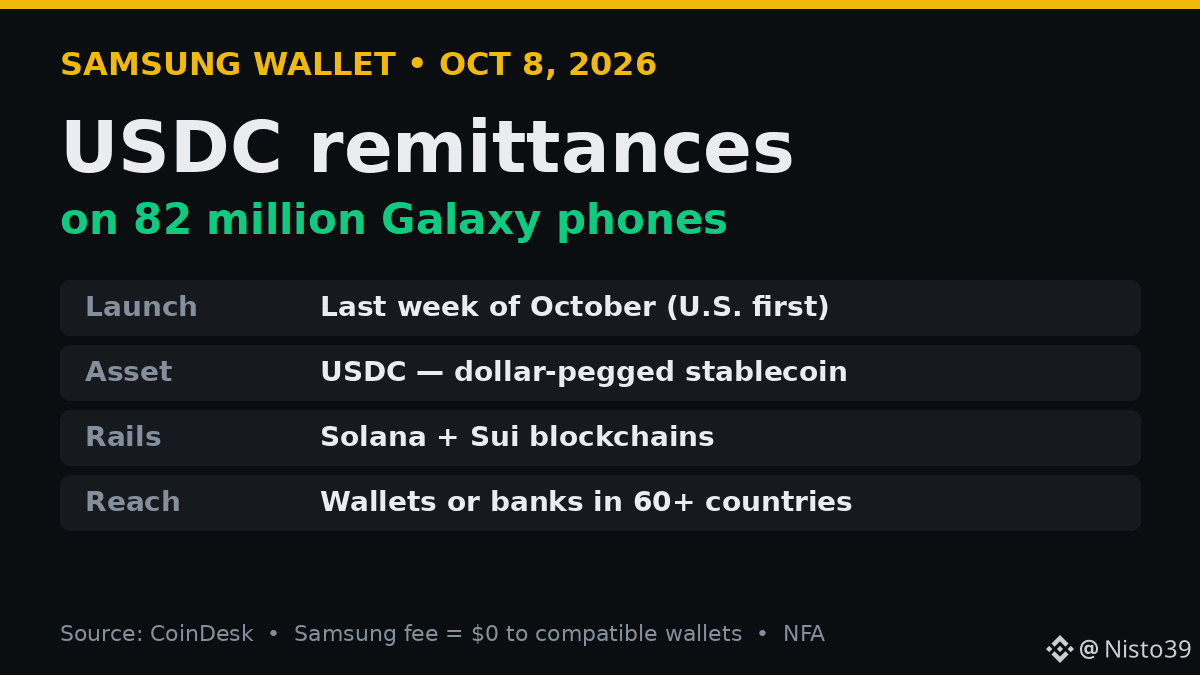
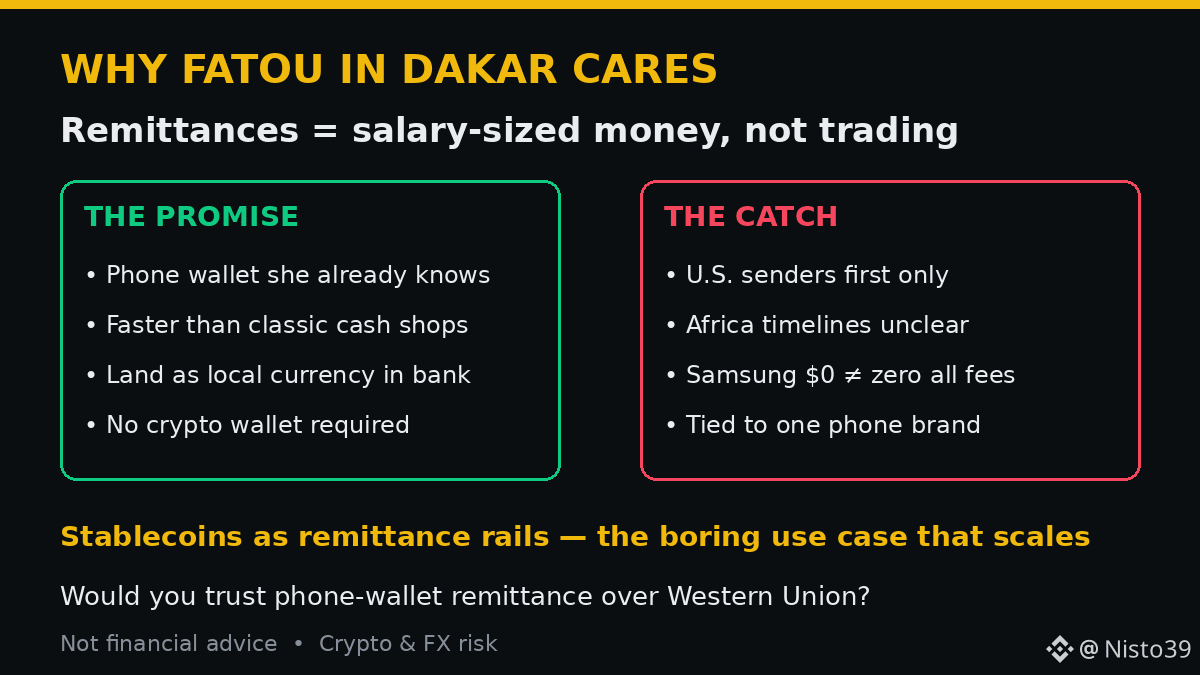
Samsung just put stablecoin remittances inside 82 million Galaxy phones 📱
On Oct 8, CoinDesk reported: starting the last week of October, eligible U.S. Galaxy users can send USDC (a dollar-pegged stablecoin — about one dollar per USDC by design) through Samsung Wallet.
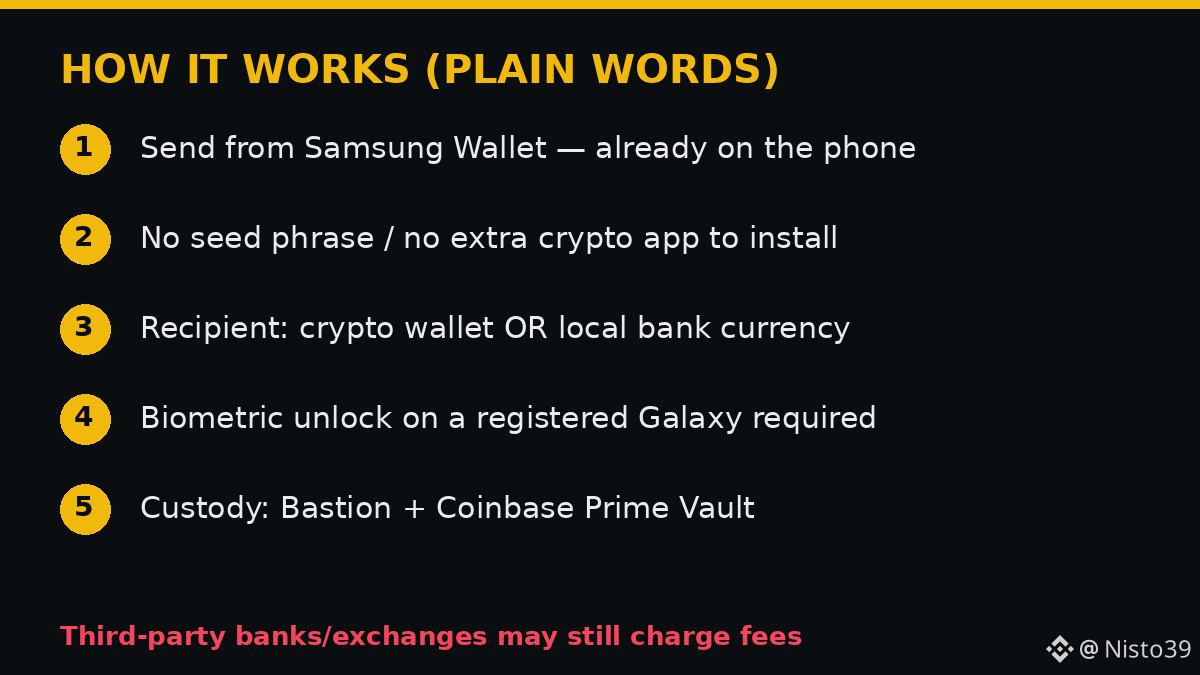
Rails behind it: $SOL and Sui for the blockchain hops. Custody via Bastion / Coinbase Prime Vault. No new crypto app. No seed phrase to memorize.
What recipients get:
• USDC to a compatible crypto wallet abroad, OR
• Local currency into a bank account in 60+ countries — without opening a crypto wallet
• Samsung charges zero fee for transfers to compatible external wallets (recipient banks/exchanges may still take a cut)
Why this matters for someone like Fatou in Dakar:
Her cousin in Houston already uses Samsung Wallet for cards and boarding passes. Remittances usually mean Western Union fees, delays, and a trip to a cash point. If money can leave a phone wallet and land as CFA in a bank — that is the remittance product Africans actually need, not another trading app.
The nuance headlines will skip 👇
• U.S. launch first. Expansion abroad depends on local regulation — Senegal/Ghana/Nigeria timelines are unclear.
• "Zero fee" = Samsung's fee. Third parties can still charge.
• Biometric auth on a registered Galaxy is required — good for security, but it ties the flow to one device brand.
Stablecoins moving salary-sized money is the boring use case that could outlast hype cycles. Phone OEMs shipping it is how it stops being "crypto" and starts being "send money."
Would you trust a phone wallet remittance over a classic money-transfer shop — or not yet? 👇
Not financial advice. Crypto & remittances carry risk: fees, FX, regulation, and custody can change. Only move money you understand.
#USDC #Solana #Remittances
Samsung just put stablecoin remittances inside 82 million Galaxy phones 📱
On Oct 8, CoinDesk reported: starting the last week of October, eligible U.S. Galaxy users can send USDC (a dollar-pegged stablecoin — about one dollar per USDC by design) through Samsung Wallet.
Rails behind it: $SOL and Sui for the blockchain hops. Custody via Bastion / Coinbase Prime Vault. No new crypto app. No seed phrase to memorize.
What recipients get:
• USDC to a compatible crypto wallet abroad, OR
• Local currency into a bank account in 60+ countries — without opening a crypto wallet
• Samsung charges zero fee for transfers to compatible external wallets (recipient banks/exchanges may still take a cut)
Why this matters for someone like Fatou in Dakar:
Her cousin in Houston already uses Samsung Wallet for cards and boarding passes. Remittances usually mean Western Union fees, delays, and a trip to a cash point. If money can leave a phone wallet and land as CFA in a bank — that is the remittance product Africans actually need, not another trading app.
The nuance headlines will skip 👇
• U.S. launch first. Expansion abroad depends on local regulation — Senegal/Ghana/Nigeria timelines are unclear.
• "Zero fee" = Samsung's fee. Third parties can still charge.
• Biometric auth on a registered Galaxy is required — good for security, but it ties the flow to one device brand.
Stablecoins moving salary-sized money is the boring use case that could outlast hype cycles. Phone OEMs shipping it is how it stops being "crypto" and starts being "send money."
Would you trust a phone wallet remittance over a classic money-transfer shop — or not yet? 👇
Not financial advice. Crypto & remittances carry risk: fees, FX, regulation, and custody can change. Only move money you understand.
#USDC #Solana #Remittances
On Oct 8, CoinDesk reported: starting the last week of October, eligible U.S. Galaxy users can send USDC (a dollar-pegged stablecoin — about one dollar per USDC by design) through Samsung Wallet.
Rails behind it: $SOL and Sui for the blockchain hops. Custody via Bastion / Coinbase Prime Vault. No new crypto app. No seed phrase to memorize.
What recipients get:
• USDC to a compatible crypto wallet abroad, OR
• Local currency into a bank account in 60+ countries — without opening a crypto wallet
• Samsung charges zero fee for transfers to compatible external wallets (recipient banks/exchanges may still take a cut)
Why this matters for someone like Fatou in Dakar:
Her cousin in Houston already uses Samsung Wallet for cards and boarding passes. Remittances usually mean Western Union fees, delays, and a trip to a cash point. If money can leave a phone wallet and land as CFA in a bank — that is the remittance product Africans actually need, not another trading app.
The nuance headlines will skip 👇
• U.S. launch first. Expansion abroad depends on local regulation — Senegal/Ghana/Nigeria timelines are unclear.
• "Zero fee" = Samsung's fee. Third parties can still charge.
• Biometric auth on a registered Galaxy is required — good for security, but it ties the flow to one device brand.
Stablecoins moving salary-sized money is the boring use case that could outlast hype cycles. Phone OEMs shipping it is how it stops being "crypto" and starts being "send money."
Would you trust a phone wallet remittance over a classic money-transfer shop — or not yet? 👇
Not financial advice. Crypto & remittances carry risk: fees, FX, regulation, and custody can change. Only move money you understand.
#USDC #Solana #Remittances
84
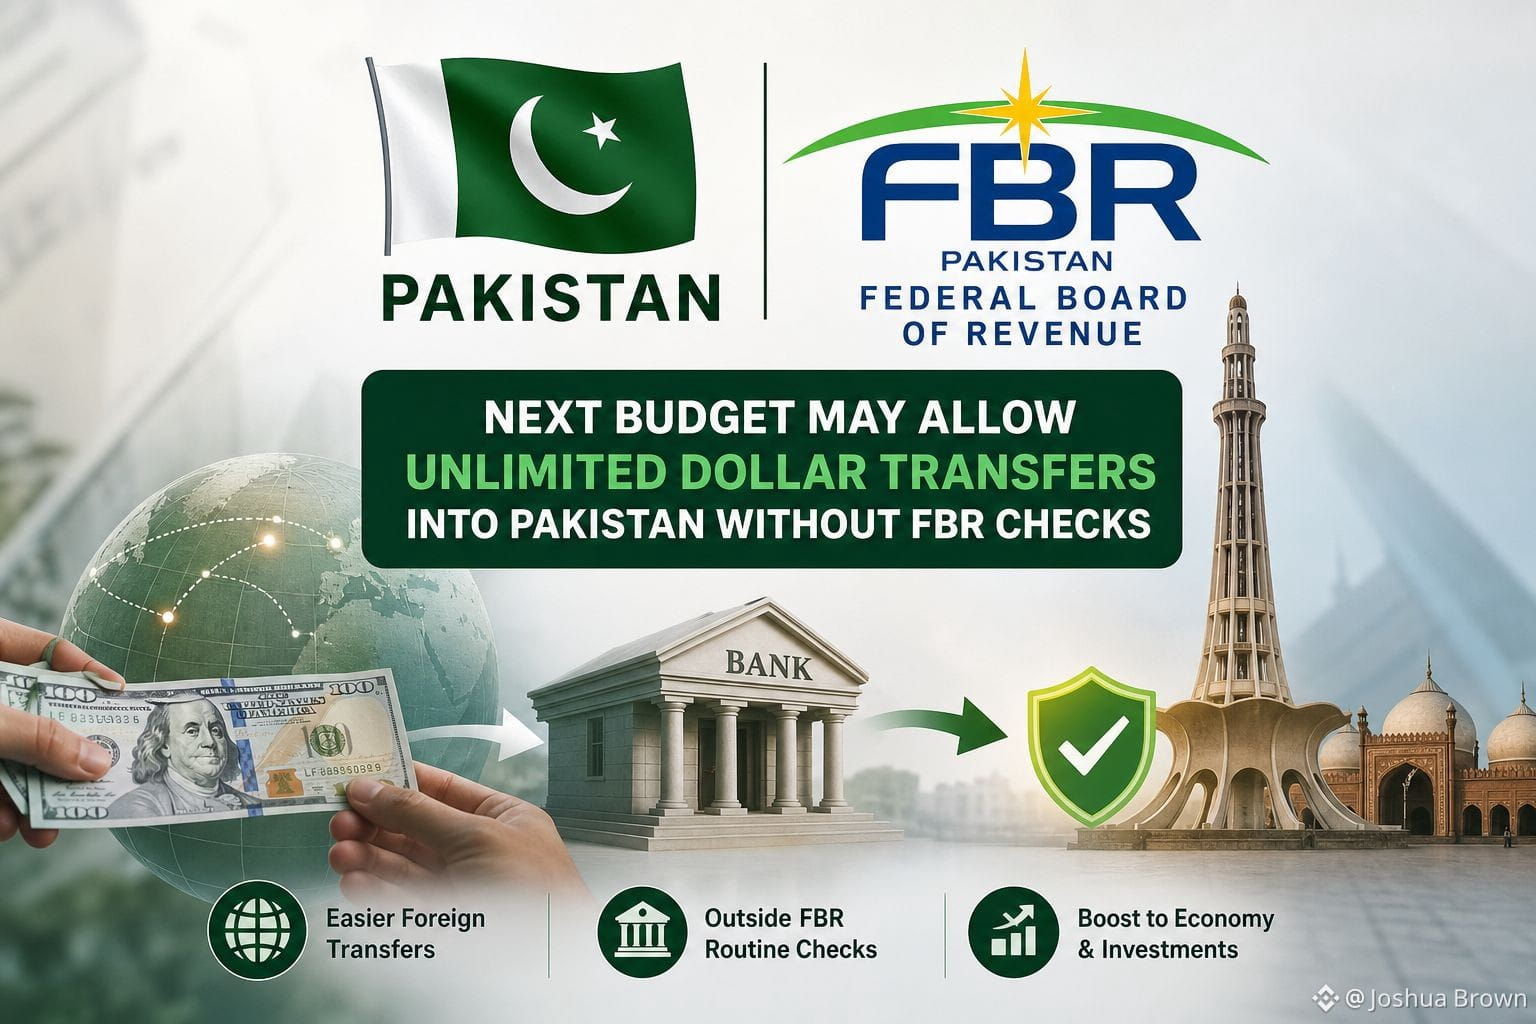
#news $BTC Pakistan may soon remove the Rs 5 million cap on foreign currency transfers received through banks. If this move gets approved, funds sent through formal banking channels could stay outside routine FBR questioning under Section 111(4).
From my view, this is a positive signal for overseas Pakistanis and for the banking sector. It can help bring more remittance flows into official channels, improve trust in the system, and make cross-border transfers more convinent for many families and investors.
A stronger banking route for incoming funds may also support foreign exchange reserves over time. The real impact will depend on the final policy details, but the direction looks encouraging.
I will be watching closely to see how the goverment structures the final framework and what it means for future capital inflows into Pakistan.
#crypto #Remittances #FBR #Banking #Economy #Finance #Investment
{spot}(BTCUSDT)
{spot}(ETHUSDT)
{spot}(BNBUSDT)
#news $BTC Pakistan may soon remove the Rs 5 million cap on foreign currency transfers received through banks. If this move gets approved, funds sent through formal banking channels could stay outside routine FBR questioning under Section 111(4).
From my view, this is a positive signal for overseas Pakistanis and for the banking sector. It can help bring more remittance flows into official channels, improve trust in the system, and make cross-border transfers more convinent for many families and investors.
A stronger banking route for incoming funds may also support foreign exchange reserves over time. The real impact will depend on the final policy details, but the direction looks encouraging.
I will be watching closely to see how the goverment structures the final framework and what it means for future capital inflows into Pakistan.
#crypto #Remittances #FBR #Banking #Economy #Finance #Investment
From my view, this is a positive signal for overseas Pakistanis and for the banking sector. It can help bring more remittance flows into official channels, improve trust in the system, and make cross-border transfers more convinent for many families and investors.
A stronger banking route for incoming funds may also support foreign exchange reserves over time. The real impact will depend on the final policy details, but the direction looks encouraging.
I will be watching closely to see how the goverment structures the final framework and what it means for future capital inflows into Pakistan.
#crypto #Remittances #FBR #Banking #Economy #Finance #Investment
4
119
The @trondao gas-free stablecoin transfer feature is revolutionary. Imagine sending USDT without paying any gas fee at all. That is what is being tested on TRON. This removes the last barrier to mainstream adoption. When sending money costs nothing, there is no reason not to use blockchain. The traditional remittance industry charges 7-10 percent. TRON makes it free. This is not incremental improvement. This is disruption. @trondao @justinsun @tether_to #GasFree #Stablecoins #Remittances
The @trondao gas-free stablecoin transfer feature is revolutionary. Imagine sending USDT without paying any gas fee at all. That is what is being tested on TRON. This removes the last barrier to mainstream adoption. When sending money costs nothing, there is no reason not to use blockchain. The traditional remittance industry charges 7-10 percent. TRON makes it free. This is not incremental improvement. This is disruption. @trondao @justinsun @tether_to #GasFree #Stablecoins #Remittances
40

·
--
Verified
Why is a South Korean regional bank turning to Ripple's payment technology? Jeonbuk Bank is deploying Ripple Payments for cross-border remittances, becoming the first regional bank in the country to do so. The service targets businesses like import-export companies, IT startups, and online content creators. Traditional transfers can take days as payments move through multiple intermediary banks, while Ripple's network settles in seconds or minutes and operates around the clock. The bank's president said the partnership helps Jeonbuk move beyond its regional role and become a global-standard digital finance leader. This deal follows two other Ripple collaborations in South Korea this year, including a tokenized government bond project with Kyobo Life Insurance and a cross-border transfer proof of concept with KBank. RLUSD is reportedly now listed on the country's four largest crypto exchanges. $XRP #XRP #Ripple #Crypto #Remittances
Why is a South Korean regional bank turning to Ripple's payment technology? Jeonbuk Bank is deploying Ripple Payments for cross-border remittances, becoming the first regional bank in the country to do so. The service targets businesses like import-export companies, IT startups, and online content creators. Traditional transfers can take days as payments move through multiple intermediary banks, while Ripple's network settles in seconds or minutes and operates around the clock. The bank's president said the partnership helps Jeonbuk move beyond its regional role and become a global-standard digital finance leader. This deal follows two other Ripple collaborations in South Korea this year, including a tokenized government bond project with Kyobo Life Insurance and a cross-border transfer proof of concept with KBank. RLUSD is reportedly now listed on the country's four largest crypto exchanges. $XRP #XRP #Ripple #Crypto #Remittances
74

·
--
Everyone thinks the lowest-fee remittance app wins, but actually, identical pricing can hide very different risks.
Crypto traders often compare fees, rush into the first product that looks cheap, and only later discover weak liquidity, slow settlement, or no real advantage. A low fee does not automatically mean a better exit or a safer transfer.
1) Two remittance startups launch on the same corridor. 2) They operate in the same jurisdictions. 3) Their fees are nearly identical. On day one, they can look impossible to distinguish.
That is where the mistake begins. If both companies rely on the same rails, including assets such as $USDC, $USDT, or $XRP, the real difference may come from liquidity, compliance, settlement speed, and user retention. Fees are the price tag, not the whole product.
Would you choose based on fees alone, or wait to see which startup proves its edge?
#Crypto #Remittances #Payments
Everyone thinks the lowest-fee remittance app wins, but actually, identical pricing can hide very different risks.
Crypto traders often compare fees, rush into the first product that looks cheap, and only later discover weak liquidity, slow settlement, or no real advantage. A low fee does not automatically mean a better exit or a safer transfer.
1) Two remittance startups launch on the same corridor. 2) They operate in the same jurisdictions. 3) Their fees are nearly identical. On day one, they can look impossible to distinguish.
That is where the mistake begins. If both companies rely on the same rails, including assets such as $USDC , $USDT, or $XRP , the real difference may come from liquidity, compliance, settlement speed, and user retention. Fees are the price tag, not the whole product.
Would you choose based on fees alone, or wait to see which startup proves its edge?
#Crypto #Remittances #Payments
Crypto traders often compare fees, rush into the first product that looks cheap, and only later discover weak liquidity, slow settlement, or no real advantage. A low fee does not automatically mean a better exit or a safer transfer.
1) Two remittance startups launch on the same corridor. 2) They operate in the same jurisdictions. 3) Their fees are nearly identical. On day one, they can look impossible to distinguish.
That is where the mistake begins. If both companies rely on the same rails, including assets such as $USDC , $USDT, or $XRP , the real difference may come from liquidity, compliance, settlement speed, and user retention. Fees are the price tag, not the whole product.
Would you choose based on fees alone, or wait to see which startup proves its edge?
#Crypto #Remittances #Payments
81

·
--
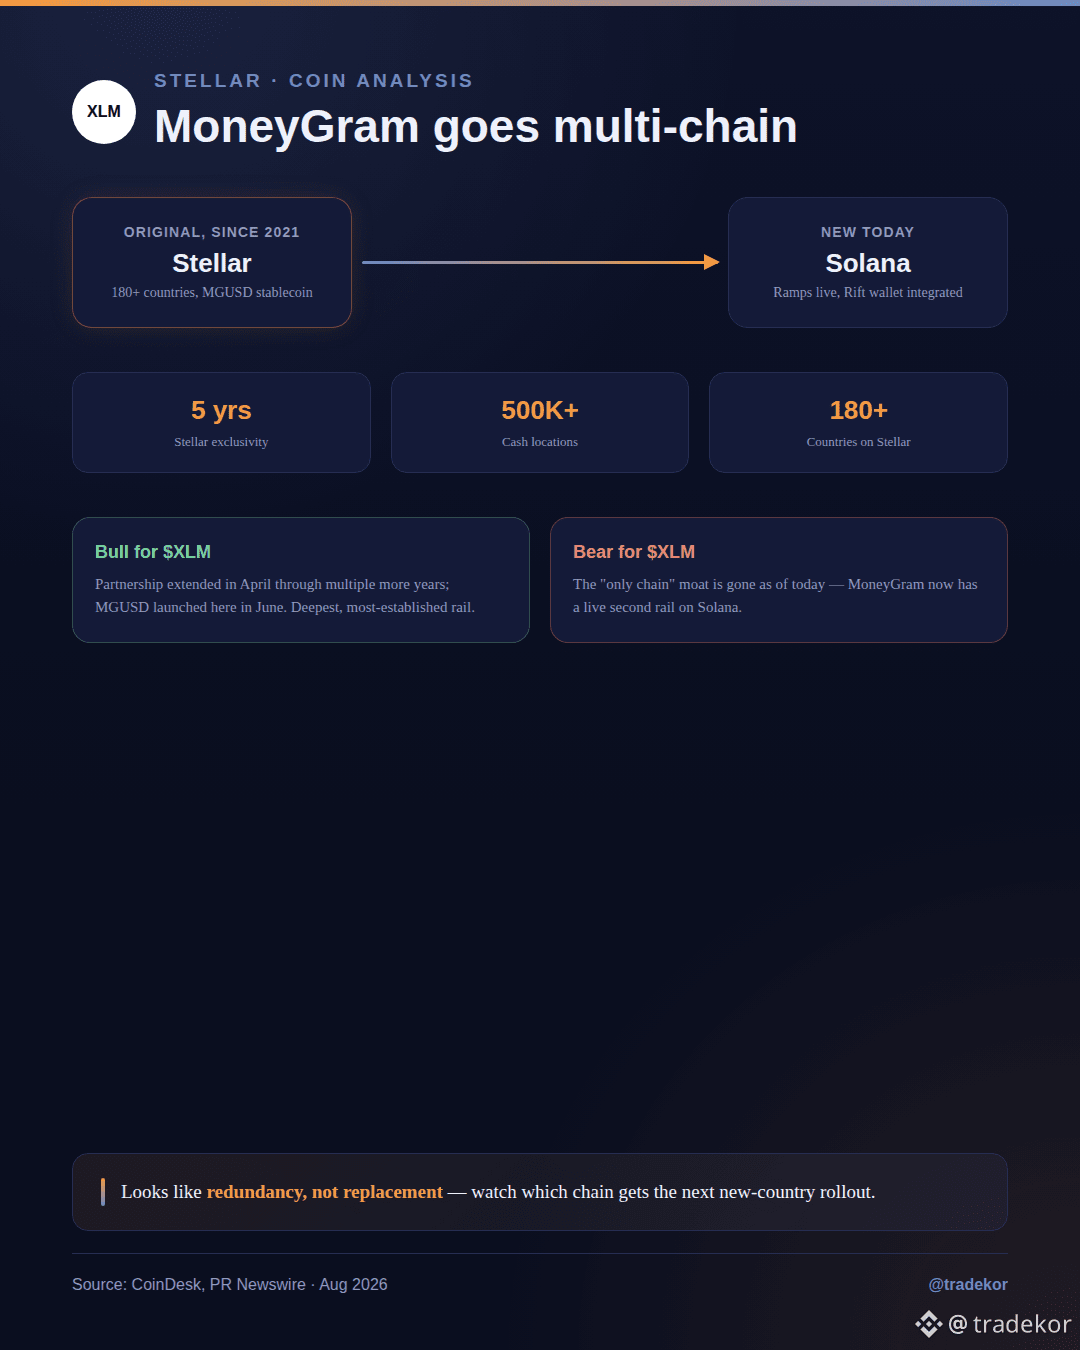
After 5 years on Stellar alone, MoneyGram just launched its remittance ramp on a second blockchain today.
The bull case for $XLM: this isn't a breakup. MoneyGram and Stellar extended their partnership in April for multiple more years, MGUSD (MoneyGram's own dollar stablecoin) launched on Stellar in June, and the integration now spans 180+ countries and 500,000+ cash locations. Stellar remains the deepest, most-established leg of MoneyGram's stack.
The bear case: today MoneyGram Ramps went live on Solana too, with Rift as the first wallet integration — on top of MoneyGram becoming an active Solana validator back in June. That's a real diversification signal. Stellar's moat here was being MoneyGram's only chain; it no longer is.
Our read: this looks like MoneyGram building redundancy and reach, not replacing Stellar — remittance infrastructure benefits from multiple rails, and Stellar's deeper, older integration (180+ countries vs. Solana's fresh launch) is hard to displace quickly. Falsifiable — if MoneyGram's stablecoin volume or new country rollouts start favoring Solana over the next two quarters, that's real share loss for Stellar. If Stellar keeps getting the bulk of new MoneyGram integrations, this was additive.
Not financial advice. DYOR.
#Stellar #MoneyGram #Remittances #CryptoAnalysis
After 5 years on Stellar alone, MoneyGram just launched its remittance ramp on a second blockchain today.
The bull case for $XLM : this isn't a breakup. MoneyGram and Stellar extended their partnership in April for multiple more years, MGUSD (MoneyGram's own dollar stablecoin) launched on Stellar in June, and the integration now spans 180+ countries and 500,000+ cash locations. Stellar remains the deepest, most-established leg of MoneyGram's stack.
The bear case: today MoneyGram Ramps went live on Solana too, with Rift as the first wallet integration — on top of MoneyGram becoming an active Solana validator back in June. That's a real diversification signal. Stellar's moat here was being MoneyGram's only chain; it no longer is.
Our read: this looks like MoneyGram building redundancy and reach, not replacing Stellar — remittance infrastructure benefits from multiple rails, and Stellar's deeper, older integration (180+ countries vs. Solana's fresh launch) is hard to displace quickly. Falsifiable — if MoneyGram's stablecoin volume or new country rollouts start favoring Solana over the next two quarters, that's real share loss for Stellar. If Stellar keeps getting the bulk of new MoneyGram integrations, this was additive.
Not financial advice. DYOR.
#Stellar #MoneyGram #Remittances #CryptoAnalysis
The bull case for $XLM : this isn't a breakup. MoneyGram and Stellar extended their partnership in April for multiple more years, MGUSD (MoneyGram's own dollar stablecoin) launched on Stellar in June, and the integration now spans 180+ countries and 500,000+ cash locations. Stellar remains the deepest, most-established leg of MoneyGram's stack.
The bear case: today MoneyGram Ramps went live on Solana too, with Rift as the first wallet integration — on top of MoneyGram becoming an active Solana validator back in June. That's a real diversification signal. Stellar's moat here was being MoneyGram's only chain; it no longer is.
Our read: this looks like MoneyGram building redundancy and reach, not replacing Stellar — remittance infrastructure benefits from multiple rails, and Stellar's deeper, older integration (180+ countries vs. Solana's fresh launch) is hard to displace quickly. Falsifiable — if MoneyGram's stablecoin volume or new country rollouts start favoring Solana over the next two quarters, that's real share loss for Stellar. If Stellar keeps getting the bulk of new MoneyGram integrations, this was additive.
Not financial advice. DYOR.
#Stellar #MoneyGram #Remittances #CryptoAnalysis
67
·
--

Article
Focus on Cross-Border Remittance Efficiency💸 Borderless Value: How $BTC
{spot}(BTCUSDT)
Is Revolutionizing Cross-Border Remittances 🌍
The legacy international payment system is fundamentally broken, plagued by slow processing times, predatory intermediary bank fees, and rigid operating hours. Fortunately, @Bitcoinworld provides a frictionless alternative by functioning as an open-source, global financial settlement network. Using this decentralized protocol, anyone with an internet connection can send capital across the planet instantly for a fraction of a dollar.
This technological leap is life-changing for millions of migrant workers who rely on international remittances to support their families back home. Instead of losing a massive percentage of their hard-earned income to traditional money transfer corporations, families receive the full value of the capital sent.
By operating continuously without central points of failure, the network democratizes access to basic financial tools. It bypasses geography and political borders entirely, transforming the global remittance market into a peer-to-peer system that treats every user with complete equality. 🚀
#GoogleLaunchesGemini3.5Flash #Remittances #GlobalPayments #fintech #FinancialInclusio
Focus on Cross-Border Remittance Efficiency
💸 Borderless Value: How $BTC
Is Revolutionizing Cross-Border Remittances 🌍
The legacy international payment system is fundamentally broken, plagued by slow processing times, predatory intermediary bank fees, and rigid operating hours. Fortunately, @Bitcoinworld provides a frictionless alternative by functioning as an open-source, global financial settlement network. Using this decentralized protocol, anyone with an internet connection can send capital across the planet instantly for a fraction of a dollar.
This technological leap is life-changing for millions of migrant workers who rely on international remittances to support their families back home. Instead of losing a massive percentage of their hard-earned income to traditional money transfer corporations, families receive the full value of the capital sent.
By operating continuously without central points of failure, the network democratizes access to basic financial tools. It bypasses geography and political borders entirely, transforming the global remittance market into a peer-to-peer system that treats every user with complete equality. 🚀
#GoogleLaunchesGemini3.5Flash #Remittances #GlobalPayments #fintech #FinancialInclusio
Is Revolutionizing Cross-Border Remittances 🌍
The legacy international payment system is fundamentally broken, plagued by slow processing times, predatory intermediary bank fees, and rigid operating hours. Fortunately, @Bitcoinworld provides a frictionless alternative by functioning as an open-source, global financial settlement network. Using this decentralized protocol, anyone with an internet connection can send capital across the planet instantly for a fraction of a dollar.
This technological leap is life-changing for millions of migrant workers who rely on international remittances to support their families back home. Instead of losing a massive percentage of their hard-earned income to traditional money transfer corporations, families receive the full value of the capital sent.
By operating continuously without central points of failure, the network democratizes access to basic financial tools. It bypasses geography and political borders entirely, transforming the global remittance market into a peer-to-peer system that treats every user with complete equality. 🚀
#GoogleLaunchesGemini3.5Flash #Remittances #GlobalPayments #fintech #FinancialInclusio
68
TRON'S CROSS-BORDER PAYMENT RAILS: CONNECTING THE WORLD 💸
Cross-border payments are one of blockchain's most compelling use cases, and TRON has become the leading network for international transfers.
Traditional cross-border transfers take 3-5 days and cost 5-10% in fees. TRON transfers settle in 3 seconds for less than $0.01.
For the 280 million migrants worldwide sending money home, TRON offers a lifeline.
As global commerce digitalizes, TRON's cross-border infrastructure becomes increasingly valuable.
@TRON DAO
#TRONEcoStar #CrossBorder #Remittances
TRON'S CROSS-BORDER PAYMENT RAILS: CONNECTING THE WORLD 💸
Cross-border payments are one of blockchain's most compelling use cases, and TRON has become the leading network for international transfers.
Traditional cross-border transfers take 3-5 days and cost 5-10% in fees. TRON transfers settle in 3 seconds for less than $0.01.
For the 280 million migrants worldwide sending money home, TRON offers a lifeline.
As global commerce digitalizes, TRON's cross-border infrastructure becomes increasingly valuable.
@TRON DAO
#TRONEcoStar #CrossBorder #Remittances
Cross-border payments are one of blockchain's most compelling use cases, and TRON has become the leading network for international transfers.
Traditional cross-border transfers take 3-5 days and cost 5-10% in fees. TRON transfers settle in 3 seconds for less than $0.01.
For the 280 million migrants worldwide sending money home, TRON offers a lifeline.
As global commerce digitalizes, TRON's cross-border infrastructure becomes increasingly valuable.
@TRON DAO
#TRONEcoStar #CrossBorder #Remittances
18

🚨 JUST IN: South Korea keeps getting more serious about crypto infrastructure.
Toss Bank, managing over 30 trillion won in assets and serving 15 million users, has partnered with $SOL to explore blockchain-powered remittances, including stablecoin transfers.
This is a bigger deal than many people realize.
For years, crypto has talked about replacing slow and expensive cross-border payments. Now we're seeing established financial institutions actually testing that idea with real users, not just crypto natives.
Toss becomes the first internet-only bank in South Korea and only the second Korean financial institution to partner with Solana. If successful, this could help make international transfers faster, cheaper, and available around the clock.
The market loves to focus on memes and hype, but adoption stories like this are what really matter in the long run.
👀 Another step toward blockchain moving from speculation to real-world utility.
#Crypto #Stablecoins #Blockchain #Remittances #Web3
{future}(SOLUSDT)
🚨 JUST IN: South Korea keeps getting more serious about crypto infrastructure.
Toss Bank, managing over 30 trillion won in assets and serving 15 million users, has partnered with $SOL to explore blockchain-powered remittances, including stablecoin transfers.
This is a bigger deal than many people realize.
For years, crypto has talked about replacing slow and expensive cross-border payments. Now we're seeing established financial institutions actually testing that idea with real users, not just crypto natives.
Toss becomes the first internet-only bank in South Korea and only the second Korean financial institution to partner with Solana. If successful, this could help make international transfers faster, cheaper, and available around the clock.
The market loves to focus on memes and hype, but adoption stories like this are what really matter in the long run.
👀 Another step toward blockchain moving from speculation to real-world utility.
#Crypto #Stablecoins #Blockchain #Remittances #Web3
Toss Bank, managing over 30 trillion won in assets and serving 15 million users, has partnered with $SOL to explore blockchain-powered remittances, including stablecoin transfers.
This is a bigger deal than many people realize.
For years, crypto has talked about replacing slow and expensive cross-border payments. Now we're seeing established financial institutions actually testing that idea with real users, not just crypto natives.
Toss becomes the first internet-only bank in South Korea and only the second Korean financial institution to partner with Solana. If successful, this could help make international transfers faster, cheaper, and available around the clock.
The market loves to focus on memes and hype, but adoption stories like this are what really matter in the long run.
👀 Another step toward blockchain moving from speculation to real-world utility.
#Crypto #Stablecoins #Blockchain #Remittances #Web3
210
·
--
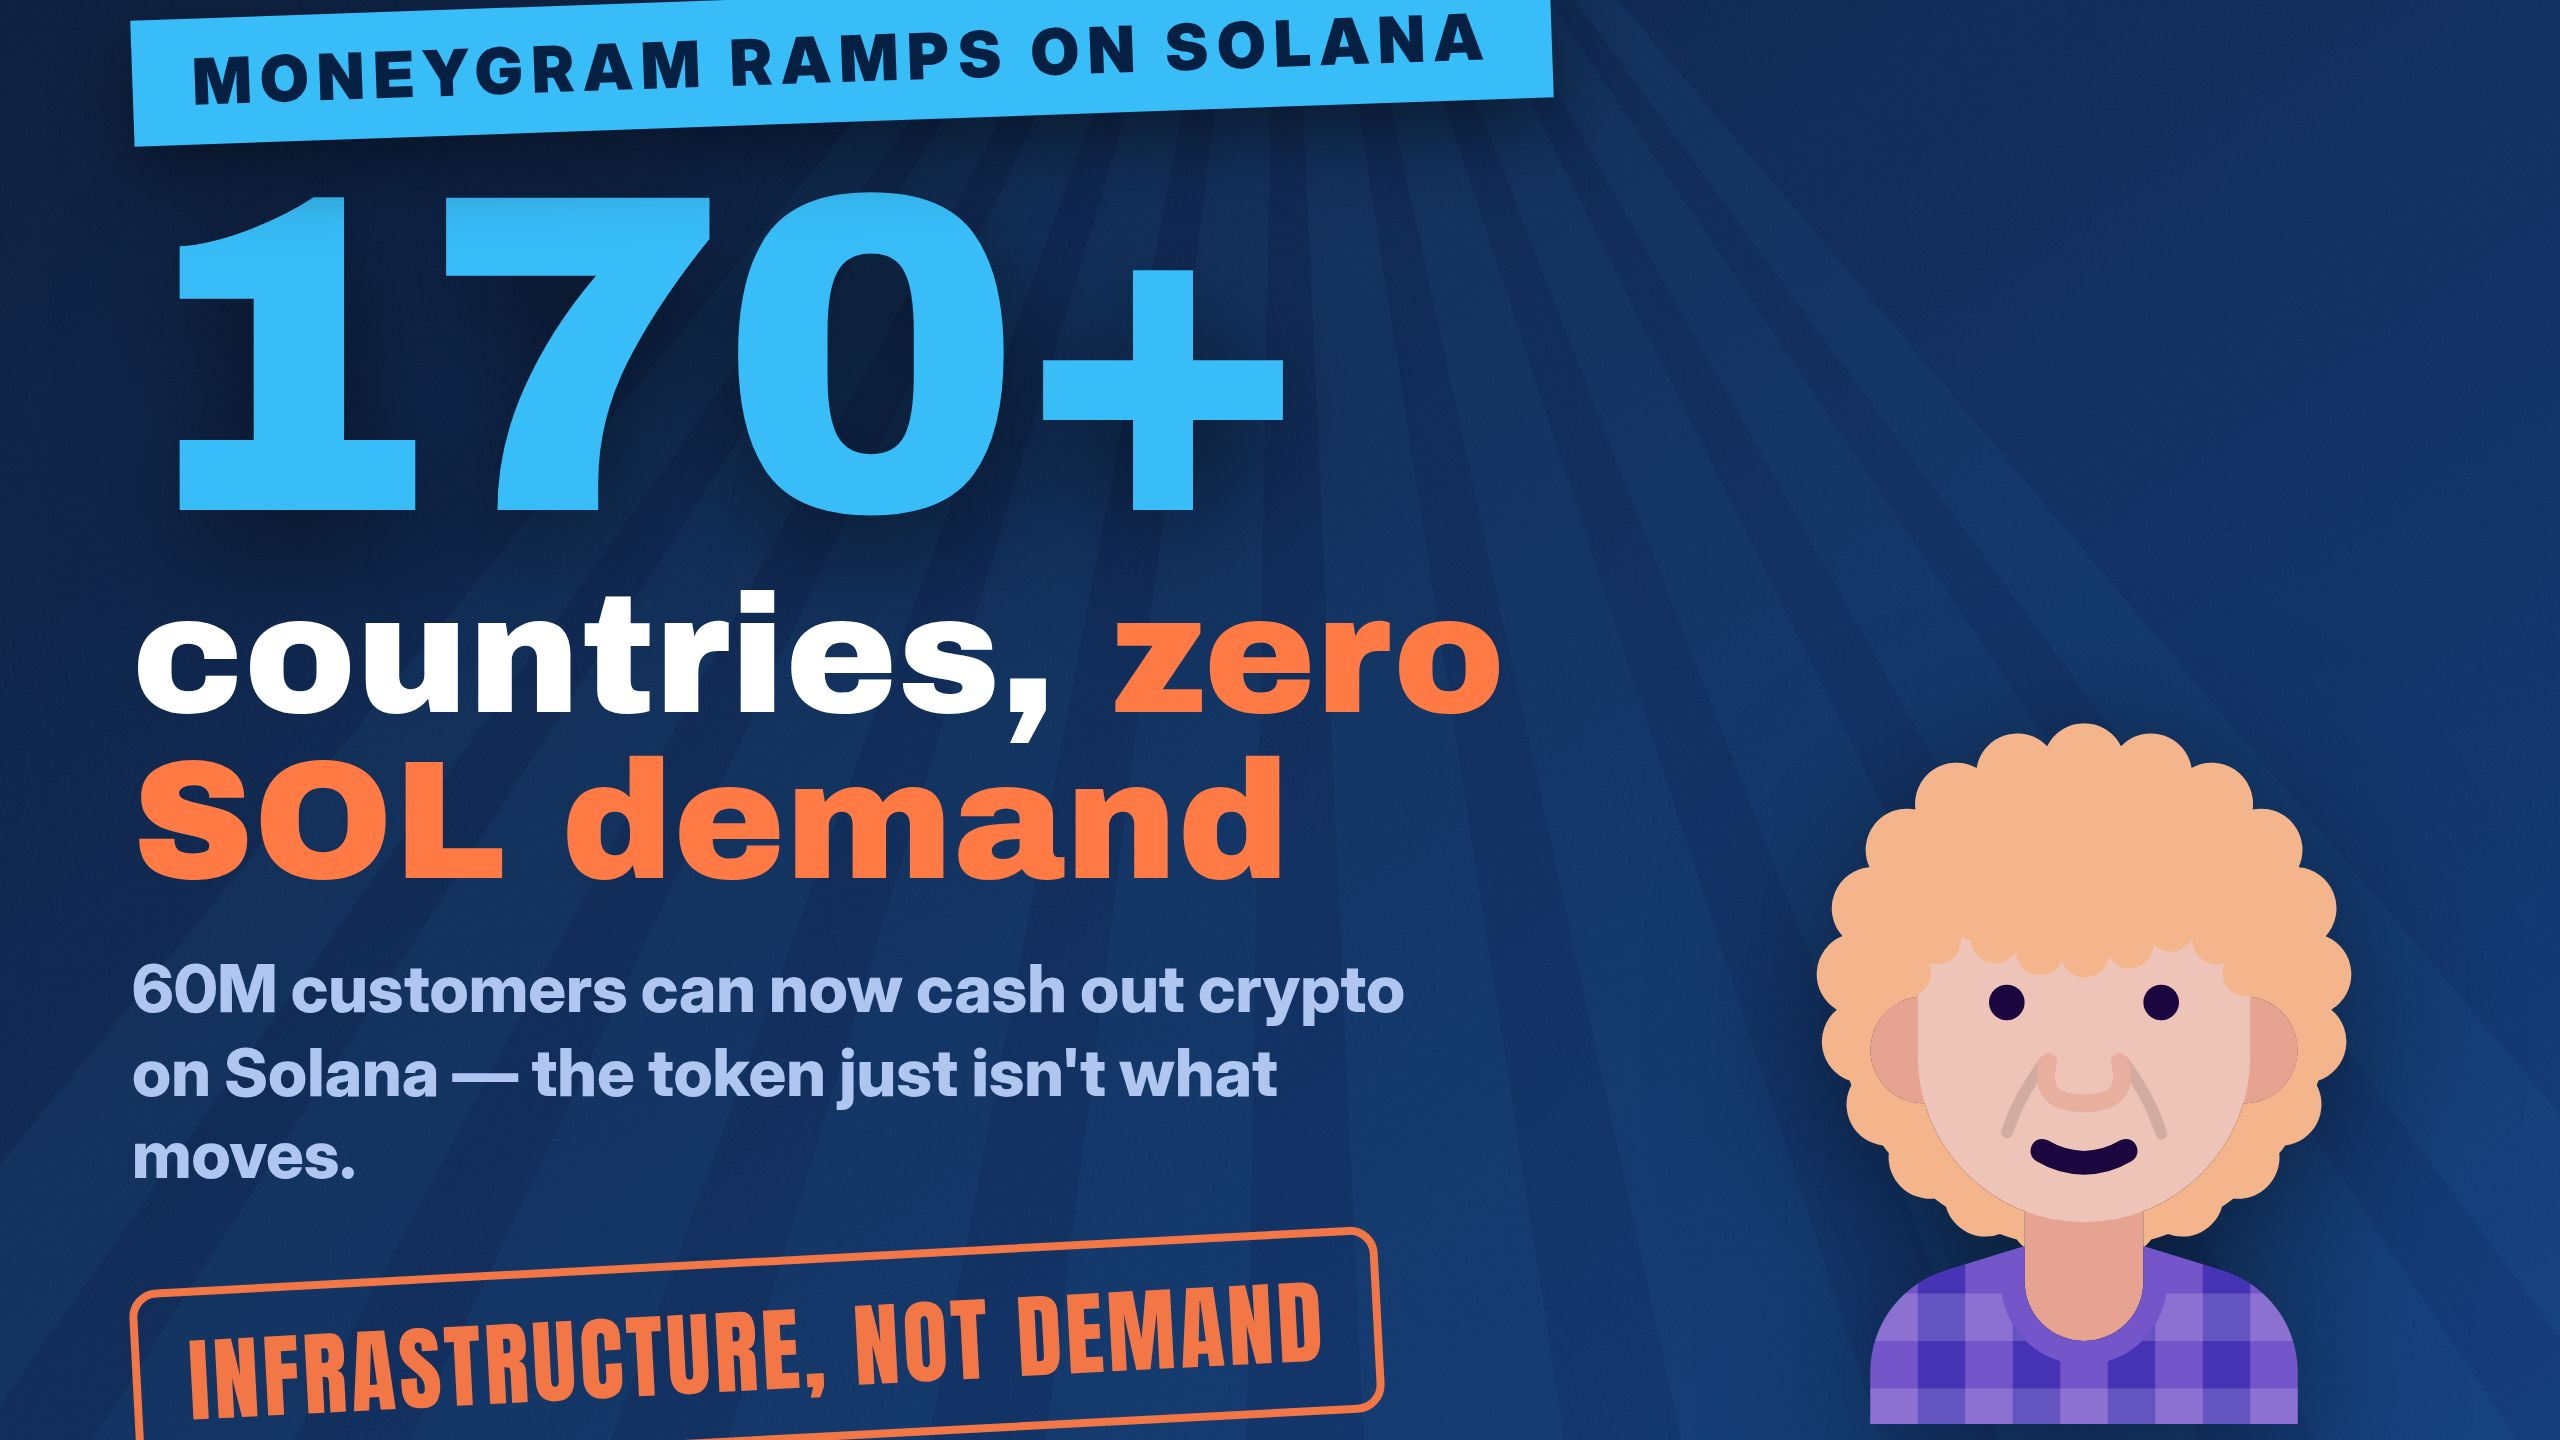
MoneyGram just plugged 60 million customers and 500,000 cash locations into Solana — and $SOL still doesn't directly benefit from a single dollar that moves through it.
The news: MoneyGram's "Ramps" API went live on Solana around August 10-12, letting people deposit cash in 25+ countries and withdraw cash in 170+ countries/territories straight from a Solana wallet. Rift became the first wallet to integrate it. This is a shipped, working cash-to-crypto bridge, not a partnership announcement or an MOU.
The catch: what moves across that rail is stablecoins, not SOL. Solana is the settlement layer underneath — fast, cheap block space — but customers are converting cash to USDC, not buying SOL. The token's role is infrastructure, not the product, and Solana already has several competing ramp partners, so this is additive, not exclusive.
SOL broke back above $75 resistance around August 15, helped by roughly $8.8M in ETF inflows and short-covering — separate from this integration, worth not conflating with it.
Our read: a real, durable proof point for Solana as cross-border settlement rail — genuinely useful for remittances and payroll-in-crypto. It's a win for network relevance, not a direct SOL demand shock. Falsifiable: watch whether MoneyGram's stablecoin volume on Solana shows up on-chain, and whether that lifts real SOL fee/activity.
Does infrastructure adoption ever actually move the token, or is this the same gap we keep seeing?
Not financial advice. DYOR.
$SOL #Solana #MoneyGram #CryptoAdoption #Remittances
MoneyGram just plugged 60 million customers and 500,000 cash locations into Solana — and $SOL still doesn't directly benefit from a single dollar that moves through it.
The news: MoneyGram's "Ramps" API went live on Solana around August 10-12, letting people deposit cash in 25+ countries and withdraw cash in 170+ countries/territories straight from a Solana wallet. Rift became the first wallet to integrate it. This is a shipped, working cash-to-crypto bridge, not a partnership announcement or an MOU.
The catch: what moves across that rail is stablecoins, not SOL. Solana is the settlement layer underneath — fast, cheap block space — but customers are converting cash to USDC, not buying SOL. The token's role is infrastructure, not the product, and Solana already has several competing ramp partners, so this is additive, not exclusive.
SOL broke back above $75 resistance around August 15, helped by roughly $8.8M in ETF inflows and short-covering — separate from this integration, worth not conflating with it.
Our read: a real, durable proof point for Solana as cross-border settlement rail — genuinely useful for remittances and payroll-in-crypto. It's a win for network relevance, not a direct SOL demand shock. Falsifiable: watch whether MoneyGram's stablecoin volume on Solana shows up on-chain, and whether that lifts real SOL fee/activity.
Does infrastructure adoption ever actually move the token, or is this the same gap we keep seeing?
Not financial advice. DYOR.
$SOL #Solana #MoneyGram #CryptoAdoption #Remittances
The news: MoneyGram's "Ramps" API went live on Solana around August 10-12, letting people deposit cash in 25+ countries and withdraw cash in 170+ countries/territories straight from a Solana wallet. Rift became the first wallet to integrate it. This is a shipped, working cash-to-crypto bridge, not a partnership announcement or an MOU.
The catch: what moves across that rail is stablecoins, not SOL. Solana is the settlement layer underneath — fast, cheap block space — but customers are converting cash to USDC, not buying SOL. The token's role is infrastructure, not the product, and Solana already has several competing ramp partners, so this is additive, not exclusive.
SOL broke back above $75 resistance around August 15, helped by roughly $8.8M in ETF inflows and short-covering — separate from this integration, worth not conflating with it.
Our read: a real, durable proof point for Solana as cross-border settlement rail — genuinely useful for remittances and payroll-in-crypto. It's a win for network relevance, not a direct SOL demand shock. Falsifiable: watch whether MoneyGram's stablecoin volume on Solana shows up on-chain, and whether that lifts real SOL fee/activity.
Does infrastructure adoption ever actually move the token, or is this the same gap we keep seeing?
Not financial advice. DYOR.
$SOL #Solana #MoneyGram #CryptoAdoption #Remittances
30
WhatsApp activates crypto payments in Latin America! ⚡️📱
A major milestone for adoption in our region. WhatsApp is officially becoming a crypto payment interface in Latam, allowing users to send and receive digital assets and stablecoins (like $USDT ) directly within their chats. This move promises to revolutionize the remittance market and financial inclusion for millions without access to traditional banking. 🚀💸
✅ The advantage: Instant cross-border transfers, no technical friction, and microscopic fees. ✅ The impact: Web3 goes mainstream by integrating into the most used app on the continent.
Have you set up your digital wallet on @Binance to connect with the new messaging economies? 📊
#WhatsApp #Stablecoins #Remittances #LatinAmerica #Binance $BTC $ETH
WhatsApp activates crypto payments in Latin America! ⚡️📱
A major milestone for adoption in our region. WhatsApp is officially becoming a crypto payment interface in Latam, allowing users to send and receive digital assets and stablecoins (like $USDT ) directly within their chats. This move promises to revolutionize the remittance market and financial inclusion for millions without access to traditional banking. 🚀💸
✅ The advantage: Instant cross-border transfers, no technical friction, and microscopic fees. ✅ The impact: Web3 goes mainstream by integrating into the most used app on the continent.
Have you set up your digital wallet on @Binance to connect with the new messaging economies? 📊
#WhatsApp #Stablecoins #Remittances #LatinAmerica #Binance $BTC $ETH
A major milestone for adoption in our region. WhatsApp is officially becoming a crypto payment interface in Latam, allowing users to send and receive digital assets and stablecoins (like $USDT ) directly within their chats. This move promises to revolutionize the remittance market and financial inclusion for millions without access to traditional banking. 🚀💸
✅ The advantage: Instant cross-border transfers, no technical friction, and microscopic fees. ✅ The impact: Web3 goes mainstream by integrating into the most used app on the continent.
Have you set up your digital wallet on @Binance to connect with the new messaging economies? 📊
#WhatsApp #Stablecoins #Remittances #LatinAmerica #Binance $BTC $ETH
2
195
·
--
Article
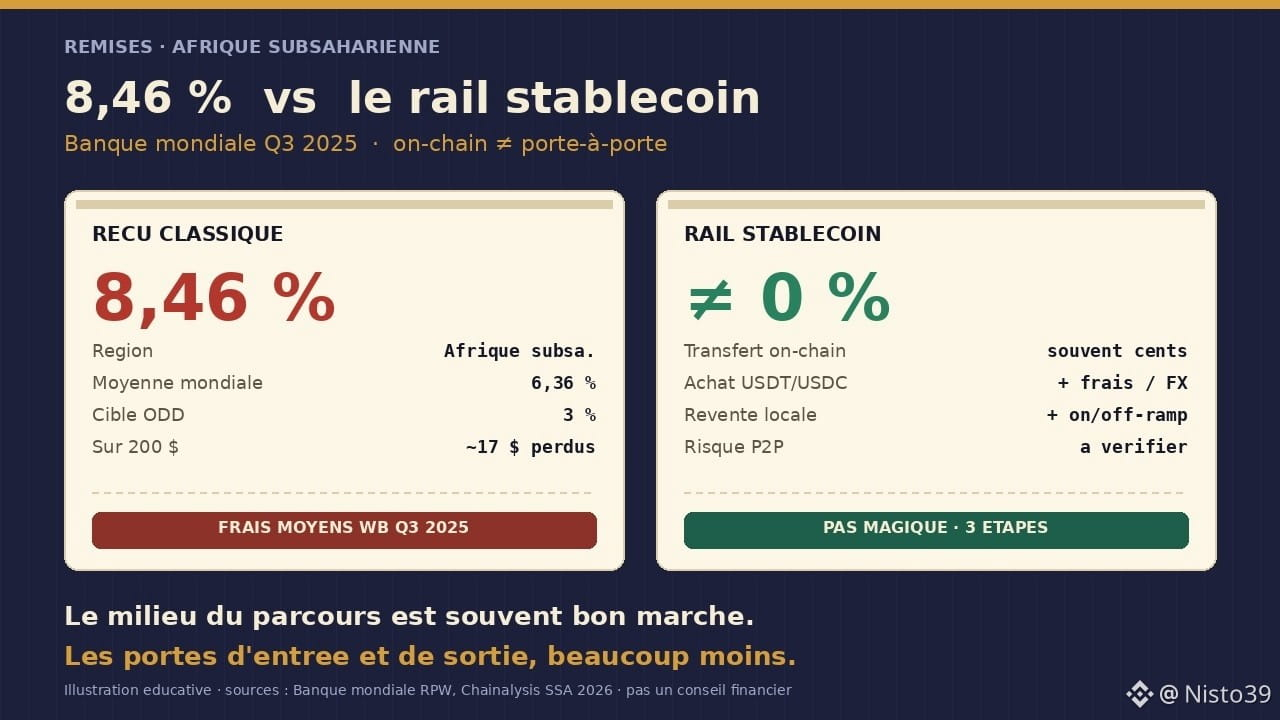
8.46%: the real cost of sending money to Africa8.46%. This is the average cost of sending money to Sub-Saharan Africa in the third quarter of 2025, according to the World Bank’s Remittance Prices Worldwide. The global average is 6.36%. Africa remains the most expensive region. The Sustainable Development Goal, meanwhile, targets 3%. We’re not there yet.
I’m not saying stablecoins have “solved” money transfers. I’m saying the gap between traditional costs and what a digital rail can offer deserves a closer look, without magic or marketing.
8.46%: the real cost of sending money to Africa
8.46%. This is the average cost of sending money to Sub-Saharan Africa in the third quarter of 2025, according to the World Bank’s Remittance Prices Worldwide. The global average is 6.36%. Africa remains the most expensive region. The Sustainable Development Goal, meanwhile, targets 3%. We’re not there yet.
I’m not saying stablecoins have “solved” money transfers. I’m saying the gap between traditional costs and what a digital rail can offer deserves a closer look, without magic or marketing.
I’m not saying stablecoins have “solved” money transfers. I’m saying the gap between traditional costs and what a digital rail can offer deserves a closer look, without magic or marketing.
66

Crypto remittances from Canada to Asia rose 141% to $2.36 billion
- According to Chainalysis, crypto transactions involving remittances from Canada to three Asian countries totaled $2.36 billion.
- Remittances to the Philippines alone rose 28% to $61 million.
- RSS data did not provide further details about the other countries or the reasons for the growth.
#CryptoNews #Chainalysis #Remittances #Canada #Asia
$btc $eth
vlikevn Titanbot
Source: CoinTelegraph
Crypto remittances from Canada to Asia rose 141% to $2.36 billion
- According to Chainalysis, crypto transactions involving remittances from Canada to three Asian countries totaled $2.36 billion.
- Remittances to the Philippines alone rose 28% to $61 million.
- RSS data did not provide further details about the other countries or the reasons for the growth.
#CryptoNews #Chainalysis #Remittances #Canada #Asia
$btc $eth
vlikevn Titanbot
Source: CoinTelegraph
- According to Chainalysis, crypto transactions involving remittances from Canada to three Asian countries totaled $2.36 billion.
- Remittances to the Philippines alone rose 28% to $61 million.
- RSS data did not provide further details about the other countries or the reasons for the growth.
#CryptoNews #Chainalysis #Remittances #Canada #Asia
$btc $eth
vlikevn Titanbot
Source: CoinTelegraph
656
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#WhatWillDriveCryptoandStocks’NextRebound?
48,801 views
680 Discussing
2
#Anthropic’s6xIPODemandSignalsPotentialRecordRaise
15,459 views
334 Discussing
3
#USCryptoETFsLose$1.48BInFiveDays
30 views
2 Discussing
4
#KoreaDigitalAssetBasicActFinalDraftExpectedEarlyJanuary
0 views
2 Discussing
5
#JaneStreetNearlyOctuplesFidelityBitcoinETFHoldings
2,100 views
60 Discussing
6
#HuangExitNvidiaStrategyInFocus
196,390 views
1,664 Discussing
7
#AnthropicRejectsIPODelayValuationinQuestion
820,417 views
5,833 Discussing
8
#FlopLabsTestnetAndAirdropToLaunchNov24
164 views
10 Discussing
9
#HedgeFundsCMEBitcoinNetShortsFall89%
19,708 views
265 Discussing
10
#BitMineReports$6.3BNetLossForFiscal2026
27,776 views
196 Discussing