
#shipping
shipping
31,803 views
170 Discussing
Hot
Latest
·
--
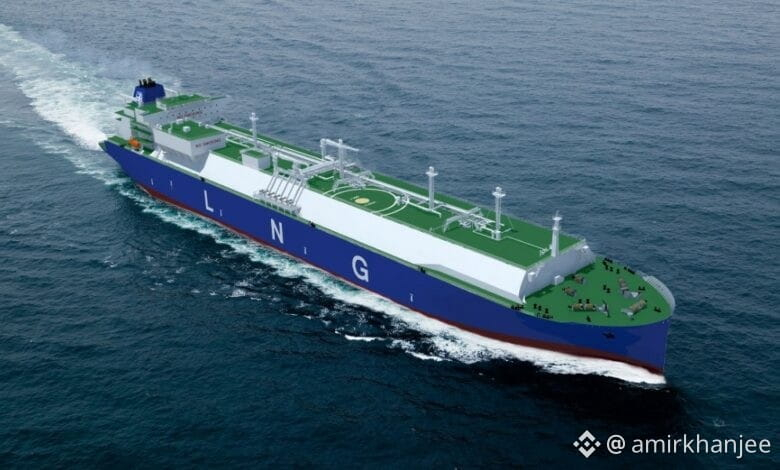
🚢💰 ADNOC L&S boosts its LNG fleet with a $900M new build deal in China 🇨🇳
More LNG carriers = stronger global energy trade 🔴⚡
Big moves in shipping, energy, and markets 🗾👀
#LNGCrisis #energy #Shipping #CryptoMarkets
👀 $DEXE $KAT $SKL
🚢💰 ADNOC L&S boosts its LNG fleet with a $900M new build deal in China 🇨🇳
More LNG carriers = stronger global energy trade 🔴⚡
Big moves in shipping, energy, and markets 🗾👀
#LNGCrisis #energy #Shipping #CryptoMarkets
👀 $DEXE $KAT $SKL
More LNG carriers = stronger global energy trade 🔴⚡
Big moves in shipping, energy, and markets 🗾👀
#LNGCrisis #energy #Shipping #CryptoMarkets
👀 $DEXE $KAT $SKL
1
194

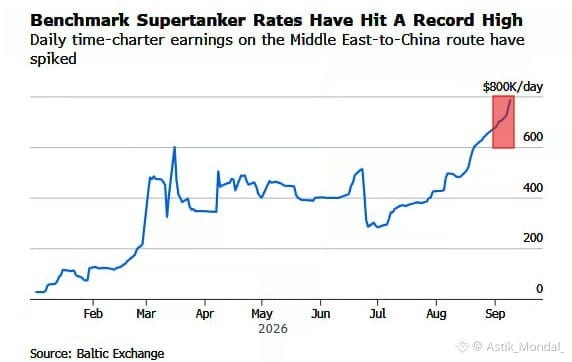
🚨 BREAKING: Shipping oil from the Middle East to China now costs nearly $800,000 a day, an all-time record, and it's a direct tax on everything that runs on fuel.
Look at that chart. Rates sat in a normal, boring range through most of the year, then exploded vertically starting in August. That's not a gradual climb, that's a market in genuine crisis.
The number itself is staggering: $800,000 per day is roughly 17 times the historical norm of $45,000 a day, according to Kpler.
The real-world cost is brutal. A single supertanker voyage from the US Gulf to Asia now runs $29.5 million, before war-risk insurance premiums even get added. Break that down and it works out to roughly $15 per barrel in shipping costs alone, on top of the oil itself.
The cause is simple: fewer ship owners are willing to send vessels anywhere near the Strait of Hormuz. With Iran's naval blockade still active, ongoing attacks on tankers, and war-risk premiums stacking on top of already-elevated fuel costs, the pool of willing carriers has shrunk fast, and every remaining vessel can now charge a fortune.
Rates have more than doubled in just two months. That's the kind of move that historically only happens during major supply shocks, wars, or blockades, not routine market cycles.
This doesn't stay contained to shipping company balance sheets. Every extra dollar tankers charge eventually shows up in refined fuel prices, in the cost of goods that get shipped using that fuel, and ultimately at the gas pump for ordinary consumers thousands of miles from the Strait of Hormuz.
The oil is still moving. It's just costing exponentially more to get it there.
#OilPrices #Hormuz #Iran #Shipping #Markets
🚨 BREAKING: Shipping oil from the Middle East to China now costs nearly $800,000 a day, an all-time record, and it's a direct tax on everything that runs on fuel.
Look at that chart. Rates sat in a normal, boring range through most of the year, then exploded vertically starting in August. That's not a gradual climb, that's a market in genuine crisis.
The number itself is staggering: $800,000 per day is roughly 17 times the historical norm of $45,000 a day, according to Kpler.
The real-world cost is brutal. A single supertanker voyage from the US Gulf to Asia now runs $29.5 million, before war-risk insurance premiums even get added. Break that down and it works out to roughly $15 per barrel in shipping costs alone, on top of the oil itself.
The cause is simple: fewer ship owners are willing to send vessels anywhere near the Strait of Hormuz. With Iran's naval blockade still active, ongoing attacks on tankers, and war-risk premiums stacking on top of already-elevated fuel costs, the pool of willing carriers has shrunk fast, and every remaining vessel can now charge a fortune.
Rates have more than doubled in just two months. That's the kind of move that historically only happens during major supply shocks, wars, or blockades, not routine market cycles.
This doesn't stay contained to shipping company balance sheets. Every extra dollar tankers charge eventually shows up in refined fuel prices, in the cost of goods that get shipped using that fuel, and ultimately at the gas pump for ordinary consumers thousands of miles from the Strait of Hormuz.
The oil is still moving. It's just costing exponentially more to get it there.
#OilPrices #Hormuz #Iran #Shipping #Markets
Look at that chart. Rates sat in a normal, boring range through most of the year, then exploded vertically starting in August. That's not a gradual climb, that's a market in genuine crisis.
The number itself is staggering: $800,000 per day is roughly 17 times the historical norm of $45,000 a day, according to Kpler.
The real-world cost is brutal. A single supertanker voyage from the US Gulf to Asia now runs $29.5 million, before war-risk insurance premiums even get added. Break that down and it works out to roughly $15 per barrel in shipping costs alone, on top of the oil itself.
The cause is simple: fewer ship owners are willing to send vessels anywhere near the Strait of Hormuz. With Iran's naval blockade still active, ongoing attacks on tankers, and war-risk premiums stacking on top of already-elevated fuel costs, the pool of willing carriers has shrunk fast, and every remaining vessel can now charge a fortune.
Rates have more than doubled in just two months. That's the kind of move that historically only happens during major supply shocks, wars, or blockades, not routine market cycles.
This doesn't stay contained to shipping company balance sheets. Every extra dollar tankers charge eventually shows up in refined fuel prices, in the cost of goods that get shipped using that fuel, and ultimately at the gas pump for ordinary consumers thousands of miles from the Strait of Hormuz.
The oil is still moving. It's just costing exponentially more to get it there.
#OilPrices #Hormuz #Iran #Shipping #Markets
1
37

·
--
Maersk’s Umm Qarn makes history! Will become the first ship to pass through the Suez Canal bidirectionally 🚢 The global trade landscape is quietly changing, and the traditional shipping industry is also embracing new technology. How will blockchain change the shipping industry? #供应链 #航运 $VET $WTC
Maersk's Umm Qarn makes history as first ship to pass Suez Canal bidirectionally🚢 Global trade landscape is changing, and traditional shipping is embracing new tech. How will blockchain transform the industry? #Shipping #SupplyChain $VET $WTC
Maersk’s Umm Qarn makes history! Will become the first ship to pass through the Suez Canal bidirectionally 🚢 The global trade landscape is quietly changing, and the traditional shipping industry is also embracing new technology. How will blockchain change the shipping industry? #供应链 #航运 $VET $WTC
Maersk's Umm Qarn makes history as first ship to pass Suez Canal bidirectionally🚢 Global trade landscape is changing, and traditional shipping is embracing new tech. How will blockchain transform the industry? #Shipping #SupplyChain $VET $WTC
Maersk's Umm Qarn makes history as first ship to pass Suez Canal bidirectionally🚢 Global trade landscape is changing, and traditional shipping is embracing new tech. How will blockchain transform the industry? #Shipping #SupplyChain $VET $WTC
225
·
--
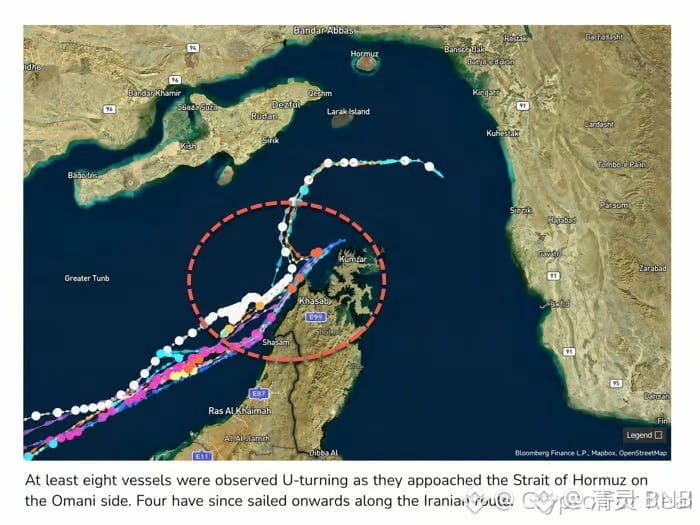
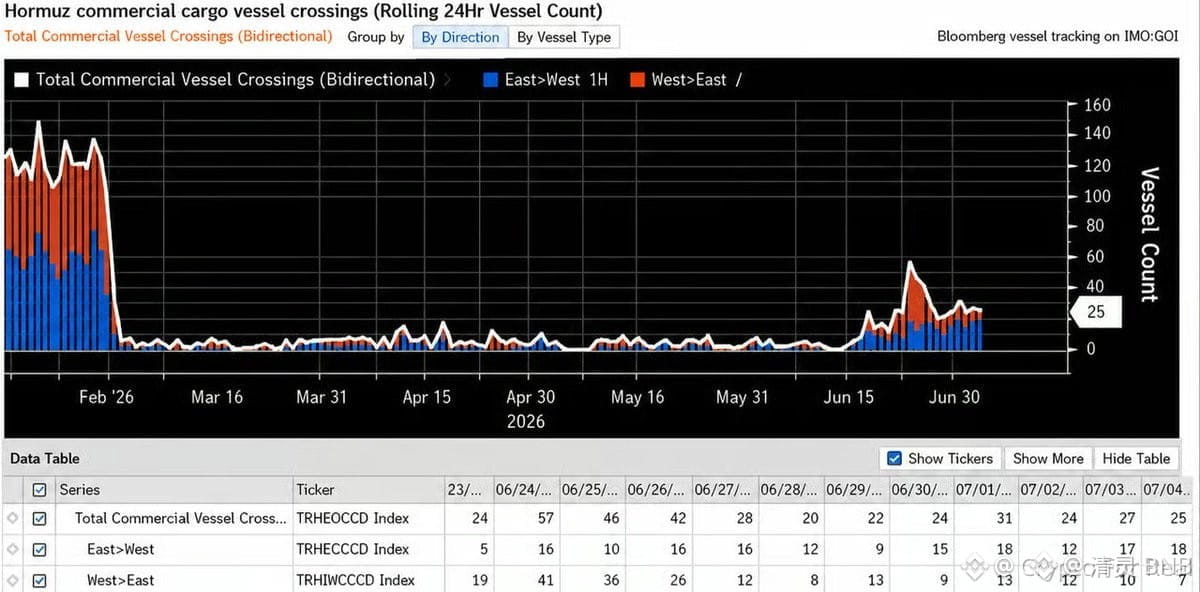
🚨 Strait of Hormuz Update
Reports indicate that shipping activity in the Strait of Hormuz is facing increased operational coordination, with several tankers reportedly altering their routes and transit patterns overnight.
📊 Why It Matters:
• Some vessels have adjusted their navigation in response to security conditions.
• Oil exports are continuing, but shipping routes remain under heightened scrutiny.
• The situation has renewed discussions about maritime security and freedom of navigation in one of the world's most important energy corridors.
As geopolitical tensions persist, markets will be watching closely for any developments that could impact global energy supplies, shipping, and broader risk sentiment.
#Oil #StraitOfHormuz #Geopolitics #Energy #Markets #Shipping
🚨 Strait of Hormuz Update
Reports indicate that shipping activity in the Strait of Hormuz is facing increased operational coordination, with several tankers reportedly altering their routes and transit patterns overnight.
📊 Why It Matters:
• Some vessels have adjusted their navigation in response to security conditions.
• Oil exports are continuing, but shipping routes remain under heightened scrutiny.
• The situation has renewed discussions about maritime security and freedom of navigation in one of the world's most important energy corridors.
As geopolitical tensions persist, markets will be watching closely for any developments that could impact global energy supplies, shipping, and broader risk sentiment.
#Oil #StraitOfHormuz #Geopolitics #Energy #Markets #Shipping
Reports indicate that shipping activity in the Strait of Hormuz is facing increased operational coordination, with several tankers reportedly altering their routes and transit patterns overnight.
📊 Why It Matters:
• Some vessels have adjusted their navigation in response to security conditions.
• Oil exports are continuing, but shipping routes remain under heightened scrutiny.
• The situation has renewed discussions about maritime security and freedom of navigation in one of the world's most important energy corridors.
As geopolitical tensions persist, markets will be watching closely for any developments that could impact global energy supplies, shipping, and broader risk sentiment.
#Oil #StraitOfHormuz #Geopolitics #Energy #Markets #Shipping
1
54

·
--
ZIM EVP sells $381K in shares as Hapag-Lloyd buyout looms
• Dotan Saar sold 15,000 ZIM shares on June 4, 2026, for ~$381,000
• Sale represented 12.9% of Saar's direct holdings, leaving 101,667 shares
• Hapag-Lloyd acquisition set at $35/share, expected to close late 2026
#CryptoNews #MarketUpdate #BinanceSquare #Shipping #Mergers
ZIM EVP sells $381K in shares as Hapag-Lloyd buyout looms
• Dotan Saar sold 15,000 ZIM shares on June 4, 2026, for ~$381,000
• Sale represented 12.9% of Saar's direct holdings, leaving 101,667 shares
• Hapag-Lloyd acquisition set at $35/share, expected to close late 2026
#CryptoNews #MarketUpdate #BinanceSquare #Shipping #Mergers
• Dotan Saar sold 15,000 ZIM shares on June 4, 2026, for ~$381,000
• Sale represented 12.9% of Saar's direct holdings, leaving 101,667 shares
• Hapag-Lloyd acquisition set at $35/share, expected to close late 2026
#CryptoNews #MarketUpdate #BinanceSquare #Shipping #Mergers
13
🚢 Iran Introduces Crypto-Based Ship Insurance for Strait of Hormuz
Iran has reportedly launched a cryptocurrency-based maritime insurance system called “Hormuz Safe”, allowing ships traveling through the Strait of Hormuz to pay insurance premiums using Bitcoin and other cryptocurrencies. The move is seen as an attempt to keep trade moving while navigating sanctions and shipping disruptions in one of the world’s most important oil routes.
🔥 Key Highlights
• 🚢 Iran introduces crypto-powered ship insurance for Hormuz transit
• ₿ Insurance premiums may be paid using Bitcoin & crypto assets
• 🌍 Aims to support shipping through a route handling a major share of global oil trade
• 🏦 Seen as an alternative to traditional banking channels amid sanctions pressure
💡 Why This Matters
Could increase real-world crypto utility beyond trading
Shows governments exploring blockchain for international commerce
May reduce reliance on traditional payment rails like SWIFT for some transactions
But sanctions and regulatory concerns could limit adoption by major global shipping firms.
⚡ Expert Insight
This is one of the more unusual real-world crypto use cases in 2026: using blockchain for maritime risk insurance. It’s potentially bullish for crypto utility narratives — but success depends on whether global shipping companies actually trust and adopt the system.
#CryptoNews #Blockchain #Shipping #GlobalTrade #CryptoAdoption $BTC $CL $BZ
{future}(BZUSDT)
{future}(CLUSDT)
{future}(BTCUSDT)
🚢 Iran Introduces Crypto-Based Ship Insurance for Strait of Hormuz
Iran has reportedly launched a cryptocurrency-based maritime insurance system called “Hormuz Safe”, allowing ships traveling through the Strait of Hormuz to pay insurance premiums using Bitcoin and other cryptocurrencies. The move is seen as an attempt to keep trade moving while navigating sanctions and shipping disruptions in one of the world’s most important oil routes.
🔥 Key Highlights
• 🚢 Iran introduces crypto-powered ship insurance for Hormuz transit
• ₿ Insurance premiums may be paid using Bitcoin & crypto assets
• 🌍 Aims to support shipping through a route handling a major share of global oil trade
• 🏦 Seen as an alternative to traditional banking channels amid sanctions pressure
💡 Why This Matters
Could increase real-world crypto utility beyond trading
Shows governments exploring blockchain for international commerce
May reduce reliance on traditional payment rails like SWIFT for some transactions
But sanctions and regulatory concerns could limit adoption by major global shipping firms.
⚡ Expert Insight
This is one of the more unusual real-world crypto use cases in 2026: using blockchain for maritime risk insurance. It’s potentially bullish for crypto utility narratives — but success depends on whether global shipping companies actually trust and adopt the system.
#CryptoNews #Blockchain #Shipping #GlobalTrade #CryptoAdoption $BTC $CL $BZ
Iran has reportedly launched a cryptocurrency-based maritime insurance system called “Hormuz Safe”, allowing ships traveling through the Strait of Hormuz to pay insurance premiums using Bitcoin and other cryptocurrencies. The move is seen as an attempt to keep trade moving while navigating sanctions and shipping disruptions in one of the world’s most important oil routes.
🔥 Key Highlights
• 🚢 Iran introduces crypto-powered ship insurance for Hormuz transit
• ₿ Insurance premiums may be paid using Bitcoin & crypto assets
• 🌍 Aims to support shipping through a route handling a major share of global oil trade
• 🏦 Seen as an alternative to traditional banking channels amid sanctions pressure
💡 Why This Matters
Could increase real-world crypto utility beyond trading
Shows governments exploring blockchain for international commerce
May reduce reliance on traditional payment rails like SWIFT for some transactions
But sanctions and regulatory concerns could limit adoption by major global shipping firms.
⚡ Expert Insight
This is one of the more unusual real-world crypto use cases in 2026: using blockchain for maritime risk insurance. It’s potentially bullish for crypto utility narratives — but success depends on whether global shipping companies actually trust and adopt the system.
#CryptoNews #Blockchain #Shipping #GlobalTrade #CryptoAdoption $BTC $CL $BZ
13
·
--
Bullish
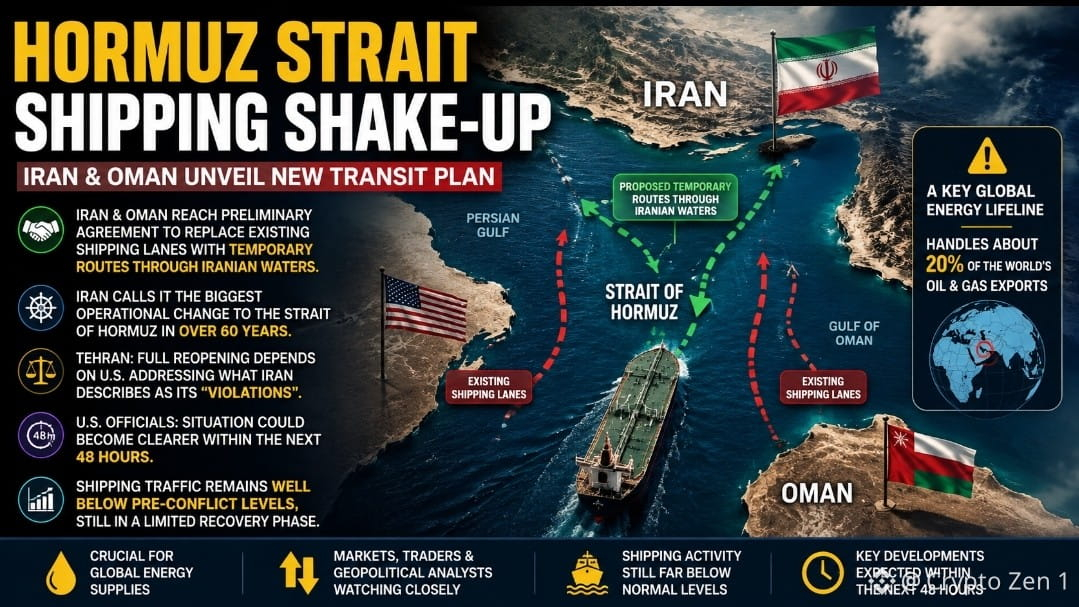
The Strait of Hormuz may be heading toward one of its biggest changes in decades.
Iran says it has reached an early agreement with Oman to temporarily guide ships through routes inside Iranian waters instead of the usual shipping lanes. If the plan moves forward, it would reshape how traffic flows through one of the world's most important waterways.
Nothing is final yet. Iran says a full reopening still depends on how the U.S. responds, and American officials expect the situation to become clearer within the next 48 hours.
For now, shipping activity is still far from normal. That is why markets are paying close attention. A large portion of the world's oil passes through this narrow passage, so even small changes can affect energy prices, investor sentiment, and global trade.
The next couple of days could tell us whether this is the beginning of a real shift or just another step in an ongoing standoff.
#UnitedStates #GlobalTrade #Shipping #OilMarkets #Energy
$KO
{future}(KOUSDT)
$RDDT
{future}(RDDTUSDT)
$ELON
{alpha}(560xe07ae3a6f1bd86b92b563084e286757eb34878d7)
The Strait of Hormuz may be heading toward one of its biggest changes in decades.
Iran says it has reached an early agreement with Oman to temporarily guide ships through routes inside Iranian waters instead of the usual shipping lanes. If the plan moves forward, it would reshape how traffic flows through one of the world's most important waterways.
Nothing is final yet. Iran says a full reopening still depends on how the U.S. responds, and American officials expect the situation to become clearer within the next 48 hours.
For now, shipping activity is still far from normal. That is why markets are paying close attention. A large portion of the world's oil passes through this narrow passage, so even small changes can affect energy prices, investor sentiment, and global trade.
The next couple of days could tell us whether this is the beginning of a real shift or just another step in an ongoing standoff.
#UnitedStates #GlobalTrade #Shipping #OilMarkets #Energy
$KO
$RDDT
$ELON
Iran says it has reached an early agreement with Oman to temporarily guide ships through routes inside Iranian waters instead of the usual shipping lanes. If the plan moves forward, it would reshape how traffic flows through one of the world's most important waterways.
Nothing is final yet. Iran says a full reopening still depends on how the U.S. responds, and American officials expect the situation to become clearer within the next 48 hours.
For now, shipping activity is still far from normal. That is why markets are paying close attention. A large portion of the world's oil passes through this narrow passage, so even small changes can affect energy prices, investor sentiment, and global trade.
The next couple of days could tell us whether this is the beginning of a real shift or just another step in an ongoing standoff.
#UnitedStates #GlobalTrade #Shipping #OilMarkets #Energy
$KO
$RDDT
$ELON
1
504

·
--
Bullish
Trafigura takes its VLCC fleet public as tanker rates surge
🚢 Trafigura has launched Volare Shipping, which is expected to list on Euronext Growth Oslo in early October under the ticker VLCC. It marks the first time the group has brought a standalone business unit to public markets rather than listing Trafigura itself.
💰 Volare currently owns 6 operating VLCCs and 8 newbuilds scheduled for delivery between 2026 and 2028. The company plans to raise about $500 million through a private placement, while Trafigura will retain a majority stake and commercial management of the fleet.
📈 The timing is notable as VLCC freight rates remain elevated amid disruptions to global oil shipping routes. Direct fleet ownership could reduce Trafigura’s reliance on the charter market and give it greater control over logistics.
⚠️ The main risk is cyclical. Tanker markets are already running hot, while the VLCC orderbook is expanding. If shipping disruptions ease and new vessel supply rises, today’s elevated freight rates may prove difficult to sustain.
#Shipping $TRUMP
Trafigura takes its VLCC fleet public as tanker rates surge
🚢 Trafigura has launched Volare Shipping, which is expected to list on Euronext Growth Oslo in early October under the ticker VLCC. It marks the first time the group has brought a standalone business unit to public markets rather than listing Trafigura itself.
💰 Volare currently owns 6 operating VLCCs and 8 newbuilds scheduled for delivery between 2026 and 2028. The company plans to raise about $500 million through a private placement, while Trafigura will retain a majority stake and commercial management of the fleet.
📈 The timing is notable as VLCC freight rates remain elevated amid disruptions to global oil shipping routes. Direct fleet ownership could reduce Trafigura’s reliance on the charter market and give it greater control over logistics.
⚠️ The main risk is cyclical. Tanker markets are already running hot, while the VLCC orderbook is expanding. If shipping disruptions ease and new vessel supply rises, today’s elevated freight rates may prove difficult to sustain.
#Shipping $TRUMP
🚢 Trafigura has launched Volare Shipping, which is expected to list on Euronext Growth Oslo in early October under the ticker VLCC. It marks the first time the group has brought a standalone business unit to public markets rather than listing Trafigura itself.
💰 Volare currently owns 6 operating VLCCs and 8 newbuilds scheduled for delivery between 2026 and 2028. The company plans to raise about $500 million through a private placement, while Trafigura will retain a majority stake and commercial management of the fleet.
📈 The timing is notable as VLCC freight rates remain elevated amid disruptions to global oil shipping routes. Direct fleet ownership could reduce Trafigura’s reliance on the charter market and give it greater control over logistics.
⚠️ The main risk is cyclical. Tanker markets are already running hot, while the VLCC orderbook is expanding. If shipping disruptions ease and new vessel supply rises, today’s elevated freight rates may prove difficult to sustain.
#Shipping $TRUMP
767
·
--
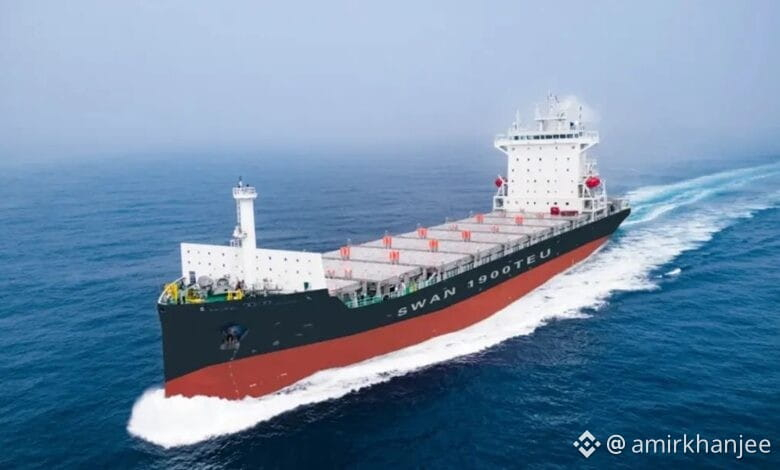
🛢️ Containerships are thinking small again.🟢
🧧 The global orderbook is nearing 13M TEU, but the real story is the shift away from megaships.
😈 Since July 2025, 74% of new orders have been for vessels under 6,500 TEU, versus less than 30% previously.
Flexibility > Size. Regional trade > Mega hubs. Efficiency > Expansion.
🔶 A major signal that shipping is adapting to a more fragmented global trade landscape. 🗾
#Shipping #Logistics #trade #SupplyChain #Maritime
👀 $SYN $ATM $LUMIA
🛢️ Containerships are thinking small again.🟢
🧧 The global orderbook is nearing 13M TEU, but the real story is the shift away from megaships.
😈 Since July 2025, 74% of new orders have been for vessels under 6,500 TEU, versus less than 30% previously.
Flexibility > Size. Regional trade > Mega hubs. Efficiency > Expansion.
🔶 A major signal that shipping is adapting to a more fragmented global trade landscape. 🗾
#Shipping #Logistics #trade #SupplyChain #Maritime
👀 $SYN $ATM $LUMIA
🧧 The global orderbook is nearing 13M TEU, but the real story is the shift away from megaships.
😈 Since July 2025, 74% of new orders have been for vessels under 6,500 TEU, versus less than 30% previously.
Flexibility > Size. Regional trade > Mega hubs. Efficiency > Expansion.
🔶 A major signal that shipping is adapting to a more fragmented global trade landscape. 🗾
#Shipping #Logistics #trade #SupplyChain #Maritime
👀 $SYN $ATM $LUMIA
1
130
·
--
#SaudiRoutesOilExportsViaSuez Two major straits closed. One major detour.
Saudi oil now sailing via the Suez Canal, but the fuel bill will skyrocket.
Navigating global tensions is getting dangerously expensive. ⛽️🚢
#Shipping #Oil #Geopolitics $BULLA $PENDLE $JCT
#SaudiRoutesOilExportsViaSuez Two major straits closed. One major detour.
Saudi oil now sailing via the Suez Canal, but the fuel bill will skyrocket.
Navigating global tensions is getting dangerously expensive. ⛽️🚢
#Shipping #Oil #Geopolitics $BULLA $PENDLE $JCT
Saudi oil now sailing via the Suez Canal, but the fuel bill will skyrocket.
Navigating global tensions is getting dangerously expensive. ⛽️🚢
#Shipping #Oil #Geopolitics $BULLA $PENDLE $JCT
247
·
--
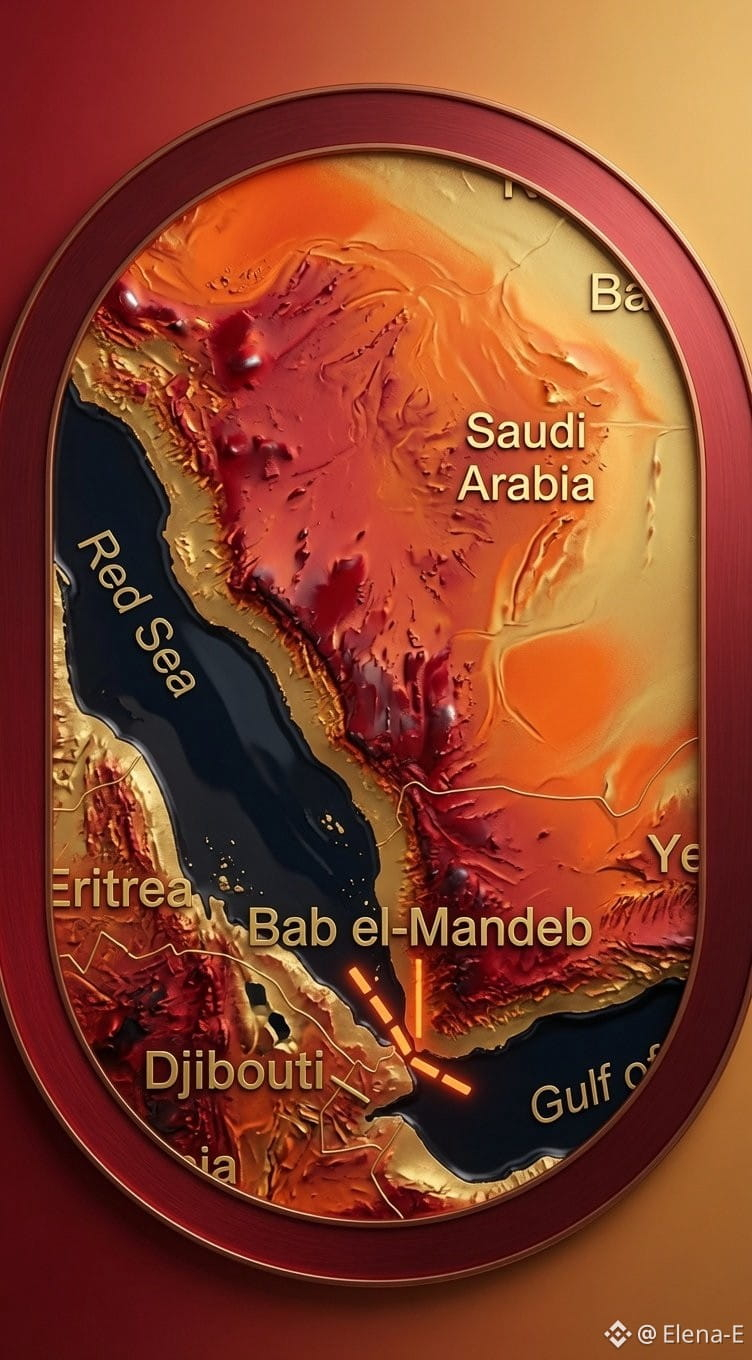
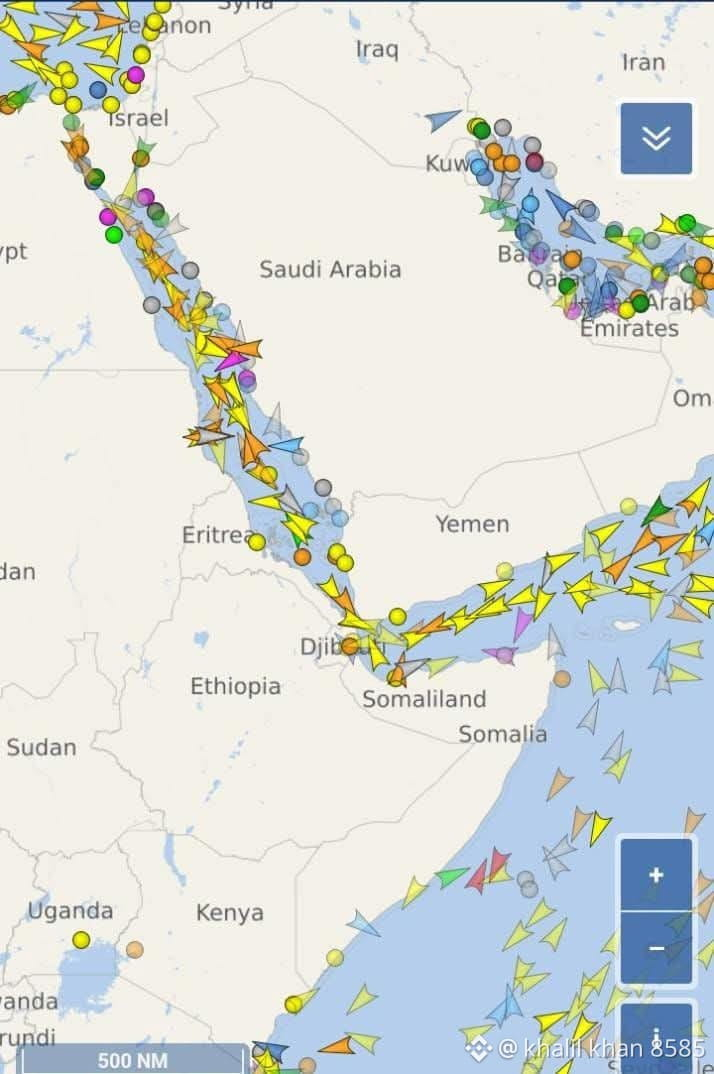
🚨 Potential Disruption in the Red Sea and Bab el-Mandeb — Possible Impact on Global Markets
The image shows unusual shipping activity along the Red Sea, Bab el-Mandeb Strait, and the Gulf of Aden. If tensions escalate or this critical maritime route experiences a temporary blockade, it could have significant consequences for global financial markets.
Potential Market Impacts
🔸 🛢️ Crude Oil: Oil prices could surge due to concerns over supply disruptions.
🔸 🥇 Gold: During periods of geopolitical uncertainty, investors typically move toward safe-haven assets, increasing demand for and the price of gold.
🔸 💵 U.S. Dollar: If global risks rise, the U.S. dollar may strengthen as a safe-haven currency. However, if higher energy costs put pressure on the U.S. economy, the market reaction could be more mixed.
🔸 📉 Global Stock Markets: Higher shipping costs, logistics disruptions, and rising import expenses could weigh on equity markets, while the energy and defense sectors may outperform.
🔸 🚢 Shipping & Freight Rates: Ships may be forced to reroute via the Cape of Good Hope, leading to longer transit times and increased transportation costs.
📌 Key Levels and Indicators for Traders
Monitor geopolitical developments closely.
Watch price movements in Brent and WTI crude oil.
Track safe-haven flows into gold.
Keep an eye on changes in shipping insurance premiums and freight rates, as they can provide early warning signals.
#Gold #XAUUSD #CrudeOil #Oil #RedSea #BabElMandeb #Shipping
$XRP
$BANK
$LAB
🚨 Potential Disruption in the Red Sea and Bab el-Mandeb — Possible Impact on Global Markets
The image shows unusual shipping activity along the Red Sea, Bab el-Mandeb Strait, and the Gulf of Aden. If tensions escalate or this critical maritime route experiences a temporary blockade, it could have significant consequences for global financial markets.
Potential Market Impacts
🔸 🛢️ Crude Oil: Oil prices could surge due to concerns over supply disruptions.
🔸 🥇 Gold: During periods of geopolitical uncertainty, investors typically move toward safe-haven assets, increasing demand for and the price of gold.
🔸 💵 U.S. Dollar: If global risks rise, the U.S. dollar may strengthen as a safe-haven currency. However, if higher energy costs put pressure on the U.S. economy, the market reaction could be more mixed.
🔸 📉 Global Stock Markets: Higher shipping costs, logistics disruptions, and rising import expenses could weigh on equity markets, while the energy and defense sectors may outperform.
🔸 🚢 Shipping & Freight Rates: Ships may be forced to reroute via the Cape of Good Hope, leading to longer transit times and increased transportation costs.
📌 Key Levels and Indicators for Traders
Monitor geopolitical developments closely.
Watch price movements in Brent and WTI crude oil.
Track safe-haven flows into gold.
Keep an eye on changes in shipping insurance premiums and freight rates, as they can provide early warning signals.
#Gold #XAUUSD #CrudeOil #Oil #RedSea #BabElMandeb #Shipping
$XRP
$BANK
$LAB
The image shows unusual shipping activity along the Red Sea, Bab el-Mandeb Strait, and the Gulf of Aden. If tensions escalate or this critical maritime route experiences a temporary blockade, it could have significant consequences for global financial markets.
Potential Market Impacts
🔸 🛢️ Crude Oil: Oil prices could surge due to concerns over supply disruptions.
🔸 🥇 Gold: During periods of geopolitical uncertainty, investors typically move toward safe-haven assets, increasing demand for and the price of gold.
🔸 💵 U.S. Dollar: If global risks rise, the U.S. dollar may strengthen as a safe-haven currency. However, if higher energy costs put pressure on the U.S. economy, the market reaction could be more mixed.
🔸 📉 Global Stock Markets: Higher shipping costs, logistics disruptions, and rising import expenses could weigh on equity markets, while the energy and defense sectors may outperform.
🔸 🚢 Shipping & Freight Rates: Ships may be forced to reroute via the Cape of Good Hope, leading to longer transit times and increased transportation costs.
📌 Key Levels and Indicators for Traders
Monitor geopolitical developments closely.
Watch price movements in Brent and WTI crude oil.
Track safe-haven flows into gold.
Keep an eye on changes in shipping insurance premiums and freight rates, as they can provide early warning signals.
#Gold #XAUUSD #CrudeOil #Oil #RedSea #BabElMandeb #Shipping
$XRP
$BANK
$LAB
139
·
--
The Containerized Freight Index Europe route contract plunged 3% intraday! The shipping market is cooling, putting pressure on the global economy? Crypto traders, what do you make of this trend? A decline in shipping may signal a slowdown in global trade, which could also affect crypto markets!#航运 #全球经济 $BTC $ETH
Euroline shipping index drops 3% today! Cooling shipping market suggests global economic pressure? Crypto traders, what's your take on this trend? Downturn in shipping may signal slowing global trade, which could impact crypto markets too! #shipping #global economy $BTC $ETH
The Containerized Freight Index Europe route contract plunged 3% intraday! The shipping market is cooling, putting pressure on the global economy? Crypto traders, what do you make of this trend? A decline in shipping may signal a slowdown in global trade, which could also affect crypto markets!#航运 #全球经济 $BTC $ETH
Euroline shipping index drops 3% today! Cooling shipping market suggests global economic pressure? Crypto traders, what's your take on this trend? Downturn in shipping may signal slowing global trade, which could impact crypto markets too! #shipping #global economy $BTC $ETH
Euroline shipping index drops 3% today! Cooling shipping market suggests global economic pressure? Crypto traders, what's your take on this trend? Downturn in shipping may signal slowing global trade, which could impact crypto markets too! #shipping #global economy $BTC $ETH
153

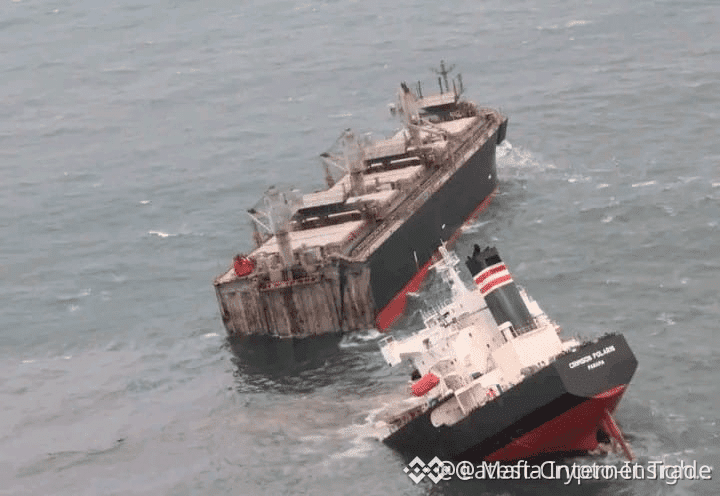
$BNB STRAIT OF HORMUZ SINKING – RISK ASSETS ON ALERT 🔥
No specific price levels provided in the input.
A bulk carrier just snapped in half near one of the world's most critical oil chokepoints. All 23 crew evacuated, but the real story is what this does to risk perception. Every time Hormuz makes headlines, capital tends to rotate out of speculative plays into safety.
The last time a maritime incident of this scale hit the news, $BNB saw a 12% intraday swing within 48 hours. History doesn't repeat, but it often rhymes. How do you see this playing out for $BNB this week?
Not financial advice. Always manage your risk.
#BNB #GeopoliticalRisk #CryptoMarket #Shipping
🔥
$BNB STRAIT OF HORMUZ SINKING – RISK ASSETS ON ALERT 🔥
No specific price levels provided in the input.
A bulk carrier just snapped in half near one of the world's most critical oil chokepoints. All 23 crew evacuated, but the real story is what this does to risk perception. Every time Hormuz makes headlines, capital tends to rotate out of speculative plays into safety.
The last time a maritime incident of this scale hit the news, $BNB saw a 12% intraday swing within 48 hours. History doesn't repeat, but it often rhymes. How do you see this playing out for $BNB this week?
Not financial advice. Always manage your risk.
#BNB #GeopoliticalRisk #CryptoMarket #Shipping
🔥
No specific price levels provided in the input.
A bulk carrier just snapped in half near one of the world's most critical oil chokepoints. All 23 crew evacuated, but the real story is what this does to risk perception. Every time Hormuz makes headlines, capital tends to rotate out of speculative plays into safety.
The last time a maritime incident of this scale hit the news, $BNB saw a 12% intraday swing within 48 hours. History doesn't repeat, but it often rhymes. How do you see this playing out for $BNB this week?
Not financial advice. Always manage your risk.
#BNB #GeopoliticalRisk #CryptoMarket #Shipping
🔥
25
·
--
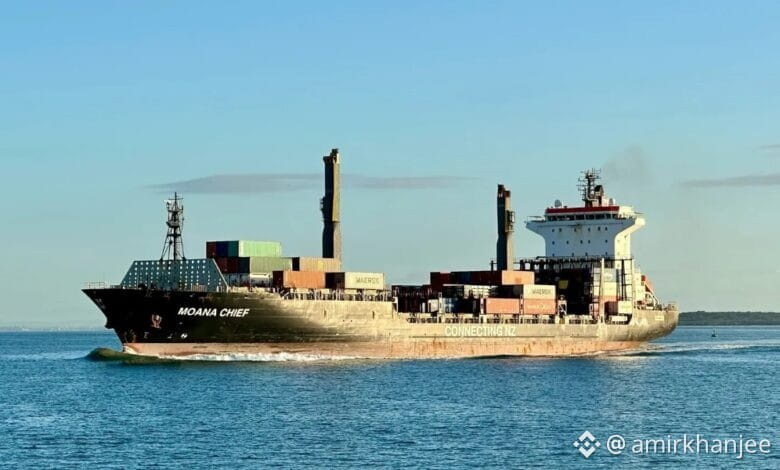
🇳🇿 New Zealand is set to lose its last flagged boxship — a major milestone for the country’s maritime sector.🟢
🌀 As global shipping evolves, it’s a reminder of how quickly national fleets can disappear without long-term investment and policy support.
🔴 #Shipping #NewZealand #Maritime #GlobalTrade
👀 $SKL $DEXE $KAT
🇳🇿 New Zealand is set to lose its last flagged boxship — a major milestone for the country’s maritime sector.🟢
🌀 As global shipping evolves, it’s a reminder of how quickly national fleets can disappear without long-term investment and policy support.
🔴 #Shipping #NewZealand #Maritime #GlobalTrade
👀 $SKL $DEXE $KAT
🌀 As global shipping evolves, it’s a reminder of how quickly national fleets can disappear without long-term investment and policy support.
🔴 #Shipping #NewZealand #Maritime #GlobalTrade
👀 $SKL $DEXE $KAT
1
231

·
--
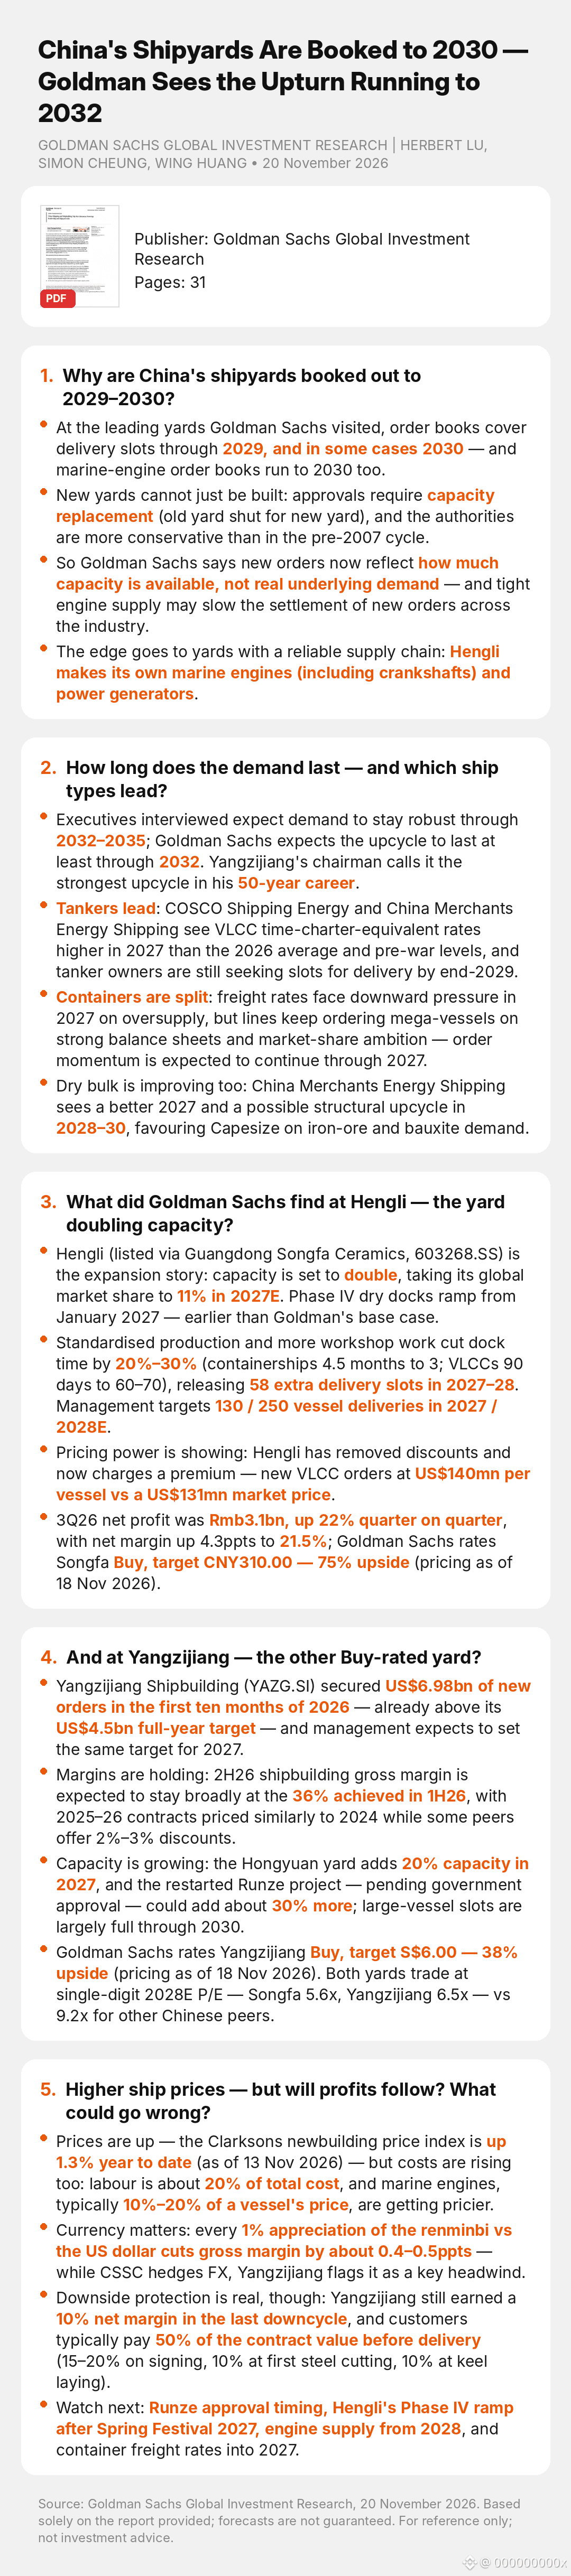
Article
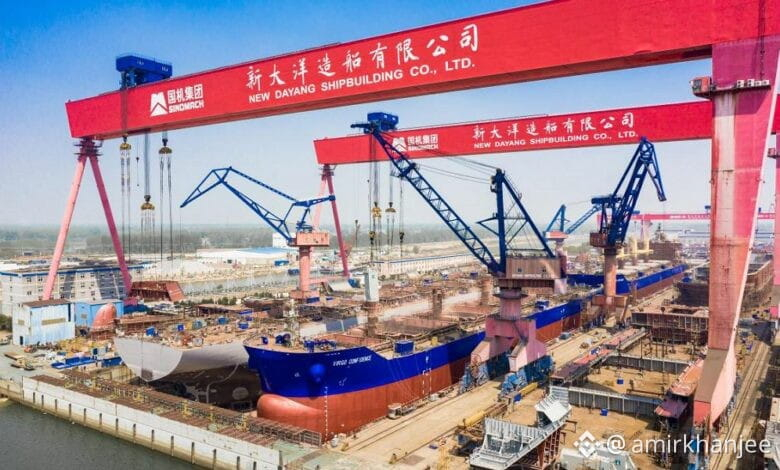
China's Shipyards Are Booked to 2030 — Goldman Sees the Upturn Running to 2032China's Shipyards Are Booked to 2030 — Goldman Sees the Upturn Running to 2032
$BS6.SI $603268.SS $BTC
GOLDMAN SACHS GLOBAL INVESTMENT RESEARCH | HERBERT LU, SIMON CHEUNG, WING HUANG • 20 November 2026
1. Why are China's shipyards booked out to 2029–2030?
• At the leading yards Goldman Sachs visited, order books cover slots through 2029, even 2030 — engine order books too.
• New yards need approvals requiring capacity replacement, and the authorities are more conservative than before the 2007 cycle.
• So new orders reflect available capacity, not real demand — and tight engine supply may slow new orders industry-wide.
• The edge goes to yards with reliable supply chains: Hengli makes its own marine engines and power generators.
2. How long does the demand last — and which ship types lead?
• Executives expect demand robust through 2032–2035; Goldman Sachs sees the upcycle lasting at least through 2032 — Yangzijiang's chairman calls it the strongest in his 50-year career.
• Tankers lead: COSCO Shipping Energy and CMES see VLCC rates higher in 2027 than the 2026 average and pre-war levels; owners still seek end-2029 slots.
• Containers are split: freight rates face pressure in 2027, but lines keep ordering mega-vessels — momentum should continue through 2027.
3. What did Goldman Sachs find at Hengli — the yard doubling capacity?
• Hengli (via Songfa Ceramics, 603268.SS): capacity set to double, global share to 11% in 2027E; Phase IV dry docks ramp from January 2027 — earlier than Goldman's base case.
• Standardised production cuts dock time 20%–30%, releasing 58 extra delivery slots in 2027–28; management targets 130 / 250 deliveries in 2027 / 2028E.
• Pricing power shows: Hengli removed discounts — new VLCC orders at US$140mn vs a US$131mn market price.
• 3Q26 net profit Rmb3.1bn, +22% QoQ, net margin 21.5%; Songfa Buy, target CNY310.00 — 75% upside (18 Nov 2026 prices).
4. And at Yangzijiang — the other Buy-rated yard?
• Yangzijiang (YAZG.SI) won US$6.98bn of new orders in 10M26 — above its US$4.5bn FY26 target — and expects the same target for 2027.
• Margins hold: 2H26 gross margin seen near 1H26's 36%, with 2025–26 contracts priced like 2024 while peers discount 2%–3%.
• Capacity grows: Hongyuan adds 20% in 2027; restarted Runze — pending approval — could add ~30% more; large-vessel slots are largely full through 2030.
• Yangzijiang Buy, target S$6.00 — 38% upside (18 Nov 2026 prices). Both yards trade at single-digit 2028E P/E (5.6x / 6.5x) vs 9.2x for other Chinese peers.
5. Higher ship prices — but will profits follow? What could go wrong?
• Prices are up — Clarksons newbuilding index +1.3% YTD (13 Nov 2026) — but so are costs: labour ~20% of total cost; engines 10%–20% of a vessel's price.
• Currency matters: every 1% renminbi gain vs the dollar cuts gross margin ~0.4–0.5ppts.
• Protection is real: Yangzijiang earned 10% net margin even in the last downcycle, and customers pay 50% before delivery.
• Watch: Runze approval, Hengli's Phase IV ramp after Spring Festival 2027, engine supply from 2028, container rates into 2027.
#Shipbuilding #Shipping #ChinaStocks #Tankers #Commodities
Source: Goldman Sachs Global Investment Research, 20 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Read the full breakdown on Unhidea: https://unhidea.com/en/articles/research-432428126b3f4851a52ef0ef87730858-en
Visit unhidea.com for more of the latest sell-side research interpretations.
China's Shipyards Are Booked to 2030 — Goldman Sees the Upturn Running to 2032
China's Shipyards Are Booked to 2030 — Goldman Sees the Upturn Running to 2032
$BS6.SI $603268.SS $BTC
GOLDMAN SACHS GLOBAL INVESTMENT RESEARCH | HERBERT LU, SIMON CHEUNG, WING HUANG • 20 November 2026
1. Why are China's shipyards booked out to 2029–2030?
• At the leading yards Goldman Sachs visited, order books cover slots through 2029, even 2030 — engine order books too.
• New yards need approvals requiring capacity replacement, and the authorities are more conservative than before the 2007 cycle.
• So new orders reflect available capacity, not real demand — and tight engine supply may slow new orders industry-wide.
• The edge goes to yards with reliable supply chains: Hengli makes its own marine engines and power generators.
2. How long does the demand last — and which ship types lead?
• Executives expect demand robust through 2032–2035; Goldman Sachs sees the upcycle lasting at least through 2032 — Yangzijiang's chairman calls it the strongest in his 50-year career.
• Tankers lead: COSCO Shipping Energy and CMES see VLCC rates higher in 2027 than the 2026 average and pre-war levels; owners still seek end-2029 slots.
• Containers are split: freight rates face pressure in 2027, but lines keep ordering mega-vessels — momentum should continue through 2027.
3. What did Goldman Sachs find at Hengli — the yard doubling capacity?
• Hengli (via Songfa Ceramics, 603268.SS): capacity set to double, global share to 11% in 2027E; Phase IV dry docks ramp from January 2027 — earlier than Goldman's base case.
• Standardised production cuts dock time 20%–30%, releasing 58 extra delivery slots in 2027–28; management targets 130 / 250 deliveries in 2027 / 2028E.
• Pricing power shows: Hengli removed discounts — new VLCC orders at US$140mn vs a US$131mn market price.
• 3Q26 net profit Rmb3.1bn, +22% QoQ, net margin 21.5%; Songfa Buy, target CNY310.00 — 75% upside (18 Nov 2026 prices).
4. And at Yangzijiang — the other Buy-rated yard?
• Yangzijiang (YAZG.SI) won US$6.98bn of new orders in 10M26 — above its US$4.5bn FY26 target — and expects the same target for 2027.
• Margins hold: 2H26 gross margin seen near 1H26's 36%, with 2025–26 contracts priced like 2024 while peers discount 2%–3%.
• Capacity grows: Hongyuan adds 20% in 2027; restarted Runze — pending approval — could add ~30% more; large-vessel slots are largely full through 2030.
• Yangzijiang Buy, target S$6.00 — 38% upside (18 Nov 2026 prices). Both yards trade at single-digit 2028E P/E (5.6x / 6.5x) vs 9.2x for other Chinese peers.
5. Higher ship prices — but will profits follow? What could go wrong?
• Prices are up — Clarksons newbuilding index +1.3% YTD (13 Nov 2026) — but so are costs: labour ~20% of total cost; engines 10%–20% of a vessel's price.
• Currency matters: every 1% renminbi gain vs the dollar cuts gross margin ~0.4–0.5ppts.
• Protection is real: Yangzijiang earned 10% net margin even in the last downcycle, and customers pay 50% before delivery.
• Watch: Runze approval, Hengli's Phase IV ramp after Spring Festival 2027, engine supply from 2028, container rates into 2027.
#Shipbuilding #Shipping #ChinaStocks #Tankers #Commodities
Source: Goldman Sachs Global Investment Research, 20 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Read the full breakdown on Unhidea: https://unhidea.com/en/articles/research-432428126b3f4851a52ef0ef87730858-en
Visit unhidea.com for more of the latest sell-side research interpretations.
$BS6.SI $603268.SS $BTC
GOLDMAN SACHS GLOBAL INVESTMENT RESEARCH | HERBERT LU, SIMON CHEUNG, WING HUANG • 20 November 2026
1. Why are China's shipyards booked out to 2029–2030?
• At the leading yards Goldman Sachs visited, order books cover slots through 2029, even 2030 — engine order books too.
• New yards need approvals requiring capacity replacement, and the authorities are more conservative than before the 2007 cycle.
• So new orders reflect available capacity, not real demand — and tight engine supply may slow new orders industry-wide.
• The edge goes to yards with reliable supply chains: Hengli makes its own marine engines and power generators.
2. How long does the demand last — and which ship types lead?
• Executives expect demand robust through 2032–2035; Goldman Sachs sees the upcycle lasting at least through 2032 — Yangzijiang's chairman calls it the strongest in his 50-year career.
• Tankers lead: COSCO Shipping Energy and CMES see VLCC rates higher in 2027 than the 2026 average and pre-war levels; owners still seek end-2029 slots.
• Containers are split: freight rates face pressure in 2027, but lines keep ordering mega-vessels — momentum should continue through 2027.
3. What did Goldman Sachs find at Hengli — the yard doubling capacity?
• Hengli (via Songfa Ceramics, 603268.SS): capacity set to double, global share to 11% in 2027E; Phase IV dry docks ramp from January 2027 — earlier than Goldman's base case.
• Standardised production cuts dock time 20%–30%, releasing 58 extra delivery slots in 2027–28; management targets 130 / 250 deliveries in 2027 / 2028E.
• Pricing power shows: Hengli removed discounts — new VLCC orders at US$140mn vs a US$131mn market price.
• 3Q26 net profit Rmb3.1bn, +22% QoQ, net margin 21.5%; Songfa Buy, target CNY310.00 — 75% upside (18 Nov 2026 prices).
4. And at Yangzijiang — the other Buy-rated yard?
• Yangzijiang (YAZG.SI) won US$6.98bn of new orders in 10M26 — above its US$4.5bn FY26 target — and expects the same target for 2027.
• Margins hold: 2H26 gross margin seen near 1H26's 36%, with 2025–26 contracts priced like 2024 while peers discount 2%–3%.
• Capacity grows: Hongyuan adds 20% in 2027; restarted Runze — pending approval — could add ~30% more; large-vessel slots are largely full through 2030.
• Yangzijiang Buy, target S$6.00 — 38% upside (18 Nov 2026 prices). Both yards trade at single-digit 2028E P/E (5.6x / 6.5x) vs 9.2x for other Chinese peers.
5. Higher ship prices — but will profits follow? What could go wrong?
• Prices are up — Clarksons newbuilding index +1.3% YTD (13 Nov 2026) — but so are costs: labour ~20% of total cost; engines 10%–20% of a vessel's price.
• Currency matters: every 1% renminbi gain vs the dollar cuts gross margin ~0.4–0.5ppts.
• Protection is real: Yangzijiang earned 10% net margin even in the last downcycle, and customers pay 50% before delivery.
• Watch: Runze approval, Hengli's Phase IV ramp after Spring Festival 2027, engine supply from 2028, container rates into 2027.
#Shipbuilding #Shipping #ChinaStocks #Tankers #Commodities
Source: Goldman Sachs Global Investment Research, 20 November 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Read the full breakdown on Unhidea: https://unhidea.com/en/articles/research-432428126b3f4851a52ef0ef87730858-en
Visit unhidea.com for more of the latest sell-side research interpretations.
36
Strait of Hormuz Security Escalation
In a dangerous tactical shift, a commercial tanker was recently targeted in the Strait of Hormuz after attackers in a speedboat attached explosive devices directly to its hull.
The blasts triggered an engine room fire, temporarily disabling the vessel before the crew managed to safely extinguish it. This marks a concerning development in maritime security across one of the world's most critical energy transit corridors.
As geopolitical tensions rise in the region, commercial shipping and oil transit face mounting risks.
Security analysts warn that if regional powers continue weaponizing these vital choke points, global energy supply chains could face severe, prolonged bottlenecks.
With insurance premiums for Middle Eastern shipping routes spiking overnight, vessel operators are urgently reassessing their security protocols before entering the gulf.
#Geopolitics #OilMarkets #StraitOfHormuz #Shipping #EnergyNews #MaritimeSecurity
$CL
{future}(CLUSDT)
$BZ
{future}(BZUSDT)
$PARTI
{future}(PARTIUSDT)
Strait of Hormuz Security Escalation
In a dangerous tactical shift, a commercial tanker was recently targeted in the Strait of Hormuz after attackers in a speedboat attached explosive devices directly to its hull.
The blasts triggered an engine room fire, temporarily disabling the vessel before the crew managed to safely extinguish it. This marks a concerning development in maritime security across one of the world's most critical energy transit corridors.
As geopolitical tensions rise in the region, commercial shipping and oil transit face mounting risks.
Security analysts warn that if regional powers continue weaponizing these vital choke points, global energy supply chains could face severe, prolonged bottlenecks.
With insurance premiums for Middle Eastern shipping routes spiking overnight, vessel operators are urgently reassessing their security protocols before entering the gulf.
#Geopolitics #OilMarkets #StraitOfHormuz #Shipping #EnergyNews #MaritimeSecurity
$CL
$BZ
$PARTI
In a dangerous tactical shift, a commercial tanker was recently targeted in the Strait of Hormuz after attackers in a speedboat attached explosive devices directly to its hull.
The blasts triggered an engine room fire, temporarily disabling the vessel before the crew managed to safely extinguish it. This marks a concerning development in maritime security across one of the world's most critical energy transit corridors.
As geopolitical tensions rise in the region, commercial shipping and oil transit face mounting risks.
Security analysts warn that if regional powers continue weaponizing these vital choke points, global energy supply chains could face severe, prolonged bottlenecks.
With insurance premiums for Middle Eastern shipping routes spiking overnight, vessel operators are urgently reassessing their security protocols before entering the gulf.
#Geopolitics #OilMarkets #StraitOfHormuz #Shipping #EnergyNews #MaritimeSecurity
$CL
$BZ
$PARTI
2
2.9k
Partly True
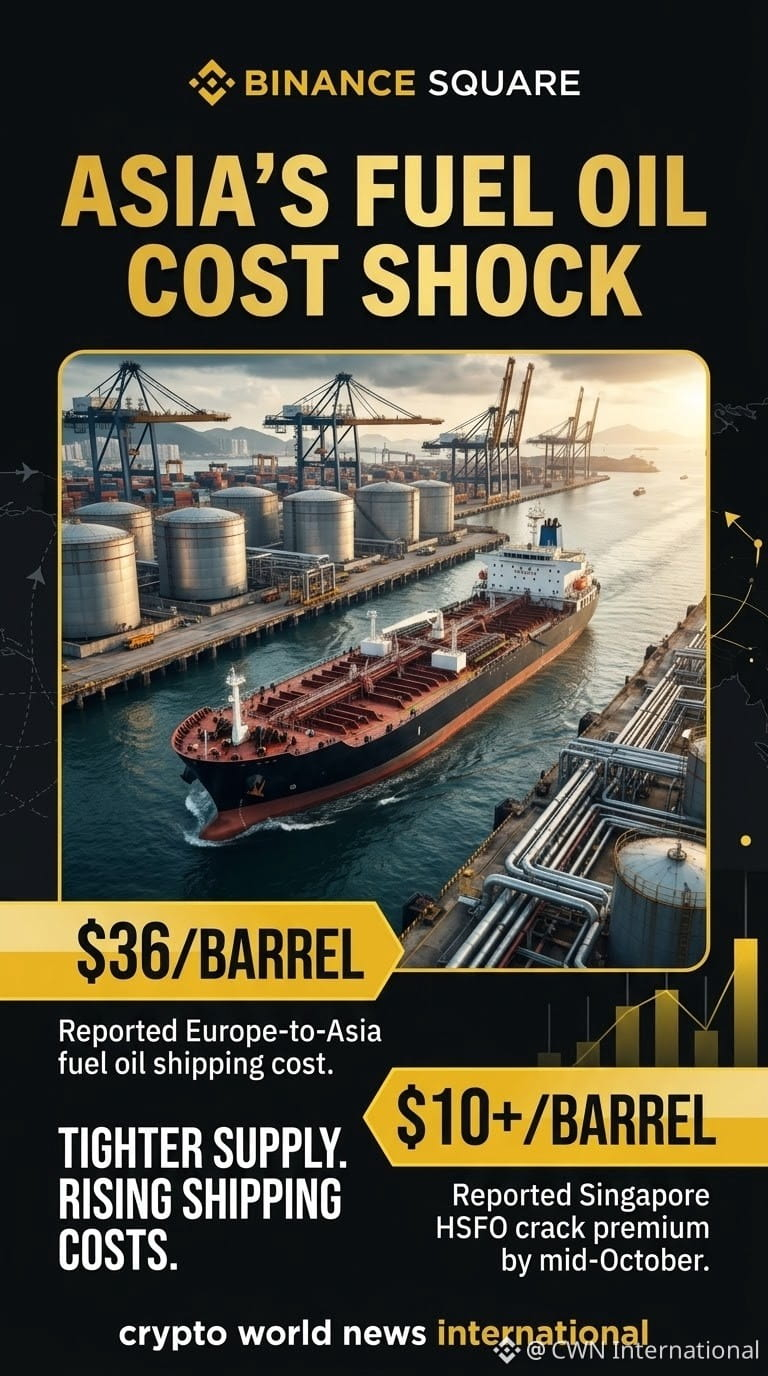
🛢️ ASIA FACES A FUEL OIL COST SHOCK AS SHIPPING EXPENSES SURGE
Summary:
Asia’s fuel oil market is facing growing cost pressure as tighter supply and soaring shipping expenses push up the cost of moving fuel across regions. The squeeze could add further pressure to shipping, trade, and energy-related businesses.
Key Points:
🔹 Fuel Oil Premium Reversal: Singapore’s high-sulphur fuel oil (HSFO) crack shifted from a discount of around $5 per barrel in February to a premium exceeding $10 per barrel by mid-October.
🔹 Shipping Costs Explode: The cost of transporting fuel oil from Europe to Asia reportedly climbed to around $36 per barrel, compared with approximately $6.50 a year earlier.
🔹 Trade Pressure: Higher fuel and freight costs could increase expenses for shipping operators and businesses reliant on energy imports.
🔹 Supply Outlook: Additional supply in the coming months could ease some of the pressure, but the outlook remains uncertain.
Market Insight:
This is more than a crude oil price story. Rising fuel oil premiums and shipping costs can feed into broader trade and inflation pressures across Asia. Markets will be watching energy supply flows, freight rates, and the potential impact on inflation and interest-rate expectations.
⚠️ Higher energy costs do not automatically mean cryptocurrency prices will rise or fall. The impact on crypto depends on broader market sentiment, liquidity, and investor positioning.
#EnergyMarkets #Asia #Shipping #Inflation #OilPrices $CL $BZ
{future}(BZUSDT)
{future}(CLUSDT)
🛢️ ASIA FACES A FUEL OIL COST SHOCK AS SHIPPING EXPENSES SURGE
Summary:
Asia’s fuel oil market is facing growing cost pressure as tighter supply and soaring shipping expenses push up the cost of moving fuel across regions. The squeeze could add further pressure to shipping, trade, and energy-related businesses.
Key Points:
🔹 Fuel Oil Premium Reversal: Singapore’s high-sulphur fuel oil (HSFO) crack shifted from a discount of around $5 per barrel in February to a premium exceeding $10 per barrel by mid-October.
🔹 Shipping Costs Explode: The cost of transporting fuel oil from Europe to Asia reportedly climbed to around $36 per barrel, compared with approximately $6.50 a year earlier.
🔹 Trade Pressure: Higher fuel and freight costs could increase expenses for shipping operators and businesses reliant on energy imports.
🔹 Supply Outlook: Additional supply in the coming months could ease some of the pressure, but the outlook remains uncertain.
Market Insight:
This is more than a crude oil price story. Rising fuel oil premiums and shipping costs can feed into broader trade and inflation pressures across Asia. Markets will be watching energy supply flows, freight rates, and the potential impact on inflation and interest-rate expectations.
⚠️ Higher energy costs do not automatically mean cryptocurrency prices will rise or fall. The impact on crypto depends on broader market sentiment, liquidity, and investor positioning.
#EnergyMarkets #Asia #Shipping #Inflation #OilPrices $CL $BZ
Summary:
Asia’s fuel oil market is facing growing cost pressure as tighter supply and soaring shipping expenses push up the cost of moving fuel across regions. The squeeze could add further pressure to shipping, trade, and energy-related businesses.
Key Points:
🔹 Fuel Oil Premium Reversal: Singapore’s high-sulphur fuel oil (HSFO) crack shifted from a discount of around $5 per barrel in February to a premium exceeding $10 per barrel by mid-October.
🔹 Shipping Costs Explode: The cost of transporting fuel oil from Europe to Asia reportedly climbed to around $36 per barrel, compared with approximately $6.50 a year earlier.
🔹 Trade Pressure: Higher fuel and freight costs could increase expenses for shipping operators and businesses reliant on energy imports.
🔹 Supply Outlook: Additional supply in the coming months could ease some of the pressure, but the outlook remains uncertain.
Market Insight:
This is more than a crude oil price story. Rising fuel oil premiums and shipping costs can feed into broader trade and inflation pressures across Asia. Markets will be watching energy supply flows, freight rates, and the potential impact on inflation and interest-rate expectations.
⚠️ Higher energy costs do not automatically mean cryptocurrency prices will rise or fall. The impact on crypto depends on broader market sentiment, liquidity, and investor positioning.
#EnergyMarkets #Asia #Shipping #Inflation #OilPrices $CL $BZ
568
·
--
🚨 Tankers U-Turn on Possible Hormuz Reopening
Strait of Hormuz is seeing early signs of limited reopening, with tanker movements slowly resuming after recent geopolitical easing ⚠️
🛢️ What’s happening?
Shipping activity is gradually restarting as tensions ease, but operations are still partially restricted.
📊 Market impact:
• Oil volatility remains high
• Tankers adjusting routes
• Insurance + risk costs still elevated
⚡ Key point:
Full normalization is not confirmed yet — recovery will likely be slow and unstable.
Bounce or breakdown in oil next?
💬 Share your view
#Oil #CrudeOil #Shipping #Geopolitics #Hormuz #EnergyMarket #Macro
🚨 Tankers U-Turn on Possible Hormuz Reopening
Strait of Hormuz is seeing early signs of limited reopening, with tanker movements slowly resuming after recent geopolitical easing ⚠️
🛢️ What’s happening?
Shipping activity is gradually restarting as tensions ease, but operations are still partially restricted.
📊 Market impact:
• Oil volatility remains high
• Tankers adjusting routes
• Insurance + risk costs still elevated
⚡ Key point:
Full normalization is not confirmed yet — recovery will likely be slow and unstable.
Bounce or breakdown in oil next?
💬 Share your view
#Oil #CrudeOil #Shipping #Geopolitics #Hormuz #EnergyMarket #Macro
Strait of Hormuz is seeing early signs of limited reopening, with tanker movements slowly resuming after recent geopolitical easing ⚠️
🛢️ What’s happening?
Shipping activity is gradually restarting as tensions ease, but operations are still partially restricted.
📊 Market impact:
• Oil volatility remains high
• Tankers adjusting routes
• Insurance + risk costs still elevated
⚡ Key point:
Full normalization is not confirmed yet — recovery will likely be slow and unstable.
Bounce or breakdown in oil next?
💬 Share your view
#Oil #CrudeOil #Shipping #Geopolitics #Hormuz #EnergyMarket #Macro
98

·
--
🚨 $BTC MACRO RISK SPIKING: HORMUZ HOSTILITIES DRIVE FUEL COSTS SURGING 🔴
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #MacroRisk #Shipping #Fuel #Crypto
🦈 📉
🚨 $BTC MACRO RISK SPIKING: HORMUZ HOSTILITIES DRIVE FUEL COSTS SURGING 🔴
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #MacroRisk #Shipping #Fuel #Crypto
🦈 📉
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #MacroRisk #Shipping #Fuel #Crypto
🦈 📉
34
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BTCReboundsAbove$60KAmidWhaleDipBuying
5,597 views
59 Discussing
2
#NvidiaLoses$2.7TrillionInMonthAndAHalf
44,691 views
209 Discussing
3
#GlobalStocksFaceLongestLosingStreakSince2023
402,328 views
2,659 Discussing
4
#BlackRockIBITPostsRecord$541MSingleDayOutflow
59,256 views
145 Discussing
5
#AnthropicPlungesTowardIPOPriceonDay2
215,608 views
1,708 Discussing
6
#TwentyOneCapitalAdds172.25BTC
104,431 views
1,110 Discussing
7
#HKBillWouldExcludeTokenizedDepositsFromVirtualAssets
14,573 views
66 Discussing
8
#HKBillProposesHK$100KFineForUnauthorizedCryptoTitles
3,621 views
30 Discussing
9
#BitMineFaces$10.1BUnrealizedETHLoss
6,986 views
32 Discussing
10
#StrategyReports$35BNetReserves
3,724 views
24 Discussing