

#nvdl
nvdl
3,127 views
61 Discussing
Hot
Latest
·
--
📉 NVDL — CONSOLIDATION & PULLBACK TOWARD MOVING AVERAGES! 🔄
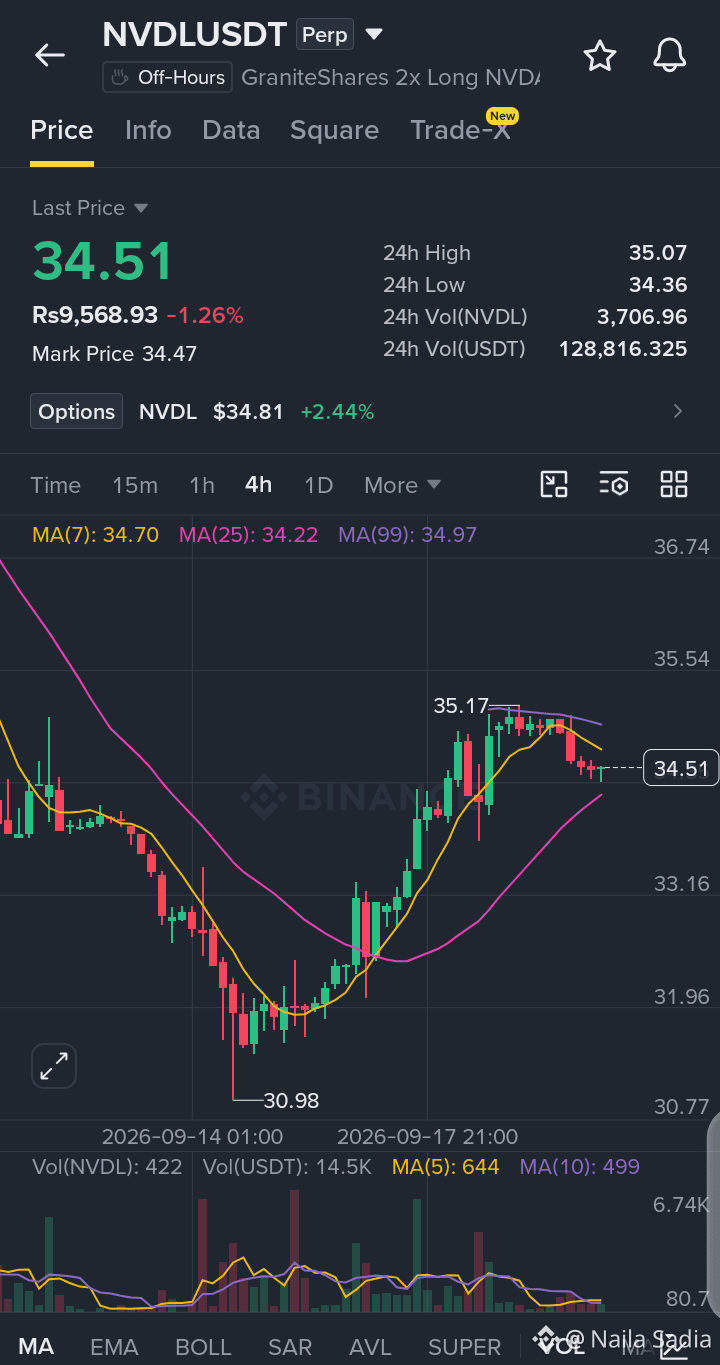
$NVDL (GraniteShares 2x Long NVDA) is trading lower at 34.51 (-1.26%), pulling back from its 24h high of 35.07 toward a 24h low of 34.36. Price is trading right between the 4H moving averages, sitting near the MA25 (34.22) while just under the MA7 (34.70) and major MA99 (34.97) lines.
📊 QUICK TRADE PLAN — 4H
🟢 LONG ENTRY: 33.80–34.30 (on support defense near the MA25 zone)
🛑 STOP LOSS: 32.90
🎯 TP1: 35.50
🎯 TP2: 36.70
Are you watching for NVDL to bounce from these moving averages, or expecting a deeper pullback? Let's discuss below! 👇
👉 Trade: $NVDL
{future}(NVDLUSDT)
#NVDL #NVIDIA #BinanceSquare #RangeBound #TradingSignal
📉 NVDL — CONSOLIDATION & PULLBACK TOWARD MOVING AVERAGES! 🔄
$NVDL (GraniteShares 2x Long NVDA) is trading lower at 34.51 (-1.26%), pulling back from its 24h high of 35.07 toward a 24h low of 34.36. Price is trading right between the 4H moving averages, sitting near the MA25 (34.22) while just under the MA7 (34.70) and major MA99 (34.97) lines.
📊 QUICK TRADE PLAN — 4H
🟢 LONG ENTRY: 33.80–34.30 (on support defense near the MA25 zone)
🛑 STOP LOSS: 32.90
🎯 TP1: 35.50
🎯 TP2: 36.70
Are you watching for NVDL to bounce from these moving averages, or expecting a deeper pullback? Let's discuss below! 👇
👉 Trade: $NVDL
#NVDL #NVIDIA #BinanceSquare #RangeBound #TradingSignal
$NVDL (GraniteShares 2x Long NVDA) is trading lower at 34.51 (-1.26%), pulling back from its 24h high of 35.07 toward a 24h low of 34.36. Price is trading right between the 4H moving averages, sitting near the MA25 (34.22) while just under the MA7 (34.70) and major MA99 (34.97) lines.
📊 QUICK TRADE PLAN — 4H
🟢 LONG ENTRY: 33.80–34.30 (on support defense near the MA25 zone)
🛑 STOP LOSS: 32.90
🎯 TP1: 35.50
🎯 TP2: 36.70
Are you watching for NVDL to bounce from these moving averages, or expecting a deeper pullback? Let's discuss below! 👇
👉 Trade: $NVDL
#NVDL #NVIDIA #BinanceSquare #RangeBound #TradingSignal
117

·
--
[M1_mag7]
In the past 24 hours it dropped 1.341%, closing at 34.58. The intraday swings of this on-chain perpetual contract, $NVDL, match the “hold your breath” feeling that US stock tech giants create right before Monday’s trading opens. The perpetual funding rate is 0—an absolutely neutral number—which means neither the longs nor the shorts are paying anyone right now; the leveraged market has, for the moment, drawn level on this particular scoreboard.
Put simply, a zero funding rate is a somewhat counterintuitive signal in the current environment. When prices fall, and market sentiment is skewed bearish, shorts would typically pay longs (i.e., the funding rate would be negative). Now it’s zero, meaning that even though the price is dropping, the force driving active shorting—and the willingness to pay the cost for it—is not as strong as people might assume. Likewise, the long side hasn’t been aggressive enough to bid up the price using a positive funding rate to snap up positions. With an open interest of 4727.70 units and a trading volume of $108,777.75, the numbers themselves aren’t large and liquidity isn’t very robust. This creates a point of observation: against the backdrop of the Mag7 segment being deeply tied to SPY/QQQ, the on-chain order book for $NVDL shows a low-liquidity, short-term standoff between longs and shorts—it’s not the leading indicator of this tech-stock volatility; it’s more like a shadow that follows along but lacks sufficient sensitivity.
So, old dog’s view is: $NVDL’s on-chain perpetuals are currently stuck in a liquidity trough that the market has temporarily forgotten. They track the volatility of the underlying asset (US tech giants), but the contract’s own pricing and leverage interest are oscillating at low levels. The strongest counter-evidence is this: if SPY or QQQ at the current level were to break out clearly in either direction, this stalemate would be shattered instantly. A large amount of capital would rush into a contract that hasn’t been priced sufficiently, causing both the contract price and the funding rate to swing sharply. Next, if the broader market chooses a direction, the cost will likely be borne by the holders who currently have relatively small positions but aren’t firmly committed in terms of direction. They’ll be forced to make a quick choice, and the sudden influx of liquidity would amplify the contract’s short-term deviation relative to the underlying.
My current action: observe, don’t touch. Add this product to a key watchlist. The condition to trigger adding to the position is: $NVDL price breaking out on increased volume above the upper bound of the current range (based on the existing 34.58 price, we need to see a strong, sustained pull upward on consecutive hour-level candles), and at the same time the funding rate turns positive and keeps rising.
Trading tag: #BinanceFutures #TradFi #USDⓈM #NVDL #NVDLUSDT $NVDL
[M1_mag7]
In the past 24 hours it dropped 1.341%, closing at 34.58. The intraday swings of this on-chain perpetual contract, $NVDL , match the “hold your breath” feeling that US stock tech giants create right before Monday’s trading opens. The perpetual funding rate is 0—an absolutely neutral number—which means neither the longs nor the shorts are paying anyone right now; the leveraged market has, for the moment, drawn level on this particular scoreboard.
Put simply, a zero funding rate is a somewhat counterintuitive signal in the current environment. When prices fall, and market sentiment is skewed bearish, shorts would typically pay longs (i.e., the funding rate would be negative). Now it’s zero, meaning that even though the price is dropping, the force driving active shorting—and the willingness to pay the cost for it—is not as strong as people might assume. Likewise, the long side hasn’t been aggressive enough to bid up the price using a positive funding rate to snap up positions. With an open interest of 4727.70 units and a trading volume of $108,777.75, the numbers themselves aren’t large and liquidity isn’t very robust. This creates a point of observation: against the backdrop of the Mag7 segment being deeply tied to SPY/QQQ, the on-chain order book for $NVDL shows a low-liquidity, short-term standoff between longs and shorts—it’s not the leading indicator of this tech-stock volatility; it’s more like a shadow that follows along but lacks sufficient sensitivity.
So, old dog’s view is: $NVDL ’s on-chain perpetuals are currently stuck in a liquidity trough that the market has temporarily forgotten. They track the volatility of the underlying asset (US tech giants), but the contract’s own pricing and leverage interest are oscillating at low levels. The strongest counter-evidence is this: if SPY or QQQ at the current level were to break out clearly in either direction, this stalemate would be shattered instantly. A large amount of capital would rush into a contract that hasn’t been priced sufficiently, causing both the contract price and the funding rate to swing sharply. Next, if the broader market chooses a direction, the cost will likely be borne by the holders who currently have relatively small positions but aren’t firmly committed in terms of direction. They’ll be forced to make a quick choice, and the sudden influx of liquidity would amplify the contract’s short-term deviation relative to the underlying.
My current action: observe, don’t touch. Add this product to a key watchlist. The condition to trigger adding to the position is: $NVDL price breaking out on increased volume above the upper bound of the current range (based on the existing 34.58 price, we need to see a strong, sustained pull upward on consecutive hour-level candles), and at the same time the funding rate turns positive and keeps rising.
Trading tag: #BinanceFutures #TradFi #USDⓈM #NVDL #NVDLUSDT $NVDL
In the past 24 hours it dropped 1.341%, closing at 34.58. The intraday swings of this on-chain perpetual contract, $NVDL , match the “hold your breath” feeling that US stock tech giants create right before Monday’s trading opens. The perpetual funding rate is 0—an absolutely neutral number—which means neither the longs nor the shorts are paying anyone right now; the leveraged market has, for the moment, drawn level on this particular scoreboard.
Put simply, a zero funding rate is a somewhat counterintuitive signal in the current environment. When prices fall, and market sentiment is skewed bearish, shorts would typically pay longs (i.e., the funding rate would be negative). Now it’s zero, meaning that even though the price is dropping, the force driving active shorting—and the willingness to pay the cost for it—is not as strong as people might assume. Likewise, the long side hasn’t been aggressive enough to bid up the price using a positive funding rate to snap up positions. With an open interest of 4727.70 units and a trading volume of $108,777.75, the numbers themselves aren’t large and liquidity isn’t very robust. This creates a point of observation: against the backdrop of the Mag7 segment being deeply tied to SPY/QQQ, the on-chain order book for $NVDL shows a low-liquidity, short-term standoff between longs and shorts—it’s not the leading indicator of this tech-stock volatility; it’s more like a shadow that follows along but lacks sufficient sensitivity.
So, old dog’s view is: $NVDL ’s on-chain perpetuals are currently stuck in a liquidity trough that the market has temporarily forgotten. They track the volatility of the underlying asset (US tech giants), but the contract’s own pricing and leverage interest are oscillating at low levels. The strongest counter-evidence is this: if SPY or QQQ at the current level were to break out clearly in either direction, this stalemate would be shattered instantly. A large amount of capital would rush into a contract that hasn’t been priced sufficiently, causing both the contract price and the funding rate to swing sharply. Next, if the broader market chooses a direction, the cost will likely be borne by the holders who currently have relatively small positions but aren’t firmly committed in terms of direction. They’ll be forced to make a quick choice, and the sudden influx of liquidity would amplify the contract’s short-term deviation relative to the underlying.
My current action: observe, don’t touch. Add this product to a key watchlist. The condition to trigger adding to the position is: $NVDL price breaking out on increased volume above the upper bound of the current range (based on the existing 34.58 price, we need to see a strong, sustained pull upward on consecutive hour-level candles), and at the same time the funding rate turns positive and keeps rising.
Trading tag: #BinanceFutures #TradFi #USDⓈM #NVDL #NVDLUSDT $NVDL
95
NVDL成交额垫底,持空到0
The data is here—see for yourself.
🔻 NVDL #NVDL 【Main】
Current: 32.2900, 24h change: -1.94%
24h trading volume is only $341,000—bottom of the whole market
→ Volume down 22.8%; selling pressure is building—keep shorting until 0
Without buying power, it’s hard to see a decent rebound
If it rebounds to around 38.7480, you can try shorting; if it breaks 42.6228, exit
These are also good opportunities to short:
····
UNI
Current 6.4270, 24h change +2.78%
Entry time: place a short order at 7.7124, set stop-loss at 10% (8.4836)
····
ARK
Current 0.163200, 24h change +0.99%
Entry time: place a short order at 0.195840, set stop-loss at 10% (0.215424)
····
⚠️ Small capital—test carefully, use strict stop-loss, and don’t do trades without risk control
#crypto
NVDL成交额垫底,持空到0
The data is here—see for yourself.
🔻 NVDL #NVDL 【Main】
Current: 32.2900, 24h change: -1.94%
24h trading volume is only $341,000—bottom of the whole market
→ Volume down 22.8%; selling pressure is building—keep shorting until 0
Without buying power, it’s hard to see a decent rebound
If it rebounds to around 38.7480, you can try shorting; if it breaks 42.6228, exit
These are also good opportunities to short:
····
UNI
Current 6.4270, 24h change +2.78%
Entry time: place a short order at 7.7124, set stop-loss at 10% (8.4836)
····
ARK
Current 0.163200, 24h change +0.99%
Entry time: place a short order at 0.195840, set stop-loss at 10% (0.215424)
····
⚠️ Small capital—test carefully, use strict stop-loss, and don’t do trades without risk control
#crypto
The data is here—see for yourself.
🔻 NVDL #NVDL 【Main】
Current: 32.2900, 24h change: -1.94%
24h trading volume is only $341,000—bottom of the whole market
→ Volume down 22.8%; selling pressure is building—keep shorting until 0
Without buying power, it’s hard to see a decent rebound
If it rebounds to around 38.7480, you can try shorting; if it breaks 42.6228, exit
These are also good opportunities to short:
····
UNI
Current 6.4270, 24h change +2.78%
Entry time: place a short order at 7.7124, set stop-loss at 10% (8.4836)
····
ARK
Current 0.163200, 24h change +0.99%
Entry time: place a short order at 0.195840, set stop-loss at 10% (0.215424)
····
⚠️ Small capital—test carefully, use strict stop-loss, and don’t do trades without risk control
#crypto
226
·
--
An old dog glanced at $NVDL: the price was 31.94, down 3.882% over the past 24 hours, with trading volume surging to nearly 300,000 lots. But the funding rate still calmly sits at 0. This scene is kind of interesting. In the semiconductor chain, the underlying is down—but in the funding market, neither the longs nor the shorts have really paid each other money. The market is in a delicate balance state.
From the perspective of the M2_semi semiconductor/AI chain, this pullback isn’t small, especially without any secondary meme for comparison—so you can only focus on $NVDL itself. Trading volume of 299,365.952 versus open interest of 5,693.83 implies extremely high turnover, suggesting frequent in-and-out activity from short-term funds, yet the price remains under pressure. The key point is the funding rate being 0. It’s neither positive nor negative, meaning the current position cost is the same for both longs and shorts—there’s no classic “longs crowded” or “shorts crowded” signal. In a funding-rate-neutral environment, a price drop is more likely attributable to spot selling pressure or new short positions opening, rather than existing long positions being forced out via liquidation.
So my view is that the current weakness is driven more by spot selling or sentiment, not by a systemic risk showing up in the derivatives market. With the funding rate at zero, it indicates position costs are balanced, and during the decline there hasn’t formed the typical squeeze structure—longs holding on to bleed negative funding, or shorts being forced out by positive funding. That implies the price may stop falling and stabilize without first squeezing out a batch of stubborn counterparty positions.
What’s the strongest counter-evidence? It’s the trading volume itself. If during the drop the volume continues to expand and the funding rate remains 0, it could also mean shorts are constantly opening new positions, and since they’re not paying funding costs for the moment, the downtrend could have more inertia. But we don’t currently have enough continuous data to verify that. On a second-order impact: if the price keeps drifting lower under a zero funding rate, it may attract even more short-term shorts to enter, until the funding rate turns negative—then the situation may shift.
My invalidation conditions are very clear: the funding rate turns. If next the funding rate turns positive, even slightly—say to +0.01%—while the price is still falling, that would mean longs are passively adding or stubbornly holding, and my original judgment would be wrong: the market would enter a more dangerous long-squeeze/crowding phase. Conversely, if the funding rate turns negative and the price rebounds, that’s a signal of a short squeeze. Right now the funding rate is 0, so my action is straightforward: observe, not rush in. Wait until the funding rate shows a clear directional tilt (for example, continuously above or below ±0.01%), and then decide.
Trading tag: #BinanceFutures #TradFi #USDⓈM #NVDL #NVDLUSDT $NVDL
An old dog glanced at $NVDL : the price was 31.94, down 3.882% over the past 24 hours, with trading volume surging to nearly 300,000 lots. But the funding rate still calmly sits at 0. This scene is kind of interesting. In the semiconductor chain, the underlying is down—but in the funding market, neither the longs nor the shorts have really paid each other money. The market is in a delicate balance state.
From the perspective of the M2_semi semiconductor/AI chain, this pullback isn’t small, especially without any secondary meme for comparison—so you can only focus on $NVDL itself. Trading volume of 299,365.952 versus open interest of 5,693.83 implies extremely high turnover, suggesting frequent in-and-out activity from short-term funds, yet the price remains under pressure. The key point is the funding rate being 0. It’s neither positive nor negative, meaning the current position cost is the same for both longs and shorts—there’s no classic “longs crowded” or “shorts crowded” signal. In a funding-rate-neutral environment, a price drop is more likely attributable to spot selling pressure or new short positions opening, rather than existing long positions being forced out via liquidation.
So my view is that the current weakness is driven more by spot selling or sentiment, not by a systemic risk showing up in the derivatives market. With the funding rate at zero, it indicates position costs are balanced, and during the decline there hasn’t formed the typical squeeze structure—longs holding on to bleed negative funding, or shorts being forced out by positive funding. That implies the price may stop falling and stabilize without first squeezing out a batch of stubborn counterparty positions.
What’s the strongest counter-evidence? It’s the trading volume itself. If during the drop the volume continues to expand and the funding rate remains 0, it could also mean shorts are constantly opening new positions, and since they’re not paying funding costs for the moment, the downtrend could have more inertia. But we don’t currently have enough continuous data to verify that. On a second-order impact: if the price keeps drifting lower under a zero funding rate, it may attract even more short-term shorts to enter, until the funding rate turns negative—then the situation may shift.
My invalidation conditions are very clear: the funding rate turns. If next the funding rate turns positive, even slightly—say to +0.01%—while the price is still falling, that would mean longs are passively adding or stubbornly holding, and my original judgment would be wrong: the market would enter a more dangerous long-squeeze/crowding phase. Conversely, if the funding rate turns negative and the price rebounds, that’s a signal of a short squeeze. Right now the funding rate is 0, so my action is straightforward: observe, not rush in. Wait until the funding rate shows a clear directional tilt (for example, continuously above or below ±0.01%), and then decide.
Trading tag: #BinanceFutures #TradFi #USDⓈM #NVDL #NVDLUSDT $NVDL
From the perspective of the M2_semi semiconductor/AI chain, this pullback isn’t small, especially without any secondary meme for comparison—so you can only focus on $NVDL itself. Trading volume of 299,365.952 versus open interest of 5,693.83 implies extremely high turnover, suggesting frequent in-and-out activity from short-term funds, yet the price remains under pressure. The key point is the funding rate being 0. It’s neither positive nor negative, meaning the current position cost is the same for both longs and shorts—there’s no classic “longs crowded” or “shorts crowded” signal. In a funding-rate-neutral environment, a price drop is more likely attributable to spot selling pressure or new short positions opening, rather than existing long positions being forced out via liquidation.
So my view is that the current weakness is driven more by spot selling or sentiment, not by a systemic risk showing up in the derivatives market. With the funding rate at zero, it indicates position costs are balanced, and during the decline there hasn’t formed the typical squeeze structure—longs holding on to bleed negative funding, or shorts being forced out by positive funding. That implies the price may stop falling and stabilize without first squeezing out a batch of stubborn counterparty positions.
What’s the strongest counter-evidence? It’s the trading volume itself. If during the drop the volume continues to expand and the funding rate remains 0, it could also mean shorts are constantly opening new positions, and since they’re not paying funding costs for the moment, the downtrend could have more inertia. But we don’t currently have enough continuous data to verify that. On a second-order impact: if the price keeps drifting lower under a zero funding rate, it may attract even more short-term shorts to enter, until the funding rate turns negative—then the situation may shift.
My invalidation conditions are very clear: the funding rate turns. If next the funding rate turns positive, even slightly—say to +0.01%—while the price is still falling, that would mean longs are passively adding or stubbornly holding, and my original judgment would be wrong: the market would enter a more dangerous long-squeeze/crowding phase. Conversely, if the funding rate turns negative and the price rebounds, that’s a signal of a short squeeze. Right now the funding rate is 0, so my action is straightforward: observe, not rush in. Wait until the funding rate shows a clear directional tilt (for example, continuously above or below ±0.01%), and then decide.
Trading tag: #BinanceFutures #TradFi #USDⓈM #NVDL #NVDLUSDT $NVDL
38

·
--
NVDL dropped 3.384% in the past 24 hours, and the funding rate is locked at 0. The price is falling, but the funding rate has gone to zero—indicating both longs and shorts are holding back, with no clear side taking the lead and paying fees.
Trump’s remarks to tech stocks caused the market to choose to sell off first, and that sentiment was carried over to on-chain U.S. stock futures contracts. With the funding rate at zero, the cost of holding long positions is lower, but the steady drift downward suggests buy-side participation isn’t strong; the market is effectively assuming shorts have the upper hand.
The strongest counterpoint is that policy could ultimately turn favorable for tech stocks, squeezing the shorts. But I believe the market will trade fear first.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
NVDL dropped 3.384% in the past 24 hours, and the funding rate is locked at 0. The price is falling, but the funding rate has gone to zero—indicating both longs and shorts are holding back, with no clear side taking the lead and paying fees.
Trump’s remarks to tech stocks caused the market to choose to sell off first, and that sentiment was carried over to on-chain U.S. stock futures contracts. With the funding rate at zero, the cost of holding long positions is lower, but the steady drift downward suggests buy-side participation isn’t strong; the market is effectively assuming shorts have the upper hand.
The strongest counterpoint is that policy could ultimately turn favorable for tech stocks, squeezing the shorts. But I believe the market will trade fear first.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
Trump’s remarks to tech stocks caused the market to choose to sell off first, and that sentiment was carried over to on-chain U.S. stock futures contracts. With the funding rate at zero, the cost of holding long positions is lower, but the steady drift downward suggests buy-side participation isn’t strong; the market is effectively assuming shorts have the upper hand.
The strongest counterpoint is that policy could ultimately turn favorable for tech stocks, squeezing the shorts. But I believe the market will trade fear first.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
11
·
--
$NVDL price 32.83, down 3.38% in the past 24 hours, open interest 5,073 contracts, and the funding rate is zero.
The shorts are probing. Price is falling but OI hasn’t collapsed, which suggests the shorts are building positions, but not at the stage of a crazy squeeze yet. A funding rate of 0 indicates that longs and shorts are temporarily balanced. The impact of the Trump trade on U.S. stocks is two-way; the market is repricing traditional assets in anticipation of a possible policy shift, and leveraged products like $NVDL have become an amplifier.
My view: The shorts are betting on a pullback in U.S. stocks, but they haven’t formed a unified force yet.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
$NVDL price 32.83, down 3.38% in the past 24 hours, open interest 5,073 contracts, and the funding rate is zero.
The shorts are probing. Price is falling but OI hasn’t collapsed, which suggests the shorts are building positions, but not at the stage of a crazy squeeze yet. A funding rate of 0 indicates that longs and shorts are temporarily balanced. The impact of the Trump trade on U.S. stocks is two-way; the market is repricing traditional assets in anticipation of a possible policy shift, and leveraged products like $NVDL have become an amplifier.
My view: The shorts are betting on a pullback in U.S. stocks, but they haven’t formed a unified force yet.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
The shorts are probing. Price is falling but OI hasn’t collapsed, which suggests the shorts are building positions, but not at the stage of a crazy squeeze yet. A funding rate of 0 indicates that longs and shorts are temporarily balanced. The impact of the Trump trade on U.S. stocks is two-way; the market is repricing traditional assets in anticipation of a possible policy shift, and leveraged products like $NVDL have become an amplifier.
My view: The shorts are betting on a pullback in U.S. stocks, but they haven’t formed a unified force yet.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
22
·
--
$NVDL In the past 24 hours, it dropped 2.495%. The price is hovering around 33.22. Trading volume is about 62,000 units. The funding rate stays at zero, and the open interest remains at 4807.72. The old dog took a quick look: this set of data is laid out on the order book for the semiconductor/AI track—like a neutral thermometer. It’s down, but there’s no panic; the funding rate isn’t skewed; and the position hasn’t been liquidated. The angle is M2_semi—watching sector peers and where we are in the cycle—but since the input didn’t include secondary data for other coins, I can only dig it out from $NVDL itself.
Why is the semiconductor chain “catching its breath” right now? From the funding rate: a zero funding rate means neither bulls nor bears are being forced to pay. Market sentiment isn’t cold or hot—it’s not crowded enough to blow someone up. With open interest at 4807.72, compared to 62,000 traded in the last 24 hours, turnover isn’t particularly fierce. The old dog judges this isn’t panic selling; it looks more like a natural pullback from a high point in the cycle. In the industry, people often say AI and semiconductors are in the middle stage of a technical upgrade cycle—demand is holding up, but valuations still need to digest. As an on-chain “US equities” proxy, $NVDL follows the swings of giants like Nvidia, but since the input doesn’t provide specific peer data, I won’t make anything up. With a single signal: price falling alongside a zero funding rate suggests selling pressure may come from profit-taking rather than bears pushing the market down. Because if bears were truly strong, the funding rate should turn negative.
So my take is: this drop in $NVDL is part of the semiconductor chain’s cycle adjustment, not a trend reversal. The trigger is simple: if the price breaks below 33.00 (near the low area of the past 24 hours), I’ll cut my position by 30%, because a breakdown could cause longs to stop out along the chain. If the funding rate turns positive and the price rebounds, I’ll watch whether it’s a fake breakout. The contrarian part is that the market might treat a zero funding rate as a safety cushion, but the old dog thinks a zero funding rate actually reveals directional ambiguity. In that kind of situation, chasing higher can trap you somewhere around mid-mountain. As for positioning: I advocate staying light and observing, not going heavy on a bet—wait for the semiconductor chain to produce a clear signal, like a sudden spike in open interest or the funding rate tilting.
Where can this judgment most easily be wrong? If the semiconductor industry suddenly releases good news—say, AI application rollout accelerates or policy support arrives—$NVDL could quickly regain lost ground. Then a break above 34.00 (recent resistance reference) would mean the adjustment is over, and I’d need to撤销 my bearish stance. Or if the funding rate suddenly turns negative, indicating the bears are gaining strength, the drop may continue—but the current data doesn’t support that.
Trading tag: #BinanceFutures #TradFi #USDⓈM #NVDL #NVDLUSDT $NVDL
$NVDL In the past 24 hours, it dropped 2.495%. The price is hovering around 33.22. Trading volume is about 62,000 units. The funding rate stays at zero, and the open interest remains at 4807.72. The old dog took a quick look: this set of data is laid out on the order book for the semiconductor/AI track—like a neutral thermometer. It’s down, but there’s no panic; the funding rate isn’t skewed; and the position hasn’t been liquidated. The angle is M2_semi—watching sector peers and where we are in the cycle—but since the input didn’t include secondary data for other coins, I can only dig it out from $NVDL itself.
Why is the semiconductor chain “catching its breath” right now? From the funding rate: a zero funding rate means neither bulls nor bears are being forced to pay. Market sentiment isn’t cold or hot—it’s not crowded enough to blow someone up. With open interest at 4807.72, compared to 62,000 traded in the last 24 hours, turnover isn’t particularly fierce. The old dog judges this isn’t panic selling; it looks more like a natural pullback from a high point in the cycle. In the industry, people often say AI and semiconductors are in the middle stage of a technical upgrade cycle—demand is holding up, but valuations still need to digest. As an on-chain “US equities” proxy, $NVDL follows the swings of giants like Nvidia, but since the input doesn’t provide specific peer data, I won’t make anything up. With a single signal: price falling alongside a zero funding rate suggests selling pressure may come from profit-taking rather than bears pushing the market down. Because if bears were truly strong, the funding rate should turn negative.
So my take is: this drop in $NVDL is part of the semiconductor chain’s cycle adjustment, not a trend reversal. The trigger is simple: if the price breaks below 33.00 (near the low area of the past 24 hours), I’ll cut my position by 30%, because a breakdown could cause longs to stop out along the chain. If the funding rate turns positive and the price rebounds, I’ll watch whether it’s a fake breakout. The contrarian part is that the market might treat a zero funding rate as a safety cushion, but the old dog thinks a zero funding rate actually reveals directional ambiguity. In that kind of situation, chasing higher can trap you somewhere around mid-mountain. As for positioning: I advocate staying light and observing, not going heavy on a bet—wait for the semiconductor chain to produce a clear signal, like a sudden spike in open interest or the funding rate tilting.
Where can this judgment most easily be wrong? If the semiconductor industry suddenly releases good news—say, AI application rollout accelerates or policy support arrives—$NVDL could quickly regain lost ground. Then a break above 34.00 (recent resistance reference) would mean the adjustment is over, and I’d need to撤销 my bearish stance. Or if the funding rate suddenly turns negative, indicating the bears are gaining strength, the drop may continue—but the current data doesn’t support that.
Trading tag: #BinanceFutures #TradFi #USDⓈM #NVDL #NVDLUSDT $NVDL
Why is the semiconductor chain “catching its breath” right now? From the funding rate: a zero funding rate means neither bulls nor bears are being forced to pay. Market sentiment isn’t cold or hot—it’s not crowded enough to blow someone up. With open interest at 4807.72, compared to 62,000 traded in the last 24 hours, turnover isn’t particularly fierce. The old dog judges this isn’t panic selling; it looks more like a natural pullback from a high point in the cycle. In the industry, people often say AI and semiconductors are in the middle stage of a technical upgrade cycle—demand is holding up, but valuations still need to digest. As an on-chain “US equities” proxy, $NVDL follows the swings of giants like Nvidia, but since the input doesn’t provide specific peer data, I won’t make anything up. With a single signal: price falling alongside a zero funding rate suggests selling pressure may come from profit-taking rather than bears pushing the market down. Because if bears were truly strong, the funding rate should turn negative.
So my take is: this drop in $NVDL is part of the semiconductor chain’s cycle adjustment, not a trend reversal. The trigger is simple: if the price breaks below 33.00 (near the low area of the past 24 hours), I’ll cut my position by 30%, because a breakdown could cause longs to stop out along the chain. If the funding rate turns positive and the price rebounds, I’ll watch whether it’s a fake breakout. The contrarian part is that the market might treat a zero funding rate as a safety cushion, but the old dog thinks a zero funding rate actually reveals directional ambiguity. In that kind of situation, chasing higher can trap you somewhere around mid-mountain. As for positioning: I advocate staying light and observing, not going heavy on a bet—wait for the semiconductor chain to produce a clear signal, like a sudden spike in open interest or the funding rate tilting.
Where can this judgment most easily be wrong? If the semiconductor industry suddenly releases good news—say, AI application rollout accelerates or policy support arrives—$NVDL could quickly regain lost ground. Then a break above 34.00 (recent resistance reference) would mean the adjustment is over, and I’d need to撤销 my bearish stance. Or if the funding rate suddenly turns negative, indicating the bears are gaining strength, the drop may continue—but the current data doesn’t support that.
Trading tag: #BinanceFutures #TradFi #USDⓈM #NVDL #NVDLUSDT $NVDL
24
·
--
$NVDL
{future}(NVDLUSDT)
NVDL is showing bullish momentum with strong volatility.
🚀 A breakout above resistance could open the way for further upside.
Losing key support may trigger a short-term pullback.
Bias: Neutral-to-Bullish — watch volume and breakout confirmation.#NVDL #BNBTops730USDT #OpenAILaunchesAgentsAPIPublicBeta #OpticalCommsStocksRallyOver3% #OpticalCommsStocksRallyOver3%
$NVDL
NVDL is showing bullish momentum with strong volatility.
🚀 A breakout above resistance could open the way for further upside.
Losing key support may trigger a short-term pullback.
Bias: Neutral-to-Bullish — watch volume and breakout confirmation.#NVDL #BNBTops730USDT #OpenAILaunchesAgentsAPIPublicBeta #OpticalCommsStocksRallyOver3% #OpticalCommsStocksRallyOver3%
NVDL is showing bullish momentum with strong volatility.
🚀 A breakout above resistance could open the way for further upside.
Losing key support may trigger a short-term pullback.
Bias: Neutral-to-Bullish — watch volume and breakout confirmation.#NVDL #BNBTops730USDT #OpenAILaunchesAgentsAPIPublicBeta #OpticalCommsStocksRallyOver3% #OpticalCommsStocksRallyOver3%

103

·
--
NVDL fell 2.36% to 34.31 within 24 hours, but the contract funding rate is zero. This is an interesting micro signal: there is downward pressure on price, but shorts do not gain any extra benefit, and longs are not being squeezed either—so the market has entered a period of watch-and-wait between bulls and bears.
Last time a similar zero-fee rate combined with a mild decline was seen, the market was often waiting for a catalyst to break the deadlock. With 4,375.66 positions held, there has been no extreme change, suggesting that the leading funds have not yet made a directional bet.
This low-volatility environment is suitable for probing.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
NVDL fell 2.36% to 34.31 within 24 hours, but the contract funding rate is zero. This is an interesting micro signal: there is downward pressure on price, but shorts do not gain any extra benefit, and longs are not being squeezed either—so the market has entered a period of watch-and-wait between bulls and bears.
Last time a similar zero-fee rate combined with a mild decline was seen, the market was often waiting for a catalyst to break the deadlock. With 4,375.66 positions held, there has been no extreme change, suggesting that the leading funds have not yet made a directional bet.
This low-volatility environment is suitable for probing.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
Last time a similar zero-fee rate combined with a mild decline was seen, the market was often waiting for a catalyst to break the deadlock. With 4,375.66 positions held, there has been no extreme change, suggesting that the leading funds have not yet made a directional bet.
This low-volatility environment is suitable for probing.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
24
·
--
$NVDL fell 2.362% over the past 24 hours; price is 34.31, and the funding rate remains at the zero line.
Although the price has pulled back, the funding rate has not fallen to negative values, indicating that the short side on the derivatives side has not made any large bets. This round of decline is more likely driven by sell pressure originating from the spot market, with a lack of bearish consensus in the futures/contract market to amplify the move. Open interest at 4375.66 showed no unusual activity, confirming the institutions’ wait-and-see stance.
Single-signal interpretation: spot sell pressure dominates. If the price continues to move downward but the funding rate still does not turn negative, it can be viewed as a sign that the spot sell-off/cleanse is complete and that contract shorts are unwilling to follow through.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
$NVDL fell 2.362% over the past 24 hours; price is 34.31, and the funding rate remains at the zero line.
Although the price has pulled back, the funding rate has not fallen to negative values, indicating that the short side on the derivatives side has not made any large bets. This round of decline is more likely driven by sell pressure originating from the spot market, with a lack of bearish consensus in the futures/contract market to amplify the move. Open interest at 4375.66 showed no unusual activity, confirming the institutions’ wait-and-see stance.
Single-signal interpretation: spot sell pressure dominates. If the price continues to move downward but the funding rate still does not turn negative, it can be viewed as a sign that the spot sell-off/cleanse is complete and that contract shorts are unwilling to follow through.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
Although the price has pulled back, the funding rate has not fallen to negative values, indicating that the short side on the derivatives side has not made any large bets. This round of decline is more likely driven by sell pressure originating from the spot market, with a lack of bearish consensus in the futures/contract market to amplify the move. Open interest at 4375.66 showed no unusual activity, confirming the institutions’ wait-and-see stance.
Single-signal interpretation: spot sell pressure dominates. If the price continues to move downward but the funding rate still does not turn negative, it can be viewed as a sign that the spot sell-off/cleanse is complete and that contract shorts are unwilling to follow through.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
11
·
--
$NVDL fell 2.362% over the past 24 hours; the price reached 34.31, but the funding rate has gone to zero. This isn’t a script for chasing shorts; both longs and shorts are waiting, and positions haven’t moved.
A slight price dip combined with zero fees indicates that the selling pressure is a slow sell-off from the spot market, not a panic squeeze from the derivatives market. Longs weren’t squeezed out by funding fees, and shorts have no motivation to add. The market is waiting for a catalyst.
The position structure is loose. Next, either the U.S. stock market broad index will set the direction, or volume will expand to break the balance. Near the current price, try a 5% position; if it falls below 33.5, cut the loss and exit.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this thesis is most likely to be wrong?
$NVDL fell 2.362% over the past 24 hours; the price reached 34.31, but the funding rate has gone to zero. This isn’t a script for chasing shorts; both longs and shorts are waiting, and positions haven’t moved.
A slight price dip combined with zero fees indicates that the selling pressure is a slow sell-off from the spot market, not a panic squeeze from the derivatives market. Longs weren’t squeezed out by funding fees, and shorts have no motivation to add. The market is waiting for a catalyst.
The position structure is loose. Next, either the U.S. stock market broad index will set the direction, or volume will expand to break the balance. Near the current price, try a 5% position; if it falls below 33.5, cut the loss and exit.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this thesis is most likely to be wrong?
A slight price dip combined with zero fees indicates that the selling pressure is a slow sell-off from the spot market, not a panic squeeze from the derivatives market. Longs weren’t squeezed out by funding fees, and shorts have no motivation to add. The market is waiting for a catalyst.
The position structure is loose. Next, either the U.S. stock market broad index will set the direction, or volume will expand to break the balance. Near the current price, try a 5% position; if it falls below 33.5, cut the loss and exit.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this thesis is most likely to be wrong?
13
·
--
$NVDL’s single-day drop of 4.8% has amplified the fragility of Bitcoin spot leveraged products under political narratives. The funding rate of 0.00059787 stays positive; with price falling alongside a positive fee rate, long positions accumulate carrying costs, while shorts collect fees. The position size is 4433.94 units. In a downward price environment, open contracts have not decreased significantly, suggesting longs are holding on rather than exiting with large-scale stop-losses.
Why does politics strike $NVDL at this point? The market is trading one hypothesis: if regulatory policy shifts or fiscal expectations tighten, high-risk, high-leverage exposures like crypto assets would be the first targets to be dumped. As a leveraged product tied to the U.S. stock market, $NVDL’s volatility directly maps to Bitcoin spot. When political winds change, Bitcoin is often viewed as a liquidity-sensitive asset. With prices down and the fee rate positive, leveraged longs are not only losing money, but are also paying funding fees on their positions—double-cost compression. After longs get trapped, if they choose to add to thin their cost, it would further increase position size and funding rates, creating a negative feedback loop.
The counterargument is that if the market quickly finishes pricing in political risk and there is no material policy implementation, then the current decline in $NVDL may be seen as oversold, triggering a rebound driven by short covering. After all, a positive funding rate indicates that there is still remaining capital on the long side, and sentiment has not completely collapsed.
But the second-order effects have already taken place. The daily carrying cost of leveraged longs is being eroded by the funding rate. If the price cannot rebound quickly, some accounts will face pressure to add collateral or be forcibly liquidated. Forced liquidation brings additional sell pressure, and liquidity may shift from high-beta products like $NVDL to traditional safe-haven assets such as Treasuries. What is the market missing? It might be overlooking the asymmetric impact of political events on retail leveraged positions. Professional institutions often have hedging tools, while retail positions in $NVDL are more exposed.
My view is that, based on the dual signals of price decline and a positive fee rate, $NVDL in the short term is in a phase where both cost burn and liquidation risk coexist. This is a single-signal judgment that depends on the current funding-rate structure staying in place. If the Bitcoin spot price stabilizes and rebounds from here, and the funding rate quickly falls further or even turns negative, then the current situation of shorts collecting fees would be reversed, and the rebound strength could be quite significant.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this set of judgments is most likely to be wrong?
$NVDL ’s single-day drop of 4.8% has amplified the fragility of Bitcoin spot leveraged products under political narratives. The funding rate of 0.00059787 stays positive; with price falling alongside a positive fee rate, long positions accumulate carrying costs, while shorts collect fees. The position size is 4433.94 units. In a downward price environment, open contracts have not decreased significantly, suggesting longs are holding on rather than exiting with large-scale stop-losses.
Why does politics strike $NVDL at this point? The market is trading one hypothesis: if regulatory policy shifts or fiscal expectations tighten, high-risk, high-leverage exposures like crypto assets would be the first targets to be dumped. As a leveraged product tied to the U.S. stock market, $NVDL ’s volatility directly maps to Bitcoin spot. When political winds change, Bitcoin is often viewed as a liquidity-sensitive asset. With prices down and the fee rate positive, leveraged longs are not only losing money, but are also paying funding fees on their positions—double-cost compression. After longs get trapped, if they choose to add to thin their cost, it would further increase position size and funding rates, creating a negative feedback loop.
The counterargument is that if the market quickly finishes pricing in political risk and there is no material policy implementation, then the current decline in $NVDL may be seen as oversold, triggering a rebound driven by short covering. After all, a positive funding rate indicates that there is still remaining capital on the long side, and sentiment has not completely collapsed.
But the second-order effects have already taken place. The daily carrying cost of leveraged longs is being eroded by the funding rate. If the price cannot rebound quickly, some accounts will face pressure to add collateral or be forcibly liquidated. Forced liquidation brings additional sell pressure, and liquidity may shift from high-beta products like $NVDL to traditional safe-haven assets such as Treasuries. What is the market missing? It might be overlooking the asymmetric impact of political events on retail leveraged positions. Professional institutions often have hedging tools, while retail positions in $NVDL are more exposed.
My view is that, based on the dual signals of price decline and a positive fee rate, $NVDL in the short term is in a phase where both cost burn and liquidation risk coexist. This is a single-signal judgment that depends on the current funding-rate structure staying in place. If the Bitcoin spot price stabilizes and rebounds from here, and the funding rate quickly falls further or even turns negative, then the current situation of shorts collecting fees would be reversed, and the rebound strength could be quite significant.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this set of judgments is most likely to be wrong?
Why does politics strike $NVDL at this point? The market is trading one hypothesis: if regulatory policy shifts or fiscal expectations tighten, high-risk, high-leverage exposures like crypto assets would be the first targets to be dumped. As a leveraged product tied to the U.S. stock market, $NVDL ’s volatility directly maps to Bitcoin spot. When political winds change, Bitcoin is often viewed as a liquidity-sensitive asset. With prices down and the fee rate positive, leveraged longs are not only losing money, but are also paying funding fees on their positions—double-cost compression. After longs get trapped, if they choose to add to thin their cost, it would further increase position size and funding rates, creating a negative feedback loop.
The counterargument is that if the market quickly finishes pricing in political risk and there is no material policy implementation, then the current decline in $NVDL may be seen as oversold, triggering a rebound driven by short covering. After all, a positive funding rate indicates that there is still remaining capital on the long side, and sentiment has not completely collapsed.
But the second-order effects have already taken place. The daily carrying cost of leveraged longs is being eroded by the funding rate. If the price cannot rebound quickly, some accounts will face pressure to add collateral or be forcibly liquidated. Forced liquidation brings additional sell pressure, and liquidity may shift from high-beta products like $NVDL to traditional safe-haven assets such as Treasuries. What is the market missing? It might be overlooking the asymmetric impact of political events on retail leveraged positions. Professional institutions often have hedging tools, while retail positions in $NVDL are more exposed.
My view is that, based on the dual signals of price decline and a positive fee rate, $NVDL in the short term is in a phase where both cost burn and liquidation risk coexist. This is a single-signal judgment that depends on the current funding-rate structure staying in place. If the Bitcoin spot price stabilizes and rebounds from here, and the funding rate quickly falls further or even turns negative, then the current situation of shorts collecting fees would be reversed, and the rebound strength could be quite significant.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this set of judgments is most likely to be wrong?
12
·
--
$NVDL fell 4.8% over the past 24 hours. The drop isn’t huge or trivial, but when you put it in the context of the turbulence surrounding the current U.S. election political cycle, the “flavor” changes. The pullback on tech stocks from political risk is shifting from the narrative level to real-money position adjustments.
Tech stock valuations depend on the discounting of future cash flows. On the numerator, the discount rate is driven by inflation and interest rates; on the denominator, it’s driven by growth expectations. Both of these are now being hijacked by the political agenda. Statements from Biden and Trump—on tech regulation, AI policy, and tariffs on China—have been cycling nonstop. The market hasn’t even had time to digest yesterday’s statements before today brings new uncertainty. In this environment, investors’ tolerance for tech stock valuations is tightening. $NVDL, as a leveraged NVIDIA ETF, is hit first. Its price volatility isn’t just a reflection of NVIDIA’s fundamentals—it’s also the market’s attempt to price in policy risk to the AI industry.
Next, look at the funding rate: 0.00059787, which is positive. That means longs are paying shorts. When the price falls and the funding is positive, you get the most classic setup of longs being trapped and adding to positions. The longs are fighting back, trying to average down costs with more buying, or believing that political noise is only temporary. But the number of open contracts at 4433.94, together with the falling price and positive funding, suggests that the longs’ average cost basis is being passively pushed higher. Every day they hold on, the cost goes up a bit. What about the shorts? They receive the funding rate; with the price falling, they profit and have no urgency to close—so they may instead be looking for fresh entry points.
What is the strongest counterargument? Perhaps the AI technology cycle is long enough to outlast any political cycle. NVIDIA’s earnings growth remains strong. A near-term drop in the stock price could just be emotion-driven noise and doesn’t necessarily mean the industry logic has broken. If next quarter’s earnings report again beats expectations, or if a candidate lays out a clear platform supporting AI development, this political valuation discount could be repaired quickly.
But I believe the market is underestimating the persistence of political maneuvering. This isn’t a one-off shock; it’s noise that runs throughout the entire election year. The second-order effect is that investors who hold leveraged tech ETFs like $NVDL will start to re-evaluate the risk-reward profile of their positions. They may cut part of the leverage, or hedge political risk exposures, and rotate toward assets with higher certainty. Those bearing the cost are traders who stubbornly hold long positions and keep imagining that political risk will instantly dissipate.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
$NVDL fell 4.8% over the past 24 hours. The drop isn’t huge or trivial, but when you put it in the context of the turbulence surrounding the current U.S. election political cycle, the “flavor” changes. The pullback on tech stocks from political risk is shifting from the narrative level to real-money position adjustments.
Tech stock valuations depend on the discounting of future cash flows. On the numerator, the discount rate is driven by inflation and interest rates; on the denominator, it’s driven by growth expectations. Both of these are now being hijacked by the political agenda. Statements from Biden and Trump—on tech regulation, AI policy, and tariffs on China—have been cycling nonstop. The market hasn’t even had time to digest yesterday’s statements before today brings new uncertainty. In this environment, investors’ tolerance for tech stock valuations is tightening. $NVDL , as a leveraged NVIDIA ETF, is hit first. Its price volatility isn’t just a reflection of NVIDIA’s fundamentals—it’s also the market’s attempt to price in policy risk to the AI industry.
Next, look at the funding rate: 0.00059787, which is positive. That means longs are paying shorts. When the price falls and the funding is positive, you get the most classic setup of longs being trapped and adding to positions. The longs are fighting back, trying to average down costs with more buying, or believing that political noise is only temporary. But the number of open contracts at 4433.94, together with the falling price and positive funding, suggests that the longs’ average cost basis is being passively pushed higher. Every day they hold on, the cost goes up a bit. What about the shorts? They receive the funding rate; with the price falling, they profit and have no urgency to close—so they may instead be looking for fresh entry points.
What is the strongest counterargument? Perhaps the AI technology cycle is long enough to outlast any political cycle. NVIDIA’s earnings growth remains strong. A near-term drop in the stock price could just be emotion-driven noise and doesn’t necessarily mean the industry logic has broken. If next quarter’s earnings report again beats expectations, or if a candidate lays out a clear platform supporting AI development, this political valuation discount could be repaired quickly.
But I believe the market is underestimating the persistence of political maneuvering. This isn’t a one-off shock; it’s noise that runs throughout the entire election year. The second-order effect is that investors who hold leveraged tech ETFs like $NVDL will start to re-evaluate the risk-reward profile of their positions. They may cut part of the leverage, or hedge political risk exposures, and rotate toward assets with higher certainty. Those bearing the cost are traders who stubbornly hold long positions and keep imagining that political risk will instantly dissipate.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
Tech stock valuations depend on the discounting of future cash flows. On the numerator, the discount rate is driven by inflation and interest rates; on the denominator, it’s driven by growth expectations. Both of these are now being hijacked by the political agenda. Statements from Biden and Trump—on tech regulation, AI policy, and tariffs on China—have been cycling nonstop. The market hasn’t even had time to digest yesterday’s statements before today brings new uncertainty. In this environment, investors’ tolerance for tech stock valuations is tightening. $NVDL , as a leveraged NVIDIA ETF, is hit first. Its price volatility isn’t just a reflection of NVIDIA’s fundamentals—it’s also the market’s attempt to price in policy risk to the AI industry.
Next, look at the funding rate: 0.00059787, which is positive. That means longs are paying shorts. When the price falls and the funding is positive, you get the most classic setup of longs being trapped and adding to positions. The longs are fighting back, trying to average down costs with more buying, or believing that political noise is only temporary. But the number of open contracts at 4433.94, together with the falling price and positive funding, suggests that the longs’ average cost basis is being passively pushed higher. Every day they hold on, the cost goes up a bit. What about the shorts? They receive the funding rate; with the price falling, they profit and have no urgency to close—so they may instead be looking for fresh entry points.
What is the strongest counterargument? Perhaps the AI technology cycle is long enough to outlast any political cycle. NVIDIA’s earnings growth remains strong. A near-term drop in the stock price could just be emotion-driven noise and doesn’t necessarily mean the industry logic has broken. If next quarter’s earnings report again beats expectations, or if a candidate lays out a clear platform supporting AI development, this political valuation discount could be repaired quickly.
But I believe the market is underestimating the persistence of political maneuvering. This isn’t a one-off shock; it’s noise that runs throughout the entire election year. The second-order effect is that investors who hold leveraged tech ETFs like $NVDL will start to re-evaluate the risk-reward profile of their positions. They may cut part of the leverage, or hedge political risk exposures, and rotate toward assets with higher certainty. Those bearing the cost are traders who stubbornly hold long positions and keep imagining that political risk will instantly dissipate.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
9
·
--
$NVDL 24 hours down 5.035% to 36.4; the funding rate is 0.00189 and is positive. Expectations of tighter political regulation have suppressed leveraged products. Longs have gotten trapped and increased positions, causing the funding rate to be positive while the price falls; the carry/holding risk is heavy. The strongest counter-evidence is that a shift toward easing policy could trigger short-covering. If long liquidations worsen, OI declining will drag the price down. This thesis is invalid if the funding rate turns negative or if the price rebounds to 37. Try a small long position, and keep the stop-loss very tight.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this set of judgments is most likely to be wrong?
$NVDL 24 hours down 5.035% to 36.4; the funding rate is 0.00189 and is positive. Expectations of tighter political regulation have suppressed leveraged products. Longs have gotten trapped and increased positions, causing the funding rate to be positive while the price falls; the carry/holding risk is heavy. The strongest counter-evidence is that a shift toward easing policy could trigger short-covering. If long liquidations worsen, OI declining will drag the price down. This thesis is invalid if the funding rate turns negative or if the price rebounds to 37. Try a small long position, and keep the stop-loss very tight.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this set of judgments is most likely to be wrong?
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this set of judgments is most likely to be wrong?
32
·
--
$NVDL 24 hours falls 5.035% to 36.4; the funding rate is 0.00188979 and stays positive. Political uncertainty suppresses risk appetite for U.S. equities; funds exit growth stocks, and long positions are trapped at rising average costs. Price declines combined with a positive funding rate build liquidation risk below. If the election stalemate drags on or regulatory policies tighten, $NVDL may test the 35 support. I choose to wait and see: cut exposure if it breaks below 35, and consider going long again only if it breaks above 38.
Trading label: #TradFi #链上美股 #NVDL
Where do you think this judgment is most likely to be wrong?
$NVDL 24 hours falls 5.035% to 36.4; the funding rate is 0.00188979 and stays positive. Political uncertainty suppresses risk appetite for U.S. equities; funds exit growth stocks, and long positions are trapped at rising average costs. Price declines combined with a positive funding rate build liquidation risk below. If the election stalemate drags on or regulatory policies tighten, $NVDL may test the 35 support. I choose to wait and see: cut exposure if it breaks below 35, and consider going long again only if it breaks above 38.
Trading label: #TradFi #链上美股 #NVDL
Where do you think this judgment is most likely to be wrong?
Trading label: #TradFi #链上美股 #NVDL
Where do you think this judgment is most likely to be wrong?
7
·
--
$NVDL leveraged ETF, down 5.04% in 24 hours, while the funding rate remains positive at 0.0019. The longs are clinging to the positive funding rate amid the selloff—this is a typical high-cost positioning structure. Any short-term rebound is likely to be knocked down by sell-off positioning.
As a technology leader, Nvidia’s leveraged products are extremely sensitive to shifts in political sentiment. Any changes in expectations around chip export controls or industrial subsidy policies will be amplified several times on the leveraged side. With the price falling and the funding rate still positive, it suggests the market’s pricing of policy uncertainty is starting to show up, but it hasn’t reached the panic-liquidation stage yet.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this thesis is most likely to be wrong?
$NVDL leveraged ETF, down 5.04% in 24 hours, while the funding rate remains positive at 0.0019. The longs are clinging to the positive funding rate amid the selloff—this is a typical high-cost positioning structure. Any short-term rebound is likely to be knocked down by sell-off positioning.
As a technology leader, Nvidia’s leveraged products are extremely sensitive to shifts in political sentiment. Any changes in expectations around chip export controls or industrial subsidy policies will be amplified several times on the leveraged side. With the price falling and the funding rate still positive, it suggests the market’s pricing of policy uncertainty is starting to show up, but it hasn’t reached the panic-liquidation stage yet.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this thesis is most likely to be wrong?
As a technology leader, Nvidia’s leveraged products are extremely sensitive to shifts in political sentiment. Any changes in expectations around chip export controls or industrial subsidy policies will be amplified several times on the leveraged side. With the price falling and the funding rate still positive, it suggests the market’s pricing of policy uncertainty is starting to show up, but it hasn’t reached the panic-liquidation stage yet.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this thesis is most likely to be wrong?
29

·
--
$NVDL fell 4.668%, quoted at 36.35, with a 24h funding rate of 0.00140215。
Amid the downtrend, the funding rate remains positive. This is a single-signal indicator: it points to longs still adding or stubbornly holding within the trapped area, without actively reducing positions. If macro risk appetite continues to contract, this structure is prone to amplify downside fragility。
The strongest counter-evidence is when price quickly rebounds so that the funding rate turns negative, forcing shorts to exit. Current position: 4983.72. If the price does not effectively move above the recent intraday high, leverage long costs will accumulate. Action: wait and watch。
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this analysis is most likely to be wrong?
$NVDL fell 4.668%, quoted at 36.35, with a 24h funding rate of 0.00140215。
Amid the downtrend, the funding rate remains positive. This is a single-signal indicator: it points to longs still adding or stubbornly holding within the trapped area, without actively reducing positions. If macro risk appetite continues to contract, this structure is prone to amplify downside fragility。
The strongest counter-evidence is when price quickly rebounds so that the funding rate turns negative, forcing shorts to exit. Current position: 4983.72. If the price does not effectively move above the recent intraday high, leverage long costs will accumulate. Action: wait and watch。
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this analysis is most likely to be wrong?
Amid the downtrend, the funding rate remains positive. This is a single-signal indicator: it points to longs still adding or stubbornly holding within the trapped area, without actively reducing positions. If macro risk appetite continues to contract, this structure is prone to amplify downside fragility。
The strongest counter-evidence is when price quickly rebounds so that the funding rate turns negative, forcing shorts to exit. Current position: 4983.72. If the price does not effectively move above the recent intraday high, leverage long costs will accumulate. Action: wait and watch。
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this analysis is most likely to be wrong?
42
·
--
$NVDL fell 4.67% over the past 24 hours, while the funding rate remained at a positive rate of 0.0014. This is a combination of a price decline and ongoing payments from long positions.
Looking at these two signals alone, my view is that short-term price pressure is still present. Even during negative price movements, longs are still charged the funding rate, creating a double cost: unrealized position losses plus a continuous cash-flow expenditure. This is one of the typical structures of longs getting trapped and averaging up, where liquidity is consumed by this negative feedback loop.
The counter-evidence lies in changes in the position size.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
$NVDL fell 4.67% over the past 24 hours, while the funding rate remained at a positive rate of 0.0014. This is a combination of a price decline and ongoing payments from long positions.
Looking at these two signals alone, my view is that short-term price pressure is still present. Even during negative price movements, longs are still charged the funding rate, creating a double cost: unrealized position losses plus a continuous cash-flow expenditure. This is one of the typical structures of longs getting trapped and averaging up, where liquidity is consumed by this negative feedback loop.
The counter-evidence lies in changes in the position size.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
Looking at these two signals alone, my view is that short-term price pressure is still present. Even during negative price movements, longs are still charged the funding rate, creating a double cost: unrealized position losses plus a continuous cash-flow expenditure. This is one of the typical structures of longs getting trapped and averaging up, where liquidity is consumed by this negative feedback loop.
The counter-evidence lies in changes in the position size.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
19
·
--
$NVDL rose 36.35, 24-hour drop 4.67%, while the funding rate remained positive at 0.0014 during the same period. Price declines coexist with a positive funding rate—this is a typical long-side trapped structure, where the cost basis is passively averaged higher.
I tend to think this is longs stubbornly resisting. A positive funding rate means longs continue paying funding fees to shorts; in a backdrop of falling price, this fee will accelerate the consumption of longs’ margin.
Trade tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
$NVDL rose 36.35, 24-hour drop 4.67%, while the funding rate remained positive at 0.0014 during the same period. Price declines coexist with a positive funding rate—this is a typical long-side trapped structure, where the cost basis is passively averaged higher.
I tend to think this is longs stubbornly resisting. A positive funding rate means longs continue paying funding fees to shorts; in a backdrop of falling price, this fee will accelerate the consumption of longs’ margin.
Trade tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
I tend to think this is longs stubbornly resisting. A positive funding rate means longs continue paying funding fees to shorts; in a backdrop of falling price, this fee will accelerate the consumption of longs’ margin.
Trade tag: #TradFi #链上美股 #NVDL
Where do you think this assessment is most likely to be wrong?
10
·
--
Over the past 24 hours, $NVDL 24 has fallen 4.668%, with a quote of 36.35. Yet the funding rate remains positive at 0.00140215. This combination points to a trapped long structure: price is declining, but longs are still paying to hold positions, and financing costs continue to accumulate.
With no external macro variables providing additional support, purely from the on-chain structure, this divergence between price and funding rate increases the likelihood of forced long liquidations. A positive funding rate during a decline is like a slow, grinding cut; if positions are too large, they may be worn down by interest first. If U.S. tech stocks release more negative news, the drop could accelerate.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this analysis is most likely wrong?
Over the past 24 hours, $NVDL 24 has fallen 4.668%, with a quote of 36.35. Yet the funding rate remains positive at 0.00140215. This combination points to a trapped long structure: price is declining, but longs are still paying to hold positions, and financing costs continue to accumulate.
With no external macro variables providing additional support, purely from the on-chain structure, this divergence between price and funding rate increases the likelihood of forced long liquidations. A positive funding rate during a decline is like a slow, grinding cut; if positions are too large, they may be worn down by interest first. If U.S. tech stocks release more negative news, the drop could accelerate.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this analysis is most likely wrong?
With no external macro variables providing additional support, purely from the on-chain structure, this divergence between price and funding rate increases the likelihood of forced long liquidations. A positive funding rate during a decline is like a slow, grinding cut; if positions are too large, they may be worn down by interest first. If U.S. tech stocks release more negative news, the drop could accelerate.
Trading tag: #TradFi #链上美股 #NVDL
Where do you think this analysis is most likely wrong?
11
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BinanceWillListHyperliquid(HYPE)
40,643 views
1,057 Discussing
2
#FedOctoberRateHikeOddsRiseTo69.7%
3,227 views
235 Discussing
3
#BitcoinFallsBelow$83,000
1,726 views
20 Discussing
4
#BitcoinFallsToAround$84,600ThisWeek
0 views
0 Discussing
5
#US30YearYieldHighestSince2004
8,555 views
261 Discussing
6
#ETHBreaksAbove$2,700
905 views
20 Discussing
7
#USWeighsPromotingDollarStablecoinsAbroad
35,728 views
1,101 Discussing
8
#US10YTreasuryYieldHits19YearHigh
34,997 views
845 Discussing
9
#SpotBitcoinETFsInflow$2.31BInFourDays
4,673 views
60 Discussing
10
#BitcoinRejectedAt$87,300Twice
0 views
0 Discussing