
#termmax
termmax
2.1M views
58,852 Discussing
Hot
Latest

·
--
🦈 WHO TRULY DICTATES DEFI YIELDS? INSIDE THE BOUNDARY MECHANICS OF $TERMMAX 💡
Fixed-rate protocols aren't just battling for pure liquidity anymore — they are fighting over precision pricing. 🔍 $TERMMAX shifts the game by relying on curators to set specific APR ranges, which the AMM then maps into dynamic pricing curves for borrowers and lenders. 🌊
📌 But here is the quiet leverage point: set those parameters too wide and execution becomes inefficient; set them too tight and sudden volatility breaks the range. Predictable yield isn't just about total capital trapped — it comes down to who controls the boundaries where that capital lives. 💡
🤔 Do you prefer algorithmic rate curves or curated yield boundaries when locking in your fixed rates? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #TERMMAX #DeFi #FixedRates #Yield #Crypto
💡 🦈
🦈 WHO TRULY DICTATES DEFI YIELDS? INSIDE THE BOUNDARY MECHANICS OF $TERMMAX 💡
Fixed-rate protocols aren't just battling for pure liquidity anymore — they are fighting over precision pricing. 🔍 $TERMMAX shifts the game by relying on curators to set specific APR ranges, which the AMM then maps into dynamic pricing curves for borrowers and lenders. 🌊
📌 But here is the quiet leverage point: set those parameters too wide and execution becomes inefficient; set them too tight and sudden volatility breaks the range. Predictable yield isn't just about total capital trapped — it comes down to who controls the boundaries where that capital lives. 💡
🤔 Do you prefer algorithmic rate curves or curated yield boundaries when locking in your fixed rates? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #TERMMAX #DeFi #FixedRates #Yield #Crypto
💡 🦈
Fixed-rate protocols aren't just battling for pure liquidity anymore — they are fighting over precision pricing. 🔍 $TERMMAX shifts the game by relying on curators to set specific APR ranges, which the AMM then maps into dynamic pricing curves for borrowers and lenders. 🌊
📌 But here is the quiet leverage point: set those parameters too wide and execution becomes inefficient; set them too tight and sudden volatility breaks the range. Predictable yield isn't just about total capital trapped — it comes down to who controls the boundaries where that capital lives. 💡
🤔 Do you prefer algorithmic rate curves or curated yield boundaries when locking in your fixed rates? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #TERMMAX #DeFi #FixedRates #Yield #Crypto
💡 🦈
3

·
--
🚨 URGENT REWARD CLAIM WINDOW OPEN FOR $TERMMAX CREATORPAD WINNERS! 💥
If you snagged allocations in the $TERMMAX CreatorPad campaign, the clock is ticking to secure your yield. 🔒 Head straight into the booster portal and verify your completed tasks immediately before the snapshot locks you out of your tokens.
We successfully swept both the global Booster Pool and landed a comfortable top #7 spot on the CreatorPad leaderboard. 📊 Smart participants know that leaving unclaimed allocations on the table is just handing free value back to the pool.
💬 Did you lock in your CreatorPad allocation in time, or did you let the verification window slip past? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #TERMMAX #CreatorPad #Airdrop #Crypto #Web3
🔥 💎
🚨 URGENT REWARD CLAIM WINDOW OPEN FOR $TERMMAX CREATORPAD WINNERS! 💥
If you snagged allocations in the $TERMMAX CreatorPad campaign, the clock is ticking to secure your yield. 🔒 Head straight into the booster portal and verify your completed tasks immediately before the snapshot locks you out of your tokens.
We successfully swept both the global Booster Pool and landed a comfortable top #7 spot on the CreatorPad leaderboard. 📊 Smart participants know that leaving unclaimed allocations on the table is just handing free value back to the pool.
💬 Did you lock in your CreatorPad allocation in time, or did you let the verification window slip past? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #TERMMAX #CreatorPad #Airdrop #Crypto #Web3
🔥 💎
If you snagged allocations in the $TERMMAX CreatorPad campaign, the clock is ticking to secure your yield. 🔒 Head straight into the booster portal and verify your completed tasks immediately before the snapshot locks you out of your tokens.
We successfully swept both the global Booster Pool and landed a comfortable top #7 spot on the CreatorPad leaderboard. 📊 Smart participants know that leaving unclaimed allocations on the table is just handing free value back to the pool.
💬 Did you lock in your CreatorPad allocation in time, or did you let the verification window slip past? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #TERMMAX #CreatorPad #Airdrop #Crypto #Web3
🔥 💎
1
·
--
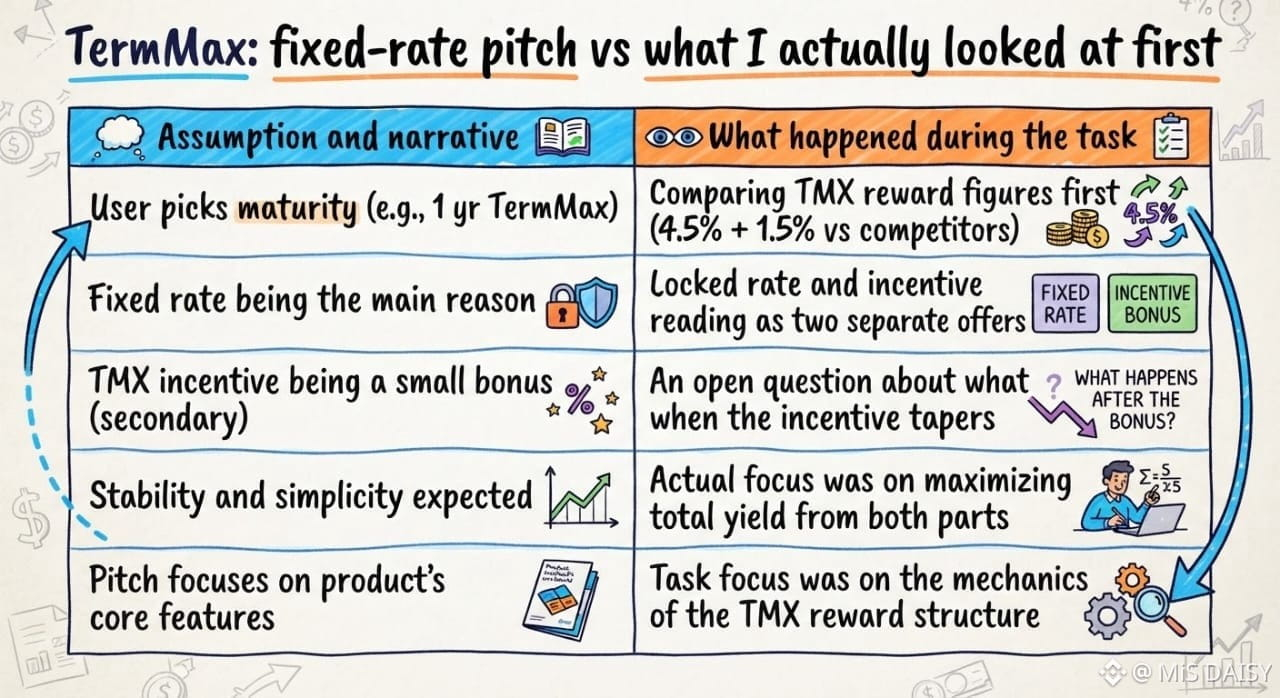
What made me pause in TermMax was how quickly my attention slid past the fixed rate and toward the number sitting beside it. The product is built on a quiet idea: pick a maturity, lock a rate, know exactly what you owe or earn. That is different from floating-rate pools where yields drift by the hour. But while moving through the task with @termmax _ts, the rate I could actually lock and the incentive layered on top of it read like two separate offers, and the second one was louder. If $TMX rewards are what make a given maturity look worth choosing, the fixed rate becomes a floor under the decision rather than the reason for it. I caught myself comparing reward figures before I compared terms, which is the opposite of the habit a fixed-rate product seems designed to build. I keep wondering what a user does once the incentive tapers and only the plain locked rate remains. Maybe demand for certainty is real but slow, and the rewards are just what keeps people in the room long enough to notice it. Or maybe they are what the room is made of. #TermMax
What made me pause in TermMax was how quickly my attention slid past the fixed rate and toward the number sitting beside it. The product is built on a quiet idea: pick a maturity, lock a rate, know exactly what you owe or earn. That is different from floating-rate pools where yields drift by the hour. But while moving through the task with @TermMax _ts, the rate I could actually lock and the incentive layered on top of it read like two separate offers, and the second one was louder. If $TMX rewards are what make a given maturity look worth choosing, the fixed rate becomes a floor under the decision rather than the reason for it. I caught myself comparing reward figures before I compared terms, which is the opposite of the habit a fixed-rate product seems designed to build. I keep wondering what a user does once the incentive tapers and only the plain locked rate remains. Maybe demand for certainty is real but slow, and the rewards are just what keeps people in the room long enough to notice it. Or maybe they are what the room is made of. #TermMax
1
852

·
--
🔍 TMX: Undervalued Opportunity or a High-Risk Recovery Play?
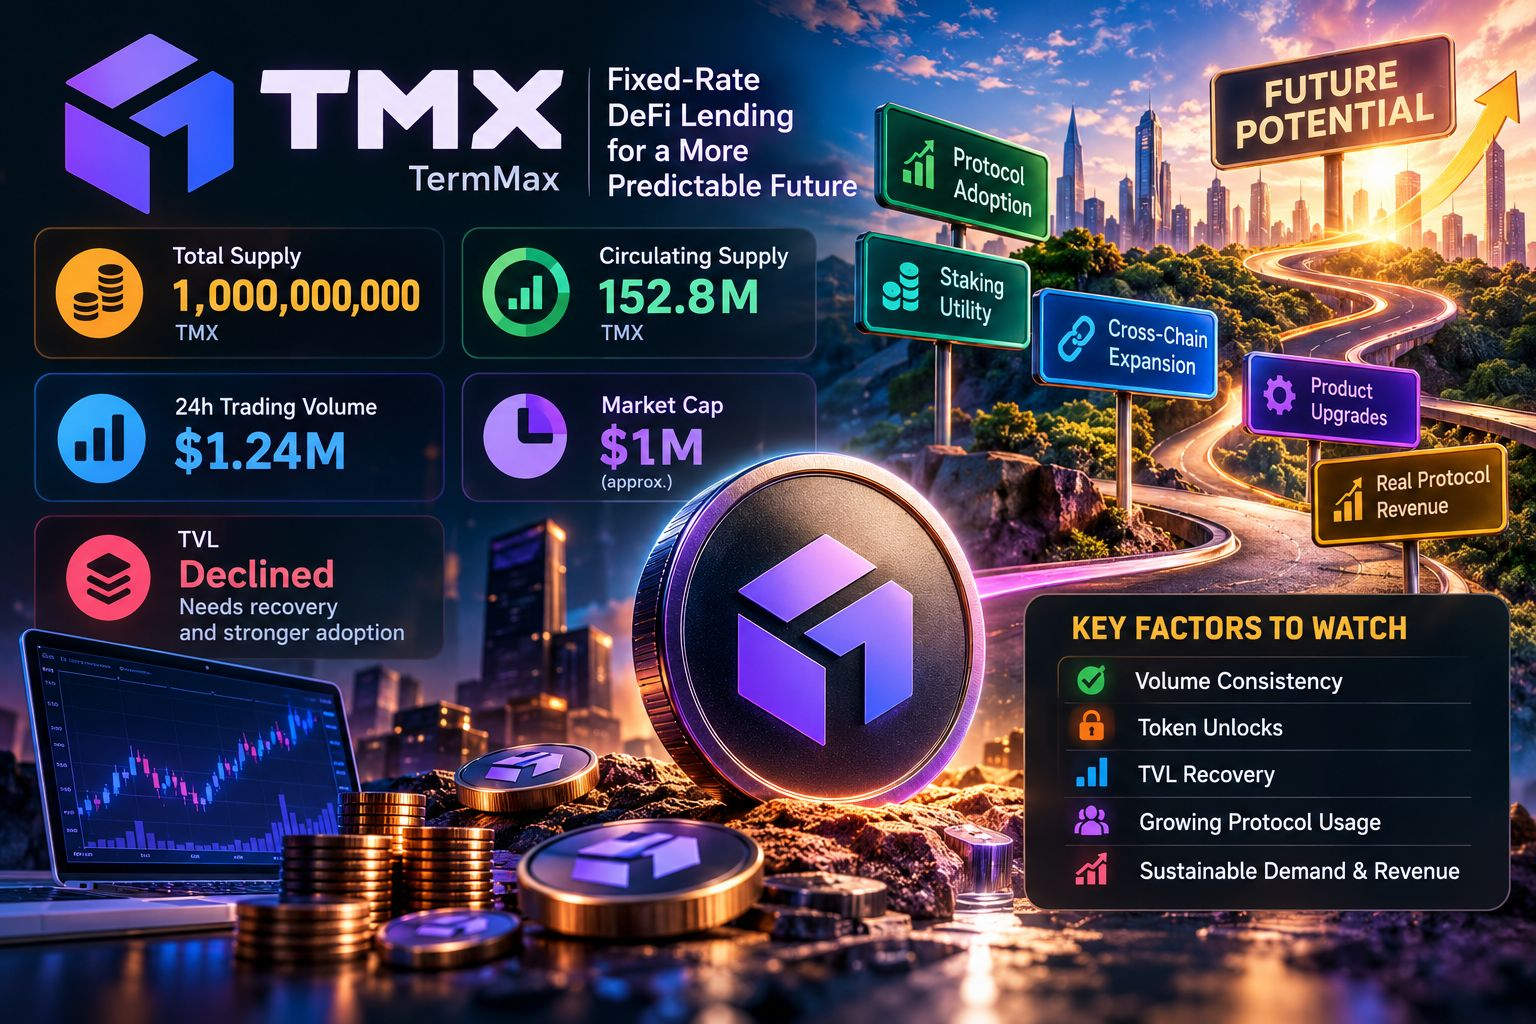
TMX has a fixed maximum supply of 1 billion tokens, with around 152.8 million currently circulating. Its reported 24-hour trading volume is approximately $1.24M, while its market cap is near $1M. However, TermMax’s TVL has dropped sharply, making protocol adoption a key metric to watch.
The long-term outlook depends on whether fixed-rate DeFi lending, staking utility, cross-chain expansion and upcoming product upgrades can attract sustainable demand. A low valuation alone does not guarantee recovery. I’ll be watching volume consistency, token unlocks, TVL recovery and real protocol revenue before drawing stronger conclusions.
Can TMX rebuild momentum through actual usage?
$ZEC
{future}(ZECUSDT)
$DASH
{future}(DASHUSDT)
$TMX
{alpha}(560x3c2f61f2e27c865981d2e7aaf6b2cdf823030039)
#TermMax
🔍 TMX: Undervalued Opportunity or a High-Risk Recovery Play?
TMX has a fixed maximum supply of 1 billion tokens, with around 152.8 million currently circulating. Its reported 24-hour trading volume is approximately $1.24M, while its market cap is near $1M. However, TermMax’s TVL has dropped sharply, making protocol adoption a key metric to watch.
The long-term outlook depends on whether fixed-rate DeFi lending, staking utility, cross-chain expansion and upcoming product upgrades can attract sustainable demand. A low valuation alone does not guarantee recovery. I’ll be watching volume consistency, token unlocks, TVL recovery and real protocol revenue before drawing stronger conclusions.
Can TMX rebuild momentum through actual usage?
$ZEC
$DASH
$TMX
#TermMax
TMX has a fixed maximum supply of 1 billion tokens, with around 152.8 million currently circulating. Its reported 24-hour trading volume is approximately $1.24M, while its market cap is near $1M. However, TermMax’s TVL has dropped sharply, making protocol adoption a key metric to watch.
The long-term outlook depends on whether fixed-rate DeFi lending, staking utility, cross-chain expansion and upcoming product upgrades can attract sustainable demand. A low valuation alone does not guarantee recovery. I’ll be watching volume consistency, token unlocks, TVL recovery and real protocol revenue before drawing stronger conclusions.
Can TMX rebuild momentum through actual usage?
$ZEC
$DASH
$TMX
#TermMax
5
2k
·
--
Let me put the conclusion first: I’m putting $TMX on my watchlist for now. The token concentration is making me seriously uneasy. 🤔
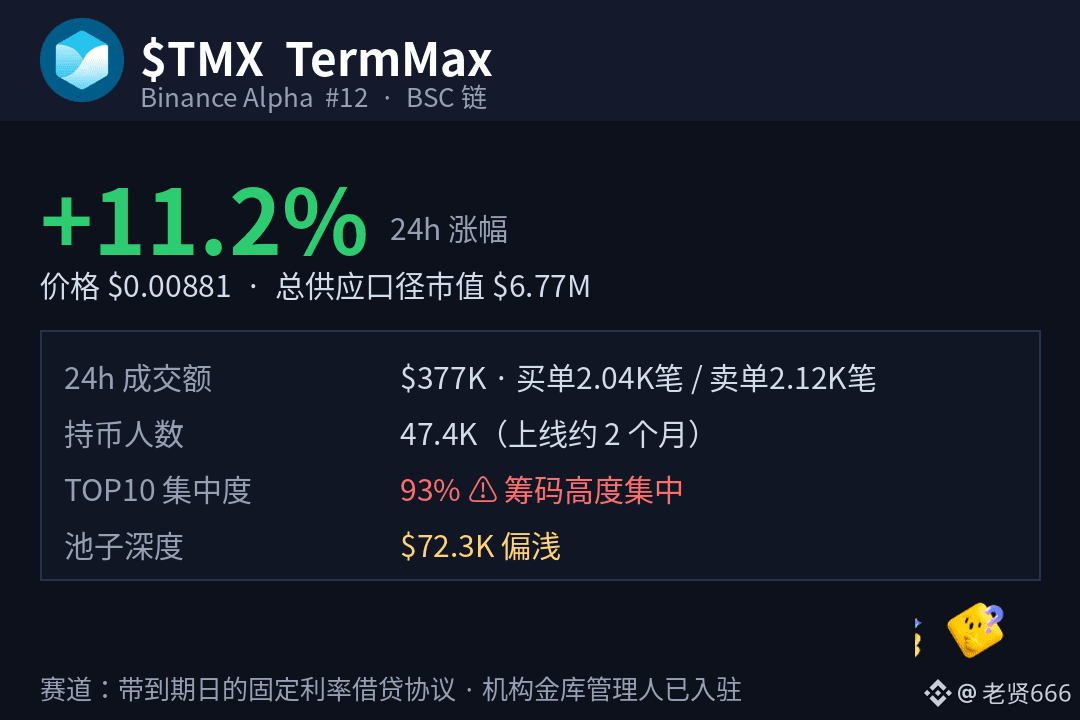
Today I went through all 280 coins on the Alpha leaderboard. TMX (TermMax) ranked 12th, up 11.2% over 24 hours, at $0.00881. What’s interesting is that it launched only two months ago, yet it already has 47,000 holders—that’s fast growth, even by Alpha standards.
On-chain, it saw $377,000 in trading volume over the past 24 hours, with 2.04K buy orders and 2.12K sell orders. Buyers and sellers are pretty evenly matched, and the activity is genuine—not just a few addresses trading back and forth. 👀
But there’s another side to the story: the top 10 wallets hold 93% of the tokens, and the liquidity pool has only a little over $70,000 in it. That’s shallow. It’s a classic case of lots of people, not much supply, and a few holders controlling most of the tokens—a small boat that gets tossed around when the waves pick up.
What does it do? It’s a fixed-rate lending protocol with set maturity dates. When you deposit, the rate and term are locked in, so neither borrowers nor lenders have to guess where floating rates will go. Its website, ts.finance, is live, and it’s already operating across several chains, including Ethereum, Arbitrum, and BNB Chain. Institutions like MEV Capital and Keyrock are also managing vaults on the platform, so there’s some substance behind it.
Verdict: Watch. Here’s what would change my mind—if token concentration stays this high and trading volume dries up, I’ll take it off the list. If ownership becomes more distributed and the liquidity pool deepens, I’ll upgrade it to active tracking.
This isn’t investment advice. Coins in the Alpha sector can drop without making a sound. Follow me, and I’ll see you in tomorrow’s ledger. 📒
#BinanceAlpha #TermMax #DeFi
Let me put the conclusion first: I’m putting $TMX on my watchlist for now. The token concentration is making me seriously uneasy. 🤔
Today I went through all 280 coins on the Alpha leaderboard. TMX (TermMax) ranked 12th, up 11.2% over 24 hours, at $0.00881. What’s interesting is that it launched only two months ago, yet it already has 47,000 holders—that’s fast growth, even by Alpha standards.
On-chain, it saw $377,000 in trading volume over the past 24 hours, with 2.04K buy orders and 2.12K sell orders. Buyers and sellers are pretty evenly matched, and the activity is genuine—not just a few addresses trading back and forth. 👀
But there’s another side to the story: the top 10 wallets hold 93% of the tokens, and the liquidity pool has only a little over $70,000 in it. That’s shallow. It’s a classic case of lots of people, not much supply, and a few holders controlling most of the tokens—a small boat that gets tossed around when the waves pick up.
What does it do? It’s a fixed-rate lending protocol with set maturity dates. When you deposit, the rate and term are locked in, so neither borrowers nor lenders have to guess where floating rates will go. Its website, ts.finance, is live, and it’s already operating across several chains, including Ethereum, Arbitrum, and BNB Chain. Institutions like MEV Capital and Keyrock are also managing vaults on the platform, so there’s some substance behind it.
Verdict: Watch. Here’s what would change my mind—if token concentration stays this high and trading volume dries up, I’ll take it off the list. If ownership becomes more distributed and the liquidity pool deepens, I’ll upgrade it to active tracking.
This isn’t investment advice. Coins in the Alpha sector can drop without making a sound. Follow me, and I’ll see you in tomorrow’s ledger. 📒
#BinanceAlpha #TermMax #DeFi
Today I went through all 280 coins on the Alpha leaderboard. TMX (TermMax) ranked 12th, up 11.2% over 24 hours, at $0.00881. What’s interesting is that it launched only two months ago, yet it already has 47,000 holders—that’s fast growth, even by Alpha standards.
On-chain, it saw $377,000 in trading volume over the past 24 hours, with 2.04K buy orders and 2.12K sell orders. Buyers and sellers are pretty evenly matched, and the activity is genuine—not just a few addresses trading back and forth. 👀
But there’s another side to the story: the top 10 wallets hold 93% of the tokens, and the liquidity pool has only a little over $70,000 in it. That’s shallow. It’s a classic case of lots of people, not much supply, and a few holders controlling most of the tokens—a small boat that gets tossed around when the waves pick up.
What does it do? It’s a fixed-rate lending protocol with set maturity dates. When you deposit, the rate and term are locked in, so neither borrowers nor lenders have to guess where floating rates will go. Its website, ts.finance, is live, and it’s already operating across several chains, including Ethereum, Arbitrum, and BNB Chain. Institutions like MEV Capital and Keyrock are also managing vaults on the platform, so there’s some substance behind it.
Verdict: Watch. Here’s what would change my mind—if token concentration stays this high and trading volume dries up, I’ll take it off the list. If ownership becomes more distributed and the liquidity pool deepens, I’ll upgrade it to active tracking.
This isn’t investment advice. Coins in the Alpha sector can drop without making a sound. Follow me, and I’ll see you in tomorrow’s ledger. 📒
#BinanceAlpha #TermMax #DeFi
592

🚨 $TERMMAX PROVES FIXED-RATE DEFI IS SHIFTING FROM ORDERBOOKS TO AMM LIQUIDITY POOLS! 🏦
Orderbook architecture offers exact rate matching, but liquidity fragmentation across fixed maturities cripples execution speed. 🏦 $TERMMAX transitioning toward custom-curve AMMs trades marginal pricing precision for continuous pool depth, allowing smart money to enter and exit positions instantly without waiting for counterparty matching.
This structural evolution mirrors early spot market expansion, proving that automated pooled liquidity is essential for fixed-income scaling. 💡 Shared liquidity architecture solves the friction of illiquid maturities, unlocking true institutional throughput for non-standard assets.
💬 Do you prioritize absolute rate precision or instant execution liquidity when locking fixed yields? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #TERMMAX #FixedRate #DeFi #Yield #Crypto
🎯 🦈
🚨 $TERMMAX PROVES FIXED-RATE DEFI IS SHIFTING FROM ORDERBOOKS TO AMM LIQUIDITY POOLS! 🏦
Orderbook architecture offers exact rate matching, but liquidity fragmentation across fixed maturities cripples execution speed. 🏦 $TERMMAX transitioning toward custom-curve AMMs trades marginal pricing precision for continuous pool depth, allowing smart money to enter and exit positions instantly without waiting for counterparty matching.
This structural evolution mirrors early spot market expansion, proving that automated pooled liquidity is essential for fixed-income scaling. 💡 Shared liquidity architecture solves the friction of illiquid maturities, unlocking true institutional throughput for non-standard assets.
💬 Do you prioritize absolute rate precision or instant execution liquidity when locking fixed yields? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #TERMMAX #FixedRate #DeFi #Yield #Crypto
🎯 🦈
Orderbook architecture offers exact rate matching, but liquidity fragmentation across fixed maturities cripples execution speed. 🏦 $TERMMAX transitioning toward custom-curve AMMs trades marginal pricing precision for continuous pool depth, allowing smart money to enter and exit positions instantly without waiting for counterparty matching.
This structural evolution mirrors early spot market expansion, proving that automated pooled liquidity is essential for fixed-income scaling. 💡 Shared liquidity architecture solves the friction of illiquid maturities, unlocking true institutional throughput for non-standard assets.
💬 Do you prioritize absolute rate precision or instant execution liquidity when locking fixed yields? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #TERMMAX #FixedRate #DeFi #Yield #Crypto
🎯 🦈
38

·
--
IS $TERMMAX SOLVING REAL DEFI DEMAND OR JUST MARKET COORDINATION? 🚨 📊
Smart money capital allocation in $TERMMAX reveals a fundamental institutional dilemma between predictable debt yield and pure execution flexibility. 🌊 While locking term rates solves structure coordination, high-volatility regimes historically favor immediate liquidity over fixed maturity schedules.
Institutional desks requiring cash flow precision and cost-locked arbitrage will treat fixed rates as a necessity. 💡 However, retail liquidity still votes with its feet, prioritizing rapid position rotation when market structure shifts unexpectedly.
Determining long-term protocol momentum comes down to real institutional adoption versus superficial rate tables. 💬 In high-volatility conditions, do you prioritize locking in structural certainty or preserving emergency exit flexibility? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #TERMMAX #DeFi #Yield #MarketStructure #Crypto
🔥 💎
IS $TERMMAX SOLVING REAL DEFI DEMAND OR JUST MARKET COORDINATION? 🚨 📊
Smart money capital allocation in $TERMMAX reveals a fundamental institutional dilemma between predictable debt yield and pure execution flexibility. 🌊 While locking term rates solves structure coordination, high-volatility regimes historically favor immediate liquidity over fixed maturity schedules.
Institutional desks requiring cash flow precision and cost-locked arbitrage will treat fixed rates as a necessity. 💡 However, retail liquidity still votes with its feet, prioritizing rapid position rotation when market structure shifts unexpectedly.
Determining long-term protocol momentum comes down to real institutional adoption versus superficial rate tables. 💬 In high-volatility conditions, do you prioritize locking in structural certainty or preserving emergency exit flexibility? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #TERMMAX #DeFi #Yield #MarketStructure #Crypto
🔥 💎
Smart money capital allocation in $TERMMAX reveals a fundamental institutional dilemma between predictable debt yield and pure execution flexibility. 🌊 While locking term rates solves structure coordination, high-volatility regimes historically favor immediate liquidity over fixed maturity schedules.
Institutional desks requiring cash flow precision and cost-locked arbitrage will treat fixed rates as a necessity. 💡 However, retail liquidity still votes with its feet, prioritizing rapid position rotation when market structure shifts unexpectedly.
Determining long-term protocol momentum comes down to real institutional adoption versus superficial rate tables. 💬 In high-volatility conditions, do you prioritize locking in structural certainty or preserving emergency exit flexibility? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #TERMMAX #DeFi #Yield #MarketStructure #Crypto
🔥 💎
39

·
--
🚨 $TERMMAX REVOLUTIONIZES RWA LIQUIDITY WITH INSTITUTIONAL PHYSICAL DELIVERY MECHANICS! 🦈
Bringing real-world assets on-chain means little if secondary market liquidity collapses under stress. 🦈 Institutional capital requires structural safety, which is why $TERMMAX is shifting the paradigm by replacing market liquidations with physical asset delivery directly to lenders.
📌 This eliminates order book slippage and preserves capital efficiency during high volatility, unlike traditional forced liquidations seen in $BTC or $ETH pools. Fixed-rate lending backed by direct settlement provides the structural clarity smart money demands before scaling size. 📊
💬 Will physical settlement mechanisms become the mandatory baseline for institutional RWA protocols? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #TERMMAX #RWA #DeFi #SmartMoney #Crypto
🎯 🦈
🚨 $TERMMAX REVOLUTIONIZES RWA LIQUIDITY WITH INSTITUTIONAL PHYSICAL DELIVERY MECHANICS! 🦈
Bringing real-world assets on-chain means little if secondary market liquidity collapses under stress. 🦈 Institutional capital requires structural safety, which is why $TERMMAX is shifting the paradigm by replacing market liquidations with physical asset delivery directly to lenders.
📌 This eliminates order book slippage and preserves capital efficiency during high volatility, unlike traditional forced liquidations seen in $BTC or $ETH pools. Fixed-rate lending backed by direct settlement provides the structural clarity smart money demands before scaling size. 📊
💬 Will physical settlement mechanisms become the mandatory baseline for institutional RWA protocols? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #TERMMAX #RWA #DeFi #SmartMoney #Crypto
🎯 🦈
Bringing real-world assets on-chain means little if secondary market liquidity collapses under stress. 🦈 Institutional capital requires structural safety, which is why $TERMMAX is shifting the paradigm by replacing market liquidations with physical asset delivery directly to lenders.
📌 This eliminates order book slippage and preserves capital efficiency during high volatility, unlike traditional forced liquidations seen in $BTC or $ETH pools. Fixed-rate lending backed by direct settlement provides the structural clarity smart money demands before scaling size. 📊
💬 Will physical settlement mechanisms become the mandatory baseline for institutional RWA protocols? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #TERMMAX #RWA #DeFi #SmartMoney #Crypto
🎯 🦈
75

·
--
Bullish
Exactly! 🔥 The real value of fixed-rate DeFi isn’t just the yield—it’s the predictability. Knowing your rate and maturity upfront makes strategy planning much easier.
TermMax is taking an interesting approach here. The next big thing to watch is whether real demand and liquidity can scale alongside the product. 👀📊
#TermMax #TermMaxBooster #TMX #DeFi #Web3 #Crypto #BinanceSquare
Exactly! 🔥 The real value of fixed-rate DeFi isn’t just the yield—it’s the predictability. Knowing your rate and maturity upfront makes strategy planning much easier.
TermMax is taking an interesting approach here. The next big thing to watch is whether real demand and liquidity can scale alongside the product. 👀📊
#TermMax #TermMaxBooster #TMX #DeFi #Web3 #Crypto #BinanceSquare
TermMax is taking an interesting approach here. The next big thing to watch is whether real demand and liquidity can scale alongside the product. 👀📊
#TermMax #TermMaxBooster #TMX #DeFi #Web3 #Crypto #BinanceSquare
Boosttrade__
·
--
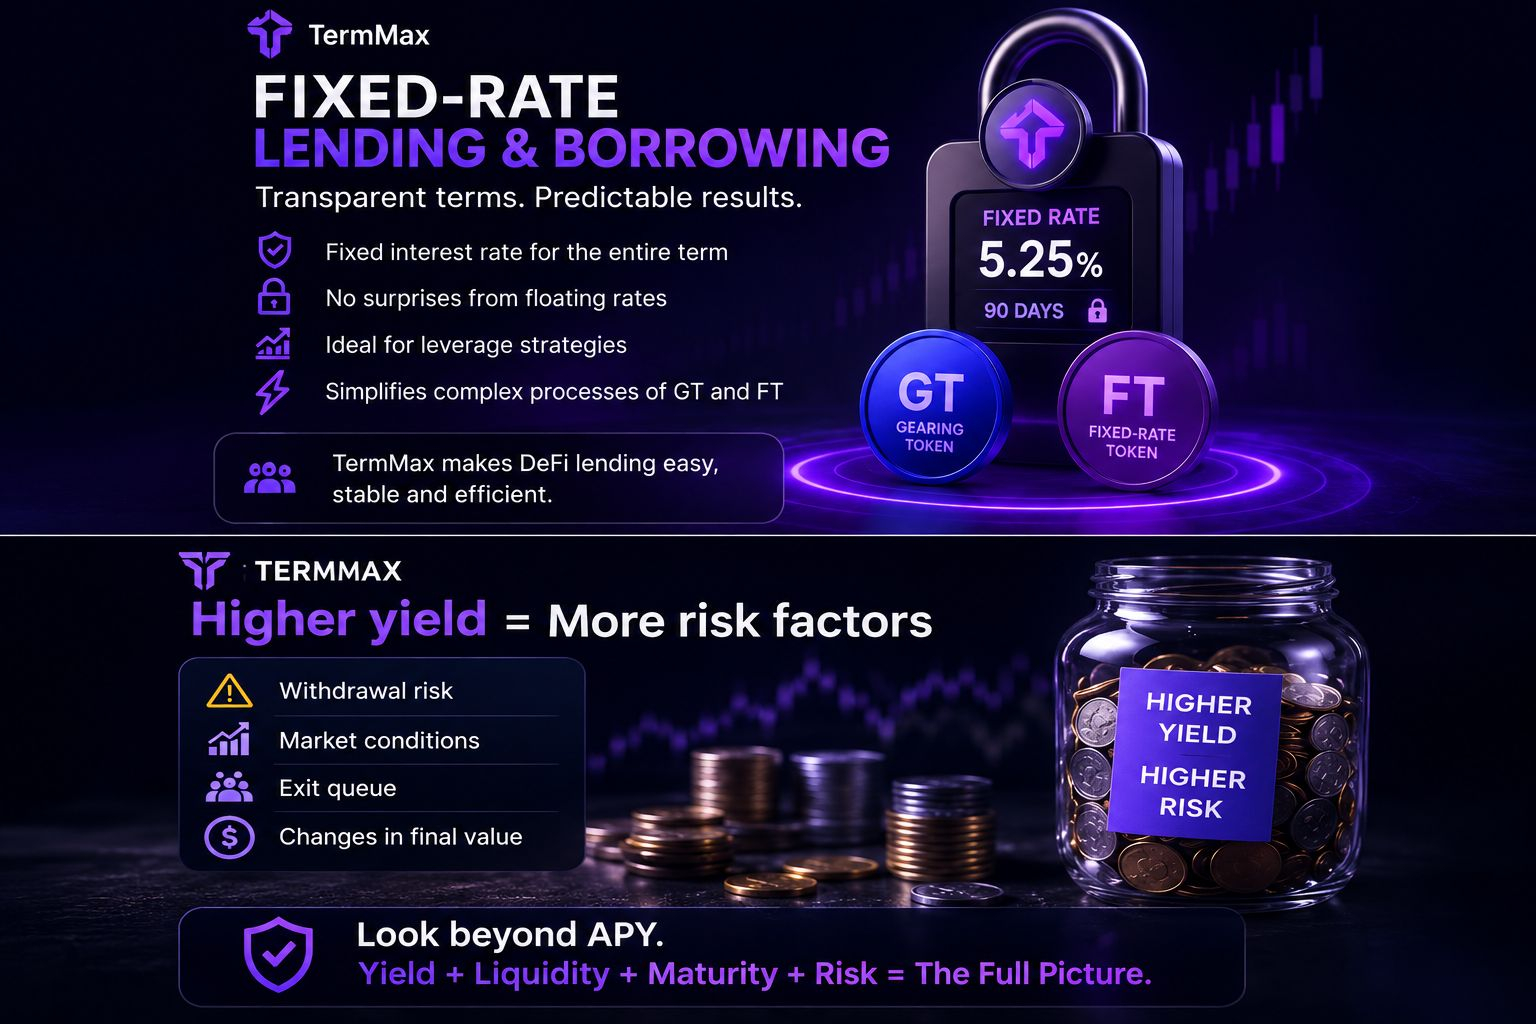
TermMax is building a more structured approach to DeFi lending and borrowing through fixed-rate markets, giving users clearer terms and more predictable outcomes.
With a fixed-rate model, you know the rate for the agreed term instead of constantly worrying about floating-rate changes. The 5.25% fixed rate for 90 days shown in the concept highlights how fixed-rate products can bring more predictability to a strategy.
⚡ Why fixed-rate lending matters:
• Predictable interest throughout the term
• Less exposure to sudden rate fluctuations
• Useful for structured and leverage-based strategies
• GT and FT can simplify different parts of the TermMax ecosystem
• Clearer planning around maturity and expected returns
But there’s another side of DeFi that every investor should understand:
Higher yield can also mean higher risk. 📈⚠️
Before chasing APY, it’s important to look beyond the headline number and consider liquidity, withdrawal conditions, maturity, market conditions, exit queues, and potential changes in asset value.
That’s why the real question isn’t just:
👉 “How much APY can I earn?”
It should be:
👉 “What is the yield, how liquid is it, how long is my capital locked, and what risks am I taking?”
For me, this is where TermMax becomes interesting — bringing more structure and transparency into DeFi lending while giving users a framework to think about both opportunity and risk.
Yield + Liquidity + Maturity + Risk = The Full Picture. 🔥
Always DYOR and understand the terms before putting capital to work.
#TermMax #TermMaxboost #DeFi #Crypto #Web3 #Lending #Borrowing #FixedRate #CryptoLending #DeFiLending #Yield #Blockchain #CryptoCommunity
#termmax @TermMax
With a fixed-rate model, you know the rate for the agreed term instead of constantly worrying about floating-rate changes. The 5.25% fixed rate for 90 days shown in the concept highlights how fixed-rate products can bring more predictability to a strategy.
⚡ Why fixed-rate lending matters:
• Predictable interest throughout the term
• Less exposure to sudden rate fluctuations
• Useful for structured and leverage-based strategies
• GT and FT can simplify different parts of the TermMax ecosystem
• Clearer planning around maturity and expected returns
But there’s another side of DeFi that every investor should understand:
Higher yield can also mean higher risk. 📈⚠️
Before chasing APY, it’s important to look beyond the headline number and consider liquidity, withdrawal conditions, maturity, market conditions, exit queues, and potential changes in asset value.
That’s why the real question isn’t just:
👉 “How much APY can I earn?”
It should be:
👉 “What is the yield, how liquid is it, how long is my capital locked, and what risks am I taking?”
For me, this is where TermMax becomes interesting — bringing more structure and transparency into DeFi lending while giving users a framework to think about both opportunity and risk.
Yield + Liquidity + Maturity + Risk = The Full Picture. 🔥
Always DYOR and understand the terms before putting capital to work.
#TermMax #TermMaxboost #DeFi #Crypto #Web3 #Lending #Borrowing #FixedRate #CryptoLending #DeFiLending #Yield #Blockchain #CryptoCommunity
#termmax @TermMax
72
·
--
#termmax @termmax TermMax is a DeFi project focused on the lending and borrowing market with fixed interest rates, helping users better manage their income and borrowing costs. The project develops products such as lending, borrowing, leverage, and vaults across multiple blockchains. A standout feature of TermMax is its focus on building fixed-income infrastructure for DeFi, while also expanding into RWA and institutional users. The TMX token is used for governance, staking, and incentivizing the ecosystem. This is a noteworthy project within the DeFi and on-chain finance trends.
#termmax @TermMax TermMax is a DeFi project focused on the lending and borrowing market with fixed interest rates, helping users better manage their income and borrowing costs. The project develops products such as lending, borrowing, leverage, and vaults across multiple blockchains. A standout feature of TermMax is its focus on building fixed-income infrastructure for DeFi, while also expanding into RWA and institutional users. The TMX token is used for governance, staking, and incentivizing the ecosystem. This is a noteworthy project within the DeFi and on-chain finance trends.
1
25

·
--
#termmax @termmax $TMX Let's be real—the constant volatility in crypto can be exhausting. That is why finding stability through fixed-rate lending feels like a breath of fresh air. @termmax is doing amazing work building predictable finance tools that help everyday users protect their hard-earned capital. #TermMax
#termmax @TermMax $TMX Let's be real—the constant volatility in crypto can be exhausting. That is why finding stability through fixed-rate lending feels like a breath of fresh air. @TermMax is doing amazing work building predictable finance tools that help everyday users protect their hard-earned capital. #TermMax
85
·
--
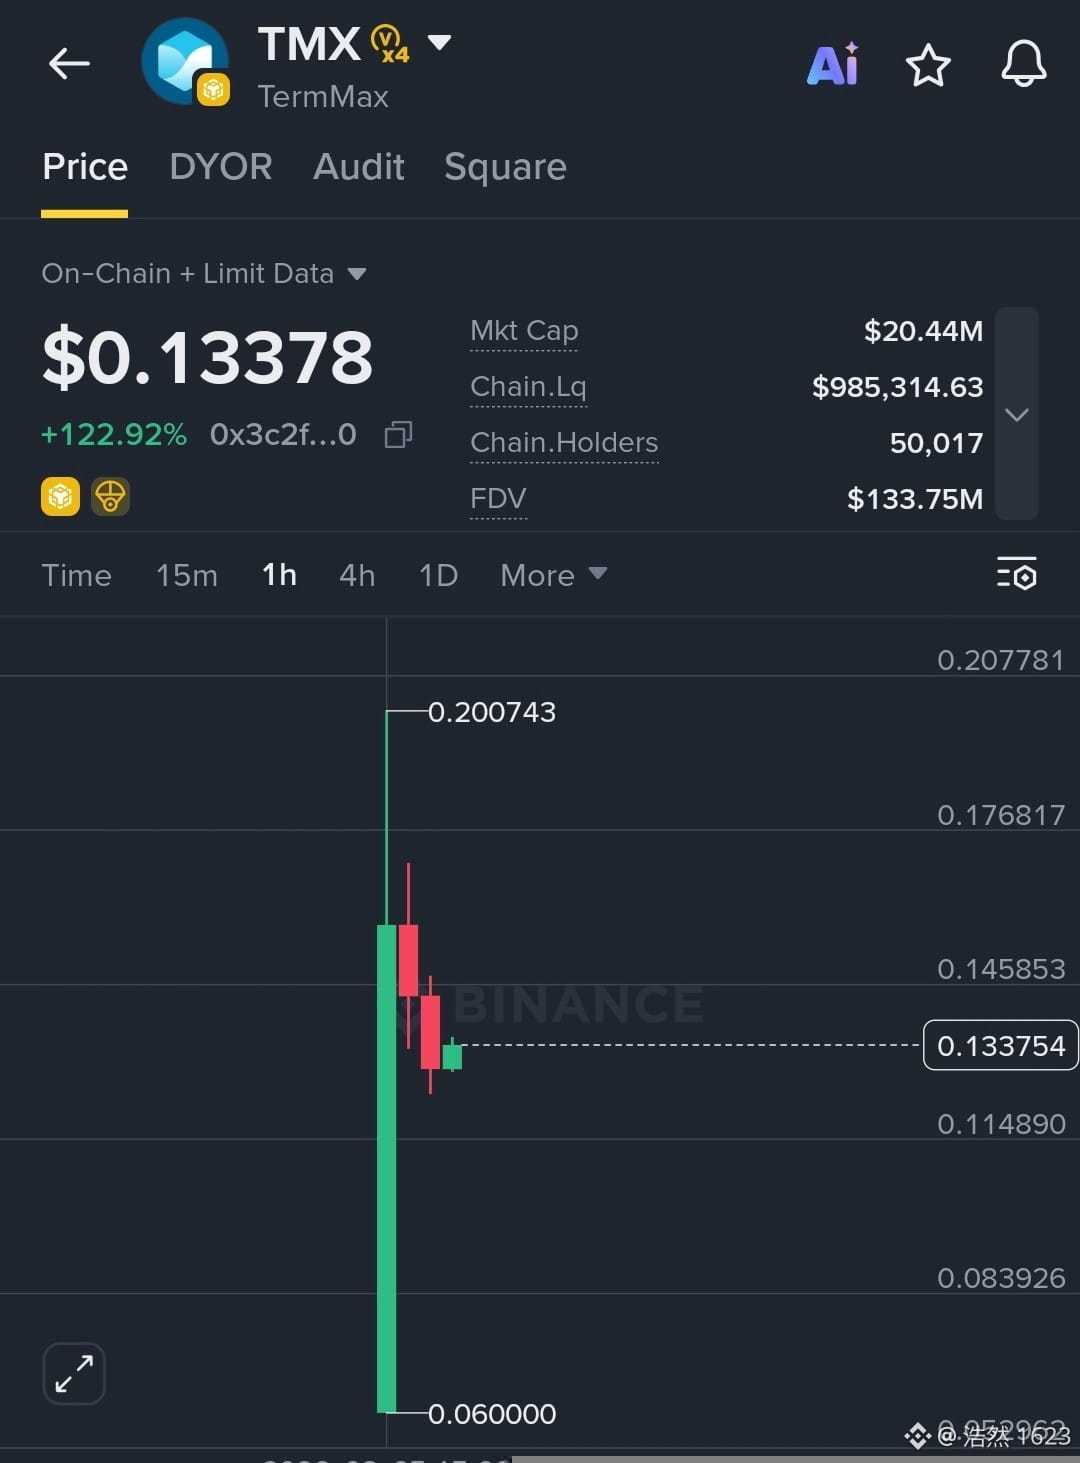
$TMX is showing massive volatility after a sharp initial spike up to 0.200743, followed by a pullback toward key support around 0.114890. Trading currently at 0.13378 with a massive gain of +122.92%, the chart reflects strong early buying volume followed by active price stabilization. As long as buyers hold the 0.11500 zone as solid support, the setup favours potential rebound continuation back toward upper resistance levels.
Target 1: 0.1458 Target 2: 0.1768 Target 3: 0.2007
#TMX #TermMax #CryptoAnalysis
$ONG
{future}(ONGUSDT)
$CYS
{alpha}(560x0c69199c1562233640e0db5ce2c399a88eb507c7)
{alpha}(560x3c2f61f2e27c865981d2e7aaf6b2cdf823030039)
$TMX is showing massive volatility after a sharp initial spike up to 0.200743, followed by a pullback toward key support around 0.114890. Trading currently at 0.13378 with a massive gain of +122.92%, the chart reflects strong early buying volume followed by active price stabilization. As long as buyers hold the 0.11500 zone as solid support, the setup favours potential rebound continuation back toward upper resistance levels.
Target 1: 0.1458 Target 2: 0.1768 Target 3: 0.2007
#TMX #TermMax #CryptoAnalysis
$ONG
$CYS
Target 1: 0.1458 Target 2: 0.1768 Target 3: 0.2007
#TMX #TermMax #CryptoAnalysis
$ONG
$CYS
1
46
·
--
Bullish
#termmax Managing interest rate volatility has always been one of the biggest bottlenecks for scalable DeFi participation. When floating yields fluctuate block-by-block, both lenders and borrowers face unpredictable returns and shifting borrowing costs.
@termmax addresses this liquidity challenge by establishing decentralized, fixed-rate and fixed-term lending and borrowing markets.
#termmax Managing interest rate volatility has always been one of the biggest bottlenecks for scalable DeFi participation. When floating yields fluctuate block-by-block, both lenders and borrowers face unpredictable returns and shifting borrowing costs.
@TermMax addresses this liquidity challenge by establishing decentralized, fixed-rate and fixed-term lending and borrowing markets.
@TermMax addresses this liquidity challenge by establishing decentralized, fixed-rate and fixed-term lending and borrowing markets.
1
1
133
·
--
#termmax When I reread the documentation of @termmax , I got stuck on a set of nouns: FT and XT. At first, I treated them as two names for the same thing—then I understood that it’s splitting a single position into two halves: one for returns and one for costs.$SPCXB
In TermMax, a fixed-term market expresses the relationship between funds by splitting it. FT represents the portion that you can recover as a fixed amount at maturity—the creditors hold that part, and the logic is close to a maturity settlement voucher. Meanwhile, the XT side corresponds to the other end of the leverage and cost structure.
Put it into plain language: in the same fixed-rate transaction, it’s divided into “a return that you’re certain to receive” and “a cost you bear in exchange for magnified returns.” Different parties with different needs take what they need—people aren’t all shoved into one vague position.$SNDKB
I used to think the split is just for accounting convenience. But then I realized this separation allows risk and returns to be priced separately and traded separately. If you want certainty, you hold FT. If you want to expand your exposure, you stand on the other side. The two sides’ demands get matched in the same market.
But the boundaries still have to be clearly stated. FT’s “fixed” refers to the maturity basis—it doesn’t mean you can sell it back at the original price anytime in the middle. The market price will move with interest rates and remaining term. The XT side naturally carries amplified risk; it’s not something you can just hold and lie back and profit. The split only clarifies roles—it doesn’t eliminate any side’s risk.
Seeing this made my understanding of #TermMax even clearer: it didn’t invent a risk-free tool. Instead, it takes two requests within the same transaction—“certainty” and “flexibility”—and turns them into two separate objects that can each circulate on their own.
Fixed-rate structure can lock in the shape of the returns, but it can’t lock in the market price when you exit mid-way.
@termmax #TermMax
#termmax When I reread the documentation of @TermMax , I got stuck on a set of nouns: FT and XT. At first, I treated them as two names for the same thing—then I understood that it’s splitting a single position into two halves: one for returns and one for costs.$SPCXB
In TermMax, a fixed-term market expresses the relationship between funds by splitting it. FT represents the portion that you can recover as a fixed amount at maturity—the creditors hold that part, and the logic is close to a maturity settlement voucher. Meanwhile, the XT side corresponds to the other end of the leverage and cost structure.
Put it into plain language: in the same fixed-rate transaction, it’s divided into “a return that you’re certain to receive” and “a cost you bear in exchange for magnified returns.” Different parties with different needs take what they need—people aren’t all shoved into one vague position.$SNDKB
I used to think the split is just for accounting convenience. But then I realized this separation allows risk and returns to be priced separately and traded separately. If you want certainty, you hold FT. If you want to expand your exposure, you stand on the other side. The two sides’ demands get matched in the same market.
But the boundaries still have to be clearly stated. FT’s “fixed” refers to the maturity basis—it doesn’t mean you can sell it back at the original price anytime in the middle. The market price will move with interest rates and remaining term. The XT side naturally carries amplified risk; it’s not something you can just hold and lie back and profit. The split only clarifies roles—it doesn’t eliminate any side’s risk.
Seeing this made my understanding of #TermMax even clearer: it didn’t invent a risk-free tool. Instead, it takes two requests within the same transaction—“certainty” and “flexibility”—and turns them into two separate objects that can each circulate on their own.
Fixed-rate structure can lock in the shape of the returns, but it can’t lock in the market price when you exit mid-way.
@TermMax #TermMax
In TermMax, a fixed-term market expresses the relationship between funds by splitting it. FT represents the portion that you can recover as a fixed amount at maturity—the creditors hold that part, and the logic is close to a maturity settlement voucher. Meanwhile, the XT side corresponds to the other end of the leverage and cost structure.
Put it into plain language: in the same fixed-rate transaction, it’s divided into “a return that you’re certain to receive” and “a cost you bear in exchange for magnified returns.” Different parties with different needs take what they need—people aren’t all shoved into one vague position.$SNDKB
I used to think the split is just for accounting convenience. But then I realized this separation allows risk and returns to be priced separately and traded separately. If you want certainty, you hold FT. If you want to expand your exposure, you stand on the other side. The two sides’ demands get matched in the same market.
But the boundaries still have to be clearly stated. FT’s “fixed” refers to the maturity basis—it doesn’t mean you can sell it back at the original price anytime in the middle. The market price will move with interest rates and remaining term. The XT side naturally carries amplified risk; it’s not something you can just hold and lie back and profit. The split only clarifies roles—it doesn’t eliminate any side’s risk.
Seeing this made my understanding of #TermMax even clearer: it didn’t invent a risk-free tool. Instead, it takes two requests within the same transaction—“certainty” and “flexibility”—and turns them into two separate objects that can each circulate on their own.
Fixed-rate structure can lock in the shape of the returns, but it can’t lock in the market price when you exit mid-way.
@TermMax #TermMax
FT和XT到底差在哪?
100%
想要确定性该持有哪个?
0%
2 votes • Voting closed
1
1
92

#termmax At 2 a.m., I wanted to add a line of stablecoin borrowing. I opened Aave and saw the USDC borrowing rate jump from 8% to 13% within a day—how could you possibly calculate the accounting for a looping strategy? I tried TermMax instead, and on the order page, it simply shows the maturity date and a fixed number. The moment the trade goes through, your total cost is locked in. I stared at the screen for a few seconds. After all these years in DeFi, it was the first time I could know—before opening a position—exactly how much I would have to repay at maturity. $SPCXB
When I break down the mechanism, I finally understand: that fixed interest rate isn’t something the protocol decides on the spot. It’s produced by market trading. Borrowing on TermMax is essentially minting FTs and selling them at a discount; the discount translated into annualized terms is your actual rate. For example, with a face value of 100 and three months to maturity, the FT might sell for 97—annualized, that’s roughly a bit over 12%. The debt is a dead number the instant the FT is minted; after that, no matter how high the pool’s utilization spikes, it has nothing to do with you. This is completely different from Aave, where pricing changes in real time with the utilization curve. Two totally different ways of thinking.
I did the math based on a real need. Borrow 50k U to run a three-month strategy. Using Aave’s floating rate average of 10%, but when the market heats up, there are plenty of days where it goes above 20%. Over three months, the interest might swing between 1250 U and 2500 U. If TermMax locks it at 12%, then the interest is 1500 U—no more, no less. Looking only at the average might not be cheaper, but if the strategy’s payoff is fixed, then floating costs are basically half naked—certainty itself should be priced in. $SNDKB
Of course, fixed also has a cost. If you repay early, you have to buy back the FT at the prevailing market price. When rates fall, FTs rise in price, and exiting will cost you a chunk. Also, in smaller markets, slippage can bite again. TermMax currently has over a hundred markets; liquidity is decent for mainstream stablecoins, while the tail markets have thinner order books. So before placing an order, figure out clearly whether this money is meant to be held to maturity—or whether it might be withdrawn at any time. That judgment is worth more than the interest-rate number itself.
#TermMax @Square-Creator-0f84001b3db77 @TermMax
#termmax At 2 a.m., I wanted to add a line of stablecoin borrowing. I opened Aave and saw the USDC borrowing rate jump from 8% to 13% within a day—how could you possibly calculate the accounting for a looping strategy? I tried TermMax instead, and on the order page, it simply shows the maturity date and a fixed number. The moment the trade goes through, your total cost is locked in. I stared at the screen for a few seconds. After all these years in DeFi, it was the first time I could know—before opening a position—exactly how much I would have to repay at maturity. $SPCXB
When I break down the mechanism, I finally understand: that fixed interest rate isn’t something the protocol decides on the spot. It’s produced by market trading. Borrowing on TermMax is essentially minting FTs and selling them at a discount; the discount translated into annualized terms is your actual rate. For example, with a face value of 100 and three months to maturity, the FT might sell for 97—annualized, that’s roughly a bit over 12%. The debt is a dead number the instant the FT is minted; after that, no matter how high the pool’s utilization spikes, it has nothing to do with you. This is completely different from Aave, where pricing changes in real time with the utilization curve. Two totally different ways of thinking.
I did the math based on a real need. Borrow 50k U to run a three-month strategy. Using Aave’s floating rate average of 10%, but when the market heats up, there are plenty of days where it goes above 20%. Over three months, the interest might swing between 1250 U and 2500 U. If TermMax locks it at 12%, then the interest is 1500 U—no more, no less. Looking only at the average might not be cheaper, but if the strategy’s payoff is fixed, then floating costs are basically half naked—certainty itself should be priced in. $SNDKB
Of course, fixed also has a cost. If you repay early, you have to buy back the FT at the prevailing market price. When rates fall, FTs rise in price, and exiting will cost you a chunk. Also, in smaller markets, slippage can bite again. TermMax currently has over a hundred markets; liquidity is decent for mainstream stablecoins, while the tail markets have thinner order books. So before placing an order, figure out clearly whether this money is meant to be held to maturity—or whether it might be withdrawn at any time. That judgment is worth more than the interest-rate number itself.
#TermMax @TalhaxAlpha @TermMax
When I break down the mechanism, I finally understand: that fixed interest rate isn’t something the protocol decides on the spot. It’s produced by market trading. Borrowing on TermMax is essentially minting FTs and selling them at a discount; the discount translated into annualized terms is your actual rate. For example, with a face value of 100 and three months to maturity, the FT might sell for 97—annualized, that’s roughly a bit over 12%. The debt is a dead number the instant the FT is minted; after that, no matter how high the pool’s utilization spikes, it has nothing to do with you. This is completely different from Aave, where pricing changes in real time with the utilization curve. Two totally different ways of thinking.
I did the math based on a real need. Borrow 50k U to run a three-month strategy. Using Aave’s floating rate average of 10%, but when the market heats up, there are plenty of days where it goes above 20%. Over three months, the interest might swing between 1250 U and 2500 U. If TermMax locks it at 12%, then the interest is 1500 U—no more, no less. Looking only at the average might not be cheaper, but if the strategy’s payoff is fixed, then floating costs are basically half naked—certainty itself should be priced in. $SNDKB
Of course, fixed also has a cost. If you repay early, you have to buy back the FT at the prevailing market price. When rates fall, FTs rise in price, and exiting will cost you a chunk. Also, in smaller markets, slippage can bite again. TermMax currently has over a hundred markets; liquidity is decent for mainstream stablecoins, while the tail markets have thinner order books. So before placing an order, figure out clearly whether this money is meant to be held to maturity—or whether it might be withdrawn at any time. That judgment is worth more than the interest-rate number itself.
#TermMax @TalhaxAlpha @TermMax
固定利率我早就想要了
0%
还是觉得浮动更灵活
100%
看提前退出的实测
0%
1 votes • Voting closed
1
80
·
--
#termmax @termmax
I see a strong idea @termmax specifically in the fact that the project is trying to build a full-fledged fixed-rate market in DeFi. Fixed terms, fixed rates, leverage, vault strategies, and the ability to work with yield-bearing collateral create the foundation for a more structured financial market on the blockchain. It’s interesting to see how this concept will evolve further.
#termmax @TermMax
I see a strong idea @TermMax specifically in the fact that the project is trying to build a full-fledged fixed-rate market in DeFi. Fixed terms, fixed rates, leverage, vault strategies, and the ability to work with yield-bearing collateral create the foundation for a more structured financial market on the blockchain. It’s interesting to see how this concept will evolve further.
I see a strong idea @TermMax specifically in the fact that the project is trying to build a full-fledged fixed-rate market in DeFi. Fixed terms, fixed rates, leverage, vault strategies, and the ability to work with yield-bearing collateral create the foundation for a more structured financial market on the blockchain. It’s interesting to see how this concept will evolve further.
94
·
--
$BLESS $ENA
TermMax vaults can change strategy at two very different speeds, depending on which direction the change moves risk.
A curator lowering exposure — pulling out of a risky market, tightening a parameter — takes effect immediately. No wait, no review.
A curator raising exposure — adding a new market, loosening a risk parameter — has to sit in a timelock first, by default one day, during which a separate Guardian role can step in and reverse it before it ever goes live.
The asymmetry is the design. It isn’t there to slow curators down in general. It’s built to slow them down in exactly one direction — the direction where depositor money ends up more exposed than it was the day before.
Depositors are still trusting a person to manage their capital well. What’s changed is how much damage that trust can do before someone else gets a chance to catch it.
#TermMax @termmax
{future}(ENAUSDT)
Should vault risk changes be symmetrical?
$BLESS $ENA
TermMax vaults can change strategy at two very different speeds, depending on which direction the change moves risk.
A curator lowering exposure — pulling out of a risky market, tightening a parameter — takes effect immediately. No wait, no review.
A curator raising exposure — adding a new market, loosening a risk parameter — has to sit in a timelock first, by default one day, during which a separate Guardian role can step in and reverse it before it ever goes live.
The asymmetry is the design. It isn’t there to slow curators down in general. It’s built to slow them down in exactly one direction — the direction where depositor money ends up more exposed than it was the day before.
Depositors are still trusting a person to manage their capital well. What’s changed is how much damage that trust can do before someone else gets a chance to catch it.
#TermMax @TermMax
Should vault risk changes be symmetrical?
TermMax vaults can change strategy at two very different speeds, depending on which direction the change moves risk.
A curator lowering exposure — pulling out of a risky market, tightening a parameter — takes effect immediately. No wait, no review.
A curator raising exposure — adding a new market, loosening a risk parameter — has to sit in a timelock first, by default one day, during which a separate Guardian role can step in and reverse it before it ever goes live.
The asymmetry is the design. It isn’t there to slow curators down in general. It’s built to slow them down in exactly one direction — the direction where depositor money ends up more exposed than it was the day before.
Depositors are still trusting a person to manage their capital well. What’s changed is how much damage that trust can do before someone else gets a chance to catch it.
#TermMax @TermMax
Should vault risk changes be symmetrical?
⚖️ Yes, keep them equal
100%
⏳ No, risk-up needs a delay
0%
⚡ Risk-down should be instant
0%
🤔 Depends on the vault
0%
1 votes • Voting closed
1
424
·
--
With TermMax’s TGE coming up soon, everyone in the group is guessing the opening price, but I’d rather chat about the product itself. At first, I treated it like a typical fixed-income token—kind of like an on-chain Yu’ebao. Later, when I split and examined FT and XT separately, I realized I’d been thinking too narrowly.
FT is like a zero-coupon bond that can be redeemed upon maturity. You lock in an amount, the yield is fixed—what you’re after is peace of mind. XT, on the other hand, separates future interest-rate volatility and turns it into a tradable asset. Once you break it down this way, debt is no longer a dead collateral you just stash away. Instead, it can be handed over in the secondary market and becomes an income-generating asset. I thought about it: isn’t this essentially bringing that interest-rate derivatives arbitrage logic from traditional finance onto the chain—while also adding a bit of decentralized attitude?
But what really surprised me is its limit order mechanism. In lending protocols I’ve played with before, the interest rate is basically decided by the platform, and users can only accept it passively. Here, though, the liquidity provider can set a minimum annualized rate, and the borrower can set a maximum interest-rate cap—then routing handles the matching. This returns pricing power to the market, so everyone can express their capital intent. I tested placing orders on the testnet; it was indeed not complicated. But the testnet liquidity is fake, so it doesn’t prove much.
Still, don’t get too excited. The downside of this kind of self-determined pricing is obvious: when the counterparty side isn’t thick enough, your orders might never get filled. And if the market goes extreme, liquidity can dry up in an instant. Also, fixed-rate locks in present risk. If market rates swing massively later, the cost you locked earlier could turn out to be a loss. I’ve been burned by other fixed-income products before—locked in a high yield for half a year, and then the market rate doubled. That feeling was really not good.
So next, I’m going to focus on three points: whether bilateral orders can produce continuous and deep liquidity; how big the slippage is under high-frequency shocks from the aggregator; and whether XT’s price truly reflects market leverage sentiment. Only after it clears these hurdles will I admit that it really has restructured lending efficiency. For now, I’ll wait for the TGE and see how real liquidity plays out.
#TermMax @termmax
With TermMax’s TGE coming up soon, everyone in the group is guessing the opening price, but I’d rather chat about the product itself. At first, I treated it like a typical fixed-income token—kind of like an on-chain Yu’ebao. Later, when I split and examined FT and XT separately, I realized I’d been thinking too narrowly.
FT is like a zero-coupon bond that can be redeemed upon maturity. You lock in an amount, the yield is fixed—what you’re after is peace of mind. XT, on the other hand, separates future interest-rate volatility and turns it into a tradable asset. Once you break it down this way, debt is no longer a dead collateral you just stash away. Instead, it can be handed over in the secondary market and becomes an income-generating asset. I thought about it: isn’t this essentially bringing that interest-rate derivatives arbitrage logic from traditional finance onto the chain—while also adding a bit of decentralized attitude?
But what really surprised me is its limit order mechanism. In lending protocols I’ve played with before, the interest rate is basically decided by the platform, and users can only accept it passively. Here, though, the liquidity provider can set a minimum annualized rate, and the borrower can set a maximum interest-rate cap—then routing handles the matching. This returns pricing power to the market, so everyone can express their capital intent. I tested placing orders on the testnet; it was indeed not complicated. But the testnet liquidity is fake, so it doesn’t prove much.
Still, don’t get too excited. The downside of this kind of self-determined pricing is obvious: when the counterparty side isn’t thick enough, your orders might never get filled. And if the market goes extreme, liquidity can dry up in an instant. Also, fixed-rate locks in present risk. If market rates swing massively later, the cost you locked earlier could turn out to be a loss. I’ve been burned by other fixed-income products before—locked in a high yield for half a year, and then the market rate doubled. That feeling was really not good.
So next, I’m going to focus on three points: whether bilateral orders can produce continuous and deep liquidity; how big the slippage is under high-frequency shocks from the aggregator; and whether XT’s price truly reflects market leverage sentiment. Only after it clears these hurdles will I admit that it really has restructured lending efficiency. For now, I’ll wait for the TGE and see how real liquidity plays out.
#TermMax @TermMax
FT is like a zero-coupon bond that can be redeemed upon maturity. You lock in an amount, the yield is fixed—what you’re after is peace of mind. XT, on the other hand, separates future interest-rate volatility and turns it into a tradable asset. Once you break it down this way, debt is no longer a dead collateral you just stash away. Instead, it can be handed over in the secondary market and becomes an income-generating asset. I thought about it: isn’t this essentially bringing that interest-rate derivatives arbitrage logic from traditional finance onto the chain—while also adding a bit of decentralized attitude?
But what really surprised me is its limit order mechanism. In lending protocols I’ve played with before, the interest rate is basically decided by the platform, and users can only accept it passively. Here, though, the liquidity provider can set a minimum annualized rate, and the borrower can set a maximum interest-rate cap—then routing handles the matching. This returns pricing power to the market, so everyone can express their capital intent. I tested placing orders on the testnet; it was indeed not complicated. But the testnet liquidity is fake, so it doesn’t prove much.
Still, don’t get too excited. The downside of this kind of self-determined pricing is obvious: when the counterparty side isn’t thick enough, your orders might never get filled. And if the market goes extreme, liquidity can dry up in an instant. Also, fixed-rate locks in present risk. If market rates swing massively later, the cost you locked earlier could turn out to be a loss. I’ve been burned by other fixed-income products before—locked in a high yield for half a year, and then the market rate doubled. That feeling was really not good.
So next, I’m going to focus on three points: whether bilateral orders can produce continuous and deep liquidity; how big the slippage is under high-frequency shocks from the aggregator; and whether XT’s price truly reflects market leverage sentiment. Only after it clears these hurdles will I admit that it really has restructured lending efficiency. For now, I’ll wait for the TGE and see how real liquidity plays out.
#TermMax @TermMax
166

·
--
Bullish
Verified
TermMax is entering a new phase with the $TMX airdrop checker now live and TGE set for August 25. Connecting the correct wallet shows your allocation based on verified activity, and the confirmation window closes on August 23. Choices around claiming, vesting, and staking bonuses are final once submitted. Behind the token news, the protocol continues to deliver fixed-rate lending and borrowing with known terms, Alpha markets on BNB Chain that offer Call and Put trading without liquidation risk, and Dual Investment vaults that reward liquidity providers with premiums and AP points. The focus on predictability has remained consistent even as the product expanded across multiple chains. This measured path from infrastructure to token launch feels intentional. Still exploring the different strategies and watching how the community prepares. @termmax #TermMax
TermMax is entering a new phase with the $TMX airdrop checker now live and TGE set for August 25. Connecting the correct wallet shows your allocation based on verified activity, and the confirmation window closes on August 23. Choices around claiming, vesting, and staking bonuses are final once submitted. Behind the token news, the protocol continues to deliver fixed-rate lending and borrowing with known terms, Alpha markets on BNB Chain that offer Call and Put trading without liquidation risk, and Dual Investment vaults that reward liquidity providers with premiums and AP points. The focus on predictability has remained consistent even as the product expanded across multiple chains. This measured path from infrastructure to token launch feels intentional. Still exploring the different strategies and watching how the community prepares. @TermMax #TermMax
1
2
5

·
--
#termmax @termmax TermMax stands out in DeFi by delivering true fixed-rate lending and borrowing with defined maturity dates. No more variable-rate surprises or constant liquidation anxiety — you lock in your yield or cost upfront. With multi-chain support (including BNB Chain), curator-managed vaults, one-click leverage, and growing TVL, it’s bringing institutional-grade predictability on-chain. Excited to see $TMX at TGE. Check out the protocol and the ongoing Binance Wallet Booster campaign!
@TermMax
#TermMax
#termmax @TermMax TermMax stands out in DeFi by delivering true fixed-rate lending and borrowing with defined maturity dates. No more variable-rate surprises or constant liquidation anxiety — you lock in your yield or cost upfront. With multi-chain support (including BNB Chain), curator-managed vaults, one-click leverage, and growing TVL, it’s bringing institutional-grade predictability on-chain. Excited to see $TMX at TGE. Check out the protocol and the ongoing Binance Wallet Booster campaign!
@TermMax
#TermMax
@TermMax
#TermMax
62
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#JobsReportRaisesHikeOdds
505,264 views
3,269 Discussing
2
#CPITestsDecemberRateOutlook
143,196 views
1,069 Discussing
3
#BitcoinRebounds$75KAsChipsLead
46,068 views
337 Discussing
4
#US Data Center Rules May Constrain AI Expansion
70,488 views
226 Discussing
5
#ARKPlans14ThematicETFsCoveringAIAndTokenizedMarkets
4,091 views
65 Discussing
6
#WillAnthropicListOnTime
150,140 views
1,314 Discussing
7
#WillUS-IranTensionsBoostSafe-HavenDemand?
65,795 views
477 Discussing
8
#BitcoinETFsSee$412MNetOutflows
14,739 views
73 Discussing
9
#HKSFCPlansToRestrictCryptoAndExchangeTerms
57,383 views
515 Discussing
10
#TradFiForBeginners
89,415 views
967 Discussing