
#rates
rates
113,099 views
445 Discussing
Hot
Latest
·
--
Markets don’t have to be in crisis for a macro shift to matter.
$AVA
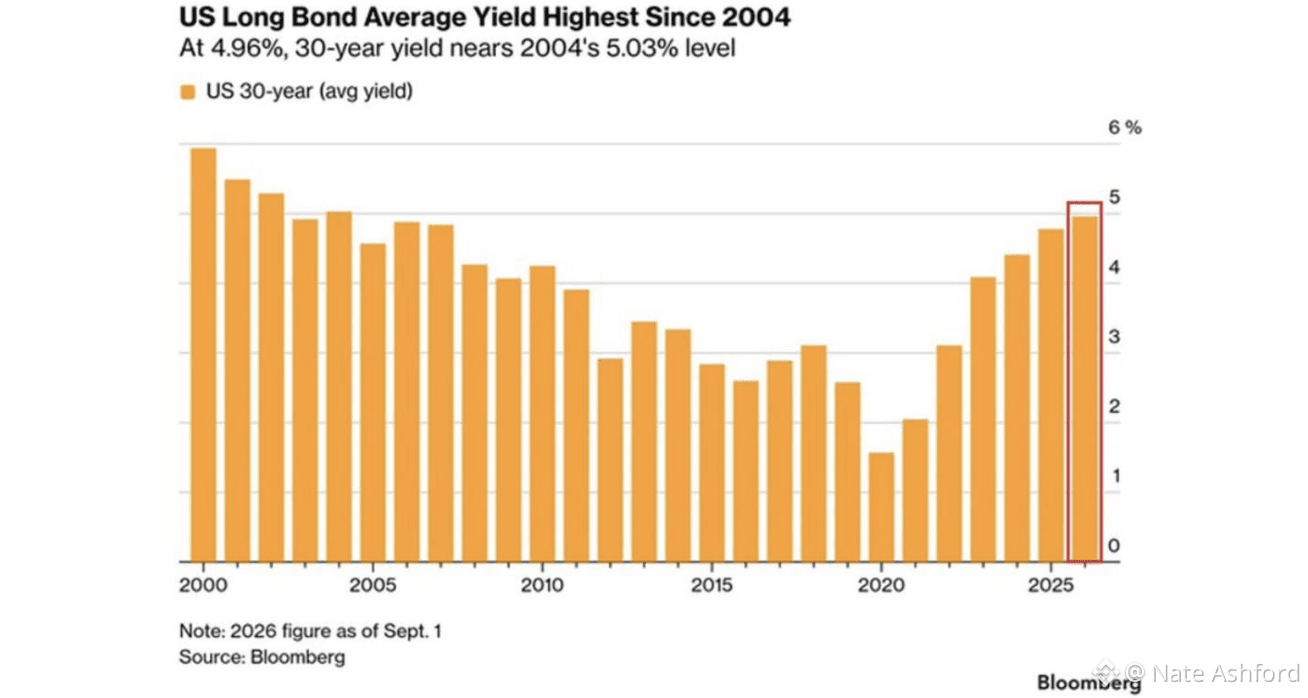
Bloomberg’s piece on Treasury yields and government debt argues that high yields may be settling in as the “new normal.” That’s important because a persistent higher-rate backdrop changes the whole market playbook: equity valuations get more pressure, financing costs stay elevated, and the dollar can stay supported if U.S. yields remain attractive.
For crypto, this is a real test of whether BTC and the broader market can keep trading as a liquidity-sensitive risk asset. Higher yields usually make speculative assets work harder for capital. At the same time, if bond stress starts to build, gold and defensive positioning can get more attention too.
$ONE
Traders should watch whether rate expectations keep drifting higher, because that would shape sentiment across stocks, forex, and digital assets. In the background, , and are among Binance’s strongest movers today — useful to watch, but the bigger signal is still the macro regime.
If high yields are becoming structural, does that ultimately cap crypto beta for longer than most traders expect?
$COTI
#GlobalMarkets #Rates #Crypto
Markets don’t have to be in crisis for a macro shift to matter.
$AVA
Bloomberg’s piece on Treasury yields and government debt argues that high yields may be settling in as the “new normal.” That’s important because a persistent higher-rate backdrop changes the whole market playbook: equity valuations get more pressure, financing costs stay elevated, and the dollar can stay supported if U.S. yields remain attractive.
For crypto, this is a real test of whether BTC and the broader market can keep trading as a liquidity-sensitive risk asset. Higher yields usually make speculative assets work harder for capital. At the same time, if bond stress starts to build, gold and defensive positioning can get more attention too.
$ONE
Traders should watch whether rate expectations keep drifting higher, because that would shape sentiment across stocks, forex, and digital assets. In the background, , and are among Binance’s strongest movers today — useful to watch, but the bigger signal is still the macro regime.
If high yields are becoming structural, does that ultimately cap crypto beta for longer than most traders expect?
$COTI
#GlobalMarkets #Rates #Crypto
$AVA
Bloomberg’s piece on Treasury yields and government debt argues that high yields may be settling in as the “new normal.” That’s important because a persistent higher-rate backdrop changes the whole market playbook: equity valuations get more pressure, financing costs stay elevated, and the dollar can stay supported if U.S. yields remain attractive.
For crypto, this is a real test of whether BTC and the broader market can keep trading as a liquidity-sensitive risk asset. Higher yields usually make speculative assets work harder for capital. At the same time, if bond stress starts to build, gold and defensive positioning can get more attention too.
$ONE
Traders should watch whether rate expectations keep drifting higher, because that would shape sentiment across stocks, forex, and digital assets. In the background, , and are among Binance’s strongest movers today — useful to watch, but the bigger signal is still the macro regime.
If high yields are becoming structural, does that ultimately cap crypto beta for longer than most traders expect?
$COTI
#GlobalMarkets #Rates #Crypto
267
·
--
Verified
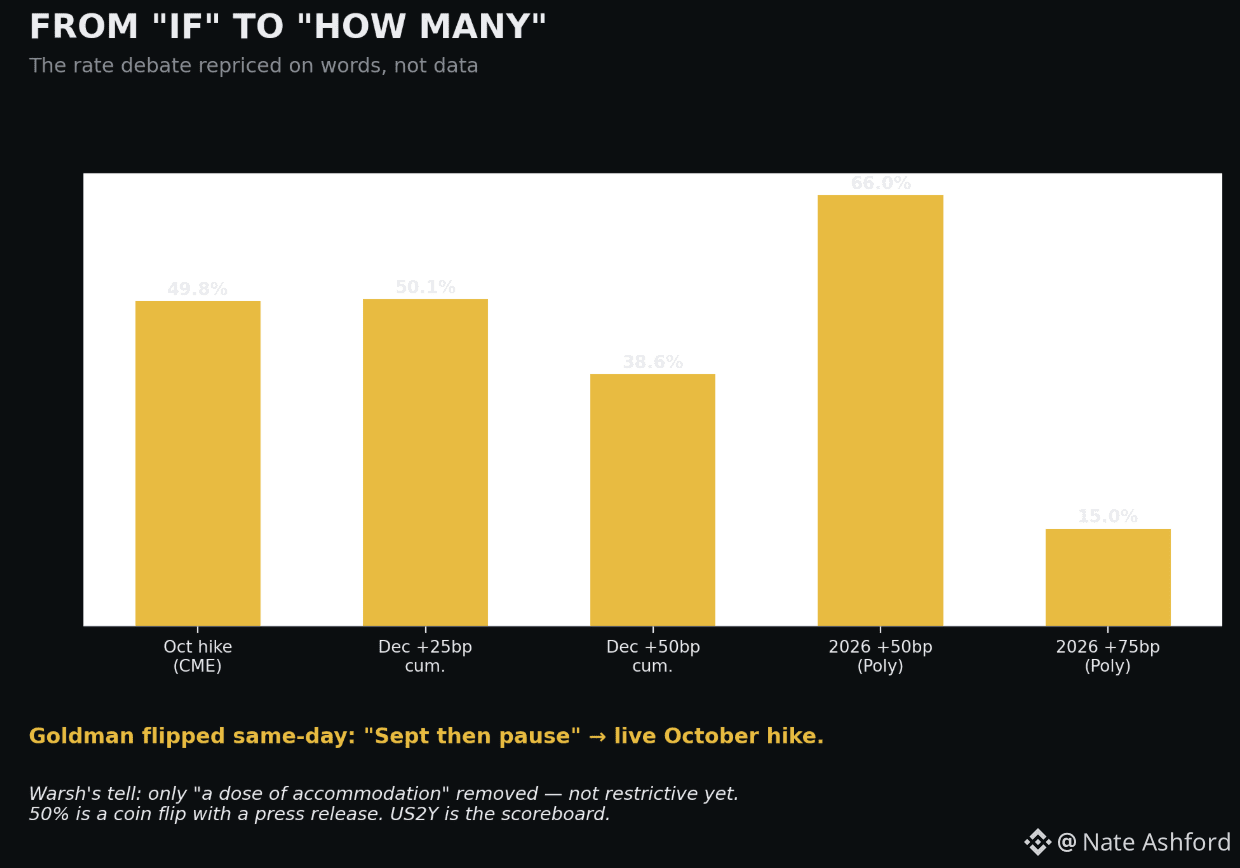
The whole debate flipped overnight, and not because a single data point changed. A week ago the question was whether the Fed would hike at all. Today October sits at 49.8% on CME, cumulative 50bp for the year is 66% on Polymarket, and Goldman abandoned its pause call for a live October hike inside a single trading day.
What moved all of that was a tone of voice. Warsh called Wednesday's hike a removal of "a dose of accommodation" and kept calling inflation "too high." Decode it: he's telling you he doesn't believe policy is even restrictive yet. A central banker who thinks he's still stimulating the economy is not one who's finished tightening.
And here's what actually changed for you — the burden of proof flipped. A month ago the bulls had to argue that hikes were coming. Now the burden is on anyone claiming they stop, and I have yet to hear one name the specific print that produces the pause. "Inflation cools" isn't an answer when the chairman has told you he'll only believe it at 2%, "clearly and sufficiently quickly."
50% is not a signal. It's a coin flip with a press release. The tell is whether October holds above 50 as real data lands, or fades like every hike scare did this summer. Watch US2Y — the front end votes with money, not opinions. #Fed #rates
The whole debate flipped overnight, and not because a single data point changed. A week ago the question was whether the Fed would hike at all. Today October sits at 49.8% on CME, cumulative 50bp for the year is 66% on Polymarket, and Goldman abandoned its pause call for a live October hike inside a single trading day.
What moved all of that was a tone of voice. Warsh called Wednesday's hike a removal of "a dose of accommodation" and kept calling inflation "too high." Decode it: he's telling you he doesn't believe policy is even restrictive yet. A central banker who thinks he's still stimulating the economy is not one who's finished tightening.
And here's what actually changed for you — the burden of proof flipped. A month ago the bulls had to argue that hikes were coming. Now the burden is on anyone claiming they stop, and I have yet to hear one name the specific print that produces the pause. "Inflation cools" isn't an answer when the chairman has told you he'll only believe it at 2%, "clearly and sufficiently quickly."
50% is not a signal. It's a coin flip with a press release. The tell is whether October holds above 50 as real data lands, or fades like every hike scare did this summer. Watch US2Y — the front end votes with money, not opinions. #Fed #rates
What moved all of that was a tone of voice. Warsh called Wednesday's hike a removal of "a dose of accommodation" and kept calling inflation "too high." Decode it: he's telling you he doesn't believe policy is even restrictive yet. A central banker who thinks he's still stimulating the economy is not one who's finished tightening.
And here's what actually changed for you — the burden of proof flipped. A month ago the bulls had to argue that hikes were coming. Now the burden is on anyone claiming they stop, and I have yet to hear one name the specific print that produces the pause. "Inflation cools" isn't an answer when the chairman has told you he'll only believe it at 2%, "clearly and sufficiently quickly."
50% is not a signal. It's a coin flip with a press release. The tell is whether October holds above 50 as real data lands, or fades like every hike scare did this summer. Watch US2Y — the front end votes with money, not opinions. #Fed #rates
AngelOfCrypto_-:
nice
1
1
578
·
--
Verified
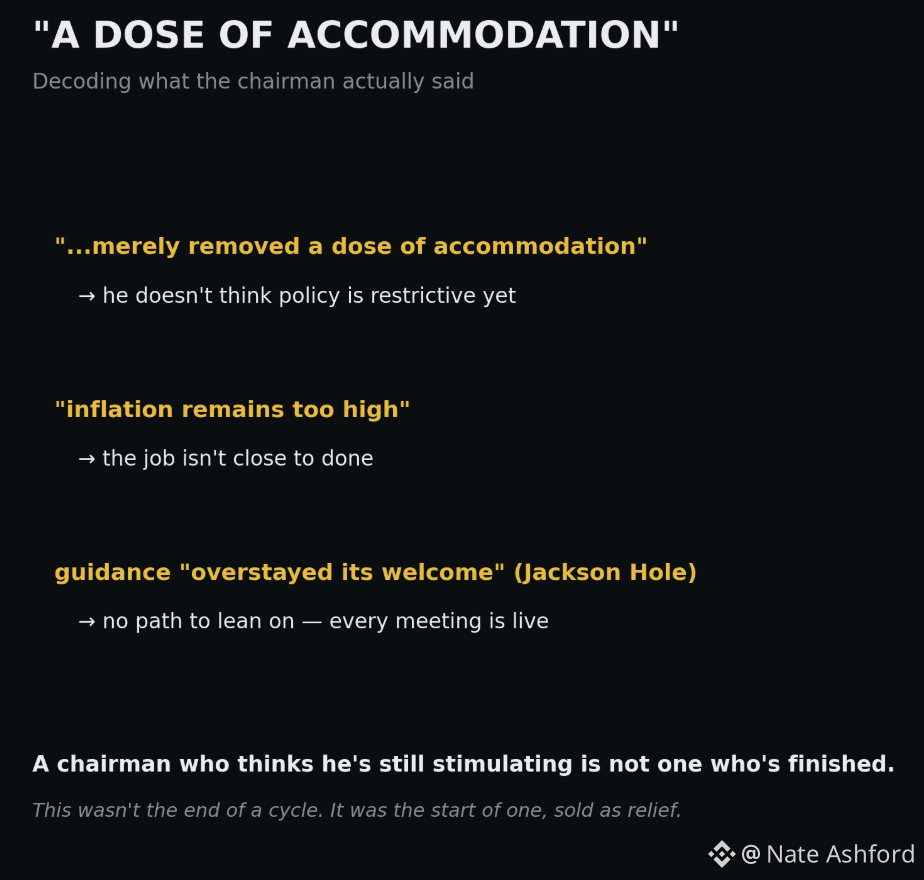
The quiet story from this meeting is the one the headlines skipped: Warsh told us, plainly, that he doesn't think he's restrictive yet.
Listen to the actual words. The hike removed "a dose of accommodation." Inflation is still "too high." Put those together and you get a chairman who believes current policy is still stimulating the economy, not restraining it. That's not a man planning to stop — it's a man explaining why he's only getting started.
This matters because of what he did to himself at Jackson Hole. He killed forward guidance, called it a practice that "overstayed its welcome," committed to "a discipline, not a decision." So there's no path to lean on, no promise to anchor expectations. Every meeting is genuinely live, and the work of figuring out the trajectory falls entirely on the market. There's no committee hand to hold anymore.
Which is exactly why the dovish "one and done" read is a misread. The market heard the accommodation line correctly even where the commentary didn't. This wasn't the end of a cycle dressed as a hike. It was the start of one, handed to you wrapped in relief.
The mispricing is the relief itself. What breaks it is the first serious person who asks: if he's not restrictive yet, what is it that makes him stop? #Fed #rates
The quiet story from this meeting is the one the headlines skipped: Warsh told us, plainly, that he doesn't think he's restrictive yet.
Listen to the actual words. The hike removed "a dose of accommodation." Inflation is still "too high." Put those together and you get a chairman who believes current policy is still stimulating the economy, not restraining it. That's not a man planning to stop — it's a man explaining why he's only getting started.
This matters because of what he did to himself at Jackson Hole. He killed forward guidance, called it a practice that "overstayed its welcome," committed to "a discipline, not a decision." So there's no path to lean on, no promise to anchor expectations. Every meeting is genuinely live, and the work of figuring out the trajectory falls entirely on the market. There's no committee hand to hold anymore.
Which is exactly why the dovish "one and done" read is a misread. The market heard the accommodation line correctly even where the commentary didn't. This wasn't the end of a cycle dressed as a hike. It was the start of one, handed to you wrapped in relief.
The mispricing is the relief itself. What breaks it is the first serious person who asks: if he's not restrictive yet, what is it that makes him stop? #Fed #rates
Listen to the actual words. The hike removed "a dose of accommodation." Inflation is still "too high." Put those together and you get a chairman who believes current policy is still stimulating the economy, not restraining it. That's not a man planning to stop — it's a man explaining why he's only getting started.
This matters because of what he did to himself at Jackson Hole. He killed forward guidance, called it a practice that "overstayed its welcome," committed to "a discipline, not a decision." So there's no path to lean on, no promise to anchor expectations. Every meeting is genuinely live, and the work of figuring out the trajectory falls entirely on the market. There's no committee hand to hold anymore.
Which is exactly why the dovish "one and done" read is a misread. The market heard the accommodation line correctly even where the commentary didn't. This wasn't the end of a cycle dressed as a hike. It was the start of one, handed to you wrapped in relief.
The mispricing is the relief itself. What breaks it is the first serious person who asks: if he's not restrictive yet, what is it that makes him stop? #Fed #rates
AngelOfCrypto_-:
nice
2
2
572
·
--
Verified
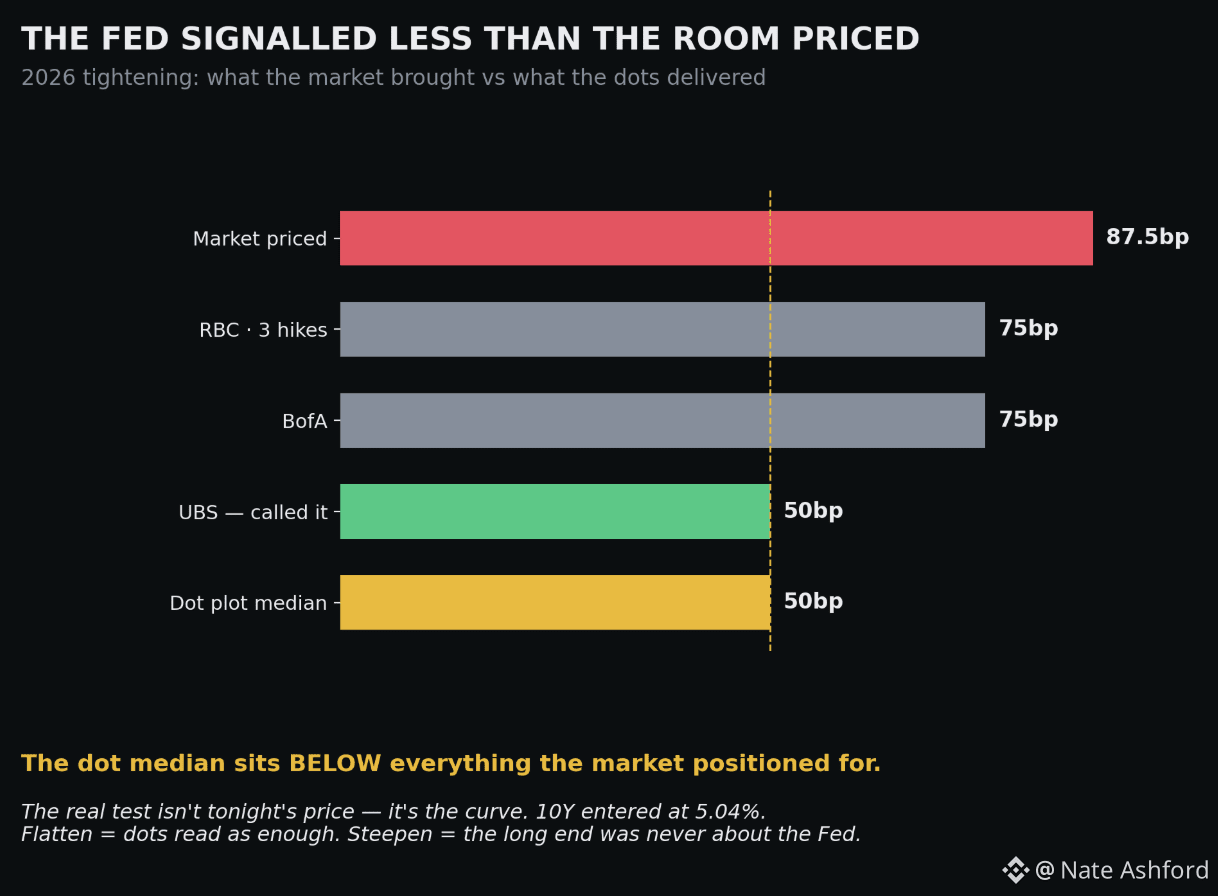
The Fed hiked 25bp to 3.75-4%. First increase since 2023. The rate was never the story.
The dot plot was. The median points to just one more hike this year — 50bp total. Now line that up against what the market brought into the room: BofA at 75, RBC at three hikes, the curve hedging ~87.5bp. The Fed just signalled LESS than everyone positioned for.
On this feed all week: with a hike 94% priced, the only tradeable surprise lived in the dots. It came in dovish. Warsh solved his own problem — he killed forward guidance at Jackson Hole, then used the dot plot to walk back excessive pricing without ever "guiding." Impersonal, deniable, effective.
But here's the real test, and it isn't the price reaction tonight. It's the curve. The 10-year walked in at 5.04%. If a dovish Fed FLATTENS it, the market read the dots as enough. If it STEEPENS — long yields rising even as the short rate went up — then bond investors are demanding a risk premium the Fed can't control, and the 5% story was never about the Fed at all.
Watch the 10-year minus the 2-year tonight. That spread, not the headline, tells you who won. #Fed #rates
The Fed hiked 25bp to 3.75-4%. First increase since 2023. The rate was never the story.
The dot plot was. The median points to just one more hike this year — 50bp total. Now line that up against what the market brought into the room: BofA at 75, RBC at three hikes, the curve hedging ~87.5bp. The Fed just signalled LESS than everyone positioned for.
On this feed all week: with a hike 94% priced, the only tradeable surprise lived in the dots. It came in dovish. Warsh solved his own problem — he killed forward guidance at Jackson Hole, then used the dot plot to walk back excessive pricing without ever "guiding." Impersonal, deniable, effective.
But here's the real test, and it isn't the price reaction tonight. It's the curve. The 10-year walked in at 5.04%. If a dovish Fed FLATTENS it, the market read the dots as enough. If it STEEPENS — long yields rising even as the short rate went up — then bond investors are demanding a risk premium the Fed can't control, and the 5% story was never about the Fed at all.
Watch the 10-year minus the 2-year tonight. That spread, not the headline, tells you who won. #Fed #rates
The dot plot was. The median points to just one more hike this year — 50bp total. Now line that up against what the market brought into the room: BofA at 75, RBC at three hikes, the curve hedging ~87.5bp. The Fed just signalled LESS than everyone positioned for.
On this feed all week: with a hike 94% priced, the only tradeable surprise lived in the dots. It came in dovish. Warsh solved his own problem — he killed forward guidance at Jackson Hole, then used the dot plot to walk back excessive pricing without ever "guiding." Impersonal, deniable, effective.
But here's the real test, and it isn't the price reaction tonight. It's the curve. The 10-year walked in at 5.04%. If a dovish Fed FLATTENS it, the market read the dots as enough. If it STEEPENS — long yields rising even as the short rate went up — then bond investors are demanding a risk premium the Fed can't control, and the 5% story was never about the Fed at all.
Watch the 10-year minus the 2-year tonight. That spread, not the headline, tells you who won. #Fed #rates
AngelOfCrypto_-:
nice
3
3
2.4k
·
--
Partly True
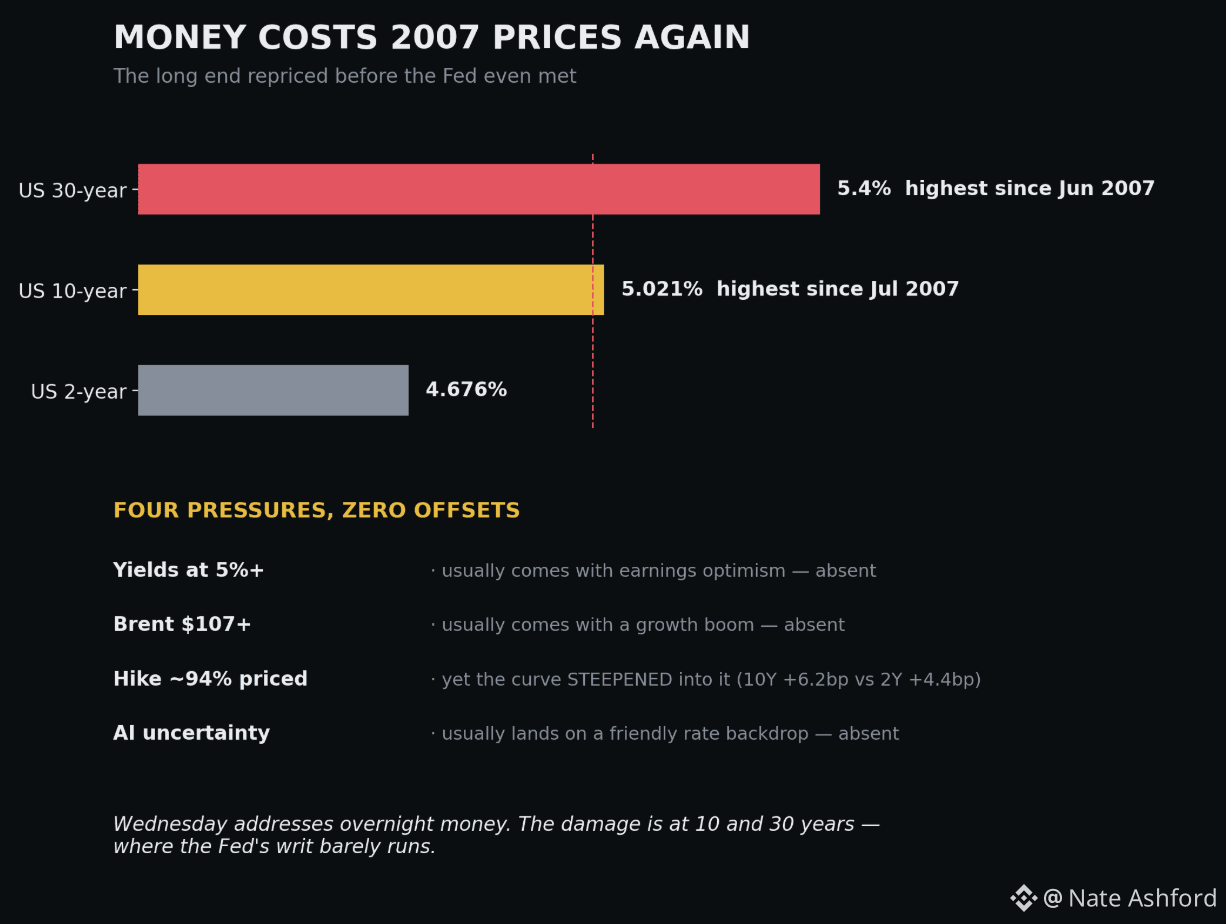
5.04%. The 10-year just printed its highest yield since July 2007. The 30-year at 5.40%, also a 2007 number. The long end didn't wait for Wednesday.
On this feed for weeks: the story was never the hike, it was the long bond quietly repricing what money costs. Today it stopped being quiet.
Here's the detail that matters most. Markets price 94% odds of tomorrow's hike — and the curve STEEPENED into it, the 10-year rising faster than the 2-year. A hike should calm the long end. It isn't. Because the long end isn't trading the Fed anymore: it's trading debt supply, the fiscal path, and an AI capex boom borrowing against the same pool of capital. Only one of those ends when the tightening cycle does.
Four pressures at once — 5% yields, $107 Brent, a priced hike, AI doubt — and the real problem is what's missing: every offset that usually cushions one of them. Energy shocks usually come with growth. Rising yields usually come with earnings optimism. Neither is on the table.
Wednesday addresses overnight money. The damage is being done at the far end of the curve, where the Fed's writ barely runs. #rates #Fed
5.04%. The 10-year just printed its highest yield since July 2007. The 30-year at 5.40%, also a 2007 number. The long end didn't wait for Wednesday.
On this feed for weeks: the story was never the hike, it was the long bond quietly repricing what money costs. Today it stopped being quiet.
Here's the detail that matters most. Markets price 94% odds of tomorrow's hike — and the curve STEEPENED into it, the 10-year rising faster than the 2-year. A hike should calm the long end. It isn't. Because the long end isn't trading the Fed anymore: it's trading debt supply, the fiscal path, and an AI capex boom borrowing against the same pool of capital. Only one of those ends when the tightening cycle does.
Four pressures at once — 5% yields, $107 Brent, a priced hike, AI doubt — and the real problem is what's missing: every offset that usually cushions one of them. Energy shocks usually come with growth. Rising yields usually come with earnings optimism. Neither is on the table.
Wednesday addresses overnight money. The damage is being done at the far end of the curve, where the Fed's writ barely runs. #rates #Fed
On this feed for weeks: the story was never the hike, it was the long bond quietly repricing what money costs. Today it stopped being quiet.
Here's the detail that matters most. Markets price 94% odds of tomorrow's hike — and the curve STEEPENED into it, the 10-year rising faster than the 2-year. A hike should calm the long end. It isn't. Because the long end isn't trading the Fed anymore: it's trading debt supply, the fiscal path, and an AI capex boom borrowing against the same pool of capital. Only one of those ends when the tightening cycle does.
Four pressures at once — 5% yields, $107 Brent, a priced hike, AI doubt — and the real problem is what's missing: every offset that usually cushions one of them. Energy shocks usually come with growth. Rising yields usually come with earnings optimism. Neither is on the table.
Wednesday addresses overnight money. The damage is being done at the far end of the curve, where the Fed's writ barely runs. #rates #Fed
AngelOfCrypto_-:
nice
3
2
1.3k

·
--
🚨 Multiple banks expect the Fed to raise rates by 25 basis points tomorrow 🧠
📊 | $BTC | $ETH | $BNB |
-Please watch, like, and leave a comment to discuss and share your views 📈
-The Federal Reserve will raise rates by 25 basis points on September 16.
-13 banks, including Goldman Sachs and Morgan Stanley, are expecting this move.
-It is expected that the market will face downward pressure and panic-driven volatility.
-Whales may accumulate during distribution or during the downtrend. 🔥
-The market may see further declines, with volatility increasing.
-Whales may continue to allocate assets at low levels.
-In the short term, a strengthening USD/interest rates could put pressure on the crypto market.
-It is expected that weekend trading volume will drop, and technical indicators show strengthening selling pressure.
-How do you think the rate hike will affect the short-term trend of crypto assets?
-Feel free to follow and share your views in the comments.
#Crypto #ETF #Whales #Market #Rates
🚨 Multiple banks expect the Fed to raise rates by 25 basis points tomorrow 🧠
📊 | $BTC | $ETH | $BNB |
-Please watch, like, and leave a comment to discuss and share your views 📈
-The Federal Reserve will raise rates by 25 basis points on September 16.
-13 banks, including Goldman Sachs and Morgan Stanley, are expecting this move.
-It is expected that the market will face downward pressure and panic-driven volatility.
-Whales may accumulate during distribution or during the downtrend. 🔥
-The market may see further declines, with volatility increasing.
-Whales may continue to allocate assets at low levels.
-In the short term, a strengthening USD/interest rates could put pressure on the crypto market.
-It is expected that weekend trading volume will drop, and technical indicators show strengthening selling pressure.
-How do you think the rate hike will affect the short-term trend of crypto assets?
-Feel free to follow and share your views in the comments.
#Crypto #ETF #Whales #Market #Rates
📊 | $BTC | $ETH | $BNB |
-Please watch, like, and leave a comment to discuss and share your views 📈
-The Federal Reserve will raise rates by 25 basis points on September 16.
-13 banks, including Goldman Sachs and Morgan Stanley, are expecting this move.
-It is expected that the market will face downward pressure and panic-driven volatility.
-Whales may accumulate during distribution or during the downtrend. 🔥
-The market may see further declines, with volatility increasing.
-Whales may continue to allocate assets at low levels.
-In the short term, a strengthening USD/interest rates could put pressure on the crypto market.
-It is expected that weekend trading volume will drop, and technical indicators show strengthening selling pressure.
-How do you think the rate hike will affect the short-term trend of crypto assets?
-Feel free to follow and share your views in the comments.
#Crypto #ETF #Whales #Market #Rates
126
·
--
Verified
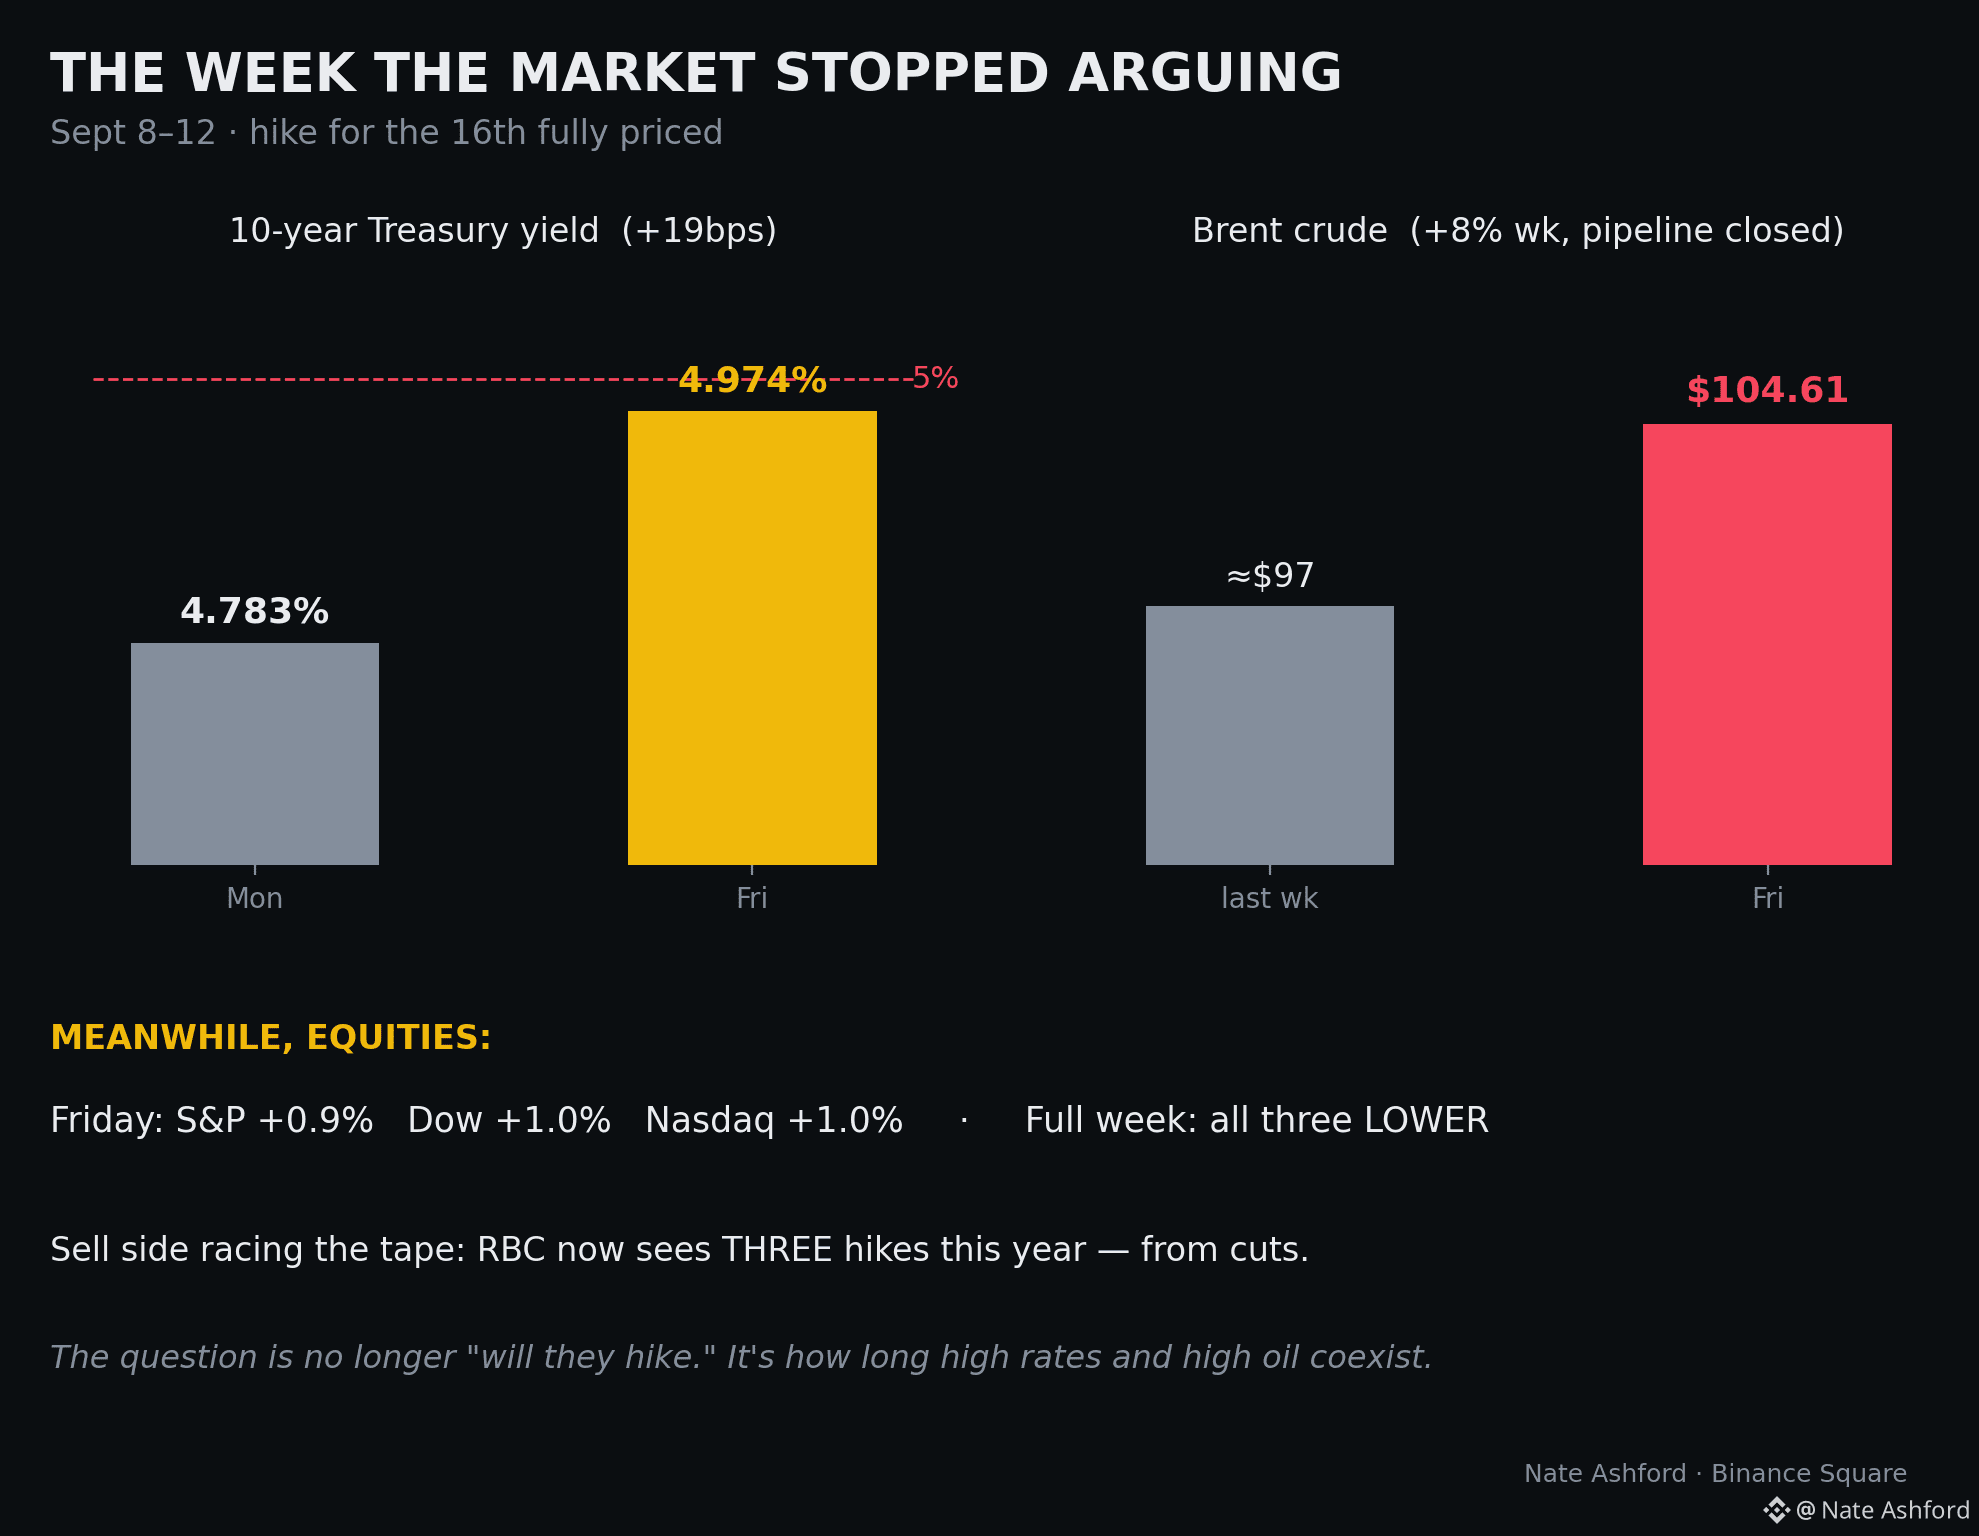
The week the market stopped arguing. Core CPI hot, hike locked for the 16th — and stocks rallied Friday on the certainty itself. S&P +0.9%, Dow +1%, Nasdaq +1%. All three still down on the week.
The bond market kept score differently: 10-year at 4.974%, from 4.783% a week ago. Nineteen basis points in five sessions, knocking on 5%.
And the sell side is now racing the tape — RBC has gone from cuts this year to THREE hikes. That's not a forecast revision. That's a regime acknowledgment.
Add Brent at $104.61, up 8% on the week with the East-West pipeline closed, and Wall Street's question has properly changed. Not "will they hike." How long do high rates and high oil coexist before something in earnings gives.
That question doesn't resolve on the 16th. It starts there. #Fed #rates
The week the market stopped arguing. Core CPI hot, hike locked for the 16th — and stocks rallied Friday on the certainty itself. S&P +0.9%, Dow +1%, Nasdaq +1%. All three still down on the week.
The bond market kept score differently: 10-year at 4.974%, from 4.783% a week ago. Nineteen basis points in five sessions, knocking on 5%.
And the sell side is now racing the tape — RBC has gone from cuts this year to THREE hikes. That's not a forecast revision. That's a regime acknowledgment.
Add Brent at $104.61, up 8% on the week with the East-West pipeline closed, and Wall Street's question has properly changed. Not "will they hike." How long do high rates and high oil coexist before something in earnings gives.
That question doesn't resolve on the 16th. It starts there. #Fed #rates
The bond market kept score differently: 10-year at 4.974%, from 4.783% a week ago. Nineteen basis points in five sessions, knocking on 5%.
And the sell side is now racing the tape — RBC has gone from cuts this year to THREE hikes. That's not a forecast revision. That's a regime acknowledgment.
Add Brent at $104.61, up 8% on the week with the East-West pipeline closed, and Wall Street's question has properly changed. Not "will they hike." How long do high rates and high oil coexist before something in earnings gives.
That question doesn't resolve on the 16th. It starts there. #Fed #rates
1
574
·
--
Another week, another AI infrastructure deal — Amazon backing Qualcomm into data center chips, with up to $4B in equity attached.
Add the running total: two labs alone have contracted compute implying $500B to $750B of spend this decade. Now the chip layer is spawning funded competitors.
Here's why this belongs on a macro feed. Williams named the drivers of high yields two weeks ago: strong economy, robust investment demand. This is the investment demand. Capex at this scale is a structural bid for capital that keeps real rates elevated no matter what the Fed does on the 16th.
The long bond has held above 5% for weeks. Everyone argues about the Fed. Almost nobody prices the simpler force: the biggest industrial buildout since the postwar era, all of it borrowing and spending at once.
The AI trade isn't just in equities. It's in your discount rate. #rates #macro
Another week, another AI infrastructure deal — Amazon backing Qualcomm into data center chips, with up to $4B in equity attached.
Add the running total: two labs alone have contracted compute implying $500B to $750B of spend this decade. Now the chip layer is spawning funded competitors.
Here's why this belongs on a macro feed. Williams named the drivers of high yields two weeks ago: strong economy, robust investment demand. This is the investment demand. Capex at this scale is a structural bid for capital that keeps real rates elevated no matter what the Fed does on the 16th.
The long bond has held above 5% for weeks. Everyone argues about the Fed. Almost nobody prices the simpler force: the biggest industrial buildout since the postwar era, all of it borrowing and spending at once.
The AI trade isn't just in equities. It's in your discount rate. #rates #macro
Add the running total: two labs alone have contracted compute implying $500B to $750B of spend this decade. Now the chip layer is spawning funded competitors.
Here's why this belongs on a macro feed. Williams named the drivers of high yields two weeks ago: strong economy, robust investment demand. This is the investment demand. Capex at this scale is a structural bid for capital that keeps real rates elevated no matter what the Fed does on the 16th.
The long bond has held above 5% for weeks. Everyone argues about the Fed. Almost nobody prices the simpler force: the biggest industrial buildout since the postwar era, all of it borrowing and spending at once.
The AI trade isn't just in equities. It's in your discount rate. #rates #macro
391
·
--
Verified
Payrolls: 162K. Unemployment steady at 4.1%. After a negative July, the labor market just voted, and it voted strong.
On the record all week here: weak data was the only thing that could stop this hike, and a positive print settles it. So it went. Odds at 58.4% for the 16th, and the sell side is falling in line — UBS now sees hikes in September AND December, Macquarie and BofA moving the same way. The debate Waller opened is losing to the data.
But the real story now isn't the market. It's the collision nobody's pricing. The White House is publicly pressing for CUTS — rates hurting competitiveness, housing affordability — at the exact moment the market prices a HIKE at 58%. Warsh is being pulled in opposite directions by his two audiences.
One of them has to be disappointed on the 16th. Central bank independence isn't a speech topic anymore. It's this meeting.
CPI on the 11th is the last input. #Fed #rates
Payrolls: 162K. Unemployment steady at 4.1%. After a negative July, the labor market just voted, and it voted strong.
On the record all week here: weak data was the only thing that could stop this hike, and a positive print settles it. So it went. Odds at 58.4% for the 16th, and the sell side is falling in line — UBS now sees hikes in September AND December, Macquarie and BofA moving the same way. The debate Waller opened is losing to the data.
But the real story now isn't the market. It's the collision nobody's pricing. The White House is publicly pressing for CUTS — rates hurting competitiveness, housing affordability — at the exact moment the market prices a HIKE at 58%. Warsh is being pulled in opposite directions by his two audiences.
One of them has to be disappointed on the 16th. Central bank independence isn't a speech topic anymore. It's this meeting.
CPI on the 11th is the last input. #Fed #rates
On the record all week here: weak data was the only thing that could stop this hike, and a positive print settles it. So it went. Odds at 58.4% for the 16th, and the sell side is falling in line — UBS now sees hikes in September AND December, Macquarie and BofA moving the same way. The debate Waller opened is losing to the data.
But the real story now isn't the market. It's the collision nobody's pricing. The White House is publicly pressing for CUTS — rates hurting competitiveness, housing affordability — at the exact moment the market prices a HIKE at 58%. Warsh is being pulled in opposite directions by his two audiences.
One of them has to be disappointed on the 16th. Central bank independence isn't a speech topic anymore. It's this meeting.
CPI on the 11th is the last input. #Fed #rates
1
1.5k

·
--
#FedHikeOddsRiseTo68%
CME FedWatch now prices a 68% chance the Fed hikes rates by 25 bps at the September 16 meeting. Just a week ago it was sitting under 40%.
What changed? Fed Chair Kevin Warsh went full hawk at Jackson Hole. He basically said inflation is still running nearly double the target and the current stance isn’t restrictive enough. Traders heard him loud and clear.
Oil is climbing, yields are rising, and the “soft landing + eventual cuts” narrative is getting shredded in real time.
This isn’t just a numbers game. Higher rates for longer hit mortgages, car loans, and business borrowing. Risk assets are already feeling the heat.
Two weeks of data left before the decision. One hot CPI print and 68% could turn into 80% real quick.
Are you still positioned for cuts… or have you already adjusted?
#Fed #Rates
#FedHikeOddsRiseTo68%
CME FedWatch now prices a 68% chance the Fed hikes rates by 25 bps at the September 16 meeting. Just a week ago it was sitting under 40%.
What changed? Fed Chair Kevin Warsh went full hawk at Jackson Hole. He basically said inflation is still running nearly double the target and the current stance isn’t restrictive enough. Traders heard him loud and clear.
Oil is climbing, yields are rising, and the “soft landing + eventual cuts” narrative is getting shredded in real time.
This isn’t just a numbers game. Higher rates for longer hit mortgages, car loans, and business borrowing. Risk assets are already feeling the heat.
Two weeks of data left before the decision. One hot CPI print and 68% could turn into 80% real quick.
Are you still positioned for cuts… or have you already adjusted?
#Fed #Rates
CME FedWatch now prices a 68% chance the Fed hikes rates by 25 bps at the September 16 meeting. Just a week ago it was sitting under 40%.
What changed? Fed Chair Kevin Warsh went full hawk at Jackson Hole. He basically said inflation is still running nearly double the target and the current stance isn’t restrictive enough. Traders heard him loud and clear.
Oil is climbing, yields are rising, and the “soft landing + eventual cuts” narrative is getting shredded in real time.
This isn’t just a numbers game. Higher rates for longer hit mortgages, car loans, and business borrowing. Risk assets are already feeling the heat.
Two weeks of data left before the decision. One hot CPI print and 68% could turn into 80% real quick.
Are you still positioned for cuts… or have you already adjusted?
#Fed #Rates
102
·
--
Verified
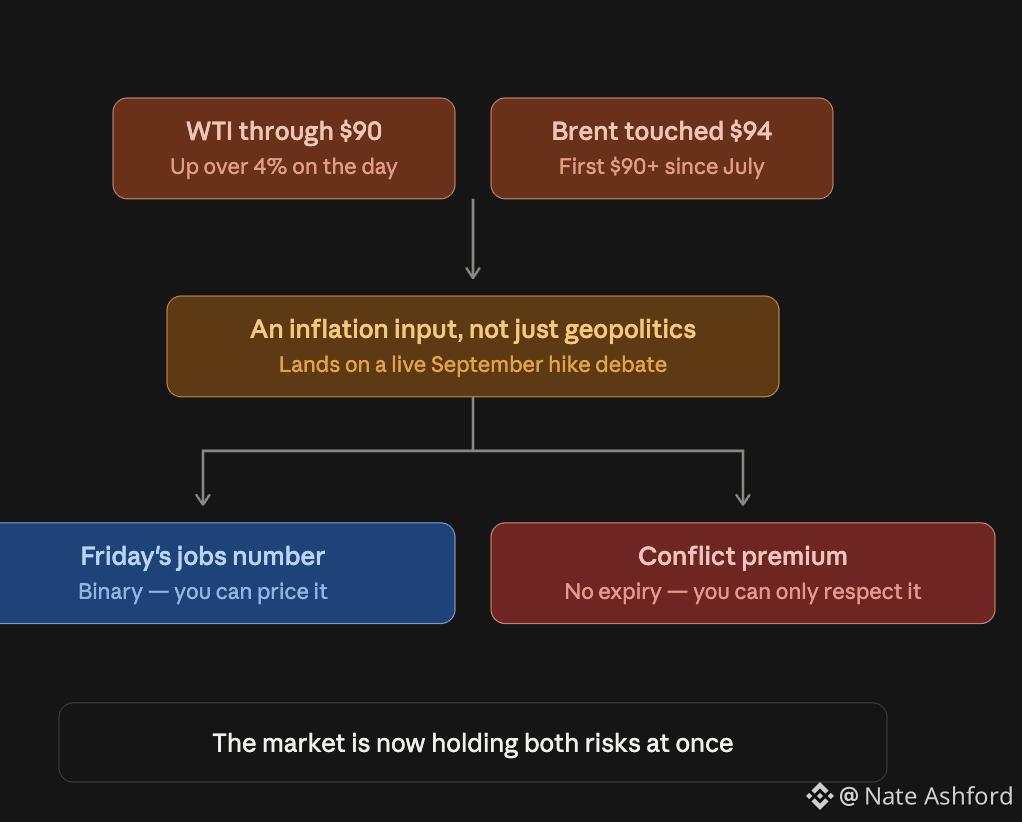
WTI through $90, up over 4% on the day. Brent touched $94. First time above $90 since late July.
The driver is on every front page. US-Iran escalation, missiles in the air, threats going both directions.
Here's what the oil move does that the headlines don't: it lands on a Fed already debating a September hike.
Crude up 4% in a session is an inflation input, not just a geopolitics story. The "hike is live" case just got a supply-side tailwind it didn't ask for.
So the market is now holding two risks at once. A binary jobs number Friday and an open-ended conflict premium with no expiry date.
One of those you can price. The other you can only respect. #macro #rates
WTI through $90, up over 4% on the day. Brent touched $94. First time above $90 since late July.
The driver is on every front page. US-Iran escalation, missiles in the air, threats going both directions.
Here's what the oil move does that the headlines don't: it lands on a Fed already debating a September hike.
Crude up 4% in a session is an inflation input, not just a geopolitics story. The "hike is live" case just got a supply-side tailwind it didn't ask for.
So the market is now holding two risks at once. A binary jobs number Friday and an open-ended conflict premium with no expiry date.
One of those you can price. The other you can only respect. #macro #rates
The driver is on every front page. US-Iran escalation, missiles in the air, threats going both directions.
Here's what the oil move does that the headlines don't: it lands on a Fed already debating a September hike.
Crude up 4% in a session is an inflation input, not just a geopolitics story. The "hike is live" case just got a supply-side tailwind it didn't ask for.
So the market is now holding two risks at once. A binary jobs number Friday and an open-ended conflict premium with no expiry date.
One of those you can price. The other you can only respect. #macro #rates
741
·
--
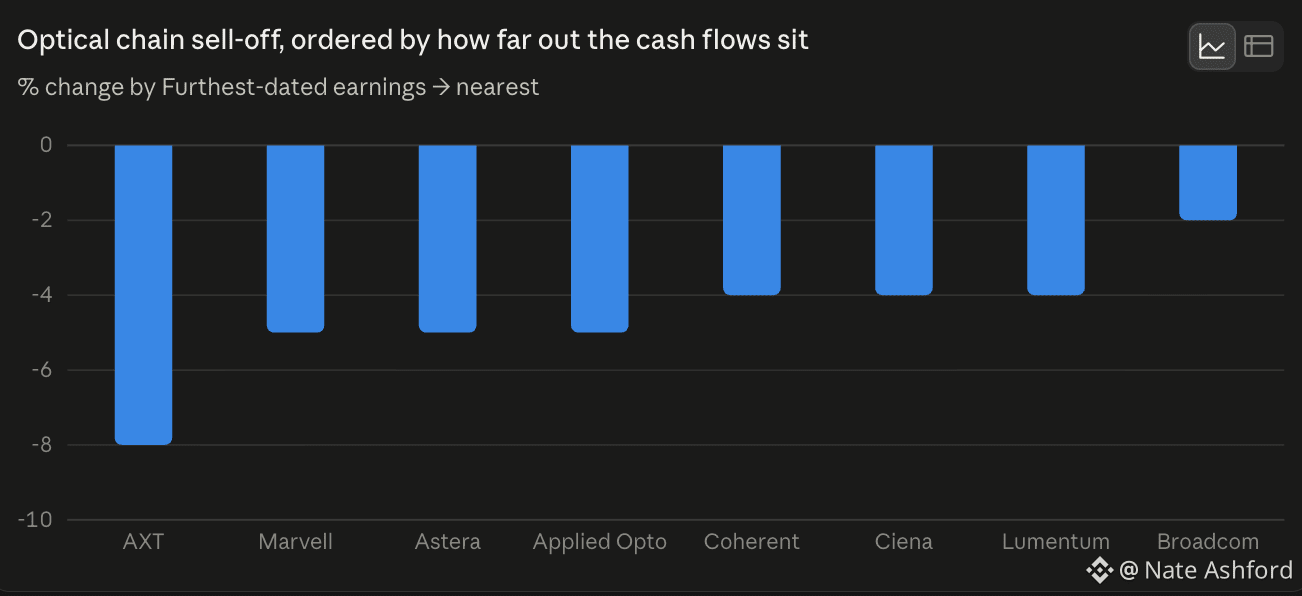
AXT down 8%. Marvell, Astera, Applied Opto down 5%. Coherent, Ciena, Lumentum down 4%. Broadcom off 2%.
That's the entire optical chain, in order of how far out the cash flows sit.
This isn't a sector story. It's a rates story with a semiconductor logo on it.
When a September hike is a coin flip, the first thing to get sold is anything priced on 2028 earnings. Optical is priced on 2028 earnings.
Notice Broadcom is the least bad. Biggest balance sheet, nearest cash flows. Same pattern as the Dow beating the Nasdaq this morning.
The AI trade isn't breaking. It's being discounted at a higher rate. Different thing. #rates #macro
AXT down 8%. Marvell, Astera, Applied Opto down 5%. Coherent, Ciena, Lumentum down 4%. Broadcom off 2%.
That's the entire optical chain, in order of how far out the cash flows sit.
This isn't a sector story. It's a rates story with a semiconductor logo on it.
When a September hike is a coin flip, the first thing to get sold is anything priced on 2028 earnings. Optical is priced on 2028 earnings.
Notice Broadcom is the least bad. Biggest balance sheet, nearest cash flows. Same pattern as the Dow beating the Nasdaq this morning.
The AI trade isn't breaking. It's being discounted at a higher rate. Different thing. #rates #macro
That's the entire optical chain, in order of how far out the cash flows sit.
This isn't a sector story. It's a rates story with a semiconductor logo on it.
When a September hike is a coin flip, the first thing to get sold is anything priced on 2028 earnings. Optical is priced on 2028 earnings.
Notice Broadcom is the least bad. Biggest balance sheet, nearest cash flows. Same pattern as the Dow beating the Nasdaq this morning.
The AI trade isn't breaking. It's being discounted at a higher rate. Different thing. #rates #macro
533
·
--
Nasdaq futures down 1% before the cash open. S&P off half a percent. Dow a touch less.
Nothing was released overnight. Read that again.
This is the hike-odds story from yesterday finding its way into equities. Rates traders repriced last week. Stock traders are catching up this morning.
Growth getting hit hardest is exactly what you'd expect if the market believes the Fed isn't done. Long-duration assets don't like a live September.
The tell is that the Dow is the least bad. That's a rates trade wearing an equity costume.
Payrolls Friday. Until then this is positioning, not news. #rates #macro
Nasdaq futures down 1% before the cash open. S&P off half a percent. Dow a touch less.
Nothing was released overnight. Read that again.
This is the hike-odds story from yesterday finding its way into equities. Rates traders repriced last week. Stock traders are catching up this morning.
Growth getting hit hardest is exactly what you'd expect if the market believes the Fed isn't done. Long-duration assets don't like a live September.
The tell is that the Dow is the least bad. That's a rates trade wearing an equity costume.
Payrolls Friday. Until then this is positioning, not news. #rates #macro
Nothing was released overnight. Read that again.
This is the hike-odds story from yesterday finding its way into equities. Rates traders repriced last week. Stock traders are catching up this morning.
Growth getting hit hardest is exactly what you'd expect if the market believes the Fed isn't done. Long-duration assets don't like a live September.
The tell is that the Dow is the least bad. That's a rates trade wearing an equity costume.
Payrolls Friday. Until then this is positioning, not news. #rates #macro
1
340
Over 98% odds the Fed holds in June — so don’t expect a “rate-cut pump” to save bad trades.
This is a patience market:
Risk assets can grind up… then snap on one hot CPI print.
Liquidity stays picky: quality wins, hype gets rugged.
Trade the chart, respect the macro, keep dry powder.
#Rates #Macro #Crypto #Altcoins!
#FedJuneRateHoldOver98Pct
Over 98% odds the Fed holds in June — so don’t expect a “rate-cut pump” to save bad trades.
This is a patience market:
Risk assets can grind up… then snap on one hot CPI print.
Liquidity stays picky: quality wins, hype gets rugged.
Trade the chart, respect the macro, keep dry powder.
#Rates #Macro #Crypto #Altcoins!
#FedJuneRateHoldOver98Pct
This is a patience market:
Risk assets can grind up… then snap on one hot CPI print.
Liquidity stays picky: quality wins, hype gets rugged.
Trade the chart, respect the macro, keep dry powder.
#Rates #Macro #Crypto #Altcoins!
#FedJuneRateHoldOver98Pct
146
·
--
Verified
Korea just sent the macro signal everyone's been arguing about, and it isn't in the price — it's in the participation. KOSPI turnover has halved from its peak. The AI retail wave that drove the rally is gone.
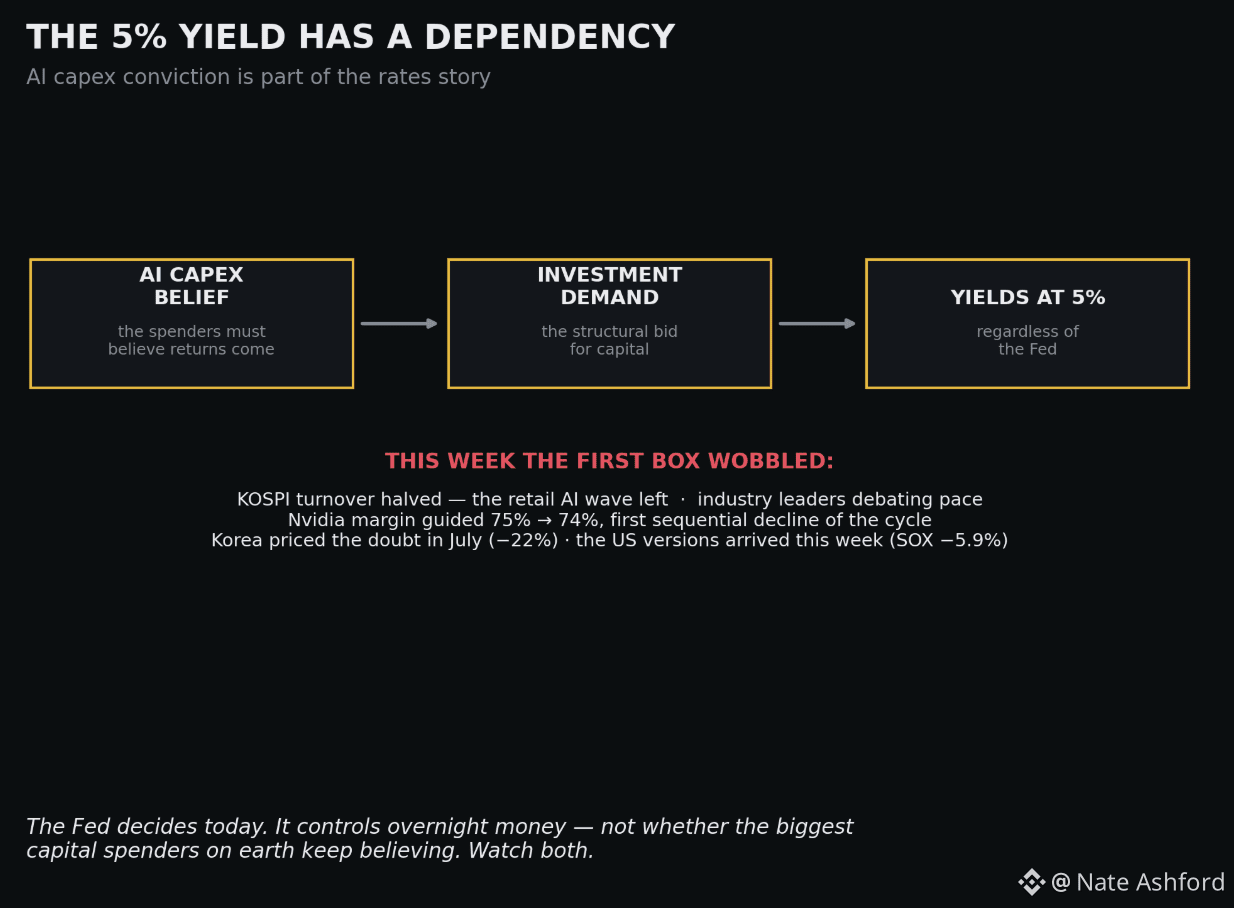
Why this belongs on a macro feed, today of all days. My standing argument: the AI buildout is a structural bid for capital — the investment demand holding real yields up regardless of the Fed. That thesis has a dependency: the spenders must believe the returns are coming.
This week the belief wobbled in public. Industry leaders debating whether to slow down. Nvidia guiding gross margin DOWN sequentially for the first time this cycle — costs rising faster than pricing. Korea's memory-heavy market registered the doubt in July, 22% worth; the US versions arrived this week, 5.9% in a session.
If capex conviction cracks, the yield story changes too — the "robust investment demand" leg under 5% Treasuries is the same trade as the KOSPI's missing volume.
The Fed decides in hours. It controls overnight money. It doesn't control whether the biggest capital spenders on earth keep believing. Watch both. #macro #rates
Korea just sent the macro signal everyone's been arguing about, and it isn't in the price — it's in the participation. KOSPI turnover has halved from its peak. The AI retail wave that drove the rally is gone.
Why this belongs on a macro feed, today of all days. My standing argument: the AI buildout is a structural bid for capital — the investment demand holding real yields up regardless of the Fed. That thesis has a dependency: the spenders must believe the returns are coming.
This week the belief wobbled in public. Industry leaders debating whether to slow down. Nvidia guiding gross margin DOWN sequentially for the first time this cycle — costs rising faster than pricing. Korea's memory-heavy market registered the doubt in July, 22% worth; the US versions arrived this week, 5.9% in a session.
If capex conviction cracks, the yield story changes too — the "robust investment demand" leg under 5% Treasuries is the same trade as the KOSPI's missing volume.
The Fed decides in hours. It controls overnight money. It doesn't control whether the biggest capital spenders on earth keep believing. Watch both. #macro #rates
Why this belongs on a macro feed, today of all days. My standing argument: the AI buildout is a structural bid for capital — the investment demand holding real yields up regardless of the Fed. That thesis has a dependency: the spenders must believe the returns are coming.
This week the belief wobbled in public. Industry leaders debating whether to slow down. Nvidia guiding gross margin DOWN sequentially for the first time this cycle — costs rising faster than pricing. Korea's memory-heavy market registered the doubt in July, 22% worth; the US versions arrived this week, 5.9% in a session.
If capex conviction cracks, the yield story changes too — the "robust investment demand" leg under 5% Treasuries is the same trade as the KOSPI's missing volume.
The Fed decides in hours. It controls overnight money. It doesn't control whether the biggest capital spenders on earth keep believing. Watch both. #macro #rates
AngelOfCrypto_-:
nice
2
2
600
·
--
📊 FOMC POLL: What’s the Fed’s next move?
With inflation still in focus, will the Fed stay hawkish—or surprise markets? 👀
$BTC
{future}(BTCUSDT)
#FedRateWatch #Rates #FOMOisReal
📊 FOMC POLL: What’s the Fed’s next move?
With inflation still in focus, will the Fed stay hawkish—or surprise markets? 👀
$BTC
#FedRateWatch #Rates #FOMOisReal
With inflation still in focus, will the Fed stay hawkish—or surprise markets? 👀
$BTC
#FedRateWatch #Rates #FOMOisReal
📉 Rate Cut
45%
⏸️ Hold Rates
22%
🔺 25bp Hike
33%
27 votes • Voting closed
1
2
3
452
·
--
China added 20 tons of gold in August. Reserves now 2,386 tons. That's 22 consecutive months of buying.
Twenty-two months is not a trade. It's a policy.
The context that gives it teeth: this run continued straight through gold's pullback, through a US hike debate, through everything. Central banks don't chase price. They accumulate against a scenario — and the scenario a 22-month gold bid hedges is less dollar dependence, fewer Treasury claims, sanction-proofing reserves.
Put it next to this week's other tape: the 10-year at 2023 highs, the long bond above 5% for weeks. The largest official buyers diversifying away from the paper the US needs to sell more of than ever. Those two facts are having a conversation, and yields are how it sounds.
Nobody announces a reserve regime change. It just shows up, 20 tons at a time. #macro #rates
China added 20 tons of gold in August. Reserves now 2,386 tons. That's 22 consecutive months of buying.
Twenty-two months is not a trade. It's a policy.
The context that gives it teeth: this run continued straight through gold's pullback, through a US hike debate, through everything. Central banks don't chase price. They accumulate against a scenario — and the scenario a 22-month gold bid hedges is less dollar dependence, fewer Treasury claims, sanction-proofing reserves.
Put it next to this week's other tape: the 10-year at 2023 highs, the long bond above 5% for weeks. The largest official buyers diversifying away from the paper the US needs to sell more of than ever. Those two facts are having a conversation, and yields are how it sounds.
Nobody announces a reserve regime change. It just shows up, 20 tons at a time. #macro #rates
Twenty-two months is not a trade. It's a policy.
The context that gives it teeth: this run continued straight through gold's pullback, through a US hike debate, through everything. Central banks don't chase price. They accumulate against a scenario — and the scenario a 22-month gold bid hedges is less dollar dependence, fewer Treasury claims, sanction-proofing reserves.
Put it next to this week's other tape: the 10-year at 2023 highs, the long bond above 5% for weeks. The largest official buyers diversifying away from the paper the US needs to sell more of than ever. Those two facts are having a conversation, and yields are how it sounds.
Nobody announces a reserve regime change. It just shows up, 20 tons at a time. #macro #rates
469
·
--
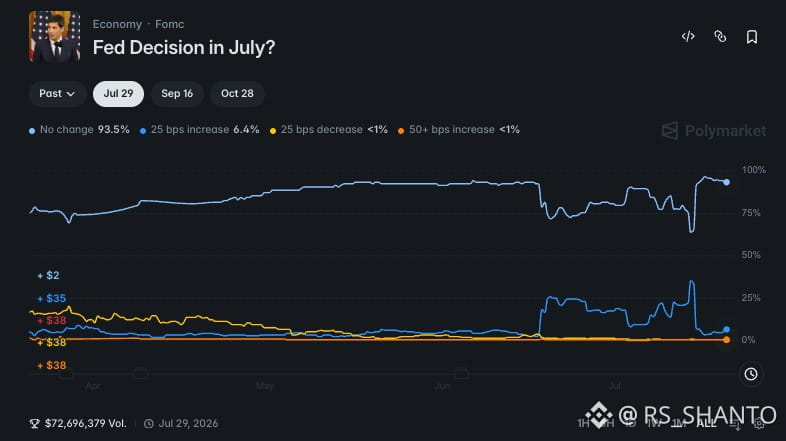
Quite a reversal to sit inside of. The 30-year backed off 5bps from the intraday high to 5.25%. Dow and S&P futures clawed back their losses and went green. Oil round-tripped from up 2% to down 1%.
All three moved together, and that's the tell. This was the conflict premium deflating, not a view change on the Fed.
One session of de-escalation trading. The hike odds didn't go anywhere.
Enjoy the green. The two events that matter — payrolls Friday, the Fed on the 16th — are still exactly where they were this morning. #rates #macro
Quite a reversal to sit inside of. The 30-year backed off 5bps from the intraday high to 5.25%. Dow and S&P futures clawed back their losses and went green. Oil round-tripped from up 2% to down 1%.
All three moved together, and that's the tell. This was the conflict premium deflating, not a view change on the Fed.
One session of de-escalation trading. The hike odds didn't go anywhere.
Enjoy the green. The two events that matter — payrolls Friday, the Fed on the 16th — are still exactly where they were this morning. #rates #macro
All three moved together, and that's the tell. This was the conflict premium deflating, not a view change on the Fed.
One session of de-escalation trading. The hike odds didn't go anywhere.
Enjoy the green. The two events that matter — payrolls Friday, the Fed on the 16th — are still exactly where they were this morning. #rates #macro
398
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BTCBreaks80K
133,594 views
2,106 Discussing
2
#SOLJumpsAbout10%
2,541 views
108 Discussing
3
#EthereumReclaims$2600
330 views
26 Discussing
4
#SECReceivesAmendedInjectiveETFFiling
2,816 views
145 Discussing
5
#SanDiskToJoinSP100OnSep21
1,727 views
86 Discussing
6
#PolygonToDeployContractBurning100MPOL
1,372 views
68 Discussing
7
#TRMReportsYouTubeScamStole274.6ETH
158 views
14 Discussing
8
#YahooFinanceEndsPolymarketPartnership
811 views
20 Discussing
9
#BuffettBecomesBerkshireChairmanEmeritus
34,444 views
673 Discussing
10
#ZcashSpotETFTops$230MMonthlyInflow
7,652 views
86 Discussing