
#fedproposesrulesforbankissuedstablecoins
fedproposesrulesforbankissuedstablecoins
59,059 views
643 Discussing
Hot
Latest

·
--
Bullish
Verified
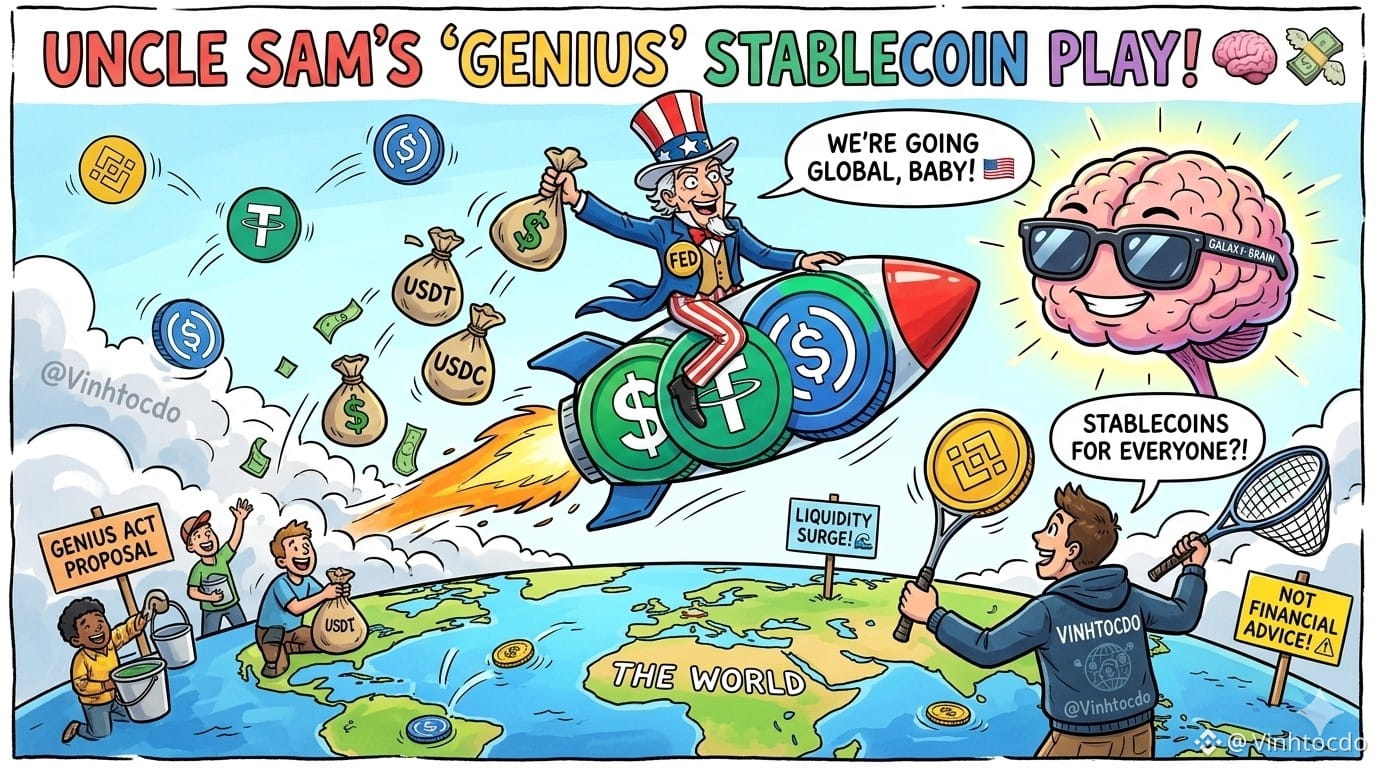
🚀 Fed is pushing Stablecoins global, and it’s pure #Genius !
So the Fed just dropped two proposals under the GENIUS Act to regulate and let banks issue stablecoins. 🧠 Uncle Sam isn’t trying to ban crypto anymore—he’s trying to export the US Dollar everywhere through blockchain! Talk about a galaxy-brain move. 💸
What should traders do?
Don't panic sell your bags. Volatility is just a side quest. Keep your stablecoins locked and loaded, stick to top-tier assets, and stay sharp for the liquidity surge! 🌊
Click to trade below to support me:
👉 $BTC
{future}(BTCUSDT)
|$ETH
{future}(ETHUSDT)
| $BNB
{future}(BNBUSDT)
🔥 New to Binance? Grab your special trading discounts!
Use Referral Code: VINHTOCDO
Or join here: [https://www.binance.com/register?ref=VINHTOCDO](https://www.binance.com/register?ref=VINHTOCDO)
⚠️ Disclaimer: This is absolutely NOT financial advice. Always do your own research!
#FedProposesRulesForBankIssuedStablecoins #VINHTOCDO #FedNews #stablecoin #CryptoTrading #USDC
🚀 Fed is pushing Stablecoins global, and it’s pure #Genius !
So the Fed just dropped two proposals under the GENIUS Act to regulate and let banks issue stablecoins. 🧠 Uncle Sam isn’t trying to ban crypto anymore—he’s trying to export the US Dollar everywhere through blockchain! Talk about a galaxy-brain move. 💸
What should traders do?
Don't panic sell your bags. Volatility is just a side quest. Keep your stablecoins locked and loaded, stick to top-tier assets, and stay sharp for the liquidity surge! 🌊
Click to trade below to support me:
👉 $BTC
|$ETH
| $BNB
🔥 New to Binance? Grab your special trading discounts!
Use Referral Code: VINHTOCDO
Or join here: https://www.binance.com/register?ref=VINHTOCDO
⚠️ Disclaimer: This is absolutely NOT financial advice. Always do your own research!
#FedProposesRulesForBankIssuedStablecoins #VINHTOCDO #FedNews #stablecoin #CryptoTrading #USDC
So the Fed just dropped two proposals under the GENIUS Act to regulate and let banks issue stablecoins. 🧠 Uncle Sam isn’t trying to ban crypto anymore—he’s trying to export the US Dollar everywhere through blockchain! Talk about a galaxy-brain move. 💸
What should traders do?
Don't panic sell your bags. Volatility is just a side quest. Keep your stablecoins locked and loaded, stick to top-tier assets, and stay sharp for the liquidity surge! 🌊
Click to trade below to support me:
👉 $BTC
|$ETH
| $BNB
🔥 New to Binance? Grab your special trading discounts!
Use Referral Code: VINHTOCDO
Or join here: https://www.binance.com/register?ref=VINHTOCDO
⚠️ Disclaimer: This is absolutely NOT financial advice. Always do your own research!
#FedProposesRulesForBankIssuedStablecoins #VINHTOCDO #FedNews #stablecoin #CryptoTrading #USDC
2
4
160
·
--
#fedproposesrulesforbankissuedstablecoins
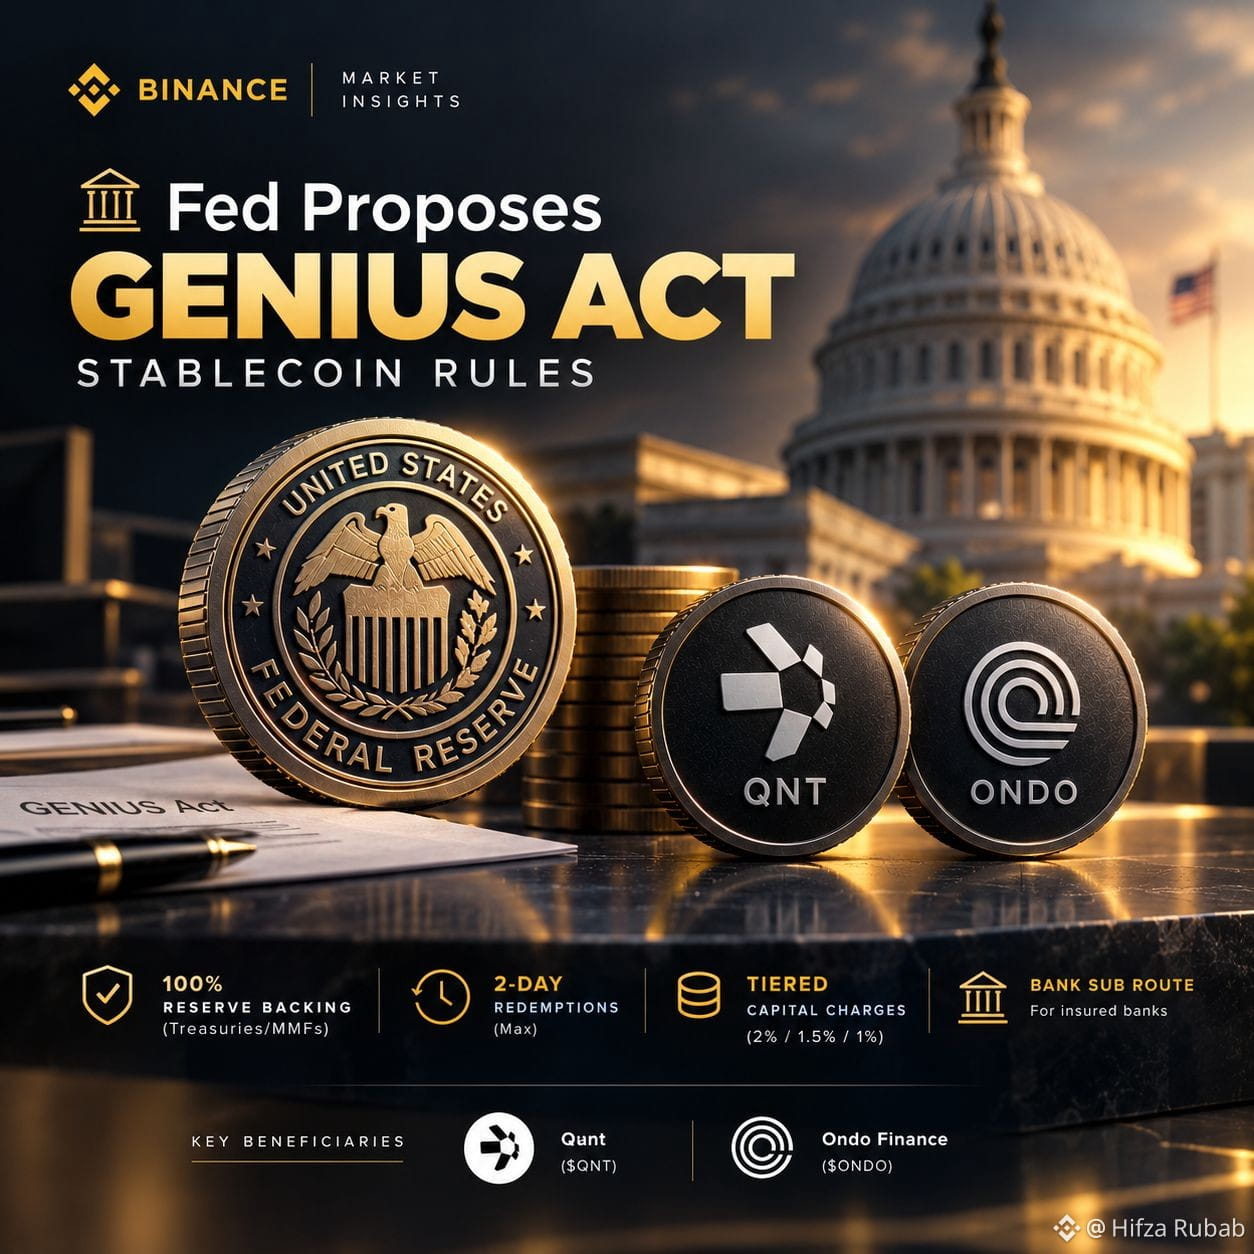
🏛️ Fed Proposes GENIUS Act Stablecoin Rules 💳🌐🚀
The US Federal Reserve 🏛️ has unveiled two major proposed rules under the GENIUS Act 📑:
100% Reserve Backing: Full liquid asset backing 💵 (Treasuries/MMFs) with monthly audits 📊 and CEO/CFO certification 📝.
Max 2-Day Redemptions: Issuers must process redemption requests within two business days ⏱️.
Tiered Capital Charges: 2% capital charge on the first $20B, 1.5% on the next $30B, and 1% above $50B 💰.
Bank Sub Route: Gives insured banks 🏦 a formal approval process to issue payment stablecoins via subsidiaries ⚡.
Key Beneficiaries🪙:
Quant ($QNT ) 🌐: Interoperability layer connecting traditional banks with tokenized assets.
Ondo Finance ($ONDO ) 🏛️: Real-world asset (RWA) protocol benefiting from institutional tokenized Treasuries.
💬 What's your take? Will strict compliance build Wall Street trust 🎯 or block smaller Web3 issuers 🛑? Drop your thoughts below! 👇✨
#FedProposesRulesForBankIssuedStablecoins
#BinanceWillListHyperliquid(HYPE)
#CFTCUpdatesGuidanceOnTokenizedAssets
#BitcoinFallsBelow$83,000
{spot}(ONDOUSDT)
{spot}(QNTUSDT)
#fedproposesrulesforbankissuedstablecoins
🏛️ Fed Proposes GENIUS Act Stablecoin Rules 💳🌐🚀
The US Federal Reserve 🏛️ has unveiled two major proposed rules under the GENIUS Act 📑:
100% Reserve Backing: Full liquid asset backing 💵 (Treasuries/MMFs) with monthly audits 📊 and CEO/CFO certification 📝.
Max 2-Day Redemptions: Issuers must process redemption requests within two business days ⏱️.
Tiered Capital Charges: 2% capital charge on the first $20B, 1.5% on the next $30B, and 1% above $50B 💰.
Bank Sub Route: Gives insured banks 🏦 a formal approval process to issue payment stablecoins via subsidiaries ⚡.
Key Beneficiaries🪙:
Quant ($QNT ) 🌐: Interoperability layer connecting traditional banks with tokenized assets.
Ondo Finance ($ONDO ) 🏛️: Real-world asset (RWA) protocol benefiting from institutional tokenized Treasuries.
💬 What's your take? Will strict compliance build Wall Street trust 🎯 or block smaller Web3 issuers 🛑? Drop your thoughts below! 👇✨
#FedProposesRulesForBankIssuedStablecoins
#BinanceWillListHyperliquid(HYPE)
#CFTCUpdatesGuidanceOnTokenizedAssets
#BitcoinFallsBelow$83,000
🏛️ Fed Proposes GENIUS Act Stablecoin Rules 💳🌐🚀
The US Federal Reserve 🏛️ has unveiled two major proposed rules under the GENIUS Act 📑:
100% Reserve Backing: Full liquid asset backing 💵 (Treasuries/MMFs) with monthly audits 📊 and CEO/CFO certification 📝.
Max 2-Day Redemptions: Issuers must process redemption requests within two business days ⏱️.
Tiered Capital Charges: 2% capital charge on the first $20B, 1.5% on the next $30B, and 1% above $50B 💰.
Bank Sub Route: Gives insured banks 🏦 a formal approval process to issue payment stablecoins via subsidiaries ⚡.
Key Beneficiaries🪙:
Quant ($QNT ) 🌐: Interoperability layer connecting traditional banks with tokenized assets.
Ondo Finance ($ONDO ) 🏛️: Real-world asset (RWA) protocol benefiting from institutional tokenized Treasuries.
💬 What's your take? Will strict compliance build Wall Street trust 🎯 or block smaller Web3 issuers 🛑? Drop your thoughts below! 👇✨
#FedProposesRulesForBankIssuedStablecoins
#BinanceWillListHyperliquid(HYPE)
#CFTCUpdatesGuidanceOnTokenizedAssets
#BitcoinFallsBelow$83,000
6
7
4.3k
·
--
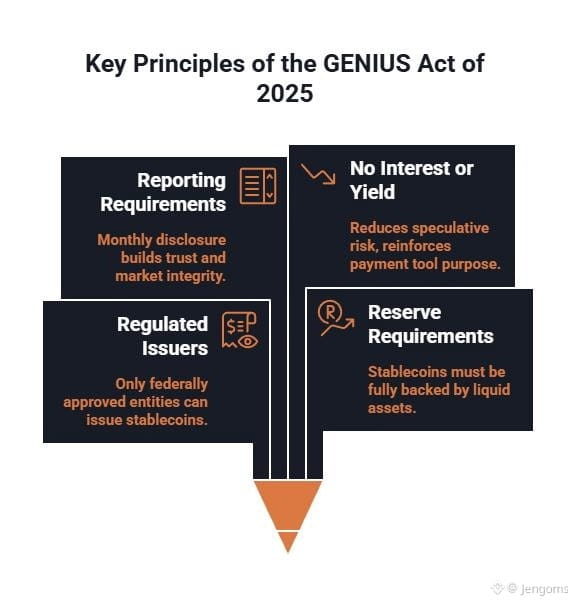
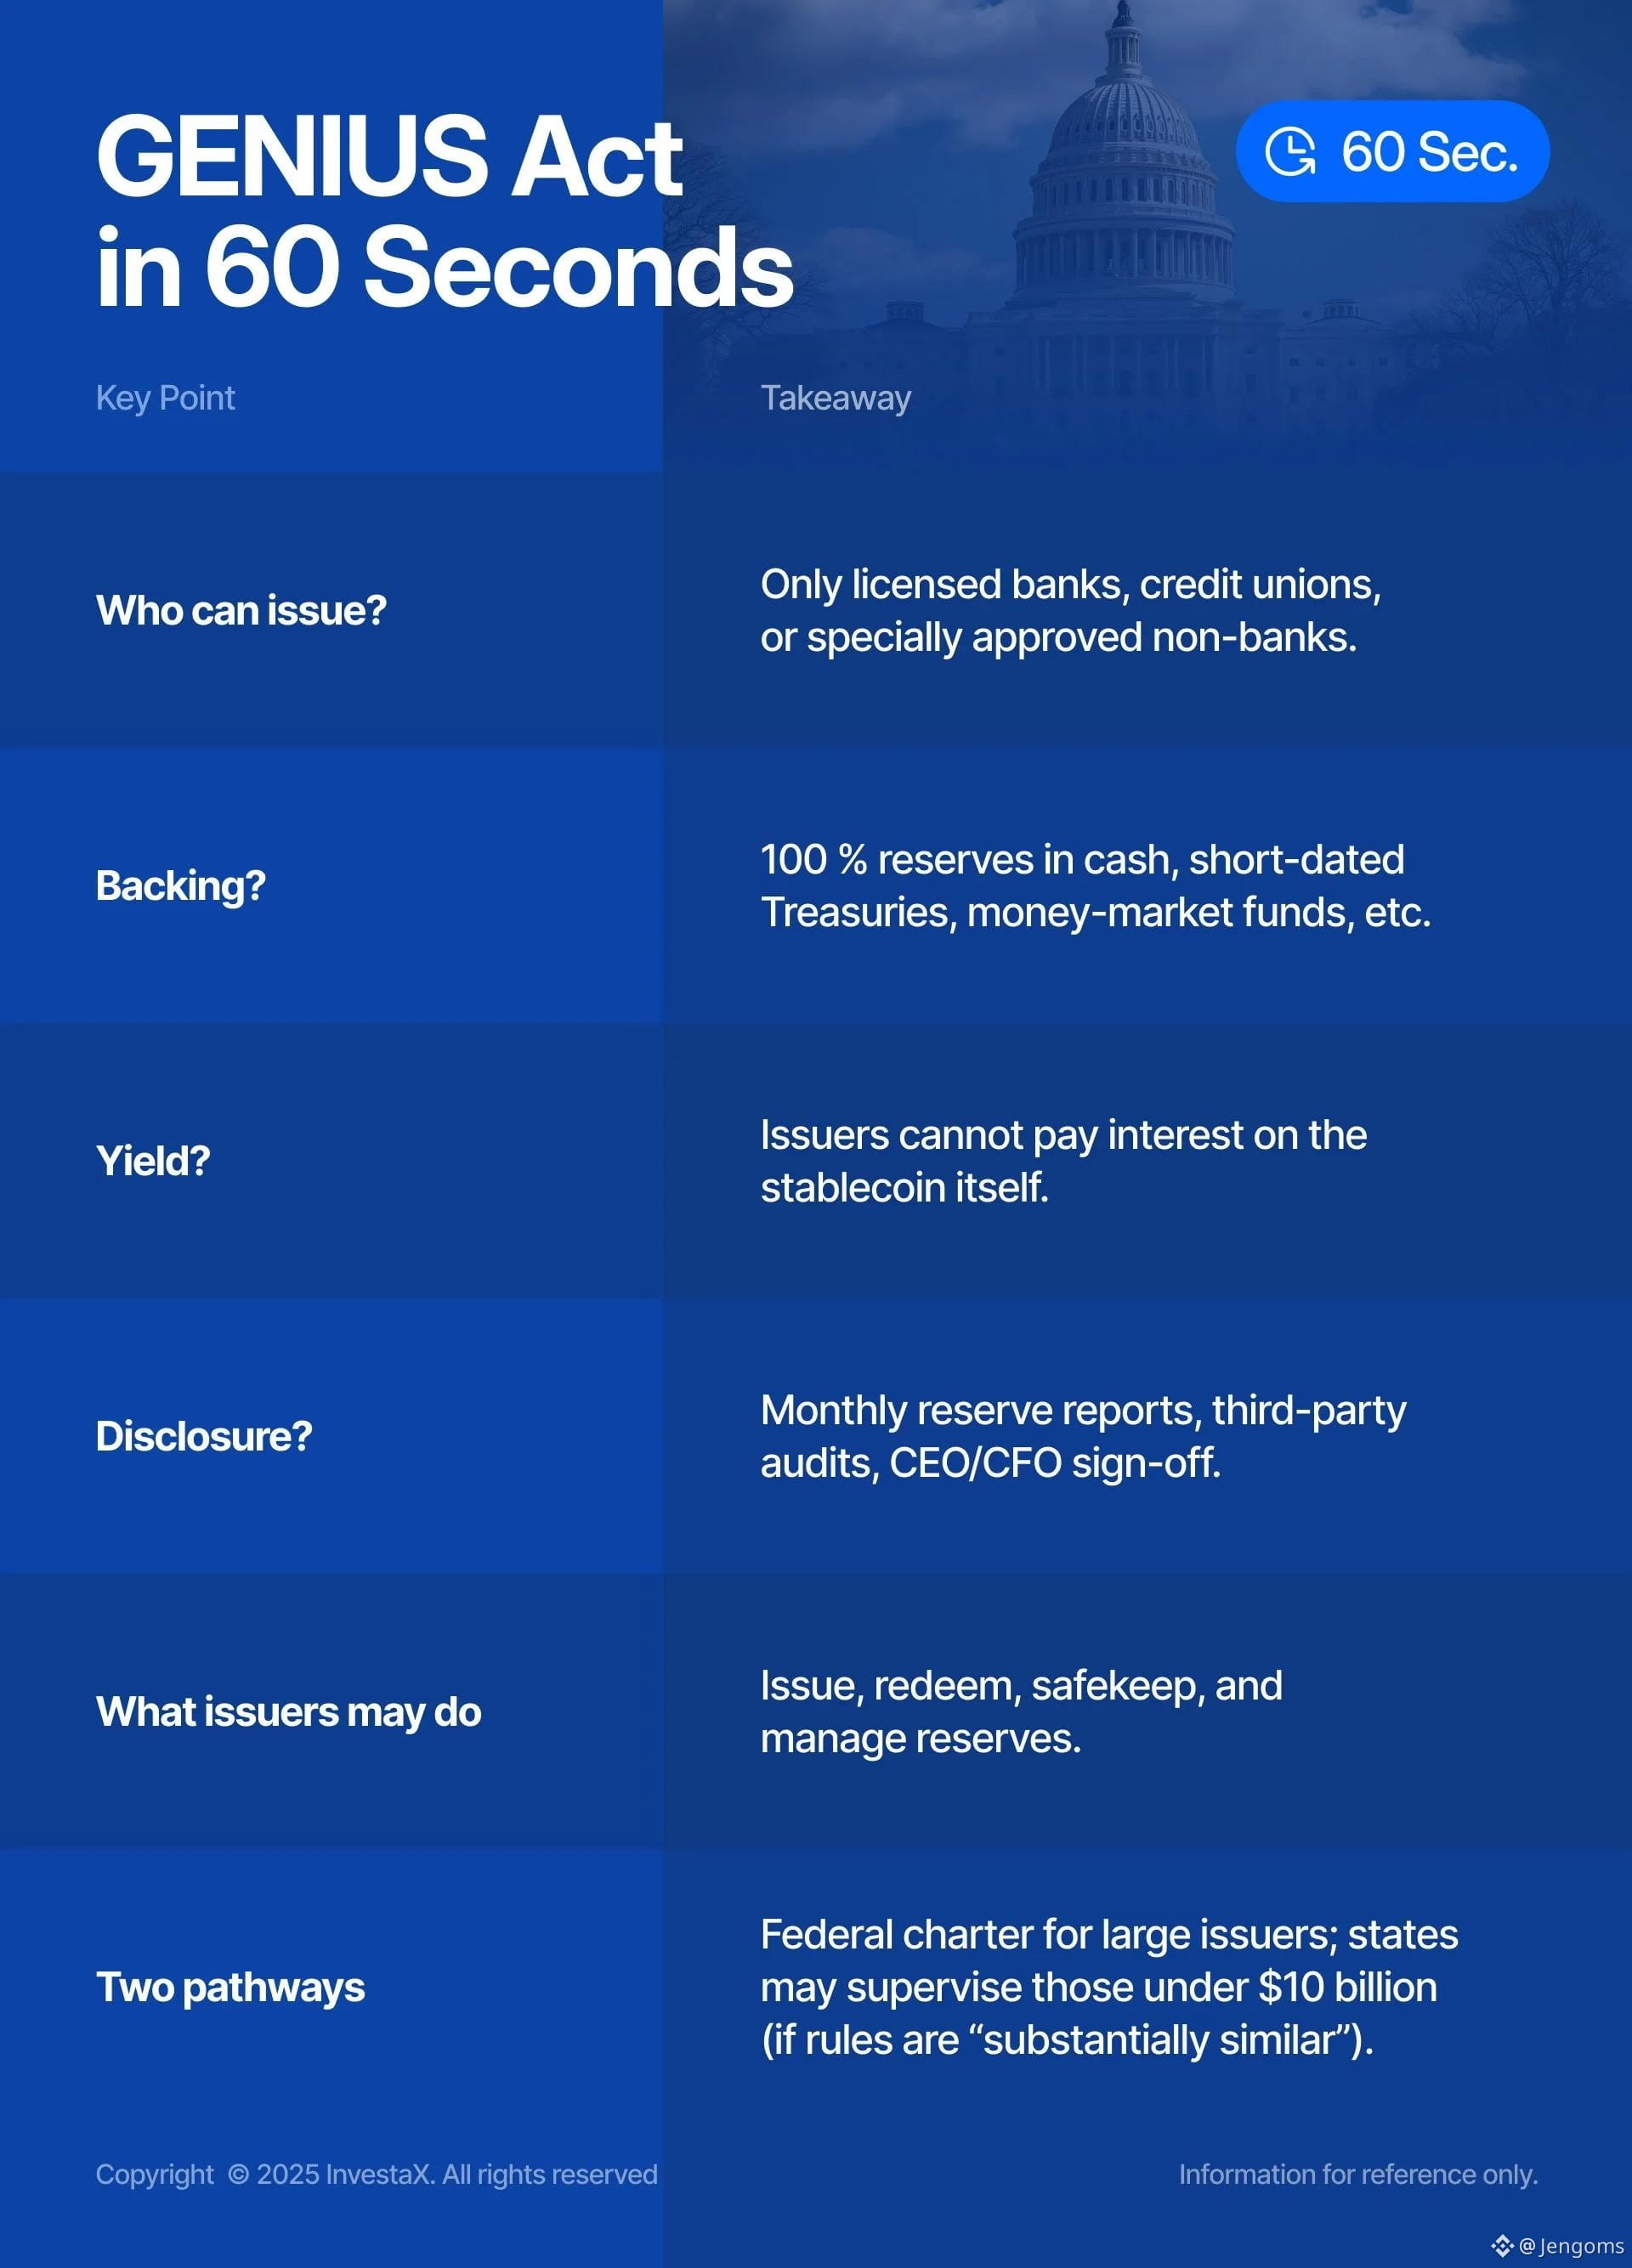
🚨 FED DROPS BIG STABLECOIN RULEBOOK
The U.S. Federal Reserve proposed new rules for Fed-supervised stablecoin issuers, including 1:1 reserve backing, capital requirements, risk-management standards, and a new application process for banks issuing payment stablecoins. The proposal is part of implementing the GENIUS Act. $ONDO
{spot}(ONDOUSDT)
$USDC
{spot}(USDCUSDT)
#FedProposesRulesForBankIssuedStablecoins #BinanceWillListHyperliquid(HYPE)
FED JUST DROPPED A BIG STABLECOIN RULEBOOK
💵 1:1 Reserve Backing
🏦 Bank Issuers Face New Rules
📊 Capital & Risk Requirements
🇺🇸 GENIUS Act Implementation
⏳ Public comments open for 60 days.
🚨 FED DROPS BIG STABLECOIN RULEBOOK
The U.S. Federal Reserve proposed new rules for Fed-supervised stablecoin issuers, including 1:1 reserve backing, capital requirements, risk-management standards, and a new application process for banks issuing payment stablecoins. The proposal is part of implementing the GENIUS Act. $ONDO
$USDC
#FedProposesRulesForBankIssuedStablecoins #BinanceWillListHyperliquid(HYPE)
FED JUST DROPPED A BIG STABLECOIN RULEBOOK
💵 1:1 Reserve Backing
🏦 Bank Issuers Face New Rules
📊 Capital & Risk Requirements
🇺🇸 GENIUS Act Implementation
⏳ Public comments open for 60 days.
The U.S. Federal Reserve proposed new rules for Fed-supervised stablecoin issuers, including 1:1 reserve backing, capital requirements, risk-management standards, and a new application process for banks issuing payment stablecoins. The proposal is part of implementing the GENIUS Act. $ONDO
$USDC
#FedProposesRulesForBankIssuedStablecoins #BinanceWillListHyperliquid(HYPE)
FED JUST DROPPED A BIG STABLECOIN RULEBOOK
💵 1:1 Reserve Backing
🏦 Bank Issuers Face New Rules
📊 Capital & Risk Requirements
🇺🇸 GENIUS Act Implementation
⏳ Public comments open for 60 days.
1
110

·
--
$BANK is getting overhyped because regulators are finally paying attention.
The Fed doesn’t care about your trades.
They care about systemic risk.
This isn’t a signal for $BANK to pump it’s a signal that bank-issued stablecoins are being pulled into the old system.
Traders think regulation means legitimacy.
I think it means more red tape and slower innovation.
I’m watching.
Not adding exposure.
If $BANK starts moving on actual bank adoption, not headlines, I’ll reconsider.
The moment a major bank announces a live, scaled stablecoin backed by $BANK that’s when I’m wrong.
You think it’s a buy?
#FedProposesRulesForBankIssuedStablecoins #BANK #CryptoNews
$BANK is getting overhyped because regulators are finally paying attention.
The Fed doesn’t care about your trades.
They care about systemic risk.
This isn’t a signal for $BANK to pump it’s a signal that bank-issued stablecoins are being pulled into the old system.
Traders think regulation means legitimacy.
I think it means more red tape and slower innovation.
I’m watching.
Not adding exposure.
If $BANK starts moving on actual bank adoption, not headlines, I’ll reconsider.
The moment a major bank announces a live, scaled stablecoin backed by $BANK that’s when I’m wrong.
You think it’s a buy?
#FedProposesRulesForBankIssuedStablecoins #BANK #CryptoNews
The Fed doesn’t care about your trades.
They care about systemic risk.
This isn’t a signal for $BANK to pump it’s a signal that bank-issued stablecoins are being pulled into the old system.
Traders think regulation means legitimacy.
I think it means more red tape and slower innovation.
I’m watching.
Not adding exposure.
If $BANK starts moving on actual bank adoption, not headlines, I’ll reconsider.
The moment a major bank announces a live, scaled stablecoin backed by $BANK that’s when I’m wrong.
You think it’s a buy?
#FedProposesRulesForBankIssuedStablecoins #BANK #CryptoNews
26
🚨 Banks + Stablecoins
The Fed is proposing a framework for banks under its supervision to issue payment stablecoins.
The rules cover reserves, capital, risk management and safeguarding backing assets.
Public comments will remain open for 60 days after Federal Register publication.
$ETH $LINK $BNB and $AVAX are worth researching across the ecosystem.
📊 Bank-issued digital dollars are getting a clearer regulatory framework.
#fedproposesrulesforbankissuedstablecoins
🚨 Banks + Stablecoins
The Fed is proposing a framework for banks under its supervision to issue payment stablecoins.
The rules cover reserves, capital, risk management and safeguarding backing assets.
Public comments will remain open for 60 days after Federal Register publication.
$ETH $LINK $BNB and $AVAX are worth researching across the ecosystem.
📊 Bank-issued digital dollars are getting a clearer regulatory framework.
#fedproposesrulesforbankissuedstablecoins
The Fed is proposing a framework for banks under its supervision to issue payment stablecoins.
The rules cover reserves, capital, risk management and safeguarding backing assets.
Public comments will remain open for 60 days after Federal Register publication.
$ETH $LINK $BNB and $AVAX are worth researching across the ecosystem.
📊 Bank-issued digital dollars are getting a clearer regulatory framework.
#fedproposesrulesforbankissuedstablecoins
157

·
--
#fedproposesrulesforbankissuedstablecoins
🏦 Macro Alert: The Fed Enters the Stablecoin Arena with Proposed Issuer Rules! 💵⚖️
The Federal Reserve officially unveiled two major regulatory proposals to implement the GENIUS Act (Guiding and Establishing National Innovation for U.S. Stablecoins), establishing strict reserve, operational, and capital standards for bank-issued payment stablecoins.
📌 Breakdown of Key Proposed Fed Rules
💵 1:1 Reserve Mandate: All Fed-supervised payment stablecoin issuers must fully back every $1 token with high-quality permissible reserve assets, including cash, Federal Reserve balances, short-term U.S. Treasuries (maturities ≤ 93 days), and qualifying repo agreements.
⏱️ Mandatory 2-Day Redemptions: Tokens must generally be redeemable at par value within two business days. If reserves fall short, issuers must notify the Fed and execute a remediation plan or immediately liquidate reserves to redeem token holders.
📊 Operational Risk Capital Charges: The proposal enforces standardized capital charges to guard against credit and operational risks—set at 2% on the first $20 Billion in outstanding stablecoins, 1.5% on the next $30 Billion, and 1% on amounts exceeding $50 Billion.
🏦 Bank Subsidiary Application Process: A separate rule outlines a structured application workflow for state member banks seeking to establish dedicated subsidiaries to issue payment stablecoins, featuring a mandatory 120-day Fed decision window upon complete application submission.
⚖️ Wall Street vs. Crypto Native Stablecoins (USDT & USDC)
Competition for Market Share: As commercial banks roll out yield-compliant or bank-backed stablecoins under federal law, established non-bank issuers like Tether ($USDT) and Circle ($USDC) face tighter compliance benchmarks in U.S. markets.
DeFi Liquidity Shift: While federal backing increases trust for institutional settlement, strict reserve limitations and 2-day redemption rules could bifurcate global crypto liquidity between regulated U.S.
#FedOctoberRateHikeOddsRiseTo69.7%
#fedproposesrulesforbankissuedstablecoins
🏦 Macro Alert: The Fed Enters the Stablecoin Arena with Proposed Issuer Rules! 💵⚖️
The Federal Reserve officially unveiled two major regulatory proposals to implement the GENIUS Act (Guiding and Establishing National Innovation for U.S. Stablecoins), establishing strict reserve, operational, and capital standards for bank-issued payment stablecoins.
📌 Breakdown of Key Proposed Fed Rules
💵 1:1 Reserve Mandate: All Fed-supervised payment stablecoin issuers must fully back every $1 token with high-quality permissible reserve assets, including cash, Federal Reserve balances, short-term U.S. Treasuries (maturities ≤ 93 days), and qualifying repo agreements.
⏱️ Mandatory 2-Day Redemptions: Tokens must generally be redeemable at par value within two business days. If reserves fall short, issuers must notify the Fed and execute a remediation plan or immediately liquidate reserves to redeem token holders.
📊 Operational Risk Capital Charges: The proposal enforces standardized capital charges to guard against credit and operational risks—set at 2% on the first $20 Billion in outstanding stablecoins, 1.5% on the next $30 Billion, and 1% on amounts exceeding $50 Billion.
🏦 Bank Subsidiary Application Process: A separate rule outlines a structured application workflow for state member banks seeking to establish dedicated subsidiaries to issue payment stablecoins, featuring a mandatory 120-day Fed decision window upon complete application submission.
⚖️ Wall Street vs. Crypto Native Stablecoins (USDT & USDC)
Competition for Market Share: As commercial banks roll out yield-compliant or bank-backed stablecoins under federal law, established non-bank issuers like Tether ($USDT) and Circle ($USDC) face tighter compliance benchmarks in U.S. markets.
DeFi Liquidity Shift: While federal backing increases trust for institutional settlement, strict reserve limitations and 2-day redemption rules could bifurcate global crypto liquidity between regulated U.S.
#FedOctoberRateHikeOddsRiseTo69.7%
🏦 Macro Alert: The Fed Enters the Stablecoin Arena with Proposed Issuer Rules! 💵⚖️
The Federal Reserve officially unveiled two major regulatory proposals to implement the GENIUS Act (Guiding and Establishing National Innovation for U.S. Stablecoins), establishing strict reserve, operational, and capital standards for bank-issued payment stablecoins.
📌 Breakdown of Key Proposed Fed Rules
💵 1:1 Reserve Mandate: All Fed-supervised payment stablecoin issuers must fully back every $1 token with high-quality permissible reserve assets, including cash, Federal Reserve balances, short-term U.S. Treasuries (maturities ≤ 93 days), and qualifying repo agreements.
⏱️ Mandatory 2-Day Redemptions: Tokens must generally be redeemable at par value within two business days. If reserves fall short, issuers must notify the Fed and execute a remediation plan or immediately liquidate reserves to redeem token holders.
📊 Operational Risk Capital Charges: The proposal enforces standardized capital charges to guard against credit and operational risks—set at 2% on the first $20 Billion in outstanding stablecoins, 1.5% on the next $30 Billion, and 1% on amounts exceeding $50 Billion.
🏦 Bank Subsidiary Application Process: A separate rule outlines a structured application workflow for state member banks seeking to establish dedicated subsidiaries to issue payment stablecoins, featuring a mandatory 120-day Fed decision window upon complete application submission.
⚖️ Wall Street vs. Crypto Native Stablecoins (USDT & USDC)
Competition for Market Share: As commercial banks roll out yield-compliant or bank-backed stablecoins under federal law, established non-bank issuers like Tether ($USDT) and Circle ($USDC) face tighter compliance benchmarks in U.S. markets.
DeFi Liquidity Shift: While federal backing increases trust for institutional settlement, strict reserve limitations and 2-day redemption rules could bifurcate global crypto liquidity between regulated U.S.
#FedOctoberRateHikeOddsRiseTo69.7%
1
2
5.5k
🏦 Fed Stablecoin Rules
The Federal Reserve has proposed new rules for bank-supervised payment stablecoin issuers.
Issuers would need to fully back stablecoins with permitted reserves, including short-term Treasuries.
The proposal also adds capital and risk-management requirements.
$BTC $ETH $BNB and $LINK remain key assets in the broader blockchain ecosystem.
💡 Stablecoin regulation is entering a more detailed phase.
#fedproposesrulesforbankissuedstablecoins
🏦 Fed Stablecoin Rules
The Federal Reserve has proposed new rules for bank-supervised payment stablecoin issuers.
Issuers would need to fully back stablecoins with permitted reserves, including short-term Treasuries.
The proposal also adds capital and risk-management requirements.
$BTC $ETH $BNB and $LINK remain key assets in the broader blockchain ecosystem.
💡 Stablecoin regulation is entering a more detailed phase.
#fedproposesrulesforbankissuedstablecoins
The Federal Reserve has proposed new rules for bank-supervised payment stablecoin issuers.
Issuers would need to fully back stablecoins with permitted reserves, including short-term Treasuries.
The proposal also adds capital and risk-management requirements.
$BTC $ETH $BNB and $LINK remain key assets in the broader blockchain ecosystem.
💡 Stablecoin regulation is entering a more detailed phase.
#fedproposesrulesforbankissuedstablecoins
26
·
--
#FedProposesRulesForBankIssuedStablecoins 🏦 Fed Proposes Rules for Bank-Issued Stablecoins
The U.S. Federal Reserve has proposed rules to regulate payment stablecoins issued by banks under the GENIUS Act. �
#FedProposesRulesForBankIssuedStablecoins 🏦 Fed Proposes Rules for Bank-Issued Stablecoins
The U.S. Federal Reserve has proposed rules to regulate payment stablecoins issued by banks under the GENIUS Act. �
The U.S. Federal Reserve has proposed rules to regulate payment stablecoins issued by banks under the GENIUS Act. �
1
2
26
·
--
Bullish
#FedProposesRulesForBankIssuedStablecoins
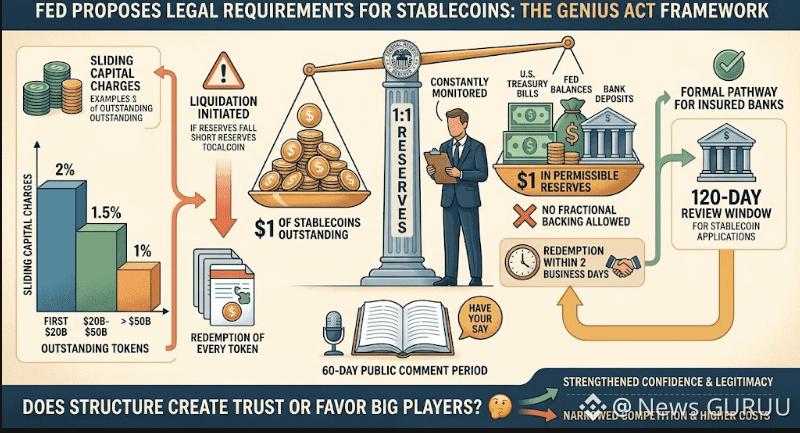
🏦 The Fed is putting real rules behind the words “fully backed.”
On September 24, the Federal Reserve proposed two frameworks under the GENIUS Act for payment stablecoins.
The core requirement: eligible issuers would have to fully back outstanding stablecoins with permitted reserve assets, including short-term Treasuries and other qualifying liquid assets. The proposals also introduce capital and risk-management standards and a formal approval process for supervised banks seeking to issue stablecoins.
The proposals are now open for 60 days of public comment before final rules are adopted.
For crypto markets, this could make stablecoin regulation more defined while also increasing compliance requirements for issuers.
🤔 Will stricter rules accelerate institutional stablecoin adoption—or make it harder for smaller issuers to compete?
TRADE $QNT $ONDO $XPL HERE
{spot}(XPLUSDT)
{spot}(ONDOUSDT)
{spot}(QNTUSDT)
#Stablecoins #GENIUSAct
#FedProposesRulesForBankIssuedStablecoins
🏦 The Fed is putting real rules behind the words “fully backed.”
On September 24, the Federal Reserve proposed two frameworks under the GENIUS Act for payment stablecoins.
The core requirement: eligible issuers would have to fully back outstanding stablecoins with permitted reserve assets, including short-term Treasuries and other qualifying liquid assets. The proposals also introduce capital and risk-management standards and a formal approval process for supervised banks seeking to issue stablecoins.
The proposals are now open for 60 days of public comment before final rules are adopted.
For crypto markets, this could make stablecoin regulation more defined while also increasing compliance requirements for issuers.
🤔 Will stricter rules accelerate institutional stablecoin adoption—or make it harder for smaller issuers to compete?
TRADE $QNT $ONDO $XPL HERE
#Stablecoins #GENIUSAct
🏦 The Fed is putting real rules behind the words “fully backed.”
On September 24, the Federal Reserve proposed two frameworks under the GENIUS Act for payment stablecoins.
The core requirement: eligible issuers would have to fully back outstanding stablecoins with permitted reserve assets, including short-term Treasuries and other qualifying liquid assets. The proposals also introduce capital and risk-management standards and a formal approval process for supervised banks seeking to issue stablecoins.
The proposals are now open for 60 days of public comment before final rules are adopted.
For crypto markets, this could make stablecoin regulation more defined while also increasing compliance requirements for issuers.
🤔 Will stricter rules accelerate institutional stablecoin adoption—or make it harder for smaller issuers to compete?
TRADE $QNT $ONDO $XPL HERE
#Stablecoins #GENIUSAct
1
124

·
--
Have you noticed how everyone treats bank-regulated stablecoins as the ultimate validation for crypto, while completely ignoring who actually loses in that scenario?
Most retail investors park their capital in liquidity pools and yield protocols without realizing how fast institutional rails can drain that volume once compliance walls go up. Getting caught holding unapproved assets during a sudden regulatory reshuffle is a fast track to getting your yield crushed.
Look at what is unfolding with the latest Fed framework for bank-issued stablecoins. The mainstream assumption is that Wall Street entering the settlement layer lifts the entire ecosystem equally. In reality, traditional banks issuing their own pegged tokens will not integrate with permissionless DeFi; they will build walled gardens that directly siphon market share from crypto-native staples like $USDT and synthetic yield designs like $ENA.
When regulated depository institutions capture stablecoin reserve yield backed directly by short-term Treasuries, the risk-reward equation changes overnight. Capital always migrates toward the path of least legal friction, especially when institutional desks demand ring-fenced collateral over decentralized alternatives.
Where do you think liquidity flows once tier-one banks launch their own pegged assets?
#FedProposesRulesForBankIssuedStablecoins #FedOctoberRateHikeOddsRiseTo69
Have you noticed how everyone treats bank-regulated stablecoins as the ultimate validation for crypto, while completely ignoring who actually loses in that scenario?
Most retail investors park their capital in liquidity pools and yield protocols without realizing how fast institutional rails can drain that volume once compliance walls go up. Getting caught holding unapproved assets during a sudden regulatory reshuffle is a fast track to getting your yield crushed.
Look at what is unfolding with the latest Fed framework for bank-issued stablecoins. The mainstream assumption is that Wall Street entering the settlement layer lifts the entire ecosystem equally. In reality, traditional banks issuing their own pegged tokens will not integrate with permissionless DeFi; they will build walled gardens that directly siphon market share from crypto-native staples like $USDT and synthetic yield designs like $ENA .
When regulated depository institutions capture stablecoin reserve yield backed directly by short-term Treasuries, the risk-reward equation changes overnight. Capital always migrates toward the path of least legal friction, especially when institutional desks demand ring-fenced collateral over decentralized alternatives.
Where do you think liquidity flows once tier-one banks launch their own pegged assets?
#FedProposesRulesForBankIssuedStablecoins #FedOctoberRateHikeOddsRiseTo69
Most retail investors park their capital in liquidity pools and yield protocols without realizing how fast institutional rails can drain that volume once compliance walls go up. Getting caught holding unapproved assets during a sudden regulatory reshuffle is a fast track to getting your yield crushed.
Look at what is unfolding with the latest Fed framework for bank-issued stablecoins. The mainstream assumption is that Wall Street entering the settlement layer lifts the entire ecosystem equally. In reality, traditional banks issuing their own pegged tokens will not integrate with permissionless DeFi; they will build walled gardens that directly siphon market share from crypto-native staples like $USDT and synthetic yield designs like $ENA .
When regulated depository institutions capture stablecoin reserve yield backed directly by short-term Treasuries, the risk-reward equation changes overnight. Capital always migrates toward the path of least legal friction, especially when institutional desks demand ring-fenced collateral over decentralized alternatives.
Where do you think liquidity flows once tier-one banks launch their own pegged assets?
#FedProposesRulesForBankIssuedStablecoins #FedOctoberRateHikeOddsRiseTo69
199
·
--
🚨 #FedProposesRulesForBankIssuedStablecoins — banks may be getting a clearer path into the stablecoin race.
The Federal Reserve has proposed a framework for bank-issued payment stablecoins, focusing on reserve quality, redemption rights, liquidity, risk management, and how these products should sit inside the regulated banking system.
This matters because stablecoins are no longer being treated as a crypto-only product.
The bigger shift is:
Banks issue stablecoins → regulated dollar rails expand → more tokenized deposits + onchain settlement → stablecoin adoption moves deeper into traditional finance.
That could strengthen the broader narrative around $USDC, tokenized assets, RWA infrastructure, and bank-backed digital dollars.
The key question now:
Do banks eventually compete with crypto-native stablecoin issuers… or become their biggest distribution partners? 👀
{future}(HYPEUSDT)
{future}(XRPUSDT)
{future}(AKEUSDT)
$HYPE $XRP $AKE
#BinanceWillListHyperliquid(HYPE) #BrazilOrdersReportingOf$10KSelfCustodyTransfers #OndoFinanceSoughtSaleAfterFoundersDeath #FedOctoberRateHikeOddsRiseTo69.7%
🚨 #FedProposesRulesForBankIssuedStablecoins — banks may be getting a clearer path into the stablecoin race.
The Federal Reserve has proposed a framework for bank-issued payment stablecoins, focusing on reserve quality, redemption rights, liquidity, risk management, and how these products should sit inside the regulated banking system.
This matters because stablecoins are no longer being treated as a crypto-only product.
The bigger shift is:
Banks issue stablecoins → regulated dollar rails expand → more tokenized deposits + onchain settlement → stablecoin adoption moves deeper into traditional finance.
That could strengthen the broader narrative around $USDC, tokenized assets, RWA infrastructure, and bank-backed digital dollars.
The key question now:
Do banks eventually compete with crypto-native stablecoin issuers… or become their biggest distribution partners? 👀
$HYPE $XRP $AKE
#BinanceWillListHyperliquid(HYPE) #BrazilOrdersReportingOf$10KSelfCustodyTransfers #OndoFinanceSoughtSaleAfterFoundersDeath #FedOctoberRateHikeOddsRiseTo69.7%
The Federal Reserve has proposed a framework for bank-issued payment stablecoins, focusing on reserve quality, redemption rights, liquidity, risk management, and how these products should sit inside the regulated banking system.
This matters because stablecoins are no longer being treated as a crypto-only product.
The bigger shift is:
Banks issue stablecoins → regulated dollar rails expand → more tokenized deposits + onchain settlement → stablecoin adoption moves deeper into traditional finance.
That could strengthen the broader narrative around $USDC, tokenized assets, RWA infrastructure, and bank-backed digital dollars.
The key question now:
Do banks eventually compete with crypto-native stablecoin issuers… or become their biggest distribution partners? 👀
$HYPE $XRP $AKE
#BinanceWillListHyperliquid(HYPE) #BrazilOrdersReportingOf$10KSelfCustodyTransfers #OndoFinanceSoughtSaleAfterFoundersDeath #FedOctoberRateHikeOddsRiseTo69.7%
1
438
🌐 Stablecoins Move Deeper Into Banking
The Federal Reserve has opened proposals covering bank-supervised stablecoin issuers.
Covered tokens would need qualifying reserve assets behind them.
The framework also addresses capital requirements and operational risks.
$BTC $ETH $BNB and $SOL remain widely watched crypto assets.
👀 Traditional banking and blockchain payments are moving closer together.
#fedproposesrulesforbankissuedstablecoins
🌐 Stablecoins Move Deeper Into Banking
The Federal Reserve has opened proposals covering bank-supervised stablecoin issuers.
Covered tokens would need qualifying reserve assets behind them.
The framework also addresses capital requirements and operational risks.
$BTC $ETH $BNB and $SOL remain widely watched crypto assets.
👀 Traditional banking and blockchain payments are moving closer together.
#fedproposesrulesforbankissuedstablecoins
The Federal Reserve has opened proposals covering bank-supervised stablecoin issuers.
Covered tokens would need qualifying reserve assets behind them.
The framework also addresses capital requirements and operational risks.
$BTC $ETH $BNB and $SOL remain widely watched crypto assets.
👀 Traditional banking and blockchain payments are moving closer together.
#fedproposesrulesforbankissuedstablecoins
69

·
--
The Fed Proposes Stablecoin Regulation Draft|Banks Still Need to Apply and Hold Adequate Reserves|ETH at 2675—don’t run ahead
My stance is neutral to cautious: this is a worth-watching regulatory development, but it is not “bank-issued stablecoins have already been approved,” nor is it a reason for ETH to necessarily surge tonight. A #FedProposesRulesForBankIssuedStablecoins has appeared on Binance Square’s trending list. I looked up the Fed’s original September 24 announcement: the Board is seeking comments on two proposals—one would apply to payment stablecoin issuers regulated by the Fed, requiring fully qualified reserve assets to adequately support issuance, along with capital, risk management, and reserve custody requirements; the other would set up a dedicated application process for regulated banks seeking to issue payment stablecoins, with application materials including a business plan and financial information. The comment period runs for 60 days after the notice is published in the Federal Register. The keywords are “proposal,” “request for comments,” and “application”—not that the rules are already effective, nor that any bank has already been granted a license.
Why does this matter for the crypto market? If the final rules establish an enforceable framework for banks to issue and redeem stablecoins, the compliant pathway for fiat to enter on-chain payments could become clearer. Exchanges, wallets, and DeFi could then potentially gain more stable USD settlement tools. But the first beneficiaries would be qualifying issuers and use cases. ETH, as a native asset on a particular network, only becomes directly transmissible when real issuance, transfers, and usage ultimately land on Ethereum and are converted into ongoing on-chain fees and demand. The draft proposal does not designate Ethereum as the only chain. The issuance scale, actual rollout timing, chain selection, and fee model are still uncertain. On the same day, Fed Governor Barr also emphasized the importance of redeeming at par in a timely manner during stressful periods—reminding me that the most core risk of stablecoins is not the marketing slogan, but reserves, redemption rights, and operational resilience.
The market has not provided clear confirmation of “regulatory good news leading to an immediate ETH rally.” When I checked KuCoin’s ETH/USDT spot price while writing, it was around $2675.5; over the past 24 hours, the high was about $2705.79 and the low about $2628.58, a move of roughly -0.38%. Price briefly probed near $2700 and then retreated, so you can’t directly attribute this fluctuation to the Fed announcement. What I’m watching now is whether $2705–$2710 can be reclaimed and held, with support levels at around $2650 and $2628. These are merely execution watch levels, not prices guaranteed by policy. If the draft is later modified significantly, rollout is blocked, or institutions ultimately choose other chains and there is no growth in Ethereum-based stablecoin activity, I would overturn the view that ETH could indirectly benefit. If price breaks below $2628 and stays there, my short-term recovery plan would also fail.
If I were trading this myself, I would not enter. I would only keep a small position for a spot long. I must wait for two full 15-minute candlesticks to close above $2710, then confirm a pullback of $2695–$2710 that does not break, and also see that the news is not corrected by official sources. Then I would enter with no more than 0.3% of total capital; I’d cut the position in half at $2735, and close the remaining position at $2760–$2770. After entry, if a 15-minute candle closes back below $2680, I’d cut the position in half; if it hits $2650, I would fully close immediately with a hard stop. If before triggering those conditions price breaks below $2628, I would cancel the entire plan. Without these conditions, I’d rather miss the move than use leverage to bet on a draft policy text that is still under consultation.
#FedProposesRulesForBankIssuedStablecoins #ETH
The above is only my personal market observation and does not constitute investment advice.
The Fed Proposes Stablecoin Regulation Draft|Banks Still Need to Apply and Hold Adequate Reserves|ETH at 2675—don’t run ahead
My stance is neutral to cautious: this is a worth-watching regulatory development, but it is not “bank-issued stablecoins have already been approved,” nor is it a reason for ETH to necessarily surge tonight. A #FedProposesRulesForBankIssuedStablecoins has appeared on Binance Square’s trending list. I looked up the Fed’s original September 24 announcement: the Board is seeking comments on two proposals—one would apply to payment stablecoin issuers regulated by the Fed, requiring fully qualified reserve assets to adequately support issuance, along with capital, risk management, and reserve custody requirements; the other would set up a dedicated application process for regulated banks seeking to issue payment stablecoins, with application materials including a business plan and financial information. The comment period runs for 60 days after the notice is published in the Federal Register. The keywords are “proposal,” “request for comments,” and “application”—not that the rules are already effective, nor that any bank has already been granted a license.
Why does this matter for the crypto market? If the final rules establish an enforceable framework for banks to issue and redeem stablecoins, the compliant pathway for fiat to enter on-chain payments could become clearer. Exchanges, wallets, and DeFi could then potentially gain more stable USD settlement tools. But the first beneficiaries would be qualifying issuers and use cases. ETH, as a native asset on a particular network, only becomes directly transmissible when real issuance, transfers, and usage ultimately land on Ethereum and are converted into ongoing on-chain fees and demand. The draft proposal does not designate Ethereum as the only chain. The issuance scale, actual rollout timing, chain selection, and fee model are still uncertain. On the same day, Fed Governor Barr also emphasized the importance of redeeming at par in a timely manner during stressful periods—reminding me that the most core risk of stablecoins is not the marketing slogan, but reserves, redemption rights, and operational resilience.
The market has not provided clear confirmation of “regulatory good news leading to an immediate ETH rally.” When I checked KuCoin’s ETH/USDT spot price while writing, it was around $2675.5; over the past 24 hours, the high was about $2705.79 and the low about $2628.58, a move of roughly -0.38%. Price briefly probed near $2700 and then retreated, so you can’t directly attribute this fluctuation to the Fed announcement. What I’m watching now is whether $2705–$2710 can be reclaimed and held, with support levels at around $2650 and $2628. These are merely execution watch levels, not prices guaranteed by policy. If the draft is later modified significantly, rollout is blocked, or institutions ultimately choose other chains and there is no growth in Ethereum-based stablecoin activity, I would overturn the view that ETH could indirectly benefit. If price breaks below $2628 and stays there, my short-term recovery plan would also fail.
If I were trading this myself, I would not enter. I would only keep a small position for a spot long. I must wait for two full 15-minute candlesticks to close above $2710, then confirm a pullback of $2695–$2710 that does not break, and also see that the news is not corrected by official sources. Then I would enter with no more than 0.3% of total capital; I’d cut the position in half at $2735, and close the remaining position at $2760–$2770. After entry, if a 15-minute candle closes back below $2680, I’d cut the position in half; if it hits $2650, I would fully close immediately with a hard stop. If before triggering those conditions price breaks below $2628, I would cancel the entire plan. Without these conditions, I’d rather miss the move than use leverage to bet on a draft policy text that is still under consultation.
#FedProposesRulesForBankIssuedStablecoins #ETH
The above is only my personal market observation and does not constitute investment advice.
My stance is neutral to cautious: this is a worth-watching regulatory development, but it is not “bank-issued stablecoins have already been approved,” nor is it a reason for ETH to necessarily surge tonight. A #FedProposesRulesForBankIssuedStablecoins has appeared on Binance Square’s trending list. I looked up the Fed’s original September 24 announcement: the Board is seeking comments on two proposals—one would apply to payment stablecoin issuers regulated by the Fed, requiring fully qualified reserve assets to adequately support issuance, along with capital, risk management, and reserve custody requirements; the other would set up a dedicated application process for regulated banks seeking to issue payment stablecoins, with application materials including a business plan and financial information. The comment period runs for 60 days after the notice is published in the Federal Register. The keywords are “proposal,” “request for comments,” and “application”—not that the rules are already effective, nor that any bank has already been granted a license.
Why does this matter for the crypto market? If the final rules establish an enforceable framework for banks to issue and redeem stablecoins, the compliant pathway for fiat to enter on-chain payments could become clearer. Exchanges, wallets, and DeFi could then potentially gain more stable USD settlement tools. But the first beneficiaries would be qualifying issuers and use cases. ETH, as a native asset on a particular network, only becomes directly transmissible when real issuance, transfers, and usage ultimately land on Ethereum and are converted into ongoing on-chain fees and demand. The draft proposal does not designate Ethereum as the only chain. The issuance scale, actual rollout timing, chain selection, and fee model are still uncertain. On the same day, Fed Governor Barr also emphasized the importance of redeeming at par in a timely manner during stressful periods—reminding me that the most core risk of stablecoins is not the marketing slogan, but reserves, redemption rights, and operational resilience.
The market has not provided clear confirmation of “regulatory good news leading to an immediate ETH rally.” When I checked KuCoin’s ETH/USDT spot price while writing, it was around $2675.5; over the past 24 hours, the high was about $2705.79 and the low about $2628.58, a move of roughly -0.38%. Price briefly probed near $2700 and then retreated, so you can’t directly attribute this fluctuation to the Fed announcement. What I’m watching now is whether $2705–$2710 can be reclaimed and held, with support levels at around $2650 and $2628. These are merely execution watch levels, not prices guaranteed by policy. If the draft is later modified significantly, rollout is blocked, or institutions ultimately choose other chains and there is no growth in Ethereum-based stablecoin activity, I would overturn the view that ETH could indirectly benefit. If price breaks below $2628 and stays there, my short-term recovery plan would also fail.
If I were trading this myself, I would not enter. I would only keep a small position for a spot long. I must wait for two full 15-minute candlesticks to close above $2710, then confirm a pullback of $2695–$2710 that does not break, and also see that the news is not corrected by official sources. Then I would enter with no more than 0.3% of total capital; I’d cut the position in half at $2735, and close the remaining position at $2760–$2770. After entry, if a 15-minute candle closes back below $2680, I’d cut the position in half; if it hits $2650, I would fully close immediately with a hard stop. If before triggering those conditions price breaks below $2628, I would cancel the entire plan. Without these conditions, I’d rather miss the move than use leverage to bet on a draft policy text that is still under consultation.
#FedProposesRulesForBankIssuedStablecoins #ETH
The above is only my personal market observation and does not constitute investment advice.
144
·
--
Bearish
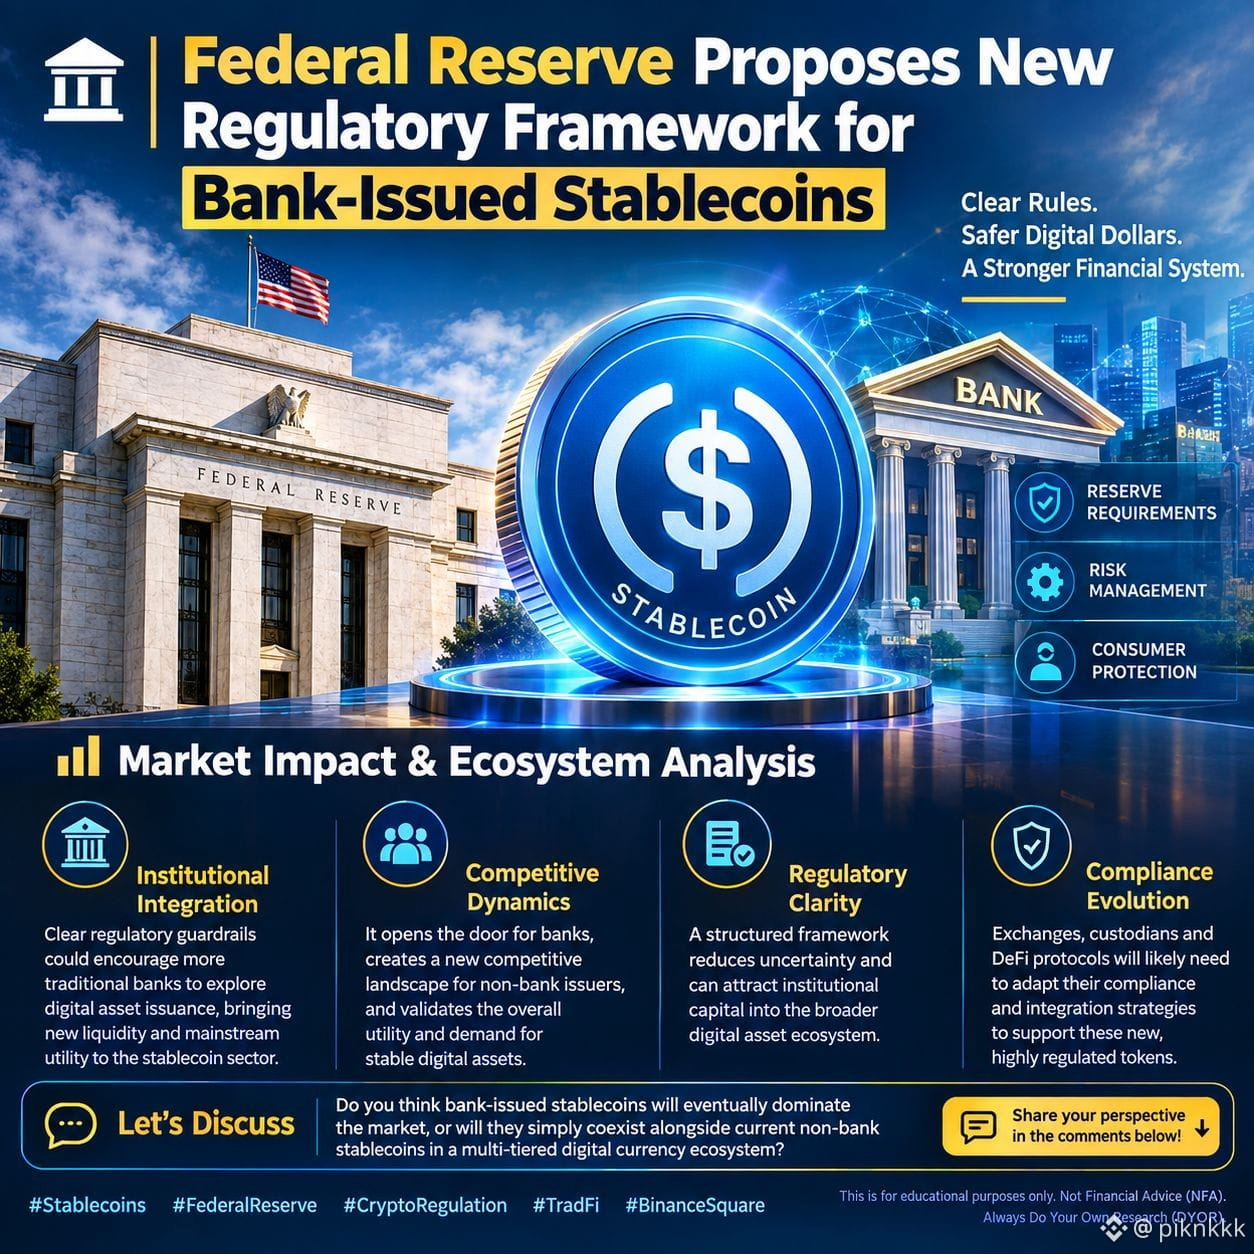
#fedproposesrulesforbankissuedstablecoins 🏦 Federal Reserve Proposes New Regulatory Framework for Bank-Issued Stablecoins
The U.S. Federal Reserve has officially requested public comment on a comprehensive regulatory framework for bank-supervised payment stablecoin issuers. This marks a pivotal step toward institutional clarity in the digital asset space.
Core News
Under the proposed rules tied to the ongoing GENIUS Act implementation the Fed has outlined clear guidelines for regulated stablecoin issuance [10]
1:1 Asset Backing Stablecoins must be fully backed by high-quality liquid assets such as short-term U.S. Treasury bills [10]
📊Tiered Capital Requirements Operational risk capital is scaled based on circulation volume (2% for the first $20B 1.5% for the next $30B and 1% for volumes exceeding $50B) [7]
Strict Redemption & Reporting Issuers must fulfill redemption requests within two business days and provide monthly, auditor verified reserve reports [7]
Tailored Bank Applications A formalized process for Fed-supervised banks to apply for issuing stablecoins through subsidiaries, requiring detailed business plans and financial disclosures [10]
📈 Market Impact
This proposal brings much-needed regulatory clarity to the digital asset ecosystem. By establishing standardized risk management and reserve requirements it is likely to boost institutional confidence in regulated, bank-backed stablecoins. However the high compliance bar may also accelerate market consolidation favoring well capitalized traditional financial institutions while challenging smaller non-bank issuers to adapt.
Join the Discussion
Do you think bank-issued stablecoins will successfully bridge Traditional Finance (TradFi) and Decentralized Finance (DeFi) or will strict regulatory requirements stifle innovation? Share your thoughts below
#Stablecoins #FederalReserve #CryptoRegulation #TradFi #BinanceSquare
This is for educational purposes only. Not Financial Advice (NFA). Always Do Your Own Research (DYOR).
$SAGA $LSK
{future}(LSKUSDT)
{future}(SAGAUSDT)
#fedproposesrulesforbankissuedstablecoins 🏦 Federal Reserve Proposes New Regulatory Framework for Bank-Issued Stablecoins
The U.S. Federal Reserve has officially requested public comment on a comprehensive regulatory framework for bank-supervised payment stablecoin issuers. This marks a pivotal step toward institutional clarity in the digital asset space.
Core News
Under the proposed rules tied to the ongoing GENIUS Act implementation the Fed has outlined clear guidelines for regulated stablecoin issuance [10]
1:1 Asset Backing Stablecoins must be fully backed by high-quality liquid assets such as short-term U.S. Treasury bills [10]
📊Tiered Capital Requirements Operational risk capital is scaled based on circulation volume (2% for the first $20B 1.5% for the next $30B and 1% for volumes exceeding $50B) [7]
Strict Redemption & Reporting Issuers must fulfill redemption requests within two business days and provide monthly, auditor verified reserve reports [7]
Tailored Bank Applications A formalized process for Fed-supervised banks to apply for issuing stablecoins through subsidiaries, requiring detailed business plans and financial disclosures [10]
📈 Market Impact
This proposal brings much-needed regulatory clarity to the digital asset ecosystem. By establishing standardized risk management and reserve requirements it is likely to boost institutional confidence in regulated, bank-backed stablecoins. However the high compliance bar may also accelerate market consolidation favoring well capitalized traditional financial institutions while challenging smaller non-bank issuers to adapt.
Join the Discussion
Do you think bank-issued stablecoins will successfully bridge Traditional Finance (TradFi) and Decentralized Finance (DeFi) or will strict regulatory requirements stifle innovation? Share your thoughts below
#Stablecoins #FederalReserve #CryptoRegulation #TradFi #BinanceSquare
This is for educational purposes only. Not Financial Advice (NFA). Always Do Your Own Research (DYOR).
$SAGA $LSK
The U.S. Federal Reserve has officially requested public comment on a comprehensive regulatory framework for bank-supervised payment stablecoin issuers. This marks a pivotal step toward institutional clarity in the digital asset space.
Core News
Under the proposed rules tied to the ongoing GENIUS Act implementation the Fed has outlined clear guidelines for regulated stablecoin issuance [10]
1:1 Asset Backing Stablecoins must be fully backed by high-quality liquid assets such as short-term U.S. Treasury bills [10]
📊Tiered Capital Requirements Operational risk capital is scaled based on circulation volume (2% for the first $20B 1.5% for the next $30B and 1% for volumes exceeding $50B) [7]
Strict Redemption & Reporting Issuers must fulfill redemption requests within two business days and provide monthly, auditor verified reserve reports [7]
Tailored Bank Applications A formalized process for Fed-supervised banks to apply for issuing stablecoins through subsidiaries, requiring detailed business plans and financial disclosures [10]
📈 Market Impact
This proposal brings much-needed regulatory clarity to the digital asset ecosystem. By establishing standardized risk management and reserve requirements it is likely to boost institutional confidence in regulated, bank-backed stablecoins. However the high compliance bar may also accelerate market consolidation favoring well capitalized traditional financial institutions while challenging smaller non-bank issuers to adapt.
Join the Discussion
Do you think bank-issued stablecoins will successfully bridge Traditional Finance (TradFi) and Decentralized Finance (DeFi) or will strict regulatory requirements stifle innovation? Share your thoughts below
#Stablecoins #FederalReserve #CryptoRegulation #TradFi #BinanceSquare
This is for educational purposes only. Not Financial Advice (NFA). Always Do Your Own Research (DYOR).
$SAGA $LSK
83
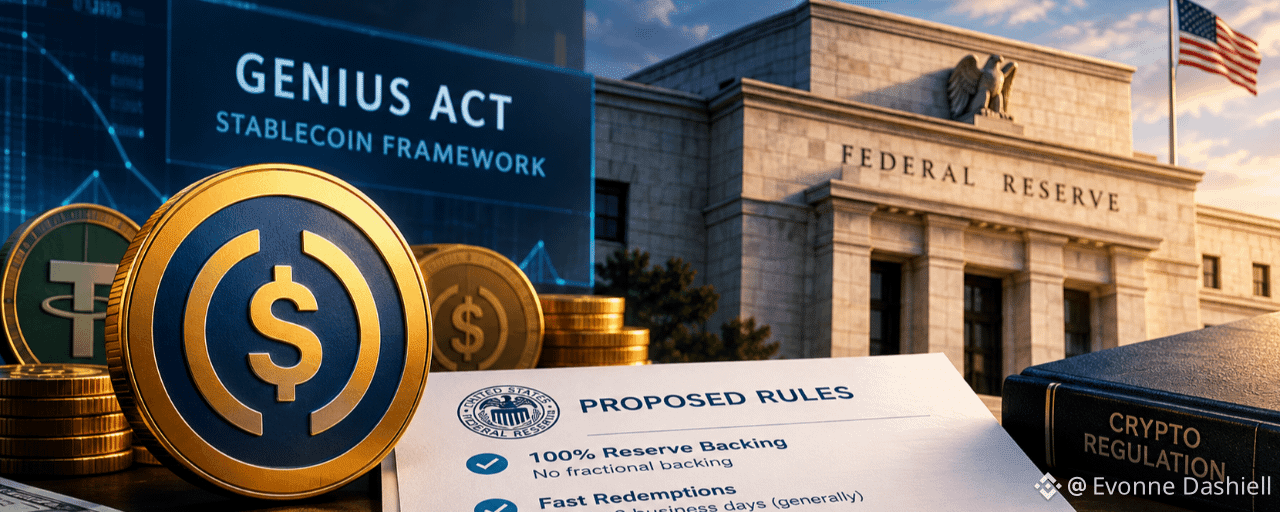
Picture this: Wall Street giants have spent years watching offshore stablecoins capture billions in market share, and now the Federal Reserve is finally laying down the blueprint for traditional banks to enter the arena.
Most crypto investors know the constant anxiety of regulatory crackdowns wiping out liquidity or depegging assets overnight. Holding dry powder shouldn't feel like a high-stakes gamble every time policy headlines hit the wire.
Think back to how the stablecoin landscape evolved from early crypto-native experiments to giants like $USDT dominating global volume. For years, authorities responded with enforcement rather than clear frameworks. This new Fed proposal shifts the playbook, offering regulated commercial banks a structured lane to issue digital cash backed by strict reserve audits and direct central bank oversight.
It sets up an interesting split when compared to synthetic and decentralized models like $ENA. Regulated bank tokens will likely bring unmatched institutional safety and direct corporate settlement rails, but they will also carry strict identity compliance and zero native yield. Decentralized alternatives will continue to compete on capital efficiency and permissionless access.
Rather than wiping out crypto liquidity, bank-issued stablecoins might actually validate the settlement technology on a trillion-dollar scale, dividing the market into regulated institutional cash and crypto-native utility tokens.
Where do you think this goes from here once traditional banks officially launch their own tokens?
#FedProposesRulesForBankIssuedStablecoins #FedOctoberRateHikeOddsRiseTo69
Picture this: Wall Street giants have spent years watching offshore stablecoins capture billions in market share, and now the Federal Reserve is finally laying down the blueprint for traditional banks to enter the arena.
Most crypto investors know the constant anxiety of regulatory crackdowns wiping out liquidity or depegging assets overnight. Holding dry powder shouldn't feel like a high-stakes gamble every time policy headlines hit the wire.
Think back to how the stablecoin landscape evolved from early crypto-native experiments to giants like $USDT dominating global volume. For years, authorities responded with enforcement rather than clear frameworks. This new Fed proposal shifts the playbook, offering regulated commercial banks a structured lane to issue digital cash backed by strict reserve audits and direct central bank oversight.
It sets up an interesting split when compared to synthetic and decentralized models like $ENA . Regulated bank tokens will likely bring unmatched institutional safety and direct corporate settlement rails, but they will also carry strict identity compliance and zero native yield. Decentralized alternatives will continue to compete on capital efficiency and permissionless access.
Rather than wiping out crypto liquidity, bank-issued stablecoins might actually validate the settlement technology on a trillion-dollar scale, dividing the market into regulated institutional cash and crypto-native utility tokens.
Where do you think this goes from here once traditional banks officially launch their own tokens?
#FedProposesRulesForBankIssuedStablecoins #FedOctoberRateHikeOddsRiseTo69
Most crypto investors know the constant anxiety of regulatory crackdowns wiping out liquidity or depegging assets overnight. Holding dry powder shouldn't feel like a high-stakes gamble every time policy headlines hit the wire.
Think back to how the stablecoin landscape evolved from early crypto-native experiments to giants like $USDT dominating global volume. For years, authorities responded with enforcement rather than clear frameworks. This new Fed proposal shifts the playbook, offering regulated commercial banks a structured lane to issue digital cash backed by strict reserve audits and direct central bank oversight.
It sets up an interesting split when compared to synthetic and decentralized models like $ENA . Regulated bank tokens will likely bring unmatched institutional safety and direct corporate settlement rails, but they will also carry strict identity compliance and zero native yield. Decentralized alternatives will continue to compete on capital efficiency and permissionless access.
Rather than wiping out crypto liquidity, bank-issued stablecoins might actually validate the settlement technology on a trillion-dollar scale, dividing the market into regulated institutional cash and crypto-native utility tokens.
Where do you think this goes from here once traditional banks officially launch their own tokens?
#FedProposesRulesForBankIssuedStablecoins #FedOctoberRateHikeOddsRiseTo69
148

#fedproposesrulesforbankissuedstablecoins
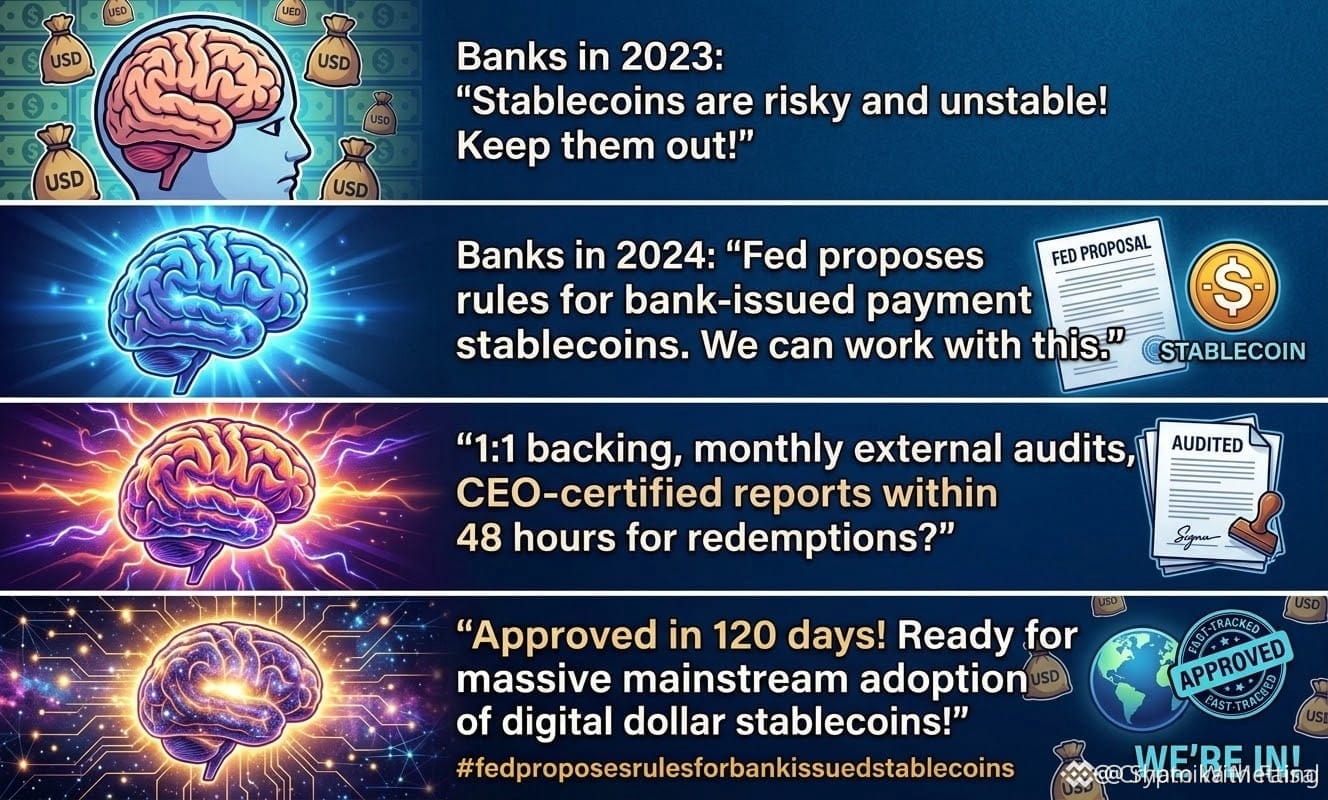
🚨 The Federal Reserve is cracking down on bank-backed stablecoins! 🚨
Is the U.S. banking system ready to fully move to the chain (on-chain)? The Federal Reserve has proposed its new framework for stablecoin payments under the upcoming GENIUS law.
Here’s what a “rulebook” looks like:
🔒 Tight 1:1 coverage: Every token worth $1 must be backed 100% by cash, short-term Treasury bills (≤ 93 days), or insured deposits.
💰 Capital buffers: Issuers must hold operating risk reserves (up to 2% based on trading volume) to absorb unexpected shocks.
🔎 CEO-approved audits: Monthly reserve reports must be audited by independent licensed public accountants (CPAs)—and must be personally signed by the CEO and CFO.
🏦 Fast-track for banks: It details how participating state banks can set up branches/subsidiaries to issue the currency, with the Federal Reserve required to make its decision within 120 days.
This is the bridge connecting traditional finance (TradFi) to digital assets before 2027.
👇 The big question: Will bank-issued stablecoins drive real mass adoption, or will they displace decentralized alternatives?
Please stay tuned
$BTC
$BNB
$SOL
#Stablecoins #GENIUSAct #FedNews
#fedproposesrulesforbankissuedstablecoins
🚨 The Federal Reserve is cracking down on bank-backed stablecoins! 🚨
Is the U.S. banking system ready to fully move to the chain (on-chain)? The Federal Reserve has proposed its new framework for stablecoin payments under the upcoming GENIUS law.
Here’s what a “rulebook” looks like:
🔒 Tight 1:1 coverage: Every token worth $1 must be backed 100% by cash, short-term Treasury bills (≤ 93 days), or insured deposits.
💰 Capital buffers: Issuers must hold operating risk reserves (up to 2% based on trading volume) to absorb unexpected shocks.
🔎 CEO-approved audits: Monthly reserve reports must be audited by independent licensed public accountants (CPAs)—and must be personally signed by the CEO and CFO.
🏦 Fast-track for banks: It details how participating state banks can set up branches/subsidiaries to issue the currency, with the Federal Reserve required to make its decision within 120 days.
This is the bridge connecting traditional finance (TradFi) to digital assets before 2027.
👇 The big question: Will bank-issued stablecoins drive real mass adoption, or will they displace decentralized alternatives?
Please stay tuned
$BTC
$BNB
$SOL
#Stablecoins #GENIUSAct #FedNews
🚨 The Federal Reserve is cracking down on bank-backed stablecoins! 🚨
Is the U.S. banking system ready to fully move to the chain (on-chain)? The Federal Reserve has proposed its new framework for stablecoin payments under the upcoming GENIUS law.
Here’s what a “rulebook” looks like:
🔒 Tight 1:1 coverage: Every token worth $1 must be backed 100% by cash, short-term Treasury bills (≤ 93 days), or insured deposits.
💰 Capital buffers: Issuers must hold operating risk reserves (up to 2% based on trading volume) to absorb unexpected shocks.
🔎 CEO-approved audits: Monthly reserve reports must be audited by independent licensed public accountants (CPAs)—and must be personally signed by the CEO and CFO.
🏦 Fast-track for banks: It details how participating state banks can set up branches/subsidiaries to issue the currency, with the Federal Reserve required to make its decision within 120 days.
This is the bridge connecting traditional finance (TradFi) to digital assets before 2027.
👇 The big question: Will bank-issued stablecoins drive real mass adoption, or will they displace decentralized alternatives?
Please stay tuned
$BTC
$BNB
$SOL
#Stablecoins #GENIUSAct #FedNews
1
10
12.6k
·
--
The Federal Reserve proposes implementing stricter regulation on banks issuing stablecoins to prevent financial risks. This measure is intended to increase transparency and accountability. Stablecoin issuance will be subject to more stringent capital requirements and operational standards. How do you think these new rules will affect the stablecoin market and users?#FedProposesRulesForBankIssuedStablecoins $USDC
#USDC
The Federal Reserve proposes implementing stricter regulation on banks issuing stablecoins to prevent financial risks. This measure is intended to increase transparency and accountability. Stablecoin issuance will be subject to more stringent capital requirements and operational standards. How do you think these new rules will affect the stablecoin market and users?#FedProposesRulesForBankIssuedStablecoins $USDC
#USDC
#USDC
15
💵 $1 Backing Gets Focus
New Fed proposals would require covered stablecoin issuers to maintain qualifying reserves.
Short-term Treasury bills and other highly liquid assets are among the proposed reserves.
Banks seeking to issue stablecoins would also face an application process.
$BTC $ETH $SOL and $BNB remain major spot-market assets.
🔎 The next chapter of digital payments is taking shape.
#fedproposesrulesforbankissuedstablecoins
💵 $1 Backing Gets Focus
New Fed proposals would require covered stablecoin issuers to maintain qualifying reserves.
Short-term Treasury bills and other highly liquid assets are among the proposed reserves.
Banks seeking to issue stablecoins would also face an application process.
$BTC $ETH $SOL and $BNB remain major spot-market assets.
🔎 The next chapter of digital payments is taking shape.
#fedproposesrulesforbankissuedstablecoins
New Fed proposals would require covered stablecoin issuers to maintain qualifying reserves.
Short-term Treasury bills and other highly liquid assets are among the proposed reserves.
Banks seeking to issue stablecoins would also face an application process.
$BTC $ETH $SOL and $BNB remain major spot-market assets.
🔎 The next chapter of digital payments is taking shape.
#fedproposesrulesforbankissuedstablecoins
1
620

·
--
Bullish
#fedproposesrulesforbankissuedstablecoins
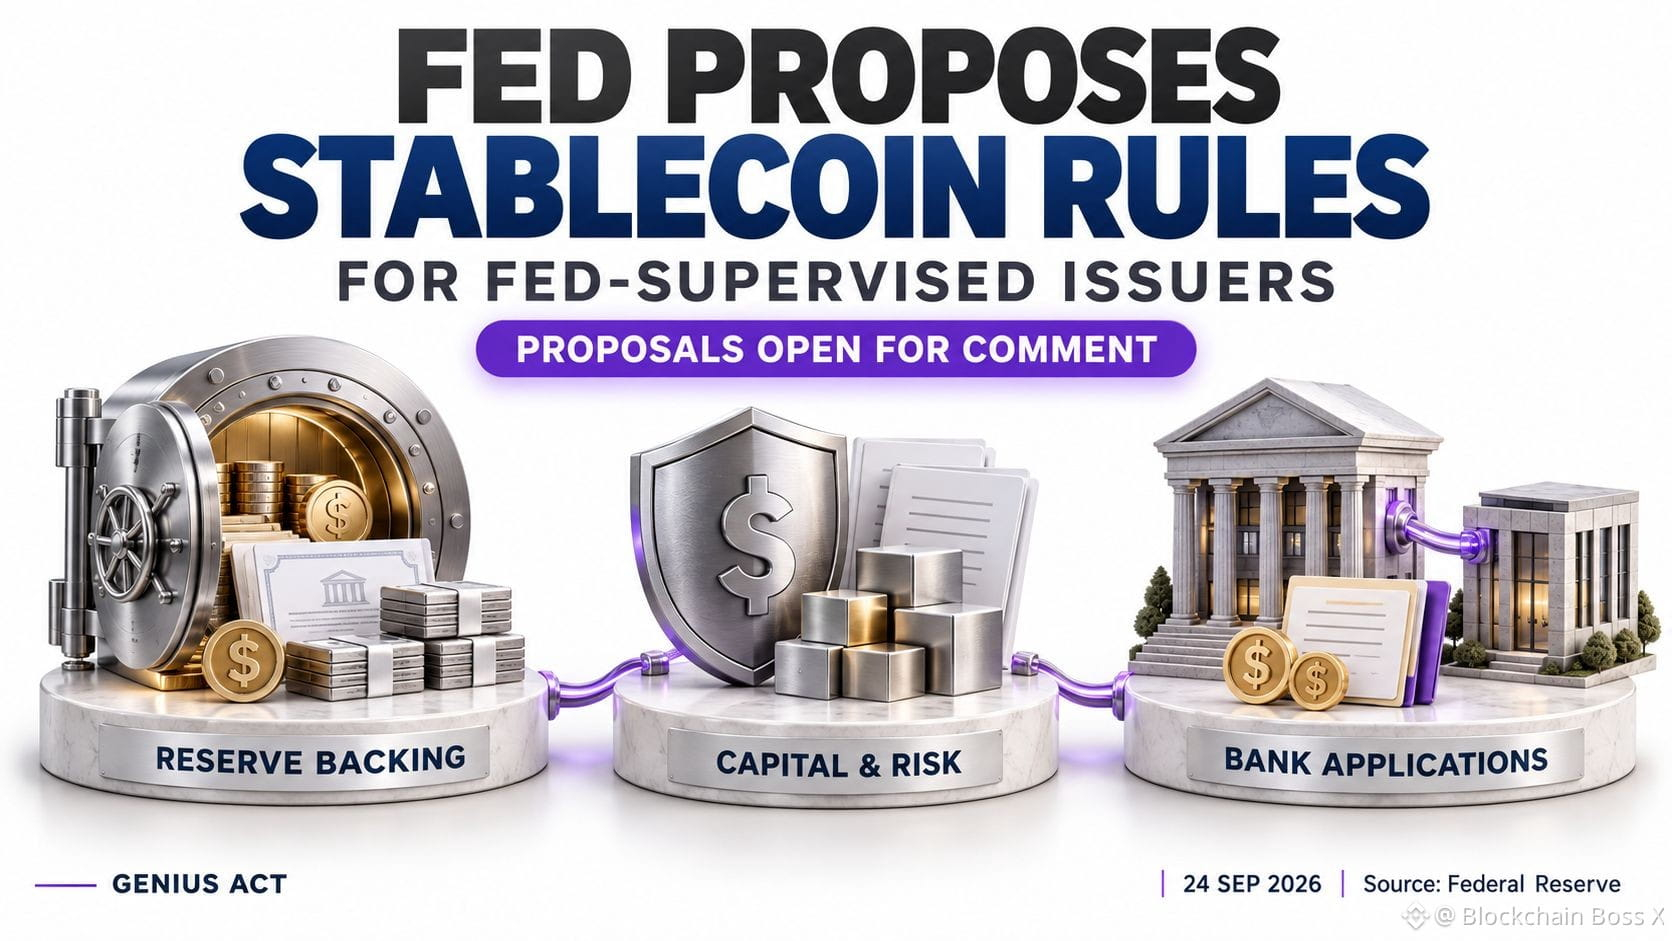
Fed Proposes Stablecoin Rules: What Would Change for Banks?
On September 24, the Federal Reserve released two proposals under the GENIUS Act for payment stablecoin issuers under its supervision.
The first would require full backing with eligible liquid reserves, including short-term Treasury bills. It also outlines capital requirements, risk management standards and rules for safeguarding reserve assets.
The second would establish an application process for supervised banks seeking approval for subsidiaries to issue stablecoins, including submitting business plans and financial information.
These remain proposals. Public comments are due 60 days after publication in the Federal Register.
My take: A clearer approval process could help banks plan stablecoin services with greater confidence. However, reserve and capital requirements would also influence operating costs, product pricing and which institutions find issuance commercially worthwhile.
For users, the practical test is reliable redemption: can they get their money back promptly, including during market stress? Governor Michael Barr specifically emphasized that concern in his response to the proposals.
I’d watch final redemption protections, reserve disclosures and actual bank launches. Clearer rules could support adoption, while payment usage, fees and customer experience would reveal whether these services deliver practical improvements.
Would you choose a bank-issued stablecoin based on the issuer’s reputation, or would redemption terms and fees matter more?
#FedProposesRulesForBankIssuedStablecoins #Stablecoins #GENIUSAct
$BTC $ETH $BNB
{future}(BNBUSDT)
{future}(ETHUSDT)
{future}(BTCUSDT)
#fedproposesrulesforbankissuedstablecoins
Fed Proposes Stablecoin Rules: What Would Change for Banks?
On September 24, the Federal Reserve released two proposals under the GENIUS Act for payment stablecoin issuers under its supervision.
The first would require full backing with eligible liquid reserves, including short-term Treasury bills. It also outlines capital requirements, risk management standards and rules for safeguarding reserve assets.
The second would establish an application process for supervised banks seeking approval for subsidiaries to issue stablecoins, including submitting business plans and financial information.
These remain proposals. Public comments are due 60 days after publication in the Federal Register.
My take: A clearer approval process could help banks plan stablecoin services with greater confidence. However, reserve and capital requirements would also influence operating costs, product pricing and which institutions find issuance commercially worthwhile.
For users, the practical test is reliable redemption: can they get their money back promptly, including during market stress? Governor Michael Barr specifically emphasized that concern in his response to the proposals.
I’d watch final redemption protections, reserve disclosures and actual bank launches. Clearer rules could support adoption, while payment usage, fees and customer experience would reveal whether these services deliver practical improvements.
Would you choose a bank-issued stablecoin based on the issuer’s reputation, or would redemption terms and fees matter more?
#FedProposesRulesForBankIssuedStablecoins #Stablecoins #GENIUSAct
$BTC $ETH $BNB
Fed Proposes Stablecoin Rules: What Would Change for Banks?
On September 24, the Federal Reserve released two proposals under the GENIUS Act for payment stablecoin issuers under its supervision.
The first would require full backing with eligible liquid reserves, including short-term Treasury bills. It also outlines capital requirements, risk management standards and rules for safeguarding reserve assets.
The second would establish an application process for supervised banks seeking approval for subsidiaries to issue stablecoins, including submitting business plans and financial information.
These remain proposals. Public comments are due 60 days after publication in the Federal Register.
My take: A clearer approval process could help banks plan stablecoin services with greater confidence. However, reserve and capital requirements would also influence operating costs, product pricing and which institutions find issuance commercially worthwhile.
For users, the practical test is reliable redemption: can they get their money back promptly, including during market stress? Governor Michael Barr specifically emphasized that concern in his response to the proposals.
I’d watch final redemption protections, reserve disclosures and actual bank launches. Clearer rules could support adoption, while payment usage, fees and customer experience would reveal whether these services deliver practical improvements.
Would you choose a bank-issued stablecoin based on the issuer’s reputation, or would redemption terms and fees matter more?
#FedProposesRulesForBankIssuedStablecoins #Stablecoins #GENIUSAct
$BTC $ETH $BNB
2
1.8k
#fedproposesrulesforbankissuedstablecoins
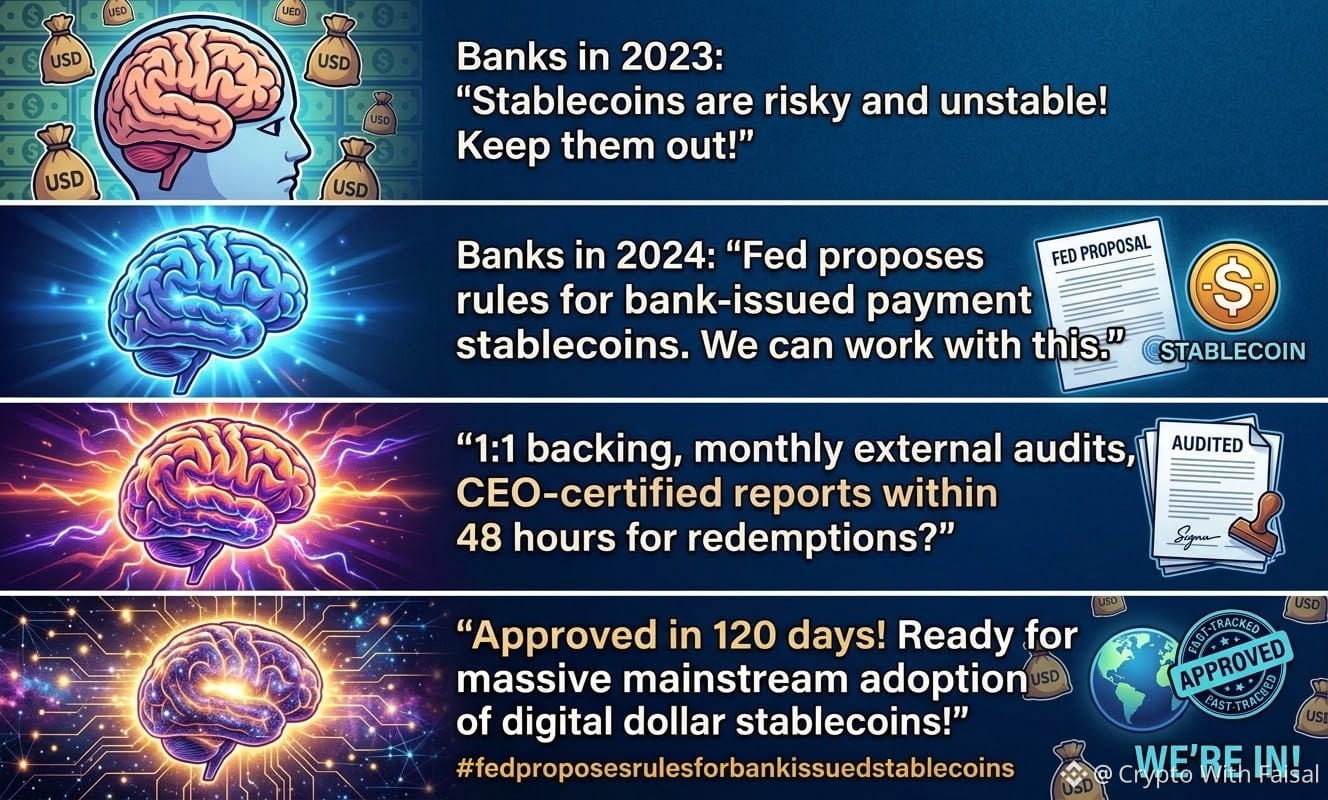
🚨 Fed Drops the Blueprint for Bank-Issued Stablecoins! 🚨
Is the U.S. banking system ready to go full on-chain? The Federal Reserve has proposed its new framework for payment stablecoins under the upcoming GENIUS Act.
Here is what the rulebook looks like:
🔒 1:1 Strict Backing: Every $1 token must be backed 100% by cash, short-term Treasuries (≤93 days), or insured deposits.
⏱️ 48-Hour Cashouts: Redemption requests must be honored within 2 business days. If reserves dip below 1:1, regulators step in immediately to enforce remediation or liquidation.
💰 Capital Buffers: Issuers must hold operational-risk reserve buffers (up to 2% based on volume) to absorb unexpected shocks.
🔎 CEO-Certified Audits: Monthly reserve reports must be audited by external CPAs—and signed off personally by the CEO & CFO.
🏦 Bank Fast-Track: Outlines how state member banks can set up issuance subsidiaries, with the Fed required to rule within 120 days.
This is the bridge connecting TradFi to digital assets ahead of 2027.
👇 Big question: Will bank-issued stablecoins drive true mass adoption, or squeeze out decentralized alternatives? Drop your view!
$BTC
{future}(BTCUSDT)
$BNB
{future}(BNBUSDT)
$SOL
{future}(SOLUSDT)
#Stablecoins #GENIUSAct #FedNews
#fedproposesrulesforbankissuedstablecoins
🚨 Fed Drops the Blueprint for Bank-Issued Stablecoins! 🚨
Is the U.S. banking system ready to go full on-chain? The Federal Reserve has proposed its new framework for payment stablecoins under the upcoming GENIUS Act.
Here is what the rulebook looks like:
🔒 1:1 Strict Backing: Every $1 token must be backed 100% by cash, short-term Treasuries (≤93 days), or insured deposits.
⏱️ 48-Hour Cashouts: Redemption requests must be honored within 2 business days. If reserves dip below 1:1, regulators step in immediately to enforce remediation or liquidation.
💰 Capital Buffers: Issuers must hold operational-risk reserve buffers (up to 2% based on volume) to absorb unexpected shocks.
🔎 CEO-Certified Audits: Monthly reserve reports must be audited by external CPAs—and signed off personally by the CEO & CFO.
🏦 Bank Fast-Track: Outlines how state member banks can set up issuance subsidiaries, with the Fed required to rule within 120 days.
This is the bridge connecting TradFi to digital assets ahead of 2027.
👇 Big question: Will bank-issued stablecoins drive true mass adoption, or squeeze out decentralized alternatives? Drop your view!
$BTC
$BNB
$SOL
#Stablecoins #GENIUSAct #FedNews
🚨 Fed Drops the Blueprint for Bank-Issued Stablecoins! 🚨
Is the U.S. banking system ready to go full on-chain? The Federal Reserve has proposed its new framework for payment stablecoins under the upcoming GENIUS Act.
Here is what the rulebook looks like:
🔒 1:1 Strict Backing: Every $1 token must be backed 100% by cash, short-term Treasuries (≤93 days), or insured deposits.
⏱️ 48-Hour Cashouts: Redemption requests must be honored within 2 business days. If reserves dip below 1:1, regulators step in immediately to enforce remediation or liquidation.
💰 Capital Buffers: Issuers must hold operational-risk reserve buffers (up to 2% based on volume) to absorb unexpected shocks.
🔎 CEO-Certified Audits: Monthly reserve reports must be audited by external CPAs—and signed off personally by the CEO & CFO.
🏦 Bank Fast-Track: Outlines how state member banks can set up issuance subsidiaries, with the Fed required to rule within 120 days.
This is the bridge connecting TradFi to digital assets ahead of 2027.
👇 Big question: Will bank-issued stablecoins drive true mass adoption, or squeeze out decentralized alternatives? Drop your view!
$BTC
$BNB
$SOL
#Stablecoins #GENIUSAct #FedNews
2
273
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BTCRebounds80K
2,158 views
210 Discussing
2
#Binance98PercentReplenished
4,404 views
297 Discussing
3
#USMidterms-WhatAreMarketsExpecting?
225,613 views
1,741 Discussing
4
#USOctoberNFP-AreRateCutsStillPossible
329,351 views
2,616 Discussing
5
#AMDBeatsExpectations-AINarrativeContinues
60,770 views
663 Discussing
6
#CircleQ3Revenue865M
13,072 views
352 Discussing
7
#BinanceIncidentReport
406,616 views
1,945 Discussing
8
#USStocksOpenHigherAsDowGains1.9%
1,060 views
44 Discussing
9
#ADPUSPrivateEmployersAdd86000JobsInOctober
482 views
24 Discussing
10
#FrenchAssemblyPassesSelfCustodiedCryptoReportingAmendment
335 views
12 Discussing