

#fedproposespaymentstablecoinrules
fedproposespaymentstablecoinrules
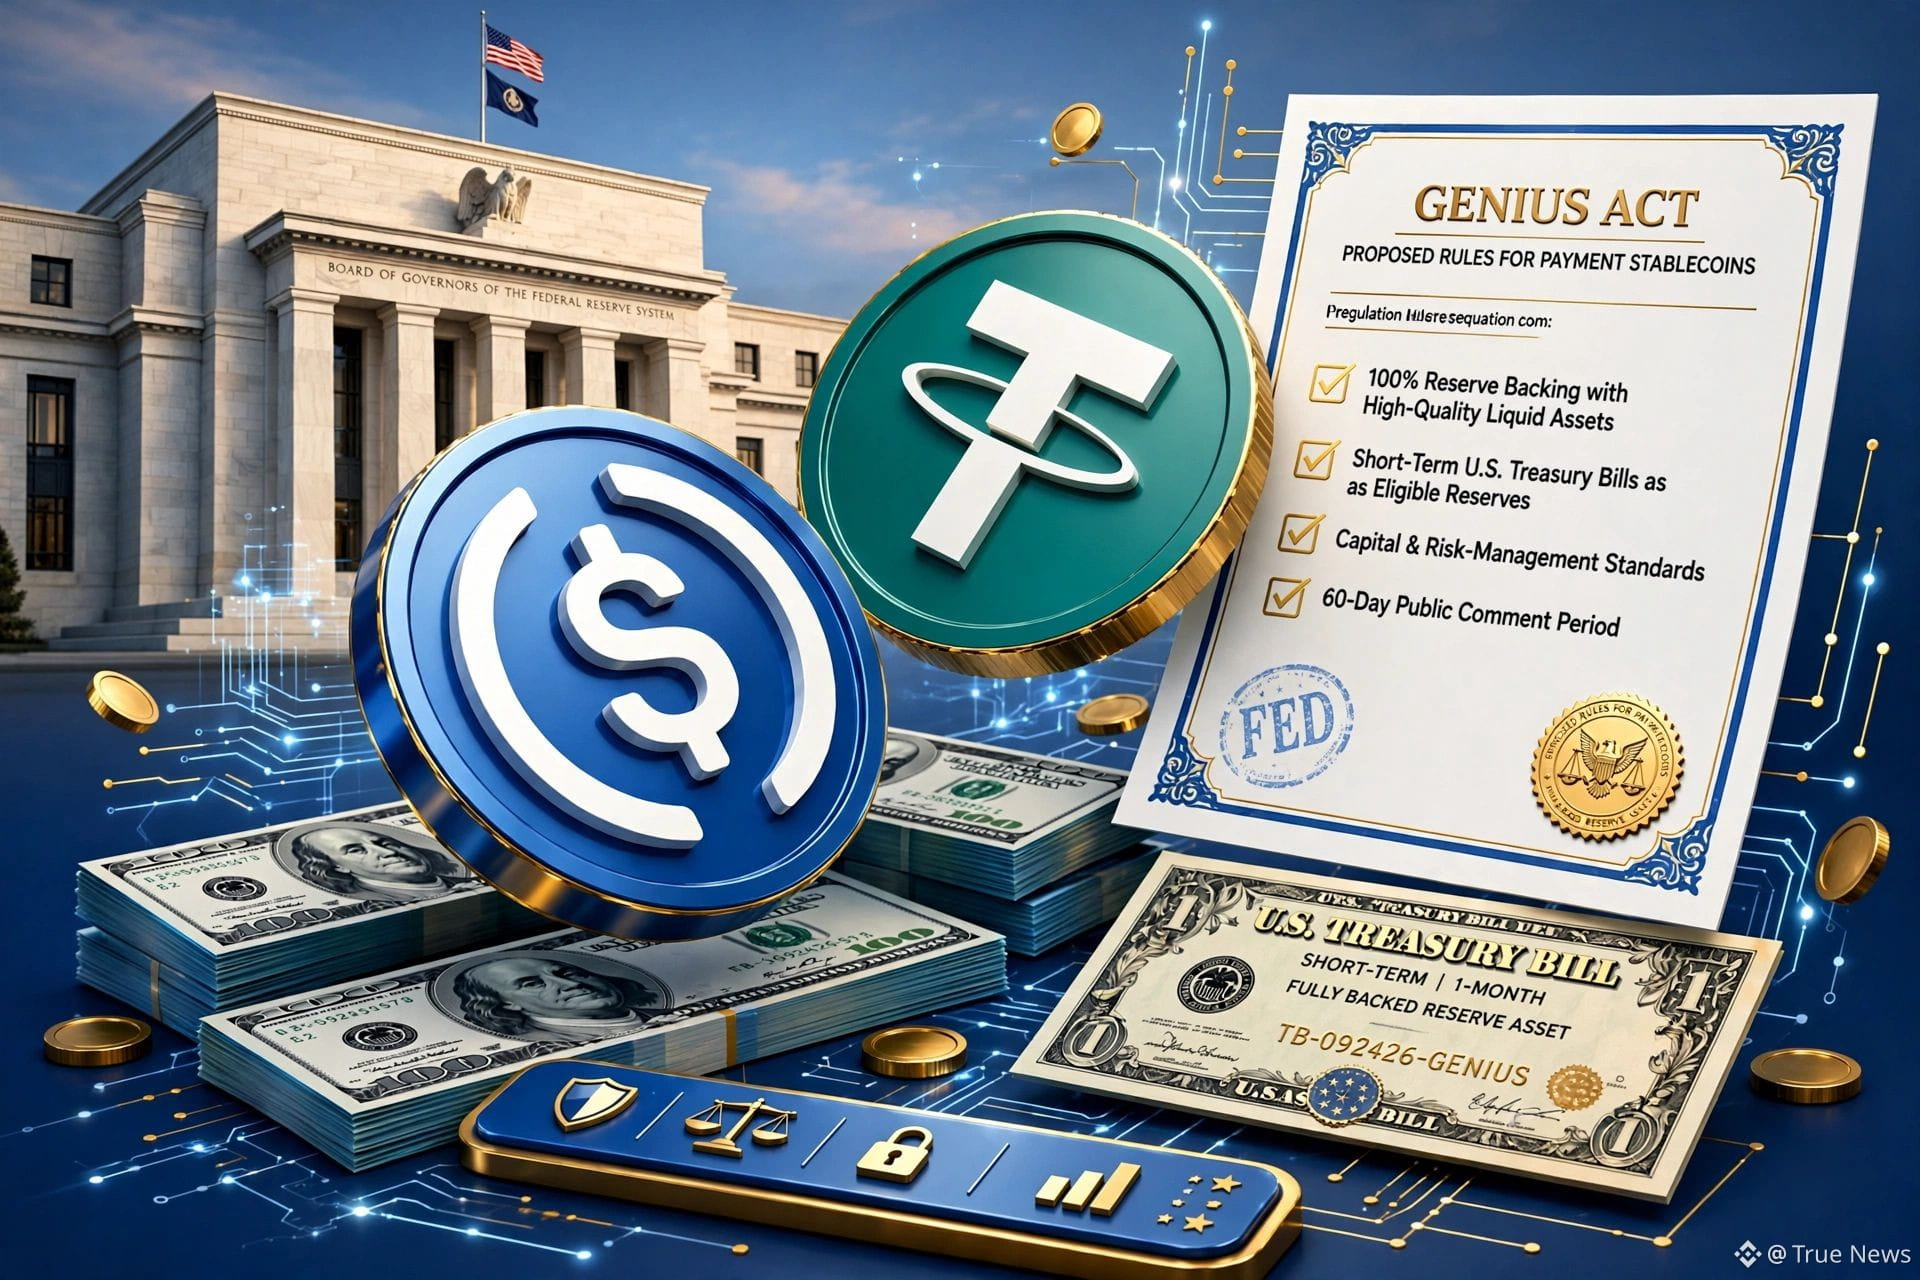
US Federal Reserve has released two proposed rules for payment stablecoins to implement the regulatory authority granted under the GENIUS Act. The proposals would move stablecoin issuance and bank-related crypto activities under formal rulemaking rather than prior enforcement guidance.
Hot
Latest
·
--
BREAKING: Federal Reserve Proposes Payment Stablecoin Rules! 🏦💵
On Sep 24, 2026, the Fed proposed 2 new rules to implement the GENIUS Act.
Key Highlights:
✅ 1:1 Backing Mandatory: Issuers must hold $1 in permitted reserves for every $1 stablecoin. Allowed reserves: cash, Fed balances, short-term T-Bills (≤93 days).
✅ 2-Day Redemption: Issuers must redeem tokens within two business days.
✅ Capital Rules: 2% on first $20B, 1% on amounts over $50B. If shortfall persists, forced liquidation & redemption.
✅ Bank Approval: 120-day Fed decision window, auto-approved if Fed is silent.
60-day public comment period is now open. This is the first concrete prudential framework for stablecoins in the US! Regulation = Mass Adoption?
What do you think, bullish for $USDT & $USDC?
#Stablecoin #Fed #GENIUSAct #CryptoRegulation #BinanceSquare #fedproposespaymentstablecoinrules
1
7
5.1k
·
--
Bullish
🚨 THE FED AND SEC ARE QUIETLY BUILDING THE RULEBOOK CRYPTO HAS BEEN WAITING FOR.
The Fed just proposed a formal framework for payment stablecoin issuers under the GENIUS Act, including 1:1 backing with high-quality liquid reserves such as short-term Treasuries, capital requirements, risk-management standards, custody rules, and a dedicated approval process for banks that want to issue stablecoins.
At almost the same time, SEC staff clarified that for functional crypto networks, things like token buybacks do not automatically create a securities contract by themselves. The SEC also stressed that this is staff guidance, not a binding new rule.
That combination matters.
Fed → clearer rules for digital dollars.
SEC → more clarity for functional crypto assets.
This is not deregulation.
It is something potentially more important:
Crypto is being pulled deeper into the regulated financial system instead of being pushed outside it.
For stablecoins, the direction is obvious: more reserves, more oversight, more bank participation.
And if that framework survives the comment process, the next phase of adoption may look less like “crypto vs banks”…
and more like banks issuing crypto-native money themselves. 👀
$USDC $CRCL $COIN $ETH
{future}(USDCUSDT)
{future}(CRCLUSDT)
{future}(COINUSDT)
#fedproposespaymentstablecoinrules #ChinaMayLetAlibabaByteDanceBuyNvidiaChips #USChinaRelease$30BTariffCutProductLists #SKoreaFSCConsidersVirtualAssetMarketMaker #ChinaIndustrialProfitGrowthSlowsFourthMonth
🚨 THE FED AND SEC ARE QUIETLY BUILDING THE RULEBOOK CRYPTO HAS BEEN WAITING FOR.
The Fed just proposed a formal framework for payment stablecoin issuers under the GENIUS Act, including 1:1 backing with high-quality liquid reserves such as short-term Treasuries, capital requirements, risk-management standards, custody rules, and a dedicated approval process for banks that want to issue stablecoins.
At almost the same time, SEC staff clarified that for functional crypto networks, things like token buybacks do not automatically create a securities contract by themselves. The SEC also stressed that this is staff guidance, not a binding new rule.
That combination matters.
Fed → clearer rules for digital dollars.
SEC → more clarity for functional crypto assets.
This is not deregulation.
It is something potentially more important:
Crypto is being pulled deeper into the regulated financial system instead of being pushed outside it.
For stablecoins, the direction is obvious: more reserves, more oversight, more bank participation.
And if that framework survives the comment process, the next phase of adoption may look less like “crypto vs banks”…
and more like banks issuing crypto-native money themselves. 👀
$USDC $CRCL $COIN $ETH
#fedproposespaymentstablecoinrules #ChinaMayLetAlibabaByteDanceBuyNvidiaChips #USChinaRelease$30BTariffCutProductLists #SKoreaFSCConsidersVirtualAssetMarketMaker #ChinaIndustrialProfitGrowthSlowsFourthMonth
Bega1911:
https://app.binance.com/uni-qr/request-to-pay?billOrderId=456225039178694656&billType=request_a_payment
2
3
4.1k
🚨 BREAKING: FED PROPOSES 2% CAPITAL REQUIREMENT FOR STABLECOIN ISSUERS! 🇺🇸💵
🏦 The proposed framework would require a 2% capital buffer on the first $20 BILLION of token issuance for covered payment stablecoin issuers.
🚫 NO DIRECT YIELD: Payment stablecoin issuers would also be prohibited from paying interest or yield directly to token holders.
📋 The proposal is part of the Federal Reserve’s implementation of the GENIUS Act and includes additional capital and risk-management requirements.
🌐 Stablecoin regulation is entering a more defined phase in the U.S.
👀 Could tighter capital rules reshape the stablecoin market?
Follow for daily updates ⚡
$QNT $ONE $BTW
#FedProposesPaymentStablecoinRules
371
·
--
Bullish
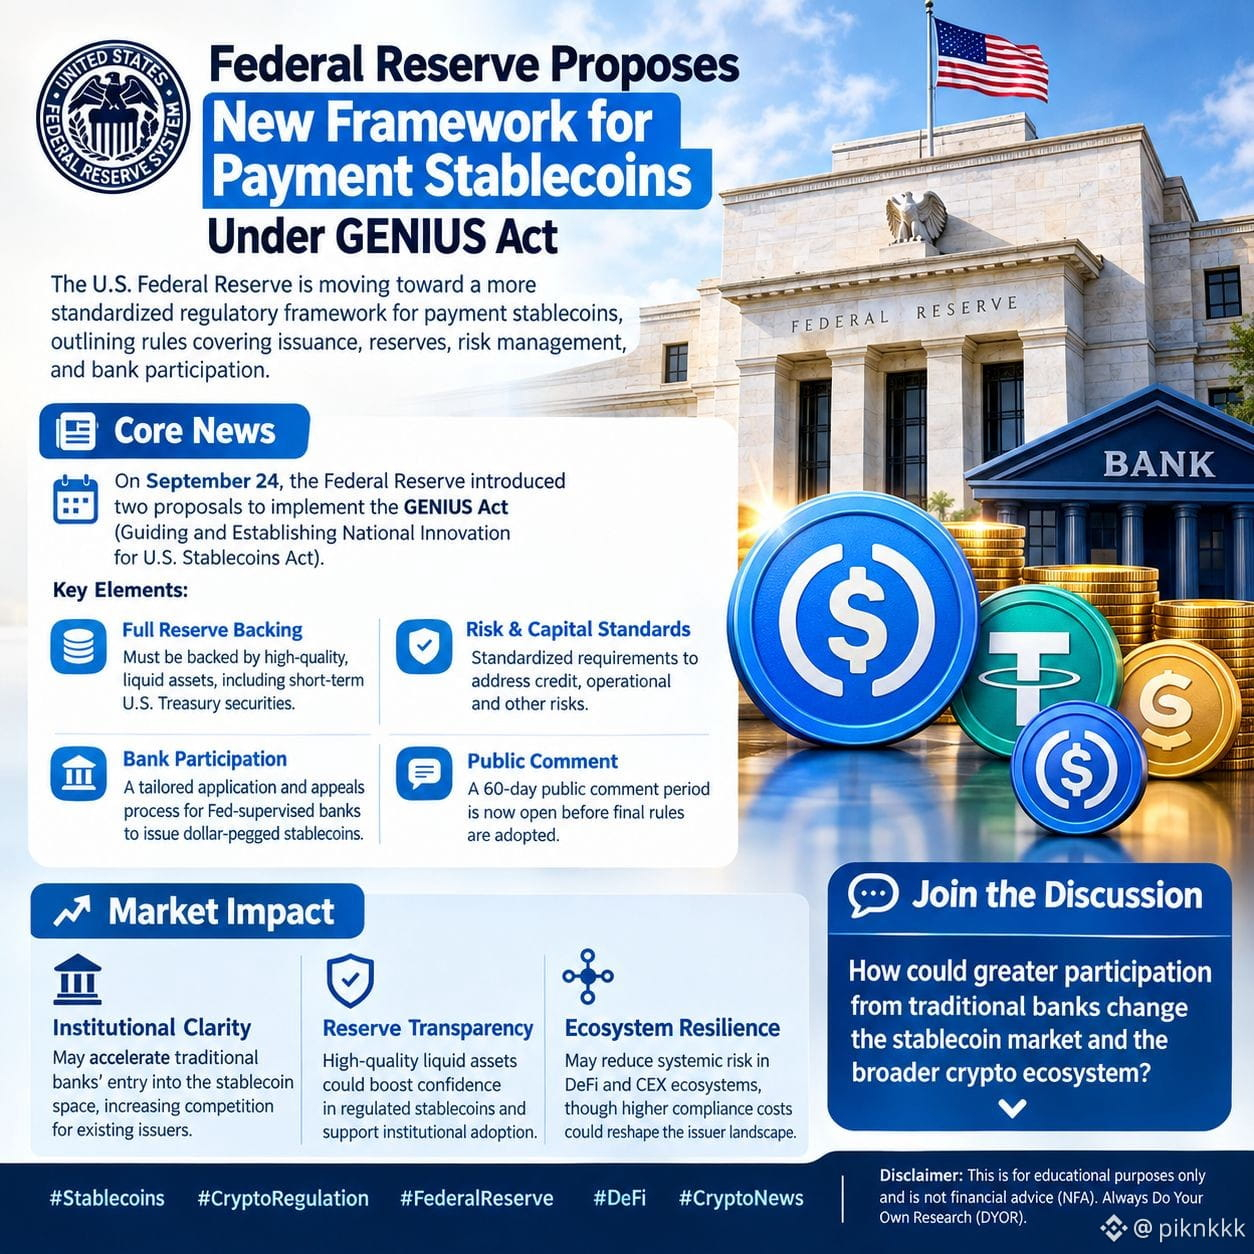
#fedproposespaymentstablecoinrules 🏛️ Fed Unveils New Regulatory Framework for Payment Stablecoins
The regulatory landscape for digital assets is taking a major step forward. The U.S. Federal Reserve has introduced proposals to standardize how payment stablecoins are issued and managed.
📰 Core News Breakdown
On Sept 24, the Fed released rules to implement the GENIUS Act. Key pillars include:
• Full Reserve Backing: Issuers must maintain 1:1 backing of tokens with high-quality, liquid assets like short-term U.S. Treasury bills.
• Strict Capital Standards: Issuers face standardized capital requirements and robust risk-management frameworks to mitigate operational risks.
• Bank Integration: A tailored application process is established for Fed-supervised banks to legally issue dollar-pegged stablecoins.
• A 60-day public comment period is now open before finalization.
📊 Market Impact Analysis
• Institutional Clarity: Clear pathways will accelerate traditional bank entry into the stablecoin sector, fostering healthy competition.
• Enhanced Trust: Mandating high-quality liquid assets strengthens the safety of regulated stablecoins, boosting institutional confidence.
• Ecosystem Resilience: Standardized frameworks reduce systemic risk in DeFi and CEX ecosystems, though compliance costs may reshape issuers.
💬 Join the Discussion
How will traditional banks entering the stablecoin space impact current market leaders and the broader DeFi ecosystem? Share your insights below! 👇
#Stablecoins #CryptoRegulation #FederalReserve #DeFi #CryptoNews
This content is for educational purposes only. Not Financial Advice (NFA). Always Do Your Own Research (DYOR).
$GRT $SEI $PUMP
{future}(PUMPUSDT)
{future}(SEIUSDT)
{future}(GRTUSDT)
#fedproposespaymentstablecoinrules 🏛️ Fed Unveils New Regulatory Framework for Payment Stablecoins
The regulatory landscape for digital assets is taking a major step forward. The U.S. Federal Reserve has introduced proposals to standardize how payment stablecoins are issued and managed.
📰 Core News Breakdown
On Sept 24, the Fed released rules to implement the GENIUS Act. Key pillars include:
• Full Reserve Backing: Issuers must maintain 1:1 backing of tokens with high-quality, liquid assets like short-term U.S. Treasury bills.
• Strict Capital Standards: Issuers face standardized capital requirements and robust risk-management frameworks to mitigate operational risks.
• Bank Integration: A tailored application process is established for Fed-supervised banks to legally issue dollar-pegged stablecoins.
• A 60-day public comment period is now open before finalization.
📊 Market Impact Analysis
• Institutional Clarity: Clear pathways will accelerate traditional bank entry into the stablecoin sector, fostering healthy competition.
• Enhanced Trust: Mandating high-quality liquid assets strengthens the safety of regulated stablecoins, boosting institutional confidence.
• Ecosystem Resilience: Standardized frameworks reduce systemic risk in DeFi and CEX ecosystems, though compliance costs may reshape issuers.
💬 Join the Discussion
How will traditional banks entering the stablecoin space impact current market leaders and the broader DeFi ecosystem? Share your insights below! 👇
#Stablecoins #CryptoRegulation #FederalReserve #DeFi #CryptoNews
This content is for educational purposes only. Not Financial Advice (NFA). Always Do Your Own Research (DYOR).
$GRT $SEI $PUMP
201
·
--
#fedproposespaymentstablecoinrules FED’S STABLECOIN RULES: A BIG CRYPTO SIGNAL
The Federal Reserve has announced two rulemaking packages to carry out the GENIUS Act placing payment stablecoins under rules.
Key points:
• 100 percent reserve backing with assets, such as short‑term Treasuries.
• Capital and risk controls.
• Redemption and reporting requirements.
• A dedicated approval process, for banks supervised by the Federal Reserve that want to issue stablecoins.
• Public comments will stay open for sixty days.
For traders this could be important because stablecoins link banking, dollar liquidity, exchanges and on‑chain payments.
Could stablecoin adoption speed up? What effect could this have on BTC. Altcoins? Share your view!..#stablecoin #crypto #cryptotrading #TradingSignals
$BTC $ETH $BNB
{future}(BTCUSDT)
{future}(ETHUSDT)
{future}(BNBUSDT)
#fedproposespaymentstablecoinrules FED’S STABLECOIN RULES: A BIG CRYPTO SIGNAL
The Federal Reserve has announced two rulemaking packages to carry out the GENIUS Act placing payment stablecoins under rules.
Key points:
• 100 percent reserve backing with assets, such as short‑term Treasuries.
• Capital and risk controls.
• Redemption and reporting requirements.
• A dedicated approval process, for banks supervised by the Federal Reserve that want to issue stablecoins.
• Public comments will stay open for sixty days.
For traders this could be important because stablecoins link banking, dollar liquidity, exchanges and on‑chain payments.
Could stablecoin adoption speed up? What effect could this have on BTC. Altcoins? Share your view!..#stablecoin #crypto #cryptotrading #TradingSignals
$BTC $ETH $BNB
434
·
--
#fedproposespaymentstablecoinrules
FED PROPOSES PAYMENT STABLECOIN RULES
The wait is over.
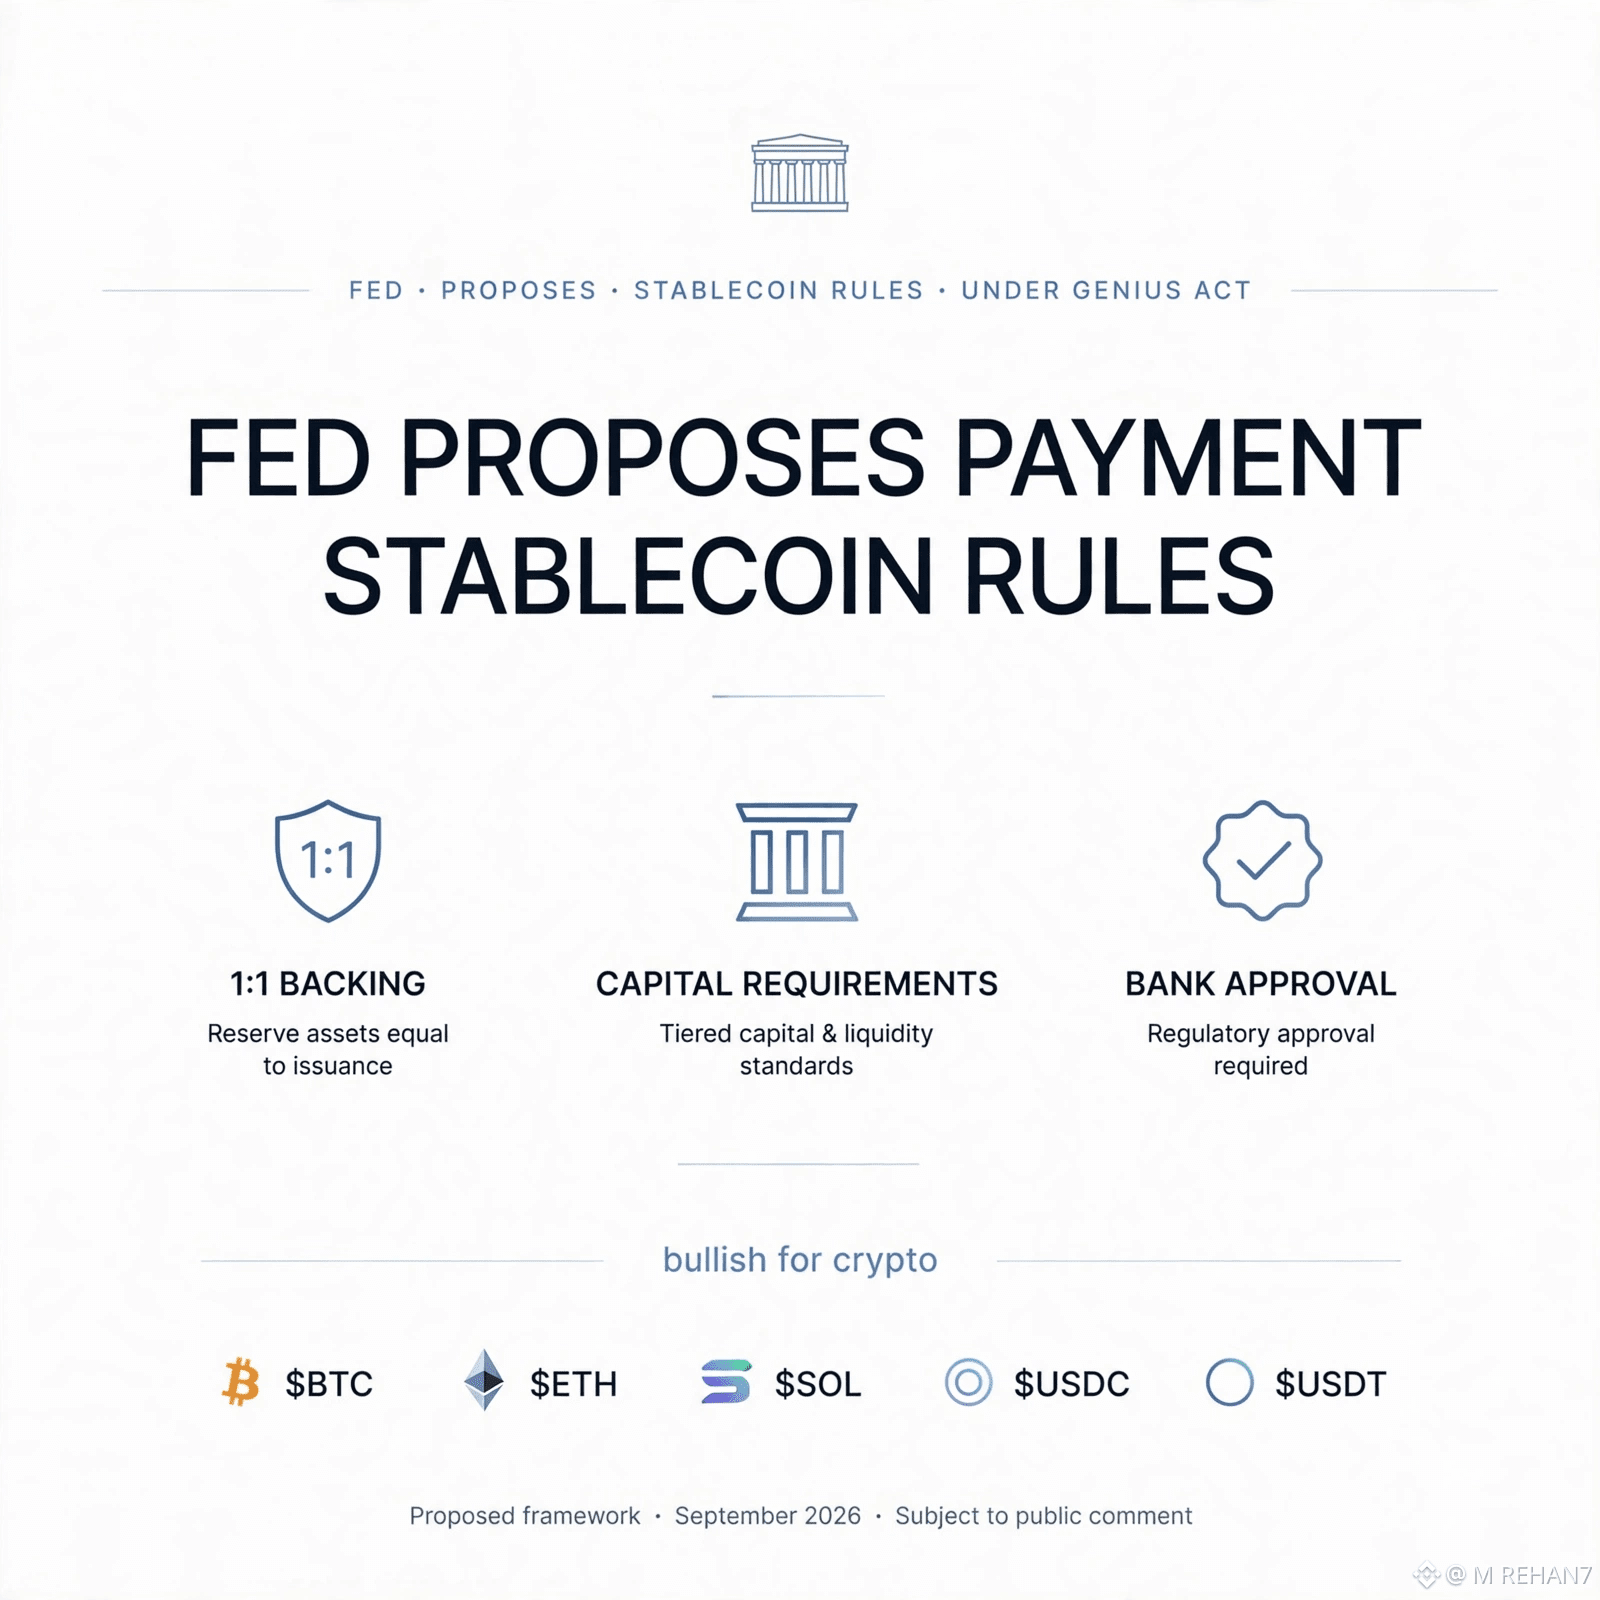
Fed Board — Sept 24, 2026 — proposed GENIUS Act framework:
• 1:1 BACKING: USDT USDC must be backed 100% by short-term Treasuries + Cash
• CAPITAL REQUIREMENTS: Tiered capital & liquidity standards mandatory
• BANK APPROVAL: Licensed pathway for banks to issue stablecoins by 2027
SEC also clarified: Token buybacks on functional networks ≠ securities.
This is not deregulation.
This is institutionalization.
Fed is pulling stablecoins INTO banking, not pushing them out.
Why it matters for us:
Trusted $USDC $USDT = Deeper $BTC $ETH $SOL liquidity
Bank-issued stablecoins = $170B market -> $300B+
Less FUD, more adoption
Biggest bullish signal for BTC $ETH $SOL since ETF approval.
Are you bullish or bearish on this?
I am BULLISH BTC $ETH $SOL USDC USDT
#fedproposespaymentstablecoinrules #BTC #ETH #SOL
3
326


·
--
Bullish
#fedproposespaymentstablecoinrules
Fed Proposes Payment Stablecoin Rules: What Would Change for Issuers?
Stablecoin adoption depends partly on confidence in the assets and systems behind each token.
On September 24, 2026, the Federal Reserve requested public feedback on two proposals under the GENIUS Act, addressing payment stablecoin issuers under its supervision and related banking activities.
The first would require full backing with eligible reserve assets, including short-term Treasury bills. It also addresses capital requirements, risk management and the safekeeping of assets backing stablecoins.
The second would establish an application process for Fed-supervised banks seeking approval for stablecoin issuance, requiring business plans, financial information and supporting documents.
These remain proposals. The comment period closes 60 days after publication in the Federal Register, and the final requirements may change.
My take: Clearer reserve and operating requirements could help banks and businesses assess stablecoin issuers more consistently. Compliance also costs money, so the final design could influence which firms can compete and how services are priced.
For users, the practical questions remain straightforward: how accessible is redemption, who safeguards the reserves, and how reliably do operations function during stress?
I would watch whether the final framework combines stronger protections with workable entry requirements. That balance could shape competition and the usefulness of payment stablecoins.
Which matters most to you: reserve transparency, reliable redemption or greater issuer competition?
#FedProposesPaymentStablecoinRules #Stablecoins #GENIUSAct
$QNT $BTW $ONE
{future}(ONEUSDT)
{future}(BTWUSDT)
{future}(QNTUSDT)
#fedproposespaymentstablecoinrules
Fed Proposes Payment Stablecoin Rules: What Would Change for Issuers?
Stablecoin adoption depends partly on confidence in the assets and systems behind each token.
On September 24, 2026, the Federal Reserve requested public feedback on two proposals under the GENIUS Act, addressing payment stablecoin issuers under its supervision and related banking activities.
The first would require full backing with eligible reserve assets, including short-term Treasury bills. It also addresses capital requirements, risk management and the safekeeping of assets backing stablecoins.
The second would establish an application process for Fed-supervised banks seeking approval for stablecoin issuance, requiring business plans, financial information and supporting documents.
These remain proposals. The comment period closes 60 days after publication in the Federal Register, and the final requirements may change.
My take: Clearer reserve and operating requirements could help banks and businesses assess stablecoin issuers more consistently. Compliance also costs money, so the final design could influence which firms can compete and how services are priced.
For users, the practical questions remain straightforward: how accessible is redemption, who safeguards the reserves, and how reliably do operations function during stress?
I would watch whether the final framework combines stronger protections with workable entry requirements. That balance could shape competition and the usefulness of payment stablecoins.
Which matters most to you: reserve transparency, reliable redemption or greater issuer competition?
#FedProposesPaymentStablecoinRules #Stablecoins #GENIUSAct
$QNT $BTW $ONE
995
#FedProposesPaymentStablecoinRules
🚨 FED PROPOSES NEW STABLECOIN RULES
The U.S. Federal Reserve has proposed two new rules for payment stablecoins as part of implementing the GENIUS Act. The proposals focus on reserve requirements, capital and risk-management standards for stablecoin issuers under the Fed’s supervision. �
Reuters +1
💵 Why This Matters for Crypto
Stablecoins such as USDC and other dollar-linked tokens are an important part of the crypto market.
Under the proposed framework, supervised stablecoin issuers would need to back their payment stablecoins with permitted reserve assets, including assets such as short-term U.S. Treasury bills. �
Reuters
The Fed is also proposing standards around capital, risk management and the regulatory process for bank-related stablecoin activities. �
VitalLaw
📌 The important point: These are proposed rules, not final rules yet. The Federal Reserve has opened a public-comment process.
🔥 Market Question
Could clearer stablecoin regulation increase confidence and adoption in crypto payments?
USDC, USDT or another stablecoin — which one do you think will benefit most from clearer regulation? 👇
#Binance #Stablecoin #USDC #USDT #CryptoNews #Crypto #GENIUSAct #FederalReserve #Bitcoin #Ethereum #BNB #BinanceSquare #CryptoMarket #Blockchain
7
·
--
🚨 THE FED ISN’T JUST REGULATING STABLECOINS — IT’S TRYING TO PREVENT THE NEXT DIGITAL BANK RUN.
The Fed’s new GENIUS Act proposals would force supervised stablecoin issuers to hold fully backed, highly liquid reserves, meet standardized capital requirements, and maintain systems that can support reliable redemptions even during market stress.
That’s the underrated part.
The real risk in stablecoins was never just whether $1 = $1 on a normal day.
It’s whether everyone can get their dollar back at the same time when markets panic.
Fed Governor Michael Barr explicitly highlighted that stablecoins need to remain redeemable at par even during periods of stress, when both issuers and reserve assets can come under pressure.
So this framework is effectively trying to turn stablecoins from:
“crypto cash” → regulated digital cash infrastructure.
If finalized, the biggest advantage may go to issuers that can already handle liquidity, custody, reserves and compliance at institutional scale.
That’s why this may matter more for $CRCL than for the stablecoin tokens themselves.
The next stablecoin race may not be about who grows fastest.
It may be about who survives a run. 👀
{stock_us}(COIN.US)
{stock_us}(CRCL.US)
{spot}(USDCUSDT)
$CRCL.US $COIN.US $USDC #BTCFallsBelow$83000 #FedProposesPaymentStablecoinRules #ChinaMayLetAlibabaByteDanceBuyNvidiaChips #USChinaRelease$30BTariffCutProductLists #SKoreaFSCConsidersVirtualAssetMarketMaker
🚨 THE FED ISN’T JUST REGULATING STABLECOINS — IT’S TRYING TO PREVENT THE NEXT DIGITAL BANK RUN.
The Fed’s new GENIUS Act proposals would force supervised stablecoin issuers to hold fully backed, highly liquid reserves, meet standardized capital requirements, and maintain systems that can support reliable redemptions even during market stress.
That’s the underrated part.
The real risk in stablecoins was never just whether $1 = $1 on a normal day.
It’s whether everyone can get their dollar back at the same time when markets panic.
Fed Governor Michael Barr explicitly highlighted that stablecoins need to remain redeemable at par even during periods of stress, when both issuers and reserve assets can come under pressure.
So this framework is effectively trying to turn stablecoins from:
“crypto cash” → regulated digital cash infrastructure.
If finalized, the biggest advantage may go to issuers that can already handle liquidity, custody, reserves and compliance at institutional scale.
That’s why this may matter more for $CRCL than for the stablecoin tokens themselves.
The next stablecoin race may not be about who grows fastest.
It may be about who survives a run. 👀
$CRCL.US $COIN.US $USDC #BTCFallsBelow$83000 #FedProposesPaymentStablecoinRules #ChinaMayLetAlibabaByteDanceBuyNvidiaChips #USChinaRelease$30BTariffCutProductLists #SKoreaFSCConsidersVirtualAssetMarketMaker
20
#FedProposesPaymentStablecoinRules
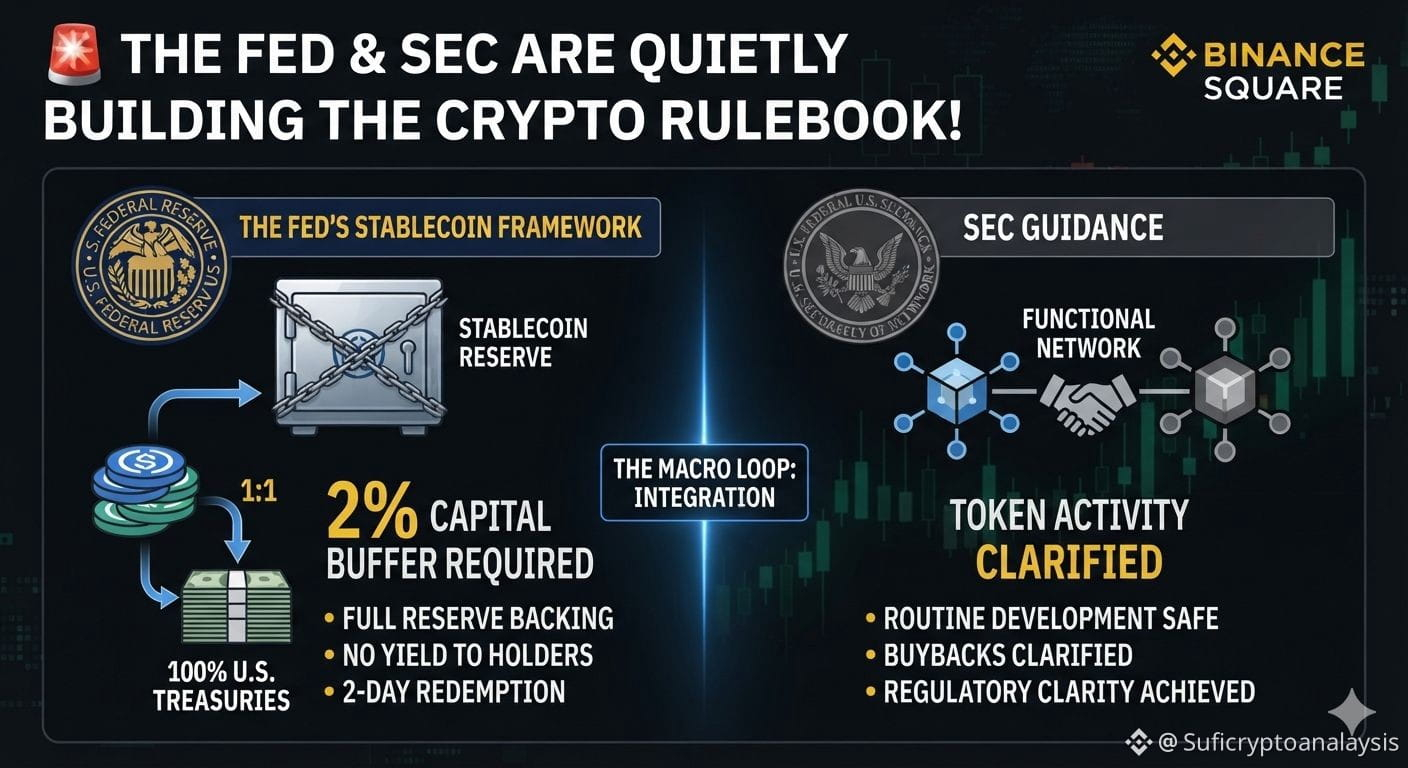
🚨 THE FED & SEC ARE QUIETLY BUILDING THE CRYPTO RULEBOOK! 🇺🇸💵The U.S. regulatory landscape just shifted dramatically, pulling digital assets deeper into the traditional financial system rather than pushing them out. If you are trading or holding right now, these two parallel moves change the macro landscape entirely.🏛️ 1. The Fed's Strict Payment Stablecoin FrameworkUnder the GENIUS Act, the Federal Reserve proposed twin packages establishing comprehensive reserve, operational, and capital requirements:100% High-Quality Reserves: Tokens must be backed 1:1 by liquid assets like short-term U.S. Treasuries (93 days or less maturity).The 2% Capital Buffer: Issuers face a mandatory 2% capital requirement on the first $20 billion of token issuance to address operational and credit risks.Strict Yield Prohibition: Issuers are completely prohibited from paying interest or yield directly to token holders.Redemption Rules: Fulfilling cash/deposit redemptions must happen within two business days.⚖️ 2. The SEC & Coreen's Regulatory TakeSEC staff clarified that activities like token buybacks and active network development do not automatically trigger securities contracts on functional networks, offering builders more breathing room. Meanwhile, incorporating Coreen's market perspective highlights that these evolving frameworks demand tighter risk management across both decentralized and centralized portfolios.📊 Token Impact Analysis: What This Means For Your Bags$USDC & Stablecoins: Margin compression will favor fully compliant, bank-backed entities.$ETH & Layer 1s: Regulatory clarity serves as a long-term institutional catalyst as ETH eyes levels toward $3,050–$3,450.$SOL : Watching support at $113–$118 amid whale exchange transfers and ETF inflows.💡 The Macro Loop: The Real Winner?Integration over deregulation means stablecoins drive Treasury demand, cementing the digital dollar's reach.What is your take? Let me know below! 👇#FedProposesPaymentStablecoinRules #CryptoRegulation #Ethereum #Solana
🚨 THE FED & SEC ARE QUIETLY BUILDING THE CRYPTO RULEBOOK! 🇺🇸💵The U.S. regulatory landscape just shifted dramatically, pulling digital assets deeper into the traditional financial system rather than pushing them out. If you are trading or holding right now, these two parallel moves change the macro landscape entirely.🏛️ 1. The Fed's Strict Payment Stablecoin FrameworkUnder the GENIUS Act, the Federal Reserve proposed twin packages establishing comprehensive reserve, operational, and capital requirements:100% High-Quality Reserves: Tokens must be backed 1:1 by liquid assets like short-term U.S. Treasuries (93 days or less maturity).The 2% Capital Buffer: Issuers face a mandatory 2% capital requirement on the first $20 billion of token issuance to address operational and credit risks.Strict Yield Prohibition: Issuers are completely prohibited from paying interest or yield directly to token holders.Redemption Rules: Fulfilling cash/deposit redemptions must happen within two business days.⚖️ 2. The SEC & Coreen's Regulatory TakeSEC staff clarified that activities like token buybacks and active network development do not automatically trigger securities contracts on functional networks, offering builders more breathing room. Meanwhile, incorporating Coreen's market perspective highlights that these evolving frameworks demand tighter risk management across both decentralized and centralized portfolios.📊 Token Impact Analysis: What This Means For Your Bags$USDC & Stablecoins: Margin compression will favor fully compliant, bank-backed entities.$ETH & Layer 1s: Regulatory clarity serves as a long-term institutional catalyst as ETH eyes levels toward $3,050–$3,450.$SOL : Watching support at $113–$118 amid whale exchange transfers and ETF inflows.💡 The Macro Loop: The Real Winner?Integration over deregulation means stablecoins drive Treasury demand, cementing the digital dollar's reach.What is your take? Let me know below! 👇#FedProposesPaymentStablecoinRules #CryptoRegulation #Ethereum #Solana
47
·
--
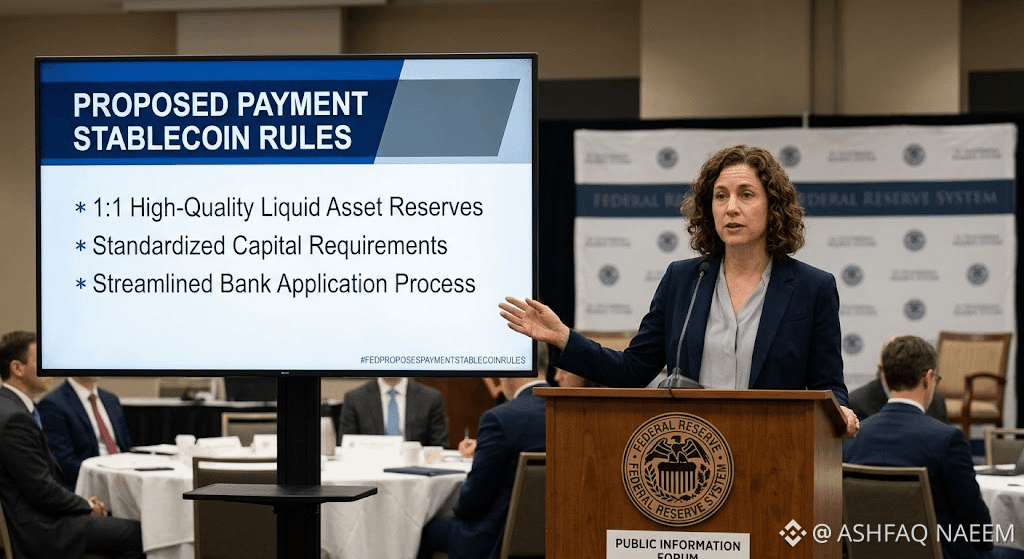
The Federal Reserve's proposed stablecoin rules under the GENIUS Act (issued September 24, 2026) focus on two main areas:
1:1 Reserve & Capital Standards: Supervised payment stablecoin issuers must fully back tokens with high-quality liquid assets (like short-term U.S. Treasuries) and maintain standardized capital buffers for operational and credit risk.
Bank Application Framework: Establishes a formal application, review, and appeals process for Fed-supervised banks seeking to create stablecoin-issuing subsidiaries.
The draft rules are open for a 60-day public comment period.
#fedproposespaymentstablecoinrules
#BTC $BTC #USDC✅ $USDC
{spot}(USDCUSDT)
{future}(BTCUSDT)
The Federal Reserve's proposed stablecoin rules under the GENIUS Act (issued September 24, 2026) focus on two main areas:
1:1 Reserve & Capital Standards: Supervised payment stablecoin issuers must fully back tokens with high-quality liquid assets (like short-term U.S. Treasuries) and maintain standardized capital buffers for operational and credit risk.
Bank Application Framework: Establishes a formal application, review, and appeals process for Fed-supervised banks seeking to create stablecoin-issuing subsidiaries.
The draft rules are open for a 60-day public comment period.
#fedproposespaymentstablecoinrules
#BTC $BTC #USDC✅ $USDC
1
37
·
--
🚨 THE UNDERRATED STABLECOIN TRADE ISN’T CRYPTO — IT’S U.S. TREASURIES.
The Fed’s proposed stablecoin framework would require regulated issuers to back payment stablecoins with high-quality liquid reserves, including short-term U.S. Treasury bills, while also setting capital and custody standards.
That creates a less obvious macro loop:
More stablecoin adoption → more reserve demand → more Treasury demand.
At the same time, SEC staff is giving functional crypto networks more room to operate, clarifying that activities like token buybacks or continued network development do not automatically create a securities contract.
Put those two together and the bigger story is not simply “crypto regulation.”
It’s this:
Washington may be turning stablecoins into a new distribution rail for dollar-denominated government debt — while simultaneously making the crypto layer easier to build on.
That could strengthen the dollar’s digital reach, increase demand for tokenized cash products, and make stablecoin issuers much more strategically important.
The hidden winner of the stablecoin boom may be the U.S. Treasury market itself. 👀
{stock_us}(COIN.US)
{future}(CRCLUSDT)
{future}(ETHUSDT)
$CRCL $COIN $USDC $ETH
#FedProposesPaymentStablecoinRules #ChinaMayLetAlibabaByteDanceBuyNvidiaChips #USChinaRelease$30BTariffCutProductLists #SKoreaFSCConsidersVirtualAssetMarketMaker #Fed
🚨 THE UNDERRATED STABLECOIN TRADE ISN’T CRYPTO — IT’S U.S. TREASURIES.
The Fed’s proposed stablecoin framework would require regulated issuers to back payment stablecoins with high-quality liquid reserves, including short-term U.S. Treasury bills, while also setting capital and custody standards.
That creates a less obvious macro loop:
More stablecoin adoption → more reserve demand → more Treasury demand.
At the same time, SEC staff is giving functional crypto networks more room to operate, clarifying that activities like token buybacks or continued network development do not automatically create a securities contract.
Put those two together and the bigger story is not simply “crypto regulation.”
It’s this:
Washington may be turning stablecoins into a new distribution rail for dollar-denominated government debt — while simultaneously making the crypto layer easier to build on.
That could strengthen the dollar’s digital reach, increase demand for tokenized cash products, and make stablecoin issuers much more strategically important.
The hidden winner of the stablecoin boom may be the U.S. Treasury market itself. 👀
$CRCL $COIN $USDC $ETH
#FedProposesPaymentStablecoinRules #ChinaMayLetAlibabaByteDanceBuyNvidiaChips #USChinaRelease$30BTariffCutProductLists #SKoreaFSCConsidersVirtualAssetMarketMaker #Fed
1
22
·
--
#FedProposesPaymentStablecoinRules
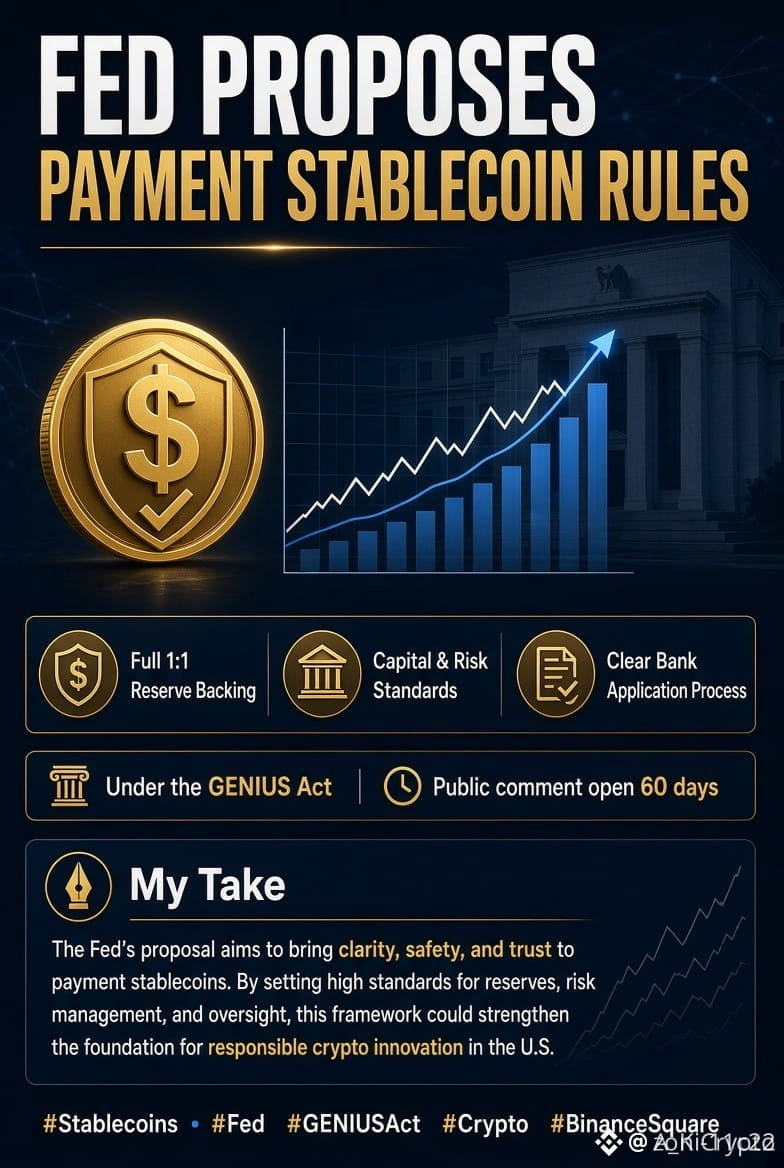
The Federal Reserve has proposed a landmark regulatory framework for payment stablecoin under the GENIUS Act, moving crypto assets deeper into the traditional $US
{alpha}(CT_7840xee962a61432231c2ede6946515beb02290cb516ad087bb06a731e922b2a5f57a::us::US)
financial system. Published on September 24, 2026, the twin proposals establish comprehensive reserve, operational, and capital requirements for stablecoin issuers. [1]
$BNB
{future}(BNBUSDT)
#FedProposesPaymentStablecoinRules
The Federal Reserve has proposed a landmark regulatory framework for payment stablecoin under the GENIUS Act, moving crypto assets deeper into the traditional $US
financial system. Published on September 24, 2026, the twin proposals establish comprehensive reserve, operational, and capital requirements for stablecoin issuers. [1]
$BNB
1
81
·
--
#FedProposesPaymentStablecoinRules
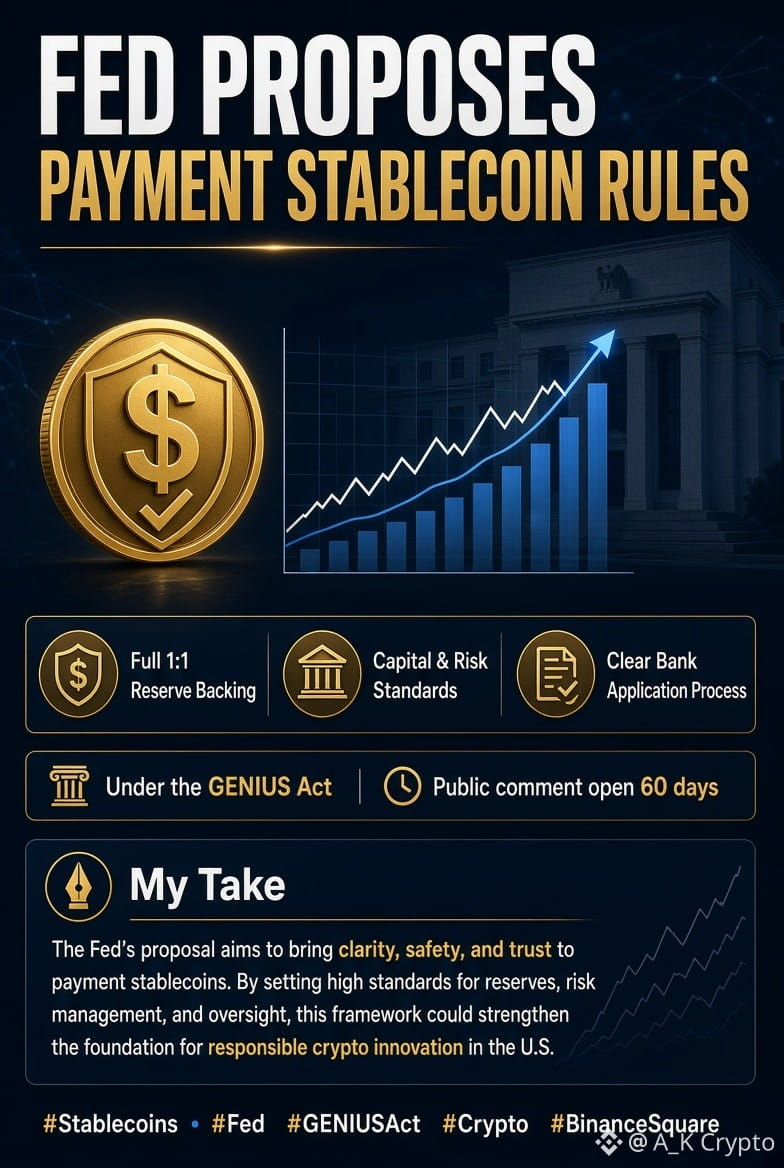
🚨 FED PROPOSES PAYMENT STABLECOIN RULES
The Federal Reserve just dropped two key proposals under the GENIUS Act for Board-supervised payment stablecoin issuers.
One requires full 1:1 backing with high-quality reserves like short-term Treasuries, plus standardized capital and risk management rules. The other sets out a clearer application process for banks wanting to issue stablecoins.
Public comment period is open for 60 days.
This is a solid step toward making dollar stablecoins safer and more reliable for everyday payments. Clear reserve rules and capital standards should build real confidence, but the final details on redemptions and risk will decide how useful these coins become. Watching closely as the framework takes shape.
#Stablecoins #Fed #GENIUSAct #Crypto #CryptoNews #BinanceSquare
1
35
·
--
#FedProposesPaymentStablecoinRules
🚨 Fed proposes new payment stablecoin rules
The U.S. Federal Reserve has proposed rules under the GENIUS Act that would require Fed-supervised payment stablecoin issuers to fully back tokens with eligible reserves, including short-term U.S. Treasury bills. The proposal also includes capital and risk-management requirements and a dedicated process for supervised banks seeking to issue payment stablecoins. Public comments will be open for 60 days after Federal Register publication.
💬 What do you think?$BTC $BNB $ETH
Will clearer stablecoin rules accelerate institutional adoption?
#Stablecoin #BNB_Market_Update #CryptoRegulation #Fed
1
72
·
--
Article
The Federal Reserve Board proposed two draft rules#fedproposespaymentstablecoinrules
The Federal Reserve Board proposed two draft rules on September 24, 2026 to implement its part of the GENIUS Act, the federal stable coin law signed in July 2025. Public comment is open for 60 days after the proposals are published in the Federal Register.
Who it covers
The Fed proposed a rule setting requirements for authorized stable coin issuers under its purview, including state member banks and other state-chartered issuers. Under the act, the Fed oversees stable coin issuers that are subsidiaries of state member banks. It also oversees state-chartered institutions without federal deposit insurance that have $10 billion or more of stable coins.
Proposal 1: reserves, capital and risk management
Full backing: Every $1 of stable coins would need at least $1 of permissible reserve assets behind it. Reserves could include U.S. dollars, Fed balances, certain bank deposits, Treasuries with 93 days or less to maturity, qualifying repos, and eligible investment funds.Redemption: Issuers must fulfill redemption requests within two business days. If backing falls below 1:1, they must immediately notify the Fed. Capital: Standardized capital requirements would address credit and operational risks, alongside risk-management standards. An issuer that stays short of required capital long enough could be forced to liquidate all reserves and redeem every coin. Custody: The proposal adds rules for Fed-supervised firms that safekeep the assets backing stable coins. It also clarifies which stable coin activities are permissible for Fed-supervised banks.
Proposal 2: bank applications
Fed-supervised banks that want to issue stable coins would follow a tailored application process rather than the standard one. Applicants would submit a business plan and financial information. The draft also sets up a process for appeals, hearings and final determinations. The GENIUS Act gives the Fed 120 days to decide complete applications.
Reaction and context
Fed Governor Michael Barr called the proposal an important step but said more work is needed. He said stable coins "will only be stable if they can be reliably and promptly redeemed at par" in a range of conditions, including market stressThe OCC and NCUA proposed their rules in February, the FDIC in April, and Treasury in August. No agency has finalized rules yet. The agencies also missed the statutory July 18 implementation deadline.The OCC's chief has said its final rule will come out by November.
These are proposals, so details could change after comments. Only banks and issuers under the Fed's supervision are covered, so issuers regulated by the OCC, FDIC or states would follow their own rules.
The Federal Reserve Board proposed two draft rules
#fedproposespaymentstablecoinrules
The Federal Reserve Board proposed two draft rules on September 24, 2026 to implement its part of the GENIUS Act, the federal stable coin law signed in July 2025. Public comment is open for 60 days after the proposals are published in the Federal Register.
Who it covers
The Fed proposed a rule setting requirements for authorized stable coin issuers under its purview, including state member banks and other state-chartered issuers. Under the act, the Fed oversees stable coin issuers that are subsidiaries of state member banks. It also oversees state-chartered institutions without federal deposit insurance that have $10 billion or more of stable coins.
Proposal 1: reserves, capital and risk management
Full backing: Every $1 of stable coins would need at least $1 of permissible reserve assets behind it. Reserves could include U.S. dollars, Fed balances, certain bank deposits, Treasuries with 93 days or less to maturity, qualifying repos, and eligible investment funds.Redemption: Issuers must fulfill redemption requests within two business days. If backing falls below 1:1, they must immediately notify the Fed. Capital: Standardized capital requirements would address credit and operational risks, alongside risk-management standards. An issuer that stays short of required capital long enough could be forced to liquidate all reserves and redeem every coin. Custody: The proposal adds rules for Fed-supervised firms that safekeep the assets backing stable coins. It also clarifies which stable coin activities are permissible for Fed-supervised banks.
Proposal 2: bank applications
Fed-supervised banks that want to issue stable coins would follow a tailored application process rather than the standard one. Applicants would submit a business plan and financial information. The draft also sets up a process for appeals, hearings and final determinations. The GENIUS Act gives the Fed 120 days to decide complete applications.
Reaction and context
Fed Governor Michael Barr called the proposal an important step but said more work is needed. He said stable coins "will only be stable if they can be reliably and promptly redeemed at par" in a range of conditions, including market stressThe OCC and NCUA proposed their rules in February, the FDIC in April, and Treasury in August. No agency has finalized rules yet. The agencies also missed the statutory July 18 implementation deadline.The OCC's chief has said its final rule will come out by November.
These are proposals, so details could change after comments. Only banks and issuers under the Fed's supervision are covered, so issuers regulated by the OCC, FDIC or states would follow their own rules.
74
The Federal Reserve has proposed new rules for payment stablecoins, signaling a significant step towards regulating this burgeoning sector of the crypto market. This move reflects growing concerns about the stability and systemic risk associated with stablecoins, especially those used for payments. The proposed regulations are likely to focus on reserve requirements, transparency, and oversight, aiming to ensure these digital assets are as safe and reliable as traditional money. While the specifics are still under review, this initiative could lead to greater institutional adoption by providing a clearer regulatory framework, but it might also introduce compliance burdens for issuers. The market will be closely watching how these proposals evolve and impact the stablecoin landscape and the broader crypto ecosystem.
Disclaimer: This content is for informational purposes only and does not constitute financial advice.
#FedProposesPaymentStablecoinRules
Disclaimer: This content is for informational purposes only and does not constitute financial advice.
#FedProposesPaymentStablecoinRules
2
66

·
--
Bullish
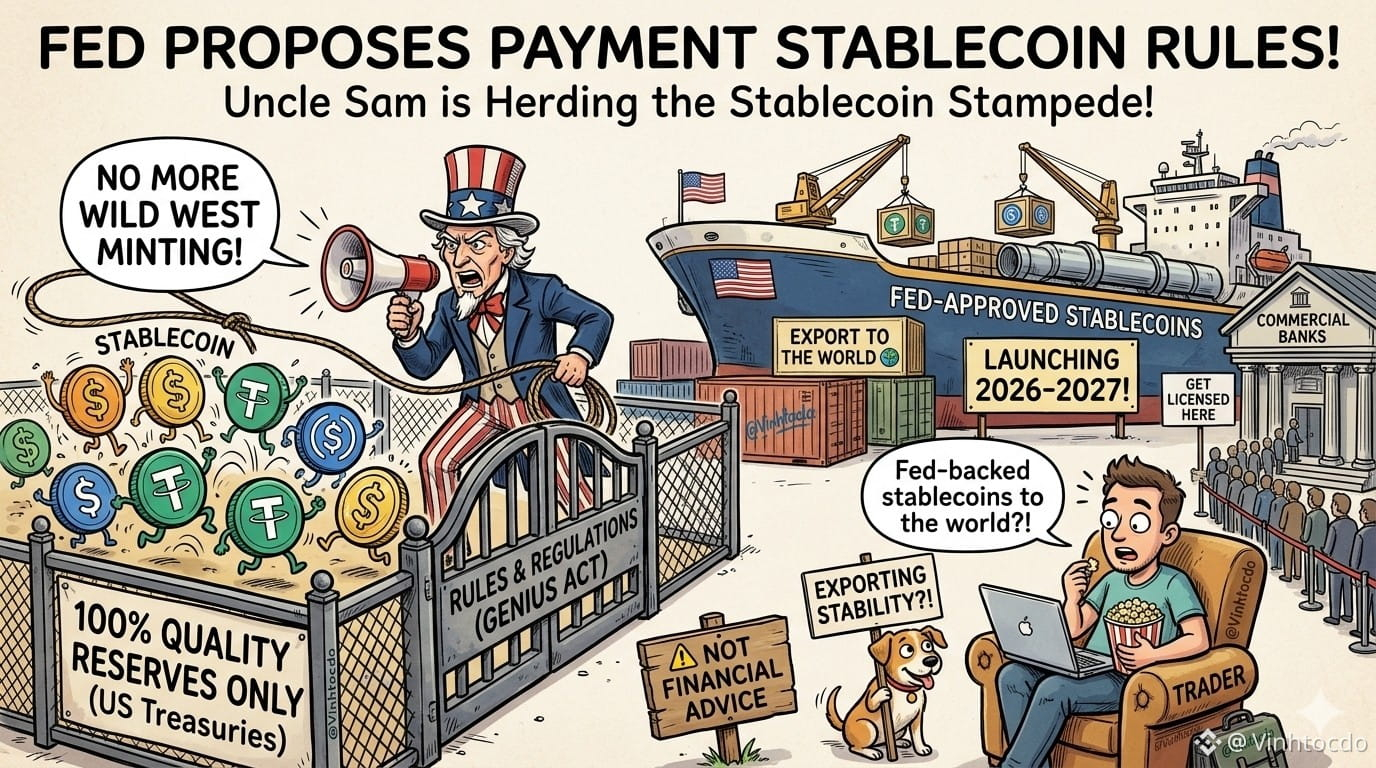
Uncle Sam wants to control the stablecoins! 🇺🇸 #fedproposespaymentstablecoinrules is officially live! The Federal Reserve just dropped new drafts to strictly regulate payment stablecoins under the GENIUS Act.
Are they preparing to export US-regulated stablecoins to the entire world? 🌍 Absolutely! They want 100% high-quality liquid reserves (hello, US Treasuries) and formal licenses for commercial banks by 2026-2027. No more Wild West minting!
What should traders do? Keep your eyes on top stablecoin projects, expect more institutional compliance, and manage your bags wisely!
⚠️ Not financial advice! New here? Use code VINHTOCDO or register via: [https://www.binance.com/register?ref=VINHTOCDO](https://www.binance.com/register?ref=VINHTOCDO)
👇 Click trade below to support me:
$BTC
{future}(BTCUSDT)
$BNB
{future}(BNBUSDT)
$ETH
{future}(ETHUSDT)
#Fed #stablecoin #CryptoNews #DeFi #USDC #VINHTOCDO
Uncle Sam wants to control the stablecoins! 🇺🇸 #fedproposespaymentstablecoinrules is officially live! The Federal Reserve just dropped new drafts to strictly regulate payment stablecoins under the GENIUS Act.
Are they preparing to export US-regulated stablecoins to the entire world? 🌍 Absolutely! They want 100% high-quality liquid reserves (hello, US Treasuries) and formal licenses for commercial banks by 2026-2027. No more Wild West minting!
What should traders do? Keep your eyes on top stablecoin projects, expect more institutional compliance, and manage your bags wisely!
⚠️ Not financial advice! New here? Use code VINHTOCDO or register via: https://www.binance.com/register?ref=VINHTOCDO
👇 Click trade below to support me:
$BTC
$BNB
$ETH
#Fed #stablecoin #CryptoNews #DeFi #USDC #VINHTOCDO
2
66
·
--
Bullish
#fedproposespaymentstablecoinrules
🚨 THE FED IS BRINGING STABLECOINS CLOSER TO TRADITIONAL FINANCE.
The Federal Reserve has proposed new rules for payment stablecoin issuers under the GENIUS Act.
💵 Full backing with permitted reserve assets
🏦 Short-term U.S. Treasury bills could qualify as reserves
🛡️ New capital & risk-management requirements
🏛️ Fed-supervised banks could apply to issue payment stablecoins
⏳ Public comments open for 60 days
This could be another major step toward regulated stablecoins becoming part of the U.S. payments system.
👀 Stablecoins are getting serious attention from Wall Street.
#Fed #stablecoin #crypto
1
142

·
--
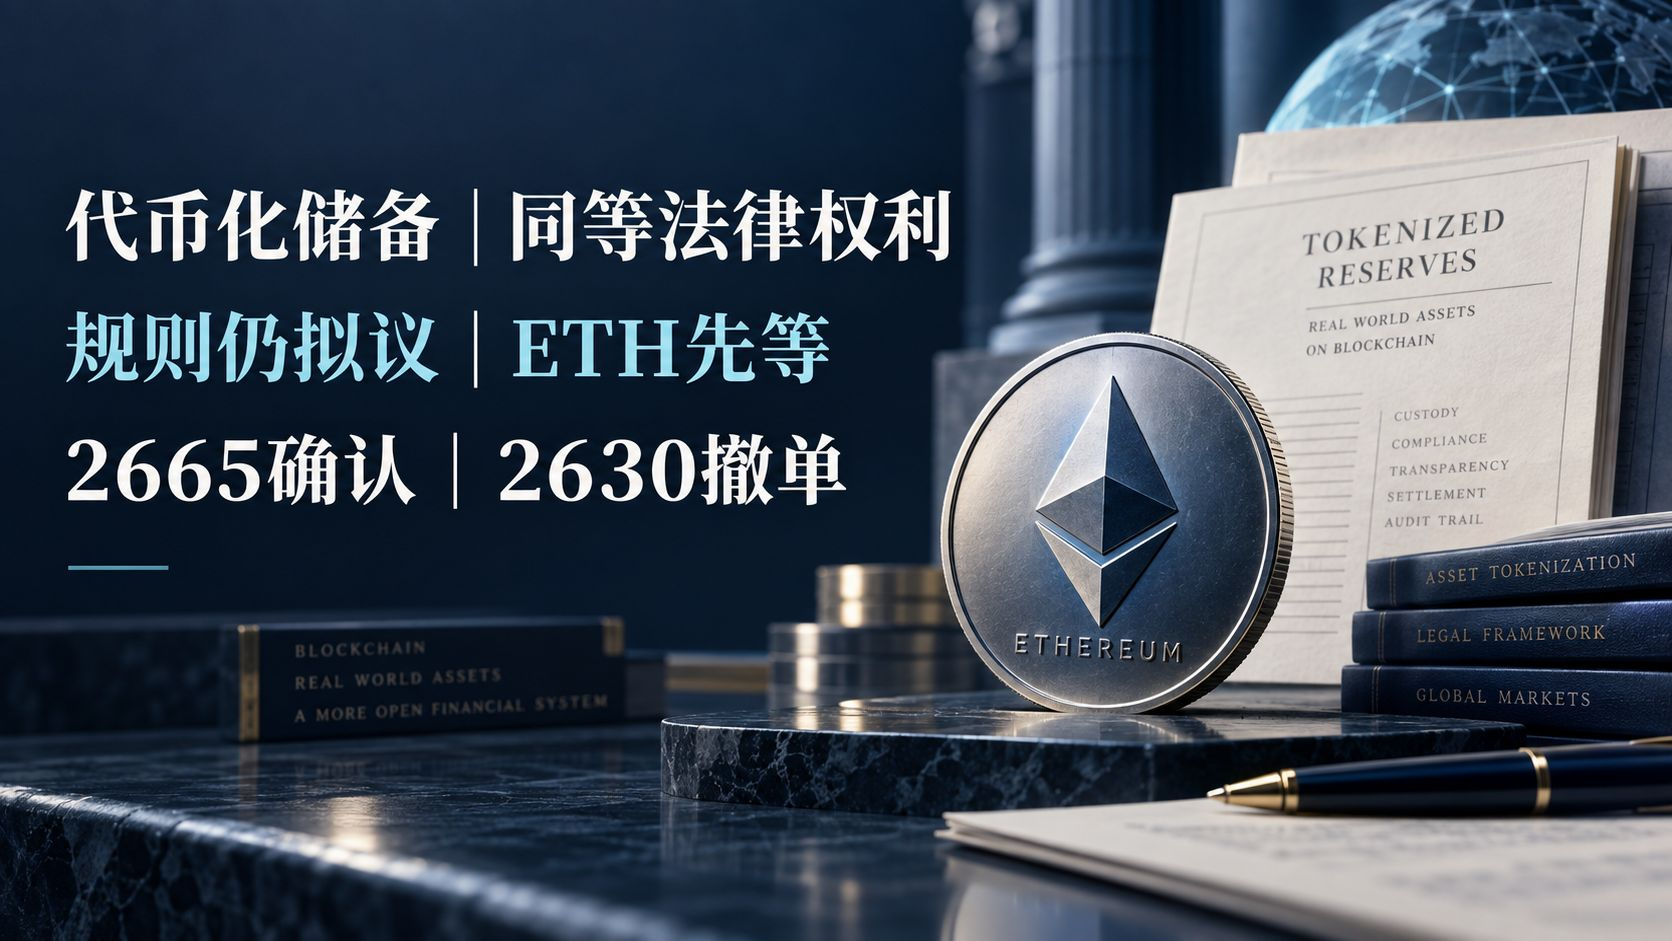
Stablecoin proposal heat rises again|Tokenized reserves must retain equal legal rights|ETH at $2,650—I’m waiting first
My stance is to prioritize clearer rules, but not to chase-buy ETH just because “reserves can be put on-chain.” On the forum, #FedProposesPaymentStablecoinRules had 258 people discussing this round, up from 206 last round—attention is increasing. My independent view is that we need to check, item by item, the asset’s legal rights, the on-chain execution path, and the demand for native coins; you can’t skip any intermediary steps.
The first-hand facts come from the U.S. Federal Reserve’s September 24 public comment document. The proposal includes 247.11 allowing certain eligible reserves to exist in tokenized form, but it requires that their legal rights be the same as those of the non-tokenized version of the same underlying asset, and that applicable laws and regulations be followed. I cross-checked the GENIUS formal bill—its Article 4 also lists that some reserves may be in tokenized form. The bill and this implementation-details proposal must not be conflated: this is not a brand-new final rule issued today, nor is it approval for all RWA tokens to serve as stablecoin reserves.
Why does this detail matter for the crypto market? My mechanism-based judgment is that having only an on-chain balance is not enough to determine who the asset belongs to, who can redeem it, or how rights can be asserted. Even if the issuer uses tokenization tools to manage reserves, it still must verify the eligibility of the underlying assets and the legal arrangements. A token whose name includes “Treasury” will not automatically meet the requirements just because it has a contract address; you must look at the actual rights received by holders, and you can’t treat marketing labels as regulatory recognition.
For ETH, tokenizing reserves may increase infrastructure demand, but that’s a potential path—not an already-realized buy order. The ledger on which it runs, whether execution requires the Ethereum mainnet, and the actual trading frequency and fees will all change the outcome. If you hold tokens representing Treasuries, you’re buying the corresponding asset rights; preparing gas fees for on-chain operations is another separate use of funds. The two volumes can’t be simply added together, and you absolutely can’t count the entire reserves amount as ETH demand.
What will I do first? I’ll review eligible assets and legal documents, then check the deployment architecture and real usage. If rights are unclear, execution doesn’t actually go through Ethereum, or there’s only a pilot with no sustained trading, then I need to lower expectations for ETH’s direct value capture. This isn’t denial of tokenization—it’s not confusing the scale of financial products with the native coin price.
How has the market reacted so far? In this round, Kraken’s USD spot ETH is around $2,650.36; over the past 24 hours, it ranged from $2,635.57 to $2,718.36, still sitting in the lower part of the window. The price hasn’t given me confirmation to chase the news, nor is there evidence that this move is caused by the reserve provisions. The U.S. ETH fund filings/facts sheet latest completion date remains September 25—it’s not something I’d frame as a new subscription today.
If I were trading this myself: I wouldn’t participate, my position would be zero. No shorting, no leverage. I’d only consider spot-condition-based long entries: if the hourly close is above 2665, then pull back to 2655–2665 and hold there, with quotes and deposits/withdrawals behaving normally—then I’d use at most 0.3% of total capital to participate. Cut the position in half at 2685, and close the remainder at 2700. Hard stop-loss at 2640, or if two consecutive hourly closes are below 2655, exit entirely. If it breaks down below 2630 before entry, cancel the plan. If there’s no follow-through after a breakout or if the channel shows abnormalities, withdraw the participation judgment and don’t add positions to recoup losses.
Facts define the boundary; price is responsible for validating follow-through. If nothing is triggered, there’s no trade—don’t write waiting as profit.
Source: the Fed Sep 24 proposal 247.11(b)(8); GENIUS formal bill Article 4; Kraken quotes. #FedProposesPaymentStablecoinRules #ETH
This is only personal market observation and does not constitute investment advice.
58
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BTCFallsBelow$83000
2,952 views
56 Discussing
2
#BitcoinSpotETFs$2.39BWeeklyNetInflow
45 views
6 Discussing
3
#FedProposesPaymentStablecoinRules
14,534 views
328 Discussing
4
#ChinaMayLetAlibabaByteDanceBuyNvidiaChips
16,730 views
373 Discussing
5
#USChinaRelease$30BTariffCutProductLists
2,596 views
42 Discussing
6
#SKoreaFSCConsidersVirtualAssetMarketMaker
11,609 views
298 Discussing
7
#ChinaIndustrialProfitGrowthSlowsFourthMonth
11,681 views
290 Discussing
8
#BitwiseFilesFinalNEARSpotETFProspectus
128,545 views
1,869 Discussing
9
#BitgetHackerMoves$83MStolenXRP
41,599 views
184 Discussing
10
#SOLSpotETFWeeklyInflow$188M
25,963 views
144 Discussing