

cryptotradehead
7k Posts
cryptotradehead
Report
Block User
backtesting, analyse, how to use AI for trading - can you be a good trader?
Open Trade
High-Frequency Trader
4.8 Years
7 Following
2.6K+ Followers
5.0K+ Liked
Posts
Portfolio
All
Quotes
HOW I TESTED IT
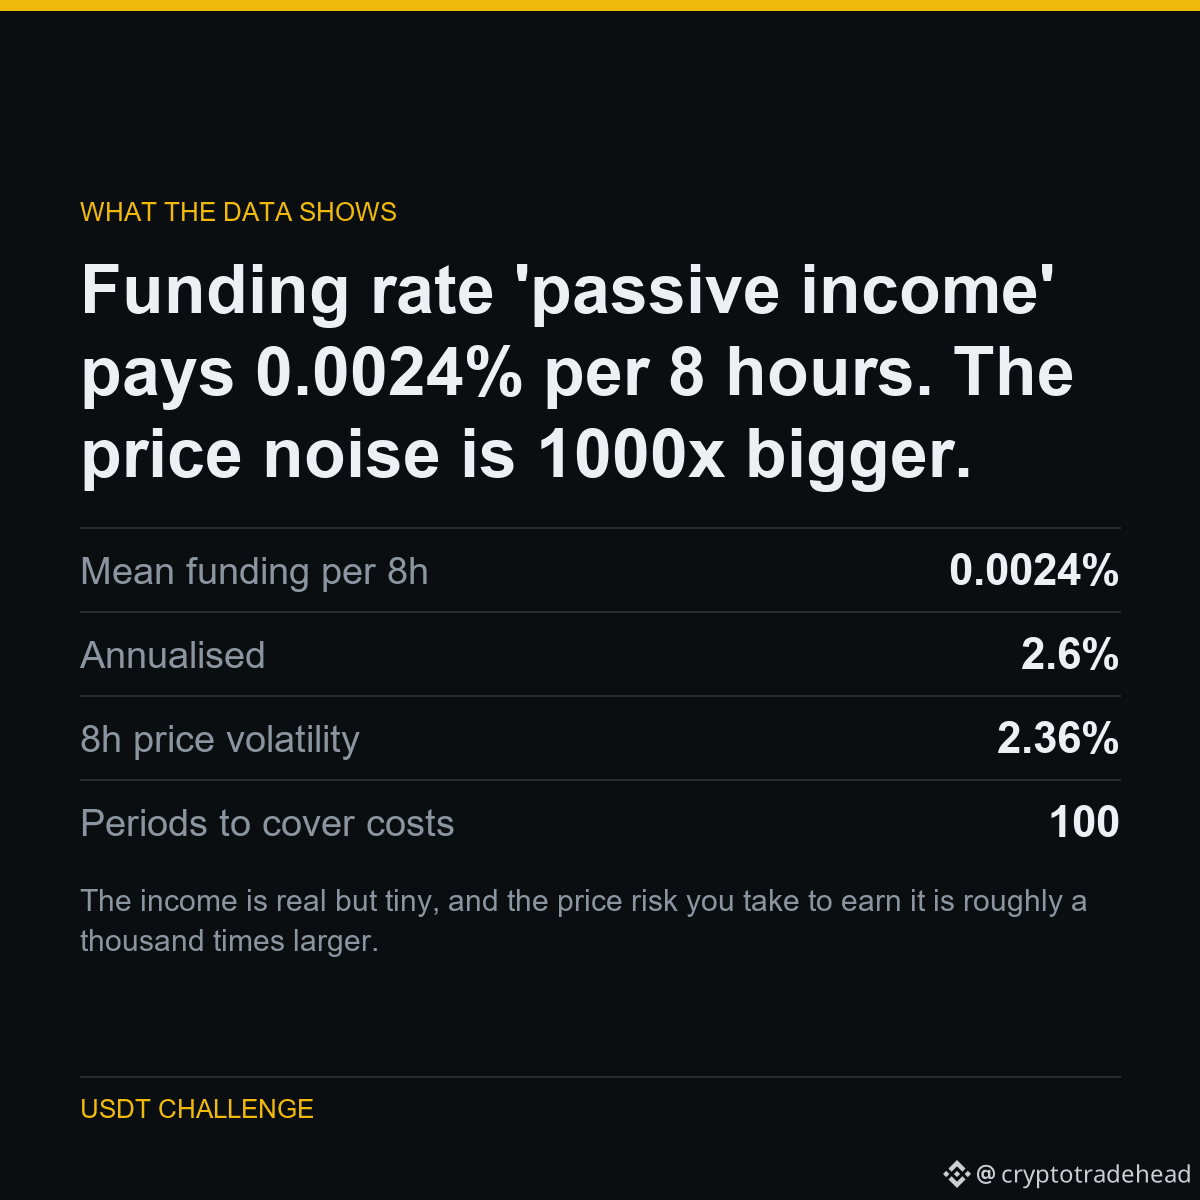
Collecting funding on perpetuals is sold as passive yield. I pulled 34,431 funding events across 7 symbols and measured it.
Average funding is 0.0024% per 8-hour period. On a 150 USDT position that is 0.0036 USDT. A round trip costs 0.36 USDT - you would hold for 33 days just to cover entry and exit.
Meanwhile the price moves 2.36% in a typical 8 hours.
THE NUMBERS
Mean funding per 8h: 0.0024%
Annualised: 2.6%
8h price volatility: 2.36%
Periods to cover costs: 100
The income is real but tiny, and the price risk you take to earn it is roughly a thousand times larger. This is why desks that trade it hedge with spot. Unhedged, it is not income - it is a directional bet with a rebate.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $ETH $SOL
#Binance #Futures #Backtesting #TradingBot #CryptoData
3
Article
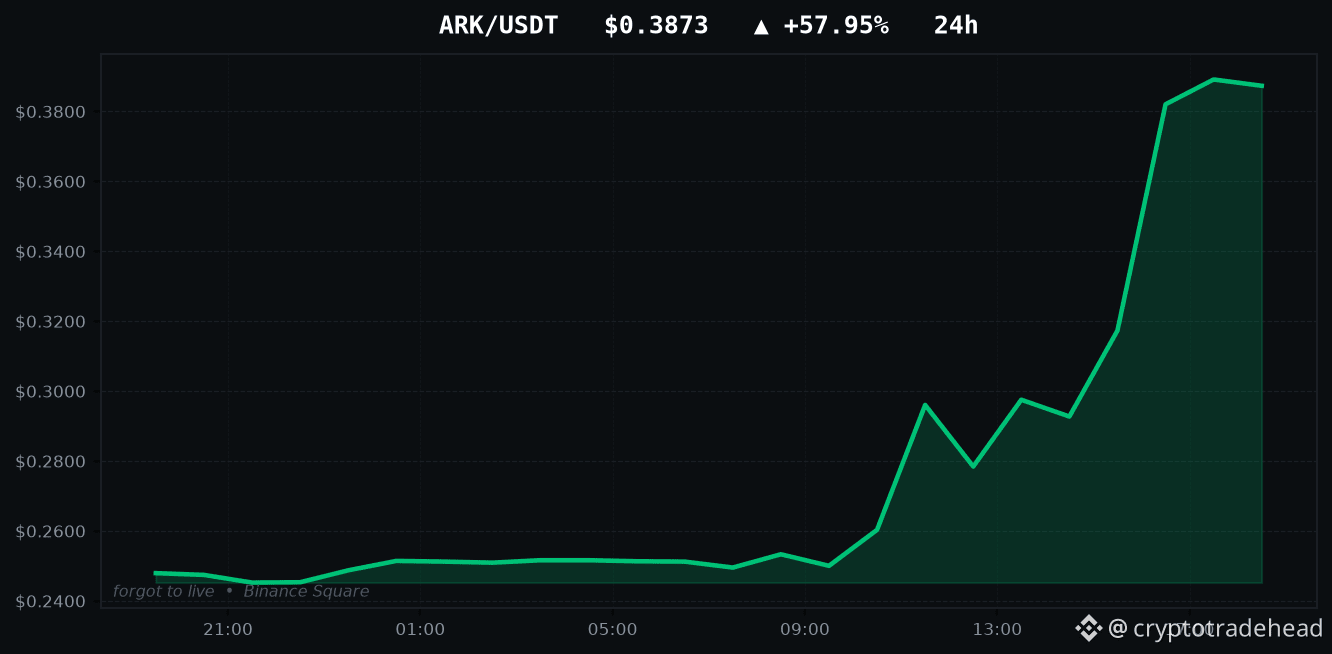
ARK is up +57.95% - I tested both ways to trade itTODAY'S TOP GAINERS
ARK: +57.95%
MOVR: +49.52%
NOM: +18.83%
GLMR: +18.03%
NIGHT: +17.71%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like ARK's +57.95%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $ARK $MOVR $NOM
#Binance #Altcoins #Futures #ARK #CryptoData
ARK is up +57.95% - I tested both ways to trade it
TODAY'S TOP GAINERS
ARK: +57.95%
MOVR: +49.52%
NOM: +18.83%
GLMR: +18.03%
NIGHT: +17.71%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like ARK's +57.95%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $ARK $MOVR $NOM
#Binance #Altcoins #Futures #ARK #CryptoData
9
HOW I TESTED IT
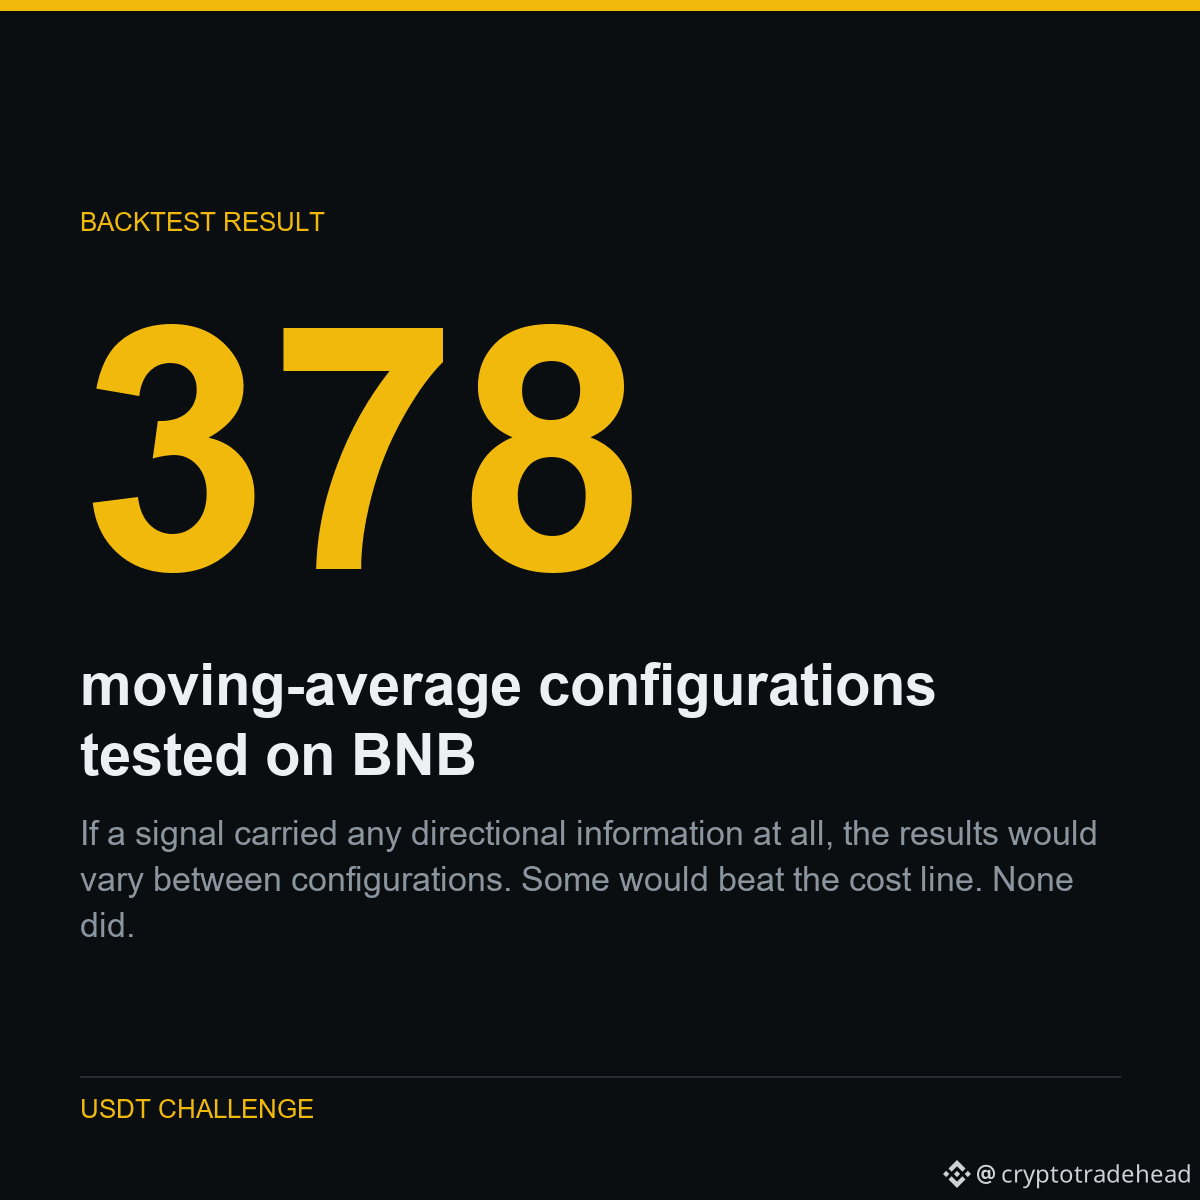
Two signal families, four timeframes, EMA and SMA, with and without a trend filter, long-only and short-only. 378 combinations in total, all with real fees and real measured slippage applied.
The round-trip cost of a trade is 0.240% of position size. The average result per trade, across every single configuration, landed between -0.361% and -0.401%.
That is the cost, and nothing else.
THE NUMBERS
Round-trip cost: 0.240%
Avg result, 15m setups: -0.361%
Avg result, 1h setups: -0.401%
Configurations profitable: 0 of 378
If a signal carried any directional information at all, the results would vary between configurations. Some would beat the cost line. None did. That is not weak edge that needs tuning - it is zero edge being charged an entry fee.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BNB
#Binance #Futures #Backtesting #TradingBot #CryptoData
12
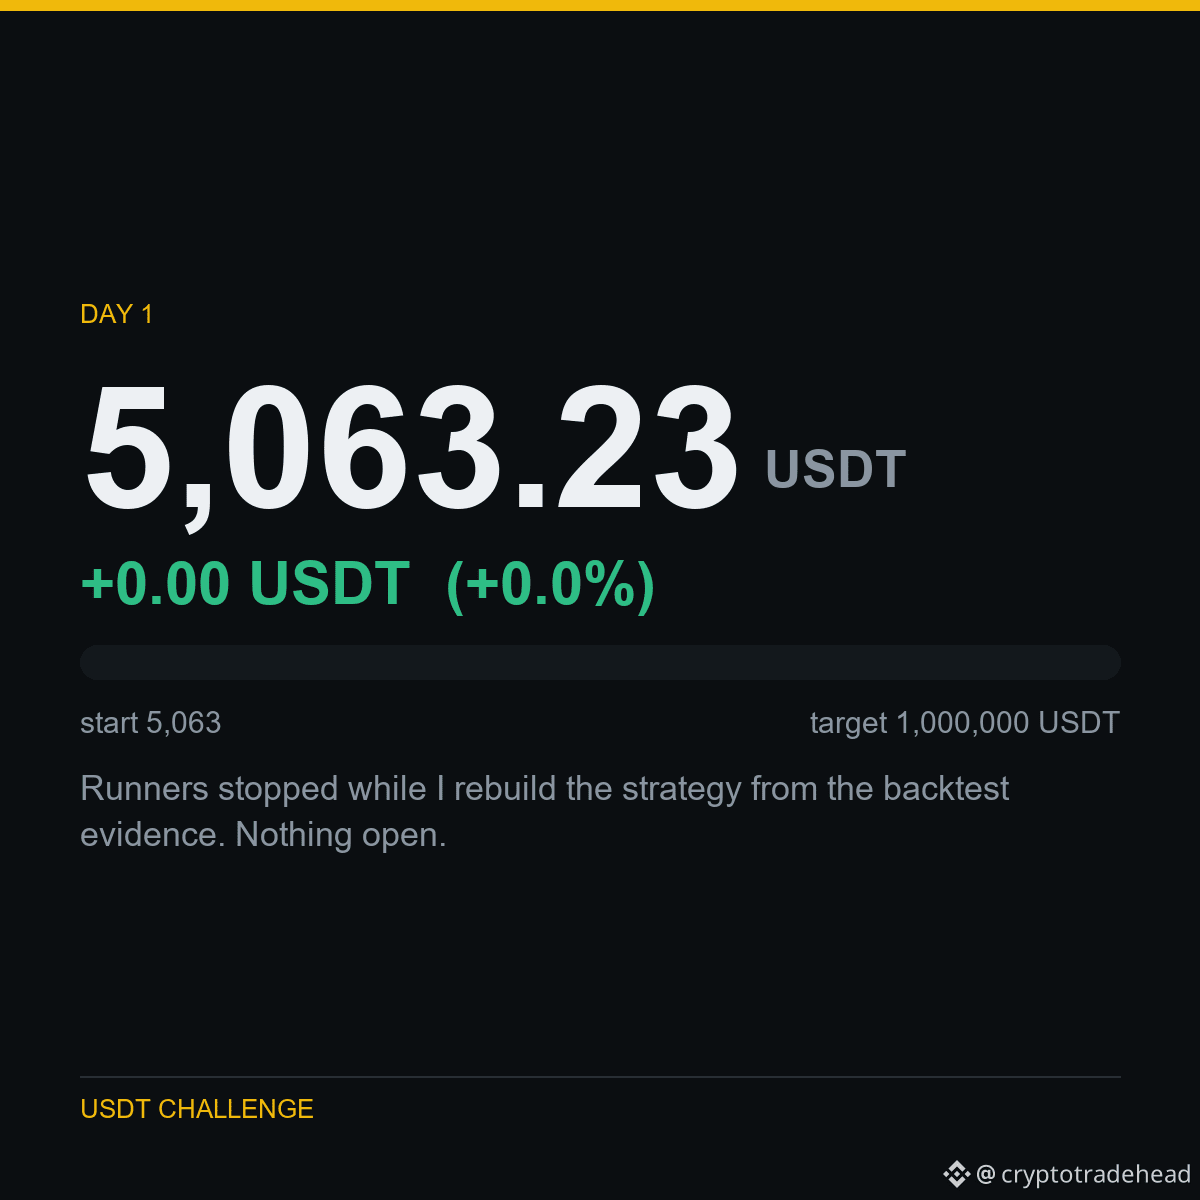
DAY 1 - 5,063 USDT to 1,000,000 USDT
Balance: 5,063.23 USDT
Change: +0.00 USDT (+0.0%)
Runners stopped while I rebuild the strategy from the backtest evidence. Nothing open.
Running on a Binance testnet account, so this is demo capital - I would rather say that than let you assume otherwise. The strategy, the costs and the losses are all real.
No signals for sale, no course, no affiliate link. Just the account and the data behind it.
Traded in this challenge: $BTC $SOL $AVAX
#Binance #USDT #Futures #TradingChallenge #Crypto
18
Article
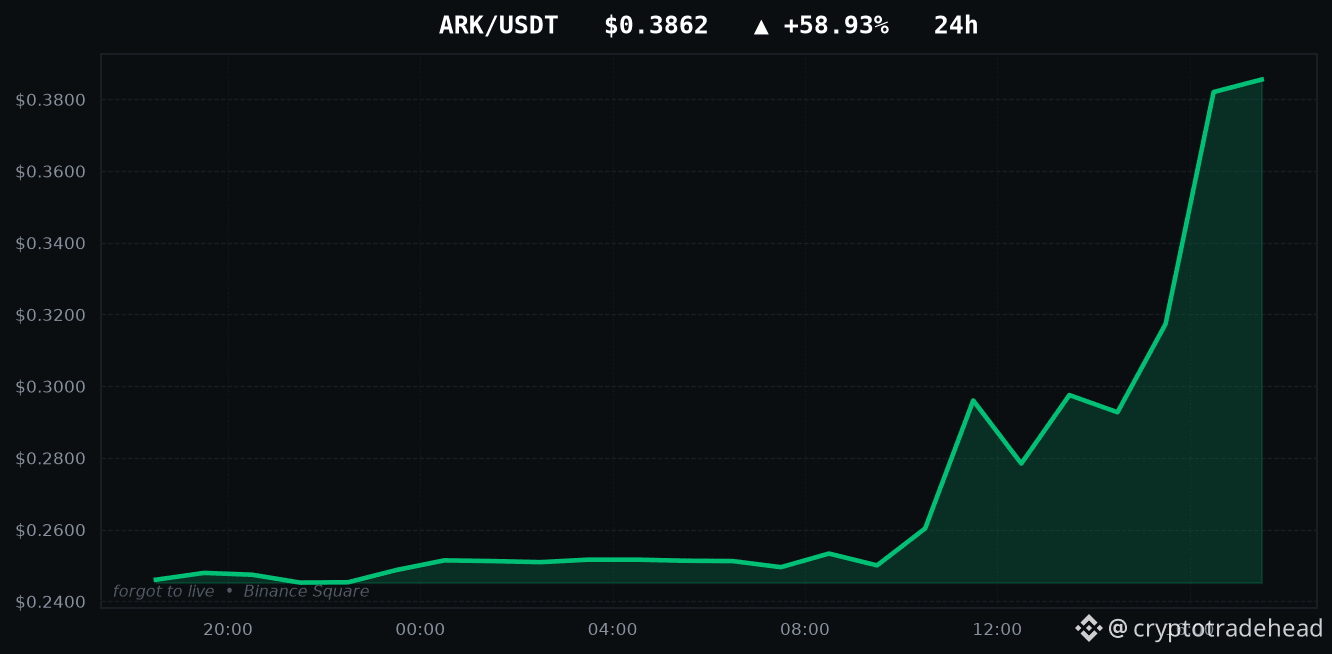
ARK is up +58.93% - I tested both ways to trade itTODAY'S TOP GAINERS
ARK: +58.93%
MOVR: +54.54%
GLMR: +23.89%
QNT: +22.89%
SOMI: +20.79%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like ARK's +58.93%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $ARK $MOVR $GLMR
#Binance #Altcoins #Futures #ARK #CryptoData
ARK is up +58.93% - I tested both ways to trade it
TODAY'S TOP GAINERS
ARK: +58.93%
MOVR: +54.54%
GLMR: +23.89%
QNT: +22.89%
SOMI: +20.79%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like ARK's +58.93%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $ARK $MOVR $GLMR
#Binance #Altcoins #Futures #ARK #CryptoData
111
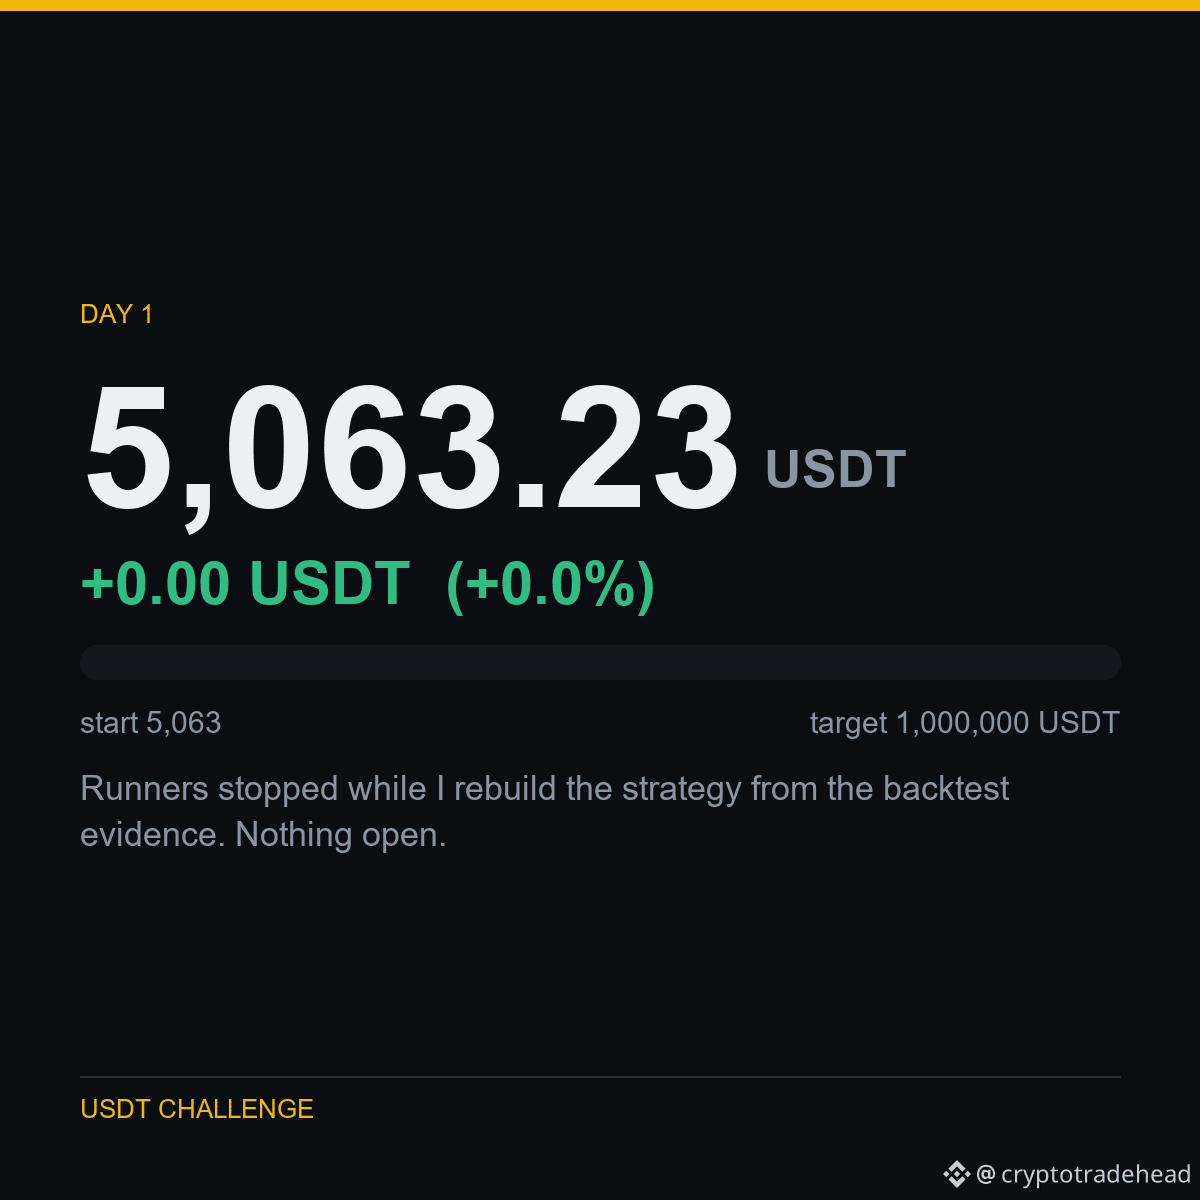
DAY 1 - 5,063 USDT to 1,000,000 USDT
Balance: 5,063.23 USDT
Change: +0.00 USDT (+0.0%)
Runners stopped while I rebuild the strategy from the backtest evidence. Nothing open.
Running on a Binance testnet account, so this is demo capital - I would rather say that than let you assume otherwise. The strategy, the costs and the losses are all real.
No signals for sale, no course, no affiliate link. Just the account and the data behind it.
Traded in this challenge: $BTC $SOL $AVAX
#Binance #USDT #Futures #TradingChallenge #Crypto
16
Article
I measured real execution costs with 48 controlled trades. One number decides everything.I measured real execution costs with 48 controlled trades. One number decides everything.
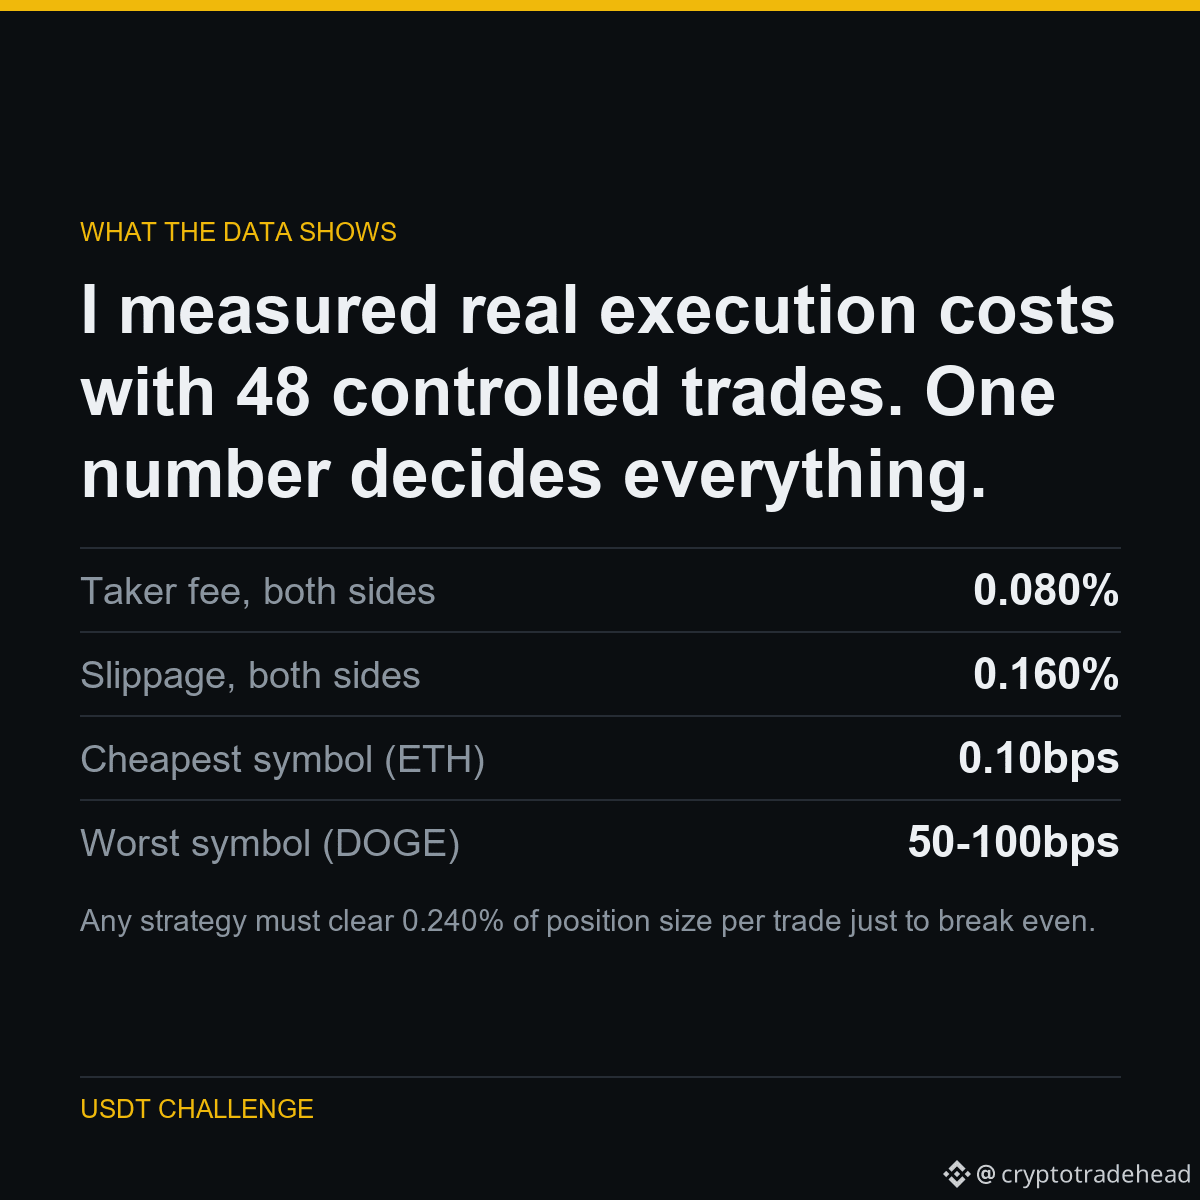
I stopped assuming what trading costs and measured it: 48 controlled round trips, entering and exiting immediately, recording the actual fill against the reference price.
Fee was constant at 0.04% per side. Slippage was not - ETH filled at essentially zero, while DOGE cost 50 to 100 basis points per round trip.
On a 150 USDT position, a round trip costs 0.36 USDT before the market moves at all.
WHAT IT MEANS
Any strategy must clear 0.240% of position size per trade just to break even. Most published setups never mention this number, which is why most published setups lose money.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $ETH $DOGE
#Binance #Futures #Backtesting #TradingBot #CryptoData
I measured real execution costs with 48 controlled trades. One number decides everything.
I measured real execution costs with 48 controlled trades. One number decides everything.
I stopped assuming what trading costs and measured it: 48 controlled round trips, entering and exiting immediately, recording the actual fill against the reference price.
Fee was constant at 0.04% per side. Slippage was not - ETH filled at essentially zero, while DOGE cost 50 to 100 basis points per round trip.
On a 150 USDT position, a round trip costs 0.36 USDT before the market moves at all.
WHAT IT MEANS
Any strategy must clear 0.240% of position size per trade just to break even. Most published setups never mention this number, which is why most published setups lose money.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $ETH $DOGE
#Binance #Futures #Backtesting #TradingBot #CryptoData
6
Article
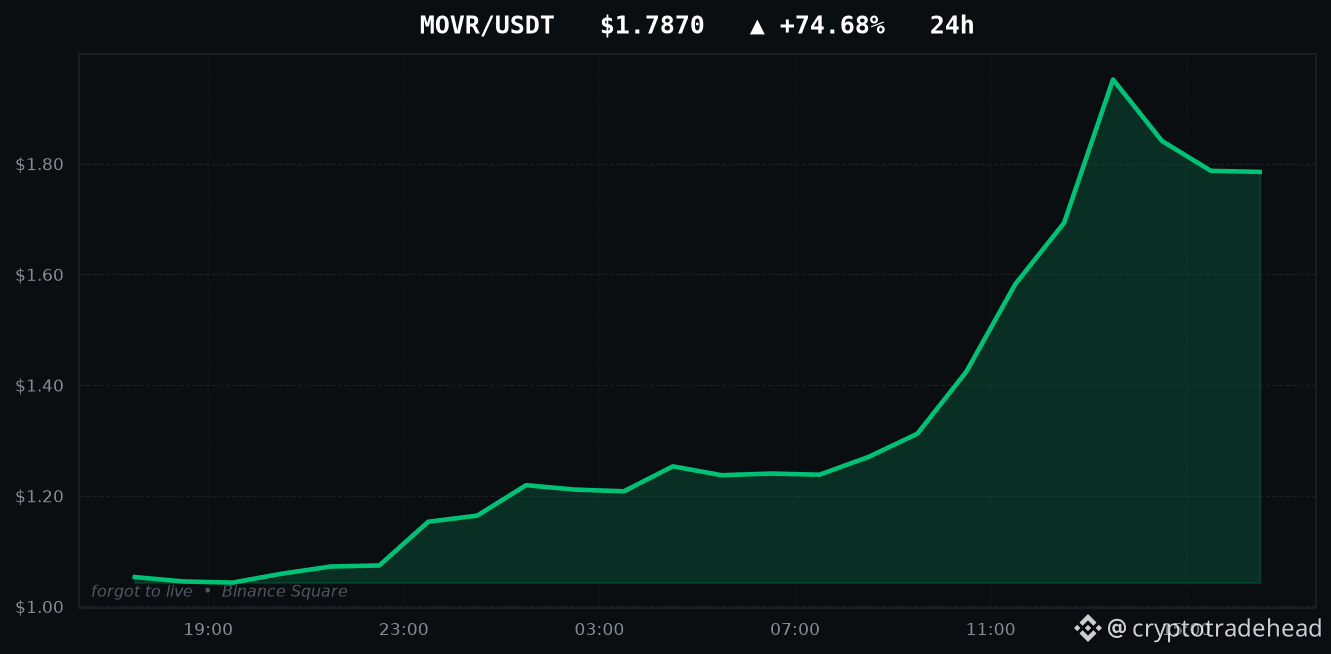
MOVR is up +74.68% - I tested both ways to trade itTODAY'S TOP GAINERS
MOVR: +74.68%
ARK: +55.61%
QNT: +27.92%
GLMR: +23.89%
GTC: +22.44%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like MOVR's +74.68%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $MOVR $ARK $QNT
#Binance #Altcoins #Futures #MOVR #CryptoData
MOVR is up +74.68% - I tested both ways to trade it
TODAY'S TOP GAINERS
MOVR: +74.68%
ARK: +55.61%
QNT: +27.92%
GLMR: +23.89%
GTC: +22.44%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like MOVR's +74.68%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $MOVR $ARK $QNT
#Binance #Altcoins #Futures #MOVR #CryptoData
2
HOW I TESTED IT
Same universe, same ranking rule, same holding period, five different years.
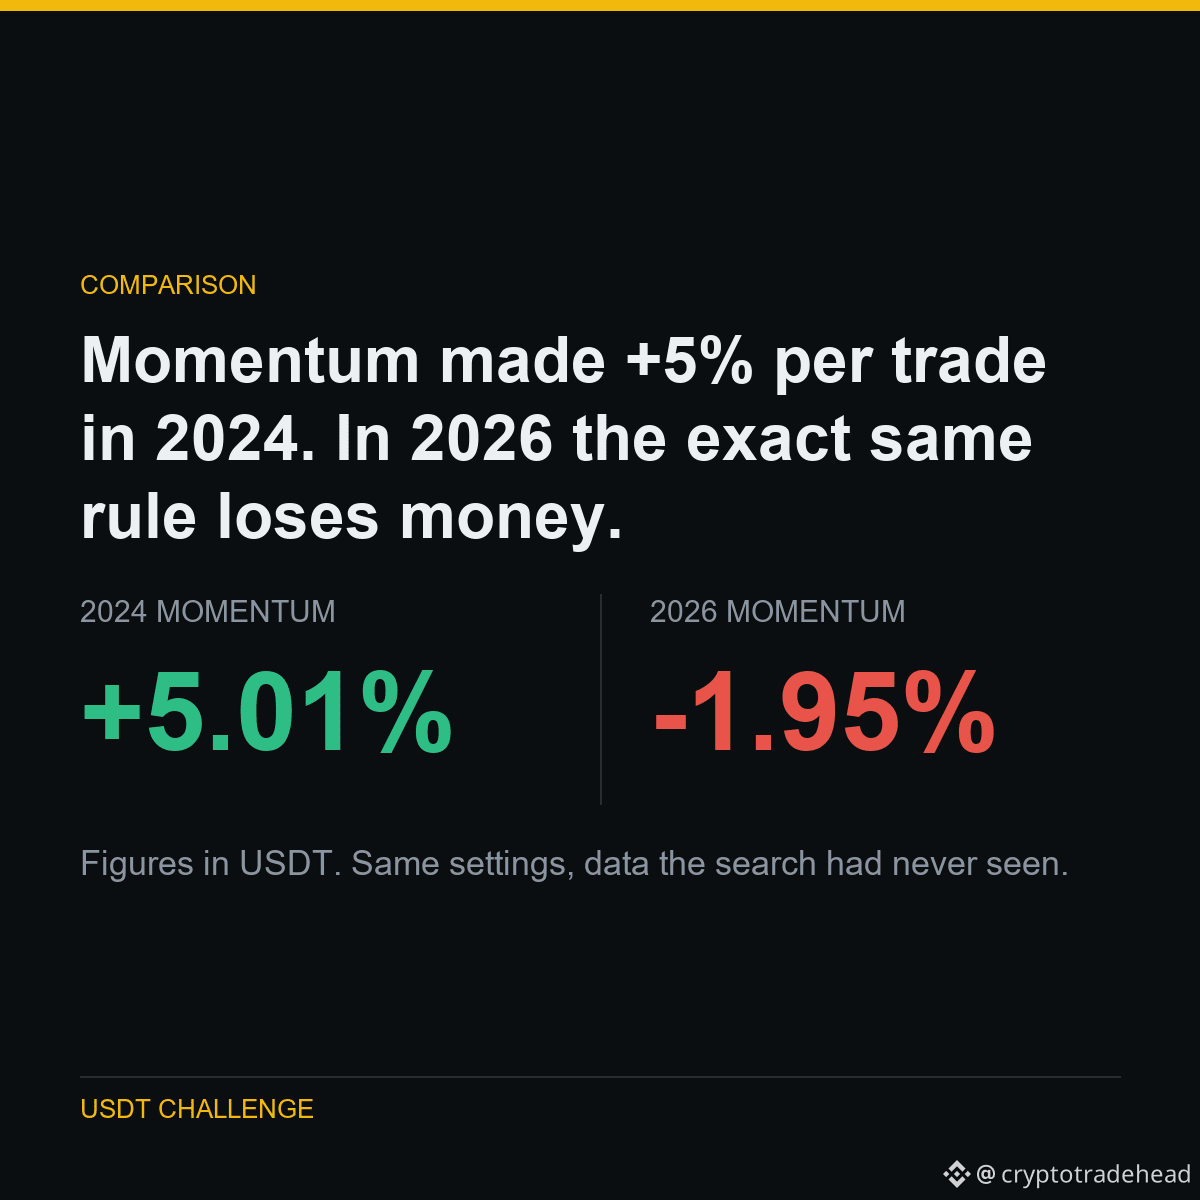
2024 and 2025 carried the whole strategy. 2026 is the worst year of the five - a 25% win rate over roughly nine months.
Buying the strongest coins and shorting the weakest has stopped working this year. Doing the opposite would have returned +1.47% per rebalance at a 69% win rate.
THE NUMBERS
2022: +0.510%
2023: -0.323%
2024: +5.008%
2025: +3.900%
2026 YTD: -1.950%
A strategy is not a fact about markets, it is a fact about a period. Anyone showing you a backtest without the year-by-year breakdown is hiding the years that did not work.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $SOL $BTC $ETH
#Binance #Futures #Backtesting #TradingBot #CryptoData
4
Article
My stop-loss order got rejected mid-crash. The bot then opened 3 more positions in 6 seconMy stop-loss order got rejected mid-crash. The bot then opened 3 more positions in 6 seconds.
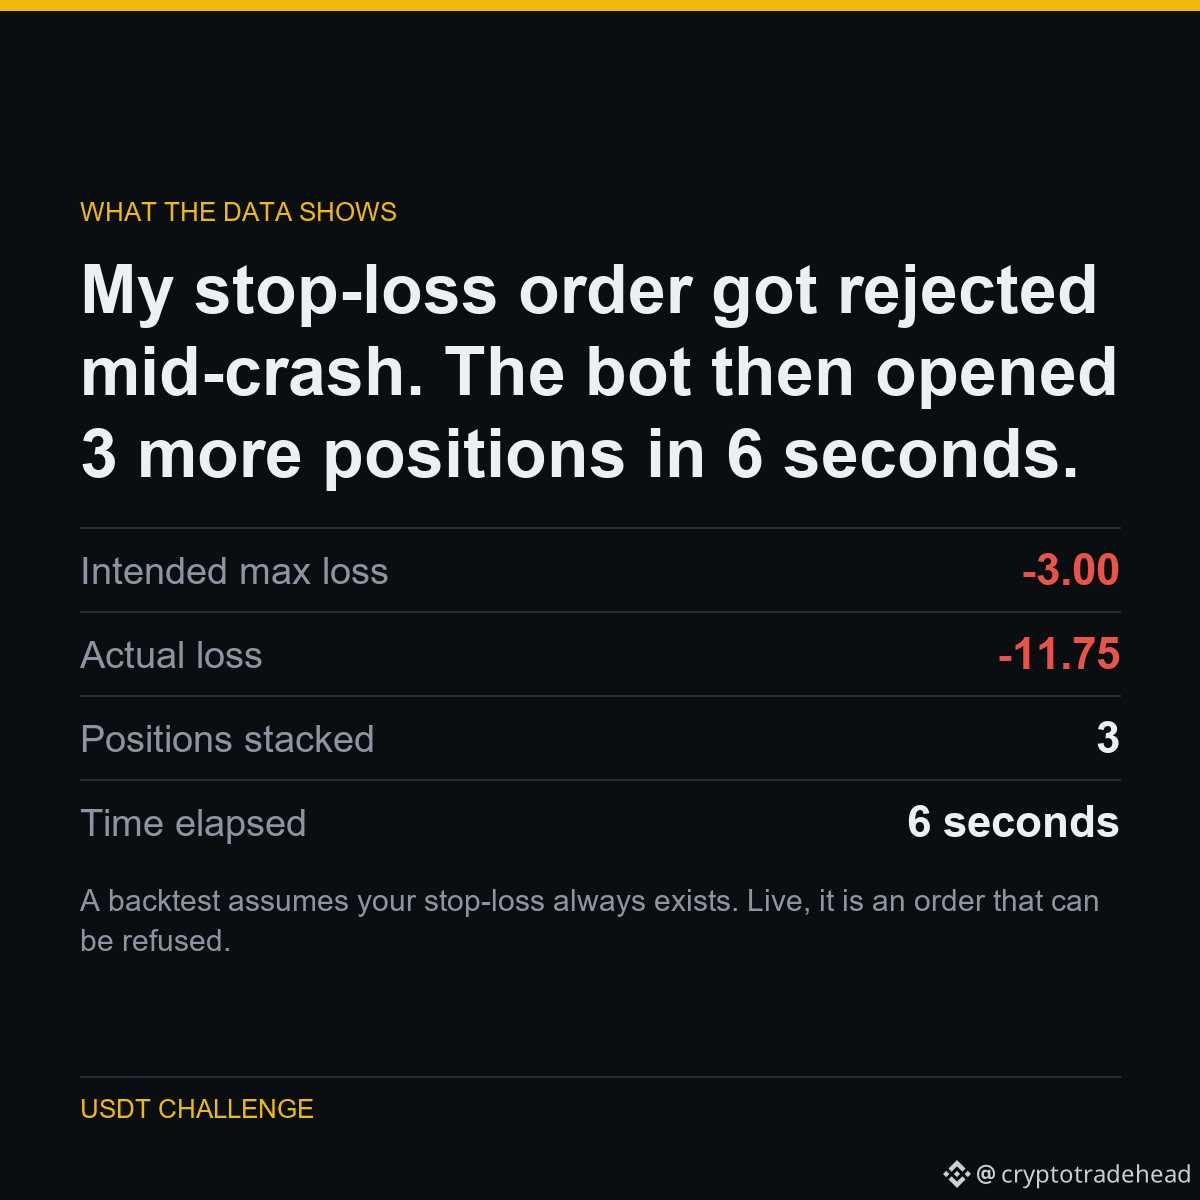
During a fast drop, Binance rejected my stop-loss with error -2021: the market had already moved past the trigger price before the order landed.
My code did not handle that rejection. The position stayed open with no stop, and because the bot's own state never recorded it, the next signal opened another position on top. Three times.
Intended risk was 3 USDT. Actual loss was 11.75 USDT.
WHAT IT MEANS
A backtest assumes your stop-loss always exists. Live, it is an order that can be refused. The gap between those two assumptions is where real money goes.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BNB
#Binance #Futures #Backtesting #TradingBot #CryptoData
My stop-loss order got rejected mid-crash. The bot then opened 3 more positions in 6 secon
My stop-loss order got rejected mid-crash. The bot then opened 3 more positions in 6 seconds.
During a fast drop, Binance rejected my stop-loss with error -2021: the market had already moved past the trigger price before the order landed.
My code did not handle that rejection. The position stayed open with no stop, and because the bot's own state never recorded it, the next signal opened another position on top. Three times.
Intended risk was 3 USDT. Actual loss was 11.75 USDT.
WHAT IT MEANS
A backtest assumes your stop-loss always exists. Live, it is an order that can be refused. The gap between those two assumptions is where real money goes.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BNB
#Binance #Futures #Backtesting #TradingBot #CryptoData
9
Article
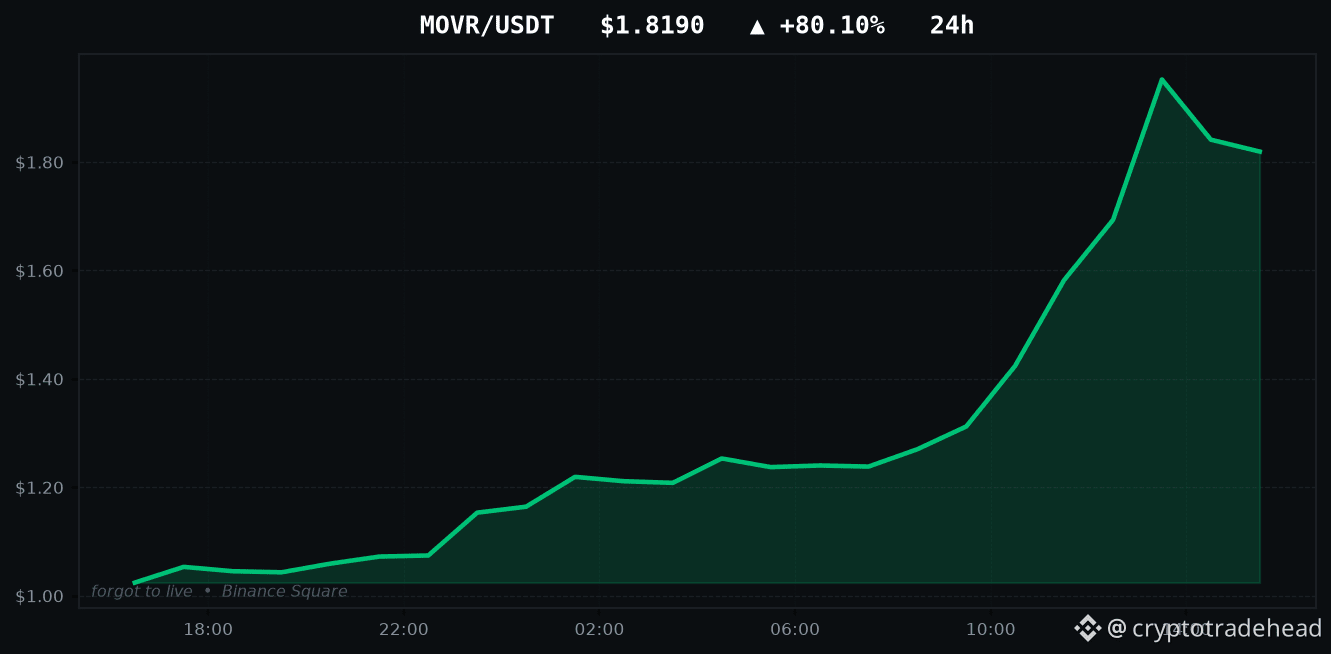
MOVR is up +80.10% - I tested both ways to trade itTODAY'S TOP GAINERS
MOVR: +80.10%
GTC: +27.82%
GLMR: +26.53%
ARK: +23.92%
NIGHT: +21.99%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like MOVR's +80.10%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $MOVR $GTC $GLMR
#Binance #Altcoins #Futures #MOVR #CryptoData
MOVR is up +80.10% - I tested both ways to trade it
TODAY'S TOP GAINERS
MOVR: +80.10%
GTC: +27.82%
GLMR: +26.53%
ARK: +23.92%
NIGHT: +21.99%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like MOVR's +80.10%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $MOVR $GTC $GLMR
#Binance #Altcoins #Futures #MOVR #CryptoData
14
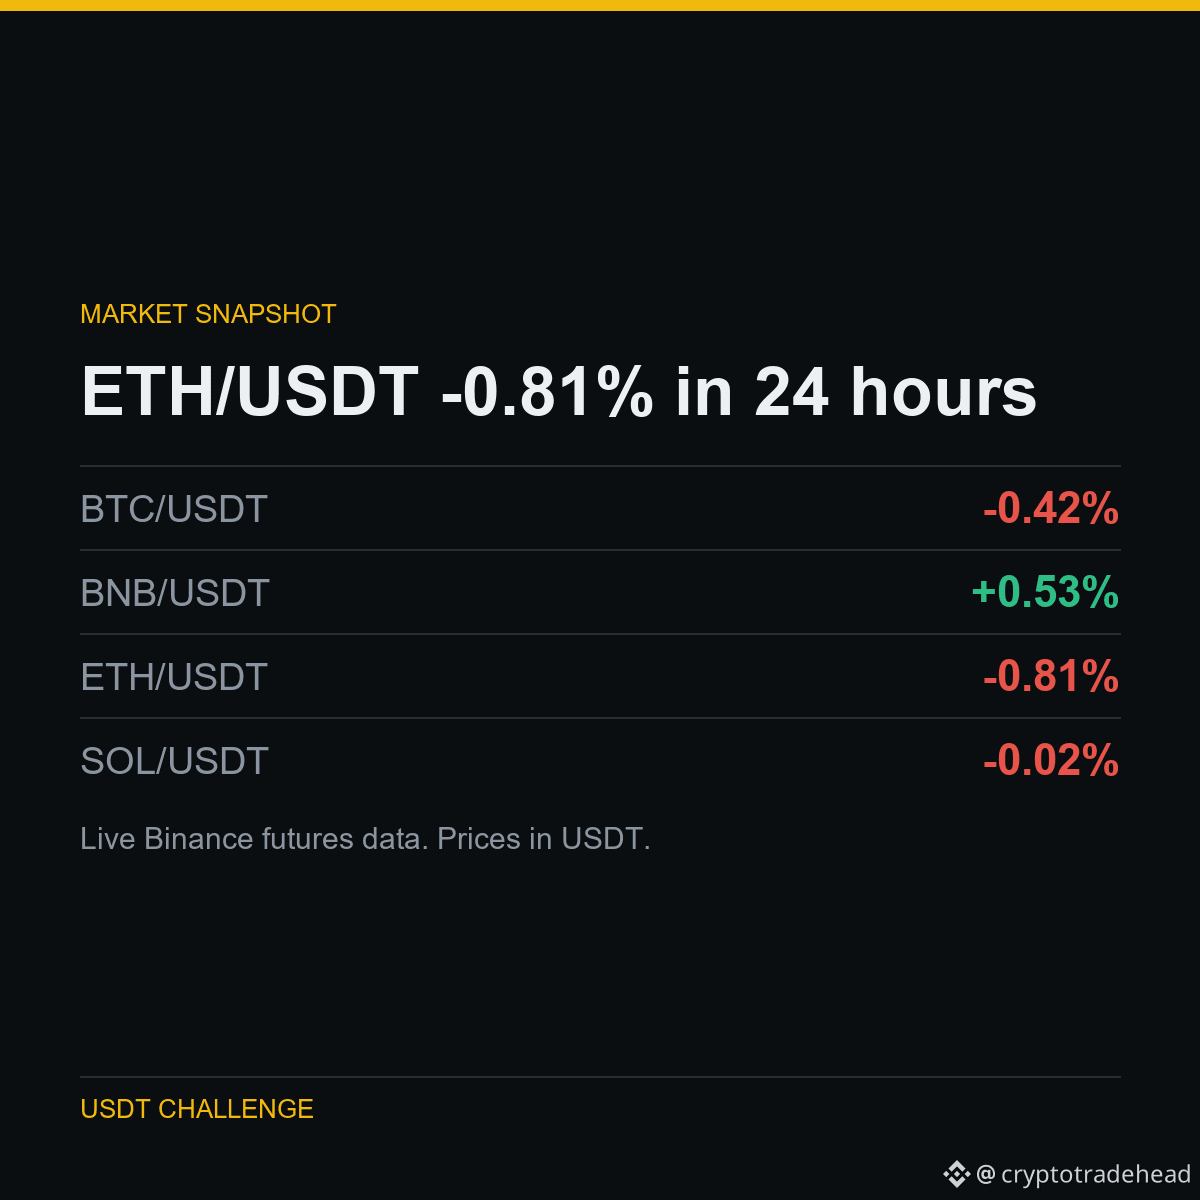
24-HOUR SNAPSHOT
BTC/USDT: 83,764.90 USDT (-0.42%)
BNB/USDT: 768.63 USDT (+0.53%)
ETH/USDT: 2,691.86 USDT (-0.81%)
SOL/USDT: 119.60 USDT (-0.02%)
Funding on ETH/USDT is +0.0068% per 8h.
Context, not a call: I do not post entries or targets. Everything I trade is logged and published after the fact, wins and losses both.
Covered above: $ETH $BNB $BTC
#Binance #Crypto #Futures #BTC #Altcoins
13
Article
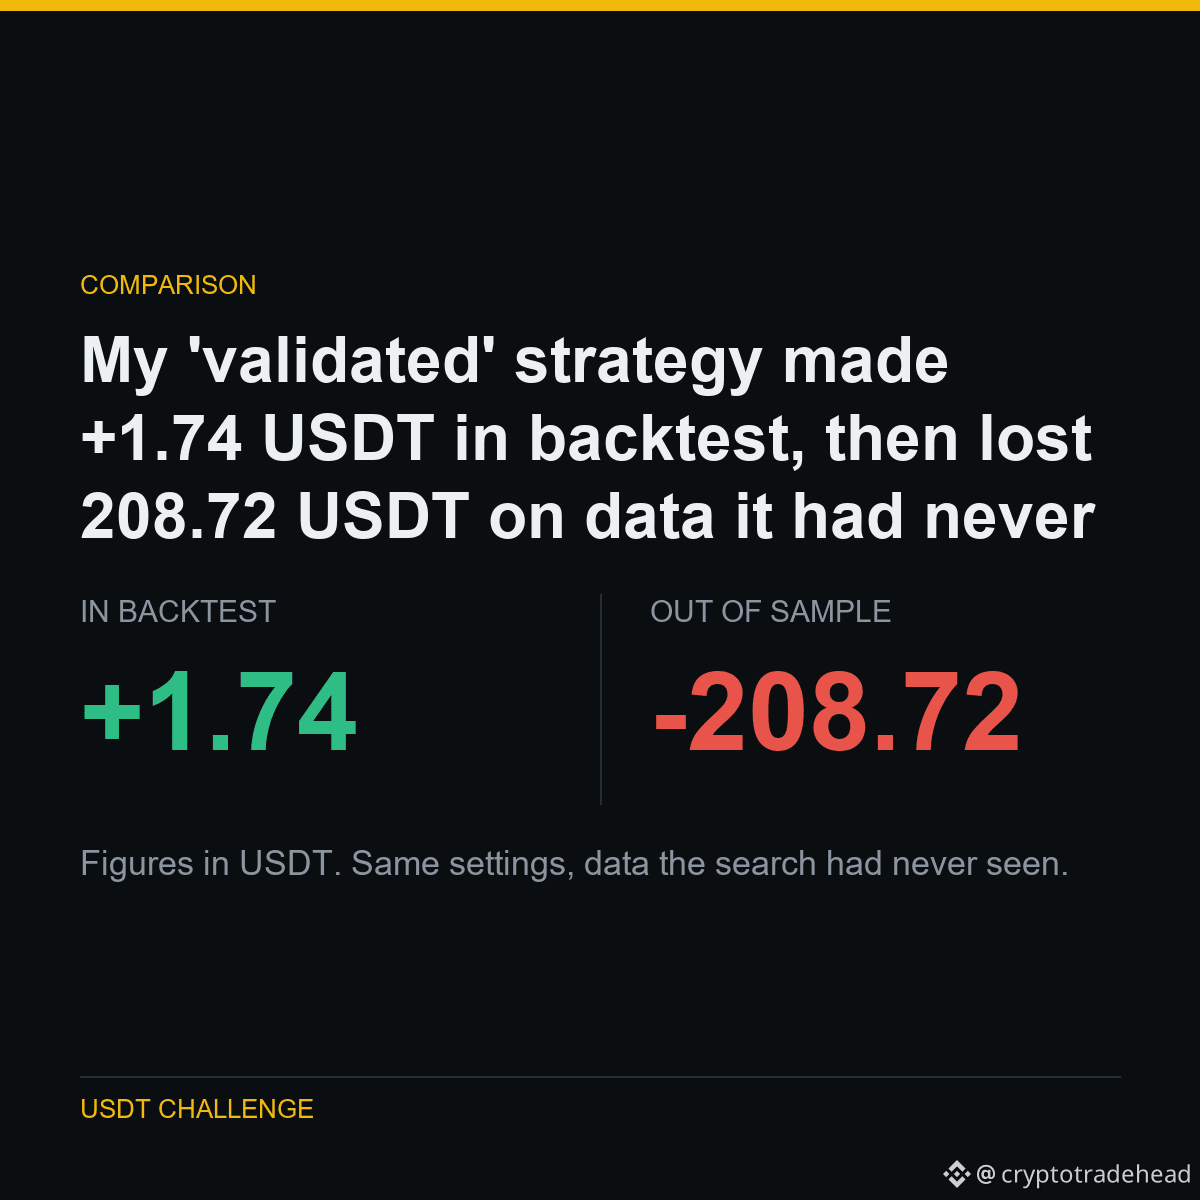
My 'validated' strategy made +1.74 USDT in backtest, then lost 208.72 USDT on data it hadMy 'validated' strategy made +1.74 USDT in backtest, then lost 208.72 USDT on data it had never seen.
I swept 40 symbols and found three that looked profitable. I called them validated and put them live.
Then I tested the exact same settings on 751 days of price history the search had never touched. All three reversed. Not marginally - completely.
Three survivors out of 40 is roughly what pure chance produces at that sample size.
WHAT IT MEANS
Searching hard enough through random data will always produce a winner. The out-of-sample test is the only thing that tells you whether you found an edge or just found noise wearing a costume.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $ETH $BNB
#Binance #Futures #Backtesting #TradingBot #CryptoData
My 'validated' strategy made +1.74 USDT in backtest, then lost 208.72 USDT on data it had
My 'validated' strategy made +1.74 USDT in backtest, then lost 208.72 USDT on data it had never seen.
I swept 40 symbols and found three that looked profitable. I called them validated and put them live.
Then I tested the exact same settings on 751 days of price history the search had never touched. All three reversed. Not marginally - completely.
Three survivors out of 40 is roughly what pure chance produces at that sample size.
WHAT IT MEANS
Searching hard enough through random data will always produce a winner. The out-of-sample test is the only thing that tells you whether you found an edge or just found noise wearing a costume.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $ETH $BNB
#Binance #Futures #Backtesting #TradingBot #CryptoData
5
Article
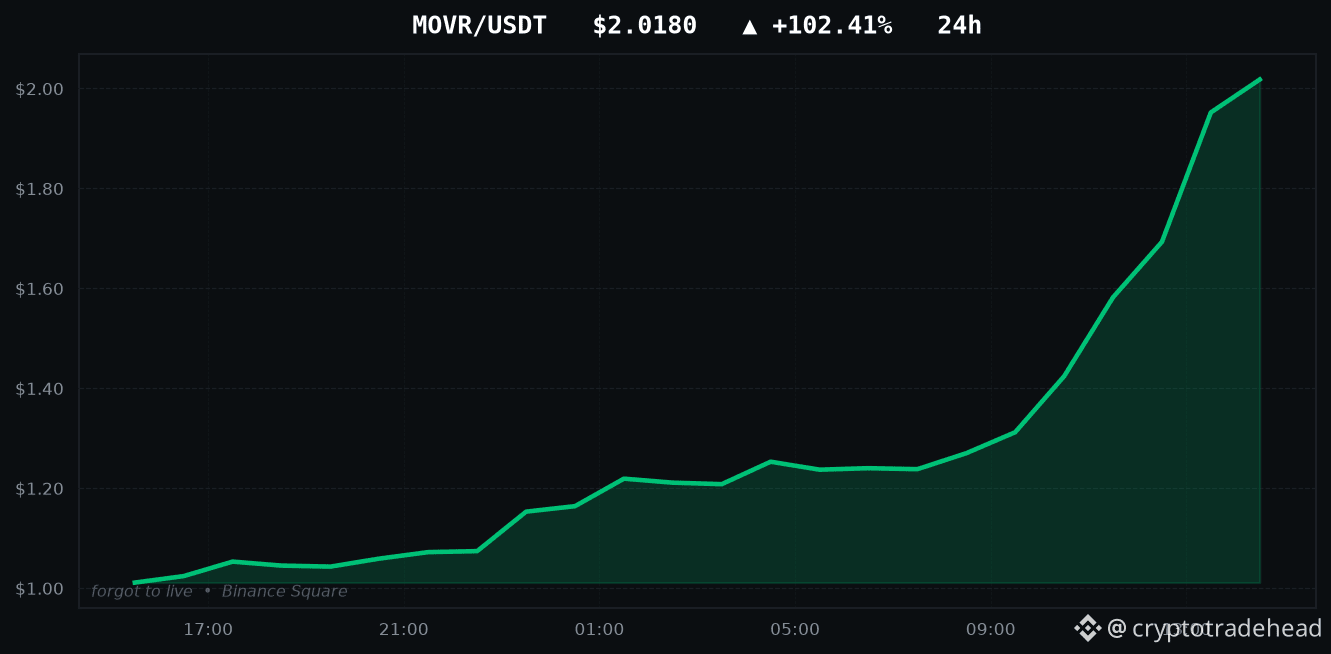
MOVR is up +102.41% - I tested both ways to trade itTODAY'S TOP GAINERS
MOVR: +102.41%
GLMR: +32.38%
GTC: +30.25%
PHA: +26.64%
ARK: +23.00%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like MOVR's +102.41%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $MOVR $GLMR $GTC
#Binance #Altcoins #Futures #MOVR #CryptoData
MOVR is up +102.41% - I tested both ways to trade it
TODAY'S TOP GAINERS
MOVR: +102.41%
GLMR: +32.38%
GTC: +30.25%
PHA: +26.64%
ARK: +23.00%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like MOVR's +102.41%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $MOVR $GLMR $GTC
#Binance #Altcoins #Futures #MOVR #CryptoData
10
Article
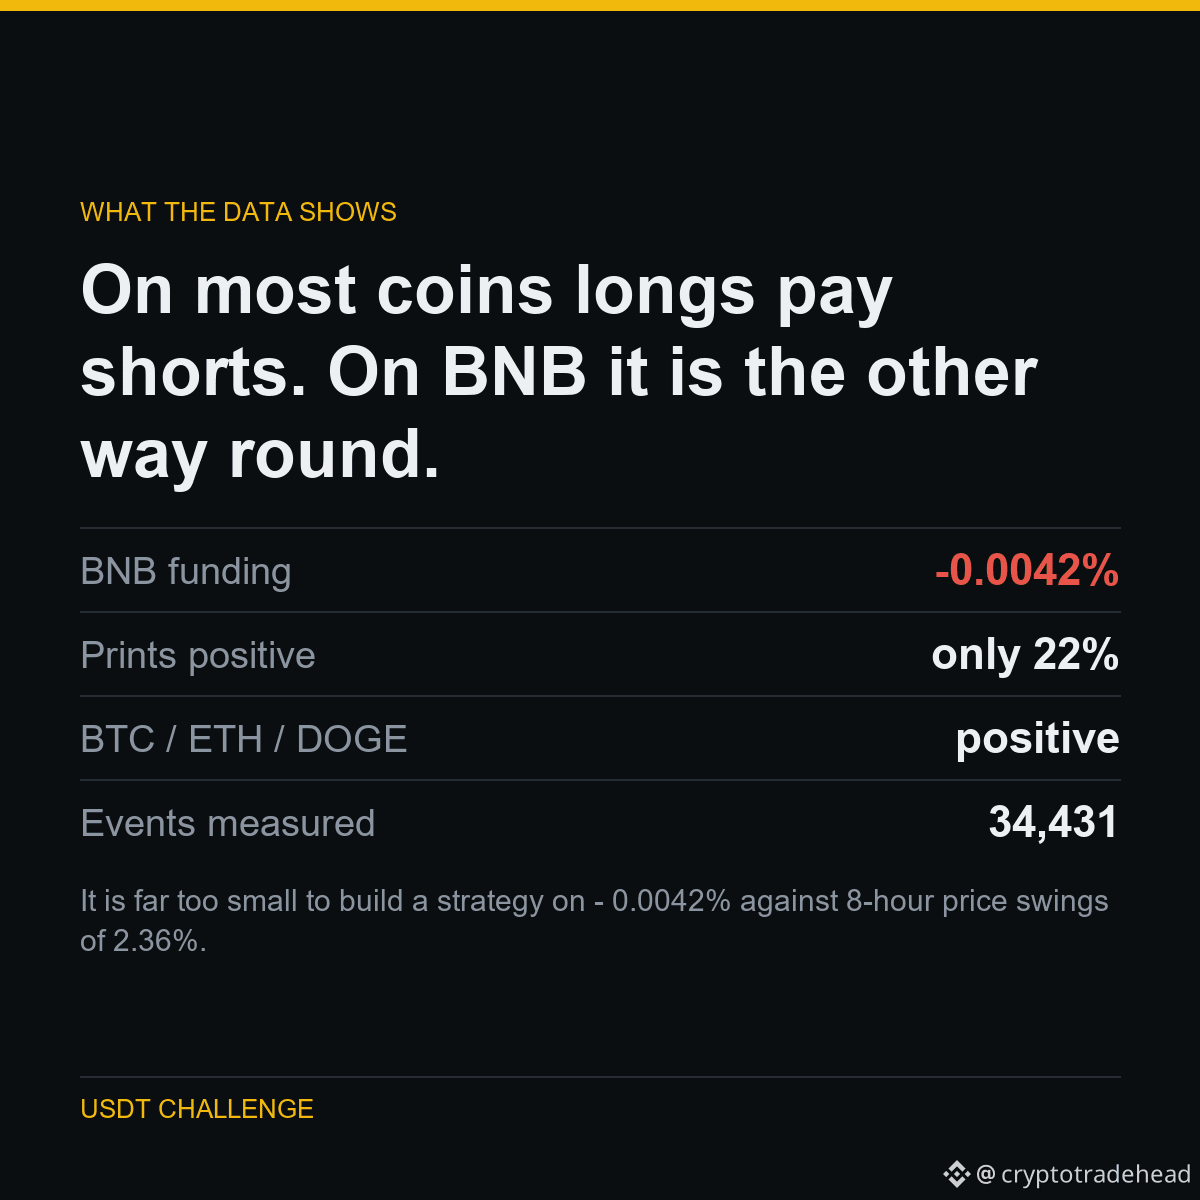
On most coins longs pay shorts. On BNB it is the other way round.On most coins longs pay shorts. On BNB it is the other way round.
Funding is the payment between long and short holders of a perpetual. Positive means longs pay shorts, which is the usual state of a market where most people are betting up.
Across 34,431 prints, BNB averages NEGATIVE funding - shorts pay longs - and only 22% of its prints are positive. BTC, ETH and DOGE are all positive.
So holding a long BNB perp is paid to exist, where a long BTC perp pays rent.
WHAT IT MEANS
It is far too small to build a strategy on - 0.0042% against 8-hour price swings of 2.36%. But if you are already holding a position, the direction of funding is not the same on every coin, and most people assume it is.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BNB $BTC $ETH
#Binance #Futures #Backtesting #TradingBot #CryptoData
On most coins longs pay shorts. On BNB it is the other way round.
On most coins longs pay shorts. On BNB it is the other way round.
Funding is the payment between long and short holders of a perpetual. Positive means longs pay shorts, which is the usual state of a market where most people are betting up.
Across 34,431 prints, BNB averages NEGATIVE funding - shorts pay longs - and only 22% of its prints are positive. BTC, ETH and DOGE are all positive.
So holding a long BNB perp is paid to exist, where a long BTC perp pays rent.
WHAT IT MEANS
It is far too small to build a strategy on - 0.0042% against 8-hour price swings of 2.36%. But if you are already holding a position, the direction of funding is not the same on every coin, and most people assume it is.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BNB $BTC $ETH
#Binance #Futures #Backtesting #TradingBot #CryptoData
6
Article
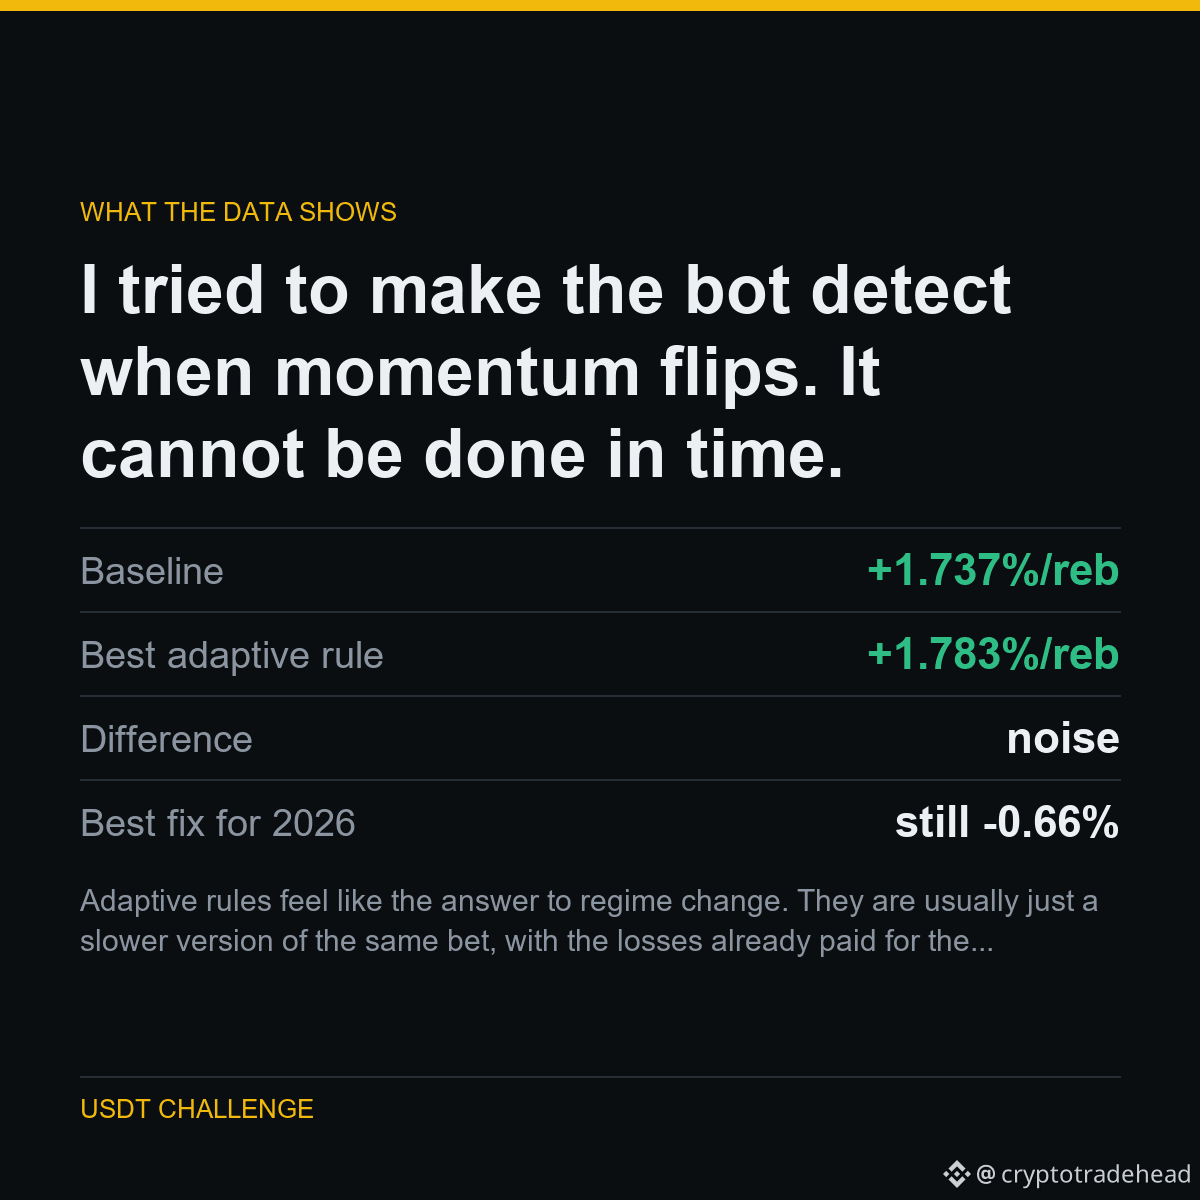
I tried to make the bot detect when momentum flips. It cannot be done in time.I tried to make the bot detect when momentum flips. It cannot be done in time.
Momentum inverted in 2026. The obvious fix: watch recent performance, and flip to the opposite rule when momentum stops paying.
I tested that over six different lookback windows. The best one returned +1.783% per rebalance against a +1.737% baseline - a difference indistinguishable from noise. Every other window was worse. None repaired 2026.
The reason is simple: by the time trailing performance tells you the regime flipped, you have already taken the losses that told you.
WHAT IT MEANS
Adaptive rules feel like the answer to regime change. They are usually just a slower version of the same bet, with the losses already paid for the signal.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $SOL $BTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
I tried to make the bot detect when momentum flips. It cannot be done in time.
I tried to make the bot detect when momentum flips. It cannot be done in time.
Momentum inverted in 2026. The obvious fix: watch recent performance, and flip to the opposite rule when momentum stops paying.
I tested that over six different lookback windows. The best one returned +1.783% per rebalance against a +1.737% baseline - a difference indistinguishable from noise. Every other window was worse. None repaired 2026.
The reason is simple: by the time trailing performance tells you the regime flipped, you have already taken the losses that told you.
WHAT IT MEANS
Adaptive rules feel like the answer to regime change. They are usually just a slower version of the same bet, with the losses already paid for the signal.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $SOL $BTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
Article
MOVR is up +88.37% - I tested both ways to trade itTODAY'S TOP GAINERS
MOVR: +88.37%
GTC: +35.80%
PHA: +24.09%
GLMR: +23.33%
ARK: +18.57%
Every account on this app will show you this list. Here is the part they skip.
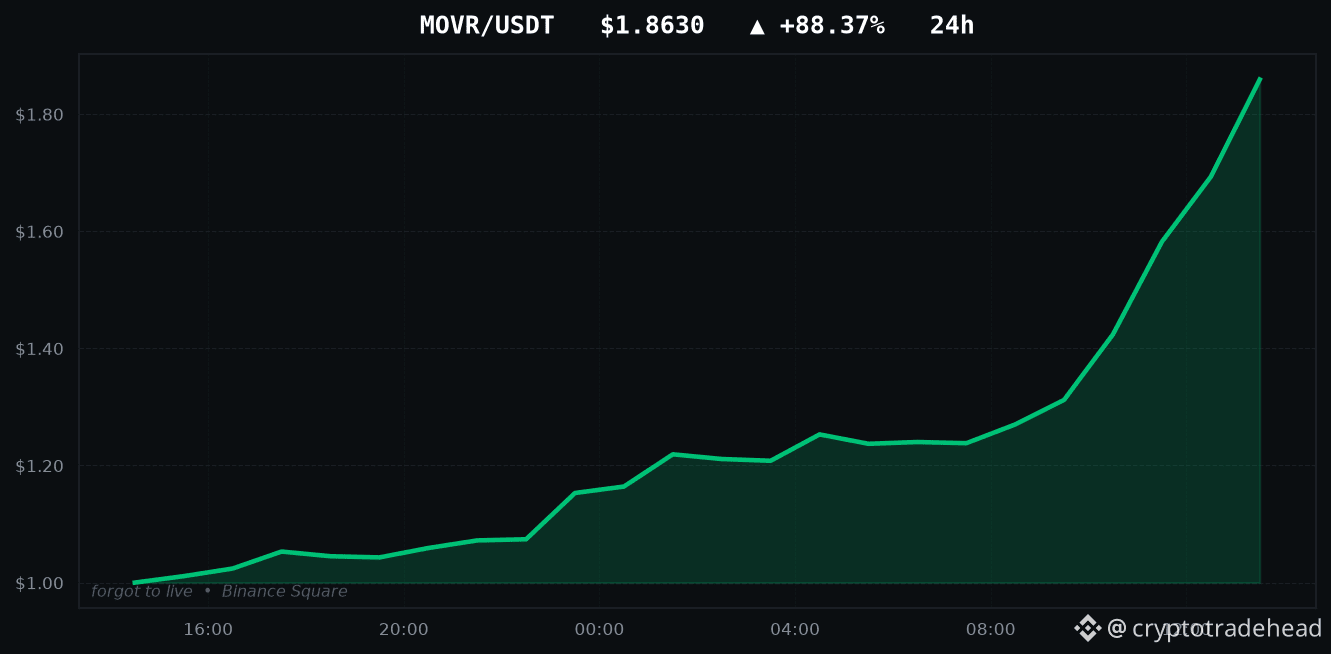
I backtested both ways of trading a move like MOVR's +88.37%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $MOVR $GTC $PHA
#Binance #Altcoins #Futures #MOVR #CryptoData
MOVR is up +88.37% - I tested both ways to trade it
TODAY'S TOP GAINERS
MOVR: +88.37%
GTC: +35.80%
PHA: +24.09%
GLMR: +23.33%
ARK: +18.57%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like MOVR's +88.37%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $MOVR $GTC $PHA
#Binance #Altcoins #Futures #MOVR #CryptoData
9
HOW I TESTED IT
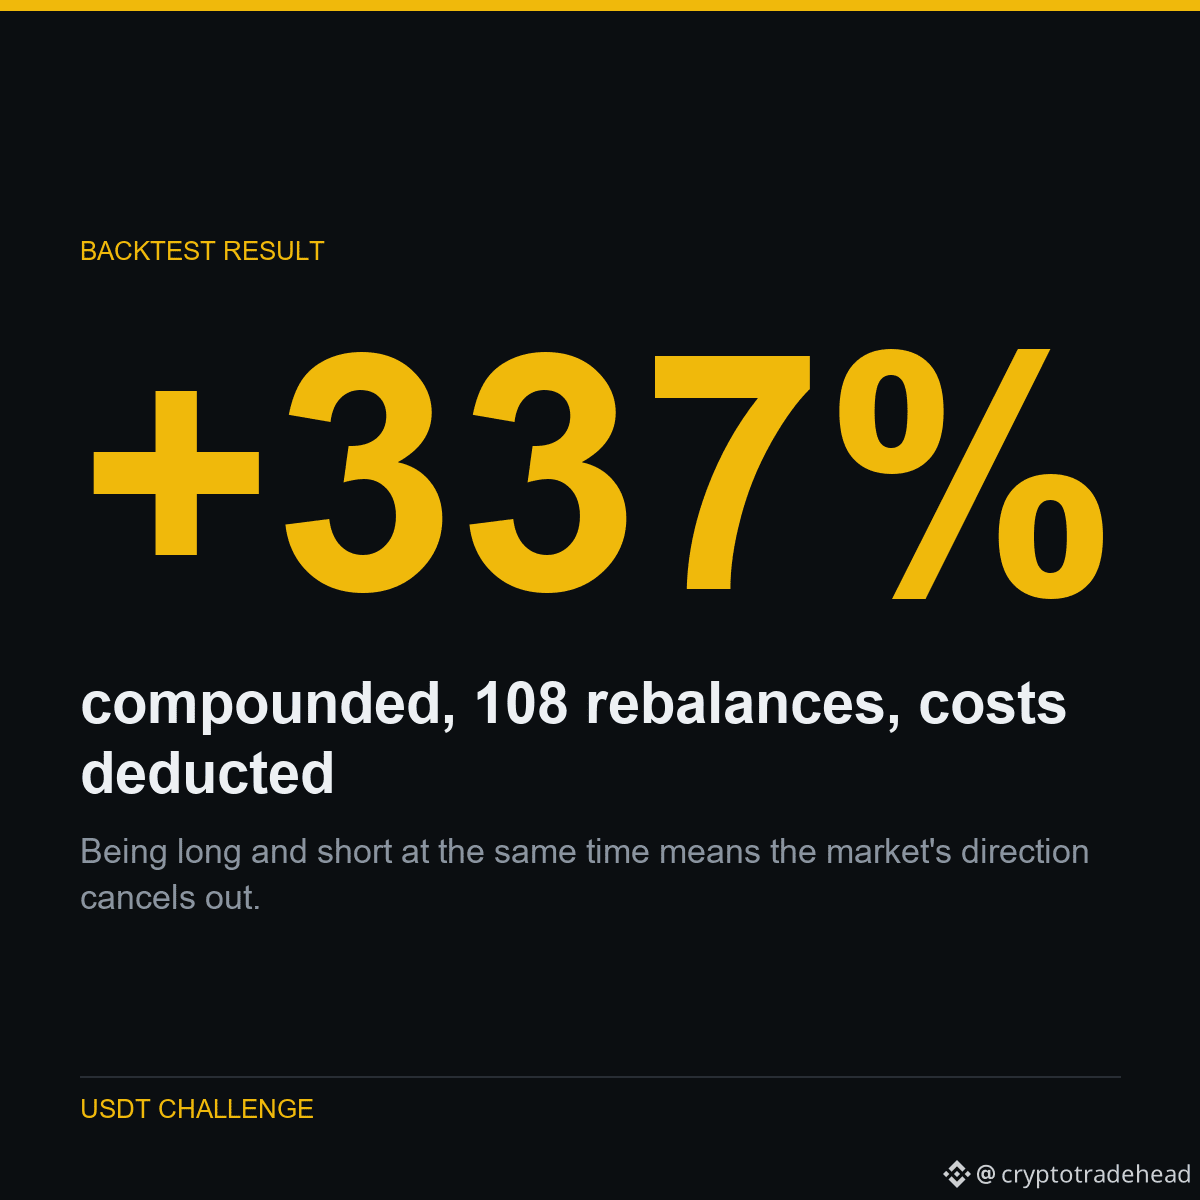
Rank 45 perpetuals by 5-day return. Long the top 5, short the bottom 5, hold 15 days, rebalance. Equal weight, dollar-neutral.
The out-of-sample control is the one that had destroyed everything before it: fix the settings on old data, then run them on data the search never touched. In-sample +1.711% per rebalance, out-of-sample +1.801%. The mean held.
It also survives costs far worse than real: still +0.48% per rebalance even at a 1.50% round trip, six times what Binance actually charges.
THE NUMBERS
Mean per rebalance: +1.737%
In-sample: +1.711%
Out-of-sample: +1.801%
Win rate: 55.6%
Being long and short at the same time means the market's direction cancels out. What is left is whether the winners keep beating the losers - which is a real question, not a bet on the market going up.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $SOL $BNB $BTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
1
Article
My best strategy loses on 64% of its trades. It is still the best one I have.My best strategy loses on 64% of its trades. It is still the best one I have.
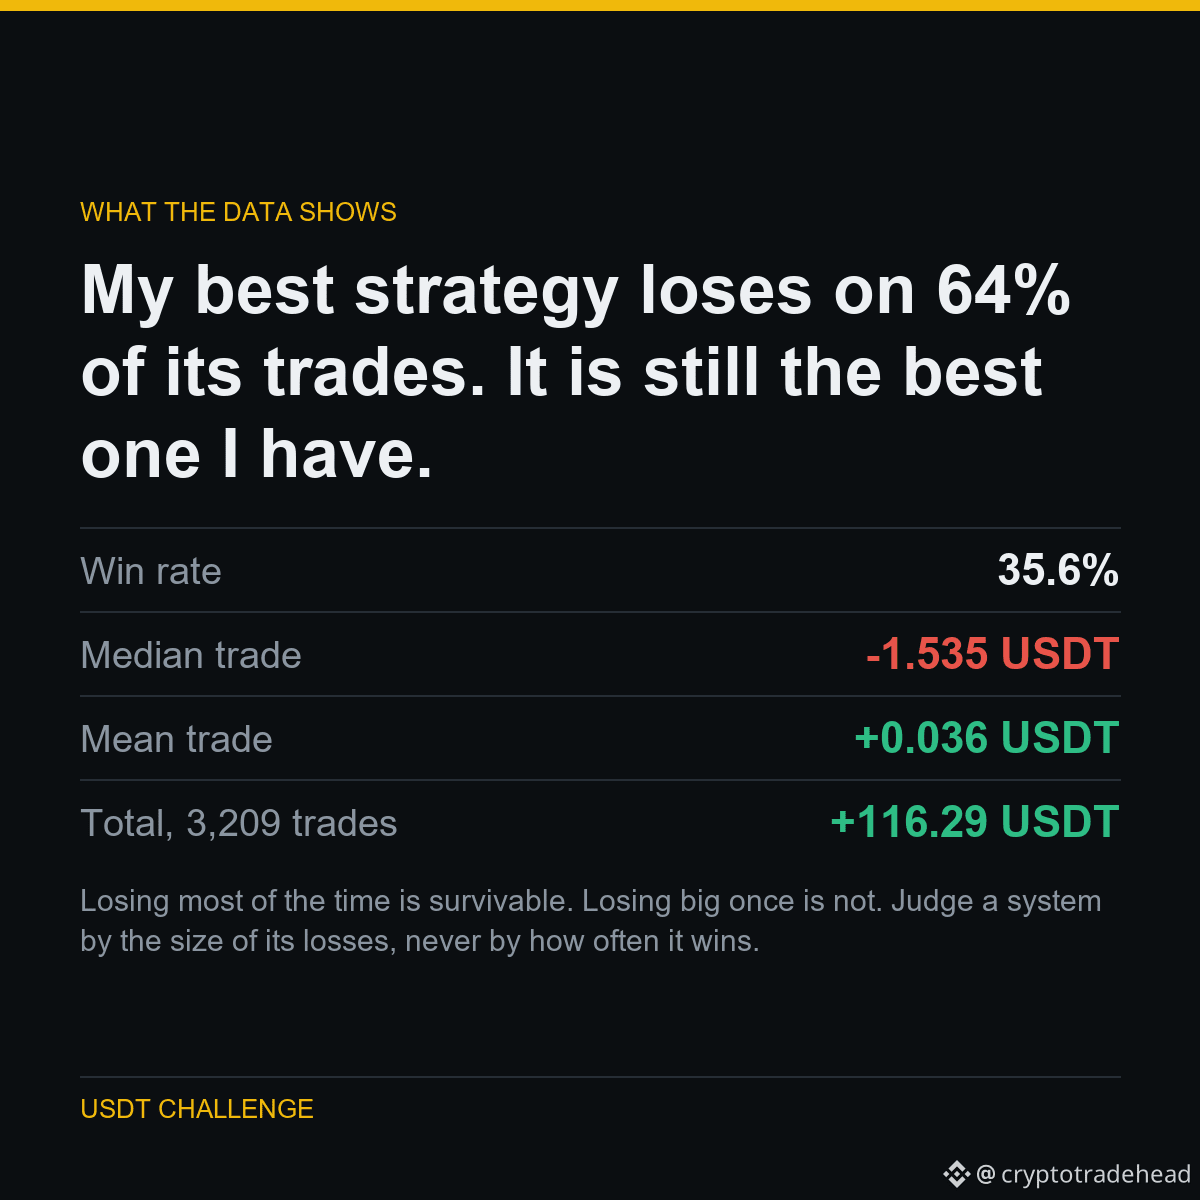
The typical trade in this system loses 1.535 USDT. Nearly two out of three trades are losers.
It is profitable anyway, because the winners are much larger than the losers. The mean trade is positive while the median is clearly negative.
It is also the opposite shape to the martingale I tested, which won 96% of the time and still lost 519.83 USDT.
WHAT IT MEANS
Losing most of the time is survivable. Losing big once is not. Judge a system by the size of its losses, never by how often it wins.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $XRP $LTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
My best strategy loses on 64% of its trades. It is still the best one I have.
My best strategy loses on 64% of its trades. It is still the best one I have.
The typical trade in this system loses 1.535 USDT. Nearly two out of three trades are losers.
It is profitable anyway, because the winners are much larger than the losers. The mean trade is positive while the median is clearly negative.
It is also the opposite shape to the martingale I tested, which won 96% of the time and still lost 519.83 USDT.
WHAT IT MEANS
Losing most of the time is survivable. Losing big once is not. Judge a system by the size of its losses, never by how often it wins.
Part of a public experiment: 5,063 USDT to 1,000,000 USDT, every result published - including the ones that make me look bad.
Run on $BTC $XRP $LTC
#Binance #Futures #Backtesting #TradingBot #CryptoData
7
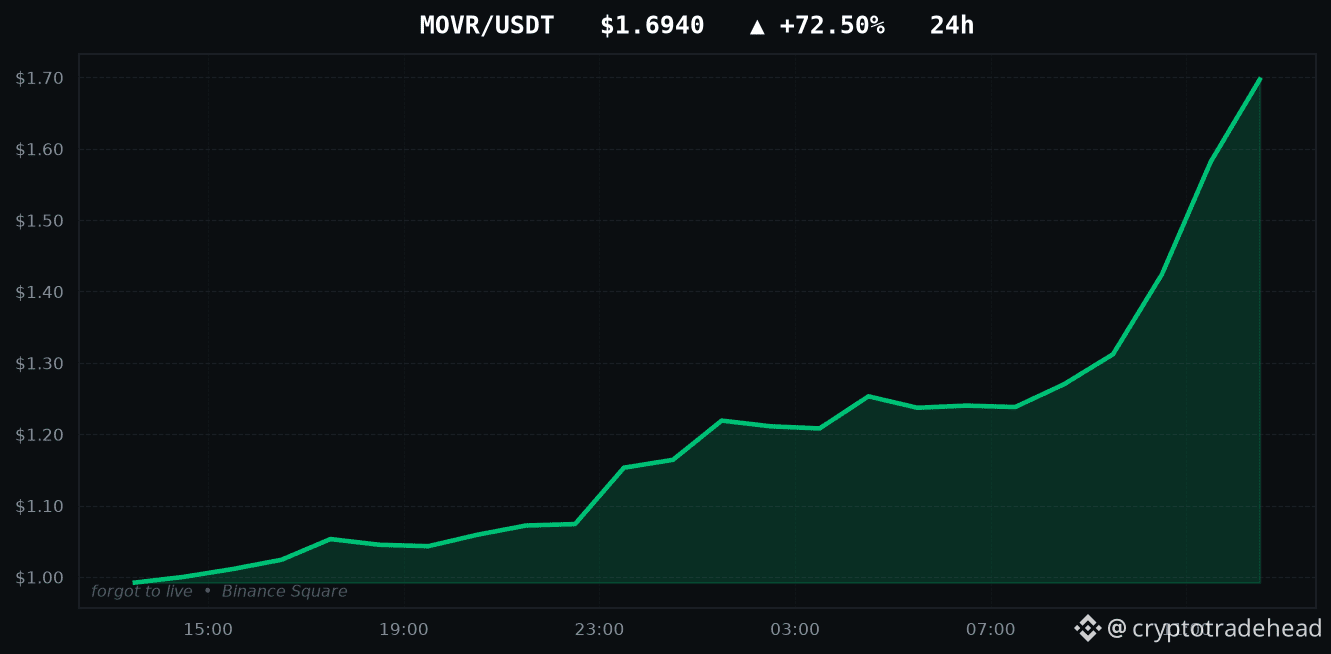
Article
MOVR is up +72.50% - I tested both ways to trade itTODAY'S TOP GAINERS
MOVR: +72.50%
GTC: +34.61%
GLMR: +19.48%
0G: +18.08%
ARK: +15.86%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like MOVR's +72.50%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $MOVR $GTC $GLMR
#Binance #Altcoins #Futures #MOVR #CryptoData
MOVR is up +72.50% - I tested both ways to trade it
TODAY'S TOP GAINERS
MOVR: +72.50%
GTC: +34.61%
GLMR: +19.48%
0G: +18.08%
ARK: +15.86%
Every account on this app will show you this list. Here is the part they skip.
I backtested both ways of trading a move like MOVR's +72.50%: buying the breakout, and fading it on the assumption it reverts. Both lost money. Not narrowly - they lost roughly the transaction cost, 0.240% per round trip, which is what a signal carrying no information looks like once you charge it fees.
A large 24-hour move tells you something already happened. It does not tell you what happens next, and the data says so in both directions.
Part of a public experiment: every strategy I test gets published, working or not.
Movers above: $MOVR $GTC $GLMR
#Binance #Altcoins #Futures #MOVR #CryptoData
10
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
BitcoinClears$85200
50 views
34 Discussing
#BitcoinClears$85200
🚨 Bitcoin is back above $85,200.
$BTC is trading around the $85K area as broader markets react to fresh U.S. economic data.
The $85K–$86K zone is now the area to watch. Traders are looking for confirmation through spot volume, price action, open interest, funding and ETF flows, while BTC dominance remains another key metric.
The bigger point: a move above a level doesn’t automatically confirm a sustained breakout. Price + volume confirmation is what matters before drawing stronger conclusions.
$BTC
| $ARK | $MOVR | $QNT
#Bitcoin #BTC #cryptotrading #CryptoMarket #BinanceSquare
S1R0Z
·0 Likes
·19 views
AltcoinSeasonIndexHoldsAbove60For5Days
2,139 views
269 Discussing
BitcoinSlipsBelow$84000
1,154 views
67 Discussing