
#polygon
polygon
12.6M views
119,195 Discussing
Hot
Latest

Article
My First Crypto Love: Can a Good Project Be a Bad Investment?I’ve analysed dozens of crypto projects. The hardest one to analyse honestly is the one I fell in love with first.
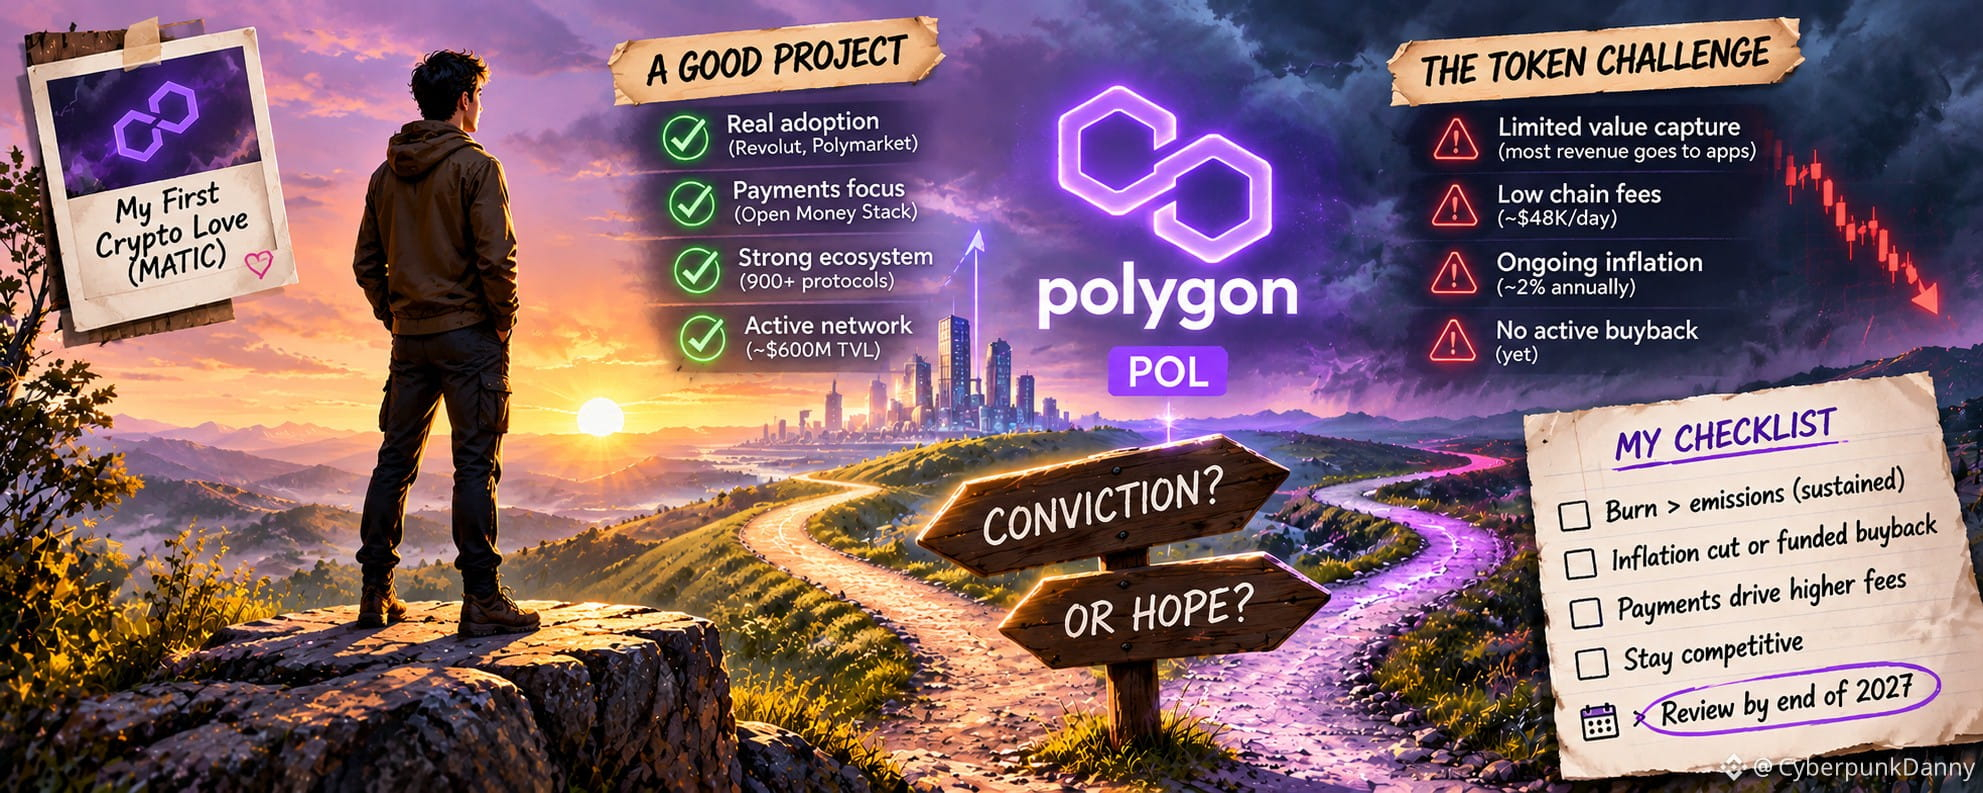
My first crypto purchase was MATIC. Four years later, it’s called POL, it trades at $0.079, and I still haven’t sold it.
I bought it somewhere between $0.25 and $0.50. That’s a loss of roughly 70–85%, depending on which buy you count. In my last post, I compared myself to a parent at a school play, clapping no matter how badly the show goes.
My portfolio app shows POL in red so consistently that I started to believe red is Polygon’s brand colour. (It’s purple. I checked.)
This time, instead of clapping, I opened the data and asked the question every long-term holder eventually has to face: can a good project still be a bad investment? Or, more personally: am I holding $POL because of conviction, or because it was my first crypto love?
The Case for Love: Polygon Is Alive
Let’s be fair to my first love. This is not a ghost town.
On DefiLlama, Polygon ranks #4 among all chains in daily app revenue, ahead of Base, BSC and Arbitrum. It has more than 900 protocols, around $600 million in DeFi TVL and about $2.8 billion in stablecoins on-chain.
The direction has also become much clearer. The team has been leaving breadcrumbs:
It stopped calling itself a Layer 2. Polygon PoS now describes itself as a sidechain, an independent chain with its own validators.
It’s shutting down the zkEVM, its most ambitious technical bet, to focus on one chain.
It’s betting on payments with the Open Money Stack, and backing that with real money: the $250 million acquisition of Coinme and Sequence.
Big names use it. Revolut launched its euro stablecoin EURR on Polygon, and Polymarket, one of the world’s biggest prediction markets, runs on it.
If I were judging a company, I’d say Polygon finally looks focused. My first love got a haircut, a new job and a five-year plan.
Why the Token Isn’t Getting the Love Back
Here’s the problem: I don’t own the network. I own the token. And the token gets surprisingly little of the value.
App revenue goes to the apps. Polygon’s daily app revenue is around $790,000, but most of it comes from Polymarket, and Polymarket settles in USDC. Its users don’t need to buy POL at all.
Chain fees are small. Only gas fees touch POL, and they’re about $48,000 a day. Solana’s are roughly seven times higher. Polygon is designed to be cheap, which is great for users and payments, but it means heavy usage still produces little fee income. You could make a thousand transactions on Polygon and still have money left for coffee. Great for users. Less great for the token that’s supposed to earn from those fees.
Revenue is falling, not growing. DefiLlama’s income statement shows Polygon’s gross protocol revenue shrinking through 2026: $11.6M in Q1, $8.1M in Q2 and $7.1M in Q3. That’s roughly $30 million a year, for a token with a market cap of about $840 million.
Activity, revenue and token-holder value are three different things. Polygon has plenty of the first, some of the second, and not enough of the third.
The Supply Problem
POL has 2% annual inflation, about 200 million new tokens every year, split between staking rewards and the community treasury. Every new token needs a buyer. For the last four years, one of those buyers has mostly been me.
The good news: 100% of base fees are burned, and the burns are real. In the first half of 2026, Polygon burned about 107.7 million POL against 105.2 million minted, making it slightly net deflationary. In September, it burned 100 million POL, about 1% of supply, in a single event.
The bad news: it doesn’t hold. In the 30 days to October 11, new emissions of 17.45 million POL beat the 13.23 million collected for burning. And the one mechanism that would turn real business revenue into POL demand, a treasury buyback, is still only a proposal.
So supply is roughly flat, not shrinking. Flat supply plus weak demand doesn’t push a price up.
The Strongest Bull Case
To be fair, the bullish case isn’t nonsense. POL pays for gas, secures the network through staking, and gains directly whenever burns beat emissions. If Polygon becomes a major payments rail, with fintechs like Revolut moving serious volume, fees go up, burns go up, and supply could finally shrink for real.
The first half of 2026 already proved that burn can beat inflation. The question is whether it can do that every month, not just in the good ones.
And yes, I can feel the hopium kicking in as I write this. Revolut, payments, burns, fintech partners… For a second I’m back in 2022, picturing MATIC at $3 and planning what to do with the profit. Then I look at the chart again, and the hopium wears off faster than a Solana memecoin pump.
Conviction or Hope?
This is the uncomfortable part. When I say “the project is good, so I’ll wait,” I need to be honest about what I’m actually waiting for.
Waiting with conviction means I know what has to happen, and I can check whether it’s happening. Waiting with hope means I’m waiting for the market to love the token again, without a clear reason why it should.
If I’m honest, my POL position has had too much hope and not enough structure. For years, my argument went like this: the tech is good, the team is serious, the project is alive, next cycle will fix it.
Maybe. But that’s not an investment thesis. That’s emotional attachment wearing analytical clothes.
Turning Love Into a Checklist
So from now on, POL earns my patience only if I can tick these boxes:
Burn bigger than emissions, sustained. Not one great month, but most months over a year.Inflation cut or a funded buyback that actually starts, not just a proposal.Payments driving higher fees. Daily chain fees growing meaningfully, not just app revenue.Staying competitive. Tron, Solana, Base, Stripe’s Tempo and Circle’s Arc all want the payments market. If they win it, Polygon’s story doesn’t matter.
And I need a deadline. If the checklist isn’t turning green by the end of 2027, I sell at least half and rotate it into BTC. Not because Polygon is bad, but because a useful network and a rewarding investment are not the same thing.
I’m writing this deadline publicly, so all of Binance Square can hold me to it. Please do. Future me will try to negotiate.
So, Am I Still Blinded by Love?
A little. Probably always will be. It was my first. Somewhere in my portfolio, the 2022 version of me is still waiting for MATIC to hit $3, and I don’t have the heart to tell him.
But there’s a difference between loving a project and being blind to it. Blind love says, “It’s good, so eventually it has to go up.” Honest love says, “It’s good, but I need a measurable reason to believe the token benefits, and a date when I stop waiting.”
My final test is the same question as last time: if I had cash today, would I buy POL at $0.079? For the first time, my answer isn’t an automatic yes or no. It’s: only if the checklist starts turning green.
In my last post, I said that in crypto, hope sometimes goes by another name: hopium. I still believe hope is a beautiful word. Strong, stubborn, resilient. I just don’t want to live on it anymore.
So this time, I gave my hope two things it never had before: a checklist and an expiry date.
That’s not blind love anymore. That’s a relationship with conditions.
What about you? Do you have a “first love” coin you’re still holding? And are you waiting with conviction, or with hope?
Not financial advice. Just my own experience, my own bags and my own mistakes. DYOR. Always DYOR, and then DYOR some more before you yourwallet.
#Polygon #POL #CryptoLesson #Tokenomics #DYOR
My First Crypto Love: Can a Good Project Be a Bad Investment?
I’ve analysed dozens of crypto projects. The hardest one to analyse honestly is the one I fell in love with first.
My first crypto purchase was MATIC. Four years later, it’s called POL, it trades at $0.079, and I still haven’t sold it.
I bought it somewhere between $0.25 and $0.50. That’s a loss of roughly 70–85%, depending on which buy you count. In my last post, I compared myself to a parent at a school play, clapping no matter how badly the show goes.
My portfolio app shows POL in red so consistently that I started to believe red is Polygon’s brand colour. (It’s purple. I checked.)
This time, instead of clapping, I opened the data and asked the question every long-term holder eventually has to face: can a good project still be a bad investment? Or, more personally: am I holding $POL because of conviction, or because it was my first crypto love?
The Case for Love: Polygon Is Alive
Let’s be fair to my first love. This is not a ghost town.
On DefiLlama, Polygon ranks #4 among all chains in daily app revenue, ahead of Base, BSC and Arbitrum. It has more than 900 protocols, around $600 million in DeFi TVL and about $2.8 billion in stablecoins on-chain.
The direction has also become much clearer. The team has been leaving breadcrumbs:
It stopped calling itself a Layer 2. Polygon PoS now describes itself as a sidechain, an independent chain with its own validators.
It’s shutting down the zkEVM, its most ambitious technical bet, to focus on one chain.
It’s betting on payments with the Open Money Stack, and backing that with real money: the $250 million acquisition of Coinme and Sequence.
Big names use it. Revolut launched its euro stablecoin EURR on Polygon, and Polymarket, one of the world’s biggest prediction markets, runs on it.
If I were judging a company, I’d say Polygon finally looks focused. My first love got a haircut, a new job and a five-year plan.
Why the Token Isn’t Getting the Love Back
Here’s the problem: I don’t own the network. I own the token. And the token gets surprisingly little of the value.
App revenue goes to the apps. Polygon’s daily app revenue is around $790,000, but most of it comes from Polymarket, and Polymarket settles in USDC. Its users don’t need to buy POL at all.
Chain fees are small. Only gas fees touch POL, and they’re about $48,000 a day. Solana’s are roughly seven times higher. Polygon is designed to be cheap, which is great for users and payments, but it means heavy usage still produces little fee income. You could make a thousand transactions on Polygon and still have money left for coffee. Great for users. Less great for the token that’s supposed to earn from those fees.
Revenue is falling, not growing. DefiLlama’s income statement shows Polygon’s gross protocol revenue shrinking through 2026: $11.6M in Q1, $8.1M in Q2 and $7.1M in Q3. That’s roughly $30 million a year, for a token with a market cap of about $840 million.
Activity, revenue and token-holder value are three different things. Polygon has plenty of the first, some of the second, and not enough of the third.
The Supply Problem
POL has 2% annual inflation, about 200 million new tokens every year, split between staking rewards and the community treasury. Every new token needs a buyer. For the last four years, one of those buyers has mostly been me.
The good news: 100% of base fees are burned, and the burns are real. In the first half of 2026, Polygon burned about 107.7 million POL against 105.2 million minted, making it slightly net deflationary. In September, it burned 100 million POL, about 1% of supply, in a single event.
The bad news: it doesn’t hold. In the 30 days to October 11, new emissions of 17.45 million POL beat the 13.23 million collected for burning. And the one mechanism that would turn real business revenue into POL demand, a treasury buyback, is still only a proposal.
So supply is roughly flat, not shrinking. Flat supply plus weak demand doesn’t push a price up.
The Strongest Bull Case
To be fair, the bullish case isn’t nonsense. POL pays for gas, secures the network through staking, and gains directly whenever burns beat emissions. If Polygon becomes a major payments rail, with fintechs like Revolut moving serious volume, fees go up, burns go up, and supply could finally shrink for real.
The first half of 2026 already proved that burn can beat inflation. The question is whether it can do that every month, not just in the good ones.
And yes, I can feel the hopium kicking in as I write this. Revolut, payments, burns, fintech partners… For a second I’m back in 2022, picturing MATIC at $3 and planning what to do with the profit. Then I look at the chart again, and the hopium wears off faster than a Solana memecoin pump.
Conviction or Hope?
This is the uncomfortable part. When I say “the project is good, so I’ll wait,” I need to be honest about what I’m actually waiting for.
Waiting with conviction means I know what has to happen, and I can check whether it’s happening. Waiting with hope means I’m waiting for the market to love the token again, without a clear reason why it should.
If I’m honest, my POL position has had too much hope and not enough structure. For years, my argument went like this: the tech is good, the team is serious, the project is alive, next cycle will fix it.
Maybe. But that’s not an investment thesis. That’s emotional attachment wearing analytical clothes.
Turning Love Into a Checklist
So from now on, POL earns my patience only if I can tick these boxes:
Burn bigger than emissions, sustained. Not one great month, but most months over a year.Inflation cut or a funded buyback that actually starts, not just a proposal.Payments driving higher fees. Daily chain fees growing meaningfully, not just app revenue.Staying competitive. Tron, Solana, Base, Stripe’s Tempo and Circle’s Arc all want the payments market. If they win it, Polygon’s story doesn’t matter.
And I need a deadline. If the checklist isn’t turning green by the end of 2027, I sell at least half and rotate it into BTC. Not because Polygon is bad, but because a useful network and a rewarding investment are not the same thing.
I’m writing this deadline publicly, so all of Binance Square can hold me to it. Please do. Future me will try to negotiate.
So, Am I Still Blinded by Love?
A little. Probably always will be. It was my first. Somewhere in my portfolio, the 2022 version of me is still waiting for MATIC to hit $3, and I don’t have the heart to tell him.
But there’s a difference between loving a project and being blind to it. Blind love says, “It’s good, so eventually it has to go up.” Honest love says, “It’s good, but I need a measurable reason to believe the token benefits, and a date when I stop waiting.”
My final test is the same question as last time: if I had cash today, would I buy POL at $0.079? For the first time, my answer isn’t an automatic yes or no. It’s: only if the checklist starts turning green.
In my last post, I said that in crypto, hope sometimes goes by another name: hopium. I still believe hope is a beautiful word. Strong, stubborn, resilient. I just don’t want to live on it anymore.
So this time, I gave my hope two things it never had before: a checklist and an expiry date.
That’s not blind love anymore. That’s a relationship with conditions.
What about you? Do you have a “first love” coin you’re still holding? And are you waiting with conviction, or with hope?
Not financial advice. Just my own experience, my own bags and my own mistakes. DYOR. Always DYOR, and then DYOR some more before you yourwallet.
#Polygon #POL #CryptoLesson #Tokenomics #DYOR
My first crypto purchase was MATIC. Four years later, it’s called POL, it trades at $0.079, and I still haven’t sold it.
I bought it somewhere between $0.25 and $0.50. That’s a loss of roughly 70–85%, depending on which buy you count. In my last post, I compared myself to a parent at a school play, clapping no matter how badly the show goes.
My portfolio app shows POL in red so consistently that I started to believe red is Polygon’s brand colour. (It’s purple. I checked.)
This time, instead of clapping, I opened the data and asked the question every long-term holder eventually has to face: can a good project still be a bad investment? Or, more personally: am I holding $POL because of conviction, or because it was my first crypto love?
The Case for Love: Polygon Is Alive
Let’s be fair to my first love. This is not a ghost town.
On DefiLlama, Polygon ranks #4 among all chains in daily app revenue, ahead of Base, BSC and Arbitrum. It has more than 900 protocols, around $600 million in DeFi TVL and about $2.8 billion in stablecoins on-chain.
The direction has also become much clearer. The team has been leaving breadcrumbs:
It stopped calling itself a Layer 2. Polygon PoS now describes itself as a sidechain, an independent chain with its own validators.
It’s shutting down the zkEVM, its most ambitious technical bet, to focus on one chain.
It’s betting on payments with the Open Money Stack, and backing that with real money: the $250 million acquisition of Coinme and Sequence.
Big names use it. Revolut launched its euro stablecoin EURR on Polygon, and Polymarket, one of the world’s biggest prediction markets, runs on it.
If I were judging a company, I’d say Polygon finally looks focused. My first love got a haircut, a new job and a five-year plan.
Why the Token Isn’t Getting the Love Back
Here’s the problem: I don’t own the network. I own the token. And the token gets surprisingly little of the value.
App revenue goes to the apps. Polygon’s daily app revenue is around $790,000, but most of it comes from Polymarket, and Polymarket settles in USDC. Its users don’t need to buy POL at all.
Chain fees are small. Only gas fees touch POL, and they’re about $48,000 a day. Solana’s are roughly seven times higher. Polygon is designed to be cheap, which is great for users and payments, but it means heavy usage still produces little fee income. You could make a thousand transactions on Polygon and still have money left for coffee. Great for users. Less great for the token that’s supposed to earn from those fees.
Revenue is falling, not growing. DefiLlama’s income statement shows Polygon’s gross protocol revenue shrinking through 2026: $11.6M in Q1, $8.1M in Q2 and $7.1M in Q3. That’s roughly $30 million a year, for a token with a market cap of about $840 million.
Activity, revenue and token-holder value are three different things. Polygon has plenty of the first, some of the second, and not enough of the third.
The Supply Problem
POL has 2% annual inflation, about 200 million new tokens every year, split between staking rewards and the community treasury. Every new token needs a buyer. For the last four years, one of those buyers has mostly been me.
The good news: 100% of base fees are burned, and the burns are real. In the first half of 2026, Polygon burned about 107.7 million POL against 105.2 million minted, making it slightly net deflationary. In September, it burned 100 million POL, about 1% of supply, in a single event.
The bad news: it doesn’t hold. In the 30 days to October 11, new emissions of 17.45 million POL beat the 13.23 million collected for burning. And the one mechanism that would turn real business revenue into POL demand, a treasury buyback, is still only a proposal.
So supply is roughly flat, not shrinking. Flat supply plus weak demand doesn’t push a price up.
The Strongest Bull Case
To be fair, the bullish case isn’t nonsense. POL pays for gas, secures the network through staking, and gains directly whenever burns beat emissions. If Polygon becomes a major payments rail, with fintechs like Revolut moving serious volume, fees go up, burns go up, and supply could finally shrink for real.
The first half of 2026 already proved that burn can beat inflation. The question is whether it can do that every month, not just in the good ones.
And yes, I can feel the hopium kicking in as I write this. Revolut, payments, burns, fintech partners… For a second I’m back in 2022, picturing MATIC at $3 and planning what to do with the profit. Then I look at the chart again, and the hopium wears off faster than a Solana memecoin pump.
Conviction or Hope?
This is the uncomfortable part. When I say “the project is good, so I’ll wait,” I need to be honest about what I’m actually waiting for.
Waiting with conviction means I know what has to happen, and I can check whether it’s happening. Waiting with hope means I’m waiting for the market to love the token again, without a clear reason why it should.
If I’m honest, my POL position has had too much hope and not enough structure. For years, my argument went like this: the tech is good, the team is serious, the project is alive, next cycle will fix it.
Maybe. But that’s not an investment thesis. That’s emotional attachment wearing analytical clothes.
Turning Love Into a Checklist
So from now on, POL earns my patience only if I can tick these boxes:
Burn bigger than emissions, sustained. Not one great month, but most months over a year.Inflation cut or a funded buyback that actually starts, not just a proposal.Payments driving higher fees. Daily chain fees growing meaningfully, not just app revenue.Staying competitive. Tron, Solana, Base, Stripe’s Tempo and Circle’s Arc all want the payments market. If they win it, Polygon’s story doesn’t matter.
And I need a deadline. If the checklist isn’t turning green by the end of 2027, I sell at least half and rotate it into BTC. Not because Polygon is bad, but because a useful network and a rewarding investment are not the same thing.
I’m writing this deadline publicly, so all of Binance Square can hold me to it. Please do. Future me will try to negotiate.
So, Am I Still Blinded by Love?
A little. Probably always will be. It was my first. Somewhere in my portfolio, the 2022 version of me is still waiting for MATIC to hit $3, and I don’t have the heart to tell him.
But there’s a difference between loving a project and being blind to it. Blind love says, “It’s good, so eventually it has to go up.” Honest love says, “It’s good, but I need a measurable reason to believe the token benefits, and a date when I stop waiting.”
My final test is the same question as last time: if I had cash today, would I buy POL at $0.079? For the first time, my answer isn’t an automatic yes or no. It’s: only if the checklist starts turning green.
In my last post, I said that in crypto, hope sometimes goes by another name: hopium. I still believe hope is a beautiful word. Strong, stubborn, resilient. I just don’t want to live on it anymore.
So this time, I gave my hope two things it never had before: a checklist and an expiry date.
That’s not blind love anymore. That’s a relationship with conditions.
What about you? Do you have a “first love” coin you’re still holding? And are you waiting with conviction, or with hope?
Not financial advice. Just my own experience, my own bags and my own mistakes. DYOR. Always DYOR, and then DYOR some more before you yourwallet.
#Polygon #POL #CryptoLesson #Tokenomics #DYOR
94

·
--
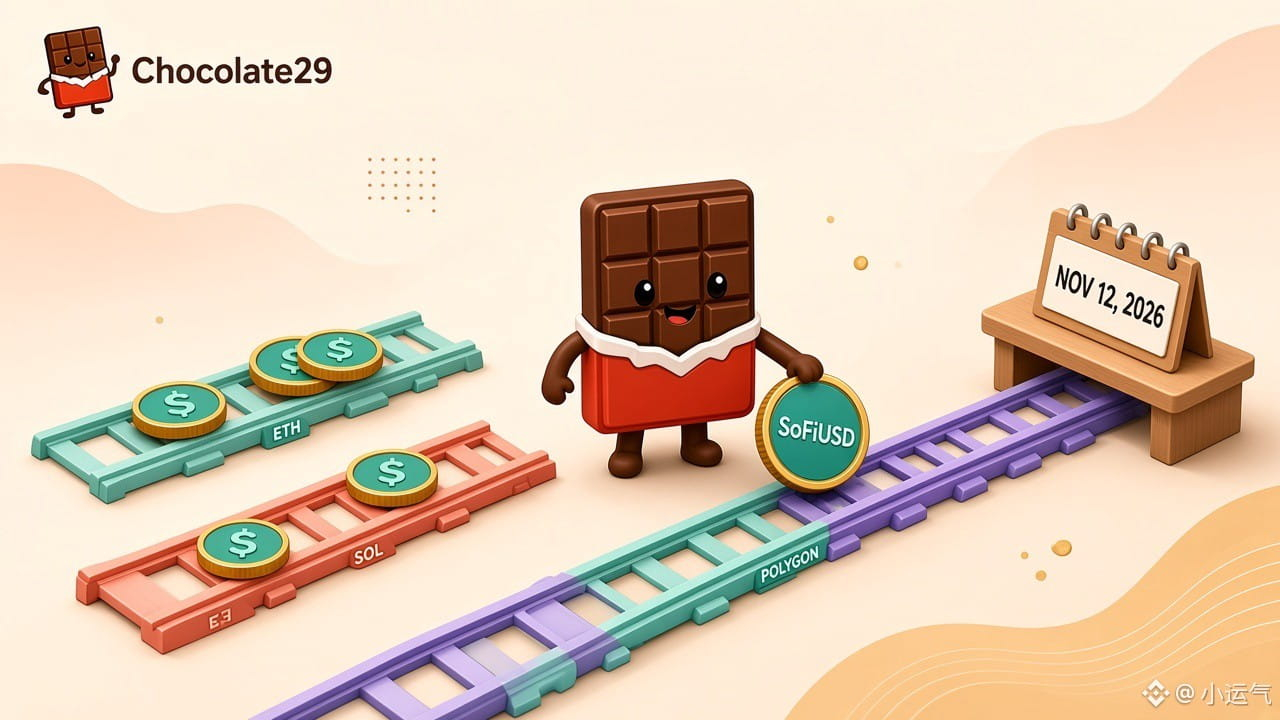
SoFiUSD, the dollar stablecoin issued by SoFi Bank, went live on Polygon on November 12, 2026, its third blockchain after Ethereum and Solana.
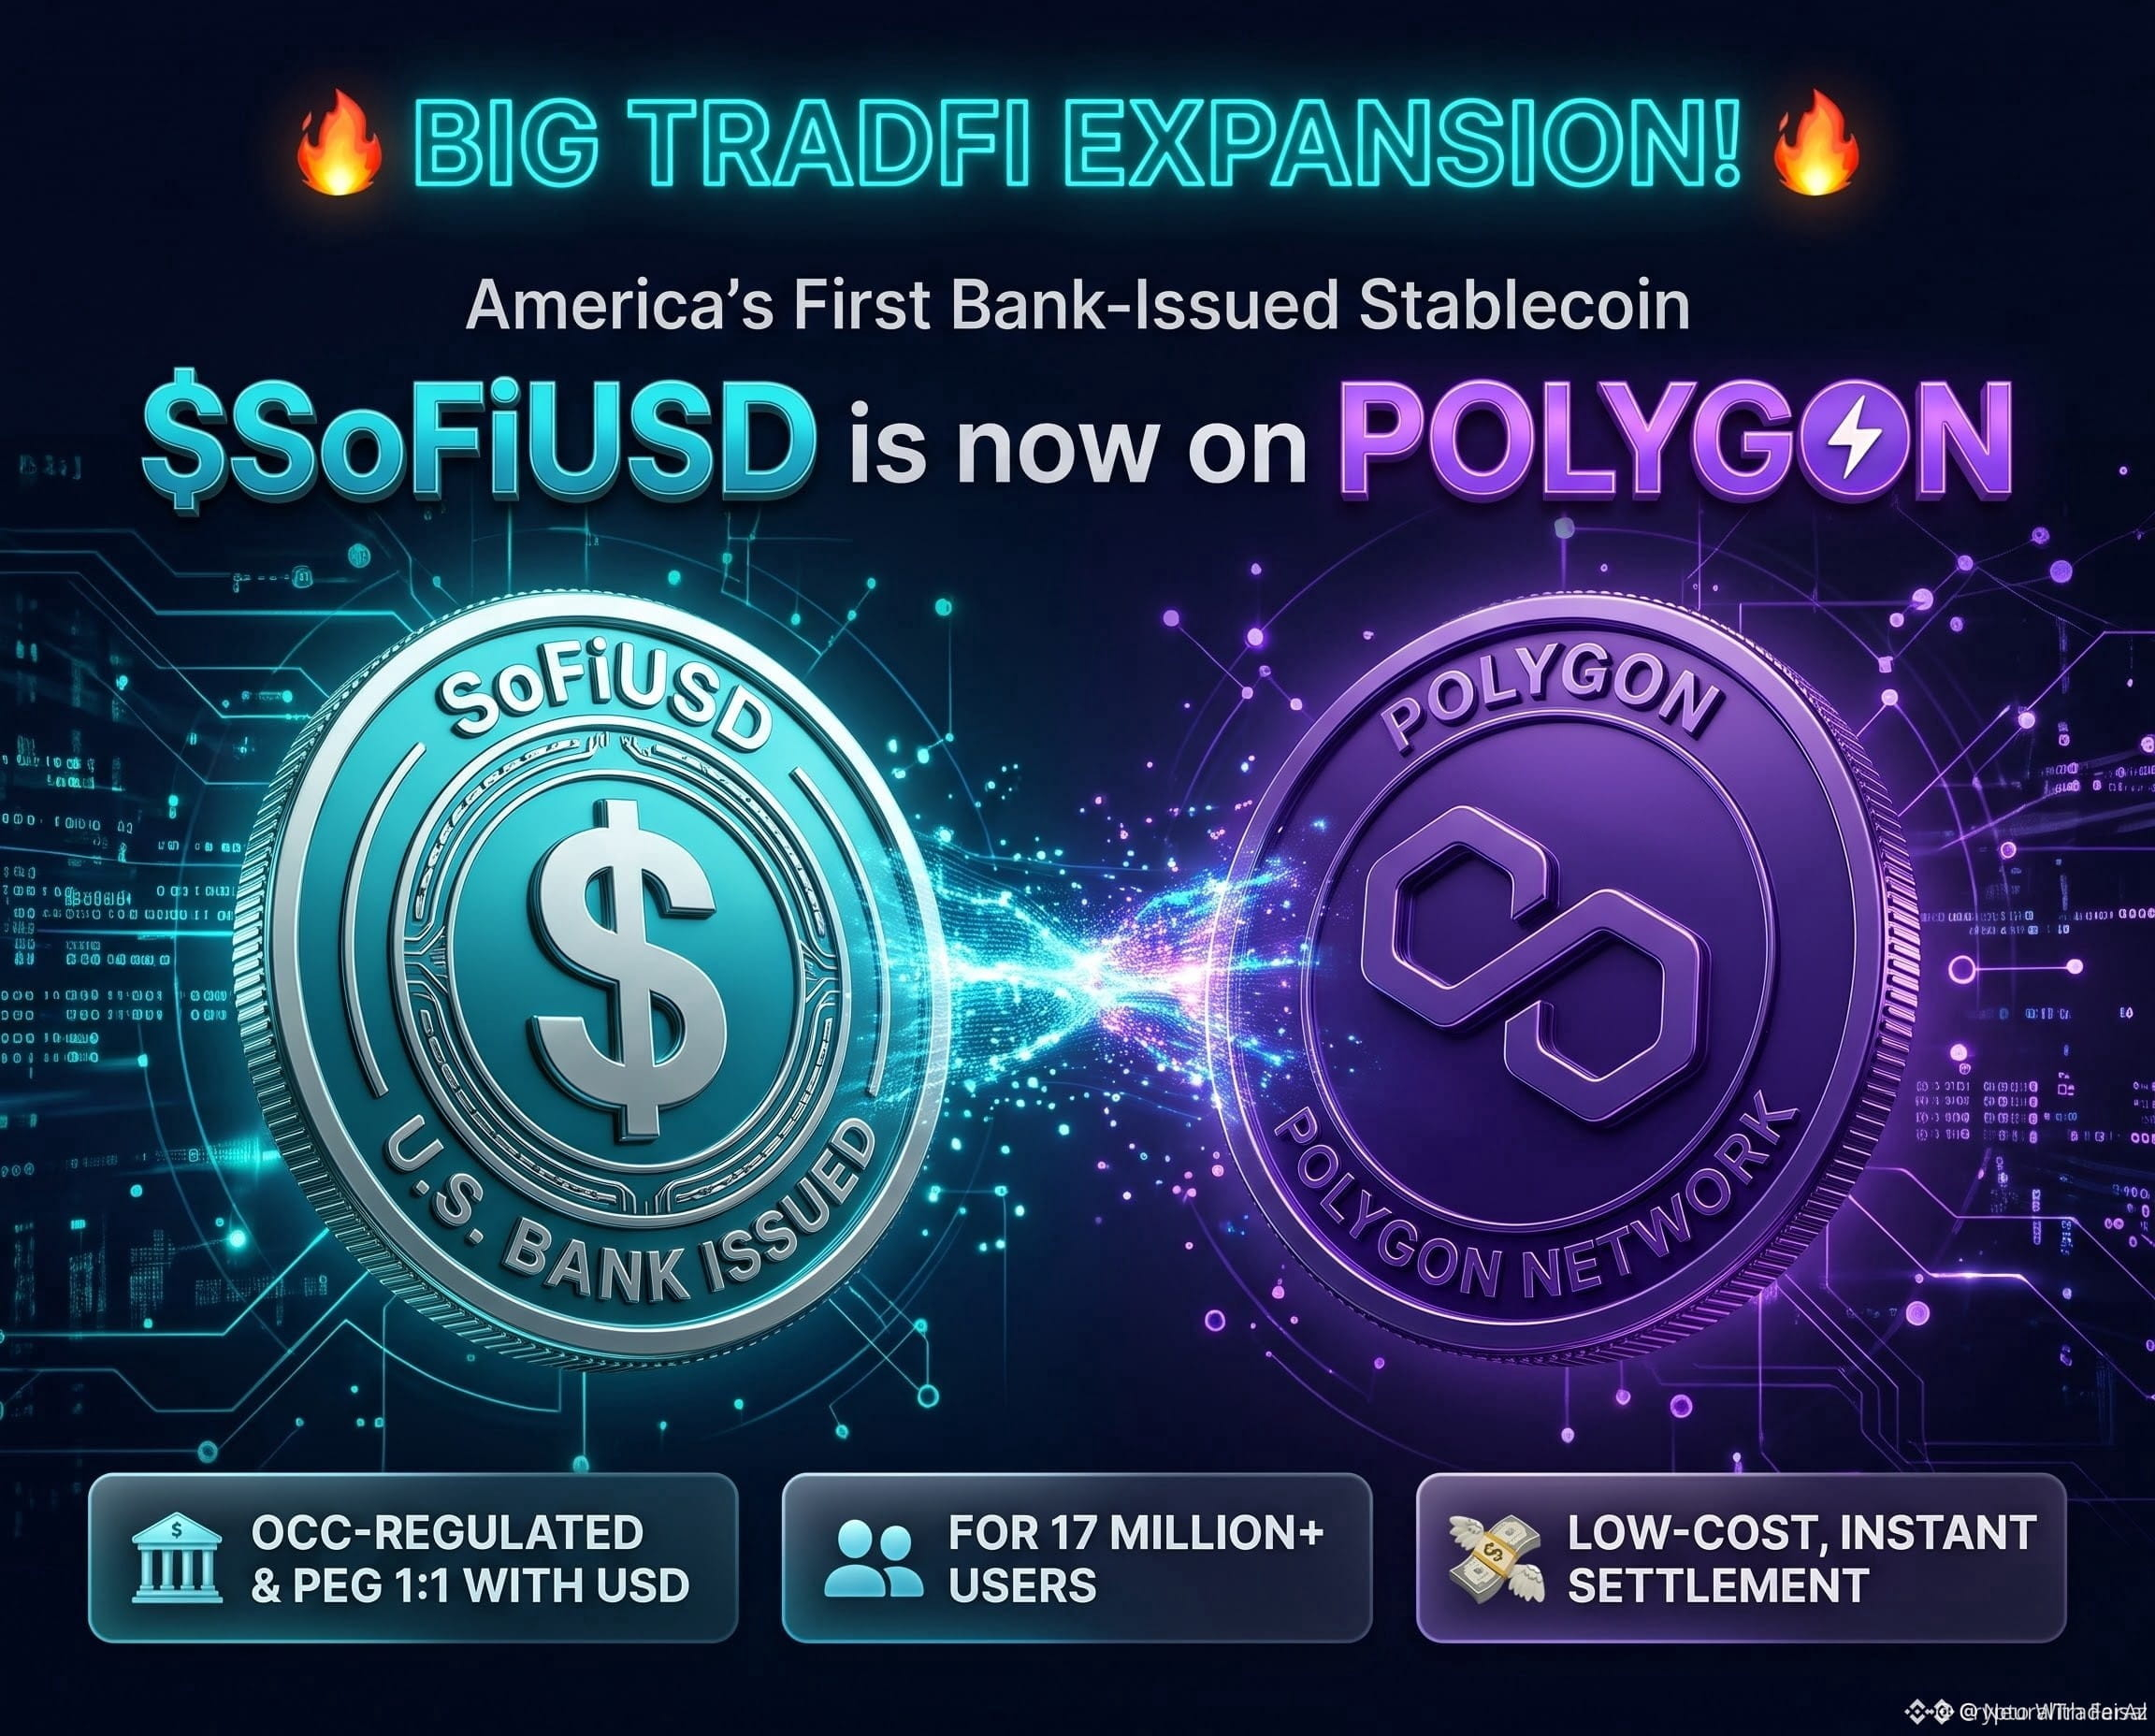
Polygon Labs said SoFi members can buy, sell, hold, and convert SoFiUSD on Polygon inside the SoFi app, with no separate wallet and no manual bridging. SoFi reported 17.1 million members at the end of September 2026. The token is issued by SoFi Bank, N.A., an OCC-regulated U.S. national bank, and is redeemable one-for-one for U.S. dollars. It is a payment stablecoin, not a bank deposit, and is not FDIC- or SIPC-insured.
SoFiUSD joins USDC, USDT, and PayPal's PYUSD on Polygon Open Money Stack, which combines wallets, fiat access, conversion, and cross-chain settlement in one integration. SoFi opened the token to members on Ethereum and Solana in May 2026.
#SoFi #Polygon #Stablecoins
DYOR. Not financial advice.
SoFiUSD, the dollar stablecoin issued by SoFi Bank, went live on Polygon on November 12, 2026, its third blockchain after Ethereum and Solana.
Polygon Labs said SoFi members can buy, sell, hold, and convert SoFiUSD on Polygon inside the SoFi app, with no separate wallet and no manual bridging. SoFi reported 17.1 million members at the end of September 2026. The token is issued by SoFi Bank, N.A., an OCC-regulated U.S. national bank, and is redeemable one-for-one for U.S. dollars. It is a payment stablecoin, not a bank deposit, and is not FDIC- or SIPC-insured.
SoFiUSD joins USDC, USDT, and PayPal's PYUSD on Polygon Open Money Stack, which combines wallets, fiat access, conversion, and cross-chain settlement in one integration. SoFi opened the token to members on Ethereum and Solana in May 2026.
#SoFi #Polygon #Stablecoins
DYOR. Not financial advice.
Polygon Labs said SoFi members can buy, sell, hold, and convert SoFiUSD on Polygon inside the SoFi app, with no separate wallet and no manual bridging. SoFi reported 17.1 million members at the end of September 2026. The token is issued by SoFi Bank, N.A., an OCC-regulated U.S. national bank, and is redeemable one-for-one for U.S. dollars. It is a payment stablecoin, not a bank deposit, and is not FDIC- or SIPC-insured.
SoFiUSD joins USDC, USDT, and PayPal's PYUSD on Polygon Open Money Stack, which combines wallets, fiat access, conversion, and cross-chain settlement in one integration. SoFi opened the token to members on Ethereum and Solana in May 2026.
#SoFi #Polygon #Stablecoins
DYOR. Not financial advice.
33

🦈 $POL NETWORK CAPTURES INSTITUTIONAL ON-RAMP AS SOFI EXPANDS DIGITAL DOLLAR LIQUIDITY 📊
Institutional infrastructure is shifting beneath our feet as a regulated U.S. banking entity bridges its native stablecoin directly into the $POL ecosystem. By eliminating friction for millions of traditional finance users without requiring external custody setups, this integration builds a robust pipeline for organic liquidity absorption. 🌊
When traditional financial architecture merges cleanly with decentralized settlement rails, capital efficiency scales exponentially across networks like $ETH and $SOL as well. Smart money tracks these structural adoption vectors long before retail catches the headline wave. 💡
Are you positioning for a major capital rotation into utility-driven infrastructure assets, or waiting for a structural retest? 💬
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #POL #Polygon #Stablecoins #Crypto
🔥 💎
🦈 $POL NETWORK CAPTURES INSTITUTIONAL ON-RAMP AS SOFI EXPANDS DIGITAL DOLLAR LIQUIDITY 📊
Institutional infrastructure is shifting beneath our feet as a regulated U.S. banking entity bridges its native stablecoin directly into the $POL ecosystem. By eliminating friction for millions of traditional finance users without requiring external custody setups, this integration builds a robust pipeline for organic liquidity absorption. 🌊
When traditional financial architecture merges cleanly with decentralized settlement rails, capital efficiency scales exponentially across networks like $ETH and $SOL as well. Smart money tracks these structural adoption vectors long before retail catches the headline wave. 💡
Are you positioning for a major capital rotation into utility-driven infrastructure assets, or waiting for a structural retest? 💬
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #POL #Polygon #Stablecoins #Crypto
🔥 💎
Institutional infrastructure is shifting beneath our feet as a regulated U.S. banking entity bridges its native stablecoin directly into the $POL ecosystem. By eliminating friction for millions of traditional finance users without requiring external custody setups, this integration builds a robust pipeline for organic liquidity absorption. 🌊
When traditional financial architecture merges cleanly with decentralized settlement rails, capital efficiency scales exponentially across networks like $ETH and $SOL as well. Smart money tracks these structural adoption vectors long before retail catches the headline wave. 💡
Are you positioning for a major capital rotation into utility-driven infrastructure assets, or waiting for a structural retest? 💬
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #POL #Polygon #Stablecoins #Crypto
🔥 💎
26

🚨 INSTITUTIONAL STABLECOIN FLOWS HIT $POL AS TRADITIONAL BANKING BRIDGES ON-CHAIN LIQUIDITY! ⚡
Traditional finance giants are quietly piping millions of retail users straight into networks like $POL and $SOL , blurring the line between legacy deposits and on-chain velocity. 🌊 But seasoned participants know the fine print matters when tokenized money shifts from insured yields to pure payment rails. 💡
True adoption won't be measured by headline expansion numbers or member counts, but by organic settlement volume that proves sustained utility. 📊 Are you tracking actual transaction velocity or just trading the initial network announcement hype? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #POL #Stablecoins #Polygon #DigitalBanking
🔥 💎
🚨 INSTITUTIONAL STABLECOIN FLOWS HIT $POL AS TRADITIONAL BANKING BRIDGES ON-CHAIN LIQUIDITY! ⚡
Traditional finance giants are quietly piping millions of retail users straight into networks like $POL and $SOL , blurring the line between legacy deposits and on-chain velocity. 🌊 But seasoned participants know the fine print matters when tokenized money shifts from insured yields to pure payment rails. 💡
True adoption won't be measured by headline expansion numbers or member counts, but by organic settlement volume that proves sustained utility. 📊 Are you tracking actual transaction velocity or just trading the initial network announcement hype? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #POL #Stablecoins #Polygon #DigitalBanking
🔥 💎
Traditional finance giants are quietly piping millions of retail users straight into networks like $POL and $SOL , blurring the line between legacy deposits and on-chain velocity. 🌊 But seasoned participants know the fine print matters when tokenized money shifts from insured yields to pure payment rails. 💡
True adoption won't be measured by headline expansion numbers or member counts, but by organic settlement volume that proves sustained utility. 📊 Are you tracking actual transaction velocity or just trading the initial network announcement hype? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #POL #Stablecoins #Polygon #DigitalBanking
🔥 💎
28

·
--
Bullish
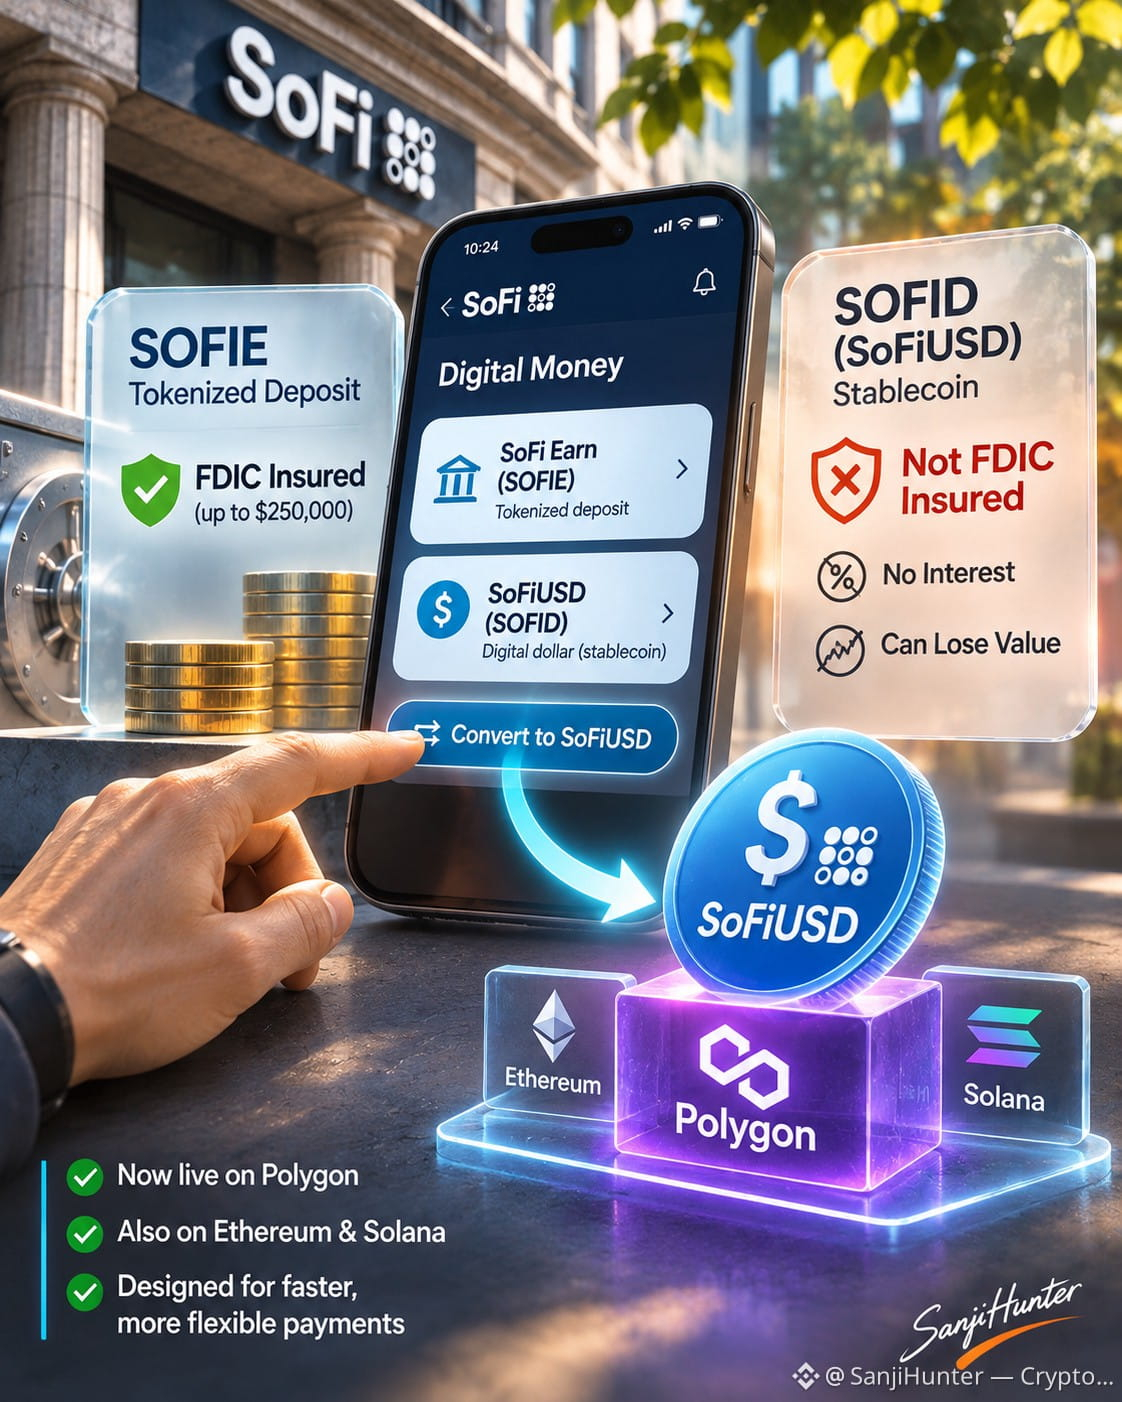
SOFI'S DIGITAL DOLLAR JUST REACHED POLYGON — BUT YOUR BANK PROTECTION DOESN'T FOLLOW
A US national bank is taking its digital dollar deeper into crypto
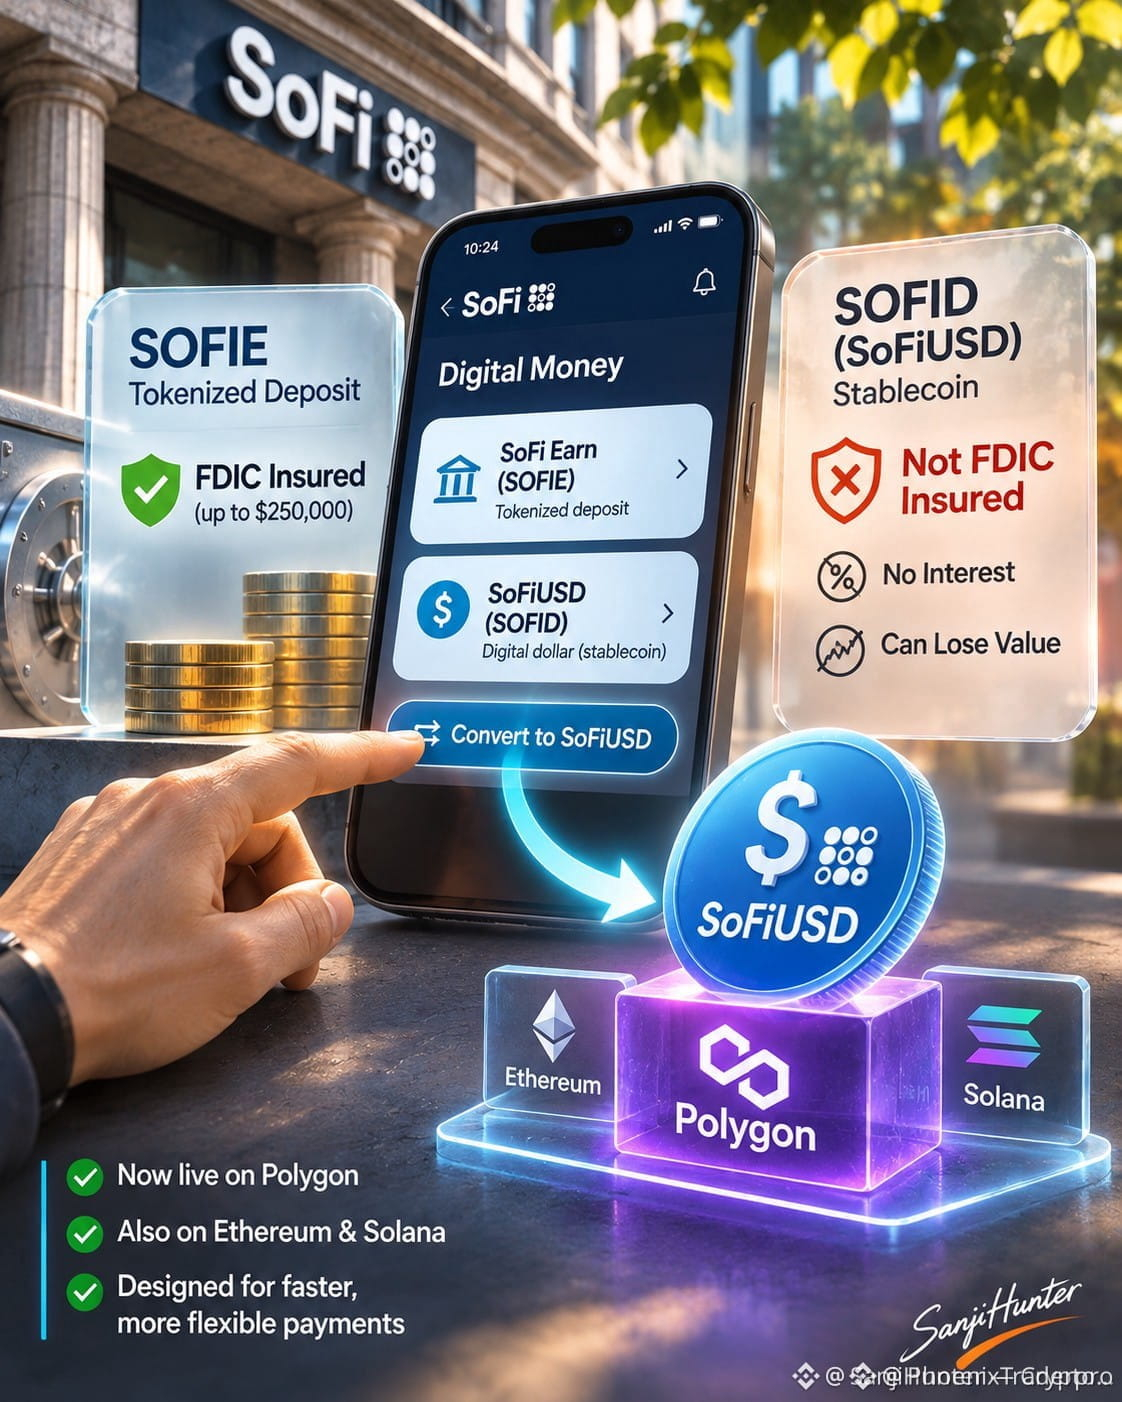
SoFiUSD (SOFID) is now live on Polygon, joining Ethereum and Solana
With more than 17 million SoFi members, the potential distribution is significant — but that doesn't mean 17 million people are using the stablecoin
$POL
{future}(POLUSDT)
🔍 The overlooked detail is what happens when bank money becomes transferable crypto
SoFi Earn (SOFIE) represents a tokenized deposit eligible for FDIC insurance under applicable limits
Convert it into SoFiUSD, and you're holding a payment stablecoin instead
SOFID is designed for 1:1 dollar redemption, but it isn't FDIC insured, doesn't earn interest and can lose value
$SOL
{future}(SOLUSDT)
⚠️ Same dollar denomination, different financial protection
The real opportunity is faster payments and settlement across networks
But adoption won't be proven by the number of supported blockchains or app members
It will be proven by actual payment activity, reliable redemption and sustained usage
Bank-issued crypto is expanding
Understanding what you actually hold matters more than ever
$ETH
{future}(ETHUSDT)
#Stablecoins #Polygon #DigitalBanking
SOFI'S DIGITAL DOLLAR JUST REACHED POLYGON — BUT YOUR BANK PROTECTION DOESN'T FOLLOW
A US national bank is taking its digital dollar deeper into crypto
SoFiUSD (SOFID) is now live on Polygon, joining Ethereum and Solana
With more than 17 million SoFi members, the potential distribution is significant — but that doesn't mean 17 million people are using the stablecoin
$POL
🔍 The overlooked detail is what happens when bank money becomes transferable crypto
SoFi Earn (SOFIE) represents a tokenized deposit eligible for FDIC insurance under applicable limits
Convert it into SoFiUSD, and you're holding a payment stablecoin instead
SOFID is designed for 1:1 dollar redemption, but it isn't FDIC insured, doesn't earn interest and can lose value
$SOL
⚠️ Same dollar denomination, different financial protection
The real opportunity is faster payments and settlement across networks
But adoption won't be proven by the number of supported blockchains or app members
It will be proven by actual payment activity, reliable redemption and sustained usage
Bank-issued crypto is expanding
Understanding what you actually hold matters more than ever
$ETH
#Stablecoins #Polygon #DigitalBanking
A US national bank is taking its digital dollar deeper into crypto
SoFiUSD (SOFID) is now live on Polygon, joining Ethereum and Solana
With more than 17 million SoFi members, the potential distribution is significant — but that doesn't mean 17 million people are using the stablecoin
$POL
🔍 The overlooked detail is what happens when bank money becomes transferable crypto
SoFi Earn (SOFIE) represents a tokenized deposit eligible for FDIC insurance under applicable limits
Convert it into SoFiUSD, and you're holding a payment stablecoin instead
SOFID is designed for 1:1 dollar redemption, but it isn't FDIC insured, doesn't earn interest and can lose value
$SOL
⚠️ Same dollar denomination, different financial protection
The real opportunity is faster payments and settlement across networks
But adoption won't be proven by the number of supported blockchains or app members
It will be proven by actual payment activity, reliable redemption and sustained usage
Bank-issued crypto is expanding
Understanding what you actually hold matters more than ever
$ETH
#Stablecoins #Polygon #DigitalBanking
206

·
--
🦈 $POL ECOSYSTEM CATALYST AS BIG TECH ENTERS THE PREDICTION MARKET ARENA 💥
Smart money tracks institutional footprints long before retail recognizes the structural shift. Meta quietly deploying its Takes prediction market app proves that crowd-sourced forecasting is transitioning from niche protocol experimentation to mainstream corporate infrastructure. 📊
While regulatory friction tests early pioneers like Kalshi and Polymarket in state courts, Big Tech validation acts as a powerful macro liquidity catalyst. This institutional acknowledgment validates decentralized forecasting models, setting the stage for massive order flow redirection across web3 infrastructure. ⚡
💬 How will traditional social giants integrating prediction mechanics impact decentralized oracle demand across the sector? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #POL #PredictionMarkets #Polygon #Crypto
🔥 💎
🦈 $POL ECOSYSTEM CATALYST AS BIG TECH ENTERS THE PREDICTION MARKET ARENA 💥
Smart money tracks institutional footprints long before retail recognizes the structural shift. Meta quietly deploying its Takes prediction market app proves that crowd-sourced forecasting is transitioning from niche protocol experimentation to mainstream corporate infrastructure. 📊
While regulatory friction tests early pioneers like Kalshi and Polymarket in state courts, Big Tech validation acts as a powerful macro liquidity catalyst. This institutional acknowledgment validates decentralized forecasting models, setting the stage for massive order flow redirection across web3 infrastructure. ⚡
💬 How will traditional social giants integrating prediction mechanics impact decentralized oracle demand across the sector? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #POL #PredictionMarkets #Polygon #Crypto
🔥 💎
Smart money tracks institutional footprints long before retail recognizes the structural shift. Meta quietly deploying its Takes prediction market app proves that crowd-sourced forecasting is transitioning from niche protocol experimentation to mainstream corporate infrastructure. 📊
While regulatory friction tests early pioneers like Kalshi and Polymarket in state courts, Big Tech validation acts as a powerful macro liquidity catalyst. This institutional acknowledgment validates decentralized forecasting models, setting the stage for massive order flow redirection across web3 infrastructure. ⚡
💬 How will traditional social giants integrating prediction mechanics impact decentralized oracle demand across the sector? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #POL #PredictionMarkets #Polygon #Crypto
🔥 💎
37
·
--
$POL (POLYGON) ANALYSIS
🔥 Current Price: ~$0.087
$POL is approaching an important technical decision zone. Buyers need to reclaim resistance to confirm a stronger recovery.
{spot}(POLUSDT)
🎯 UPSIDE TARGETS
🟢 Target 1: $0.0906 🟢 Target 2: $0.0933 🟢 Target 3: $0.0968 🟢 Target 4: $0.1004
📌 SUPPORT LEVELS
🔵 S1: $0.0859 🔵 S 2: $0.0824
🔵 Support 3: $0.0746
📈 BULLISH SCENARIO
A confirmed daily close above $0.0906 with strong volume could open the way towards $0.0933 and $0.0968.
A stronger breakout could bring $0.1004 into focus.
📉 BEARISH SCENARIO
If POL loses $0.0859 on a confirmed daily closing basis, further downside towards $0.0824 and $0.0746 becomes possible.
⚡ MY TRADING VIEW
POL needs a confirmed breakout before a bullish reversal can be trusted. Avoid chasing sudden pumps. Watch volume, price action and Bitcoin's direction.
❗Always manage risk and do your own research.
#POL #Polygon #Altcoins
$POL (POLYGON) ANALYSIS
🔥 Current Price: ~$0.087
$POL is approaching an important technical decision zone. Buyers need to reclaim resistance to confirm a stronger recovery.
🎯 UPSIDE TARGETS
🟢 Target 1: $0.0906 🟢 Target 2: $0.0933 🟢 Target 3: $0.0968 🟢 Target 4: $0.1004
📌 SUPPORT LEVELS
🔵 S1: $0.0859 🔵 S 2: $0.0824
🔵 Support 3: $0.0746
📈 BULLISH SCENARIO
A confirmed daily close above $0.0906 with strong volume could open the way towards $0.0933 and $0.0968.
A stronger breakout could bring $0.1004 into focus.
📉 BEARISH SCENARIO
If POL loses $0.0859 on a confirmed daily closing basis, further downside towards $0.0824 and $0.0746 becomes possible.
⚡ MY TRADING VIEW
POL needs a confirmed breakout before a bullish reversal can be trusted. Avoid chasing sudden pumps. Watch volume, price action and Bitcoin's direction.
❗Always manage risk and do your own research.
#POL #Polygon #Altcoins
🔥 Current Price: ~$0.087
$POL is approaching an important technical decision zone. Buyers need to reclaim resistance to confirm a stronger recovery.
🎯 UPSIDE TARGETS
🟢 Target 1: $0.0906 🟢 Target 2: $0.0933 🟢 Target 3: $0.0968 🟢 Target 4: $0.1004
📌 SUPPORT LEVELS
🔵 S1: $0.0859 🔵 S 2: $0.0824
🔵 Support 3: $0.0746
📈 BULLISH SCENARIO
A confirmed daily close above $0.0906 with strong volume could open the way towards $0.0933 and $0.0968.
A stronger breakout could bring $0.1004 into focus.
📉 BEARISH SCENARIO
If POL loses $0.0859 on a confirmed daily closing basis, further downside towards $0.0824 and $0.0746 becomes possible.
⚡ MY TRADING VIEW
POL needs a confirmed breakout before a bullish reversal can be trusted. Avoid chasing sudden pumps. Watch volume, price action and Bitcoin's direction.
❗Always manage risk and do your own research.
#POL #Polygon #Altcoins
352
·
--
Bullish
Polygon continues to strengthen its blockchain ecosystem through innovation, scalability, and expanding Web3 adoption.
For investors who believe in the future of blockchain technology, $POL could be an interesting asset to watch and consider for long-term accumulation.
Market volatility creates both opportunities and risks. Smart research, patience, and disciplined entry decisions remain essential.
Stay focused on the long-term vision. Keep learning, watch market conditions, and make informed investment decisions. #Polygon #pol #Web3 #crptonews
{spot}(POLUSDT)
Polygon continues to strengthen its blockchain ecosystem through innovation, scalability, and expanding Web3 adoption.
For investors who believe in the future of blockchain technology, $POL could be an interesting asset to watch and consider for long-term accumulation.
Market volatility creates both opportunities and risks. Smart research, patience, and disciplined entry decisions remain essential.
Stay focused on the long-term vision. Keep learning, watch market conditions, and make informed investment decisions. #Polygon #pol #Web3 #crptonews
For investors who believe in the future of blockchain technology, $POL could be an interesting asset to watch and consider for long-term accumulation.
Market volatility creates both opportunities and risks. Smart research, patience, and disciplined entry decisions remain essential.
Stay focused on the long-term vision. Keep learning, watch market conditions, and make informed investment decisions. #Polygon #pol #Web3 #crptonews
1
432

·
--
#SoFiExpandsSoFiUSDStablecoinToPolygon
🏦 A US Bank's Dollar Token Just Got Its Third Chain
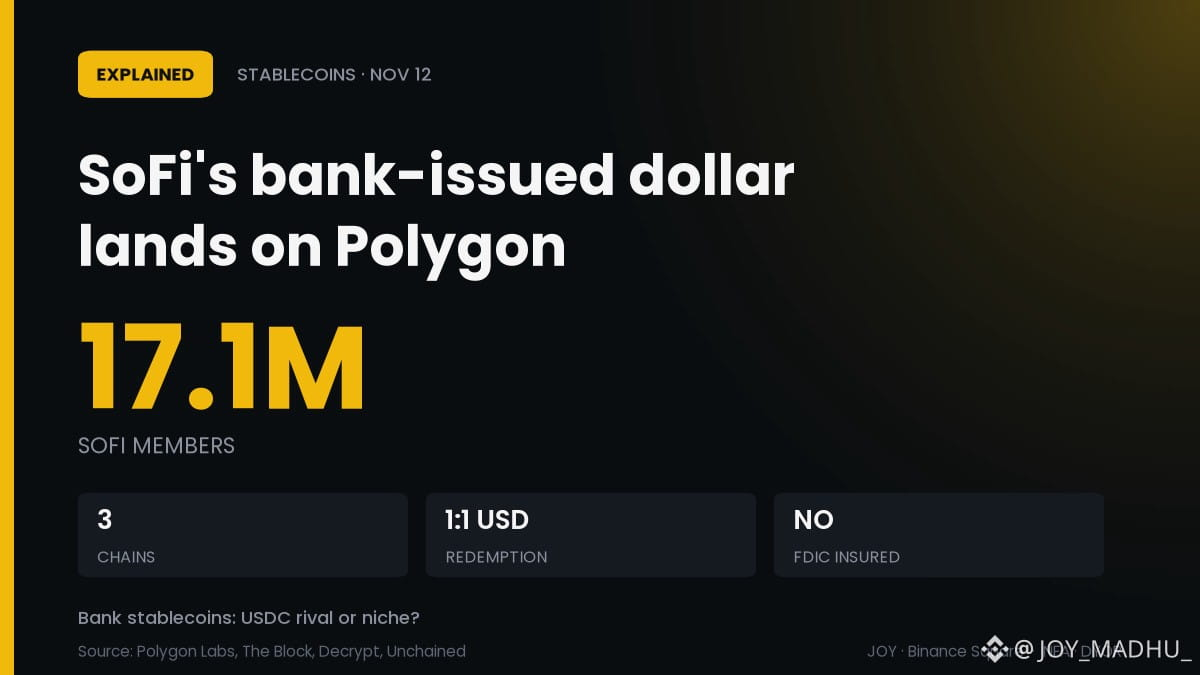
SoFiUSD, the first stablecoin from a US national bank, went live on Polygon on Nov 12.
📊 SoFi members: 17.1M at end of September
🏦 Issuer: SoFi Bank, OCC-regulated, redeemable 1:1 for USD
📈 Chains: Ethereum, Solana, now Polygon
⚠️ Not FDIC or SIPC insured; joins USDC, USDT, PYUSD
The catch: holding it on-chain gives no direct right to redeem; only approved customers can.
Will bank stablecoins grab 10%+ of stablecoin payments by end of 2027, or stay niche? 👇
$POL
#SoFiExpandsSoFiUSDStablecoinToPolygon #Stablecoins #Polygon
#SoFiExpandsSoFiUSDStablecoinToPolygon
🏦 A US Bank's Dollar Token Just Got Its Third Chain
SoFiUSD, the first stablecoin from a US national bank, went live on Polygon on Nov 12.
📊 SoFi members: 17.1M at end of September
🏦 Issuer: SoFi Bank, OCC-regulated, redeemable 1:1 for USD
📈 Chains: Ethereum, Solana, now Polygon
⚠️ Not FDIC or SIPC insured; joins USDC, USDT, PYUSD
The catch: holding it on-chain gives no direct right to redeem; only approved customers can.
Will bank stablecoins grab 10%+ of stablecoin payments by end of 2027, or stay niche? 👇
$POL
#SoFiExpandsSoFiUSDStablecoinToPolygon #Stablecoins #Polygon
🏦 A US Bank's Dollar Token Just Got Its Third Chain
SoFiUSD, the first stablecoin from a US national bank, went live on Polygon on Nov 12.
📊 SoFi members: 17.1M at end of September
🏦 Issuer: SoFi Bank, OCC-regulated, redeemable 1:1 for USD
📈 Chains: Ethereum, Solana, now Polygon
⚠️ Not FDIC or SIPC insured; joins USDC, USDT, PYUSD
The catch: holding it on-chain gives no direct right to redeem; only approved customers can.
Will bank stablecoins grab 10%+ of stablecoin payments by end of 2027, or stay niche? 👇
$POL
#SoFiExpandsSoFiUSDStablecoinToPolygon #Stablecoins #Polygon
63
·
--
Verified
$POL Is Getting a Real-World Stable coin Use Case 👀
Polygon’s POL token is back in focus after SoFiUSD, a bank-issued stable coin, was integrated with Polygon.
The interesting part isn't just the announcement — it's whether this integration leads to meaningful payment activity and network usage.
Will real-world stable coin adoption become a stronger driver for $POL?
Worth watching the adoption data, trading volume, and price reaction before making any decision.
#POL #Polygon #Stablecoins #cryptotrading
{spot}(POLUSDT)
$POL Is Getting a Real-World Stable coin Use Case 👀
Polygon’s POL token is back in focus after SoFiUSD, a bank-issued stable coin, was integrated with Polygon.
The interesting part isn't just the announcement — it's whether this integration leads to meaningful payment activity and network usage.
Will real-world stable coin adoption become a stronger driver for $POL ?
Worth watching the adoption data, trading volume, and price reaction before making any decision.
#POL #Polygon #Stablecoins #cryptotrading
Polygon’s POL token is back in focus after SoFiUSD, a bank-issued stable coin, was integrated with Polygon.
The interesting part isn't just the announcement — it's whether this integration leads to meaningful payment activity and network usage.
Will real-world stable coin adoption become a stronger driver for $POL ?
Worth watching the adoption data, trading volume, and price reaction before making any decision.
#POL #Polygon #Stablecoins #cryptotrading
2
649
·
--
One green name in a sea of red — $POL is up 1.3% near $0.087 while $BTC bleeds 6.8% to $68.5K. No headline, just relative strength: it leads L2s today. Hold $0.084 and buyers stay in charge; lose it and the flush catches up. Buying the odd one out, or waiting? #Polygon #CryptoMarket #Write2Earn
One green name in a sea of red — $POL is up 1.3% near $0.087 while $BTC bleeds 6.8% to $68.5K. No headline, just relative strength: it leads L2s today. Hold $0.084 and buyers stay in charge; lose it and the flush catches up. Buying the odd one out, or waiting? #Polygon #CryptoMarket #Write2Earn
9
·
--
Verified
#sofiexpandssofiusdstablecointopolygon
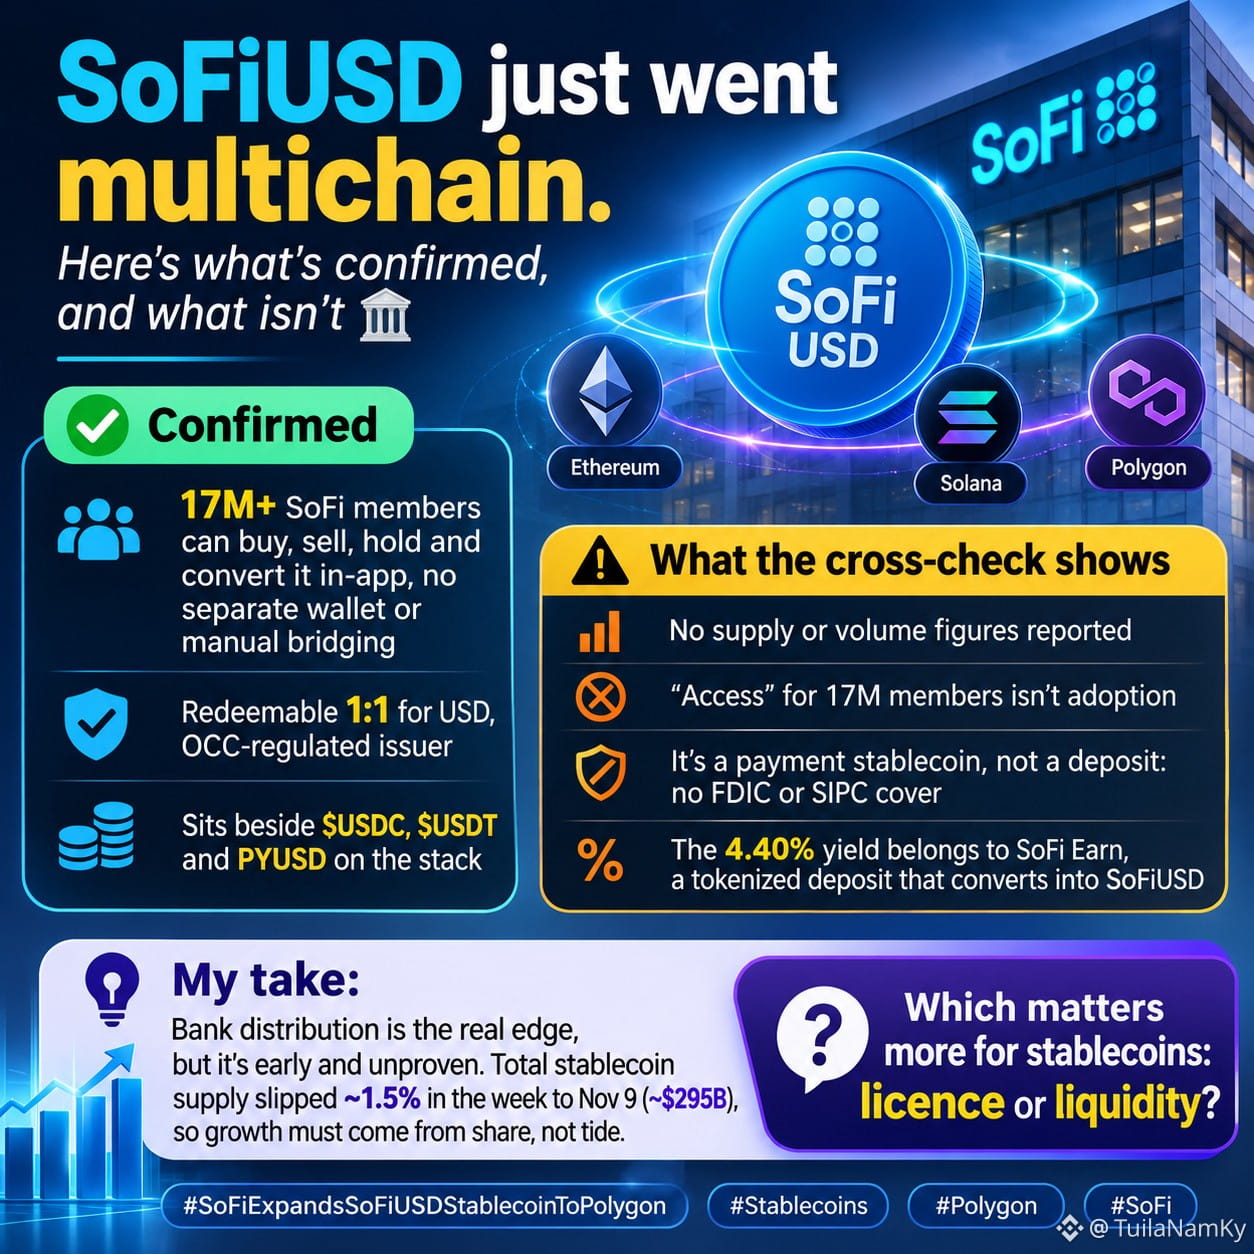
SoFiUSD just went multichain. Here's what's confirmed, and what isn't 🏦
On Nov 12, Polygon Labs ($POL) said SoFiUSD, issued by SoFi Bank, N.A., is live on its Open Money Stack, joining Ethereum and Solana.
✅ Confirmed
• 17M+ SoFi members can buy, sell, hold and convert it in-app, no separate wallet or manual bridging
• Redeemable 1:1 for USD, OCC-regulated issuer
• Sits beside $USDC, USDT and PYUSD on the stack
⚠️ What the cross-check shows
• No supply or volume figures reported
• "Access" for 17M members isn't adoption
• It's a payment stablecoin, not a deposit: no FDIC or SIPC cover
• The 4.40% yield belongs to SoFi Earn, a tokenized deposit that converts into SoFiUSD
🧠 My take: bank distribution is the real edge, but it's early and unproven. Total stablecoin supply slipped ~1.5% in the week to Nov 9 (~$295B), so growth must come from share, not tide.
Which matters more for stablecoins: licence or liquidity?
#Stablecoins #Polygon #SoFi
$POL
{future}(POLUSDT)
$USDC
{future}(USDCUSDT)
$USDT
#sofiexpandssofiusdstablecointopolygon
SoFiUSD just went multichain. Here's what's confirmed, and what isn't 🏦
On Nov 12, Polygon Labs ($POL ) said SoFiUSD, issued by SoFi Bank, N.A., is live on its Open Money Stack, joining Ethereum and Solana.
✅ Confirmed
• 17M+ SoFi members can buy, sell, hold and convert it in-app, no separate wallet or manual bridging
• Redeemable 1:1 for USD, OCC-regulated issuer
• Sits beside $USDC , USDT and PYUSD on the stack
⚠️ What the cross-check shows
• No supply or volume figures reported
• "Access" for 17M members isn't adoption
• It's a payment stablecoin, not a deposit: no FDIC or SIPC cover
• The 4.40% yield belongs to SoFi Earn, a tokenized deposit that converts into SoFiUSD
🧠 My take: bank distribution is the real edge, but it's early and unproven. Total stablecoin supply slipped ~1.5% in the week to Nov 9 (~$295B), so growth must come from share, not tide.
Which matters more for stablecoins: licence or liquidity?
#Stablecoins #Polygon #SoFi
$POL
$USDC
$USDT
SoFiUSD just went multichain. Here's what's confirmed, and what isn't 🏦
On Nov 12, Polygon Labs ($POL ) said SoFiUSD, issued by SoFi Bank, N.A., is live on its Open Money Stack, joining Ethereum and Solana.
✅ Confirmed
• 17M+ SoFi members can buy, sell, hold and convert it in-app, no separate wallet or manual bridging
• Redeemable 1:1 for USD, OCC-regulated issuer
• Sits beside $USDC , USDT and PYUSD on the stack
⚠️ What the cross-check shows
• No supply or volume figures reported
• "Access" for 17M members isn't adoption
• It's a payment stablecoin, not a deposit: no FDIC or SIPC cover
• The 4.40% yield belongs to SoFi Earn, a tokenized deposit that converts into SoFiUSD
🧠 My take: bank distribution is the real edge, but it's early and unproven. Total stablecoin supply slipped ~1.5% in the week to Nov 9 (~$295B), so growth must come from share, not tide.
Which matters more for stablecoins: licence or liquidity?
#Stablecoins #Polygon #SoFi
$POL
$USDC
$USDT
1
846
🚨 17 MILLION TRADFI USERS JUST LANDED ON $POL WITHOUT A SINGLE WALLET FRICTION! ⚡
When an OCC-regulated national bank plugs seventeen million retail accounts directly into a blockchain network, the plumbing of finance officially shifts. 🌊 This bypasses every traditional onboarding hurdle by integrating digital dollars straight into user apps with zero external wallet friction.
Smart money tracks where real-world utility meets institutional validation, and this Open Money Stack integration proves scalability is winning the race. 📊 Watch how liquidity flows as traditional banking giants race to capture on-chain yield without the technical roadblocks.
💬 Are legacy banking stablecoins about to get completely outpaced by regulated network integrations? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #POL #Polygon #Stablecoins #Crypto
🔥 💎
🚨 17 MILLION TRADFI USERS JUST LANDED ON $POL WITHOUT A SINGLE WALLET FRICTION! ⚡
When an OCC-regulated national bank plugs seventeen million retail accounts directly into a blockchain network, the plumbing of finance officially shifts. 🌊 This bypasses every traditional onboarding hurdle by integrating digital dollars straight into user apps with zero external wallet friction.
Smart money tracks where real-world utility meets institutional validation, and this Open Money Stack integration proves scalability is winning the race. 📊 Watch how liquidity flows as traditional banking giants race to capture on-chain yield without the technical roadblocks.
💬 Are legacy banking stablecoins about to get completely outpaced by regulated network integrations? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #POL #Polygon #Stablecoins #Crypto
🔥 💎
When an OCC-regulated national bank plugs seventeen million retail accounts directly into a blockchain network, the plumbing of finance officially shifts. 🌊 This bypasses every traditional onboarding hurdle by integrating digital dollars straight into user apps with zero external wallet friction.
Smart money tracks where real-world utility meets institutional validation, and this Open Money Stack integration proves scalability is winning the race. 📊 Watch how liquidity flows as traditional banking giants race to capture on-chain yield without the technical roadblocks.
💬 Are legacy banking stablecoins about to get completely outpaced by regulated network integrations? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #POL #Polygon #Stablecoins #Crypto
🔥 💎
7

Verified
🚨 TRADFI MEETS DEFI: The Stablecoin Wars Just Leveled Up! 🚨
As a trader watching the bridge between traditional banking and Web3, this is the exact adoption catalyst we’ve been waiting for. SoFi—an OCC-regulated U.S. national bank—just expanded its SoFiUSD stablecoin to the Polygon network.
Here’s the pure alpha on why this is a massive shift:
🔥 Retail Reach: Over 17 MILLION SoFi app users can now hold, trade, and settle digital dollars directly on Polygon. The best part? Zero external crypto wallets are required.
🔥 Seamless Tech: It leverages the Polygon Open Money Stack for lightning-fast, low-cost cross-chain payment settlement.
🔥 Regulated & Pegged: Issued directly by a national U.S. bank and redeemable 1:1 for USD.
🔥 Ecosystem Growth: Already live on ETH and SOL, adding Polygon highlights the heavy institutional demand for scalable, low-fee payment rails.
This isn’t just another token launch. It’s a regulated TradFi giant validating Polygon’s infrastructure for everyday retail payments. When onboarding friction drops to zero for 17M users, liquidity typically follows.
Will we see a massive capital rotation into POL, or will other national banks rush to build their own stablecoins to compete? Drop your targets below! 👇📊
$POL
{future}(POLUSDT)
$ETH
{future}(ETHUSDT)
$SOL
{future}(SOLUSDT)
#sofiexpandssofiusdstablecointopolygon #Polygon #POL #Stablecoins
🚨 TRADFI MEETS DEFI: The Stablecoin Wars Just Leveled Up! 🚨
As a trader watching the bridge between traditional banking and Web3, this is the exact adoption catalyst we’ve been waiting for. SoFi—an OCC-regulated U.S. national bank—just expanded its SoFiUSD stablecoin to the Polygon network.
Here’s the pure alpha on why this is a massive shift:
🔥 Retail Reach: Over 17 MILLION SoFi app users can now hold, trade, and settle digital dollars directly on Polygon. The best part? Zero external crypto wallets are required.
🔥 Seamless Tech: It leverages the Polygon Open Money Stack for lightning-fast, low-cost cross-chain payment settlement.
🔥 Regulated & Pegged: Issued directly by a national U.S. bank and redeemable 1:1 for USD.
🔥 Ecosystem Growth: Already live on ETH and SOL, adding Polygon highlights the heavy institutional demand for scalable, low-fee payment rails.
This isn’t just another token launch. It’s a regulated TradFi giant validating Polygon’s infrastructure for everyday retail payments. When onboarding friction drops to zero for 17M users, liquidity typically follows.
Will we see a massive capital rotation into POL, or will other national banks rush to build their own stablecoins to compete? Drop your targets below! 👇📊
$POL
$ETH
$SOL
#sofiexpandssofiusdstablecointopolygon #Polygon #POL #Stablecoins
As a trader watching the bridge between traditional banking and Web3, this is the exact adoption catalyst we’ve been waiting for. SoFi—an OCC-regulated U.S. national bank—just expanded its SoFiUSD stablecoin to the Polygon network.
Here’s the pure alpha on why this is a massive shift:
🔥 Retail Reach: Over 17 MILLION SoFi app users can now hold, trade, and settle digital dollars directly on Polygon. The best part? Zero external crypto wallets are required.
🔥 Seamless Tech: It leverages the Polygon Open Money Stack for lightning-fast, low-cost cross-chain payment settlement.
🔥 Regulated & Pegged: Issued directly by a national U.S. bank and redeemable 1:1 for USD.
🔥 Ecosystem Growth: Already live on ETH and SOL, adding Polygon highlights the heavy institutional demand for scalable, low-fee payment rails.
This isn’t just another token launch. It’s a regulated TradFi giant validating Polygon’s infrastructure for everyday retail payments. When onboarding friction drops to zero for 17M users, liquidity typically follows.
Will we see a massive capital rotation into POL, or will other national banks rush to build their own stablecoins to compete? Drop your targets below! 👇📊
$POL
$ETH
$SOL
#sofiexpandssofiusdstablecointopolygon #Polygon #POL #Stablecoins
1
935
·
--
What a Crisis Reveals About a Network.
Strong networks are not defined by how they perform on quiet days. They are defined by how they respond when something goes wrong. In the Polygon case, block producers first blocked the affected addresses, and only afterward did the community consider a deeper fix. This sequence shows how quickly a coordinated validator set can act when it needs to.
At the same time, the episode raises fair questions. How much coordination is too much, and who decides when an exception is justified? The proposal itself describes the action as extreme and limits it to a short list of addresses, which suggests the community is aware of the precedent.
Because of this, long-term investors can learn a useful habit: study how a project behaves under pressure, not only how it markets itself. Over time, a transparent response to a crisis builds more trust than any roadmap graphic.
Build your portfolio on knowledge, patience, and a proven strategy. If you want to be part of that journey, join my copy trading account here: [https://www.binance.com/en/copy-trading/lead-details/5293024773212277505?timeRange=365D](https://www.binance.com/en/copy-trading/lead-details/5293024773212277505?timeRange=365D)
$POL $ETH
#Polygon #Layer2 #CryptoResearch #BinanceSquare #LongTermInvesting
What a Crisis Reveals About a Network.
Strong networks are not defined by how they perform on quiet days. They are defined by how they respond when something goes wrong. In the Polygon case, block producers first blocked the affected addresses, and only afterward did the community consider a deeper fix. This sequence shows how quickly a coordinated validator set can act when it needs to.
At the same time, the episode raises fair questions. How much coordination is too much, and who decides when an exception is justified? The proposal itself describes the action as extreme and limits it to a short list of addresses, which suggests the community is aware of the precedent.
Because of this, long-term investors can learn a useful habit: study how a project behaves under pressure, not only how it markets itself. Over time, a transparent response to a crisis builds more trust than any roadmap graphic.
Build your portfolio on knowledge, patience, and a proven strategy. If you want to be part of that journey, join my copy trading account here: https://www.binance.com/en/copy-trading/lead-details/5293024773212277505?timeRange=365D
$POL $ETH
#Polygon #Layer2 #CryptoResearch #BinanceSquare #LongTermInvesting
Strong networks are not defined by how they perform on quiet days. They are defined by how they respond when something goes wrong. In the Polygon case, block producers first blocked the affected addresses, and only afterward did the community consider a deeper fix. This sequence shows how quickly a coordinated validator set can act when it needs to.
At the same time, the episode raises fair questions. How much coordination is too much, and who decides when an exception is justified? The proposal itself describes the action as extreme and limits it to a short list of addresses, which suggests the community is aware of the precedent.
Because of this, long-term investors can learn a useful habit: study how a project behaves under pressure, not only how it markets itself. Over time, a transparent response to a crisis builds more trust than any roadmap graphic.
Build your portfolio on knowledge, patience, and a proven strategy. If you want to be part of that journey, join my copy trading account here: https://www.binance.com/en/copy-trading/lead-details/5293024773212277505?timeRange=365D
$POL $ETH
#Polygon #Layer2 #CryptoResearch #BinanceSquare #LongTermInvesting
My Spot Portfolio
0 / 300
Minimum 10USDT
Public
7D PNL
(USDT)
-39.91
7D ROI
-7.16%
AUM
$517.65
Win Rate
18.75%
92
·
--
Article
A bank has issued its own stablecoin: SoFiUSD is on Polygon. I looked past the headline and focused on these three lines of fine printYesterday I saw a post that kept me thinking for a while: Polygon announced on November 12 that SoFiUSD had launched on Polygon, making it the third chain after Ethereum and Solana. Polygon said it was the first stablecoin issued by a U.S. national bank.
First, let’s be clear about what this coin is, so the words “issued by a bank” don’t give the wrong impression. The issuer is SoFi Bank, N.A., a national bank regulated by the U.S. Office of the Comptroller of the Currency (OCC). Each SoFiUSD can be redeemed for U.S. dollars at a 1:1 rate through SoFi Bank. SoFi has more than 17 million members, who can buy, sell, hold, and exchange it directly in the app—without setting up a separate wallet or manually bridging it across chains.
A bank has issued its own stablecoin: SoFiUSD is on Polygon. I looked past the headline and focused on these three lines of fine print
Yesterday I saw a post that kept me thinking for a while: Polygon announced on November 12 that SoFiUSD had launched on Polygon, making it the third chain after Ethereum and Solana. Polygon said it was the first stablecoin issued by a U.S. national bank.
First, let’s be clear about what this coin is, so the words “issued by a bank” don’t give the wrong impression. The issuer is SoFi Bank, N.A., a national bank regulated by the U.S. Office of the Comptroller of the Currency (OCC). Each SoFiUSD can be redeemed for U.S. dollars at a 1:1 rate through SoFi Bank. SoFi has more than 17 million members, who can buy, sell, hold, and exchange it directly in the app—without setting up a separate wallet or manually bridging it across chains.
First, let’s be clear about what this coin is, so the words “issued by a bank” don’t give the wrong impression. The issuer is SoFi Bank, N.A., a national bank regulated by the U.S. Office of the Comptroller of the Currency (OCC). Each SoFiUSD can be redeemed for U.S. dollars at a 1:1 rate through SoFi Bank. SoFi has more than 17 million members, who can buy, sell, hold, and exchange it directly in the app—without setting up a separate wallet or manually bridging it across chains.
312
🚀 160% APY on Polygon?! DeFi Yield Hunters, Take Notice!
Polygon (@0xPolygon) is attracting attention with some eye-catching DeFi yields.
According to @ElanInsights' Income Dashboard, after filtering Polygon yield pools with more than $1M in TVL and ranking them by APY, one opportunity stood out.
🔥 Uniswap v4's USDC-ATH pool is offering a staggering 160.10% APY, backed by approximately $1.24M in TVL at the time of writing.
That's a serious yield opportunity worth watching.
Could $POL be emerging as a new destination for serious DeFi capital and yield farmers?
One thing is certain: Polygon's DeFi ecosystem deserves a closer look. 👀
Explore the dashboard: bscnhive.com/income-nov-twe…
#Polygon #DeFi #Uniswap #Crypto
{future}(POLUSDT)
🚀 160% APY on Polygon?! DeFi Yield Hunters, Take Notice!
Polygon (@0xPolygon) is attracting attention with some eye-catching DeFi yields.
According to @ElanInsights' Income Dashboard, after filtering Polygon yield pools with more than $1M in TVL and ranking them by APY, one opportunity stood out.
🔥 Uniswap v4's USDC-ATH pool is offering a staggering 160.10% APY, backed by approximately $1.24M in TVL at the time of writing.
That's a serious yield opportunity worth watching.
Could $POL be emerging as a new destination for serious DeFi capital and yield farmers?
One thing is certain: Polygon's DeFi ecosystem deserves a closer look. 👀
Explore the dashboard: bscnhive.com/income-nov-twe…
#Polygon #DeFi #Uniswap #Crypto
Polygon (@0xPolygon) is attracting attention with some eye-catching DeFi yields.
According to @ElanInsights' Income Dashboard, after filtering Polygon yield pools with more than $1M in TVL and ranking them by APY, one opportunity stood out.
🔥 Uniswap v4's USDC-ATH pool is offering a staggering 160.10% APY, backed by approximately $1.24M in TVL at the time of writing.
That's a serious yield opportunity worth watching.
Could $POL be emerging as a new destination for serious DeFi capital and yield farmers?
One thing is certain: Polygon's DeFi ecosystem deserves a closer look. 👀
Explore the dashboard: bscnhive.com/income-nov-twe…
#Polygon #DeFi #Uniswap #Crypto
213

POL spot check 📉
Polygon's POL is trading around $0.086, down ~1.5-2% in the last 24h. The slide continues — down ~10% this week and ~12% over the last month, with a market cap near $928M (rank #76).
Key levels to watch:
• Support: $0.0859 (today's low), then $0.085
• Resistance: $0.0902 (today's high), then $0.092
Polygon still powers one of the biggest L2 ecosystems (TVL ~$630M), but POL is stuck under $0.09 while the wider market bleeds. A daily close back above $0.09 would be the first sign buyers are stepping in. Until then, the trend stays weak.
$BTC is holding ~$73.5K with spot ETF outflows now 5 days straight — risk-off mood across the board.
Not financial advice. DYOR.
#Polygon #Crypto #Altcoins
POL spot check 📉
Polygon's POL is trading around $0.086, down ~1.5-2% in the last 24h. The slide continues — down ~10% this week and ~12% over the last month, with a market cap near $928M (rank #76).
Key levels to watch:
• Support: $0.0859 (today's low), then $0.085
• Resistance: $0.0902 (today's high), then $0.092
Polygon still powers one of the biggest L2 ecosystems (TVL ~$630M), but POL is stuck under $0.09 while the wider market bleeds. A daily close back above $0.09 would be the first sign buyers are stepping in. Until then, the trend stays weak.
$BTC is holding ~$73.5K with spot ETF outflows now 5 days straight — risk-off mood across the board.
Not financial advice. DYOR.
#Polygon #Crypto #Altcoins
Polygon's POL is trading around $0.086, down ~1.5-2% in the last 24h. The slide continues — down ~10% this week and ~12% over the last month, with a market cap near $928M (rank #76).
Key levels to watch:
• Support: $0.0859 (today's low), then $0.085
• Resistance: $0.0902 (today's high), then $0.092
Polygon still powers one of the biggest L2 ecosystems (TVL ~$630M), but POL is stuck under $0.09 while the wider market bleeds. A daily close back above $0.09 would be the first sign buyers are stepping in. Until then, the trend stays weak.
$BTC is holding ~$73.5K with spot ETF outflows now 5 days straight — risk-off mood across the board.
Not financial advice. DYOR.
#Polygon #Crypto #Altcoins
65
·
--
Bearish
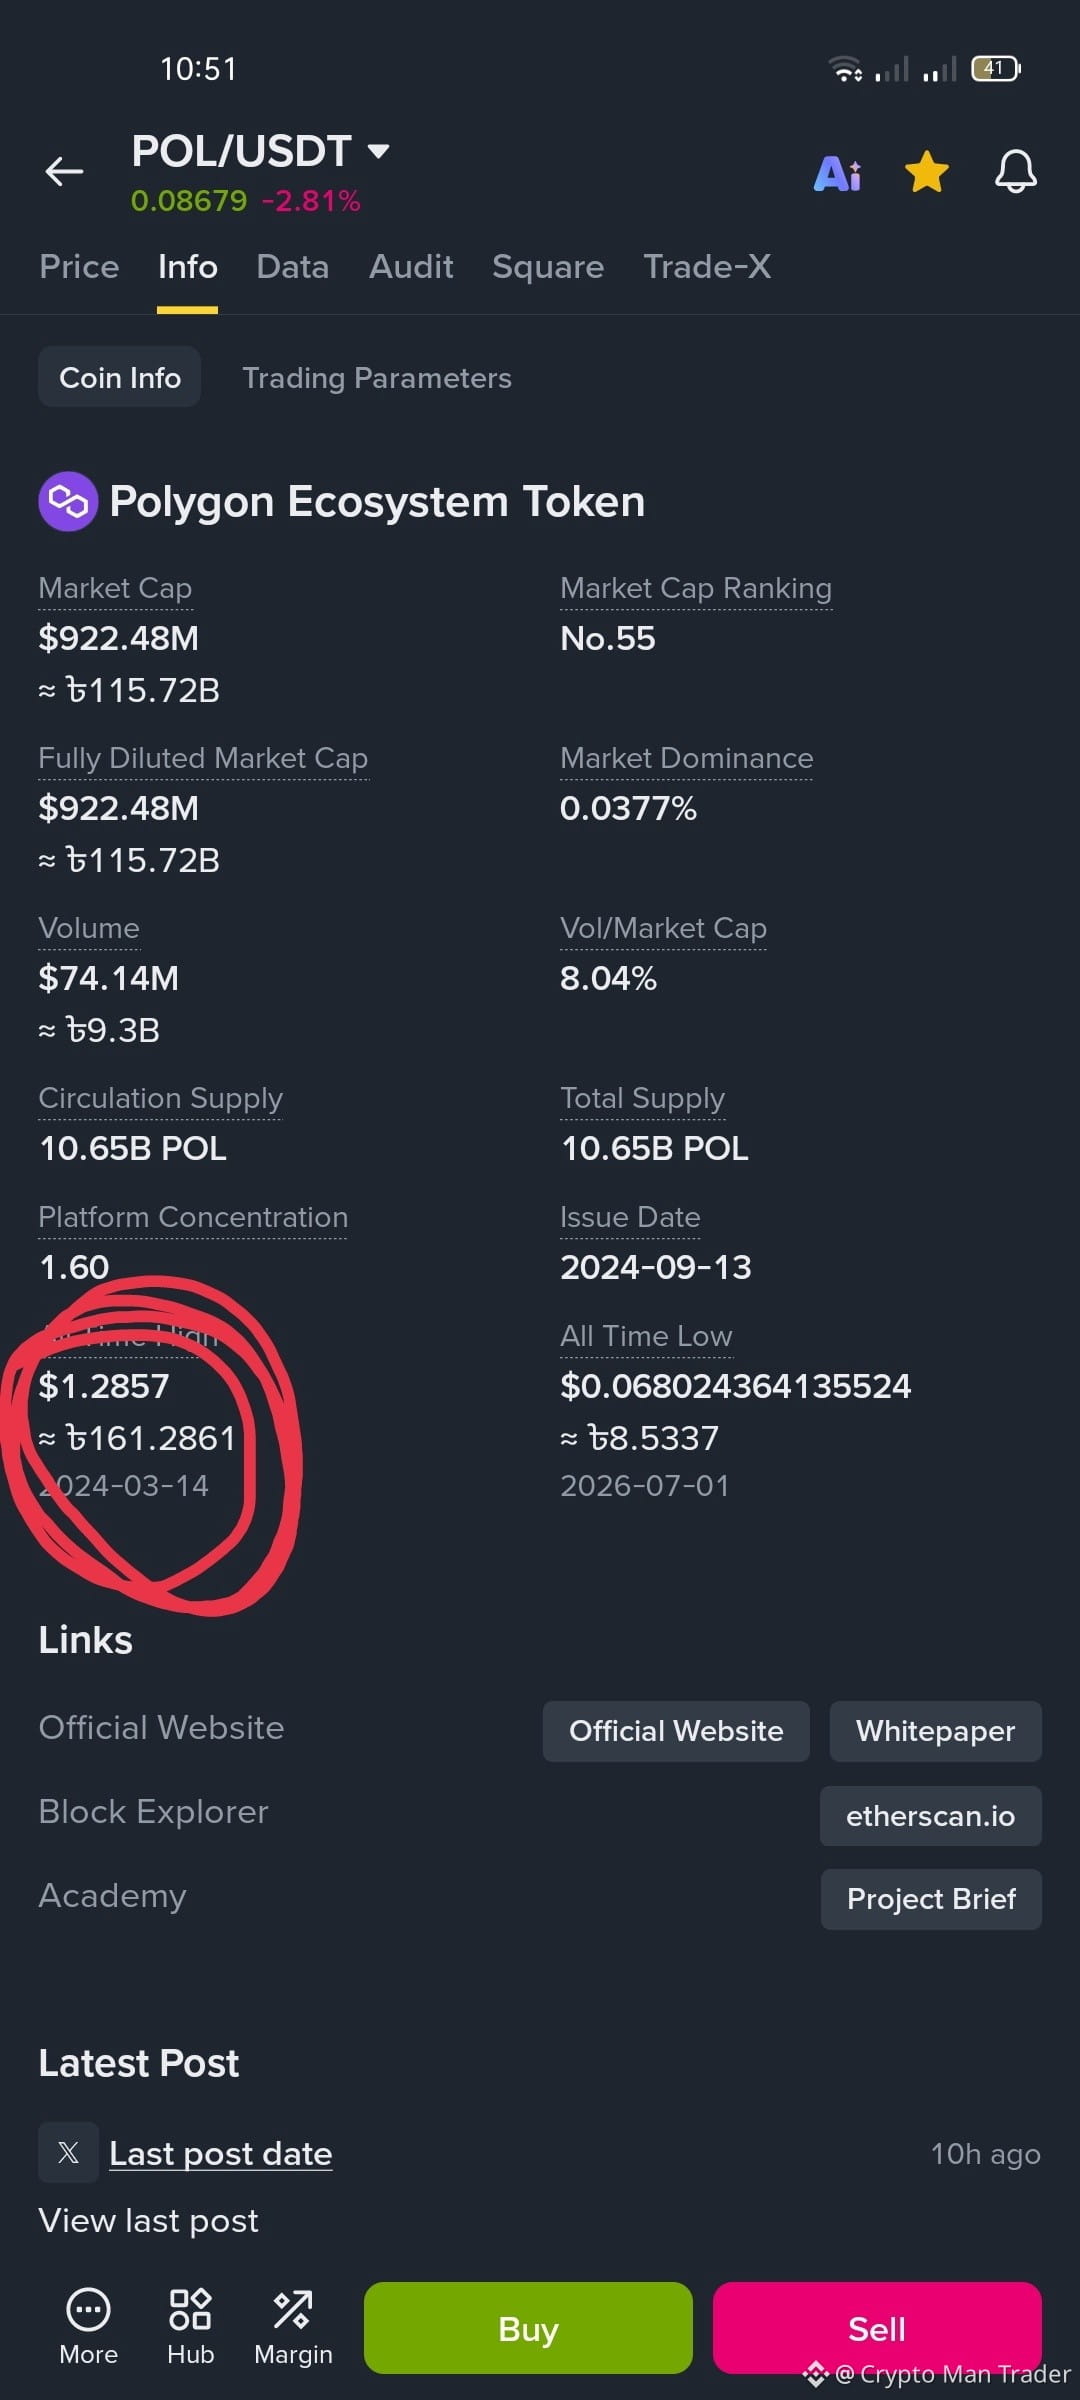
🚀 CAN $POL
{spot}(POLUSDT)
HIT $1 USDT BY THE END OF 2026? 👀🔥
Imagine seeing $POL (Polygon) back at $1! 🤯
Could 2026 become the year of a major POL comeback?
📈 Bulls are watching for strong momentum. 🐂 Growing adoption could bring renewed attention. 🔥 A broader crypto bull run may support a recovery.
🎯 2026 DREAM TARGET: $1 USDT
Is $1 possible for $POL, or is this target too ambitious?
💬 POL HOLDERS, ARE YOU STILL BULLISH?
Comment your prediction below! 👇
#POL #Polygon #Crypto #Binance #Altcoins #2026Prediction
🚀 CAN $POL
HIT $1 USDT BY THE END OF 2026? 👀🔥
Imagine seeing $POL (Polygon) back at $1! 🤯
Could 2026 become the year of a major POL comeback?
📈 Bulls are watching for strong momentum. 🐂 Growing adoption could bring renewed attention. 🔥 A broader crypto bull run may support a recovery.
🎯 2026 DREAM TARGET: $1 USDT
Is $1 possible for $POL , or is this target too ambitious?
💬 POL HOLDERS, ARE YOU STILL BULLISH?
Comment your prediction below! 👇
#POL #Polygon #Crypto #Binance #Altcoins #2026Prediction
HIT $1 USDT BY THE END OF 2026? 👀🔥
Imagine seeing $POL (Polygon) back at $1! 🤯
Could 2026 become the year of a major POL comeback?
📈 Bulls are watching for strong momentum. 🐂 Growing adoption could bring renewed attention. 🔥 A broader crypto bull run may support a recovery.
🎯 2026 DREAM TARGET: $1 USDT
Is $1 possible for $POL , or is this target too ambitious?
💬 POL HOLDERS, ARE YOU STILL BULLISH?
Comment your prediction below! 👇
#POL #Polygon #Crypto #Binance #Altcoins #2026Prediction
78
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#A Packed Week of Earnings and Data Tests Markets
40,720 views
296 Discussing
2
#AnthropicIPOTestsInvestorAppetiteForAI
52,157 views
933 Discussing
3
#BitcoinExtendsLosingStreakToSixWeeks
14,387 views
302 Discussing
4
#XRPFallsTo$0.89LowestSinceNovember2024
4,342 views
33 Discussing
5
#HuangReportedlyConsidersReturnToNvidia
76,471 views
962 Discussing
6
#SP500AndNasdaqFuturesHitQuarterlyLows
3,716 views
86 Discussing
7
#CaliforniaVotersBackProp42BarringNewCryptoTaxes
3,869 views
94 Discussing
8
#HKPlansDigitalAssetRegulatoryBillByYearEnd
3,607 views
80 Discussing
9
#MUFGSMFGMizuhoPlanYenBackedStablecoin
14,495 views
186 Discussing
10
#HKMAAndSwiftExploreTokenizedDepositInteroperability
696 views
14 Discussing