
#applereportsmixedresults
applereportsmixedresults
119,400 views
1,040 Discussing
Hot
Latest


·
--
Article
Apple Margins Tighten as Memory Costs Bite, Overshadowing an Upbeat Holiday ForecastApple shares fell about 3% in extended trading on Monday after the company paired better-than-expected fiscal fourth-quarter results with a disappointing margin forecast, warning that surging memory chip prices and the cost of running its new AI tools would squeeze profitability into the holiday season.
Revenue for the quarter ended September 26 rose 12% year over year to $114.5 billion, topping analysts' expectations of roughly $113.4 billion. Earnings per share came in at $2.10, ahead of the $1.99 consensus. Gross margin reached 47.9%, slightly above estimates.
The results marked Apple's first earnings report under new Chief Executive Officer John Ternus, who succeeded Tim Cook on September 1. They also exposed a growing divide within the business: a resilient iPhone and a surprisingly strong Mac contrasted with softer iPad, China and wearables sales, while a looming margin squeeze raised questions about whether rising prices can keep Apple's profit machine running at historic rates.
iPhone and Mac Carry the Quarter
The iPhone, Apple's biggest moneymaker, remained strong, with revenue climbing 17% to $57.6 billion and beating the $56.5 billion analysts had expected. The company managed that despite a reshuffled launch calendar: Apple released only the iPhone 18 Pro line in September, delaying the regular iPhone 18 and new iPhone Air to the first half of 2027, while the foldable iPhone Duo did not reach store shelves until October 23 — well into the current quarter.
Mac revenue was the standout, surging 24% to $10.8 billion and smashing the $9.6 billion consensus by roughly $1 billion. A wave of new products — a touch-screen MacBook Pro, a refreshed iMac and a new low-end MacBook Pro — ship on November 6, with a MacBook Neo and MacBook Air expected early next year to keep momentum going.
Services, which includes the App Store, iCloud, Apple Pay and Apple TV, rose 9.8% to $31.6 billion, in line with estimates. Net income was $30.7 billion.
iPad, China and Wearables Disappoint
Not every segment kept pace. iPad revenue came in at $6.23 billion, missing the $6.9 billion estimate, though a new iPad mini is launching this quarter and an iPad Air, low-end tablet and iPad Pro refresh are due next year. The wearables, home and accessories category brought in $8.3 billion, down 7.9% year over year and short of the $9 billion forecast, as the quarter's AirPods 5 and new smartwatches were only minor updates.
Sales in greater China rose about 20% to $17.5 billion, but still fell more than $1 billion short of estimates near $18.9 billion. Chief Financial Officer Kevan Parekh blamed supply-chain constraints that limited Apple's ability to deliver products to meet demand. Even so, Counterpoint Research found Apple grew its smartphone market share from 18% to 22% during a quarter in which global shipments shrank 20% amid the component crunch.
Memory Crunch and AI Costs Threaten Margins
The biggest concern for investors was the outlook. Apple guided to revenue growth of 7% to 10% in the December quarter, beating the 6.1% Wall Street expected, but projected gross margin of just 45% to 46%, below the roughly 47% analysts modeled and down from above 50% in the June quarter.
Ternus pointed to an "unprecedented" rise in memory chip prices as the data-center building boom hoovers up supply, compounded by the expense of powering Apple's new "Siri AI" assistant. The company had raised prices across its device lineup in late June — including a $100 increase on iPhones — to help offset higher component costs, and said tariff refunds added 5 cents to earnings per share. But with stockpiles of cheaper components dwindling, both Ternus and Parekh warned margins would keep sliding.
The pressure arrives alongside lofty investor expectations. A recent rally — fueled by Apple's reputation as a haven from the AI spending frenzy gripping rivals like Google, Amazon and Nvidia — added roughly $1 trillion in market value and pushed Apple briefly above a $5 trillion valuation. Yet analysts note the stock trades at about 36 times next year's expected earnings even as profit is seen growing just 1%, while the once-reliable services engine slows under regulatory pressure on App Store fees.
For Apple, the foldable iPhone Duo and a refreshed Mac lineup offer bright spots heading into the holidays, with Ternus declaring the company had capped off its "best fiscal year ever." But investors will be watching whether higher prices and new products can offset tightening margins — and whether Apple can finally accelerate an innovation engine that has lagged in AI.
Apple Margins Tighten as Memory Costs Bite, Overshadowing an Upbeat Holiday Forecast
Apple shares fell about 3% in extended trading on Monday after the company paired better-than-expected fiscal fourth-quarter results with a disappointing margin forecast, warning that surging memory chip prices and the cost of running its new AI tools would squeeze profitability into the holiday season.
Revenue for the quarter ended September 26 rose 12% year over year to $114.5 billion, topping analysts' expectations of roughly $113.4 billion. Earnings per share came in at $2.10, ahead of the $1.99 consensus. Gross margin reached 47.9%, slightly above estimates.
The results marked Apple's first earnings report under new Chief Executive Officer John Ternus, who succeeded Tim Cook on September 1. They also exposed a growing divide within the business: a resilient iPhone and a surprisingly strong Mac contrasted with softer iPad, China and wearables sales, while a looming margin squeeze raised questions about whether rising prices can keep Apple's profit machine running at historic rates.
iPhone and Mac Carry the Quarter
The iPhone, Apple's biggest moneymaker, remained strong, with revenue climbing 17% to $57.6 billion and beating the $56.5 billion analysts had expected. The company managed that despite a reshuffled launch calendar: Apple released only the iPhone 18 Pro line in September, delaying the regular iPhone 18 and new iPhone Air to the first half of 2027, while the foldable iPhone Duo did not reach store shelves until October 23 — well into the current quarter.
Mac revenue was the standout, surging 24% to $10.8 billion and smashing the $9.6 billion consensus by roughly $1 billion. A wave of new products — a touch-screen MacBook Pro, a refreshed iMac and a new low-end MacBook Pro — ship on November 6, with a MacBook Neo and MacBook Air expected early next year to keep momentum going.
Services, which includes the App Store, iCloud, Apple Pay and Apple TV, rose 9.8% to $31.6 billion, in line with estimates. Net income was $30.7 billion.
iPad, China and Wearables Disappoint
Not every segment kept pace. iPad revenue came in at $6.23 billion, missing the $6.9 billion estimate, though a new iPad mini is launching this quarter and an iPad Air, low-end tablet and iPad Pro refresh are due next year. The wearables, home and accessories category brought in $8.3 billion, down 7.9% year over year and short of the $9 billion forecast, as the quarter's AirPods 5 and new smartwatches were only minor updates.
Sales in greater China rose about 20% to $17.5 billion, but still fell more than $1 billion short of estimates near $18.9 billion. Chief Financial Officer Kevan Parekh blamed supply-chain constraints that limited Apple's ability to deliver products to meet demand. Even so, Counterpoint Research found Apple grew its smartphone market share from 18% to 22% during a quarter in which global shipments shrank 20% amid the component crunch.
Memory Crunch and AI Costs Threaten Margins
The biggest concern for investors was the outlook. Apple guided to revenue growth of 7% to 10% in the December quarter, beating the 6.1% Wall Street expected, but projected gross margin of just 45% to 46%, below the roughly 47% analysts modeled and down from above 50% in the June quarter.
Ternus pointed to an "unprecedented" rise in memory chip prices as the data-center building boom hoovers up supply, compounded by the expense of powering Apple's new "Siri AI" assistant. The company had raised prices across its device lineup in late June — including a $100 increase on iPhones — to help offset higher component costs, and said tariff refunds added 5 cents to earnings per share. But with stockpiles of cheaper components dwindling, both Ternus and Parekh warned margins would keep sliding.
The pressure arrives alongside lofty investor expectations. A recent rally — fueled by Apple's reputation as a haven from the AI spending frenzy gripping rivals like Google, Amazon and Nvidia — added roughly $1 trillion in market value and pushed Apple briefly above a $5 trillion valuation. Yet analysts note the stock trades at about 36 times next year's expected earnings even as profit is seen growing just 1%, while the once-reliable services engine slows under regulatory pressure on App Store fees.
For Apple, the foldable iPhone Duo and a refreshed Mac lineup offer bright spots heading into the holidays, with Ternus declaring the company had capped off its "best fiscal year ever." But investors will be watching whether higher prices and new products can offset tightening margins — and whether Apple can finally accelerate an innovation engine that has lagged in AI.
Revenue for the quarter ended September 26 rose 12% year over year to $114.5 billion, topping analysts' expectations of roughly $113.4 billion. Earnings per share came in at $2.10, ahead of the $1.99 consensus. Gross margin reached 47.9%, slightly above estimates.
The results marked Apple's first earnings report under new Chief Executive Officer John Ternus, who succeeded Tim Cook on September 1. They also exposed a growing divide within the business: a resilient iPhone and a surprisingly strong Mac contrasted with softer iPad, China and wearables sales, while a looming margin squeeze raised questions about whether rising prices can keep Apple's profit machine running at historic rates.
iPhone and Mac Carry the Quarter
The iPhone, Apple's biggest moneymaker, remained strong, with revenue climbing 17% to $57.6 billion and beating the $56.5 billion analysts had expected. The company managed that despite a reshuffled launch calendar: Apple released only the iPhone 18 Pro line in September, delaying the regular iPhone 18 and new iPhone Air to the first half of 2027, while the foldable iPhone Duo did not reach store shelves until October 23 — well into the current quarter.
Mac revenue was the standout, surging 24% to $10.8 billion and smashing the $9.6 billion consensus by roughly $1 billion. A wave of new products — a touch-screen MacBook Pro, a refreshed iMac and a new low-end MacBook Pro — ship on November 6, with a MacBook Neo and MacBook Air expected early next year to keep momentum going.
Services, which includes the App Store, iCloud, Apple Pay and Apple TV, rose 9.8% to $31.6 billion, in line with estimates. Net income was $30.7 billion.
iPad, China and Wearables Disappoint
Not every segment kept pace. iPad revenue came in at $6.23 billion, missing the $6.9 billion estimate, though a new iPad mini is launching this quarter and an iPad Air, low-end tablet and iPad Pro refresh are due next year. The wearables, home and accessories category brought in $8.3 billion, down 7.9% year over year and short of the $9 billion forecast, as the quarter's AirPods 5 and new smartwatches were only minor updates.
Sales in greater China rose about 20% to $17.5 billion, but still fell more than $1 billion short of estimates near $18.9 billion. Chief Financial Officer Kevan Parekh blamed supply-chain constraints that limited Apple's ability to deliver products to meet demand. Even so, Counterpoint Research found Apple grew its smartphone market share from 18% to 22% during a quarter in which global shipments shrank 20% amid the component crunch.
Memory Crunch and AI Costs Threaten Margins
The biggest concern for investors was the outlook. Apple guided to revenue growth of 7% to 10% in the December quarter, beating the 6.1% Wall Street expected, but projected gross margin of just 45% to 46%, below the roughly 47% analysts modeled and down from above 50% in the June quarter.
Ternus pointed to an "unprecedented" rise in memory chip prices as the data-center building boom hoovers up supply, compounded by the expense of powering Apple's new "Siri AI" assistant. The company had raised prices across its device lineup in late June — including a $100 increase on iPhones — to help offset higher component costs, and said tariff refunds added 5 cents to earnings per share. But with stockpiles of cheaper components dwindling, both Ternus and Parekh warned margins would keep sliding.
The pressure arrives alongside lofty investor expectations. A recent rally — fueled by Apple's reputation as a haven from the AI spending frenzy gripping rivals like Google, Amazon and Nvidia — added roughly $1 trillion in market value and pushed Apple briefly above a $5 trillion valuation. Yet analysts note the stock trades at about 36 times next year's expected earnings even as profit is seen growing just 1%, while the once-reliable services engine slows under regulatory pressure on App Store fees.
For Apple, the foldable iPhone Duo and a refreshed Mac lineup offer bright spots heading into the holidays, with Ternus declaring the company had capped off its "best fiscal year ever." But investors will be watching whether higher prices and new products can offset tightening margins — and whether Apple can finally accelerate an innovation engine that has lagged in AI.
RTSAO:
A good quarter and a cautious outlook can both be true. Strong sales are encouraging, but the next test is whether margins can hold as memory costs rise.
3
1
1.6k
·
--
Article
#. 🚨 Apple Reports Mixed Results: Beat on Numbers, Pressure on Margins 🍎📊#USOctoberNFP-AreRateCutsStillPossible
Apple's latest quarterly report delivered a familiar Wall Street puzzle: **strong numbers, but a nervous market.** 😬 The company beat revenue and earnings expectations, yet investors focused on rising costs, profit margins, and what comes next. 👀
## 📊 The Key Highlights
According to the post, here is what Apple reported:
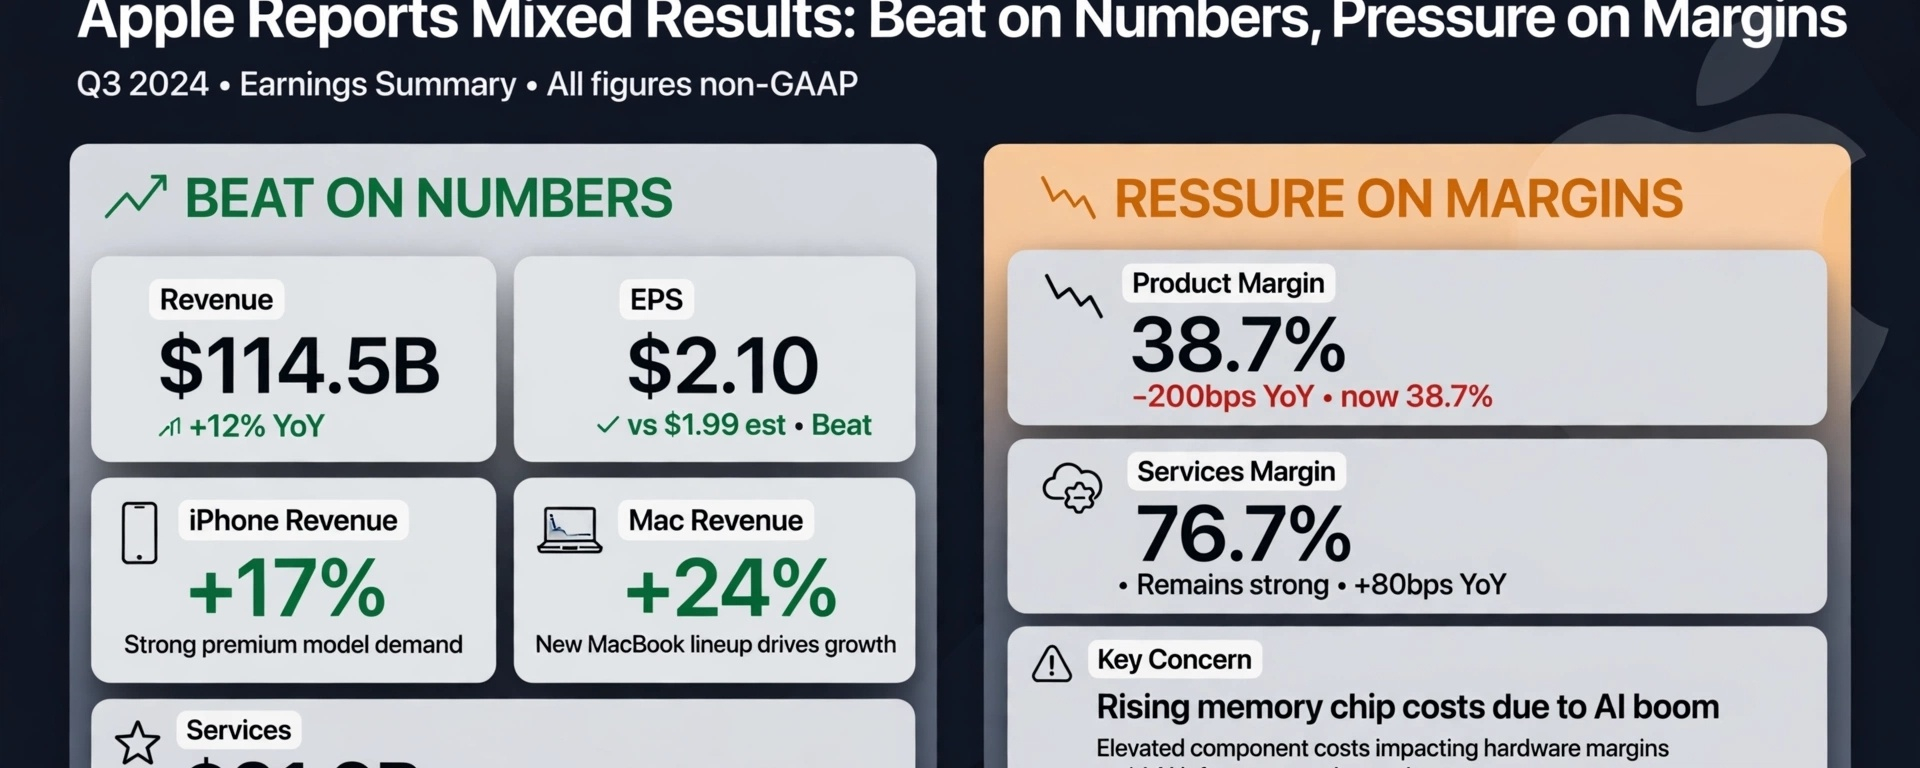
- 💰 **Revenue:** **$114.5 billion**, up **12%** year over year
- 📈 **EPS:** **$2.10**, beating expectations of **$1.99**
- 📱 **iPhone revenue:** up **17%**
- 💻 **Mac revenue:** up **24%**
- 🛍️ **Services:** a record **$31.6 billion**
As a sanity check, last year's September quarter revenue was about $102.5 billion, so $114.5 billion fits with roughly 12% growth. ✅
## ⚠️ The Key Concerns
Beneath the headline beat, the post flags several worries:
1. 📉 **iPad revenue fell 10%.** iPad has been the weak spot in recent quarters, and it declined again in the June quarter too.
2. 🧠 **Rising memory-chip costs** may pressure margins.
3. 🏭 **Supply constraints** remain a challenge.
4. 🔭 **Future profitability** is what investors are watching most.
## 🧠 Why Memory Costs Matter So Much
This isn't a one-quarter story. 🔁 Apple's CEO earlier warned that memory costs would climb significantly and have an increasing impact on the business. The cause is the global AI boom, since AI data centers are consuming huge amounts of high-bandwidth memory and tightening supply for everyone. 🤖
You can already see the effect in the numbers. Apple's product gross margin fell about 200 basis points to 38.7% in the March quarter. 📉 The good news is that Services carries a gross margin near 76.7%, which helps cushion the blow. 🛡️
## 🏁 A New Chapter at the Top
This report also arrives during a leadership transition. 👔 Tim Cook stepped aside as CEO in September, with hardware chief **John Ternus** taking over. Investors are now watching how the new leadership handles costs, supply, and growth. 🔍
## 📉 Why Did the Stock Come Under Pressure?
Markets don't trade on the past. They trade on the future. 🔮 After the June quarter, Apple's shares dropped nearly 5% even though revenue was a record, because guidance was weaker than analysts hoped (9–11% growth versus expectations above 12%). 😮 The same dynamic can repeat: **beating expectations isn't enough if the outlook disappoints.** 🎯
## 🐂 The Bull Case
1. 🛍️ **Services keep growing,** adding high-margin, recurring revenue.
2. 📱 **iPhone demand is strong,** with a 17% gain in the post.
3. 💻 **Mac momentum** is real, up 24%.
4. 💵 **Shareholder returns:** Apple approved a new $100 billion buyback earlier this year.
5. 🌏 **Global installed base** keeps expanding.
## 🐻 The Bear Case
1. 🧮 **Margin squeeze** from memory costs that may last for quarters.
2. 📦 **Supply limits** could cap sales growth even when demand is there.
3. 📉 **iPad weakness** shows not every product is thriving.
4. 🔮 **Guidance risk:** soft forecasts can outweigh strong results.
5. 🏢 **CEO transition** adds uncertainty.
## 🛡️ Smart Habits for Earnings Season
- 📚 Read the **guidance and the call**, not just the headline numbers.
- 📏 Compare **margins**, not only revenue.
- ⏱️ Expect **volatility** right after reports. Moves can reverse in days.
- 🧠 Avoid emotional trades. A "beat" can still lead to a selloff.
- 🔍 Verify figures on Apple's official investor relations page.
## 🧾 Final Thoughts
Apple's report shows a company with strong demand and a powerful ecosystem, but with a real cost challenge on the horizon. 🌗 So, **can Apple maintain its growth despite increasing costs?** 🤔 Its scale, pricing power, and Services business give it real defenses. But how well it handles memory costs and supply limits will likely decide how the market views the next few quarters. ⏳
*⚠️ Note: The figures in the "Key Highlights" section come from the post you shared. I couldn't find an official source confirming them, so please check Apple's official earnings release before publishing. This is general information, not financial advice.*
#Apple #AAPL #StockMarket #TechStocks #Earnings 🔥
---
Sources:
- [Neowin: Apple June quarter results and guidance](https://www.neowin.net/news/apple-posts-strongest-june-quarter-ever-driven-by-iphone-and-mac-growth/)
- [FX Leaders: memory costs and product margin](https://www.fxleaders.com/?p=447942)
- [Free Press Journal: Cook's memory cost warning](https://www.freepressjournal.in/tech/apple-warns-of-significantly-higher-memory-costs-ahead-may-impact-iphone-18-series-price)
- [Yahoo Finance: Ternus succession and memory shortage](https://finance.yahoo.com/news/apple-stock-rises-after-q2-earnings-top-estimates-on-strong-iphone-china-sales-174442778.html)
- [Apple via Business Wire: prior-year quarter](https://www.businesswire.com/news/home/20251030333927/en)#AppleReportsMixedResults #PalantirSlides3PercentOn$2BRevenue #FrenchAssemblyRejectsTwoCryptoExitTaxProposals #Nasdaq100EntersCorrection
#. 🚨 Apple Reports Mixed Results: Beat on Numbers, Pressure on Margins 🍎📊
#USOctoberNFP-AreRateCutsStillPossible
Apple's latest quarterly report delivered a familiar Wall Street puzzle: **strong numbers, but a nervous market.** 😬 The company beat revenue and earnings expectations, yet investors focused on rising costs, profit margins, and what comes next. 👀
## 📊 The Key Highlights
According to the post, here is what Apple reported:
- 💰 **Revenue:** **$114.5 billion**, up **12%** year over year
- 📈 **EPS:** **$2.10**, beating expectations of **$1.99**
- 📱 **iPhone revenue:** up **17%**
- 💻 **Mac revenue:** up **24%**
- 🛍️ **Services:** a record **$31.6 billion**
As a sanity check, last year's September quarter revenue was about $102.5 billion, so $114.5 billion fits with roughly 12% growth. ✅
## ⚠️ The Key Concerns
Beneath the headline beat, the post flags several worries:
1. 📉 **iPad revenue fell 10%.** iPad has been the weak spot in recent quarters, and it declined again in the June quarter too.
2. 🧠 **Rising memory-chip costs** may pressure margins.
3. 🏭 **Supply constraints** remain a challenge.
4. 🔭 **Future profitability** is what investors are watching most.
## 🧠 Why Memory Costs Matter So Much
This isn't a one-quarter story. 🔁 Apple's CEO earlier warned that memory costs would climb significantly and have an increasing impact on the business. The cause is the global AI boom, since AI data centers are consuming huge amounts of high-bandwidth memory and tightening supply for everyone. 🤖
You can already see the effect in the numbers. Apple's product gross margin fell about 200 basis points to 38.7% in the March quarter. 📉 The good news is that Services carries a gross margin near 76.7%, which helps cushion the blow. 🛡️
## 🏁 A New Chapter at the Top
This report also arrives during a leadership transition. 👔 Tim Cook stepped aside as CEO in September, with hardware chief **John Ternus** taking over. Investors are now watching how the new leadership handles costs, supply, and growth. 🔍
## 📉 Why Did the Stock Come Under Pressure?
Markets don't trade on the past. They trade on the future. 🔮 After the June quarter, Apple's shares dropped nearly 5% even though revenue was a record, because guidance was weaker than analysts hoped (9–11% growth versus expectations above 12%). 😮 The same dynamic can repeat: **beating expectations isn't enough if the outlook disappoints.** 🎯
## 🐂 The Bull Case
1. 🛍️ **Services keep growing,** adding high-margin, recurring revenue.
2. 📱 **iPhone demand is strong,** with a 17% gain in the post.
3. 💻 **Mac momentum** is real, up 24%.
4. 💵 **Shareholder returns:** Apple approved a new $100 billion buyback earlier this year.
5. 🌏 **Global installed base** keeps expanding.
## 🐻 The Bear Case
1. 🧮 **Margin squeeze** from memory costs that may last for quarters.
2. 📦 **Supply limits** could cap sales growth even when demand is there.
3. 📉 **iPad weakness** shows not every product is thriving.
4. 🔮 **Guidance risk:** soft forecasts can outweigh strong results.
5. 🏢 **CEO transition** adds uncertainty.
## 🛡️ Smart Habits for Earnings Season
- 📚 Read the **guidance and the call**, not just the headline numbers.
- 📏 Compare **margins**, not only revenue.
- ⏱️ Expect **volatility** right after reports. Moves can reverse in days.
- 🧠 Avoid emotional trades. A "beat" can still lead to a selloff.
- 🔍 Verify figures on Apple's official investor relations page.
## 🧾 Final Thoughts
Apple's report shows a company with strong demand and a powerful ecosystem, but with a real cost challenge on the horizon. 🌗 So, **can Apple maintain its growth despite increasing costs?** 🤔 Its scale, pricing power, and Services business give it real defenses. But how well it handles memory costs and supply limits will likely decide how the market views the next few quarters. ⏳
*⚠️ Note: The figures in the "Key Highlights" section come from the post you shared. I couldn't find an official source confirming them, so please check Apple's official earnings release before publishing. This is general information, not financial advice.*
#Apple #AAPL #StockMarket #TechStocks #Earnings 🔥
---
Sources:
- [Neowin: Apple June quarter results and guidance](https://www.neowin.net/news/apple-posts-strongest-june-quarter-ever-driven-by-iphone-and-mac-growth/)
- [FX Leaders: memory costs and product margin](https://www.fxleaders.com/?p=447942)
- [Free Press Journal: Cook's memory cost warning](https://www.freepressjournal.in/tech/apple-warns-of-significantly-higher-memory-costs-ahead-may-impact-iphone-18-series-price)
- [Yahoo Finance: Ternus succession and memory shortage](https://finance.yahoo.com/news/apple-stock-rises-after-q2-earnings-top-estimates-on-strong-iphone-china-sales-174442778.html)
- [Apple via Business Wire: prior-year quarter](https://www.businesswire.com/news/home/20251030333927/en)#AppleReportsMixedResults #PalantirSlides3PercentOn$2BRevenue #FrenchAssemblyRejectsTwoCryptoExitTaxProposals #Nasdaq100EntersCorrection
Apple's latest quarterly report delivered a familiar Wall Street puzzle: **strong numbers, but a nervous market.** 😬 The company beat revenue and earnings expectations, yet investors focused on rising costs, profit margins, and what comes next. 👀
## 📊 The Key Highlights
According to the post, here is what Apple reported:
- 💰 **Revenue:** **$114.5 billion**, up **12%** year over year
- 📈 **EPS:** **$2.10**, beating expectations of **$1.99**
- 📱 **iPhone revenue:** up **17%**
- 💻 **Mac revenue:** up **24%**
- 🛍️ **Services:** a record **$31.6 billion**
As a sanity check, last year's September quarter revenue was about $102.5 billion, so $114.5 billion fits with roughly 12% growth. ✅
## ⚠️ The Key Concerns
Beneath the headline beat, the post flags several worries:
1. 📉 **iPad revenue fell 10%.** iPad has been the weak spot in recent quarters, and it declined again in the June quarter too.
2. 🧠 **Rising memory-chip costs** may pressure margins.
3. 🏭 **Supply constraints** remain a challenge.
4. 🔭 **Future profitability** is what investors are watching most.
## 🧠 Why Memory Costs Matter So Much
This isn't a one-quarter story. 🔁 Apple's CEO earlier warned that memory costs would climb significantly and have an increasing impact on the business. The cause is the global AI boom, since AI data centers are consuming huge amounts of high-bandwidth memory and tightening supply for everyone. 🤖
You can already see the effect in the numbers. Apple's product gross margin fell about 200 basis points to 38.7% in the March quarter. 📉 The good news is that Services carries a gross margin near 76.7%, which helps cushion the blow. 🛡️
## 🏁 A New Chapter at the Top
This report also arrives during a leadership transition. 👔 Tim Cook stepped aside as CEO in September, with hardware chief **John Ternus** taking over. Investors are now watching how the new leadership handles costs, supply, and growth. 🔍
## 📉 Why Did the Stock Come Under Pressure?
Markets don't trade on the past. They trade on the future. 🔮 After the June quarter, Apple's shares dropped nearly 5% even though revenue was a record, because guidance was weaker than analysts hoped (9–11% growth versus expectations above 12%). 😮 The same dynamic can repeat: **beating expectations isn't enough if the outlook disappoints.** 🎯
## 🐂 The Bull Case
1. 🛍️ **Services keep growing,** adding high-margin, recurring revenue.
2. 📱 **iPhone demand is strong,** with a 17% gain in the post.
3. 💻 **Mac momentum** is real, up 24%.
4. 💵 **Shareholder returns:** Apple approved a new $100 billion buyback earlier this year.
5. 🌏 **Global installed base** keeps expanding.
## 🐻 The Bear Case
1. 🧮 **Margin squeeze** from memory costs that may last for quarters.
2. 📦 **Supply limits** could cap sales growth even when demand is there.
3. 📉 **iPad weakness** shows not every product is thriving.
4. 🔮 **Guidance risk:** soft forecasts can outweigh strong results.
5. 🏢 **CEO transition** adds uncertainty.
## 🛡️ Smart Habits for Earnings Season
- 📚 Read the **guidance and the call**, not just the headline numbers.
- 📏 Compare **margins**, not only revenue.
- ⏱️ Expect **volatility** right after reports. Moves can reverse in days.
- 🧠 Avoid emotional trades. A "beat" can still lead to a selloff.
- 🔍 Verify figures on Apple's official investor relations page.
## 🧾 Final Thoughts
Apple's report shows a company with strong demand and a powerful ecosystem, but with a real cost challenge on the horizon. 🌗 So, **can Apple maintain its growth despite increasing costs?** 🤔 Its scale, pricing power, and Services business give it real defenses. But how well it handles memory costs and supply limits will likely decide how the market views the next few quarters. ⏳
*⚠️ Note: The figures in the "Key Highlights" section come from the post you shared. I couldn't find an official source confirming them, so please check Apple's official earnings release before publishing. This is general information, not financial advice.*
#Apple #AAPL #StockMarket #TechStocks #Earnings 🔥
---
Sources:
- [Neowin: Apple June quarter results and guidance](https://www.neowin.net/news/apple-posts-strongest-june-quarter-ever-driven-by-iphone-and-mac-growth/)
- [FX Leaders: memory costs and product margin](https://www.fxleaders.com/?p=447942)
- [Free Press Journal: Cook's memory cost warning](https://www.freepressjournal.in/tech/apple-warns-of-significantly-higher-memory-costs-ahead-may-impact-iphone-18-series-price)
- [Yahoo Finance: Ternus succession and memory shortage](https://finance.yahoo.com/news/apple-stock-rises-after-q2-earnings-top-estimates-on-strong-iphone-china-sales-174442778.html)
- [Apple via Business Wire: prior-year quarter](https://www.businesswire.com/news/home/20251030333927/en)#AppleReportsMixedResults #PalantirSlides3PercentOn$2BRevenue #FrenchAssemblyRejectsTwoCryptoExitTaxProposals #Nasdaq100EntersCorrection
271
#applereportsmixedresults
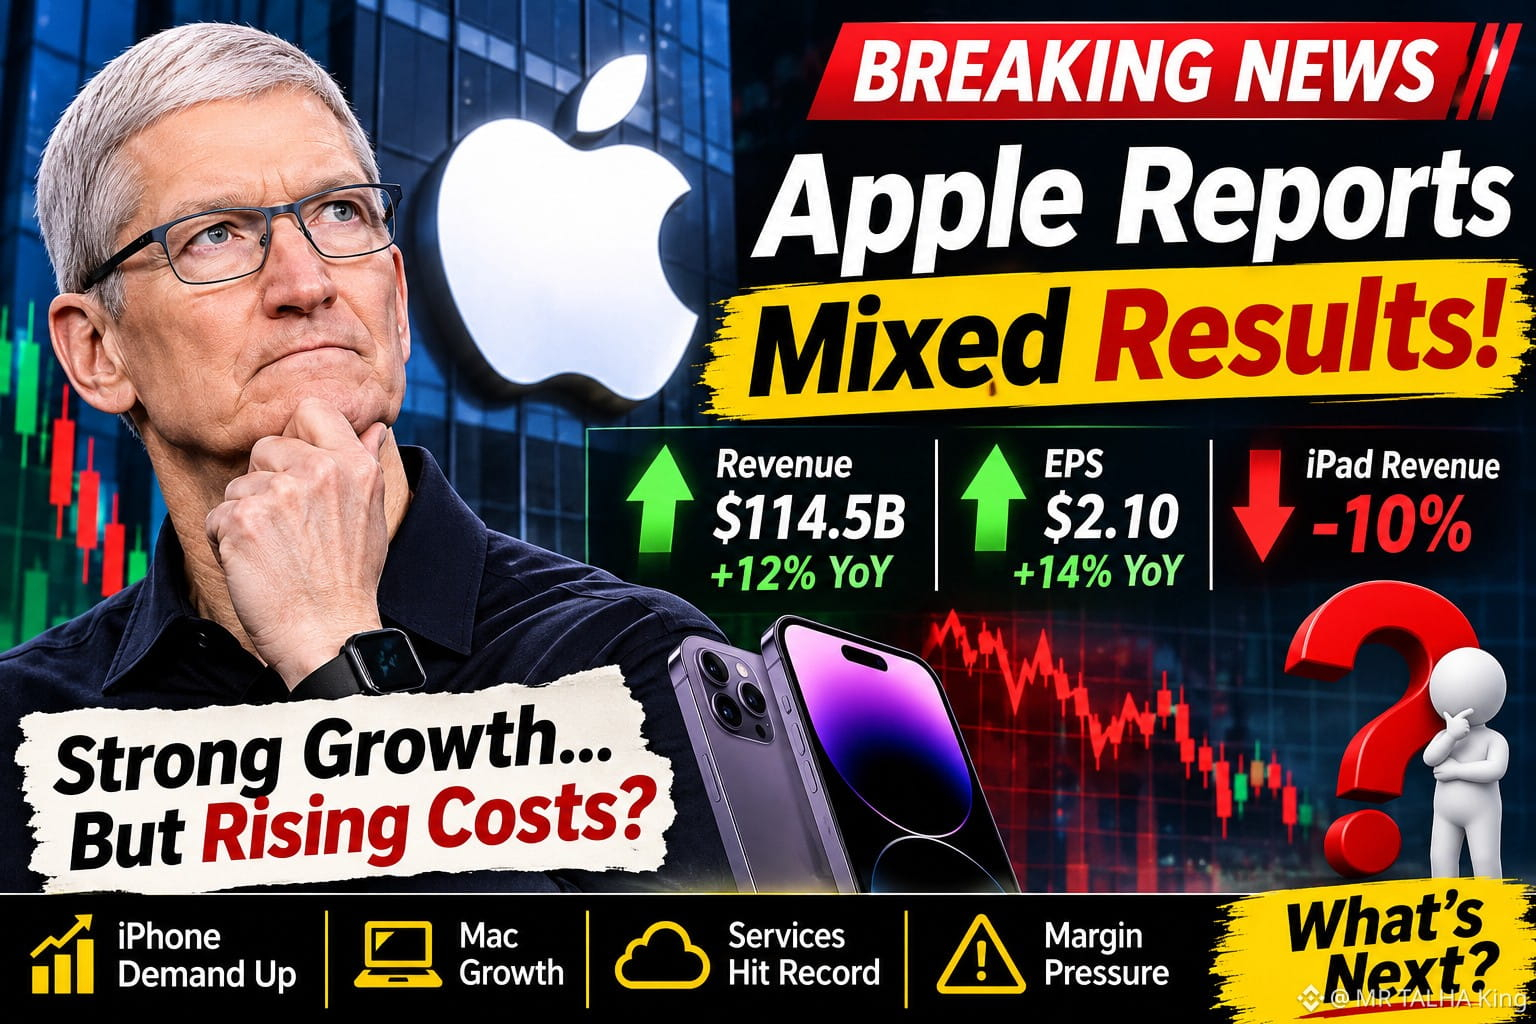
🚨 APPLE REPORTS MIXED RESULTS! 🍎📊
Apple delivered mixed quarterly results, beating revenue and earnings expectations while facing concerns over rising costs and profit margins.
📊 KEY HIGHLIGHTS:
🔹 Revenue reached $114.5B, up 12% year over year.
🔹 EPS hit $2.10, beating expectations of $1.99.
🔹 iPhone revenue increased 17%.
🔹 Mac revenue grew 24%.
🔹 Services reached a record $31.6B.
⚠️ KEY CONCERNS:
🔸 iPad revenue declined 10%.
🔸 Rising memory-chip costs may pressure margins.
🔸 Supply constraints remain a challenge.
🔸 Investors are watching future profitability.
📉 Despite beating expectations, Apple shares faced pressure as investors focused on rising costs and future guidance.
💬 YOUR TAKE: Can Apple maintain its growth despite increasing costs?
#Apple #AAPL #StockMarket #TechStocks
$AAPL
{future}(AAPLUSDT)
#applereportsmixedresults
🚨 APPLE REPORTS MIXED RESULTS! 🍎📊
Apple delivered mixed quarterly results, beating revenue and earnings expectations while facing concerns over rising costs and profit margins.
📊 KEY HIGHLIGHTS:
🔹 Revenue reached $114.5B, up 12% year over year.
🔹 EPS hit $2.10, beating expectations of $1.99.
🔹 iPhone revenue increased 17%.
🔹 Mac revenue grew 24%.
🔹 Services reached a record $31.6B.
⚠️ KEY CONCERNS:
🔸 iPad revenue declined 10%.
🔸 Rising memory-chip costs may pressure margins.
🔸 Supply constraints remain a challenge.
🔸 Investors are watching future profitability.
📉 Despite beating expectations, Apple shares faced pressure as investors focused on rising costs and future guidance.
💬 YOUR TAKE: Can Apple maintain its growth despite increasing costs?
#Apple #AAPL #StockMarket #TechStocks
$AAPL
🚨 APPLE REPORTS MIXED RESULTS! 🍎📊
Apple delivered mixed quarterly results, beating revenue and earnings expectations while facing concerns over rising costs and profit margins.
📊 KEY HIGHLIGHTS:
🔹 Revenue reached $114.5B, up 12% year over year.
🔹 EPS hit $2.10, beating expectations of $1.99.
🔹 iPhone revenue increased 17%.
🔹 Mac revenue grew 24%.
🔹 Services reached a record $31.6B.
⚠️ KEY CONCERNS:
🔸 iPad revenue declined 10%.
🔸 Rising memory-chip costs may pressure margins.
🔸 Supply constraints remain a challenge.
🔸 Investors are watching future profitability.
📉 Despite beating expectations, Apple shares faced pressure as investors focused on rising costs and future guidance.
💬 YOUR TAKE: Can Apple maintain its growth despite increasing costs?
#Apple #AAPL #StockMarket #TechStocks
$AAPL
454
Verified
#AppleReportsMixedResults
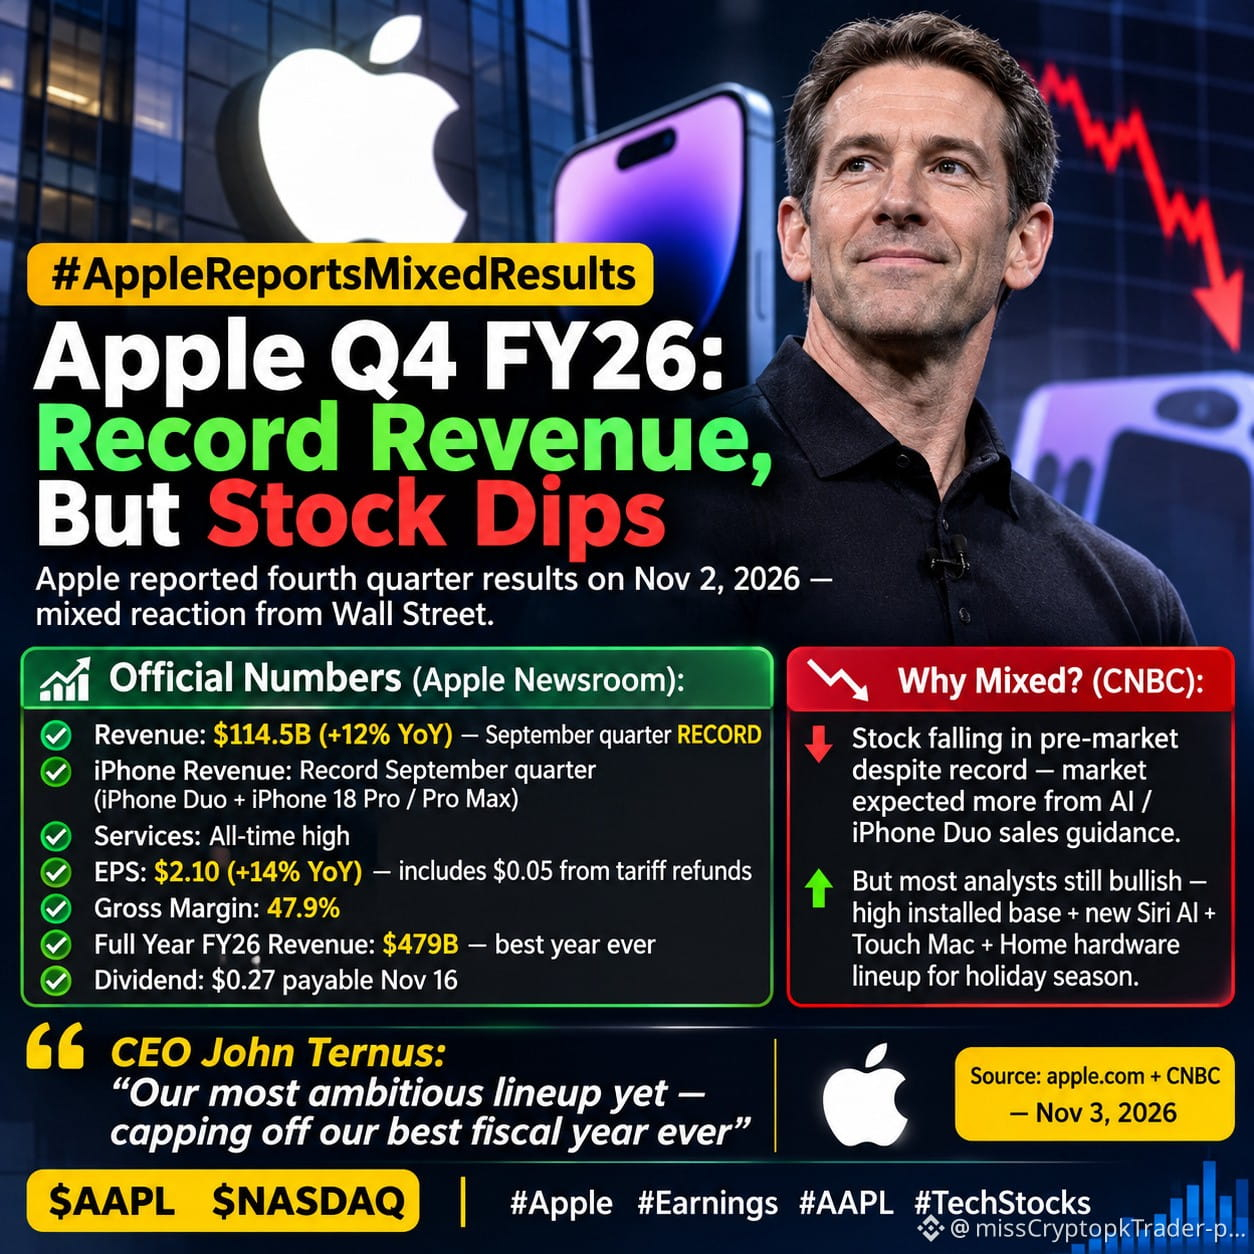
🍎 Apple Q4 FY26: Record Revenue, But Stock Dips
Apple reported fourth quarter results on Nov 2, 2026 — mixed reaction from Wall Street.
Official Numbers (Apple Newsroom):
✅ Revenue: $114.5B (+12% YoY) — September quarter RECORD
✅ iPhone Revenue: Record September quarter (iPhone Duo + iPhone 18 Pro / Pro Max)
✅ Services: All-time high
✅ EPS: $2.10 (+14% YoY) — includes $0.05 from tariff refunds
✅ Gross Margin: 47.9%
✅ Full Year FY26 Revenue: $479B — best year ever
✅ Dividend: $0.27 payable Nov 16
Why Mixed? (CNBC):
📉 Stock falling in pre-market despite record — market expected more from AI / iPhone Duo sales guidance.
📈 But most analysts still bullish — high installed base + new Siri AI + Touch Mac + Home hardware lineup for holiday season.
CEO John Ternus: "Our most ambitious lineup yet — capping off our best fiscal year ever"
$AAPL
#Apple #Earnings #NASDAQ #AAPLUSDT
#AppleReportsMixedResults
🍎 Apple Q4 FY26: Record Revenue, But Stock Dips
Apple reported fourth quarter results on Nov 2, 2026 — mixed reaction from Wall Street.
Official Numbers (Apple Newsroom):
✅ Revenue: $114.5B (+12% YoY) — September quarter RECORD
✅ iPhone Revenue: Record September quarter (iPhone Duo + iPhone 18 Pro / Pro Max)
✅ Services: All-time high
✅ EPS: $2.10 (+14% YoY) — includes $0.05 from tariff refunds
✅ Gross Margin: 47.9%
✅ Full Year FY26 Revenue: $479B — best year ever
✅ Dividend: $0.27 payable Nov 16
Why Mixed? (CNBC):
📉 Stock falling in pre-market despite record — market expected more from AI / iPhone Duo sales guidance.
📈 But most analysts still bullish — high installed base + new Siri AI + Touch Mac + Home hardware lineup for holiday season.
CEO John Ternus: "Our most ambitious lineup yet — capping off our best fiscal year ever"
$AAPL
#Apple #Earnings #NASDAQ #AAPLUSDT
🍎 Apple Q4 FY26: Record Revenue, But Stock Dips
Apple reported fourth quarter results on Nov 2, 2026 — mixed reaction from Wall Street.
Official Numbers (Apple Newsroom):
✅ Revenue: $114.5B (+12% YoY) — September quarter RECORD
✅ iPhone Revenue: Record September quarter (iPhone Duo + iPhone 18 Pro / Pro Max)
✅ Services: All-time high
✅ EPS: $2.10 (+14% YoY) — includes $0.05 from tariff refunds
✅ Gross Margin: 47.9%
✅ Full Year FY26 Revenue: $479B — best year ever
✅ Dividend: $0.27 payable Nov 16
Why Mixed? (CNBC):
📉 Stock falling in pre-market despite record — market expected more from AI / iPhone Duo sales guidance.
📈 But most analysts still bullish — high installed base + new Siri AI + Touch Mac + Home hardware lineup for holiday season.
CEO John Ternus: "Our most ambitious lineup yet — capping off our best fiscal year ever"
$AAPL
#Apple #Earnings #NASDAQ #AAPLUSDT
1
270
·
--
#applereportsmixedresults Apple Q4 Breakdown:
✅ Revenue: $114.5B (Beat) ✅ EPS: $2.10 (Beat) ❌ Market Reaction: Shares down ~3% due to forward guidance and margin concerns.
Even strong balance sheets can't always satisfy high market expectations. Are you buying the dip or staying on the sidelines? 🧠💡
#TechStocks #Trading #Finance $BTC
{future}(BTCUSDT)
#applereportsmixedresults Apple Q4 Breakdown:
✅ Revenue: $114.5B (Beat) ✅ EPS: $2.10 (Beat) ❌ Market Reaction: Shares down ~3% due to forward guidance and margin concerns.
Even strong balance sheets can't always satisfy high market expectations. Are you buying the dip or staying on the sidelines? 🧠💡
#TechStocks #Trading #Finance $BTC
✅ Revenue: $114.5B (Beat) ✅ EPS: $2.10 (Beat) ❌ Market Reaction: Shares down ~3% due to forward guidance and margin concerns.
Even strong balance sheets can't always satisfy high market expectations. Are you buying the dip or staying on the sidelines? 🧠💡
#TechStocks #Trading #Finance $BTC
429
·
--
Bullish
Verified
#applereportsmixedresults 🍏 APPLE Q4 BEATS ON REVENUE BUT MARGIN SQUEEZE WEIGHS ON STOCK! 📉⚠️
Q4 Beat Under New CEO: In John Ternus’s debut earnings as CEO, Apple reported Q4 revenue of $114.5B (+12% YoY) and EPS of $2.10, beating market estimates despite broader headwinds.
iPhone & Mac Surge: iPhone revenue jumped 17% to $57.6B, while Mac sales stood out with a massive 24% surge to $10.8B, fueled by strong hardware demand.
Margin Pressure Ahead: Apple guided Q1 gross margins down to 45%–46%, disappointing investors as surging memory chip prices and AI compute costs squeeze profitability into the holiday season.
Mixed Regional Performance: Greater China sales reached $17.5B (+20%), but missed estimates due to supply constraints, while Services hit $31.6B.
💬 YOUR TURN: Do you think component cost inflation and AI expenses will limit Apple's upside, or will the upcoming Mac and iPhone releases drive a new high?
👇 Drop your thoughts below!
"CLICK ON THE BELOW YELLOW COIN TAG TO GO TO DESIRED TRADING PAGE TO GET BENEFIT TRADE" $AAPLB
{spot}(AAPLBUSDT)
$ETH
{future}(ETHUSDT)
$ZEC
{future}(ZECUSDT)
#BinanceReopensWithdrawalsForMoreAssets #USMidtermElections #Apple #EarningsSeason
#applereportsmixedresults 🍏 APPLE Q4 BEATS ON REVENUE BUT MARGIN SQUEEZE WEIGHS ON STOCK! 📉⚠️
Q4 Beat Under New CEO: In John Ternus’s debut earnings as CEO, Apple reported Q4 revenue of $114.5B (+12% YoY) and EPS of $2.10, beating market estimates despite broader headwinds.
iPhone & Mac Surge: iPhone revenue jumped 17% to $57.6B, while Mac sales stood out with a massive 24% surge to $10.8B, fueled by strong hardware demand.
Margin Pressure Ahead: Apple guided Q1 gross margins down to 45%–46%, disappointing investors as surging memory chip prices and AI compute costs squeeze profitability into the holiday season.
Mixed Regional Performance: Greater China sales reached $17.5B (+20%), but missed estimates due to supply constraints, while Services hit $31.6B.
💬 YOUR TURN: Do you think component cost inflation and AI expenses will limit Apple's upside, or will the upcoming Mac and iPhone releases drive a new high?
👇 Drop your thoughts below!
"CLICK ON THE BELOW YELLOW COIN TAG TO GO TO DESIRED TRADING PAGE TO GET BENEFIT TRADE" $AAPLB
$ETH
$ZEC
#BinanceReopensWithdrawalsForMoreAssets #USMidtermElections #Apple #EarningsSeason
Q4 Beat Under New CEO: In John Ternus’s debut earnings as CEO, Apple reported Q4 revenue of $114.5B (+12% YoY) and EPS of $2.10, beating market estimates despite broader headwinds.
iPhone & Mac Surge: iPhone revenue jumped 17% to $57.6B, while Mac sales stood out with a massive 24% surge to $10.8B, fueled by strong hardware demand.
Margin Pressure Ahead: Apple guided Q1 gross margins down to 45%–46%, disappointing investors as surging memory chip prices and AI compute costs squeeze profitability into the holiday season.
Mixed Regional Performance: Greater China sales reached $17.5B (+20%), but missed estimates due to supply constraints, while Services hit $31.6B.
💬 YOUR TURN: Do you think component cost inflation and AI expenses will limit Apple's upside, or will the upcoming Mac and iPhone releases drive a new high?
👇 Drop your thoughts below!
"CLICK ON THE BELOW YELLOW COIN TAG TO GO TO DESIRED TRADING PAGE TO GET BENEFIT TRADE" $AAPLB
$ETH
$ZEC
#BinanceReopensWithdrawalsForMoreAssets #USMidtermElections #Apple #EarningsSeason
2
908
·
--
Verified
#applereportsmixedresults Apple Just Dropped Mixed Signals! 🍏📉
Apple posted a record $114.5B in revenue and beat EPS estimates, but the stock still dipped! Why? Investors are raising eyebrows over tightening margins and regional growth slowdowns.
Big tech earnings are getting complicated. Are markets setting up for a wider correction, or is this just a classic sell-the-news event? Let’s discuss below! 👇
#Apple #StockMarket #Macro #Trading $SOL
{future}(SOLVUSDT)
$BTC
{future}(BTCUSDT)
#applereportsmixedresults Apple Just Dropped Mixed Signals! 🍏📉
Apple posted a record $114.5B in revenue and beat EPS estimates, but the stock still dipped! Why? Investors are raising eyebrows over tightening margins and regional growth slowdowns.
Big tech earnings are getting complicated. Are markets setting up for a wider correction, or is this just a classic sell-the-news event? Let’s discuss below! 👇
#Apple #StockMarket #Macro #Trading $SOL
$BTC
Apple posted a record $114.5B in revenue and beat EPS estimates, but the stock still dipped! Why? Investors are raising eyebrows over tightening margins and regional growth slowdowns.
Big tech earnings are getting complicated. Are markets setting up for a wider correction, or is this just a classic sell-the-news event? Let’s discuss below! 👇
#Apple #StockMarket #Macro #Trading $SOL
$BTC
4
4.9k
·
--
Verified
🚨 APPLE BEATS EARNINGS, BUT WALL STREET ISN'T IMPRESSED — IS $AAPL A BUY-THE-DIP OPPORTUNITY? 🍎📉
Apple just reported record quarterly revenue, yet the stock is struggling to gain momentum.
So what's worrying investors? 👀
📊 Q4 EARNINGS SNAPSHOT:
💰 Revenue: $114.5B (+12%)
📈 EPS: $2.10 (+14%)
📱 iPhone revenue: $57.6B (+17%)
🔥 Services revenue: $31.6B — ALL-TIME HIGH
Strong numbers, right?
BUT HERE'S THE PROBLEM…
Apple expects gross margins to fall to 45–46% next quarter as memory-chip prices and AI costs rise.
And while iPhone demand remains strong, weaker iPad, wearables, and China sales are raising questions.
Not financial advice. DYOR.
{spot}(AAPLBUSDT)
{stock_us}(AAPL.US)
{future}(AAPLUSDT)
#applereportsmixedresults #BinanceReopensWithdrawalsForMoreAssets #BinanceHourlyDepositsExceedWithdrawals #PalantirSlides3PercentOn$2BRevenue #USMidtermElections
🚨 APPLE BEATS EARNINGS, BUT WALL STREET ISN'T IMPRESSED — IS $AAPL A BUY-THE-DIP OPPORTUNITY? 🍎📉
Apple just reported record quarterly revenue, yet the stock is struggling to gain momentum.
So what's worrying investors? 👀
📊 Q4 EARNINGS SNAPSHOT:
💰 Revenue: $114.5B (+12%)
📈 EPS: $2.10 (+14%)
📱 iPhone revenue: $57.6B (+17%)
🔥 Services revenue: $31.6B — ALL-TIME HIGH
Strong numbers, right?
BUT HERE'S THE PROBLEM…
Apple expects gross margins to fall to 45–46% next quarter as memory-chip prices and AI costs rise.
And while iPhone demand remains strong, weaker iPad, wearables, and China sales are raising questions.
Not financial advice. DYOR.
#applereportsmixedresults #BinanceReopensWithdrawalsForMoreAssets #BinanceHourlyDepositsExceedWithdrawals #PalantirSlides3PercentOn$2BRevenue #USMidtermElections
Apple just reported record quarterly revenue, yet the stock is struggling to gain momentum.
So what's worrying investors? 👀
📊 Q4 EARNINGS SNAPSHOT:
💰 Revenue: $114.5B (+12%)
📈 EPS: $2.10 (+14%)
📱 iPhone revenue: $57.6B (+17%)
🔥 Services revenue: $31.6B — ALL-TIME HIGH
Strong numbers, right?
BUT HERE'S THE PROBLEM…
Apple expects gross margins to fall to 45–46% next quarter as memory-chip prices and AI costs rise.
And while iPhone demand remains strong, weaker iPad, wearables, and China sales are raising questions.
Not financial advice. DYOR.
#applereportsmixedresults #BinanceReopensWithdrawalsForMoreAssets #BinanceHourlyDepositsExceedWithdrawals #PalantirSlides3PercentOn$2BRevenue #USMidtermElections
AAPL-2.33%
AAPLUS-0.47%
619

APPLE REPORTS $114.5B REVENUE — RECORD iPHONE SALES, BUT MARGIN WARNING SHAKES INVESTOR CONFIDENCE!Apple delivered impressive quarterly numbers, but Wall Street is looking beyond the headline revenue.
The company's first earnings report under new CEO John Ternus showed powerful iPhone demand and record Services revenue. However, rising component costs are creating new pressure for the next quarter.
🧮 THE BIG NUMBERS: APPLE Q4 2026
💰 Total revenue: $114.5 billion, up 12% year over year.📱 iPhone revenue: $57.6 billion, up 17%.☁️ Services revenue: $31.6 billion, up 10%, reaching an all-time high.💻 Mac revenue: $10.8 billion, up 24%.📲 iPad revenue: $6.2 billion, down 10%.📈 Earnings per share: $2.10, up 14%.
iPhone sales were particularly impressive, despite supply constraints and the relatively short contribution from the new iPhone 18 Pro lineup during the quarter.
🔥 THE HIDDEN DETAIL: TARIFF REFUNDS BOOSTED MARGINS
Apple reported a gross margin of 47.9%.
But there's an important detail investors shouldn't ignore:
Approximately 1 percentage point of that margin came from favorable tariff refunds.
Without that benefit, higher memory costs would have put more pressure on the underlying margin performance.
⚠️ THE BIGGEST CONCERN: DECEMBER QUARTER OUTLOOK
Apple expects:
Revenue growth of 7%–10% year over year.Gross margin of 45%–46%.Services revenue growth of 8%–9%.
The revenue forecast is encouraging and could produce Apple's strongest December quarter ever.
However, the projected margin decline reflects rising memory prices and additional costs associated with the Siri AI rollout.
📉 WHY DID APPLE SHARES FACE PRESSURE?
Investors were focused on profitability rather than revenue alone.
During the earnings call, Apple's shares fell around 4% before recovering some of those losses.
The concern is straightforward: strong demand is positive, but increasing production costs could reduce the profit Apple earns from each sale.
👔 JOHN TERNUS' FIRST BIG TEST
This was the first earnings report under Apple's new CEO, John Ternus.
His immediate challenge is balancing three priorities:
1️⃣ Meeting strong demand for Apple's latest products.
2️⃣ Managing rising memory and component costs.
3️⃣ Protecting margins while expanding AI capabilities.
🔥 MY TAKE
Apple's demand story remains strong, especially with iPhone and Services.
But the next quarter will be an important test of profitability. Investors should watch memory costs, product supply and whether Apple can maintain its margins without relying on temporary benefits such as tariff refunds.
Strong sales are impressive. Sustainable profits are what matter next.
👇 Do you think Apple's strong iPhone demand can overcome rising production costs, or could margin pressure become the bigger problem?
#AppleReportsMixedResults
{spot}(AAPLBUSDT)
APPLE REPORTS $114.5B REVENUE — RECORD iPHONE SALES, BUT MARGIN WARNING SHAKES INVESTOR CONFIDENCE!
Apple delivered impressive quarterly numbers, but Wall Street is looking beyond the headline revenue.
The company's first earnings report under new CEO John Ternus showed powerful iPhone demand and record Services revenue. However, rising component costs are creating new pressure for the next quarter.
🧮 THE BIG NUMBERS: APPLE Q4 2026
💰 Total revenue: $114.5 billion, up 12% year over year.📱 iPhone revenue: $57.6 billion, up 17%.☁️ Services revenue: $31.6 billion, up 10%, reaching an all-time high.💻 Mac revenue: $10.8 billion, up 24%.📲 iPad revenue: $6.2 billion, down 10%.📈 Earnings per share: $2.10, up 14%.
iPhone sales were particularly impressive, despite supply constraints and the relatively short contribution from the new iPhone 18 Pro lineup during the quarter.
🔥 THE HIDDEN DETAIL: TARIFF REFUNDS BOOSTED MARGINS
Apple reported a gross margin of 47.9%.
But there's an important detail investors shouldn't ignore:
Approximately 1 percentage point of that margin came from favorable tariff refunds.
Without that benefit, higher memory costs would have put more pressure on the underlying margin performance.
⚠️ THE BIGGEST CONCERN: DECEMBER QUARTER OUTLOOK
Apple expects:
Revenue growth of 7%–10% year over year.Gross margin of 45%–46%.Services revenue growth of 8%–9%.
The revenue forecast is encouraging and could produce Apple's strongest December quarter ever.
However, the projected margin decline reflects rising memory prices and additional costs associated with the Siri AI rollout.
📉 WHY DID APPLE SHARES FACE PRESSURE?
Investors were focused on profitability rather than revenue alone.
During the earnings call, Apple's shares fell around 4% before recovering some of those losses.
The concern is straightforward: strong demand is positive, but increasing production costs could reduce the profit Apple earns from each sale.
👔 JOHN TERNUS' FIRST BIG TEST
This was the first earnings report under Apple's new CEO, John Ternus.
His immediate challenge is balancing three priorities:
1️⃣ Meeting strong demand for Apple's latest products.
2️⃣ Managing rising memory and component costs.
3️⃣ Protecting margins while expanding AI capabilities.
🔥 MY TAKE
Apple's demand story remains strong, especially with iPhone and Services.
But the next quarter will be an important test of profitability. Investors should watch memory costs, product supply and whether Apple can maintain its margins without relying on temporary benefits such as tariff refunds.
Strong sales are impressive. Sustainable profits are what matter next.
👇 Do you think Apple's strong iPhone demand can overcome rising production costs, or could margin pressure become the bigger problem?
#AppleReportsMixedResults
The company's first earnings report under new CEO John Ternus showed powerful iPhone demand and record Services revenue. However, rising component costs are creating new pressure for the next quarter.
🧮 THE BIG NUMBERS: APPLE Q4 2026
💰 Total revenue: $114.5 billion, up 12% year over year.📱 iPhone revenue: $57.6 billion, up 17%.☁️ Services revenue: $31.6 billion, up 10%, reaching an all-time high.💻 Mac revenue: $10.8 billion, up 24%.📲 iPad revenue: $6.2 billion, down 10%.📈 Earnings per share: $2.10, up 14%.
iPhone sales were particularly impressive, despite supply constraints and the relatively short contribution from the new iPhone 18 Pro lineup during the quarter.
🔥 THE HIDDEN DETAIL: TARIFF REFUNDS BOOSTED MARGINS
Apple reported a gross margin of 47.9%.
But there's an important detail investors shouldn't ignore:
Approximately 1 percentage point of that margin came from favorable tariff refunds.
Without that benefit, higher memory costs would have put more pressure on the underlying margin performance.
⚠️ THE BIGGEST CONCERN: DECEMBER QUARTER OUTLOOK
Apple expects:
Revenue growth of 7%–10% year over year.Gross margin of 45%–46%.Services revenue growth of 8%–9%.
The revenue forecast is encouraging and could produce Apple's strongest December quarter ever.
However, the projected margin decline reflects rising memory prices and additional costs associated with the Siri AI rollout.
📉 WHY DID APPLE SHARES FACE PRESSURE?
Investors were focused on profitability rather than revenue alone.
During the earnings call, Apple's shares fell around 4% before recovering some of those losses.
The concern is straightforward: strong demand is positive, but increasing production costs could reduce the profit Apple earns from each sale.
👔 JOHN TERNUS' FIRST BIG TEST
This was the first earnings report under Apple's new CEO, John Ternus.
His immediate challenge is balancing three priorities:
1️⃣ Meeting strong demand for Apple's latest products.
2️⃣ Managing rising memory and component costs.
3️⃣ Protecting margins while expanding AI capabilities.
🔥 MY TAKE
Apple's demand story remains strong, especially with iPhone and Services.
But the next quarter will be an important test of profitability. Investors should watch memory costs, product supply and whether Apple can maintain its margins without relying on temporary benefits such as tariff refunds.
Strong sales are impressive. Sustainable profits are what matter next.
👇 Do you think Apple's strong iPhone demand can overcome rising production costs, or could margin pressure become the bigger problem?
#AppleReportsMixedResults
97
·
--
#AppleReportsMixedResults
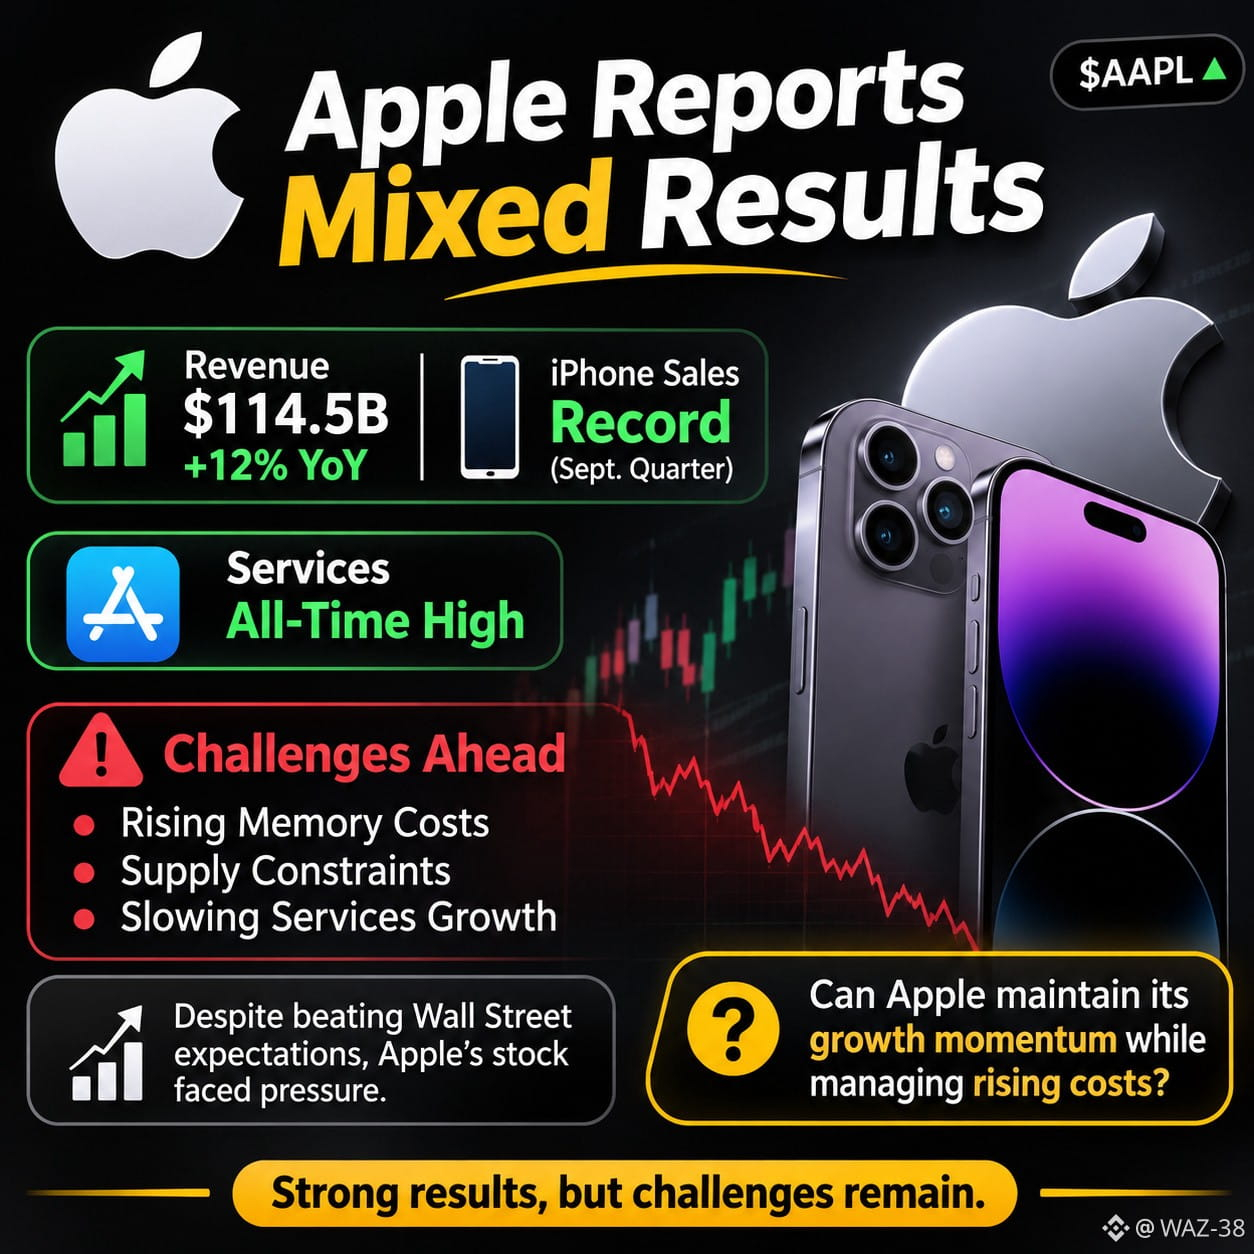
Apple delivered a strong quarterly performance, with revenue reaching $114.5 billion, up 12% year over year. iPhone sales hit a September-quarter record, while Services achieved an all-time high. However, rising memory costs, supply constraints, and slowing Services growth are creating concerns about future margins. Despite beating Wall Street's earnings expectations, Apple's stock faced pressure as investors weighed these challenges.
The bigger question is whether Apple can maintain its growth momentum while managing rising costs and expanding its AI strategy.
Strong results, but challenges remain.
$AAPL #Apple #StockMarket
#AppleReportsMixedResults
Apple delivered a strong quarterly performance, with revenue reaching $114.5 billion, up 12% year over year. iPhone sales hit a September-quarter record, while Services achieved an all-time high. However, rising memory costs, supply constraints, and slowing Services growth are creating concerns about future margins. Despite beating Wall Street's earnings expectations, Apple's stock faced pressure as investors weighed these challenges.
The bigger question is whether Apple can maintain its growth momentum while managing rising costs and expanding its AI strategy.
Strong results, but challenges remain.
$AAPL #Apple #StockMarket
Apple delivered a strong quarterly performance, with revenue reaching $114.5 billion, up 12% year over year. iPhone sales hit a September-quarter record, while Services achieved an all-time high. However, rising memory costs, supply constraints, and slowing Services growth are creating concerns about future margins. Despite beating Wall Street's earnings expectations, Apple's stock faced pressure as investors weighed these challenges.
The bigger question is whether Apple can maintain its growth momentum while managing rising costs and expanding its AI strategy.
Strong results, but challenges remain.
$AAPL #Apple #StockMarket
عبدالله الشهاب:
كلامت
1
204
·
--
Bearish
#applereportsmixedresults
🍎 Apple Delivers Record Revenue, But Rising Costs Raise Market Concerns
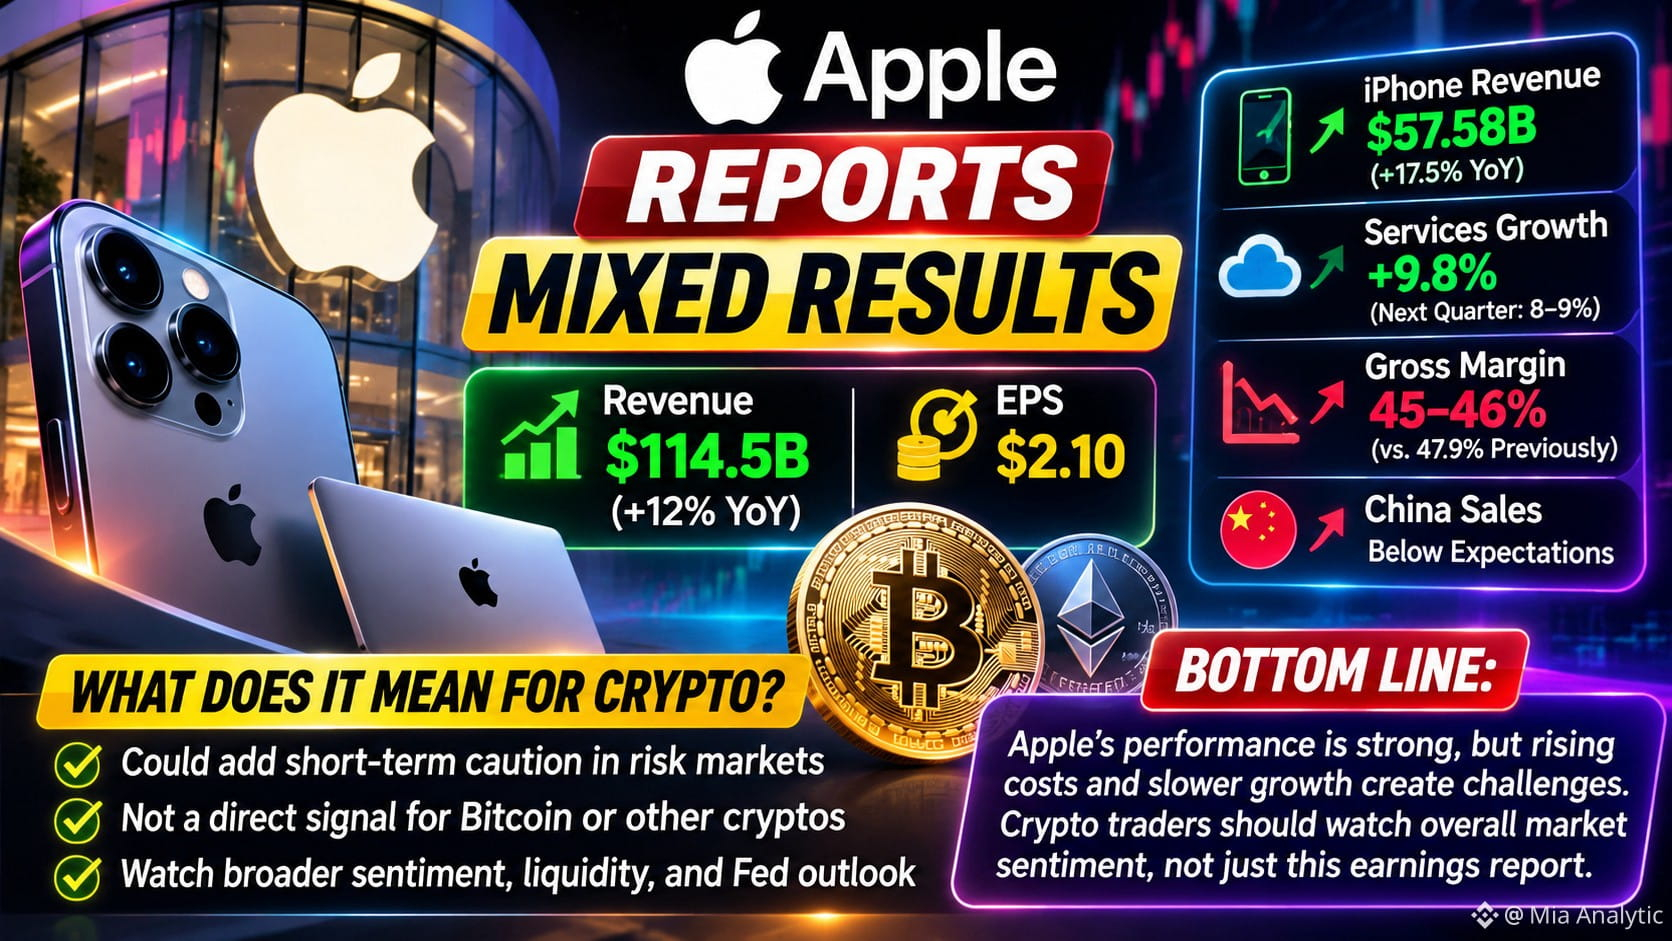
Apple reported mixed fiscal Q4 2026 results, beating Wall Street expectations with $114.5 billion in revenue, up 12% year over year, and earnings per share of $2.10.
The iPhone business remained strong, with revenue climbing 17.5% to $57.58 billion. However, investors are focusing on several challenges:
• Rising Costs: Higher memory-chip prices could pressure Apple's profit margins.
• Slowing Services Growth: Services revenue increased 9.8%, while management expects 8–9% growth in the next quarter.
• Margin Pressure: Apple expects gross margins of 45–46% for the December quarter, compared with 47.9% previously.
• China Market: Sales came in below analyst expectations.
📊 What Does This Mean for Crypto?
Apple's results matter beyond traditional technology stocks. Weak forward guidance and rising costs could increase caution across risk-sensitive markets, including cryptocurrencies.
However, Apple's earnings do not directly determine Bitcoin's direction. Traders should also monitor broader market liquidity, Federal Reserve expectations, institutional flows, and overall risk appetite.
Bottom Line: Apple's current performance remains strong, but its future profitability faces challenges. Crypto traders should watch how broader market sentiment reacts rather than treating this earnings report as an independent bullish or bearish signal.
#AppleEarnings #AppleStock #CryptoMarket #Bitcoin
$AKE $TRUTH $BEAMX
{future}(BEAMXUSDT)
{future}(TRUTHUSDT)
{future}(AKEUSDT)
#applereportsmixedresults
🍎 Apple Delivers Record Revenue, But Rising Costs Raise Market Concerns
Apple reported mixed fiscal Q4 2026 results, beating Wall Street expectations with $114.5 billion in revenue, up 12% year over year, and earnings per share of $2.10.
The iPhone business remained strong, with revenue climbing 17.5% to $57.58 billion. However, investors are focusing on several challenges:
• Rising Costs: Higher memory-chip prices could pressure Apple's profit margins.
• Slowing Services Growth: Services revenue increased 9.8%, while management expects 8–9% growth in the next quarter.
• Margin Pressure: Apple expects gross margins of 45–46% for the December quarter, compared with 47.9% previously.
• China Market: Sales came in below analyst expectations.
📊 What Does This Mean for Crypto?
Apple's results matter beyond traditional technology stocks. Weak forward guidance and rising costs could increase caution across risk-sensitive markets, including cryptocurrencies.
However, Apple's earnings do not directly determine Bitcoin's direction. Traders should also monitor broader market liquidity, Federal Reserve expectations, institutional flows, and overall risk appetite.
Bottom Line: Apple's current performance remains strong, but its future profitability faces challenges. Crypto traders should watch how broader market sentiment reacts rather than treating this earnings report as an independent bullish or bearish signal.
#AppleEarnings #AppleStock #CryptoMarket #Bitcoin
$AKE $TRUTH $BEAMX
🍎 Apple Delivers Record Revenue, But Rising Costs Raise Market Concerns
Apple reported mixed fiscal Q4 2026 results, beating Wall Street expectations with $114.5 billion in revenue, up 12% year over year, and earnings per share of $2.10.
The iPhone business remained strong, with revenue climbing 17.5% to $57.58 billion. However, investors are focusing on several challenges:
• Rising Costs: Higher memory-chip prices could pressure Apple's profit margins.
• Slowing Services Growth: Services revenue increased 9.8%, while management expects 8–9% growth in the next quarter.
• Margin Pressure: Apple expects gross margins of 45–46% for the December quarter, compared with 47.9% previously.
• China Market: Sales came in below analyst expectations.
📊 What Does This Mean for Crypto?
Apple's results matter beyond traditional technology stocks. Weak forward guidance and rising costs could increase caution across risk-sensitive markets, including cryptocurrencies.
However, Apple's earnings do not directly determine Bitcoin's direction. Traders should also monitor broader market liquidity, Federal Reserve expectations, institutional flows, and overall risk appetite.
Bottom Line: Apple's current performance remains strong, but its future profitability faces challenges. Crypto traders should watch how broader market sentiment reacts rather than treating this earnings report as an independent bullish or bearish signal.
#AppleEarnings #AppleStock #CryptoMarket #Bitcoin
$AKE $TRUTH $BEAMX
333
·
--
#applereportsmixedresults is NOT what headline says — Apple just played the best smoke-and-mirrors quarter of 2026
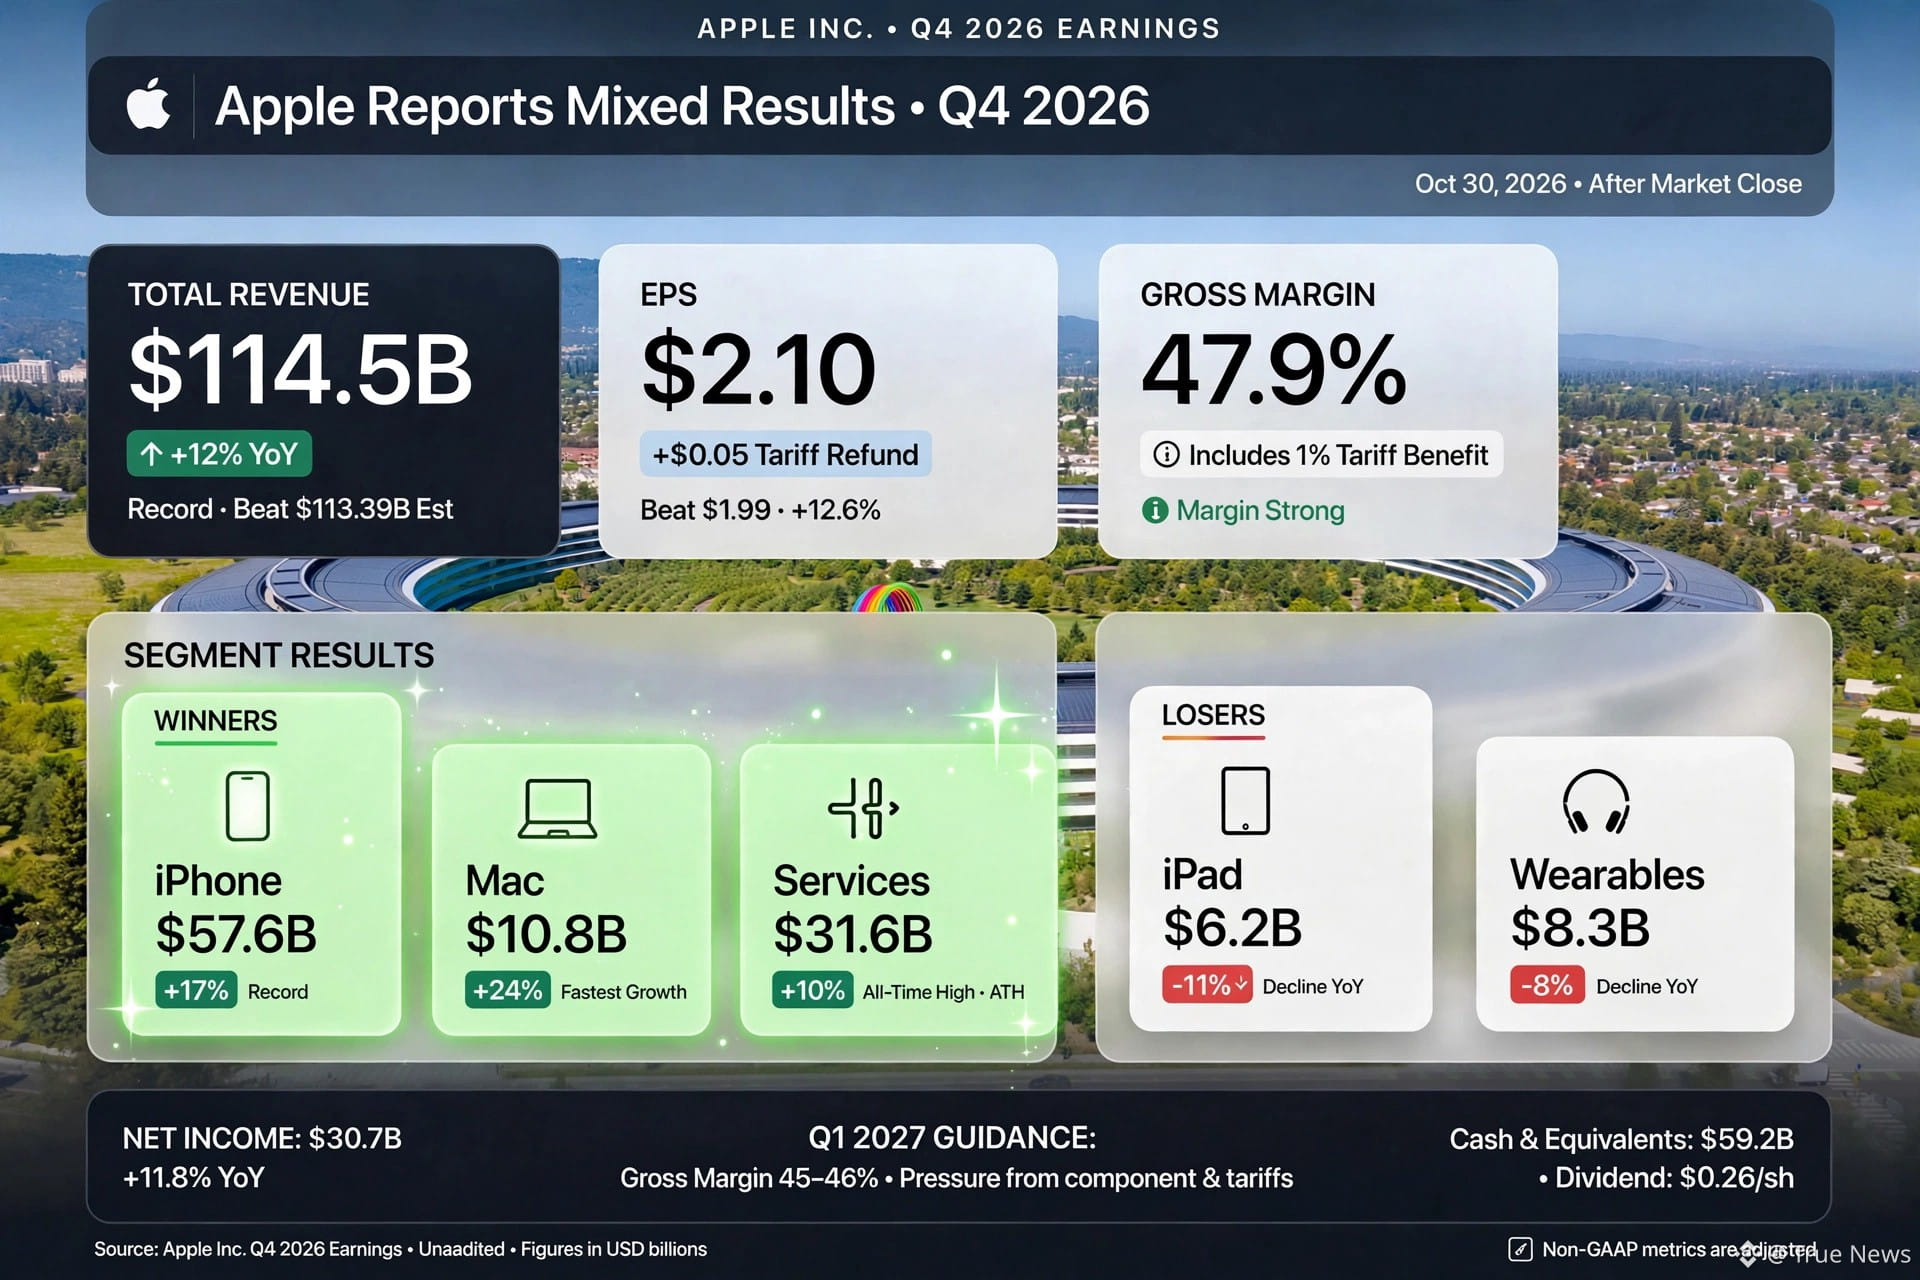
Everyone saw $114.5B revenue +12% YoY, record September quarter, beat $113.39B est. But here's what 90% missed:
The $0.05 tariff trick: EPS $2.10 beat $1.99, but $0.05 came from a one-time tariff refund.
Gross margin 47.9% beat 47.5%, but 1% point was that same refund. Strip it and true margin is ∼46.9%. That's why AAPL dropped ∼3% after-hours despite a beat — guidance for Q1 2027 is 45-46% with component & AI cost pressure.
Insider split no one talks about: This was new CEO John Ternus' FIRST earnings call. iPhone $57.6B +17% record with iPhone 18 Pro / Pro Max A20 Pro chip + variable-aperture + smaller Dynamic Island did 50%+ of total revenue. Mac $10.8B +24% fastest growth in 2 years, full FY Mac $37.9B vs $33.7B last year. Services $31.6B ATH +10% but slowing.
Losers: iPad $6.2B -11% YoY, Wearables $8.3B -8% YoY — Apple blamed tough compare vs Watch SE 3 & AirPods Pro 3 launch last year. And these Q4 numbers ended Sept 27 — so M6 iMac, OLED iPad mini, HomeView smart-home push are NOT even in this quarter. That's the setup for Dec quarter 7-10% growth guide.
Crypto angle? When Mag7 wobbles like this, risk appetite rotates. $RBTC held $114K as Apple sold off, $ETH DeFi TVL rose, and SOL mobile Saga sales actually spiked on Apple Services strength. Tech = liquidity = crypto beta.
This was a beat with a warning label.
Hashtags:
#applereportsmixedresults #applereportsmixedresults Pro #TechStocksToday #AAPLStock#applereportsmixedresults
#applereportsmixedresults is NOT what headline says — Apple just played the best smoke-and-mirrors quarter of 2026
Everyone saw $114.5B revenue +12% YoY, record September quarter, beat $113.39B est. But here's what 90% missed:
The $0.05 tariff trick: EPS $2.10 beat $1.99, but $0.05 came from a one-time tariff refund.
Gross margin 47.9% beat 47.5%, but 1% point was that same refund. Strip it and true margin is ∼46.9%. That's why AAPL dropped ∼3% after-hours despite a beat — guidance for Q1 2027 is 45-46% with component & AI cost pressure.
Insider split no one talks about: This was new CEO John Ternus' FIRST earnings call. iPhone $57.6B +17% record with iPhone 18 Pro / Pro Max A20 Pro chip + variable-aperture + smaller Dynamic Island did 50%+ of total revenue. Mac $10.8B +24% fastest growth in 2 years, full FY Mac $37.9B vs $33.7B last year. Services $31.6B ATH +10% but slowing.
Losers: iPad $6.2B -11% YoY, Wearables $8.3B -8% YoY — Apple blamed tough compare vs Watch SE 3 & AirPods Pro 3 launch last year. And these Q4 numbers ended Sept 27 — so M6 iMac, OLED iPad mini, HomeView smart-home push are NOT even in this quarter. That's the setup for Dec quarter 7-10% growth guide.
Crypto angle? When Mag7 wobbles like this, risk appetite rotates. $RBTC held $114K as Apple sold off, $ETH DeFi TVL rose, and SOL mobile Saga sales actually spiked on Apple Services strength. Tech = liquidity = crypto beta.
This was a beat with a warning label.
Hashtags:
#applereportsmixedresults #applereportsmixedresults Pro #TechStocksToday #AAPLStock#applereportsmixedresults
Everyone saw $114.5B revenue +12% YoY, record September quarter, beat $113.39B est. But here's what 90% missed:
The $0.05 tariff trick: EPS $2.10 beat $1.99, but $0.05 came from a one-time tariff refund.
Gross margin 47.9% beat 47.5%, but 1% point was that same refund. Strip it and true margin is ∼46.9%. That's why AAPL dropped ∼3% after-hours despite a beat — guidance for Q1 2027 is 45-46% with component & AI cost pressure.
Insider split no one talks about: This was new CEO John Ternus' FIRST earnings call. iPhone $57.6B +17% record with iPhone 18 Pro / Pro Max A20 Pro chip + variable-aperture + smaller Dynamic Island did 50%+ of total revenue. Mac $10.8B +24% fastest growth in 2 years, full FY Mac $37.9B vs $33.7B last year. Services $31.6B ATH +10% but slowing.
Losers: iPad $6.2B -11% YoY, Wearables $8.3B -8% YoY — Apple blamed tough compare vs Watch SE 3 & AirPods Pro 3 launch last year. And these Q4 numbers ended Sept 27 — so M6 iMac, OLED iPad mini, HomeView smart-home push are NOT even in this quarter. That's the setup for Dec quarter 7-10% growth guide.
Crypto angle? When Mag7 wobbles like this, risk appetite rotates. $RBTC held $114K as Apple sold off, $ETH DeFi TVL rose, and SOL mobile Saga sales actually spiked on Apple Services strength. Tech = liquidity = crypto beta.
This was a beat with a warning label.
Hashtags:
#applereportsmixedresults #applereportsmixedresults Pro #TechStocksToday #AAPLStock#applereportsmixedresults
1
481


·
--
Verified
Apple delivered better than expected earnings, yet its shares fell around 3% in after hours trading. So, what went wrong?
Revenue increased 12% year over year to $114.5 billion, while EPS reached $2.10, beating estimates of $1.99. iPhone revenue grew 17%, and Mac sales jumped 24%.
But investors are looking beyond strong quarterly results and focusing on future profitability.
Apple expects gross margins of just 46% for the current quarter, below market expectations. Rising memory chip prices, driven by AI data center demand, and the growing costs of running its new Siri AI tools are putting pressure on margins.
The bigger question is. Can Apple continue growing without sacrificing profitability?
Trading at around 36 times forward earnings, expectations remain high. Strong sales alone may no longer be enough to satisfy investors.
Apple's biggest challenge now is staying competitive in the AI race while protecting its profit margins.
#applereportsmixedresults $AAPLB
{spot}(AAPLBUSDT)
Apple delivered better than expected earnings, yet its shares fell around 3% in after hours trading. So, what went wrong?
Revenue increased 12% year over year to $114.5 billion, while EPS reached $2.10, beating estimates of $1.99. iPhone revenue grew 17%, and Mac sales jumped 24%.
But investors are looking beyond strong quarterly results and focusing on future profitability.
Apple expects gross margins of just 46% for the current quarter, below market expectations. Rising memory chip prices, driven by AI data center demand, and the growing costs of running its new Siri AI tools are putting pressure on margins.
The bigger question is. Can Apple continue growing without sacrificing profitability?
Trading at around 36 times forward earnings, expectations remain high. Strong sales alone may no longer be enough to satisfy investors.
Apple's biggest challenge now is staying competitive in the AI race while protecting its profit margins.
#applereportsmixedresults $AAPLB
Revenue increased 12% year over year to $114.5 billion, while EPS reached $2.10, beating estimates of $1.99. iPhone revenue grew 17%, and Mac sales jumped 24%.
But investors are looking beyond strong quarterly results and focusing on future profitability.
Apple expects gross margins of just 46% for the current quarter, below market expectations. Rising memory chip prices, driven by AI data center demand, and the growing costs of running its new Siri AI tools are putting pressure on margins.
The bigger question is. Can Apple continue growing without sacrificing profitability?
Trading at around 36 times forward earnings, expectations remain high. Strong sales alone may no longer be enough to satisfy investors.
Apple's biggest challenge now is staying competitive in the AI race while protecting its profit margins.
#applereportsmixedresults $AAPLB
1
638
💼 Not Every Segment Is Growing
Apple delivered strong overall revenue, but iPad revenue declined 10% year over year. Different product categories are showing different growth patterns. $AAPL
#applereportsmixedresults
💼 Not Every Segment Is Growing
Apple delivered strong overall revenue, but iPad revenue declined 10% year over year. Different product categories are showing different growth patterns. $AAPL
#applereportsmixedresults
Apple delivered strong overall revenue, but iPad revenue declined 10% year over year. Different product categories are showing different growth patterns. $AAPL
#applereportsmixedresults
19
The Pressure Behind Profits
Strong earnings do not remove every challenge. Rising memory costs and supply constraints could put pressure on Apple's upcoming quarterly margins. $AAPL
#applereportsmixedresults
The Pressure Behind Profits
Strong earnings do not remove every challenge. Rising memory costs and supply constraints could put pressure on Apple's upcoming quarterly margins. $AAPL
#applereportsmixedresults
Strong earnings do not remove every challenge. Rising memory costs and supply constraints could put pressure on Apple's upcoming quarterly margins. $AAPL
#applereportsmixedresults
21
🍏 Strong iPhone Performance
Apple reported $114.5 billion in quarterly revenue, up 12% year over year. iPhone revenue reached a September-quarter record, showing continued demand for its flagship products. $AAPL
#applereportsmixedresults
🍏 Strong iPhone Performance
Apple reported $114.5 billion in quarterly revenue, up 12% year over year. iPhone revenue reached a September-quarter record, showing continued demand for its flagship products. $AAPL
#applereportsmixedresults
Apple reported $114.5 billion in quarterly revenue, up 12% year over year. iPhone revenue reached a September-quarter record, showing continued demand for its flagship products. $AAPL
#applereportsmixedresults
13
🔎 What Comes Next for Apple?
Apple expects December-quarter revenue growth of 7%–10%, while forecasting a gross margin of 45%–46%. The next quarter will test its ability to balance demand, costs and profitability. $AAPL $BTC
#applereportsmixedresults
🔎 What Comes Next for Apple?
Apple expects December-quarter revenue growth of 7%–10%, while forecasting a gross margin of 45%–46%. The next quarter will test its ability to balance demand, costs and profitability. $AAPL $BTC
#applereportsmixedresults
Apple expects December-quarter revenue growth of 7%–10%, while forecasting a gross margin of 45%–46%. The next quarter will test its ability to balance demand, costs and profitability. $AAPL $BTC
#applereportsmixedresults
17
Article
Apple Reports Mixed Results Record:#AppleReportsMixedResults
Apple Delivers Record Revenue, but Rising Costs Cloud Its Earnings Outlook
Apple’s latest earnings beat Wall Street expectations, yet rising memory prices, supply constraints and a challenging holiday-quarter outlook are raising fresh questions about the company’s profitability.
Apple has delivered another record-breaking quarter, but the technology giant’s latest financial results reveal a more complicated picture beneath the headline numbers.
The company reported fiscal fourth-quarter revenue of $114.5 billion for the quarter ended September 26, 2026, representing a 12% increase from a year earlier. Earnings per share reached $2.10, exceeding analyst expectations, while net income climbed to $30.71 billion.
The results mark a strong start for CEO John Ternus, who took over from Tim Cook in September. However, investors are weighing Apple’s impressive sales performance against rising production costs and growing uncertainty about its profit margins.
iPhone remains Apple’s biggest growth engine
The iPhone continued to lead Apple’s financial performance, generating $57.6 billion in revenue, up approximately 17% year over year.
Services revenue also reached a new record of $31.6 billion, highlighting the continued importance of Apple’s ecosystem of subscriptions and digital services. Mac revenue delivered another positive surprise, while several other product categories struggled to keep pace.
The company’s performance demonstrates that demand for its premium devices remains resilient, even as consumers and businesses face a challenging economic environment.
The hidden pressure behind the earnings beat
Despite the strong headline figures, Apple faces a growing cost challenge.
Higher memory prices are putting pressure on profitability, while expenses associated with the development and rollout of Siri’s AI capabilities are adding to the company’s spending.
Apple reported a gross margin of 47.9% for the September quarter, but management expects that figure to fall to between 45% and 46% in the December quarter.
The company also benefited from tariff refunds during the latest reporting period, which added approximately $0.05 to earnings per share. This means investors must look beyond the headline earnings beat to understand the underlying strength of Apple’s business.
Holiday quarter becomes the real test
Apple expects revenue growth of approximately 7% to 10% year over year for the December quarter, traditionally one of its most important sales periods.
The outlook suggests that demand remains healthy, but rising component costs and supply limitations could make it more difficult for Apple to translate higher sales into stronger profits.
For investors, the key question is no longer simply whether Apple can sell more devices. It is whether the company can protect its margins while continuing to invest in artificial intelligence and maintain its competitive position.
What it means for the market
Apple’s latest results reinforce the strength of its consumer business, but they also highlight a broader challenge facing the technology sector: strong demand does not automatically translate into expanding profit margins.
The company’s ability to manage memory costs, maintain product availability and turn AI investments into commercially valuable services will be crucial in the months ahead.
Bottom line: Apple’s earnings were stronger than expected, but the market now has to decide whether record revenue can overcome rising costs. The December quarter may provide the clearest indication of whether Apple’s growth story is entering another powerful phase—or facing a more difficult period.
This article is for informational purposes only and does not constitute investment advice.
Apple Reports Mixed Results Record:
#AppleReportsMixedResults
Apple Delivers Record Revenue, but Rising Costs Cloud Its Earnings Outlook
Apple’s latest earnings beat Wall Street expectations, yet rising memory prices, supply constraints and a challenging holiday-quarter outlook are raising fresh questions about the company’s profitability.
Apple has delivered another record-breaking quarter, but the technology giant’s latest financial results reveal a more complicated picture beneath the headline numbers.
The company reported fiscal fourth-quarter revenue of $114.5 billion for the quarter ended September 26, 2026, representing a 12% increase from a year earlier. Earnings per share reached $2.10, exceeding analyst expectations, while net income climbed to $30.71 billion.
The results mark a strong start for CEO John Ternus, who took over from Tim Cook in September. However, investors are weighing Apple’s impressive sales performance against rising production costs and growing uncertainty about its profit margins.
iPhone remains Apple’s biggest growth engine
The iPhone continued to lead Apple’s financial performance, generating $57.6 billion in revenue, up approximately 17% year over year.
Services revenue also reached a new record of $31.6 billion, highlighting the continued importance of Apple’s ecosystem of subscriptions and digital services. Mac revenue delivered another positive surprise, while several other product categories struggled to keep pace.
The company’s performance demonstrates that demand for its premium devices remains resilient, even as consumers and businesses face a challenging economic environment.
The hidden pressure behind the earnings beat
Despite the strong headline figures, Apple faces a growing cost challenge.
Higher memory prices are putting pressure on profitability, while expenses associated with the development and rollout of Siri’s AI capabilities are adding to the company’s spending.
Apple reported a gross margin of 47.9% for the September quarter, but management expects that figure to fall to between 45% and 46% in the December quarter.
The company also benefited from tariff refunds during the latest reporting period, which added approximately $0.05 to earnings per share. This means investors must look beyond the headline earnings beat to understand the underlying strength of Apple’s business.
Holiday quarter becomes the real test
Apple expects revenue growth of approximately 7% to 10% year over year for the December quarter, traditionally one of its most important sales periods.
The outlook suggests that demand remains healthy, but rising component costs and supply limitations could make it more difficult for Apple to translate higher sales into stronger profits.
For investors, the key question is no longer simply whether Apple can sell more devices. It is whether the company can protect its margins while continuing to invest in artificial intelligence and maintain its competitive position.
What it means for the market
Apple’s latest results reinforce the strength of its consumer business, but they also highlight a broader challenge facing the technology sector: strong demand does not automatically translate into expanding profit margins.
The company’s ability to manage memory costs, maintain product availability and turn AI investments into commercially valuable services will be crucial in the months ahead.
Bottom line: Apple’s earnings were stronger than expected, but the market now has to decide whether record revenue can overcome rising costs. The December quarter may provide the clearest indication of whether Apple’s growth story is entering another powerful phase—or facing a more difficult period.
This article is for informational purposes only and does not constitute investment advice.
Apple Delivers Record Revenue, but Rising Costs Cloud Its Earnings Outlook
Apple’s latest earnings beat Wall Street expectations, yet rising memory prices, supply constraints and a challenging holiday-quarter outlook are raising fresh questions about the company’s profitability.
Apple has delivered another record-breaking quarter, but the technology giant’s latest financial results reveal a more complicated picture beneath the headline numbers.
The company reported fiscal fourth-quarter revenue of $114.5 billion for the quarter ended September 26, 2026, representing a 12% increase from a year earlier. Earnings per share reached $2.10, exceeding analyst expectations, while net income climbed to $30.71 billion.
The results mark a strong start for CEO John Ternus, who took over from Tim Cook in September. However, investors are weighing Apple’s impressive sales performance against rising production costs and growing uncertainty about its profit margins.
iPhone remains Apple’s biggest growth engine
The iPhone continued to lead Apple’s financial performance, generating $57.6 billion in revenue, up approximately 17% year over year.
Services revenue also reached a new record of $31.6 billion, highlighting the continued importance of Apple’s ecosystem of subscriptions and digital services. Mac revenue delivered another positive surprise, while several other product categories struggled to keep pace.
The company’s performance demonstrates that demand for its premium devices remains resilient, even as consumers and businesses face a challenging economic environment.
The hidden pressure behind the earnings beat
Despite the strong headline figures, Apple faces a growing cost challenge.
Higher memory prices are putting pressure on profitability, while expenses associated with the development and rollout of Siri’s AI capabilities are adding to the company’s spending.
Apple reported a gross margin of 47.9% for the September quarter, but management expects that figure to fall to between 45% and 46% in the December quarter.
The company also benefited from tariff refunds during the latest reporting period, which added approximately $0.05 to earnings per share. This means investors must look beyond the headline earnings beat to understand the underlying strength of Apple’s business.
Holiday quarter becomes the real test
Apple expects revenue growth of approximately 7% to 10% year over year for the December quarter, traditionally one of its most important sales periods.
The outlook suggests that demand remains healthy, but rising component costs and supply limitations could make it more difficult for Apple to translate higher sales into stronger profits.
For investors, the key question is no longer simply whether Apple can sell more devices. It is whether the company can protect its margins while continuing to invest in artificial intelligence and maintain its competitive position.
What it means for the market
Apple’s latest results reinforce the strength of its consumer business, but they also highlight a broader challenge facing the technology sector: strong demand does not automatically translate into expanding profit margins.
The company’s ability to manage memory costs, maintain product availability and turn AI investments into commercially valuable services will be crucial in the months ahead.
Bottom line: Apple’s earnings were stronger than expected, but the market now has to decide whether record revenue can overcome rising costs. The December quarter may provide the clearest indication of whether Apple’s growth story is entering another powerful phase—or facing a more difficult period.
This article is for informational purposes only and does not constitute investment advice.
13

·
--
Bullish
#applereportsmixedresults
🚨 APPLE'S LATEST EARNINGS ARE IN — BILLIONS GENERATED, BUT INVESTORS AREN'T FULLY CONVINCED! 🍎👀
Apple has reported mixed financial results, leaving Wall Street questioning whether the tech giant can maintain its impressive growth momentum.
🔥 What Happened?
💰 Revenue showed solid year-over-year growth.
📈 Earnings performance delivered encouraging signals.
🍎 iPhone sales remained a major contributor.
🚀 Apple's Services business continued to demonstrate strength.
⚠️ However, rising costs and profitability concerns are keeping investors cautious.
📊 Why It Matters
Apple remains one of the biggest players in global technology, but strong revenue alone isn't enough to guarantee a stock rally.
Investors are watching three major factors:
Apple's ability to grow iPhone demand.
Whether AI features can create a new revenue opportunity.
Whether rising expenses will squeeze profit margins.
👀 THE BIG QUESTION: Can Apple turn its AI ambitions into its next major growth engine, or is its best growth phase already behind it?
#Apple #stockmarket #technews $AAPLB
{spot}(AAPLBUSDT)
#applereportsmixedresults
🚨 APPLE'S LATEST EARNINGS ARE IN — BILLIONS GENERATED, BUT INVESTORS AREN'T FULLY CONVINCED! 🍎👀
Apple has reported mixed financial results, leaving Wall Street questioning whether the tech giant can maintain its impressive growth momentum.
🔥 What Happened?
💰 Revenue showed solid year-over-year growth.
📈 Earnings performance delivered encouraging signals.
🍎 iPhone sales remained a major contributor.
🚀 Apple's Services business continued to demonstrate strength.
⚠️ However, rising costs and profitability concerns are keeping investors cautious.
📊 Why It Matters
Apple remains one of the biggest players in global technology, but strong revenue alone isn't enough to guarantee a stock rally.
Investors are watching three major factors:
Apple's ability to grow iPhone demand.
Whether AI features can create a new revenue opportunity.
Whether rising expenses will squeeze profit margins.
👀 THE BIG QUESTION: Can Apple turn its AI ambitions into its next major growth engine, or is its best growth phase already behind it?
#Apple #stockmarket #technews $AAPLB
🚨 APPLE'S LATEST EARNINGS ARE IN — BILLIONS GENERATED, BUT INVESTORS AREN'T FULLY CONVINCED! 🍎👀
Apple has reported mixed financial results, leaving Wall Street questioning whether the tech giant can maintain its impressive growth momentum.
🔥 What Happened?
💰 Revenue showed solid year-over-year growth.
📈 Earnings performance delivered encouraging signals.
🍎 iPhone sales remained a major contributor.
🚀 Apple's Services business continued to demonstrate strength.
⚠️ However, rising costs and profitability concerns are keeping investors cautious.
📊 Why It Matters
Apple remains one of the biggest players in global technology, but strong revenue alone isn't enough to guarantee a stock rally.
Investors are watching three major factors:
Apple's ability to grow iPhone demand.
Whether AI features can create a new revenue opportunity.
Whether rising expenses will squeeze profit margins.
👀 THE BIG QUESTION: Can Apple turn its AI ambitions into its next major growth engine, or is its best growth phase already behind it?
#Apple #stockmarket #technews $AAPLB
183

·
--
#AppleReportsMixedResults
📊 $AAPL just dropped its Q4 numbers under new CEO John Ternus!
Revenue hit a September-quarter record $114.5B (+12%), EPS $2.10 (+14%), iPhone and Services both set records. Full-year revenue also smashed records at ~$479B.
But… lower margin guidance for the holiday quarter (memory costs rising) and weaker iPad/Wearables sent the stock sliding after hours. Classic mixed bag.
Strong iPhone demand and Services growth show the ecosystem is still rock-solid. Hitting records under a new CEO is impressive. The margin pressure is real though — rising costs could squeeze profits short-term. Long-term, $AAPL ’s cash machine and loyalty remain unmatched. Watch the holiday guidance closely for the next move.
Bullish or cautious on $AAPL ? Drop your thoughts 👇
#Apple #AAPL #Earnings #TechStocks #CryptoMarkets
#AppleReportsMixedResults
📊 $AAPL just dropped its Q4 numbers under new CEO John Ternus!
Revenue hit a September-quarter record $114.5B (+12%), EPS $2.10 (+14%), iPhone and Services both set records. Full-year revenue also smashed records at ~$479B.
But… lower margin guidance for the holiday quarter (memory costs rising) and weaker iPad/Wearables sent the stock sliding after hours. Classic mixed bag.
Strong iPhone demand and Services growth show the ecosystem is still rock-solid. Hitting records under a new CEO is impressive. The margin pressure is real though — rising costs could squeeze profits short-term. Long-term, $AAPL ’s cash machine and loyalty remain unmatched. Watch the holiday guidance closely for the next move.
Bullish or cautious on $AAPL ? Drop your thoughts 👇
#Apple #AAPL #Earnings #TechStocks #CryptoMarkets
📊 $AAPL just dropped its Q4 numbers under new CEO John Ternus!
Revenue hit a September-quarter record $114.5B (+12%), EPS $2.10 (+14%), iPhone and Services both set records. Full-year revenue also smashed records at ~$479B.
But… lower margin guidance for the holiday quarter (memory costs rising) and weaker iPad/Wearables sent the stock sliding after hours. Classic mixed bag.
Strong iPhone demand and Services growth show the ecosystem is still rock-solid. Hitting records under a new CEO is impressive. The margin pressure is real though — rising costs could squeeze profits short-term. Long-term, $AAPL ’s cash machine and loyalty remain unmatched. Watch the holiday guidance closely for the next move.
Bullish or cautious on $AAPL ? Drop your thoughts 👇
#Apple #AAPL #Earnings #TechStocks #CryptoMarkets
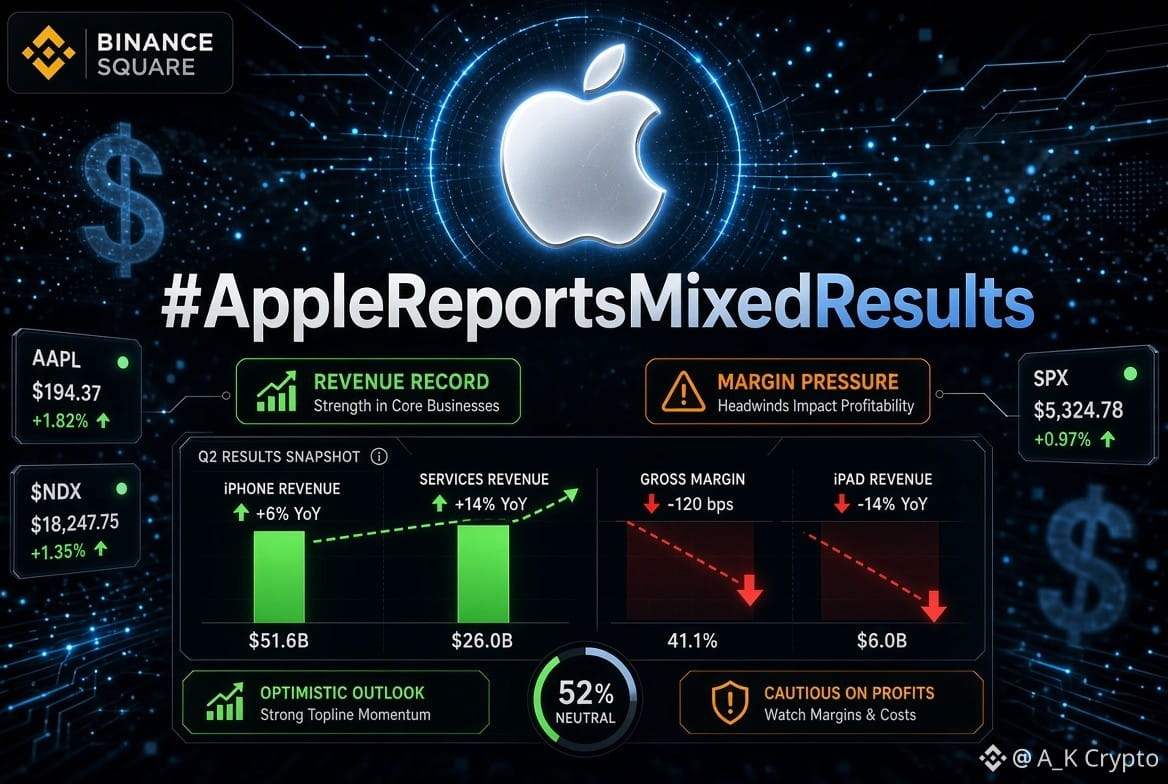
196
·
--
Verified
Apple's earnings are mixed. Sales look great. The outlook doesn't.
Revenue hit $114.5B, up 12%. iPhone did $57.6B, up 17%, with only eight days of iPhone 18 Pro sales in the quarter. Services set a new high too.
iPad missed, though. And the margin got a lift. About a point of that 47.9% came from tariff refunds.
Then the outlook. Apple expects December revenue up 7% to 10%, above what analysts expected. But it sees gross margin at 45% to 46%. The stock dropped on that.
It's John Ternus' first report as CEO. Demand is strong. Margins are the part I'd watch next quarter.
#AppleReportsMixedResults
Apple's earnings are mixed. Sales look great. The outlook doesn't.
Revenue hit $114.5B, up 12%. iPhone did $57.6B, up 17%, with only eight days of iPhone 18 Pro sales in the quarter. Services set a new high too.
iPad missed, though. And the margin got a lift. About a point of that 47.9% came from tariff refunds.
Then the outlook. Apple expects December revenue up 7% to 10%, above what analysts expected. But it sees gross margin at 45% to 46%. The stock dropped on that.
It's John Ternus' first report as CEO. Demand is strong. Margins are the part I'd watch next quarter.
#AppleReportsMixedResults
Revenue hit $114.5B, up 12%. iPhone did $57.6B, up 17%, with only eight days of iPhone 18 Pro sales in the quarter. Services set a new high too.
iPad missed, though. And the margin got a lift. About a point of that 47.9% came from tariff refunds.
Then the outlook. Apple expects December revenue up 7% to 10%, above what analysts expected. But it sees gross margin at 45% to 46%. The stock dropped on that.
It's John Ternus' first report as CEO. Demand is strong. Margins are the part I'd watch next quarter.
#AppleReportsMixedResults
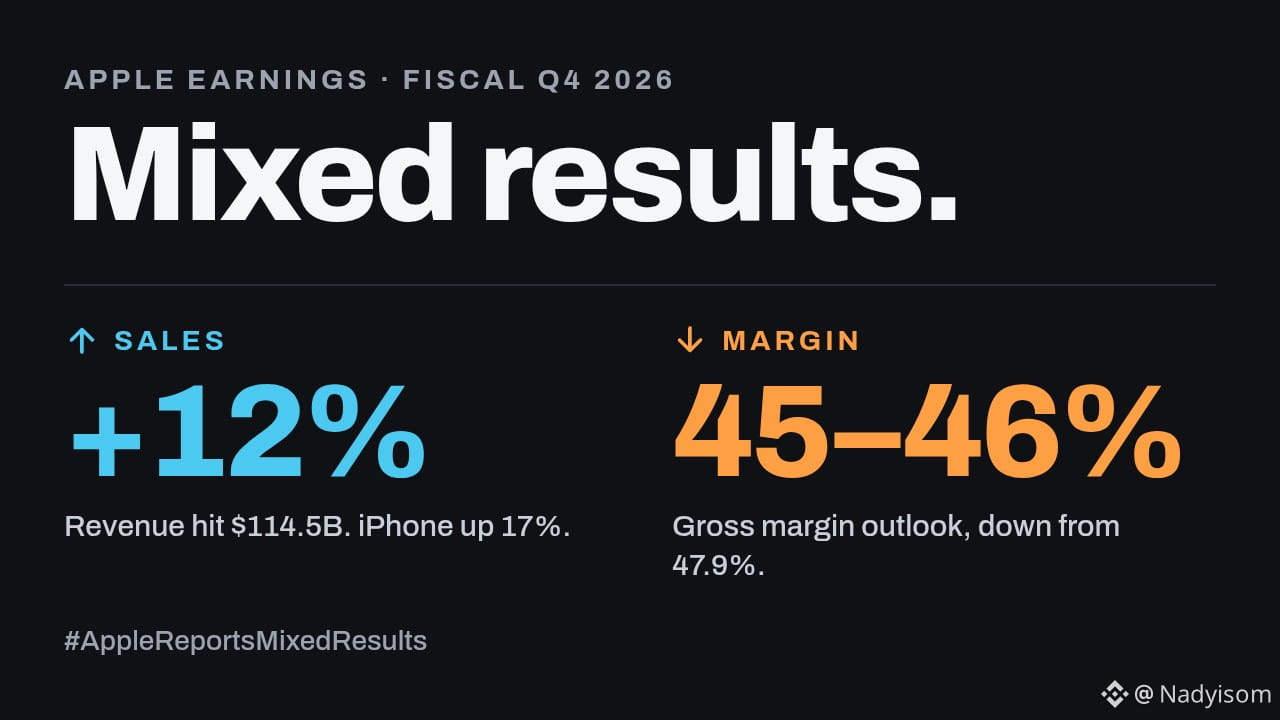
10
1.9k
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BinanceReopensWithdrawalsForMoreAssets
1.1M views
5,636 Discussing
2
#$2TWipedOutHedgeFundsFaceLiquidation
3 views
1 Discussing
3
#AnthropicIPOValuationDoubts
10,566 views
316 Discussing
4
#SouthKoreaDelaysCryptoTaxationUntil2029
0 views
0 Discussing
5
#HongKongPlansTaxIncentivesCoveringDigitalAssets
0 views
0 Discussing
6
#ECBTargetsDigitalEuroIssuanceIn2029
0 views
0 Discussing
7
#ChainalysisBreachExposedPasswordHashesAndLiveTokens
8 views
3 Discussing
8
#UkraineCentralBankOpposesCurrentCryptoAssetBill
665 views
35 Discussing
9
#CoreScientificExpectsToExitBitcoinMiningByYearEnd2026
247 views
8 Discussing
10
#USStocksSlipandCryptoMarketUnderBroadPressure
117,508 views
736 Discussing