
#creditcard:
creditcard:
10,839 views
31 Discussing
Hot
Latest
Hi, this post is for gamers
who are in Venezuela.
Binance has helped me a lot with virtual purchases thanks to its Binance virtual credit card, for example, in Call of Duty Mobile.
To get some CP, you need to use third-party websites that could be scams, but
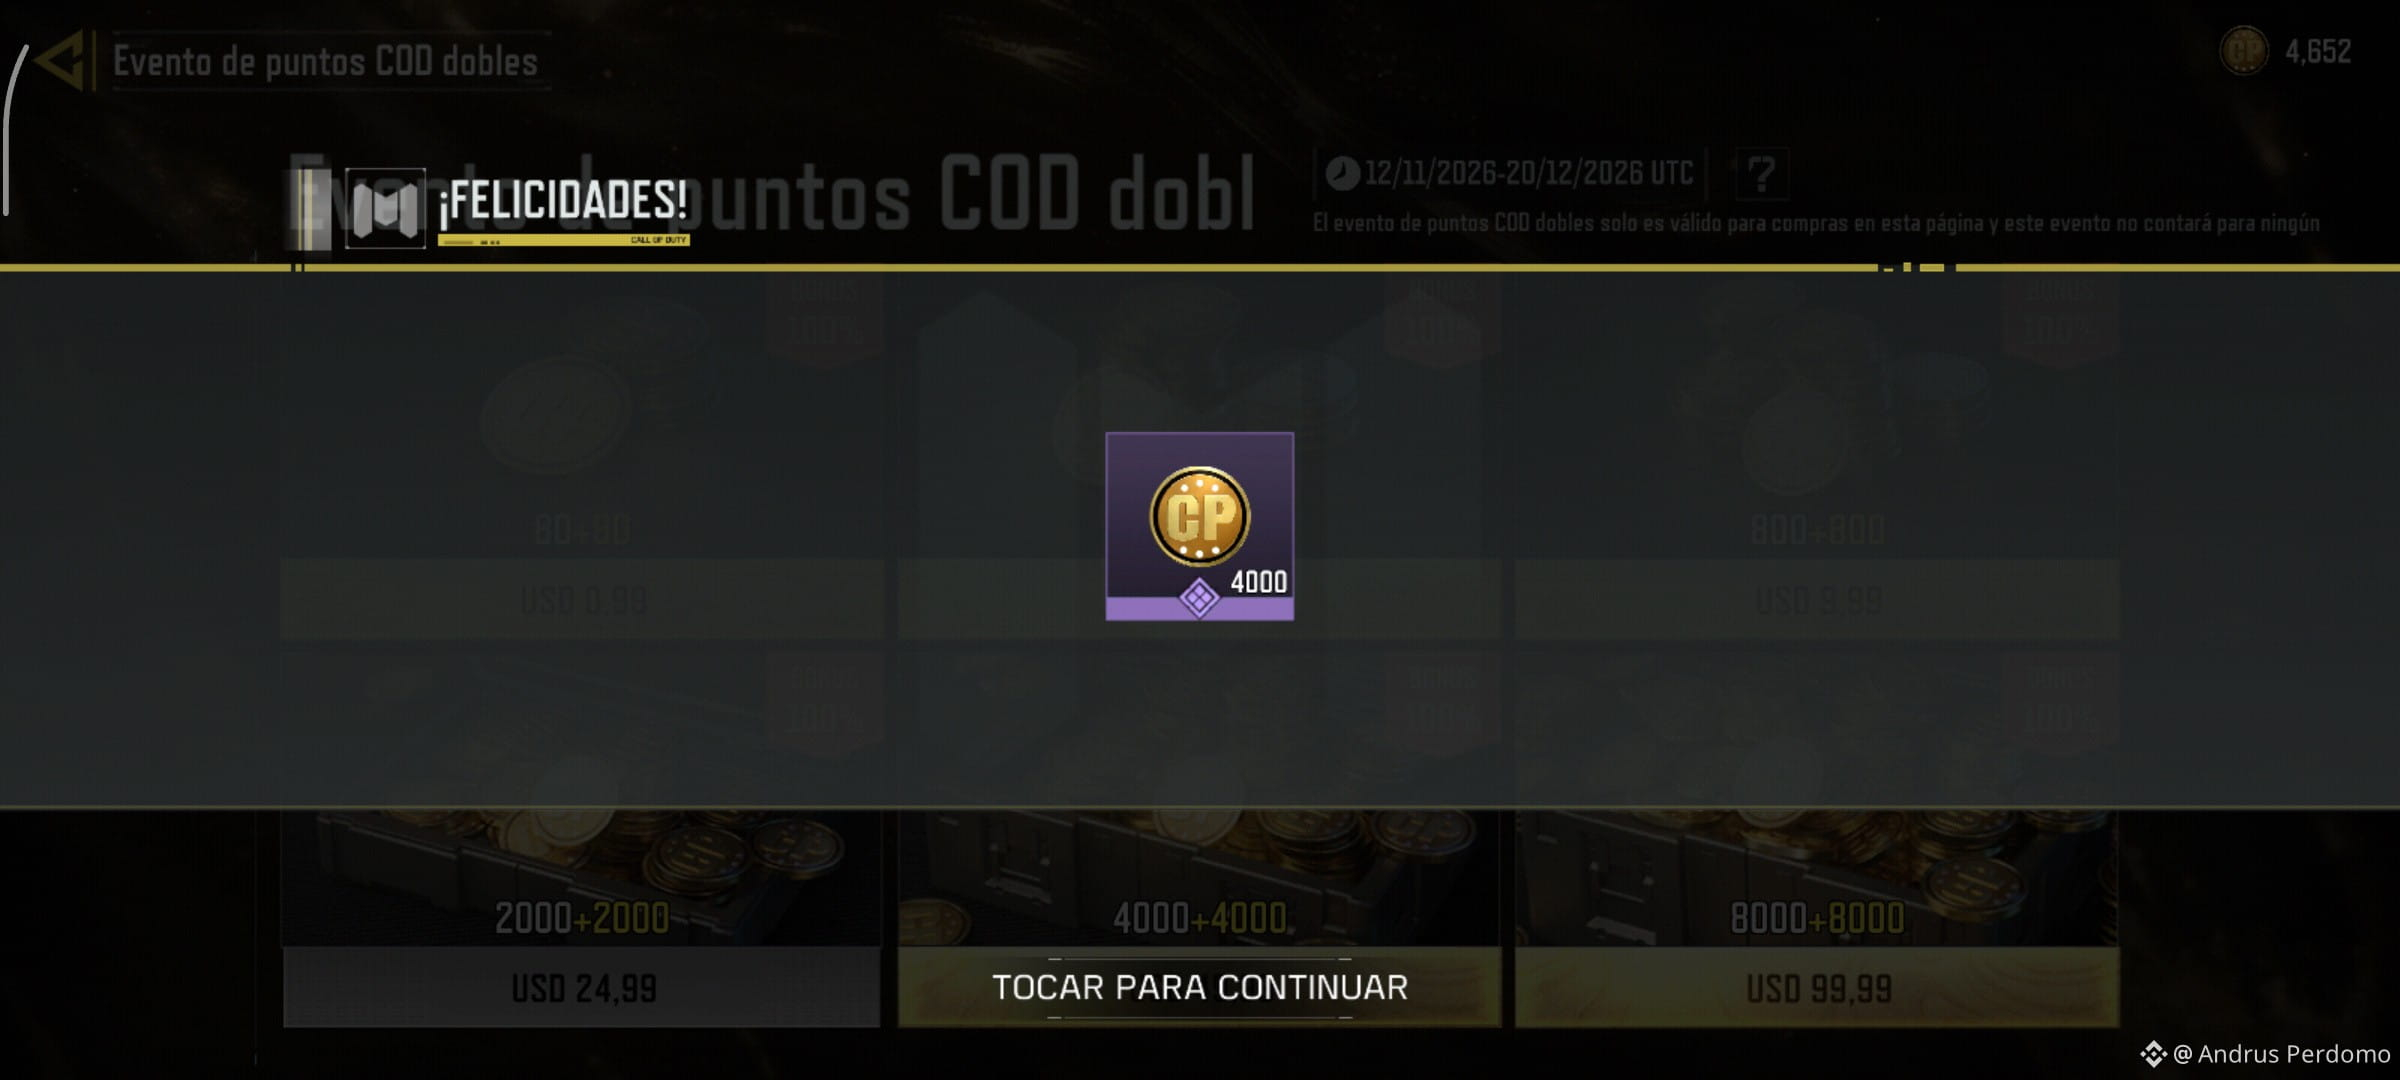
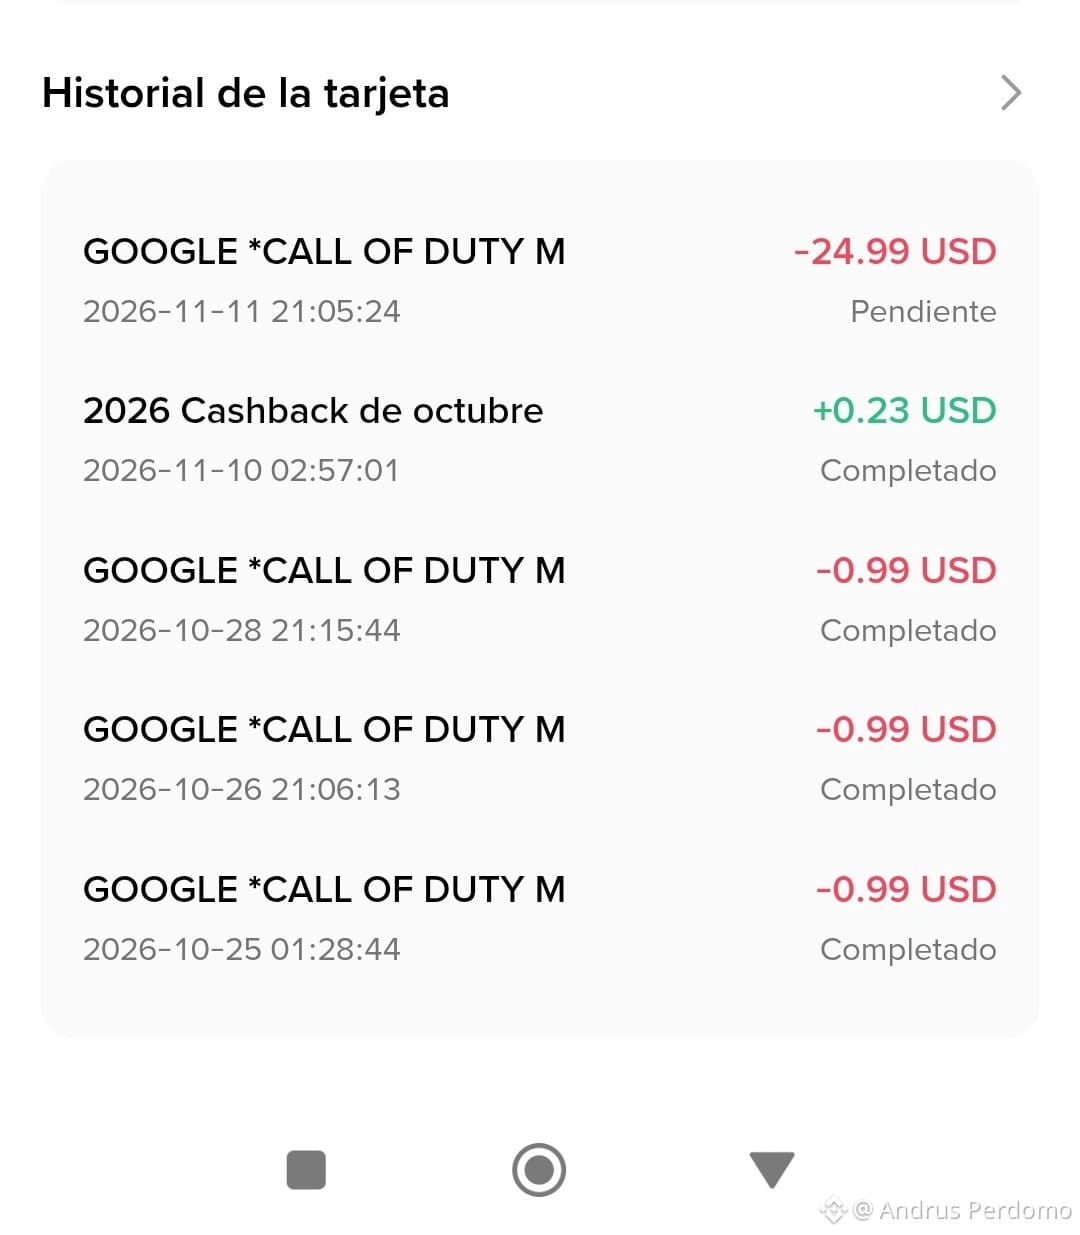
I have the Binance virtual credit card, so it's safer and faster to buy CP in the game without any problems. Get one and you'll see I'm not lying. Here's a little history of a purchase I made.#CreditCard: 😘
Hi, this post is for gamers
who are in Venezuela.
Binance has helped me a lot with virtual purchases thanks to its Binance virtual credit card, for example, in Call of Duty Mobile.
To get some CP, you need to use third-party websites that could be scams, but
I have the Binance virtual credit card, so it's safer and faster to buy CP in the game without any problems. Get one and you'll see I'm not lying. Here's a little history of a purchase I made.#CreditCard: 😘
who are in Venezuela.
Binance has helped me a lot with virtual purchases thanks to its Binance virtual credit card, for example, in Call of Duty Mobile.
To get some CP, you need to use third-party websites that could be scams, but
I have the Binance virtual credit card, so it's safer and faster to buy CP in the game without any problems. Get one and you'll see I'm not lying. Here's a little history of a purchase I made.#CreditCard: 😘
Sr Detective:
Quien gasta $25usd de madrazo en un juego para celular
1
1
466
·
--
Article
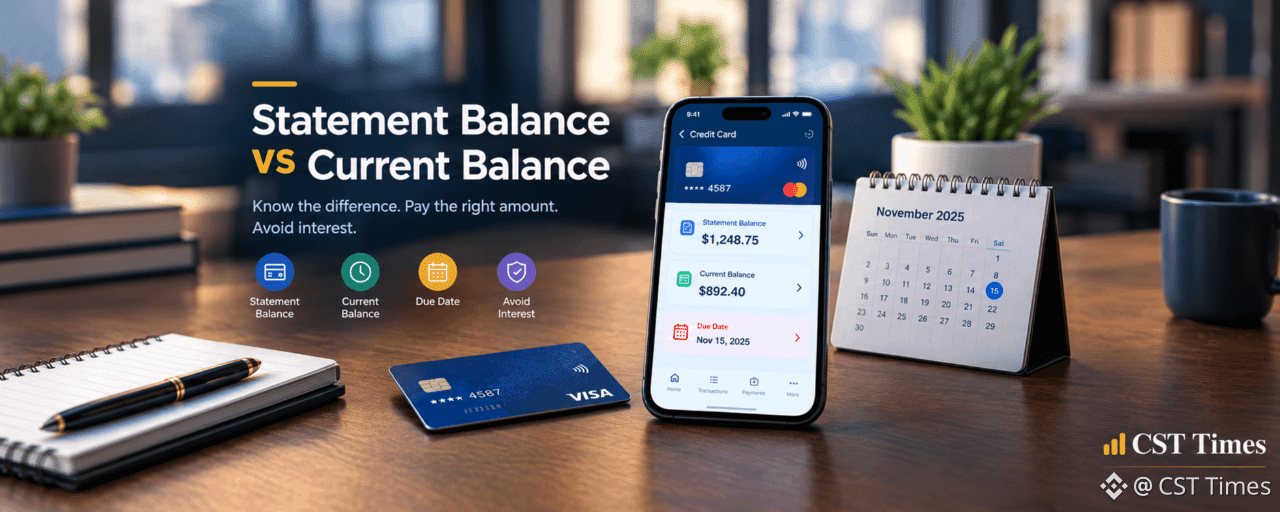
Statement Balance vs Current Balance: Why Your Credit Card Shows Two Different AmountsQuick Summary:
Have you ever opened your credit card app and noticed that your statement balance is different from your current balance?
It can be confusing, especially when you are trying to understand how much you actually need to pay.
The good news is that these two numbers serve different purposes.
What Is a Statement Balance?
Your statement balance is the amount you owed when your previous billing cycle ended. It reflects the transactions included in that billing statement.
This amount is important because it helps you understand what you need to pay by your due date. Depending on your card's terms and whether you carried a previous balance, paying the full statement balance on time generally helps you avoid interest on purchases.
What Is a Current Balance?
Your current balance shows the transactions posted to your account up to that point. It may include new purchases and payments made after your last statement was issued.
That is why your current balance can be higher or lower than your statement balance. The numbers can change as you use your card and make payments.
Which Balance Should You Pay?
This is where many cardholders become confused.
Paying your current balance may clear more of what you owe, but it is not always necessary to pay that full amount by the due date to avoid interest on purchases.
Your statement balance is usually the key figure to check. However, previous unpaid balances, interest charges and the terms of your card can affect what you actually owe.
It is also worth remembering that paying only the minimum amount does not generally mean the rest of your balance is interest-free.
Understand Your Credit Card Before Making a Payment
Knowing the difference between these balances can help you read your credit card statement more confidently and avoid common payment mistakes.
There are other details worth understanding, including what happens after a partial payment, how payment timing works, and why interest may sometimes appear even after you have paid.
At CST Times, we break down personal finance topics into practical, easy-to-understand guides to help readers make more informed financial decisions.
For the full explanation, payment examples, and five practical rules to help you decide what to pay, read our complete guide here:
Note: Credit card terms and interest rules vary by issuer. Check your card agreement or contact your card provider if you are unsure about the amount due.
#PersonalFinance #CreditCard: #MoneyTips #FinancialLiberty #CSTTimes
Statement Balance vs Current Balance: Why Your Credit Card Shows Two Different Amounts
Quick Summary:
Have you ever opened your credit card app and noticed that your statement balance is different from your current balance?
It can be confusing, especially when you are trying to understand how much you actually need to pay.
The good news is that these two numbers serve different purposes.
What Is a Statement Balance?
Your statement balance is the amount you owed when your previous billing cycle ended. It reflects the transactions included in that billing statement.
This amount is important because it helps you understand what you need to pay by your due date. Depending on your card's terms and whether you carried a previous balance, paying the full statement balance on time generally helps you avoid interest on purchases.
What Is a Current Balance?
Your current balance shows the transactions posted to your account up to that point. It may include new purchases and payments made after your last statement was issued.
That is why your current balance can be higher or lower than your statement balance. The numbers can change as you use your card and make payments.
Which Balance Should You Pay?
This is where many cardholders become confused.
Paying your current balance may clear more of what you owe, but it is not always necessary to pay that full amount by the due date to avoid interest on purchases.
Your statement balance is usually the key figure to check. However, previous unpaid balances, interest charges and the terms of your card can affect what you actually owe.
It is also worth remembering that paying only the minimum amount does not generally mean the rest of your balance is interest-free.
Understand Your Credit Card Before Making a Payment
Knowing the difference between these balances can help you read your credit card statement more confidently and avoid common payment mistakes.
There are other details worth understanding, including what happens after a partial payment, how payment timing works, and why interest may sometimes appear even after you have paid.
At CST Times, we break down personal finance topics into practical, easy-to-understand guides to help readers make more informed financial decisions.
For the full explanation, payment examples, and five practical rules to help you decide what to pay, read our complete guide here:
Note: Credit card terms and interest rules vary by issuer. Check your card agreement or contact your card provider if you are unsure about the amount due.
#PersonalFinance #CreditCard: #MoneyTips #FinancialLiberty #CSTTimes
Have you ever opened your credit card app and noticed that your statement balance is different from your current balance?
It can be confusing, especially when you are trying to understand how much you actually need to pay.
The good news is that these two numbers serve different purposes.
What Is a Statement Balance?
Your statement balance is the amount you owed when your previous billing cycle ended. It reflects the transactions included in that billing statement.
This amount is important because it helps you understand what you need to pay by your due date. Depending on your card's terms and whether you carried a previous balance, paying the full statement balance on time generally helps you avoid interest on purchases.
What Is a Current Balance?
Your current balance shows the transactions posted to your account up to that point. It may include new purchases and payments made after your last statement was issued.
That is why your current balance can be higher or lower than your statement balance. The numbers can change as you use your card and make payments.
Which Balance Should You Pay?
This is where many cardholders become confused.
Paying your current balance may clear more of what you owe, but it is not always necessary to pay that full amount by the due date to avoid interest on purchases.
Your statement balance is usually the key figure to check. However, previous unpaid balances, interest charges and the terms of your card can affect what you actually owe.
It is also worth remembering that paying only the minimum amount does not generally mean the rest of your balance is interest-free.
Understand Your Credit Card Before Making a Payment
Knowing the difference between these balances can help you read your credit card statement more confidently and avoid common payment mistakes.
There are other details worth understanding, including what happens after a partial payment, how payment timing works, and why interest may sometimes appear even after you have paid.
At CST Times, we break down personal finance topics into practical, easy-to-understand guides to help readers make more informed financial decisions.
For the full explanation, payment examples, and five practical rules to help you decide what to pay, read our complete guide here:
Note: Credit card terms and interest rules vary by issuer. Check your card agreement or contact your card provider if you are unsure about the amount due.
#PersonalFinance #CreditCard: #MoneyTips #FinancialLiberty #CSTTimes
1
100

·
--
#Write2Earn
UPDATES🚨🚨: Las Vegas businesses adopt Bitcoin payments to cut credit card fees.
#lasvegas #bitcoin #CreditCard: $BTC
#Write2Earn
UPDATES🚨🚨: Las Vegas businesses adopt Bitcoin payments to cut credit card fees.
#lasvegas #bitcoin #CreditCard: $BTC
UPDATES🚨🚨: Las Vegas businesses adopt Bitcoin payments to cut credit card fees.
#lasvegas #bitcoin #CreditCard: $BTC
4
86
·
--
🚨 U.S. CREDIT CARD DEBT HITS RECORD
Total outstanding credit card balances have reached $1.25 TRILLION — nearly double the $660B level in 2013. $SOL
📊 What it signals:
• Rising consumer leverage
• Growing pressure from high interest rates
• Potential stress on household spending power$XRP
⚠️ Credit expansion can support short-term growth — but increases long-term financial risk.$ZAMA
🧠 When debt climbs while rates stay high, the economy becomes more fragile.
#CreditCard: #US #HotTrends
{spot}(ZAMAUSDT)
{spot}(XRPUSDT)
{spot}(SOLUSDT)
🚨 U.S. CREDIT CARD DEBT HITS RECORD
Total outstanding credit card balances have reached $1.25 TRILLION — nearly double the $660B level in 2013. $SOL
📊 What it signals:
• Rising consumer leverage
• Growing pressure from high interest rates
• Potential stress on household spending power$XRP
⚠️ Credit expansion can support short-term growth — but increases long-term financial risk.$ZAMA
🧠 When debt climbs while rates stay high, the economy becomes more fragile.
#CreditCard: #US #HotTrends
Total outstanding credit card balances have reached $1.25 TRILLION — nearly double the $660B level in 2013. $SOL
📊 What it signals:
• Rising consumer leverage
• Growing pressure from high interest rates
• Potential stress on household spending power$XRP
⚠️ Credit expansion can support short-term growth — but increases long-term financial risk.$ZAMA
🧠 When debt climbs while rates stay high, the economy becomes more fragile.
#CreditCard: #US #HotTrends
3
393

✅ In just six months of 2026, the use of crypto cards has already hit $4.3 billion, nearly matching the total volume recorded in 2025. It's projected to close the year at $10 billion.
🔹 Hackers made off with around $17 million by exploiting vulnerabilities in smart contracts, in a fresh incident impacting DeFi protocols.
🔹 Toss Bank has been testing the Solana network for transfers, in an experiment assessing its use in banking operations.
🔹 Bridges between crypto networks remain a weak point in DeFi, racking up multiple hacks due to design flaws and cross-chain verification issues.
#HackerAlert #defi #CreditCard: #tarjetascripto #ciberseguridad $SOL
✅ In just six months of 2026, the use of crypto cards has already hit $4.3 billion, nearly matching the total volume recorded in 2025. It's projected to close the year at $10 billion.
🔹 Hackers made off with around $17 million by exploiting vulnerabilities in smart contracts, in a fresh incident impacting DeFi protocols.
🔹 Toss Bank has been testing the Solana network for transfers, in an experiment assessing its use in banking operations.
🔹 Bridges between crypto networks remain a weak point in DeFi, racking up multiple hacks due to design flaws and cross-chain verification issues.
#HackerAlert #defi #CreditCard: #tarjetascripto #ciberseguridad $SOL
🔹 Hackers made off with around $17 million by exploiting vulnerabilities in smart contracts, in a fresh incident impacting DeFi protocols.
🔹 Toss Bank has been testing the Solana network for transfers, in an experiment assessing its use in banking operations.
🔹 Bridges between crypto networks remain a weak point in DeFi, racking up multiple hacks due to design flaws and cross-chain verification issues.
#HackerAlert #defi #CreditCard: #tarjetascripto #ciberseguridad $SOL
3
98
·
--

Jeeva_jvan
·
--
BullishCrypto is no longer the future… it’s happening now. 💳🔥
Spending crypto with the Binance Visa Card just feels different — fast, simple, and global. This is how Web3 connects to the real world.
BNB isn’t just a token… it’s utility. 💛
#BNB #Binance #Crypto #Web3 #FutureOfPayments $BNB
Spending crypto with the Binance Visa Card just feels different — fast, simple, and global. This is how Web3 connects to the real world.
BNB isn’t just a token… it’s utility. 💛
#BNB #Binance #Crypto #Web3 #FutureOfPayments $BNB
115
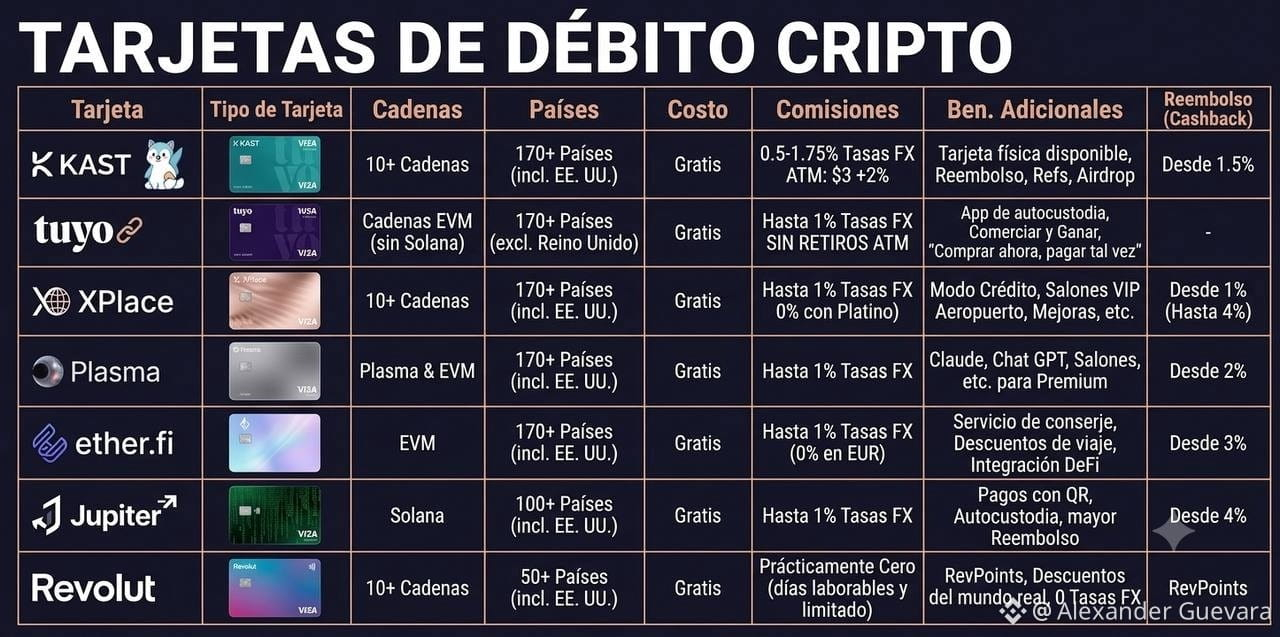
🟢🤑The best Crypto Credit Cards
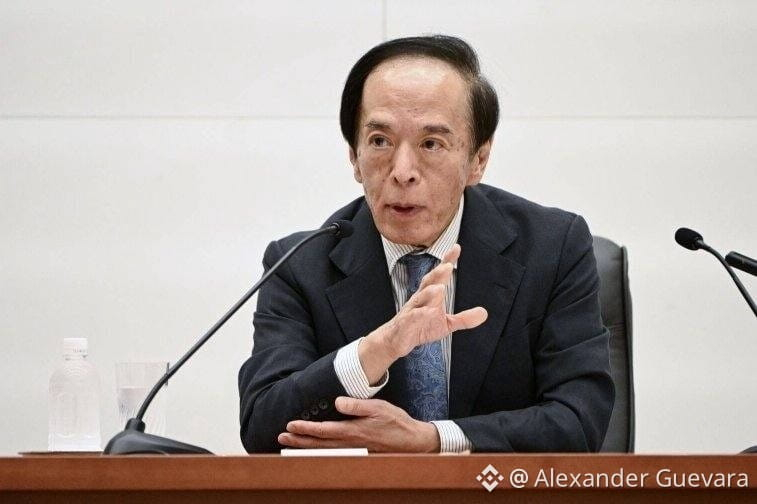
🤑WARNING: 🚨 The Bank of Japan is expected to hike rates to 1% on June 16, the highest level in 30 years.
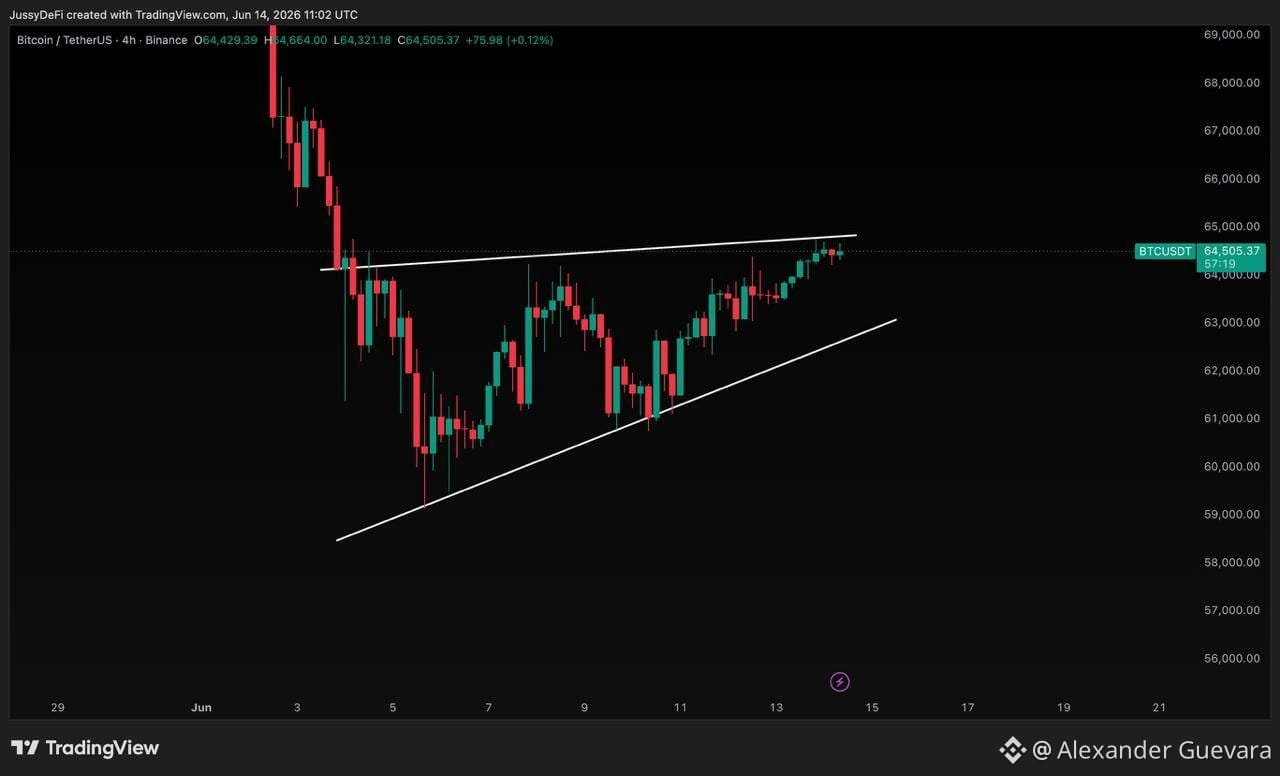
Next week will definitely be volatile for $BTC !
🤑If BTC closes June above $60,000
Then I would expect a small bounce in July/August and a final low in September/October, with Q1 of 2027 looking very bullish
Because we would basically be entering the bull market phase again in 2027
(Of course, I'll update if there are any changes)
#CreditCard: #BTC #inversioninteligente #Inversiones #japon
🟢🤑The best Crypto Credit Cards
🤑WARNING: 🚨 The Bank of Japan is expected to hike rates to 1% on June 16, the highest level in 30 years.
Next week will definitely be volatile for $BTC !
🤑If BTC closes June above $60,000
Then I would expect a small bounce in July/August and a final low in September/October, with Q1 of 2027 looking very bullish
Because we would basically be entering the bull market phase again in 2027
(Of course, I'll update if there are any changes)
#CreditCard: #BTC #inversioninteligente #Inversiones #japon
🤑WARNING: 🚨 The Bank of Japan is expected to hike rates to 1% on June 16, the highest level in 30 years.
Next week will definitely be volatile for $BTC !
🤑If BTC closes June above $60,000
Then I would expect a small bounce in July/August and a final low in September/October, with Q1 of 2027 looking very bullish
Because we would basically be entering the bull market phase again in 2027
(Of course, I'll update if there are any changes)
#CreditCard: #BTC #inversioninteligente #Inversiones #japon
3
61
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#WhatWillDriveCryptoandStocks’NextRebound?
24,099 views
427 Discussing
2
#Anthropic’s6xIPODemandSignalsPotentialRecordRaise
7,337 views
188 Discussing
3
#USSpotBitcoinETFsSee$1.56BYTDNetOutflows
0 views
0 Discussing
4
#HuangExitNvidiaStrategyInFocus
166,616 views
1,517 Discussing
5
#AnthropicRejectsIPODelayValuationinQuestion
786,389 views
5,688 Discussing
6
#HedgeFundsCMEBitcoinNetShortsFall89%
13,174 views
207 Discussing
7
#BitMineReports$6.3BNetLossForFiscal2026
23,569 views
187 Discussing
8
#TradFiForBeginners
563,790 views
3,947 Discussing
9
#SoFiExpandsSoFiUSDStablecoinToPolygon
8,065 views
120 Discussing
10
#TetherGoldXAUTCompletesKPMGAudit
11,472 views
130 Discussing