
#autoparts
autoparts
0 views
2 Discussing
Hot
Latest

·
--
Article
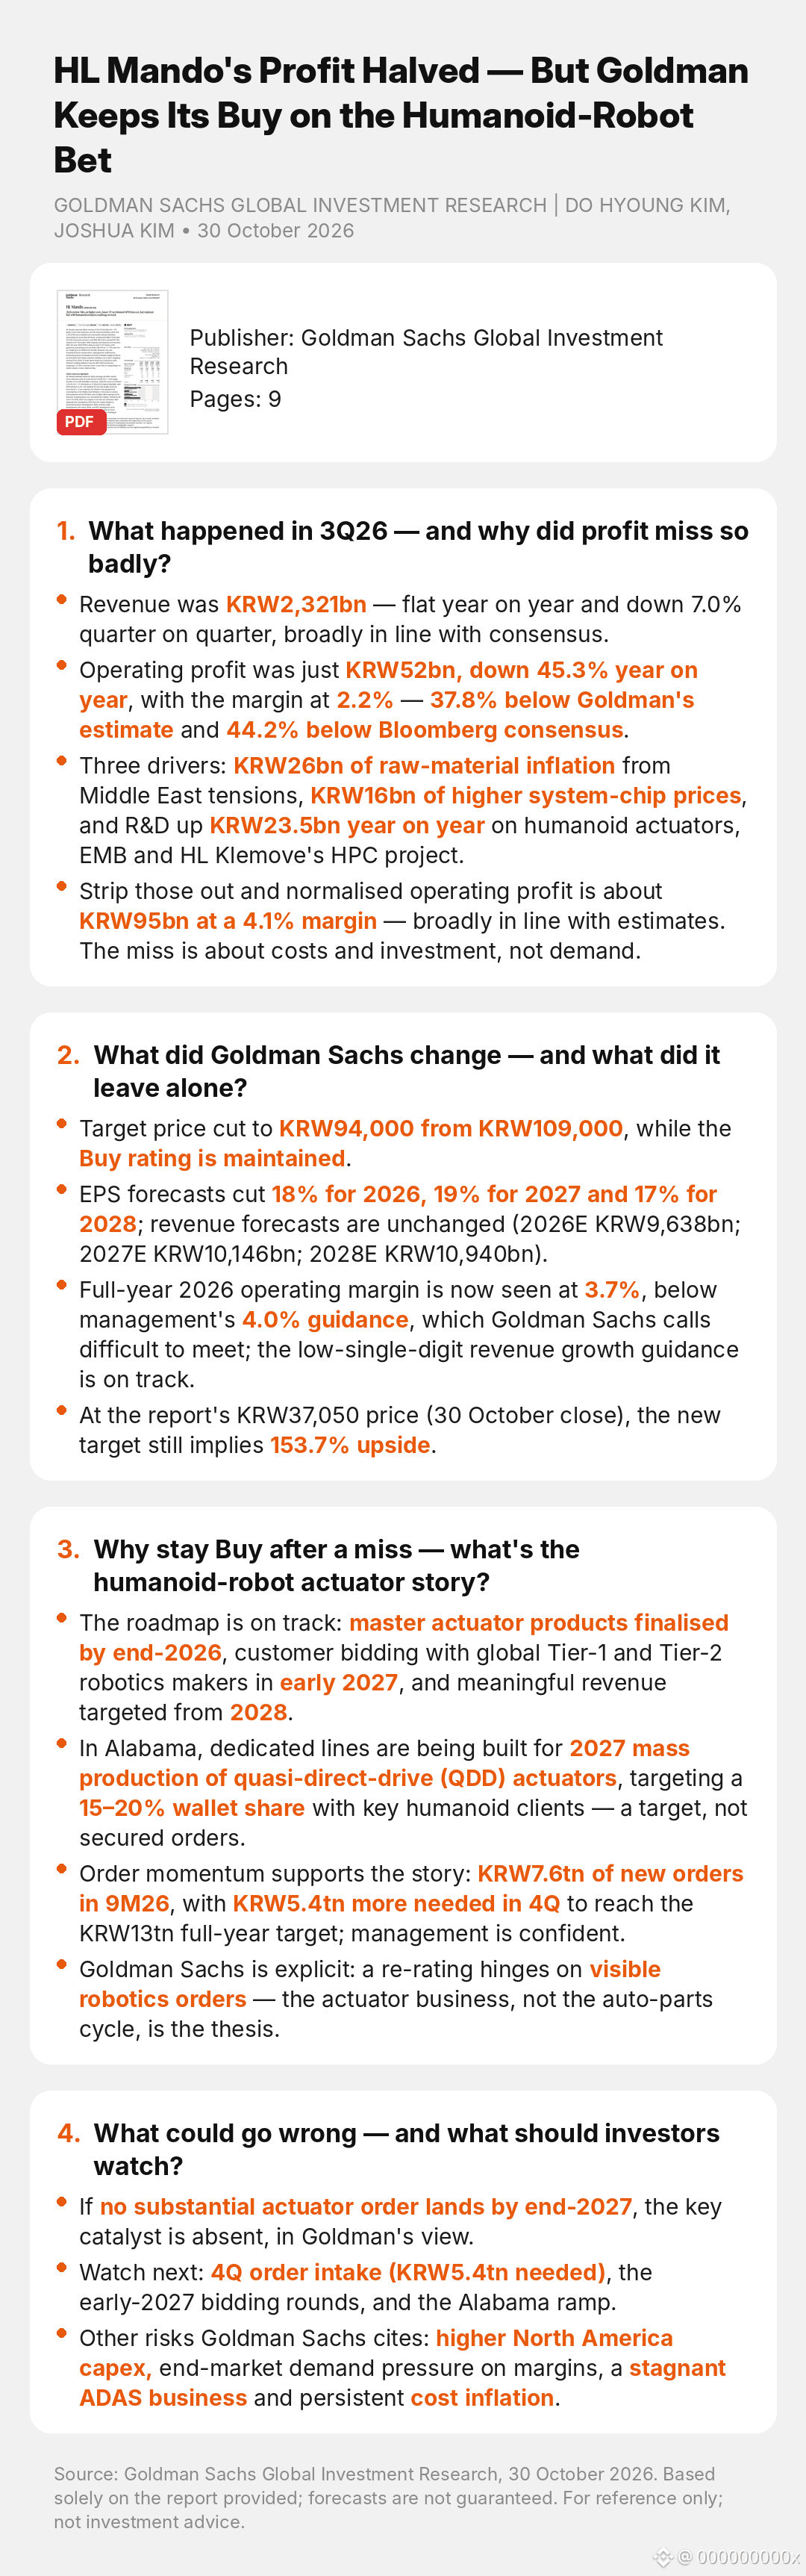
HL Mando's Profit Halved — But Goldman Keeps Its Buy on the Humanoid-Robot BetHL Mando's Profit Halved — But Goldman Keeps Its Buy on the Humanoid-Robot Bet
$204320.KS
GOLDMAN SACHS GLOBAL INVESTMENT RESEARCH | DO HYOUNG KIM, JOSHUA KIM • 30 October 2026
1. What happened in 3Q26 — and why did profit miss so badly?
• Revenue was KRW2,321bn — flat year on year and down 7.0% quarter on quarter, broadly in line with consensus.
• Operating profit was just KRW52bn, down 45.3% year on year, with the margin at 2.2% — 37.8% below Goldman's estimate and 44.2% below Bloomberg consensus.
• Three drivers: KRW26bn of raw-material inflation from Middle East tensions, KRW16bn of higher system-chip prices, and R&D up KRW23.5bn year on year on humanoid actuators, EMB and HL Klemove's HPC project.
• Strip those out and normalised operating profit is about KRW95bn at a 4.1% margin — broadly in line with estimates. The miss is about costs and investment, not demand.
2. What did Goldman Sachs change — and what did it leave alone?
• Target price cut to KRW94,000 from KRW109,000, while the Buy rating is maintained.
• EPS forecasts cut 18% for 2026, 19% for 2027 and 17% for 2028; revenue forecasts are unchanged (2026E KRW9,638bn; 2027E KRW10,146bn; 2028E KRW10,940bn).
• Full-year 2026 operating margin is now seen at 3.7%, below management's 4.0% guidance, which Goldman Sachs calls difficult to meet; the low-single-digit revenue growth guidance is on track.
• At the report's KRW37,050 price (30 October close), the new target still implies 153.7% upside.
3. Why stay Buy after a miss — what's the humanoid-robot actuator story?
• The roadmap is on track: master actuator products finalised by end-2026, customer bidding with global Tier-1 and Tier-2 robotics makers in early 2027, and meaningful revenue targeted from 2028.
• In Alabama, dedicated lines are being built for 2027 mass production of quasi-direct-drive (QDD) actuators, targeting a 15–20% wallet share with key humanoid clients — a target, not secured orders.
• Order momentum supports the story: KRW7.6tn of new orders in 9M26, with KRW5.4tn more needed in 4Q to reach the KRW13tn full-year target; management is confident.
• Goldman Sachs is explicit: a re-rating hinges on visible robotics orders — the actuator business, not the auto-parts cycle, is the thesis.
4. What could go wrong — and what should investors watch?
• If no substantial actuator order lands by end-2027, the key catalyst is absent, in Goldman's view.
• Watch next: 4Q order intake (KRW5.4tn needed), the early-2027 bidding rounds, and the Alabama ramp.
• Other risks Goldman Sachs cites: higher North America capex, end-market demand pressure on margins, a stagnant ADAS business and persistent cost inflation.
#HumanoidRobots #Robotics #AI #AutoParts #Korea
Source: Goldman Sachs Global Investment Research, 30 October 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Read the full breakdown on Unhidea: https://unhidea.com/en/articles/research-c3a686906990453489fcfb879a5a76fc-en
Visit unhidea.com for more of the latest sell-side research interpretations.
HL Mando's Profit Halved — But Goldman Keeps Its Buy on the Humanoid-Robot Bet
HL Mando's Profit Halved — But Goldman Keeps Its Buy on the Humanoid-Robot Bet
$204320.KS
GOLDMAN SACHS GLOBAL INVESTMENT RESEARCH | DO HYOUNG KIM, JOSHUA KIM • 30 October 2026
1. What happened in 3Q26 — and why did profit miss so badly?
• Revenue was KRW2,321bn — flat year on year and down 7.0% quarter on quarter, broadly in line with consensus.
• Operating profit was just KRW52bn, down 45.3% year on year, with the margin at 2.2% — 37.8% below Goldman's estimate and 44.2% below Bloomberg consensus.
• Three drivers: KRW26bn of raw-material inflation from Middle East tensions, KRW16bn of higher system-chip prices, and R&D up KRW23.5bn year on year on humanoid actuators, EMB and HL Klemove's HPC project.
• Strip those out and normalised operating profit is about KRW95bn at a 4.1% margin — broadly in line with estimates. The miss is about costs and investment, not demand.
2. What did Goldman Sachs change — and what did it leave alone?
• Target price cut to KRW94,000 from KRW109,000, while the Buy rating is maintained.
• EPS forecasts cut 18% for 2026, 19% for 2027 and 17% for 2028; revenue forecasts are unchanged (2026E KRW9,638bn; 2027E KRW10,146bn; 2028E KRW10,940bn).
• Full-year 2026 operating margin is now seen at 3.7%, below management's 4.0% guidance, which Goldman Sachs calls difficult to meet; the low-single-digit revenue growth guidance is on track.
• At the report's KRW37,050 price (30 October close), the new target still implies 153.7% upside.
3. Why stay Buy after a miss — what's the humanoid-robot actuator story?
• The roadmap is on track: master actuator products finalised by end-2026, customer bidding with global Tier-1 and Tier-2 robotics makers in early 2027, and meaningful revenue targeted from 2028.
• In Alabama, dedicated lines are being built for 2027 mass production of quasi-direct-drive (QDD) actuators, targeting a 15–20% wallet share with key humanoid clients — a target, not secured orders.
• Order momentum supports the story: KRW7.6tn of new orders in 9M26, with KRW5.4tn more needed in 4Q to reach the KRW13tn full-year target; management is confident.
• Goldman Sachs is explicit: a re-rating hinges on visible robotics orders — the actuator business, not the auto-parts cycle, is the thesis.
4. What could go wrong — and what should investors watch?
• If no substantial actuator order lands by end-2027, the key catalyst is absent, in Goldman's view.
• Watch next: 4Q order intake (KRW5.4tn needed), the early-2027 bidding rounds, and the Alabama ramp.
• Other risks Goldman Sachs cites: higher North America capex, end-market demand pressure on margins, a stagnant ADAS business and persistent cost inflation.
#HumanoidRobots #Robotics #AI #AutoParts #Korea
Source: Goldman Sachs Global Investment Research, 30 October 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Read the full breakdown on Unhidea: https://unhidea.com/en/articles/research-c3a686906990453489fcfb879a5a76fc-en
Visit unhidea.com for more of the latest sell-side research interpretations.
$204320.KS
GOLDMAN SACHS GLOBAL INVESTMENT RESEARCH | DO HYOUNG KIM, JOSHUA KIM • 30 October 2026
1. What happened in 3Q26 — and why did profit miss so badly?
• Revenue was KRW2,321bn — flat year on year and down 7.0% quarter on quarter, broadly in line with consensus.
• Operating profit was just KRW52bn, down 45.3% year on year, with the margin at 2.2% — 37.8% below Goldman's estimate and 44.2% below Bloomberg consensus.
• Three drivers: KRW26bn of raw-material inflation from Middle East tensions, KRW16bn of higher system-chip prices, and R&D up KRW23.5bn year on year on humanoid actuators, EMB and HL Klemove's HPC project.
• Strip those out and normalised operating profit is about KRW95bn at a 4.1% margin — broadly in line with estimates. The miss is about costs and investment, not demand.
2. What did Goldman Sachs change — and what did it leave alone?
• Target price cut to KRW94,000 from KRW109,000, while the Buy rating is maintained.
• EPS forecasts cut 18% for 2026, 19% for 2027 and 17% for 2028; revenue forecasts are unchanged (2026E KRW9,638bn; 2027E KRW10,146bn; 2028E KRW10,940bn).
• Full-year 2026 operating margin is now seen at 3.7%, below management's 4.0% guidance, which Goldman Sachs calls difficult to meet; the low-single-digit revenue growth guidance is on track.
• At the report's KRW37,050 price (30 October close), the new target still implies 153.7% upside.
3. Why stay Buy after a miss — what's the humanoid-robot actuator story?
• The roadmap is on track: master actuator products finalised by end-2026, customer bidding with global Tier-1 and Tier-2 robotics makers in early 2027, and meaningful revenue targeted from 2028.
• In Alabama, dedicated lines are being built for 2027 mass production of quasi-direct-drive (QDD) actuators, targeting a 15–20% wallet share with key humanoid clients — a target, not secured orders.
• Order momentum supports the story: KRW7.6tn of new orders in 9M26, with KRW5.4tn more needed in 4Q to reach the KRW13tn full-year target; management is confident.
• Goldman Sachs is explicit: a re-rating hinges on visible robotics orders — the actuator business, not the auto-parts cycle, is the thesis.
4. What could go wrong — and what should investors watch?
• If no substantial actuator order lands by end-2027, the key catalyst is absent, in Goldman's view.
• Watch next: 4Q order intake (KRW5.4tn needed), the early-2027 bidding rounds, and the Alabama ramp.
• Other risks Goldman Sachs cites: higher North America capex, end-market demand pressure on margins, a stagnant ADAS business and persistent cost inflation.
#HumanoidRobots #Robotics #AI #AutoParts #Korea
Source: Goldman Sachs Global Investment Research, 30 October 2026. Based solely on the report provided; forecasts are not guaranteed. For reference only; not investment advice.
Read the full breakdown on Unhidea: https://unhidea.com/en/articles/research-c3a686906990453489fcfb879a5a76fc-en
Visit unhidea.com for more of the latest sell-side research interpretations.
1
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BTCReboundsAbove$60KAmidWhaleDipBuying
5,597 views
59 Discussing
2
#NvidiaLoses$2.7TrillionInMonthAndAHalf
44,691 views
209 Discussing
3
#GlobalStocksFaceLongestLosingStreakSince2023
402,328 views
2,668 Discussing
4
#BlackRockIBITPostsRecord$541MSingleDayOutflow
59,781 views
146 Discussing
5
#AnthropicPlungesTowardIPOPriceonDay2
215,608 views
1,713 Discussing
6
#TwentyOneCapitalAdds172.25BTC
105,300 views
1,117 Discussing
7
#HKBillWouldExcludeTokenizedDepositsFromVirtualAssets
14,573 views
67 Discussing
8
#HKBillProposesHK$100KFineForUnauthorizedCryptoTitles
3,621 views
30 Discussing
9
#BitMineFaces$10.1BUnrealizedETHLoss
6,986 views
32 Discussing
10
#StrategyReports$35BNetReserves
3,741 views
24 Discussing