

#velo
velo
311,707 views
1,010 Discussing
Hot
Latest

·
--
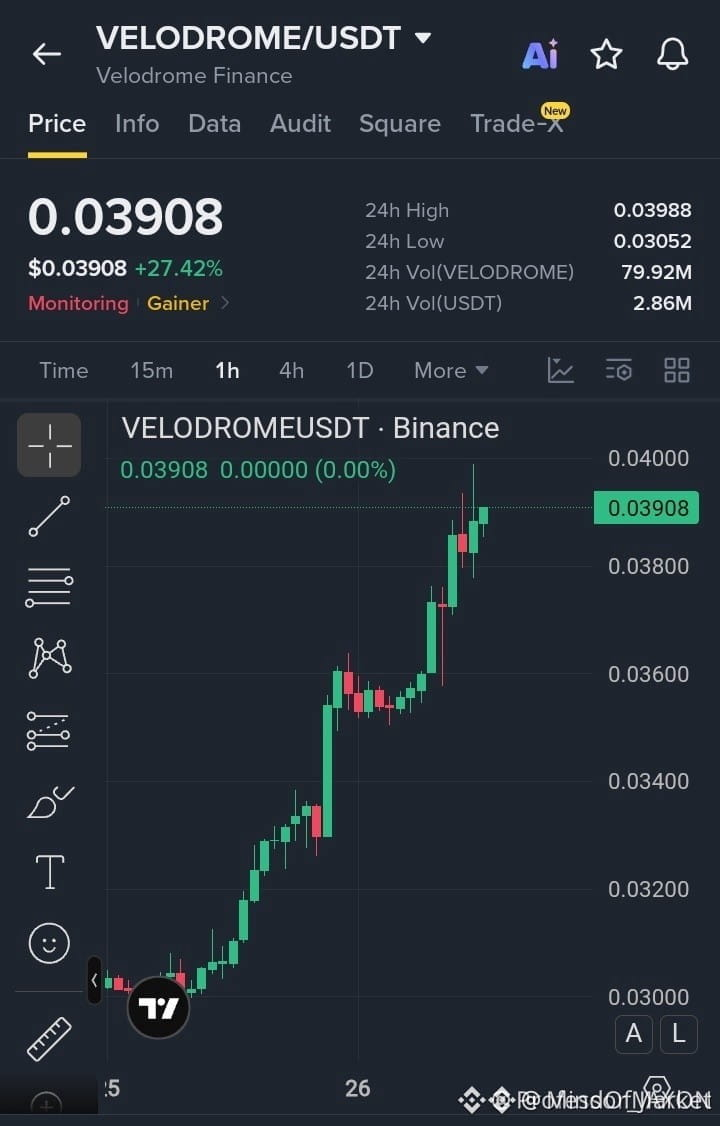
⚡ $VELO STRUCTURAL RECLAIM SETS UP POTENTIAL IMPULSE TOWARD THE 0.040 INEFFICIENCY! 📈
Entry: 0.0385 - 0.0391 ⚡
Target: 0.0400 / 0.0415 / 0.0430 🚀
Stop Loss: 0.0376 ⚠️
$VELO is maintaining a clean bullish market structure on the 1H timeframe, printing sequential higher highs while holding firmly above the recent breakout demand zone. 📊 Order flow dynamics indicate steady institutional accumulation beneath the immediate $0.0400 liquidity wall.
💡 A decisive volume expansion beyond $0.0400 opens a direct path toward upper structural targets up to $0.0430. 🔍 As long as price respects structural invalidation at $0.0376, buyers retain firm control of momentum.
💬 Are you positioning within this demand zone or waiting for a confirmed candle close above resistance? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #VELO #LongSetup #Crypto #Breakout
🦈 🎯
6
·
--
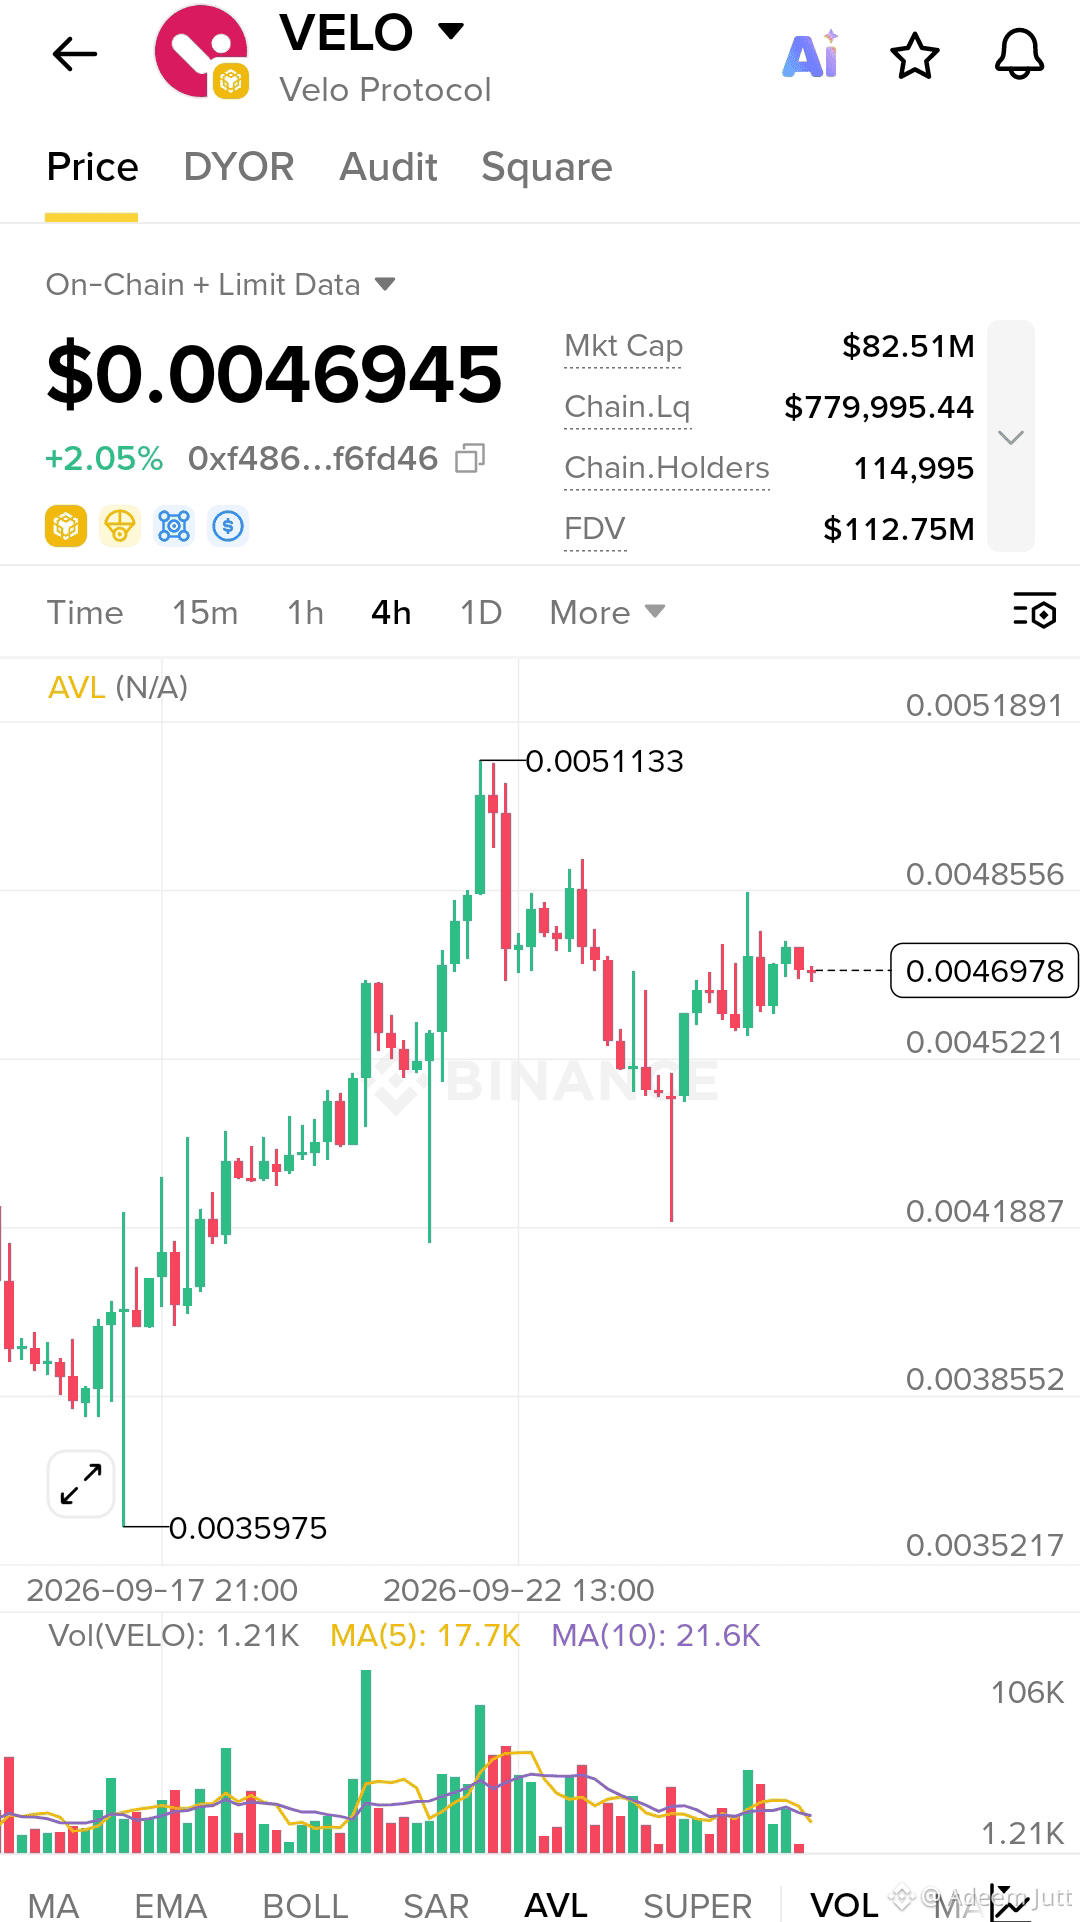
🚨 $VELO Is Quiet… But Not for Long. 👀
$VELO is holding above key support after a strong bounce. Bulls are defending the trend, and a breakout above $0.00474 could trigger the next leg up. 📈$PHA
Watch: Support $0.00460 | Resistance $0.00474 | A clean breakout could bring fresh momentum. 🔥
#Velo #ALPHA🔥 #BinanceSquare #PolymarketBankFailureBetsDrawFDICConcern #CircleMints500MUSDCOnSolana
{alpha}(560xf486ad071f3bee968384d2e39e2d8af0fcf6fd46)
🚨 $VELO Is Quiet… But Not for Long. 👀
$VELO is holding above key support after a strong bounce. Bulls are defending the trend, and a breakout above $0.00474 could trigger the next leg up. 📈$PHA
Watch: Support $0.00460 | Resistance $0.00474 | A clean breakout could bring fresh momentum. 🔥
#Velo #ALPHA🔥 #BinanceSquare #PolymarketBankFailureBetsDrawFDICConcern #CircleMints500MUSDCOnSolana
1
1
81
·
--
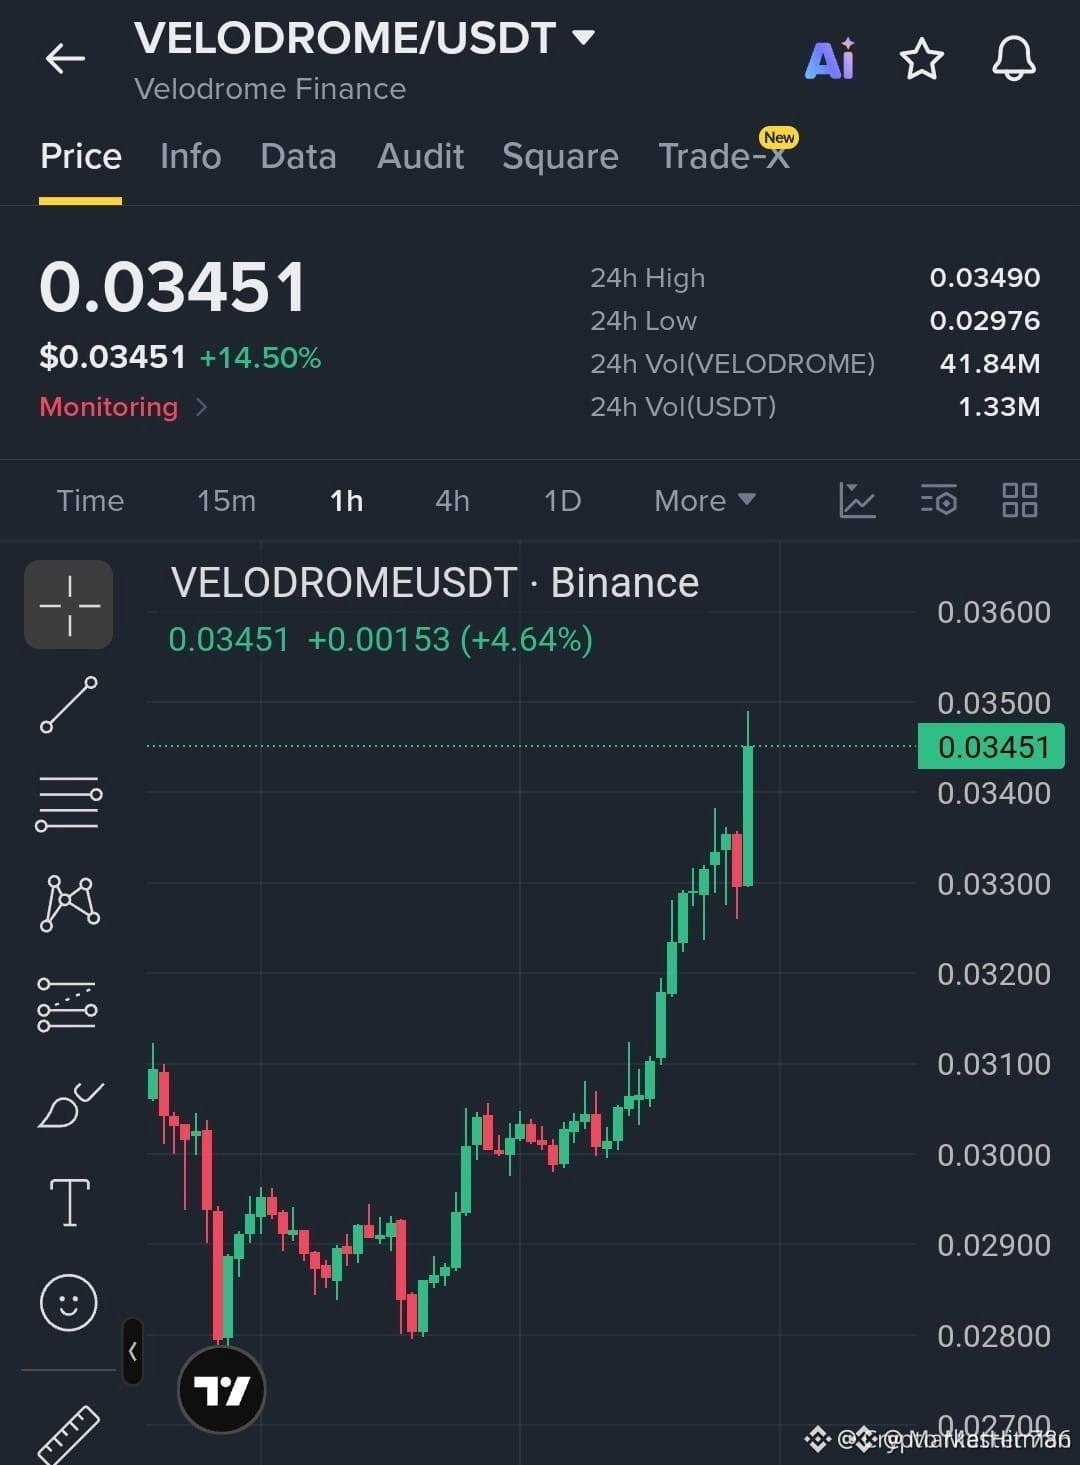
🚀 #VELODROMEUSDT +27% EXPLOSION! Forecast Inside 📈
$VELO blasting to 0.03929 on 358M volume! Parabolic green candle smashed upper Bollinger (0.03564), crushing EMA8/13/21. RSI(14) 80.4 + KDJ J 104 = extreme overbought exhaustion after the vertical run from 0.030 lows.
⚡ SHORT SETUP:
Entry: 0.0393
TP1: 0.0355 | TP2: 0.0330
SL: 0.0415
Strong momentum but classic mean-reversion setup as price sits far above bands. Watch for rejection at 0.0395 high.
Trade $VELOUSDT Perp NOW on Binance! Follow & turn 🔔 ON ✅ Don’t fade this move!
#VELO #VELODROME #BinanceFutures #CryptoSignal #AltcoinPump #DeFi #ShortSetup #TradingAlert #BinanceSquare #CryptoTrading
6
291

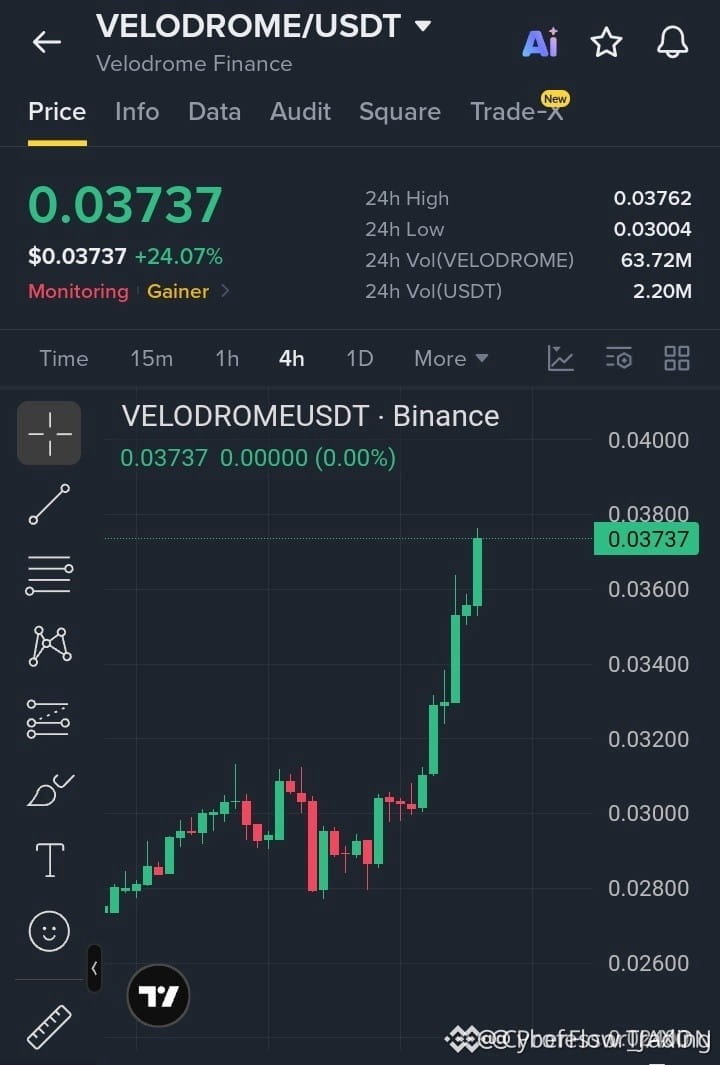
💥 $VELO EXPLODES THROUGH MAJOR RESISTANCE TO OPEN HIGH-CONVICTION CONTINUATION PATH! 📈
Entry: 0.0365 - 0.0374 ⚡
Target: 0.0390, 0.0410, 0.0435 🚀
Stop Loss: 0.0345 ⚠️
📌 Buyers just sliced through the heavy supply ceiling between 0.034 and 0.036, transforming previous overhead resistance into a fresh launchpad. 📊 As long as market structure holds above this reclaim zone on the 4H timeframe, momentum remains firmly in control for a clean wave higher.
💡 Order flow favors expansion toward upper liquidity pools while bids stack up smoothly on minor pullbacks. 💬 Are you placing your bids on this breakout retest or waiting for 0.040 to clear first? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #VELO #LongSetup #Breakout #Altcoins #Crypto
🔥 ⚡
5
·
--
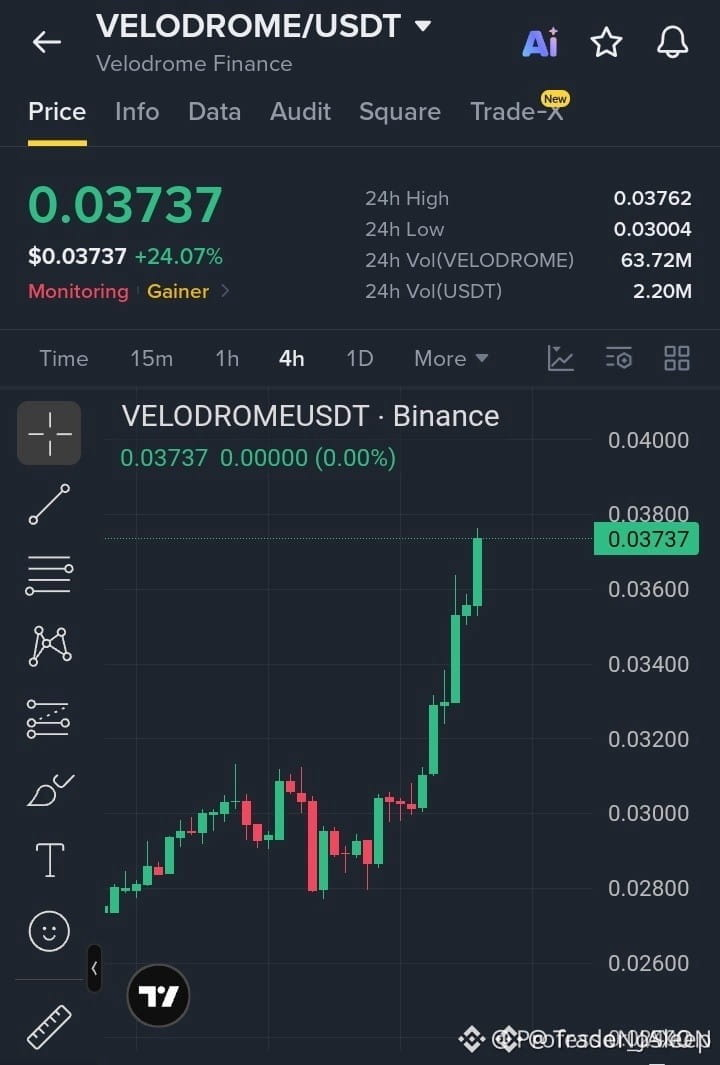
⚡ $VELO RECLAIMS KEY RESISTANCE AREA AS INSTITUTIONAL DEMAND FUELS BREAKOUT EXPANSION 📈
Entry: $0.0365 - $0.0374 ⚡
Target: $0.0390 / $0.0410 / $0.0435 🚀
Stop Loss: $0.0345 ⚠️
📌 Smart money has cleared the supply overhang between $0.034 and $0.036, establishing a strong structural base on the 4H timeframe. 🔍 As long as price holds above this former resistance-turned-support zone, order flow remains firmly skewed toward buyer control.
📊 The current expansion phase points toward clean liquidity fills above local structural highs. 💡 Securing higher-low acceptance on smaller timeframes provides the ideal catalyst for progressive continuation toward higher macro targets. 💬 Are you waiting for a retest of the order block, or tracking the momentum directly into the upper target levels? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #VELO #Breakout #Altcoins #Crypto
🎯 🦈
1
·
--
🚨 $VELO RECLAIMS KEY RANGE STRUCTURE AS SMART MONEY ACCUMULATES FOR EXPANSION 💥
Entry: 0.0352 - 0.0365 ⚡
Target: 0.0420 🚀
Stop Loss: 0.0338 ⚠️
The 4H market structure on $VELO exhibits a textbook bullish continuation after reclaiming the previous range high. Institutional buyers are actively defending this demand zone, establishing higher lows with sustained order flow absorption. 📊
As long as price holds above support, structural momentum favors an expansion toward overhead liquidity pools up to 0.0420. 💡 Key validation relies on a clean breakout above the 0.03775 resistance pivot to unlock full continuation velocity. 🔍
💬 Are you positioning for the breakout above 0.03775 or waiting for a deeper retest into demand? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #VELO #Altcoins #MarketStructure #Crypto
🎯 🦈
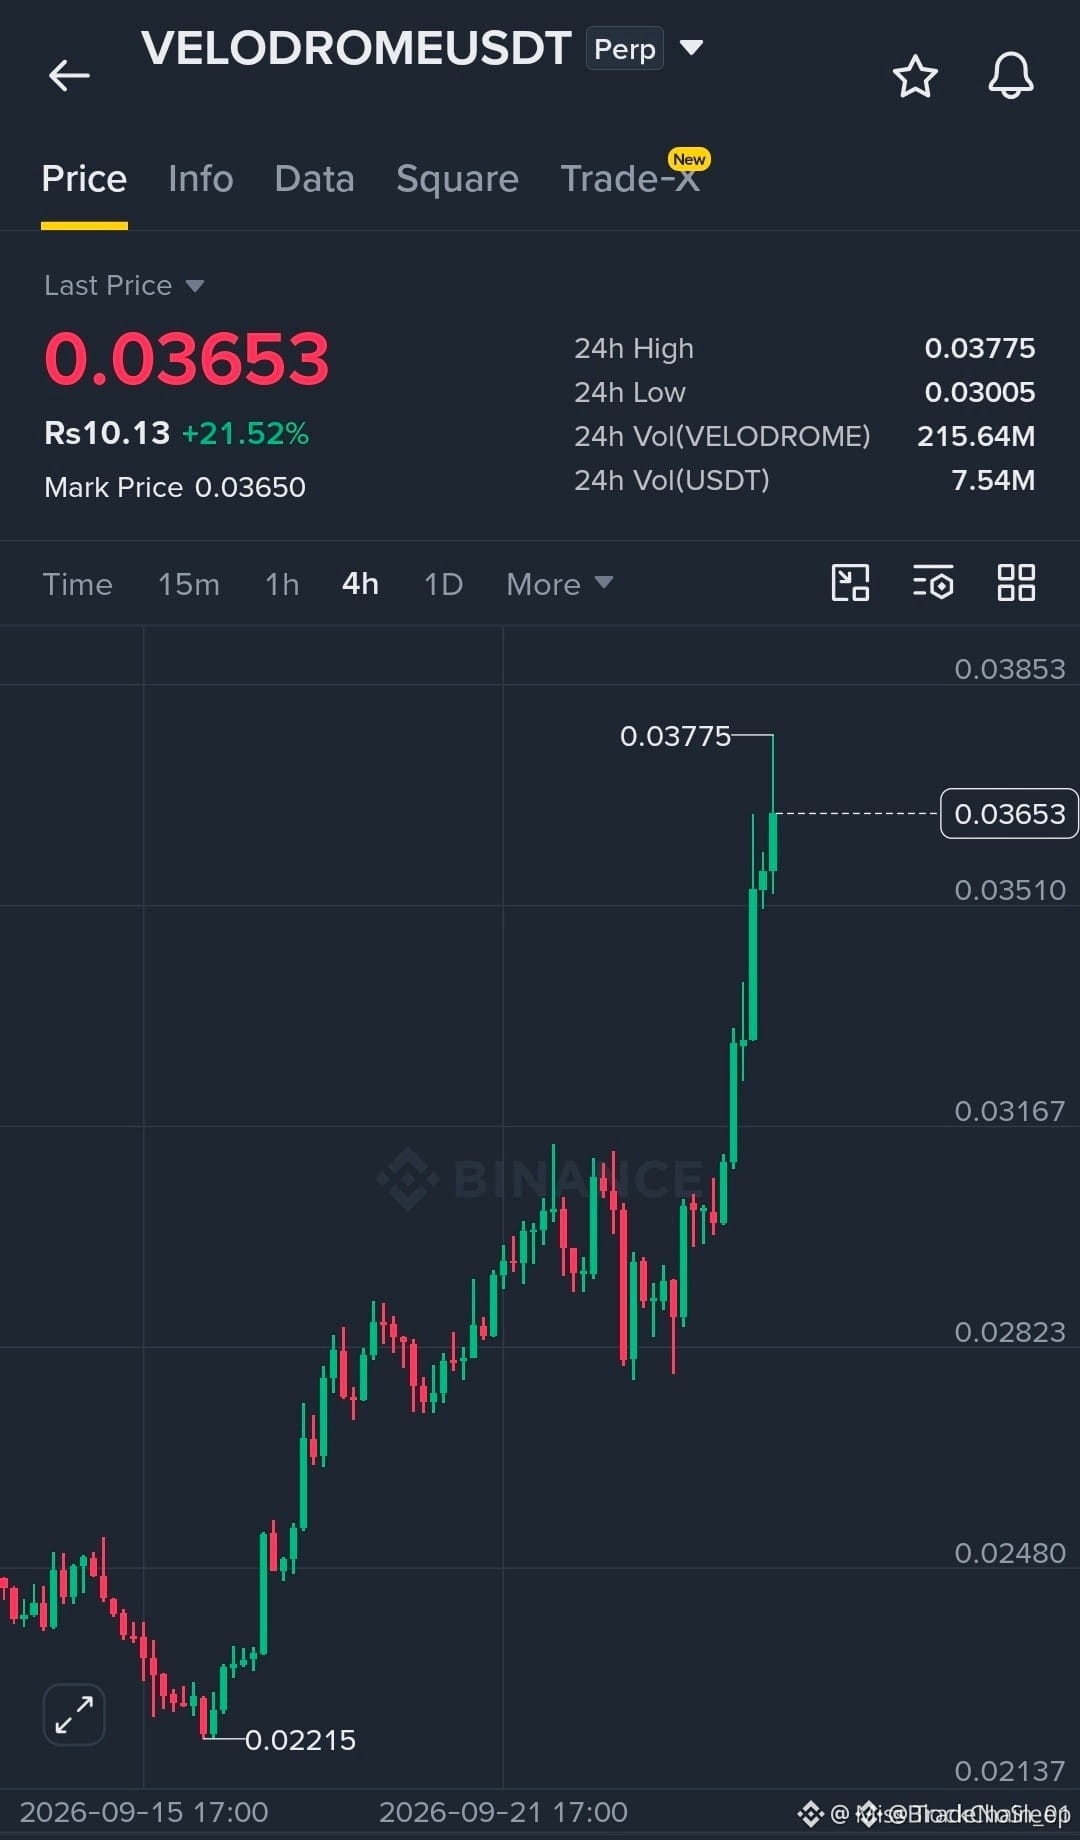

⚡ $VELO EXPANDING OUT OF RANGE AS 4H BULLS LOCK IN THE BREAKOUT STRUCTURE! 📈
Entry: 0.0365 - 0.0352 🟢
Target: 0.0378 - 0.0420 🚀
Stop Loss: 0.0338 ⚠️
📌 The 4H structural shift on $VELO is displaying classic continuation signals after shattering local resistance and turning previous overhead supply into solid ground. 📊 Buyers are firmly absorbing dips near the range high, setting the stage for a volatility expansion toward upper liquidity pools.
💡 As long as support holds, this order flow profile favors a clean drift into higher targets as sellers run out of ammo. 💬 Do you expect $VELO to slice straight through the 0.03775 level or build a base here first? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #VELO #LongSetup #Breakout #Crypto
🔥 ⚡
21
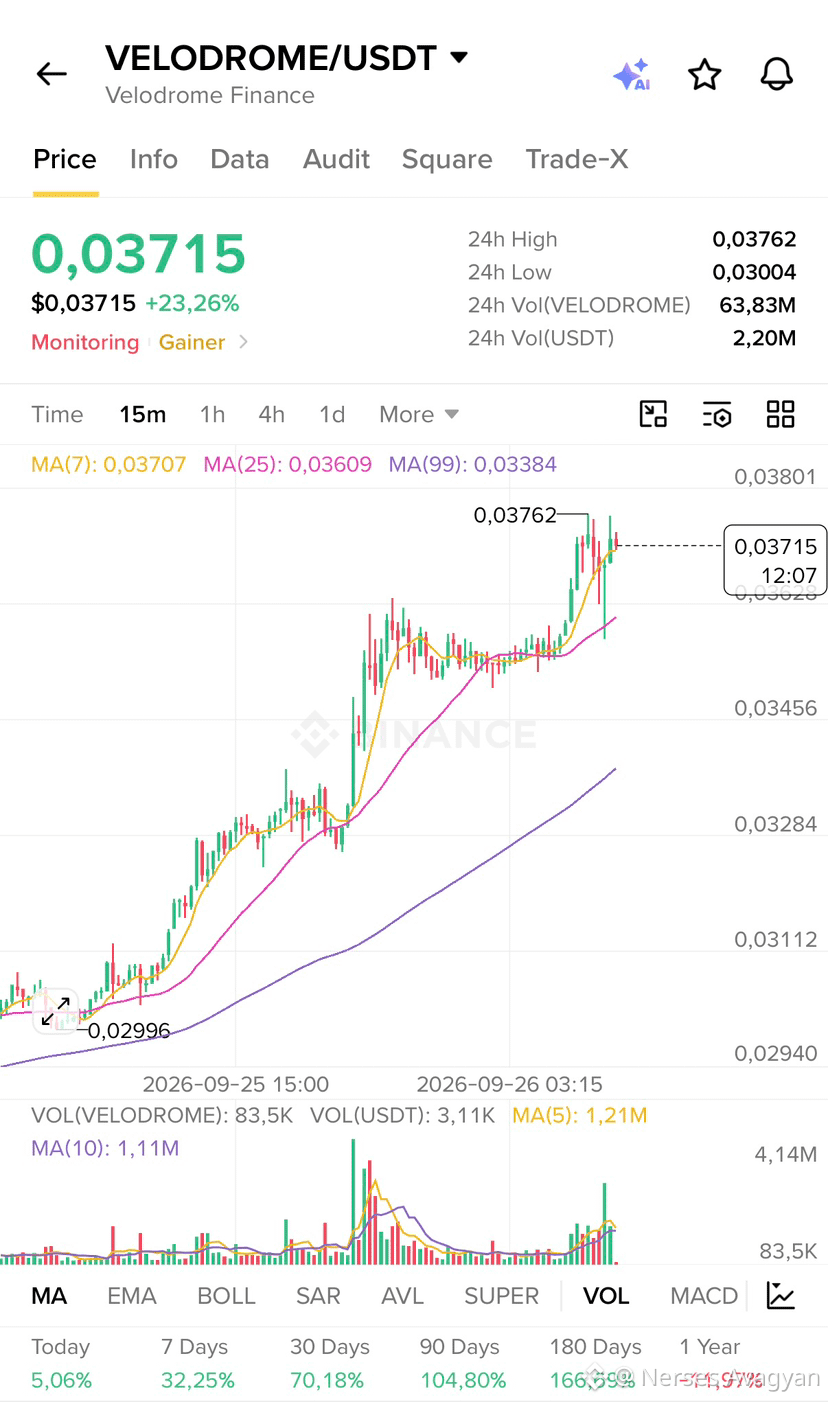
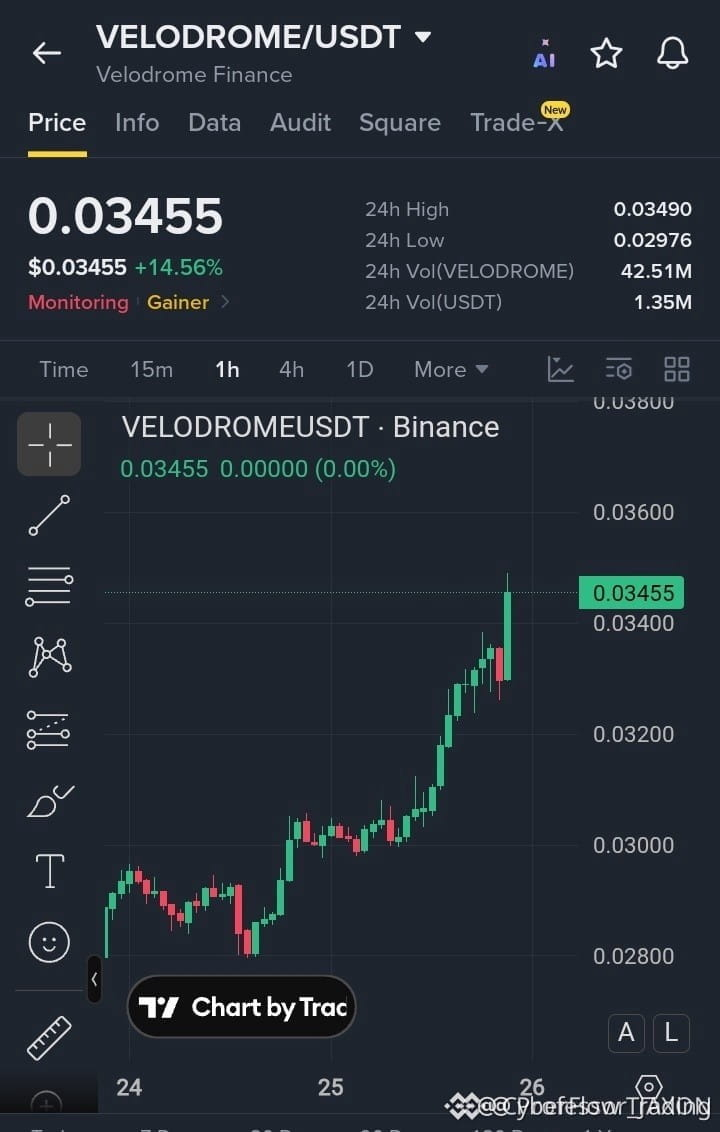
⚡ $VELO EXPANDING FROM CLEAN BREAKOUT ZONE TOWARD HIGHER RESISTANCE LEVELS! 🚀
Entry: $0.03420 - $0.03460 ⚡
Target 1: $0.03600 🚀
Target 2: $0.03800 🎯
Target 3: $0.04050 💥
Stop Loss: $0.03280 ⚠️
📌 $VELO is flexed in a classic higher-high structure after clearing key overhead supply. Buyers are aggressively defending the breakout zone, signaling strong expansion velocity into the next liquidity pockets. 📊
💡 As long as demand holds firm above support, the path of least resistance points straight into upper resistance levels. Market momentum heavily favors aggressive bids on this continuation sequence. 🤔 Are you riding this trend continuation or waiting for a deeper pullback? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #VELO #LongSetup #Breakout #Crypto #Altcoins
🔥 ⚡
4
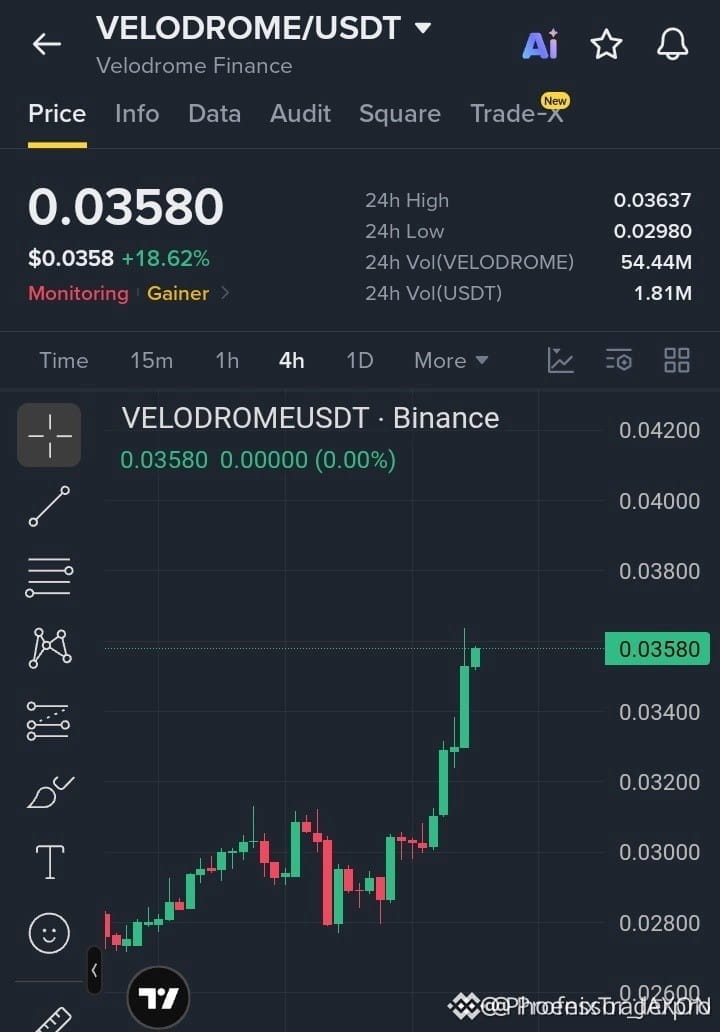
⚡ $VELO CRACKING RESISTANCE WITH STRONG MOMENTUM AS BUYERS CLAIM THE 0.0340 ZONE! 💥
Entry: 0.0352 - 0.0358 ⚡
Target: 0.0380 - 0.0420 🚀
Stop Loss: 0.0338 ⚠️
📌 Sellers just lost control of the 0.0340 supply wall as aggressive market orders pushed price higher with pure expansion on the 4H timeframe. 📊 The structural flip suggests order flow has shifted decisively bullish, turning former resistance into fresh support.
💡 As long as bulls defend this breakout floor, velocity stays intact for a multi-target expansion toward the upper resistance levels. 💬 Are you riding this momentum wave or waiting to see if support gets retested first? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #VELO #LongSetup #Breakout #Crypto
🔥 💎
26
·
--
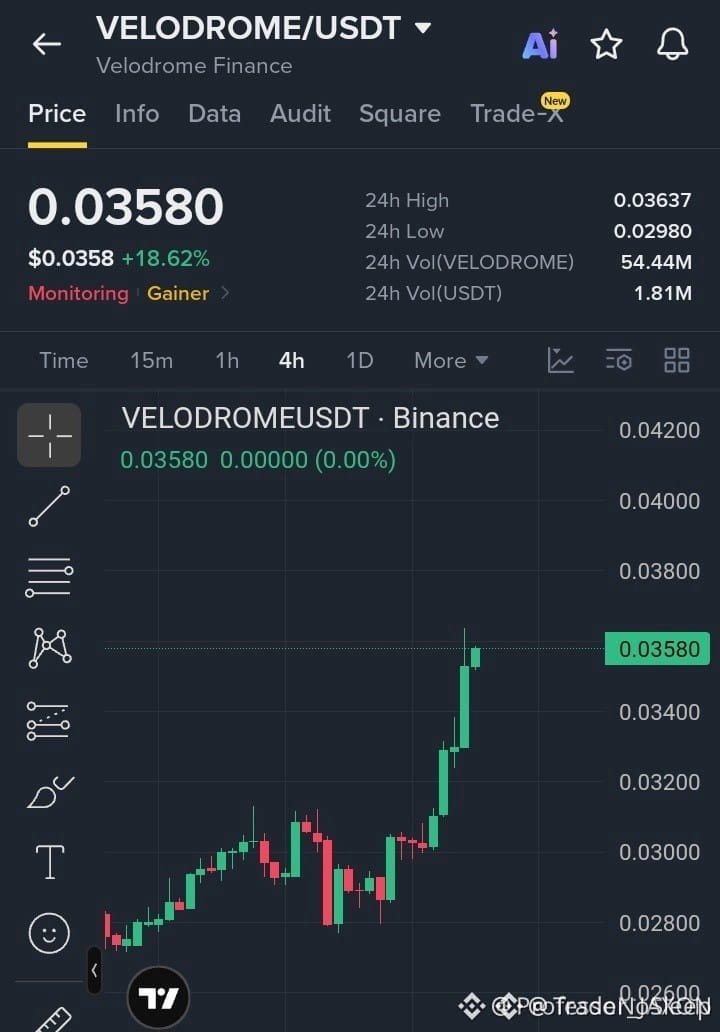
🚨 $VELO BREAKS KEY STRUCTURE WITH HEAVY INSTITUTIONAL MOMENTUM INSIDE THE DEMAND ZONE! 📈
Entry: 0.0352 - 0.0358 ⚡
Target: 0.0380 - 0.0420 🚀
Stop Loss: 0.0338 ⚠️
Institutional order flow has flipped the 0.0340 resistance into a clean support shelf. 📊 Strong 4H candle closes confirm smart money accumulation as market structure expands toward upper liquidity pools.
📌 As long as price action respects this newly formed demand block, buyers remain in full control of the trend. 🌊 We are looking for momentum to absorb resting overhead liquidity into our targets. 💬 Is $VELO leading your breakout watchlist this session or are you waiting for a deeper retest? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #VELO #Breakout #Altcoins #Crypto #MarketStructure
🎯 🦈
2

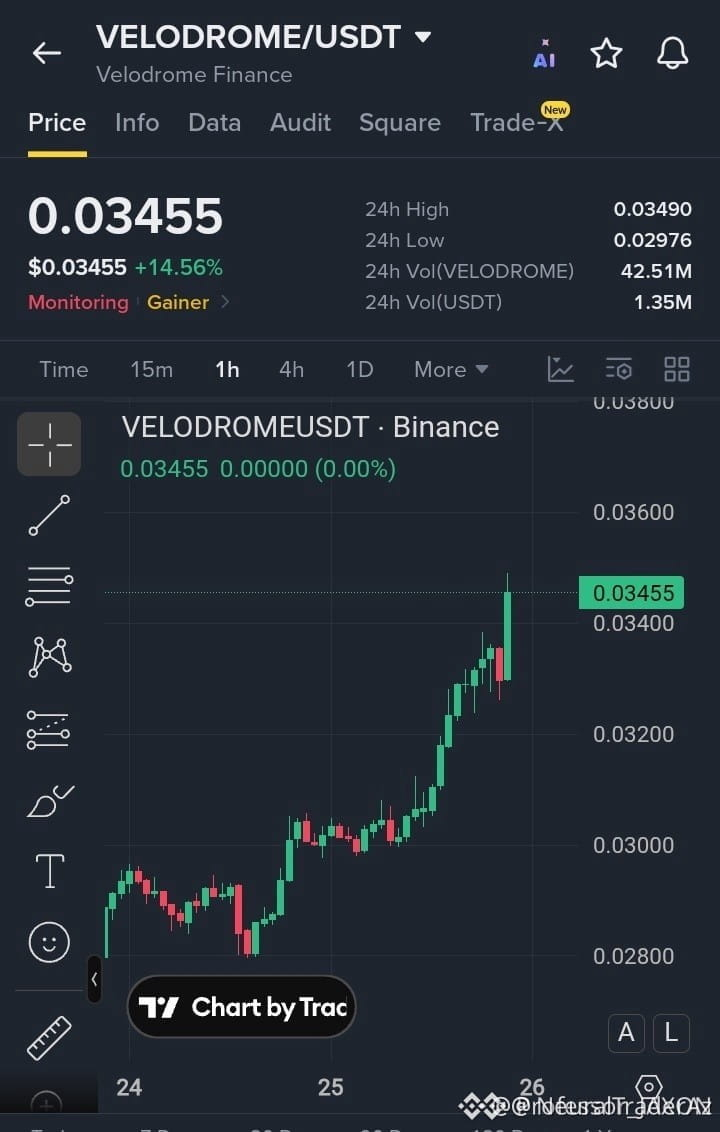
⚡ $VELODROME PRINTS CLEAN STRUCTURAL BREAKOUT AS BUY-SIDE LIQUIDITY EXPANDS ABOVE RESISTANCE! 📈
Entry: $0.03420 - $0.03460 ⚡
Target: $0.03600 - $0.04050 🚀
Stop Loss: $0.03280 ⚠️
Institutional order flow behind $VELO is displaying a clean structural expansion, printing higher highs while absorbing sell-side liquidity at resistance. 📊 As long as this breakout origin holds off the demand retest, market structure heavily favors upside continuation.
🔍 With buy-side liquidity resting above recent swing highs, sustained holding above the key pivot validates momentum toward upper inefficiencies. 💡 Risk is tightly defined against the lower structural level, providing a clean institutional trade location. 💬 Are you waiting for a deeper retest of the entry range or bidding the momentum breakout now? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #VELO #VELODROME #LongSetup #Breakout #Crypto
🎯 🦈
1

·
--
⚡ $VELODROME BREAKING OUT AS BUYERS STAKE CLAIM ON FRESH LOCAL HIGHS! 🚀
Entry: 0.0340 - 0.0345 ⚡
Target: 0.0355 / 0.0365 / 0.0380 🚀
Stop Loss: 0.0327 ⚠️
📌 Aggressive bid volume is absorbing overhead resistance on $VELODROME , signalling a textbook continuation pattern. 📊 Buyers are defending higher lows with real conviction, setting up a smooth runway toward fresh local highs.
💡 With immediate order flow aligned behind the bulls, the current accumulation window offers an ideal risk-reward layout before liquidity sweeps higher targets. 💬 Are you riding this continuation push or standing on the sidelines? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #VELO #LongSetup #Altcoins #Breakout #Crypto
🎯 ⚡
3
·
--
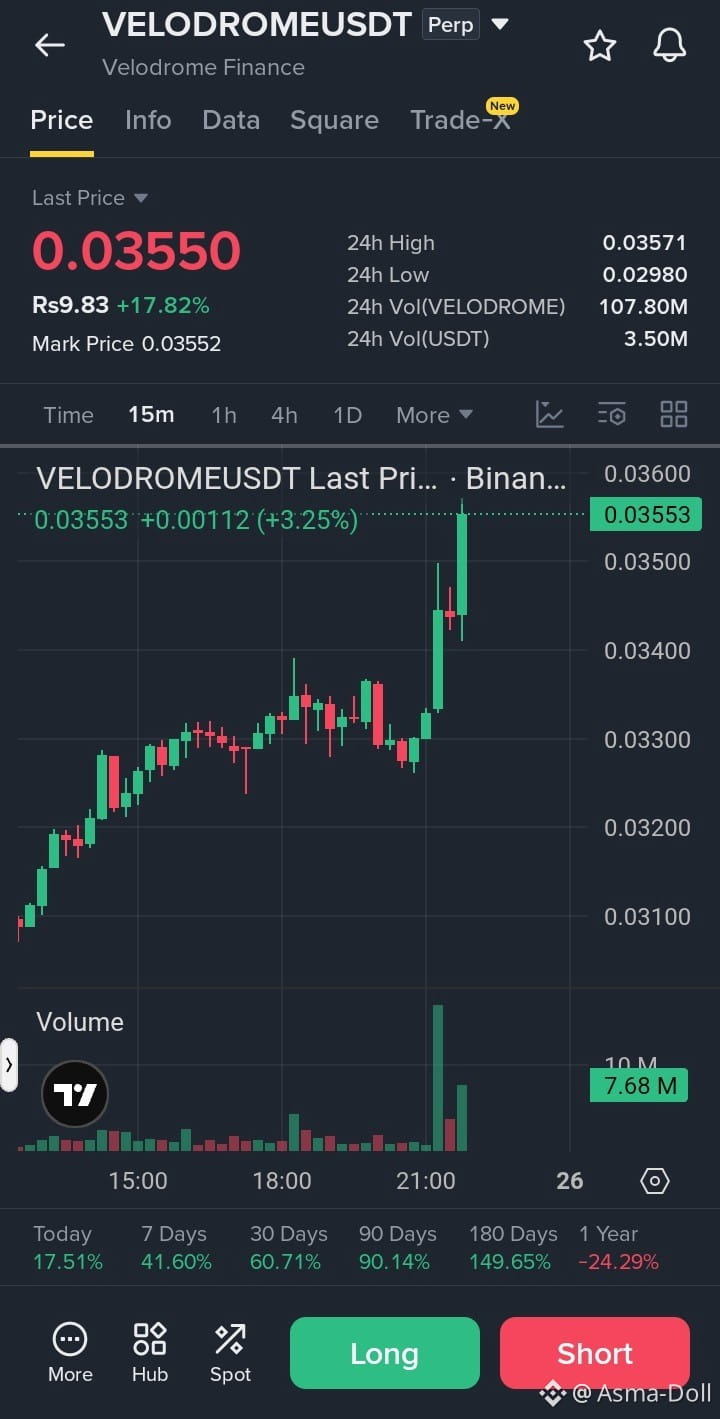
$VELODROME /USDT — SHORT 📉
Entry: 0.03520 – 0.03560
Stop Loss: 0.03720
TP1: 0.03400
TP2: 0.03250
TP3: 0.03000
Trade here $VELODROME
{future}(VELODROMEUSDT)
Analysis:
Price is up sharply +17.82% and sitting near the 24h high 0.03571.
Strong momentum can create a pullback after rejection near the high.
Recent VELO data also shows a substantial move from the ~$0.025 area into the ~$0.03+ region.
Confirmation: Wait for a clean rejection around 0.0357 and breakdown below 0.0350.
If 0.0340 breaks with volume, downside can accelerate toward TP2/TP3.
⚠️ Invalidation: Sustained breakout above 0.03720.
#VELODROME #VELO #USDT #CryptoShort #BinanceFutures
$VELODROME /USDT — SHORT 📉
Entry: 0.03520 – 0.03560
Stop Loss: 0.03720
TP1: 0.03400
TP2: 0.03250
TP3: 0.03000
Trade here $VELODROME
Analysis:
Price is up sharply +17.82% and sitting near the 24h high 0.03571.
Strong momentum can create a pullback after rejection near the high.
Recent VELO data also shows a substantial move from the ~$0.025 area into the ~$0.03+ region.
Confirmation: Wait for a clean rejection around 0.0357 and breakdown below 0.0350.
If 0.0340 breaks with volume, downside can accelerate toward TP2/TP3.
⚠️ Invalidation: Sustained breakout above 0.03720.
#VELODROME #VELO #USDT #CryptoShort #BinanceFutures
10
·
--
Aerodrome + Velodrome combined into Aero; launched in one go on October 21 with 7 EVM chains (Base, Ethereum mainnet, OP mainnet, Arbitrum, Ink, Circle’s Arc, Robinhood Chain)
First, the numbers: • AERO $0.79, market cap $787 million, 24h −7.9% (on the day of the news it briefly surged +26%) • VELO $0.034, market cap $45.4 million, 24h −6.7% • VELO market cap ÷ AERO market cap = 5.76%, while the split for the merger is 5.5% / 94.5% = 5.82%
My take:
1) The merger arbitrage is basically gone. VELO is only about 1% undervalued relative to its fair value; after accounting for slippage and migration costs, there’s basically no profit to be made. If you’re betting on “VELO will catch up after the exchange ratio is announced,” the odds just aren’t attractive anymore.
2) The real point isn’t the merger itself, but whether “100% of revenue goes to stakers + unified cross-chain liquidity” can be delivered. Aero currently accounts for about 17% of EVM spot trading volume; the official goal is to triple it—this is a narrative, not an already-proven fact.
3) Risk checklist: launching on 7 chains at the same time is a major execution test; VELO was delisted from Binance on September 13, and liquidity during the migration period may thin out; the rally in AERO is driven by expectations, not revenue.
In one sentence: the merger is certain, the arbitrage is not, and revenue delivery is still unknown. Don’t treat the narrative as fundamentals.
$AERO $VELODROME
#Aero #Velo
{spot}(AEROUSDT)
Aerodrome + Velodrome combined into Aero; launched in one go on October 21 with 7 EVM chains (Base, Ethereum mainnet, OP mainnet, Arbitrum, Ink, Circle’s Arc, Robinhood Chain)
First, the numbers: • AERO $0.79, market cap $787 million, 24h −7.9% (on the day of the news it briefly surged +26%) • VELO $0.034, market cap $45.4 million, 24h −6.7% • VELO market cap ÷ AERO market cap = 5.76%, while the split for the merger is 5.5% / 94.5% = 5.82%
My take:
1) The merger arbitrage is basically gone. VELO is only about 1% undervalued relative to its fair value; after accounting for slippage and migration costs, there’s basically no profit to be made. If you’re betting on “VELO will catch up after the exchange ratio is announced,” the odds just aren’t attractive anymore.
2) The real point isn’t the merger itself, but whether “100% of revenue goes to stakers + unified cross-chain liquidity” can be delivered. Aero currently accounts for about 17% of EVM spot trading volume; the official goal is to triple it—this is a narrative, not an already-proven fact.
3) Risk checklist: launching on 7 chains at the same time is a major execution test; VELO was delisted from Binance on September 13, and liquidity during the migration period may thin out; the rally in AERO is driven by expectations, not revenue.
In one sentence: the merger is certain, the arbitrage is not, and revenue delivery is still unknown. Don’t treat the narrative as fundamentals.
$AERO $VELODROME
#Aero #Velo
86

·
--
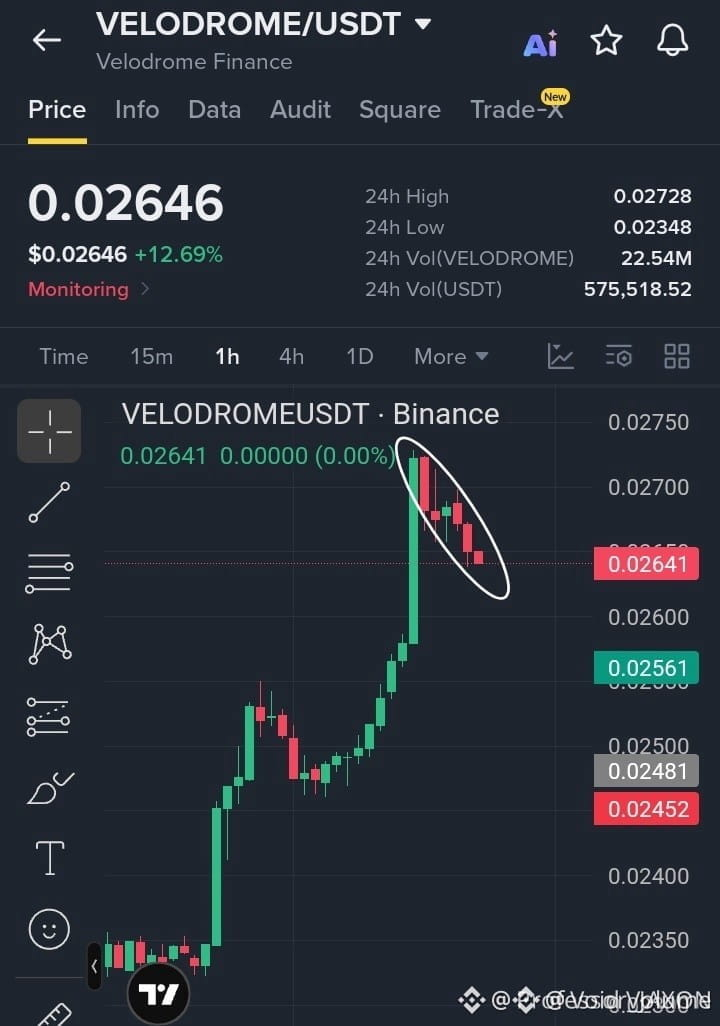
🚨 $VELO REJECTS LOCAL HIGH AS INSTITUTIONAL LIQUIDITY SWEEP FUELS DOWNSTREAM CONTINUATION 📉
Entry: 0.02640 - 0.02655 🔴
Target: 0.02452 🎯
Stop Loss: 0.02735 🛑
The impulse move into upper liquidity met immediate distribution, leaving a clear structural rejection on the lower timeframes. 📉 Smart money absorbed buying momentum at the local high, printing lower candle closes and building pressure directly above the critical 0.02640 pivot.
A clean breakdown below this structural shelf confirms downside order flow expansion toward lower inefficiencies at 0.02561 and 0.02452. 🔍 Risk parameters remain exceptionally sharp with invalidation strictly set above the sweep high. 💭 Are you front-running this breakdown or waiting for the sub-0.02640 confirmation close? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #VELO #ShortSetup #Crypto #Trading #MarketStructure
📉 🔻
29
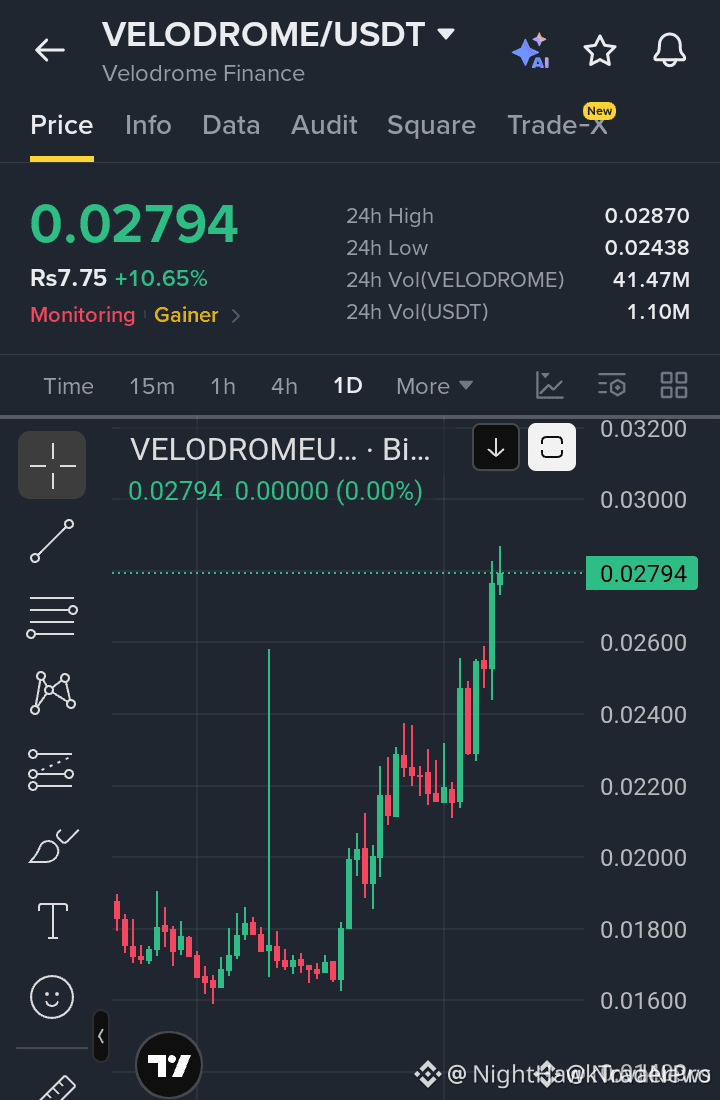
🚨 $VELO BREAKING THROUGH RESISTANCE – MOMENTUM IS UNLEASHED! 🟢
Target: 0.03200 🚀
Stop Loss: 0.02430 ⚠️
📊 The order flow on the 4H chart shows a decisive liquidity sweep as buyers lock in the last demand zone. ⚡ Smart money is loading up, pushing $VELO past the $0.0305 ceiling and igniting a fresh wave of retail inflows on the Optimism L2 hub. 🌊 With volume spiking and the RSI climbing out of oversold territory, the next leg could rocket toward the next resistance cluster.
💬 Who’s ready to ride this velocity surge or waiting for the next pullback to re‑enter? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #VELO #LongSetup #DeFi #Optimism #Crypto
🔥 💎
63

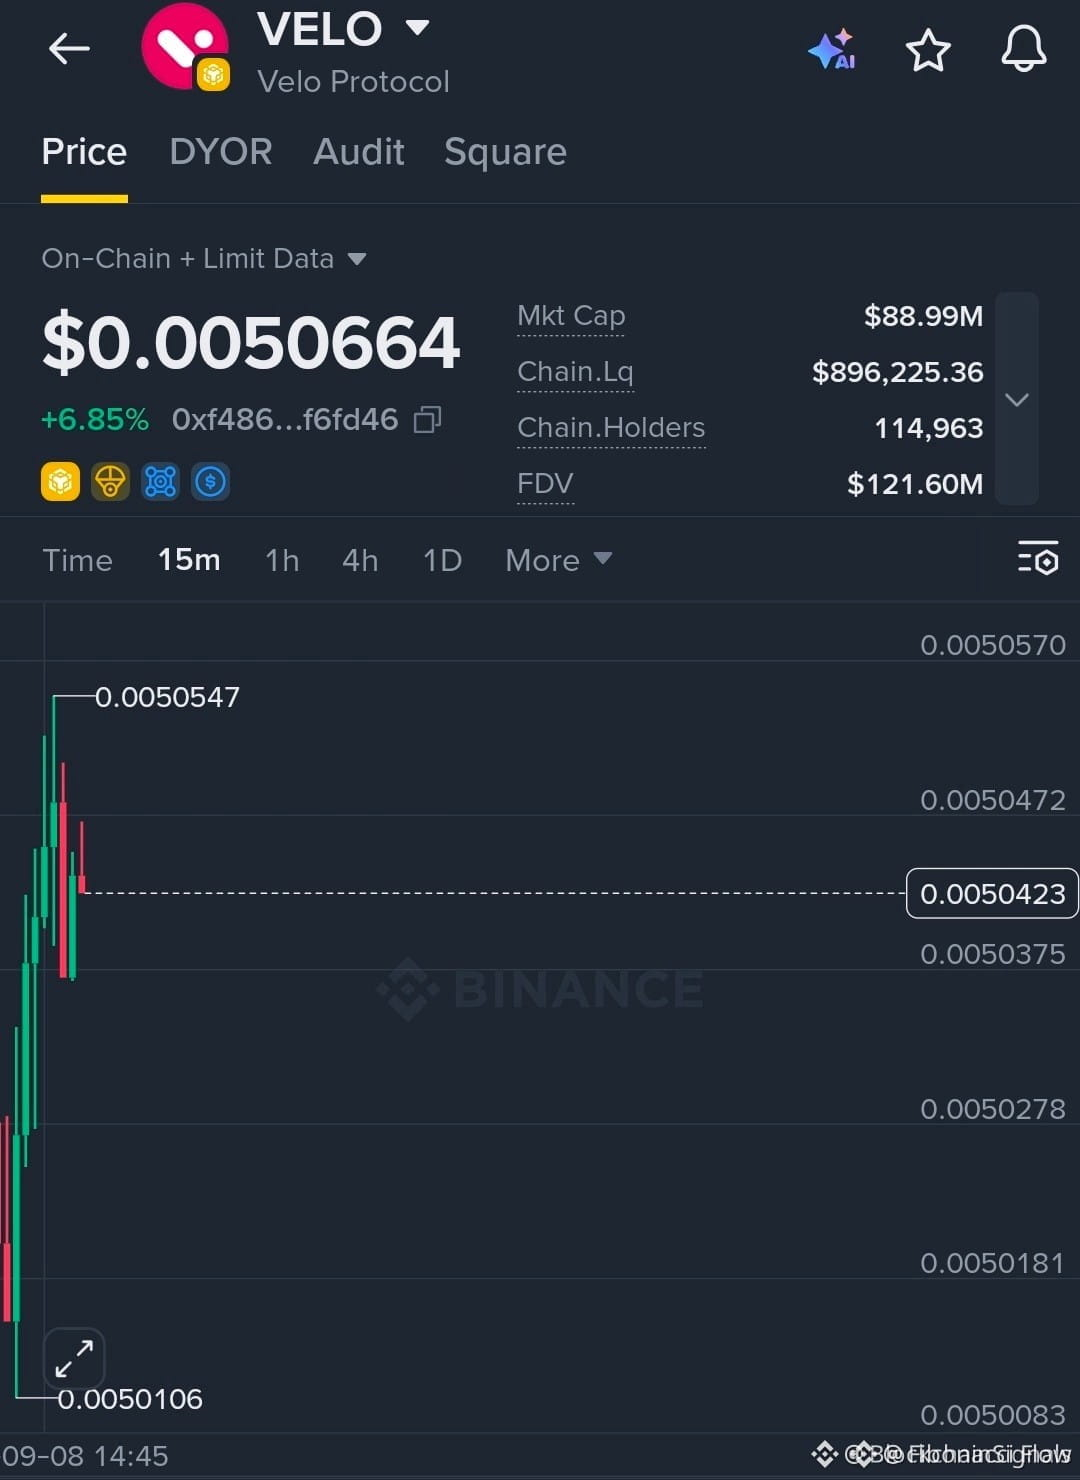
🔴 $VELO BEARS SWEEP THE SPIKE, REJECTION LOOMS! ⚡
Entry: 0.00504–0.00507 ⚡
Target: 0.00503, 0.00502, 0.00501 🚀
Stop Loss: 0.00510 ⚠️
Liquidity turned aggressive at the spike, swallowing the last bullish order block and flipping the tape into a sharp rejection. 📊 Volume spikes confirm sellers are stacking the deck, and the order flow shows a clear liquidity sweep beneath the recent high.
The short window is narrow—entry sits between 0.00504‑0.00507, with the stop barely above the last swing. 🦈 Keep an eye on the 4‑hour chart; a fresh wave of sell pressure could drive the price down to the next cluster of demand. ⚡
💬 Are you ready to ride the downside or waiting for the next liquidity trap?
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #VELO #ShortSetup #LiquiditySweep #Crypto
🦈 🔥
18
🚨 $VELODROME — SOMETHING IMPORTANT IS HAPPENING TODAY 👀
If you hold or watch $VELO, don't ignore today's date.
📅 September 13
An upcoming Binance delisting event is listed for $VELO, making this a coin worth watching closely today.
But here's the important part:
❌ Don't blindly buy
❌ Don't blindly short
Instead, watch the market reaction.
📊 Volume
📉 Price volatility
💰 Liquidity
🔥 Exchange activity
A major exchange event can create unusual volatility, and the reaction can be very different from what people expect.
👀 The real question:
Will $VELODROME experience heavy selling, or will traders already have priced the news in?
👇 What are you watching?
🔴 Heavy volatility
🟢 Recovery
👀 No major reaction
Open $VELODROME , check the chart and DYOR before taking any action.
📌 Follow Crypto Insights for important crypto events and market setups before they become old news.
#Velo #crypto #coins #TradingCommunity #CryptoInsights
2
82

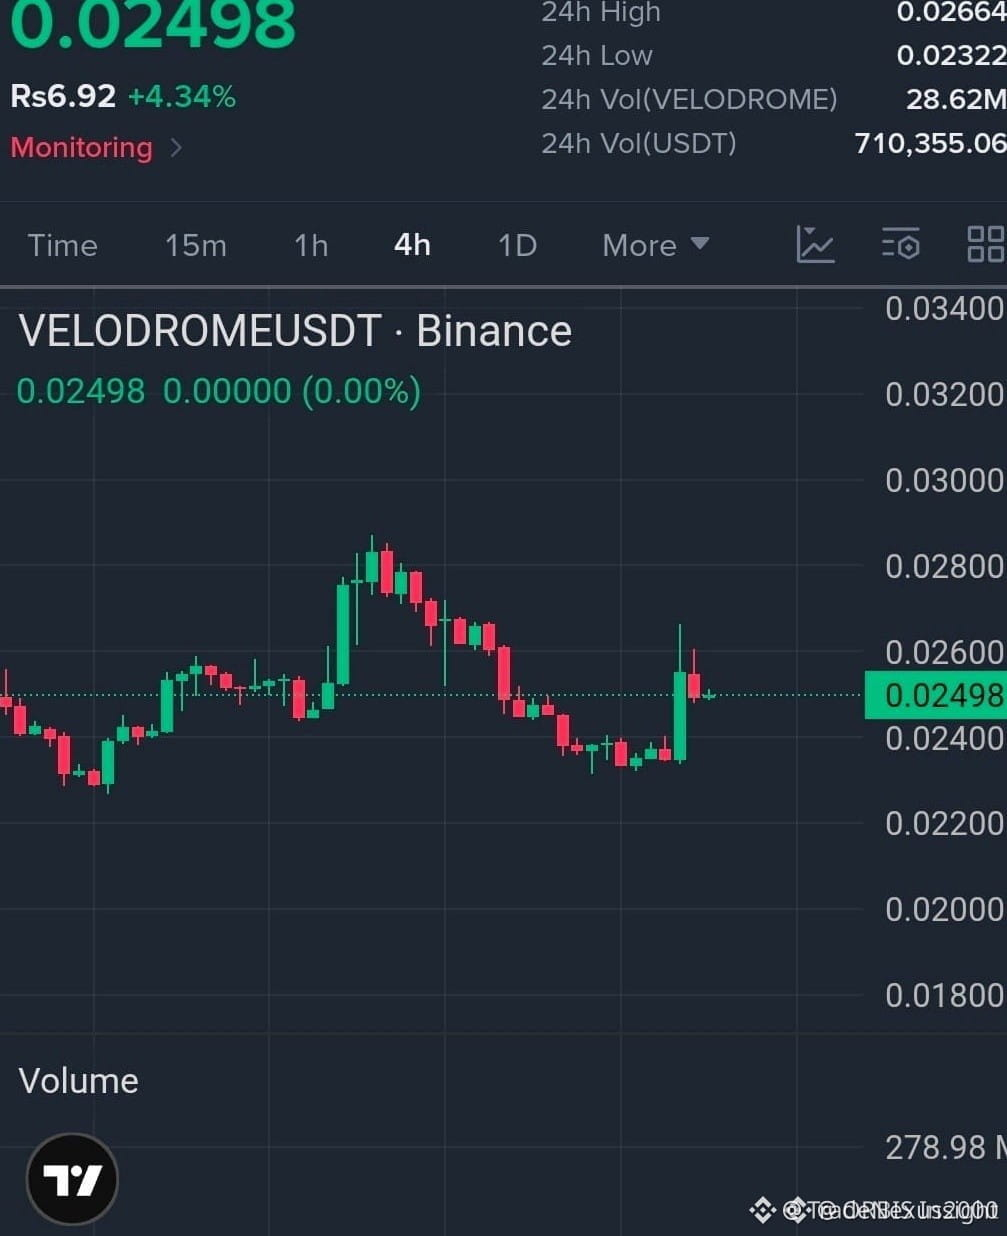
🚨 $VELO COMPRESSING AT BASE SUPPORT AS INSTITUTIONAL DEMAND BUILDS FOR EXPANSION! 📈
Entry: 0.0245 - 0.0250 ⚡
Target: 0.0266 - 0.0280 🚀
Stop Loss: 0.0232 ⚠️
📌 $VELO is displaying textbook market structure compression right above local demand. Institutional order flow shows continuous absorption of floating supply between 0.0245 and 0.0250, signaling smart money defense across the accumulation block.
📊 Volume contraction paired with higher lows indicates seller exhaustion before the liquidity hunt toward upper targets. 💡 Once buy-side liquidity is swept above the immediate high, structural expansion should follow swiftly. 💬 Are you positioning inside this accumulation zone or waiting for the breakout confirmation? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #VELO #Crypto #Trading #MarketStructure
🎯 🦈
32
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#BTCFallsBelow$83000
2,174 views
54 Discussing
2
#BitcoinSpotETFs$2.39BWeeklyNetInflow
0 views
4 Discussing
3
#FedProposesPaymentStablecoinRules
12,231 views
301 Discussing
4
#ChinaMayLetAlibabaByteDanceBuyNvidiaChips
14,494 views
352 Discussing
5
#USChinaRelease$30BTariffCutProductLists
2,381 views
41 Discussing
6
#SKoreaFSCConsidersVirtualAssetMarketMaker
11,053 views
290 Discussing
7
#ChinaIndustrialProfitGrowthSlowsFourthMonth
11,302 views
281 Discussing
8
#BitwiseFilesFinalNEARSpotETFProspectus
127,672 views
1,861 Discussing
9
#BitgetHackerMoves$83MStolenXRP
41,452 views
182 Discussing
10
#SOLSpotETFWeeklyInflow$188M
25,890 views
144 Discussing