

#forexinsights
forexinsights
79,256 views
83 Discussing
Hot
Latest

·
--
Bullish
RBA Raises Rates to 15-Year High, AUD Still Weakens
🏦 The RBA raised the cash rate by 25 basis points to 4.60%, the highest level since October 2011 and its fourth hike of 2026. The unanimous decision came as the central bank said inflation remains too high and upside price risks are materializing.
🔥 The RBA highlighted elevated energy costs from Middle East tensions, AI-related technology prices and persistent domestic price pressures, even as consumption, housing and the labor market show signs of cooling.
🎙 At the press conference, Governor Michele Bullock said the Board had also considered holding rates steady and hoped the current level would be restrictive enough, softening the tone of the official statement.
📉 AUD/USD initially rose but later fell below 0.7000, suggesting the hike was largely priced in. Australian inflation, oil prices and upcoming US data will be key ahead of the November 3 meeting.
#ForexInsights $ARB
153
·
--
Bullish
Japanese yen strengthens after Tokyo warning, USD/JPY slips toward 156.5
🇯🇵 The Japanese yen strengthened during the European session after top FX official Atsushi Mimura warned that markets should take Tokyo’s message “literally,” while stressing that Japan does not lack the resources to intervene if necessary.
📉 USD/JPY quickly retreated from above 157 to around 156.5–156.8. The yen also gained against EUR, GBP and several other major currencies, suggesting the move was driven largely by JPY-specific factors rather than broad USD weakness.
⚠️ This remains verbal intervention, with no confirmation that Japan directly bought yen during the session. However, following its previous large-scale intervention, warnings from Tokyo now carry greater weight.
📊 USD/JPY is still trading broadly within the 155–160 range. The US–Japan yield gap remains wide, so the latest yen rebound is not yet enough to confirm a sustained trend reversal.
#ForexInsights $YB $YFI $YGG
212
·
--
Bullish
Verified
USD closes a second consecutive weekly gain as US yields and Fed expectations rise
💵 The USD remained dominant during the September 21–25 week, with DXY rising from around 100.2–100.4 to nearly 101.40, its highest level in roughly two months, before easing back toward 101 by the end of the week. The move was driven mainly by a broader repricing of a more hawkish Fed outlook rather than by a single event.
📈 US flash PMI data for September stood out, with the Composite index rising to 58.4, Services reaching 58.7 and Manufacturing 57.0. Stronger growth alongside higher input costs pushed markets to price in a greater chance of another Fed rate hike in October, while also driving US Treasury yields higher.
🌍 Diverging economic conditions also supported the dollar. Eurozone PMI improved, helping the EUR hold up relatively better, while GBP came under pressure from softer UK data. AUD and CAD also weakened as broad USD strength outweighed support from RBA expectations and oil-price movements.
🇯🇵 JPY was the main late-week exception. USD/JPY approached 159 before falling sharply as signals from Japan reinforced concerns over excessive yen weakness and kept intervention risk in focus. The yen rebound helped DXY cool on Friday but did not change the broader weekly trend.
🛢️ Elevated oil prices and Middle East tensions continued to add to global inflation pressure, reinforcing the case for higher US yields. However, oil’s pullback late in the week also showed that USD gains could face temporary corrections as geopolitical expectations shift.
📅 Attention now turns to the RBA decision on September 29 and US PCE inflation on September 30. If US inflation remains firm, yields and the dollar could stay supported; a softer-than-expected PCE reading would give heavily sold currencies more room for a technical rebound.
#ForexInsights $BTC
1
1.2k
·
--
Bullish
Verified
USD Leads FX Markets After a Week of Policy Divergence
💵 The US dollar ended the week of September 14–19 as one of the strongest G10 currencies, with the DXY breaking above 100 and reaching its highest level in around seven weeks. The move was mainly driven by the Fed’s return to rate hikes, relatively resilient US economic data, and elevated Treasury yields.
🏦 The Fed raised rates by 25 basis points to 3.75–4.00% and kept the door open to further tightening if inflation does not cool sufficiently. Meanwhile, the BoE held rates at 3.75% while warning about energy-driven inflation risks, and the BoJ lifted rates to 1.25%, although its cautious guidance left the yen under pressure.
📉 This policy divergence was clearly reflected across major FX pairs. EUR/USD fell toward 1.145, GBP/USD traded around 1.33, while USD/JPY briefly moved above 158 despite Japan’s latest rate increase. The yield gap with the US remains a significant headwind for the euro, pound and especially the yen.
🛢 Oil prices remaining above $100 per barrel continue to add to global inflation pressure. For the US, high energy prices combined with resilient economic data are reinforcing expectations that rates may stay elevated for longer, while energy-importing economies such as the Eurozone and Japan face greater pressure.
📊 During September 21–25, attention will shift toward preliminary September PMI data and fresh signals from trade and policy developments. If US data remain firm and yields stay elevated, the dollar could continue to find support. Conversely, weaker PMI readings or a meaningful decline in oil prices could trigger a technical correction after the dollar’s strong weekly advance.
#ForexInsights $USDC
1
651
·
--
Bullish
Global FX overview for May 25–30 as the USD softened slightly but stayed balanced around DXY 99
📌 The FX market was relatively quiet last week, with no major rate decisions from the Fed, ECB, BoJ, or BoE. DXY mostly traded between 98.9 and 99.3, showing mild USD weakness but no clear breakout.
🌐 The main driver was risk-on sentiment as markets priced in lower US–Iran tensions and reduced risk around the Strait of Hormuz. WTI oil briefly fell around 6–6.5%, easing energy inflation concerns and reducing safe-haven demand for the USD.
💵 US data kept the greenback in a mixed position. April Core PCE rose 3.3% YoY, showing sticky inflation, while Q1 GDP was revised down to 1.6%, pointing to softer growth. This gave the USD some support from a less dovish Fed outlook, but also limited its upside.
📈 EUR, GBP, and AUD generally benefited from the risk-on backdrop and relatively firmer policy expectations. GBP/USD stayed better supported, while AUD/USD held up despite weaker Australian labor data.
🛢️ USD/CAD was the key outlier as CAD came under pressure from lower oil prices and weak Canadian growth data. This showed that crude oil remains an important driver for commodity-linked FX.
⏱️ Looking ahead, markets may wait for a fresh catalyst before forming a stronger trend. Key factors include US–Iran headlines, oil prices, Fed speeches, Europe and UK inflation data, and DXY’s reaction around 98.8–99.5.
🔎 Overall, FX stayed mostly sideways with a slight USD-bearish bias. However, sticky US inflation and a cautious Fed mean a deeper USD decline still needs stronger confirmation from data and geopolitical news.
#ForexInsights $BTC $SOL $HYPE
257
·
--
Bullish
USD accelerates after strong NFP as Forex enters the new week under pressure from US rates and Middle East risks
📌 USD was the main focus of the Forex market last week as DXY rose from around 99.2 to nearly 100.1, reflecting dual support from stronger-than-expected US jobs data and defensive demand amid Middle East tensions.
💡 May NFP came in at +172,000, far above expectations of around 85,000, while the unemployment rate held at 4.3%. The data reduced expectations for early Fed easing, pushed US yields higher, and helped USD maintain its short-term advantage.
⚠️ EUR/USD came under clear pressure, falling toward 1.152 after the NFP release, as the Eurozone remains more sensitive to higher energy prices. GBP/USD also weakened alongside the stronger dollar, while commodity currencies such as AUD lacked momentum as risk appetite stayed restrained.
⏱️ USD/JPY remained a key hotspot as it hovered near the 160 area, where intervention risk from Japan continues to rise. The US-Japan rate gap still supports the upside trend, but the higher the pair moves, the more likely volatility may widen if Tokyo signals action.
🔎 Tensions around Iran and the Strait of Hormuz remain a major variable for currency markets. Higher oil prices pressure energy-importing economies such as the Eurozone and Japan, while USD benefits from its safe-haven role and the US economy’s relatively lower vulnerability to an energy shock.
✅ Next week, markets will focus on US CPI on June 10, followed by BoJ and Fed meetings in mid-June. USD still holds the advantage if US data remains firm and geopolitical risks do not cool, but reversal risk will increase if inflation softens or Middle East tensions show signs of easing.
#ForexInsights $USDT $AUD $EUR
85
·
--
Bullish
Verified
Global FX Market Overview: USD stayed firm as oil, geopolitics, and rate expectations shaped market sentiment
📌 The FX market was driven less by isolated macro data and more by a broader mix of U.S.–Iran tensions, elevated oil prices, and shifting expectations around central bank policy. In that environment, the USD remained the strongest major currency, supported by safe-haven demand and the view that the Fed may need to keep rates higher for longer.
💡 The DXY moved close to the 99 area, its highest level in several weeks, before losing some momentum as hopes for a possible easing in U.S.–Iran tensions improved risk sentiment. Still, the USD pullback was limited because high oil prices continued to raise inflation concerns, while the latest Fed tone remained cautious.
⚠️ The EUR was the clearest weak spot among major currencies. Eurozone PMI data disappointed, with Composite PMI falling to 47.5 and Services PMI dropping to 46.4, while France showed deeper weakness. This reinforced stagflation concerns in the Eurozone and kept EUR/USD under pressure after the pair lost the 1.17 area.
🔎 USD/JPY continued to trade near elevated levels around 159 as the USD stayed strong and the BoJ offered limited support for the yen. GBP/USD remained volatile around 1.33–1.34, while AUD/USD weakened toward the 0.713–0.715 area due to softer China data and weaker risk appetite.
⏱️ Commodity currencies were mixed. CAD received partial support from higher oil prices, but the stronger USD limited its upside. AUD and NZD remained more vulnerable because of their close link to China’s outlook and global risk sentiment. In EM Asia, stronger U.S. yields, high oil prices, and USD demand kept pressure on regional currencies.
✅ Looking ahead, oil prices, U.S.–Iran headlines, and comments from the Fed, ECB, and BoJ will remain the main FX drivers. The short-term bias still favors the USD if oil stays elevated and geopolitical risks remain unresolved, but a fast correction is possible if risk-on sentiment returns.
#ForexInsights
1
1
849
·
--
Bullish
The British pound came under pressure as the UK political crisis expanded into fiscal risk
📌 The British pound fell sharply after Health Secretary Wes Streeting resigned and publicly called for a Labour leadership contest, increasing pressure on Prime Minister Keir Starmer after the party’s heavy losses in local elections.
💷 GBP briefly dropped 0.2% to 1.3502 USD before stabilizing around 1.3518 USD, while also weakening against the euro to around 86.68 pence/EUR. The move shows that currency markets are the most sensitive channel as investors begin pricing in UK political risk.
📉 UK government bonds were more stable, with the 10-year gilt yield falling 4.2 basis points to 5.026%, while the FTSE 100 still rose slightly by 0.38%. This suggests investors have not moved into full panic mode, but are becoming more defensive amid policy uncertainty.
⚠️ The key issue is not only the resignation of a senior minister, but the possibility that the crisis could lead to a shift in fiscal direction. If a new leader signals looser spending, tax changes, or weaker budget discipline, pressure on GBP and gilts could return.
🔎 In the short term, markets will watch whether a leadership contest is formally triggered. If the crisis is contained quickly, GBP could recover part of its losses; otherwise, any deeper signs of division within Labour may keep the pound under pressure.
#ForexInsights $BTC $TON $XMR
218
·
--
Bullish
RBA Raises Rates to 4.10% as the Middle East Oil Shock Starts Spilling Into Currency Markets
🌍 The FX market opened the week cautiously, with the U.S. dollar holding firm on safe-haven demand while higher oil prices continued to raise concerns about a new wave of global inflation pressure.
🏦 The RBA then delivered a 25 bps rate hike to 4.10%, marking its second consecutive increase. The key detail was the narrow 5-4 vote, showing policymakers remain divided even as the central bank acknowledged that rising fuel costs and higher inflation expectations could keep inflation elevated for longer than previously expected.
📉 This suggests central banks are starting to respond more clearly to the war-driven oil shock, but the market still lacks consensus on how far tightening may go from here. That leaves AUD supported by the rate backdrop, while short-term volatility is likely to stay elevated as traders continue repricing a busy week of major central bank meetings.
#ForexInsights #MacroUpdate $AR $B3 $CC
3
13
6.8k
·
--
Bullish
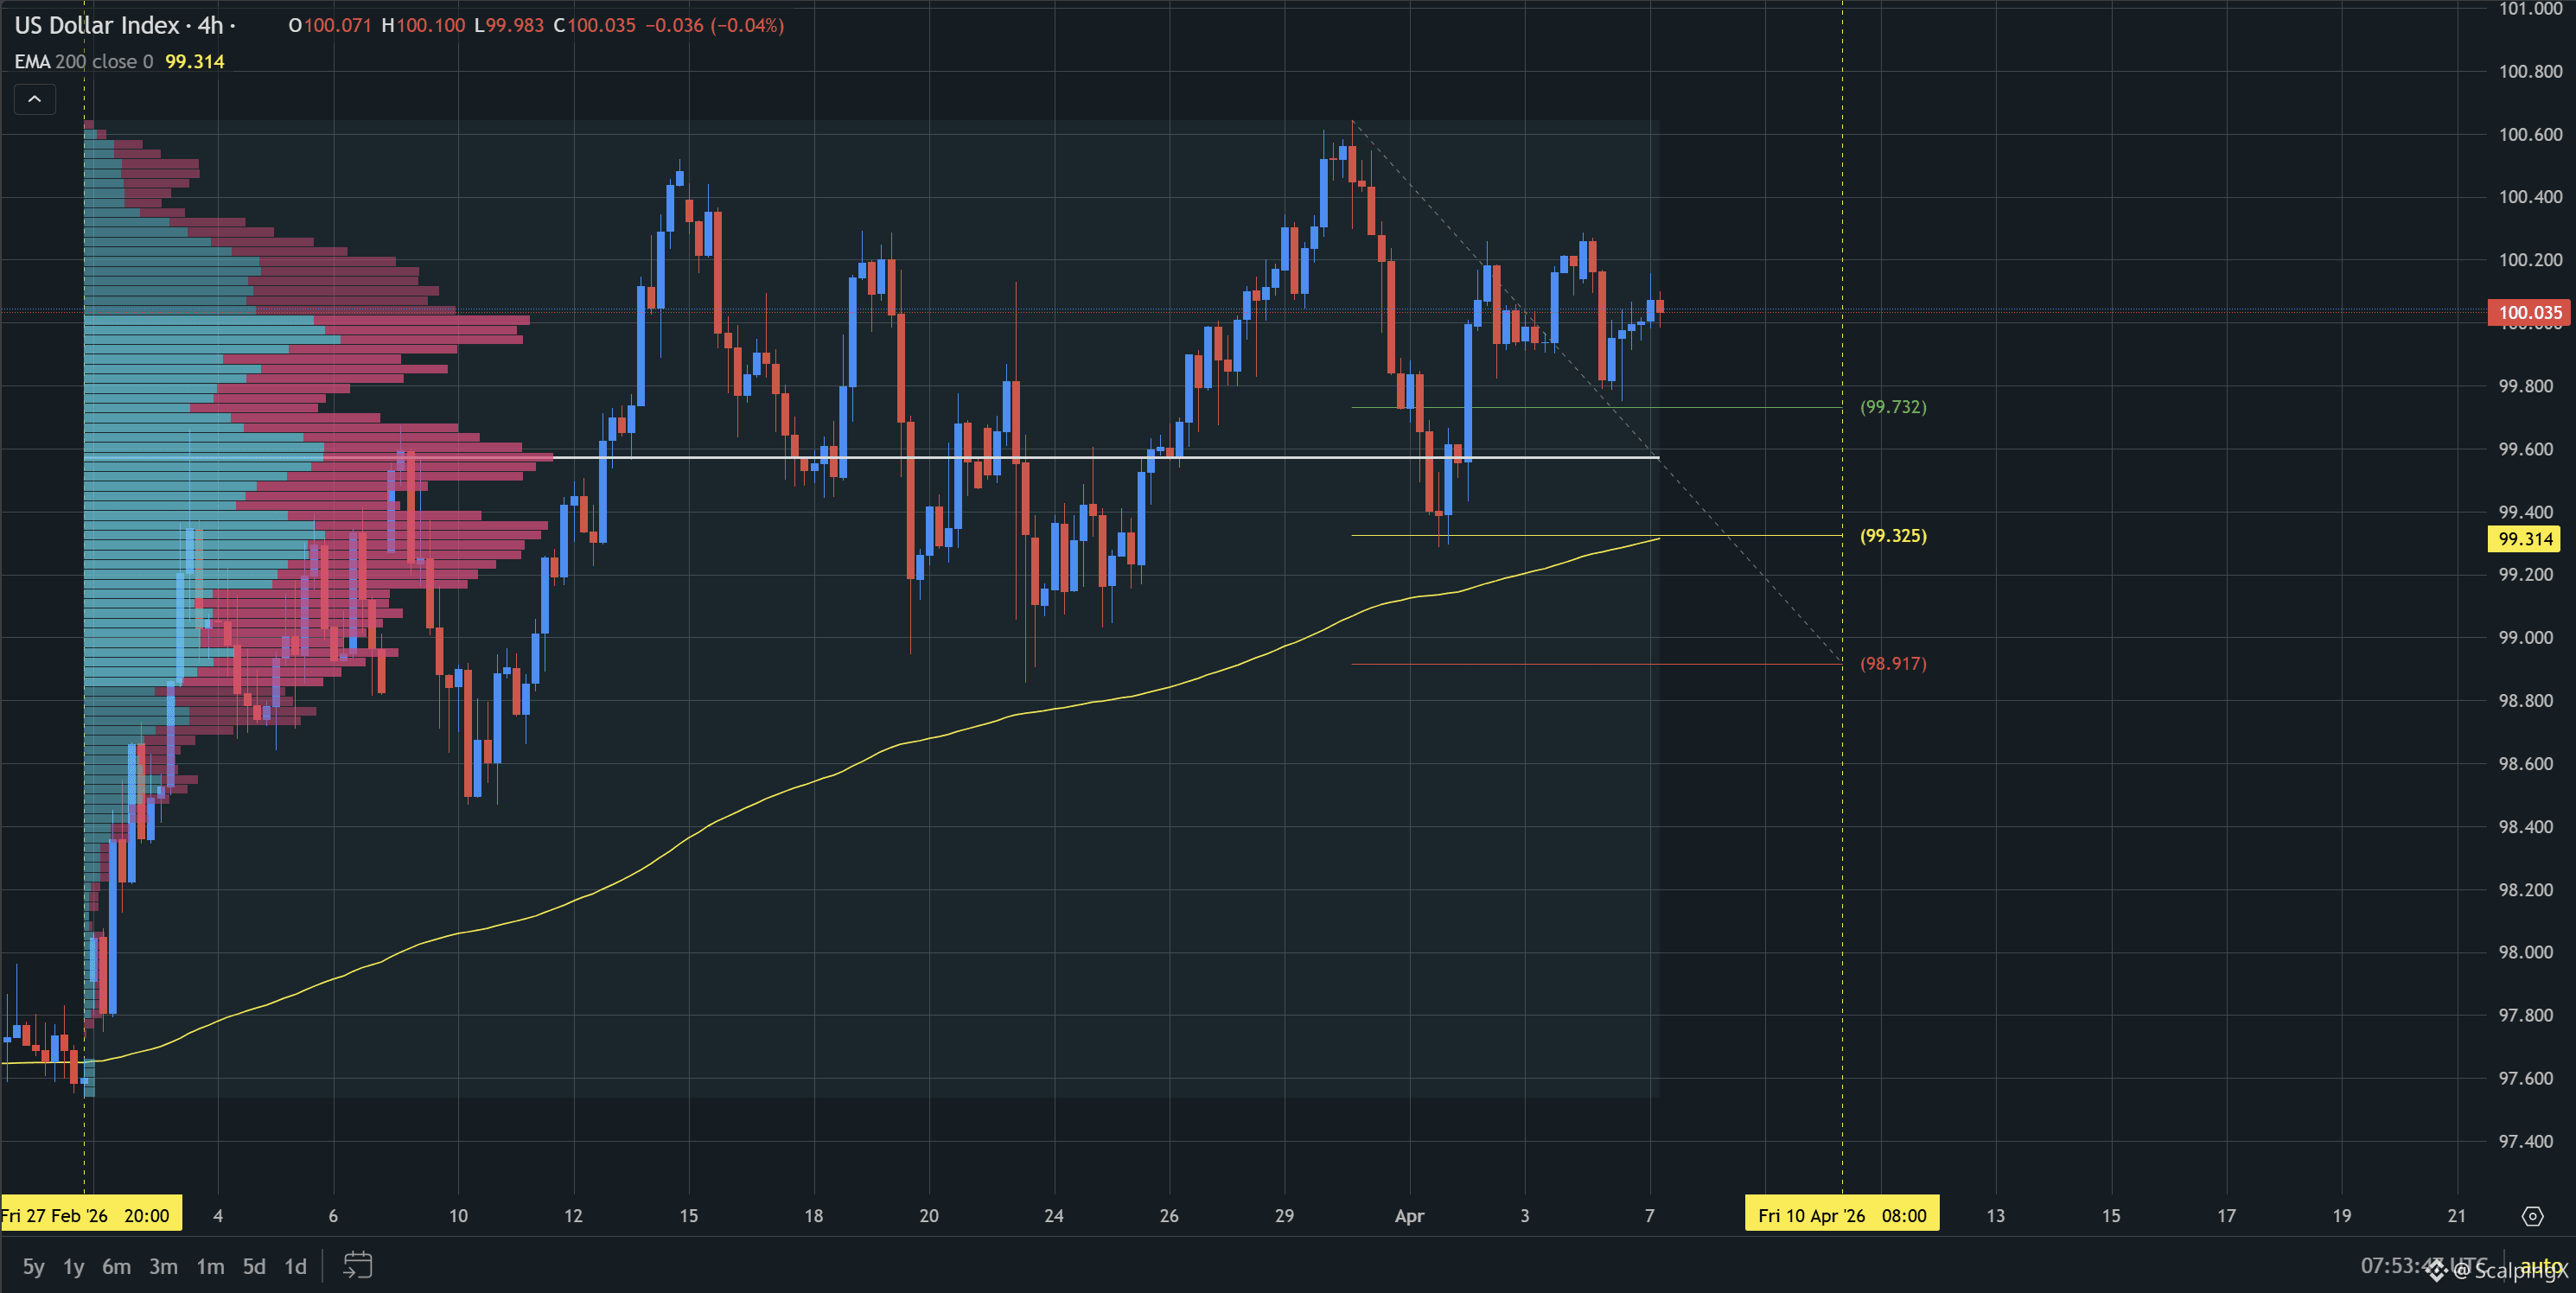
#DXY
SC02 H4 - pending Buy order. Entry lies within HVN + is not affected by any weak zone, the current support zone is approximately 0.41% wide. The uptrend has been ongoing for 38 days 8 hours, with the maximum recorded price increase of 3.06%. If price loses this support zone, the trend will most likely reverse to the downside.
#TradingSetup #ForexInsights $BTC $ETH $SOL
760
·
--
Bearish
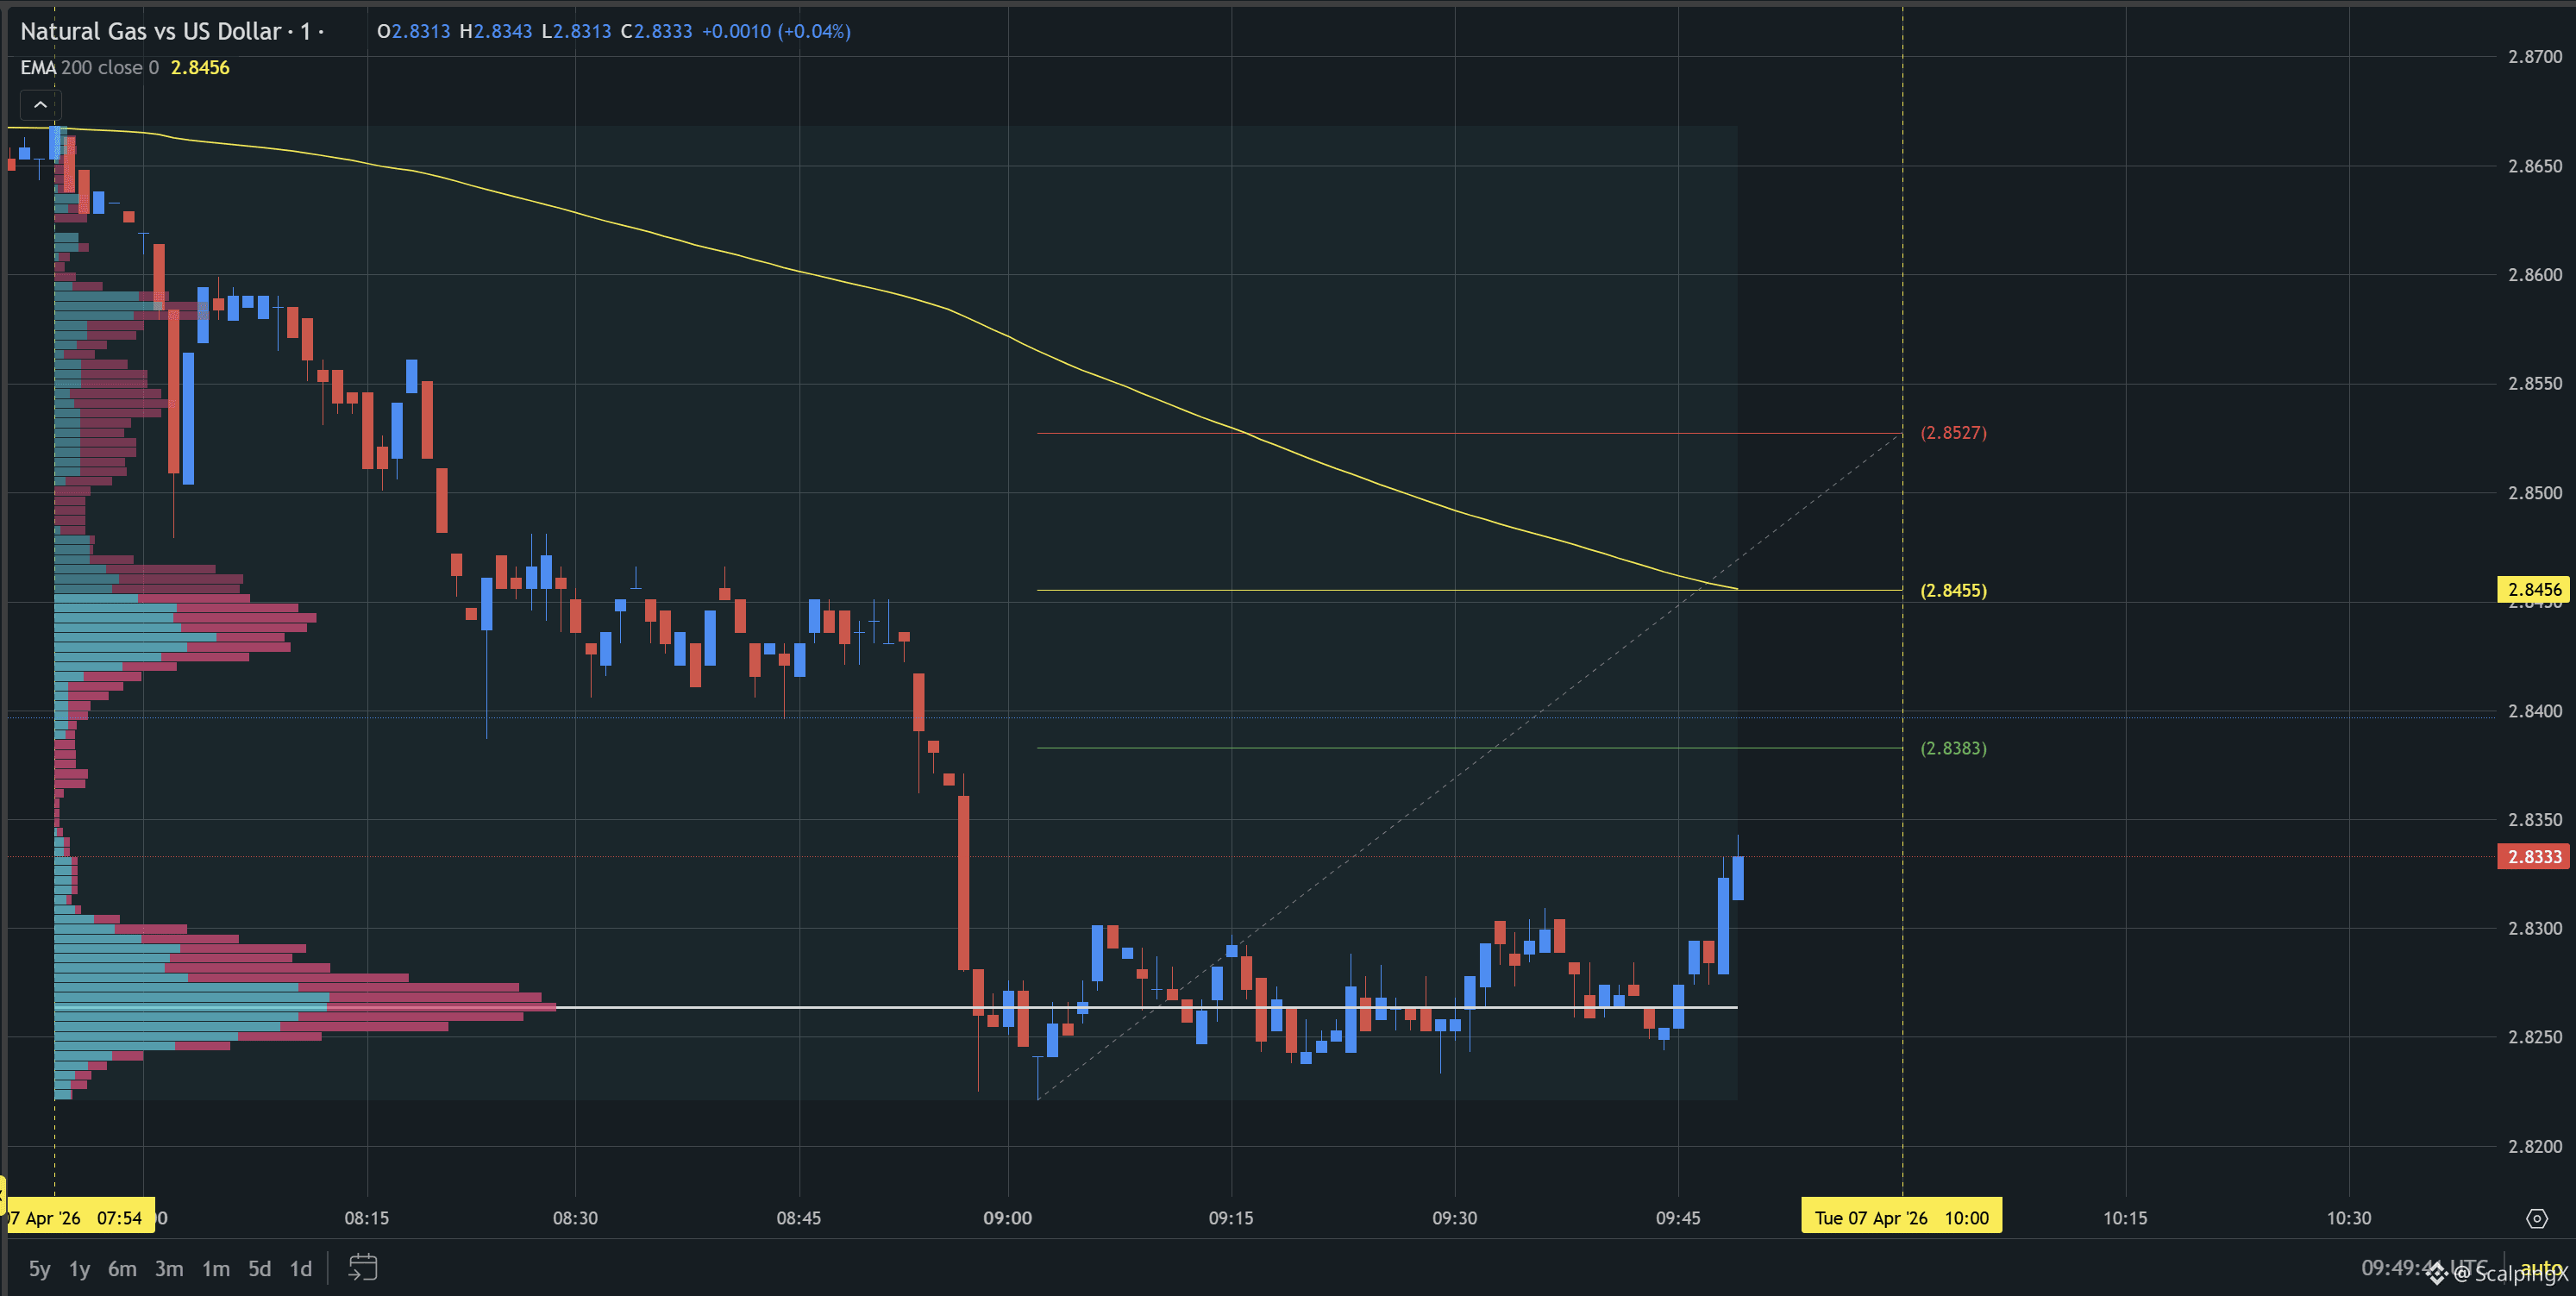
#XNG /USD
SC02 M1 - pending Sell order. Entry lies within LVN + is not affected by any weak zone, the current resistance zone is approximately 0.25% wide. The downtrend has been ongoing for 1 hour 56 minutes, with the maximum recorded price decrease of 1.56%. If price breaks this resistance zone, the trend will most likely reverse to the upside.
#TradingSetup #ForexInsights $DOGE $SUI $LTC
1
829
·
--
Bullish
The USD dominated FX on May 11–16 as hot US inflation, higher yields, and the oil shock pushed capital back into the greenback
📌 The USD had one of its strongest weeks in months, with DXY rising from around 98 toward the 99+ area. The move was not only driven by safe-haven demand, but also by a major repricing of the US rate outlook after hotter-than-expected inflation data.
💡 US CPI rose 3.8% year-on-year, while PPI climbed to 6.0%, showing that the energy shock is starting to feed into broader prices. With oil holding near $100 per barrel due to Iran tensions and Hormuz risks, the market quickly pushed back expectations for early Fed easing.
📈 Higher US Treasury yields, moving around the 4.5–4.7% area, strengthened the yield advantage of the USD. This pressured EUR/USD, GBP/USD, AUD/USD, and NZD/USD, while USD/JPY continued moving toward the 158–160 zone despite intervention risks from Japan.
🔎 EUR/USD showed the clearest weakness, falling for five straight sessions and returning toward the 1.16 handle. GBP gained little support from stronger UK GDP, while AUD and NZD were hit by weaker risk appetite and reduced demand for commodity currencies.
🌐 Emerging-market FX also came under pressure, especially in Asian economies exposed to higher energy import costs. INR, IDR, KRW, PHP, and THB remained vulnerable to both USD strength and elevated oil prices, while carry-supported currencies such as MXN and ZAR showed better resilience.
⚠️ The key point is that FX did not fully follow the risk-on tone in US equities. In currency markets, the USD is currently acting as both a higher-yielding currency and a geopolitical safe-haven, making it difficult for other major currencies to recover strongly.
✅ Looking ahead, the short-term bias still favors the USD if oil stays high, US yields remain firm, and Hormuz tensions do not ease clearly. The biggest reversal risk would be a sharp drop in oil or a strong diplomatic signal that reduces both inflation premium and safe-haven demand.
#ForexInsights $TON $ADA $DOGE
130
·
--
Bullish
USD strengthens as hotter-than-expected US inflation revives Fed rate-hike expectations
📌 The US Dollar Index rose to 98.48, up 0.6% for the week, as markets adjusted their monetary policy expectations after a series of stronger-than-expected US inflation readings.
💡 Treasury yields also moved higher, with the 2-year yield rising to 3.9773% and the 10-year yield reaching 4.4669%, showing that investors are pricing in the possibility of a more hawkish Fed stance.
🔎 According to CME FedWatch, the probability of a Fed rate hike in December has climbed to 31.8%, up from 16% last week. This shift has given the dollar stronger support against the euro and the British pound.
⚠️ Safe-haven flows also helped lift the greenback, as Iran-related tensions remain unresolved and the Trump-Xi summit stays at the center of global market attention.
📊 The yuan strengthening to its highest level in three years is a positive signal for trade negotiation expectations, but not enough to weaken the dollar’s safe-haven role in the short term.
✅ Over the next 24–48 hours, the dollar may retain its advantage if US yields remain elevated and the US-China summit does not produce a strong enough signal to trigger a clear risk-on move.
#ForexInsights $BTC $HYPE $TON
89
·
--
Bullish
Global FX Market Overview, May 4–9 – USD caught between Hormuz risk and monetary policy divergence
📌 Over the past week, the FX market was driven more by geopolitics than by traditional macro data. Tensions around the Strait of Hormuz pushed WTI oil briefly toward $102.5 per barrel before prices pulled back sharply as de-escalation signals emerged, causing capital flows to swing quickly between risk-off and risk-on.
💡 DXY moved narrowly around the 98 area, showing that the USD still retained its safe-haven role during stress periods but lacked enough strength to form a clear uptrend. Pressure came from expectations that the Fed would remain more cautious than the ECB, BoE, and RBA, while weaker-than-expected US labor data only played a secondary role.
🔎 EUR/USD climbed toward 1.174–1.175, GBP/USD held around 1.353–1.360, while AUD and NZD stood out as risk appetite returned and the RBA raised rates to 4.35%. CAD was also relatively supported by still-elevated oil prices, helping USDCAD remain more stable than many other major pairs.
⚠️ USD/JPY was the most volatile pair, briefly approaching 160 before falling back to the 154–155 area after BoJ intervention, then recovering toward 156–157. This pair is now reflecting safe-haven demand, carry trade flows, and intervention risk at the same time, so the chance of sharp volatility remains high.
⏱️ Emerging-market currencies faced clearer pressure, especially in energy-importing economies such as IDR, KRW, and INR. When oil stays high, import costs and inflation pressure make EM FX vulnerable during risk-off phases, even though some recovery appeared when markets priced in lower geopolitical tension.
✅ Next week, the key levels to watch are WTI oil around $100–105 and the US 10Y yield near 4.45%. If Hormuz tensions keep easing, the USD may remain soft while EUR, GBP, and AUD stay supported; otherwise, a new escalation headline could quickly bring USD, JPY, and CHF back to the center of defensive flows.
#ForexInsights $BTC $BNB $TON
106
·
--
Bullish
#USD /CAD
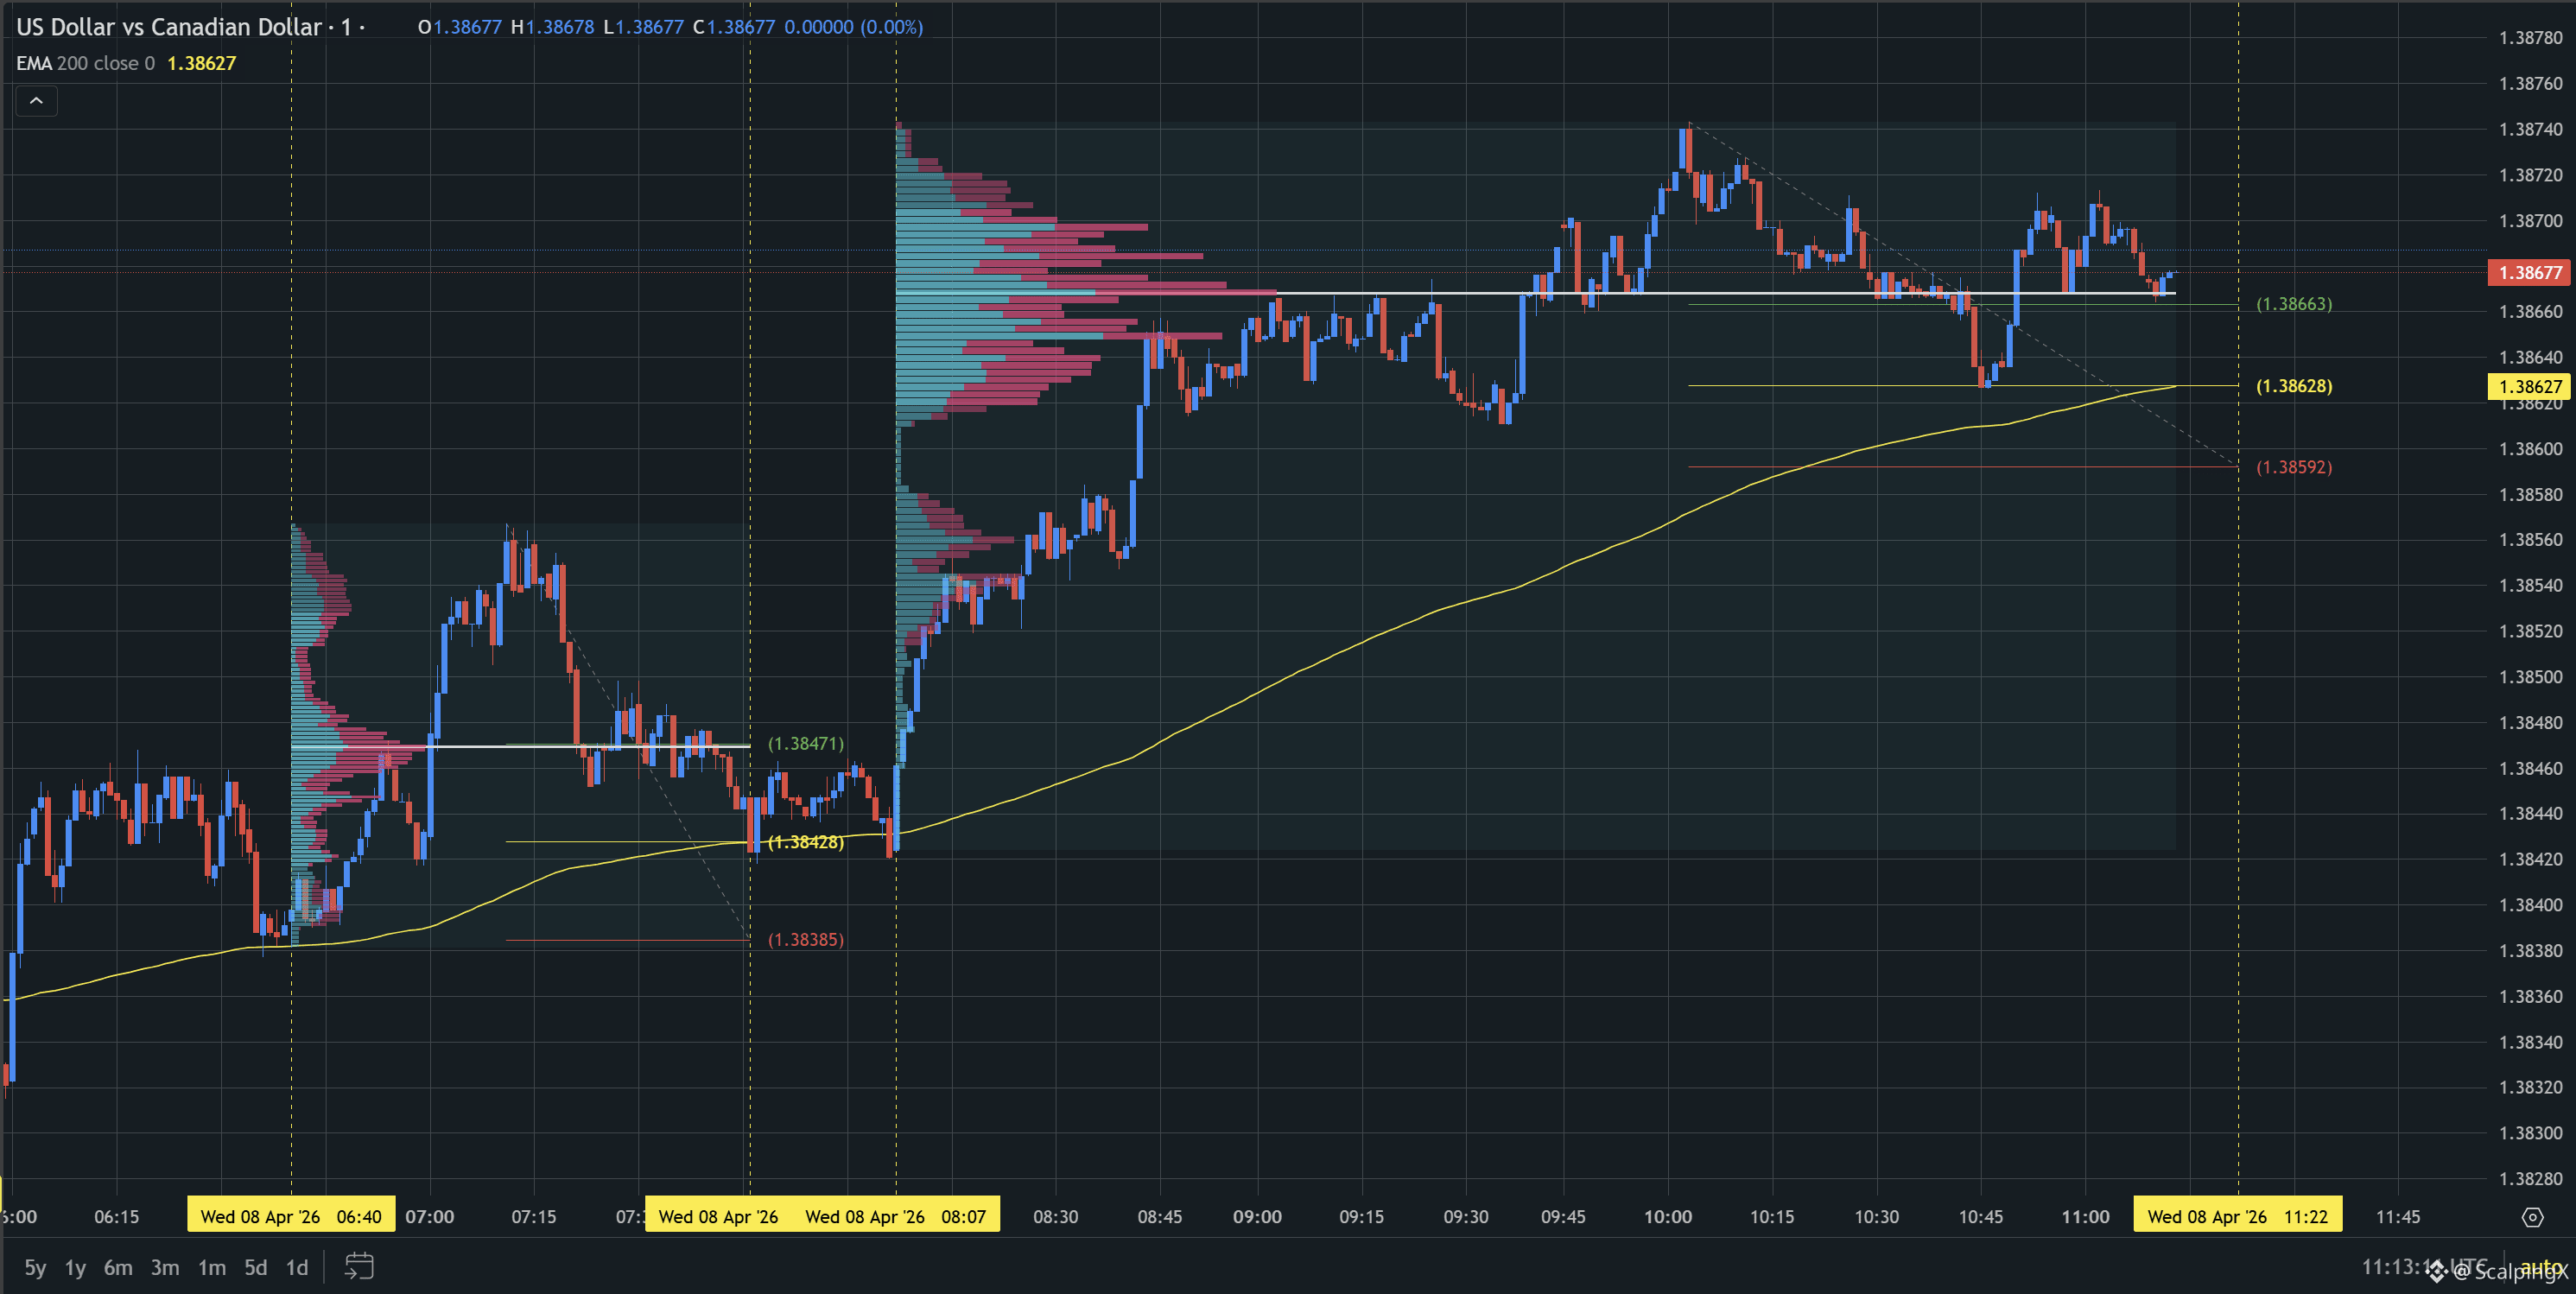
SC02 M1 - pending Buy order. Entry lies within LVN + satisfies positive simplification with a very profitable previous Buy order, the current support zone is approximately 0.03% wide. The uptrend has been ongoing for 3 hours 7 minutes, with the maximum recorded price increase of 0.23%. If price loses this support zone, the trend will most likely reverse to the downside.
#TradingSetup #ForexInsights $CAKE $CC $DOT
175
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#FedMinutesFocusOnOctoberPause
11,219 views
310 Discussing
2
#BinanceLaunchesBinanceIntelligence
917,526 views
5,589 Discussing
3
#RobinhoodAdds$25MInBitcoinToBalanceSheet
650 views
27 Discussing
4
#SP500AndNasdaqHitRecordHighs
3,931 views
168 Discussing
5
#USMortgageRatesRiseTo7.49%
3,871 views
147 Discussing
6
#BTCFallsBelow$84K
71,157 views
191 Discussing
7
#DubaiVARAIssuesReserveAssetAuditCircular
27,856 views
756 Discussing
8
#SECApproves3XBitcoinETF
26,854 views
617 Discussing
9
#WinklevossFilesSpotZcashETFApplication
35,138 views
733 Discussing
10
#SouthKoreaAITradeLiftsWorldcoinTo$7.41B
3,785 views
52 Discussing