

#earningsseaso
earningsseaso
188 views
9 Discussing
Hot
Latest
$AMZN is crashing in premarket trading - down 7.1% to $226.48
Why the market is punishing Amazon today:
Q3 earnings miss:
Revenue: $201.94B vs. $202.22B expected ❌
EPS: $1.89 vs. $1.97 expected ❌
Even a record operating margin of 13.9% couldn’t save the day.
Weak Q4 guidance:
Midpoint of the guidance range: $243.5B, below Wall Street’s higher expectations. The holiday quarter is shaping up to be weak.
The real knockout blow - AI capital expenditures:
This is why Nasdaq futures are down -2.19% and tech stocks are falling:
Full-year capital expenditures: $220 billion in 2026 - all for AI data centers
Free cash flow: -$42.4 billion over the past twelve months, versus +$14.8B last year
The CEO says spending in 2027 will be “much higher”
The market’s question: When will all this AI spending actually start generating profits?
Amazon and Intel alone are expected to erase $300B in market value today. This, combined with Alphabet’s -12% drop yesterday, means the AI trade is in trouble.
Is this a buying opportunity or the beginning of the AI bubble bursting?
Please follow
#amazon #stockmarket #EarningsSeaso #EarningsSeason
#AmazonSharesFallAbout7%InPremarketTrading
$AMZN is crashing in premarket trading - down 7.1% to $226.48
Why the market is punishing Amazon today:
Q3 earnings miss:
Revenue: $201.94B vs. $202.22B expected ❌
EPS: $1.89 vs. $1.97 expected ❌
Even a record operating margin of 13.9% couldn’t save the day.
Weak Q4 guidance:
Midpoint of the guidance range: $243.5B, below Wall Street’s higher expectations. The holiday quarter is shaping up to be weak.
The real knockout blow - AI capital expenditures:
This is why Nasdaq futures are down -2.19% and tech stocks are falling:
Full-year capital expenditures: $220 billion in 2026 - all for AI data centers
Free cash flow: -$42.4 billion over the past twelve months, versus +$14.8B last year
The CEO says spending in 2027 will be “much higher”
The market’s question: When will all this AI spending actually start generating profits?
Amazon and Intel alone are expected to erase $300B in market value today. This, combined with Alphabet’s -12% drop yesterday, means the AI trade is in trouble.
Is this a buying opportunity or the beginning of the AI bubble bursting?
Please follow
#amazon #stockmarket #EarningsSeaso #EarningsSeason
#AmazonSharesFallAbout7%InPremarketTrading
Why the market is punishing Amazon today:
Q3 earnings miss:
Revenue: $201.94B vs. $202.22B expected ❌
EPS: $1.89 vs. $1.97 expected ❌
Even a record operating margin of 13.9% couldn’t save the day.
Weak Q4 guidance:
Midpoint of the guidance range: $243.5B, below Wall Street’s higher expectations. The holiday quarter is shaping up to be weak.
The real knockout blow - AI capital expenditures:
This is why Nasdaq futures are down -2.19% and tech stocks are falling:
Full-year capital expenditures: $220 billion in 2026 - all for AI data centers
Free cash flow: -$42.4 billion over the past twelve months, versus +$14.8B last year
The CEO says spending in 2027 will be “much higher”
The market’s question: When will all this AI spending actually start generating profits?
Amazon and Intel alone are expected to erase $300B in market value today. This, combined with Alphabet’s -12% drop yesterday, means the AI trade is in trouble.
Is this a buying opportunity or the beginning of the AI bubble bursting?
Please follow
#amazon #stockmarket #EarningsSeaso #EarningsSeason
#AmazonSharesFallAbout7%InPremarketTrading
1
41
·
--
#BinancePick Based on the historical performance of the last 8 quarters, I expect Alphabet $GOOGL to beat earnings expectations again. The main driver will be Google Cloud revenue growth and the successful integration of Gemini AI features into Search and advertising services. Technically, the stock is trading in positive territory, and I expect a strong bullish reaction as soon as the official figures are announced. What is your outlook for the stock’s movement?
#BinancePick #EarningsSeaso
$GOOGLB
#BinancePick Based on the historical performance of the last 8 quarters, I expect Alphabet $GOOGL to beat earnings expectations again. The main driver will be Google Cloud revenue growth and the successful integration of Gemini AI features into Search and advertising services. Technically, the stock is trading in positive territory, and I expect a strong bullish reaction as soon as the official figures are announced. What is your outlook for the stock’s movement?
#BinancePick #EarningsSeaso
$GOOGLB
#BinancePick #EarningsSeaso
$GOOGLB
1
67
·
--
Bullish
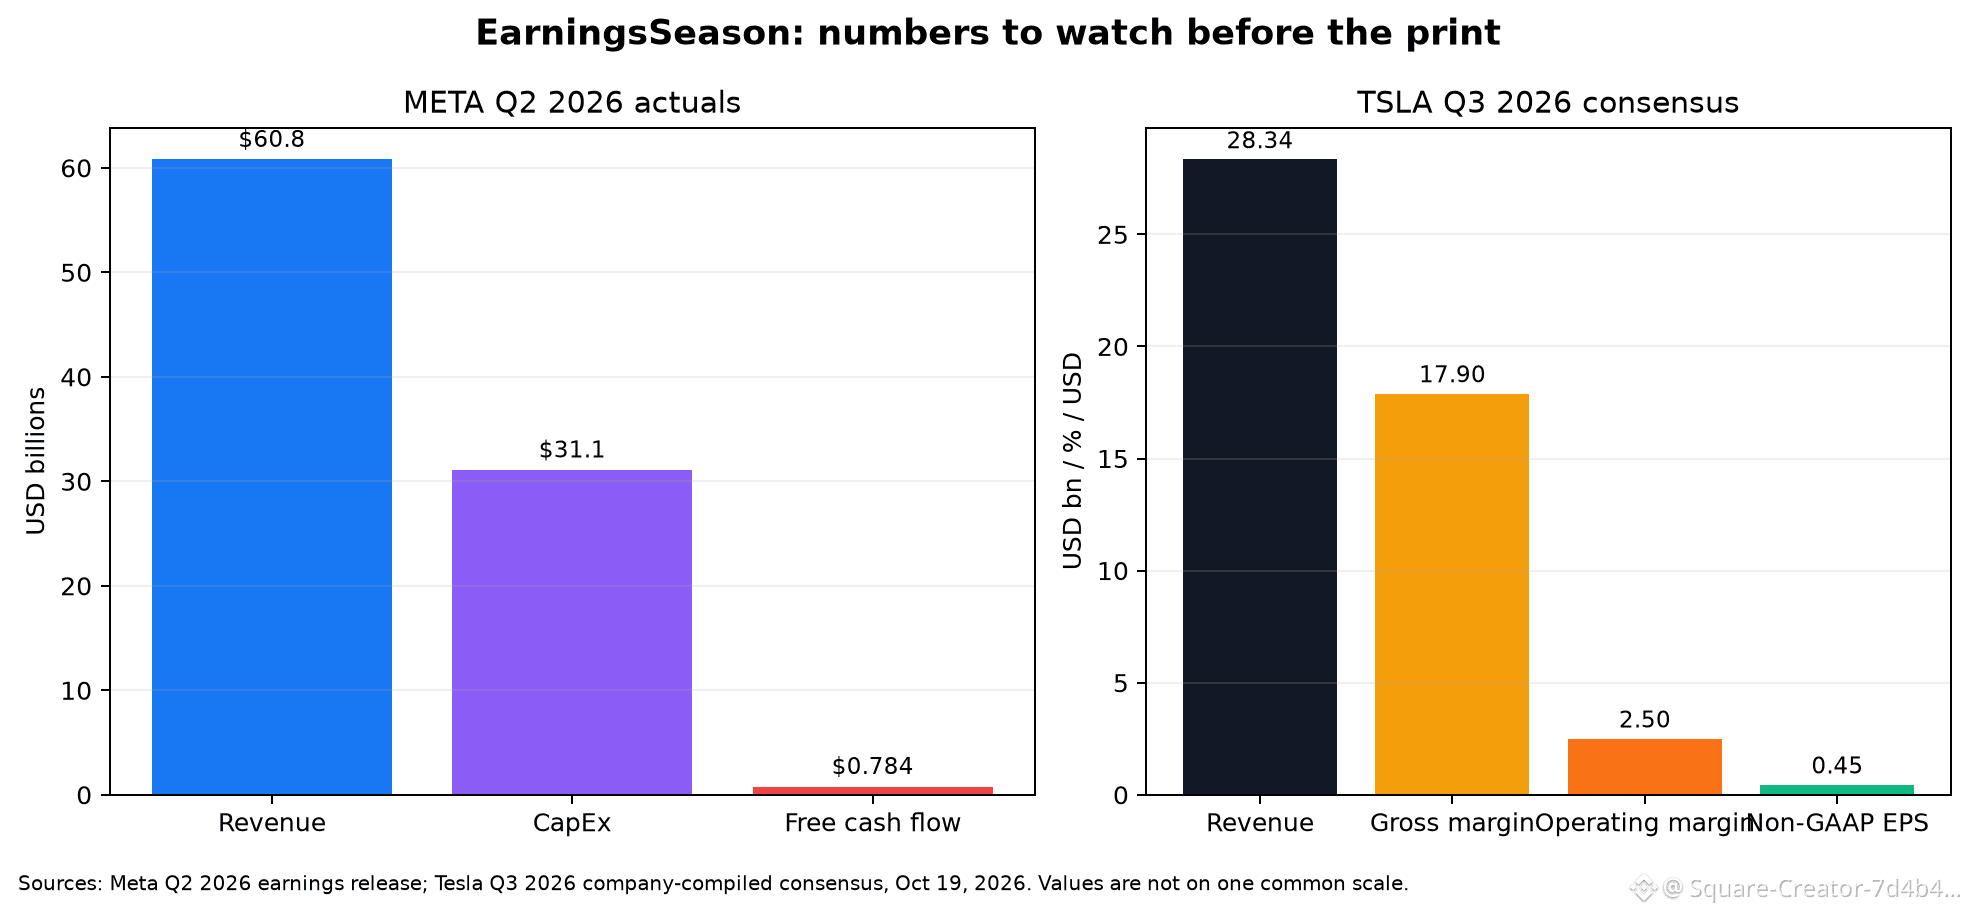
META vs. TSLA before #EarningsSeason: I choose META, but not just because of the hype around Muse.
In Q2, Meta's revenue grew 28% to $60.8B, and ad prices rose 12%. But CapEx was $31.1B, while free cash flow was only $0.784B, with annual CapEx guidance of $130–145B.
For Tesla, the official Q3 consensus is $28.34B in revenue and a 17.9% gross margin, but expected free cash flow is -$4.51B. The Roadster is an engineering marvel, but it won't generate profits until there is measurable production, scale, and margins.
My plan: keep risk small ahead of the announcement, then increase my exposure to META only if results support ad growth, guidance, and margins without CapEx getting out of control. As for TSLA, I need evidence that deliveries are translating into cash and margins—not just a tech showcase.
The real question: Who proves that AI spending is turning into cash flow?
#EarningsSeaso eason $METAB TA $TSLAB
META vs. TSLA before #EarningsSeason: I choose META, but not just because of the hype around Muse.
In Q2, Meta's revenue grew 28% to $60.8B, and ad prices rose 12%. But CapEx was $31.1B, while free cash flow was only $0.784B, with annual CapEx guidance of $130–145B.
For Tesla, the official Q3 consensus is $28.34B in revenue and a 17.9% gross margin, but expected free cash flow is -$4.51B. The Roadster is an engineering marvel, but it won't generate profits until there is measurable production, scale, and margins.
My plan: keep risk small ahead of the announcement, then increase my exposure to META only if results support ad growth, guidance, and margins without CapEx getting out of control. As for TSLA, I need evidence that deliveries are translating into cash and margins—not just a tech showcase.
The real question: Who proves that AI spending is turning into cash flow?
#EarningsSeaso eason $METAB TA $TSLAB
In Q2, Meta's revenue grew 28% to $60.8B, and ad prices rose 12%. But CapEx was $31.1B, while free cash flow was only $0.784B, with annual CapEx guidance of $130–145B.
For Tesla, the official Q3 consensus is $28.34B in revenue and a 17.9% gross margin, but expected free cash flow is -$4.51B. The Roadster is an engineering marvel, but it won't generate profits until there is measurable production, scale, and margins.
My plan: keep risk small ahead of the announcement, then increase my exposure to META only if results support ad growth, guidance, and margins without CapEx getting out of control. As for TSLA, I need evidence that deliveries are translating into cash and margins—not just a tech showcase.
The real question: Who proves that AI spending is turning into cash flow?
#EarningsSeaso eason $METAB TA $TSLAB
92
·
--
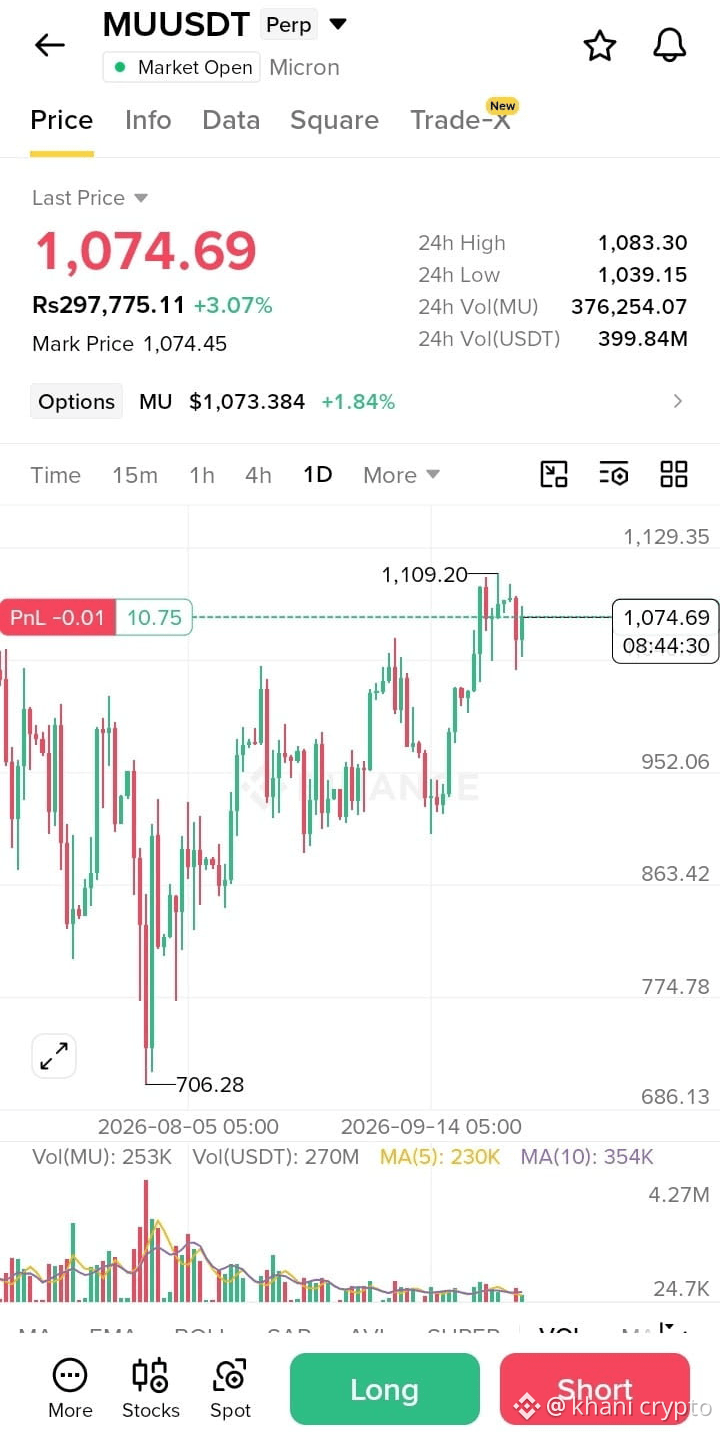
$MU 📈
The stock $MU rose from 706 to 1,074 before the announcement of the fourth-quarter results of fiscal year 2026.
📊 My view: positive, but cautious.
✅ Continued demand for HBM and AI supports the memory cycle.
✅ The gross profit margin may exceed the 86% level.
⚠️ Trading volumes are declining despite the ongoing rise, which is a signal worth monitoring.
I opened a small Long position, and after the results are released I’ll determine the next step based on the forward guidance:
🟢 If guidance is strong → I’ll continue holding.
🔴 If it’s weak → I’ll exit the trade.
⚠️ Risk: If margins come in below expectations, we could see a sharp pullback.
Not financial advice. Do your own research before making any decision.
#EarningsSeaso
{future}(MUUSDT)
$MU 📈
The stock $MU rose from 706 to 1,074 before the announcement of the fourth-quarter results of fiscal year 2026.
📊 My view: positive, but cautious.
✅ Continued demand for HBM and AI supports the memory cycle.
✅ The gross profit margin may exceed the 86% level.
⚠️ Trading volumes are declining despite the ongoing rise, which is a signal worth monitoring.
I opened a small Long position, and after the results are released I’ll determine the next step based on the forward guidance:
🟢 If guidance is strong → I’ll continue holding.
🔴 If it’s weak → I’ll exit the trade.
⚠️ Risk: If margins come in below expectations, we could see a sharp pullback.
Not financial advice. Do your own research before making any decision.
#EarningsSeaso
The stock $MU rose from 706 to 1,074 before the announcement of the fourth-quarter results of fiscal year 2026.
📊 My view: positive, but cautious.
✅ Continued demand for HBM and AI supports the memory cycle.
✅ The gross profit margin may exceed the 86% level.
⚠️ Trading volumes are declining despite the ongoing rise, which is a signal worth monitoring.
I opened a small Long position, and after the results are released I’ll determine the next step based on the forward guidance:
🟢 If guidance is strong → I’ll continue holding.
🔴 If it’s weak → I’ll exit the trade.
⚠️ Risk: If margins come in below expectations, we could see a sharp pullback.
Not financial advice. Do your own research before making any decision.
#EarningsSeaso
28
·
--
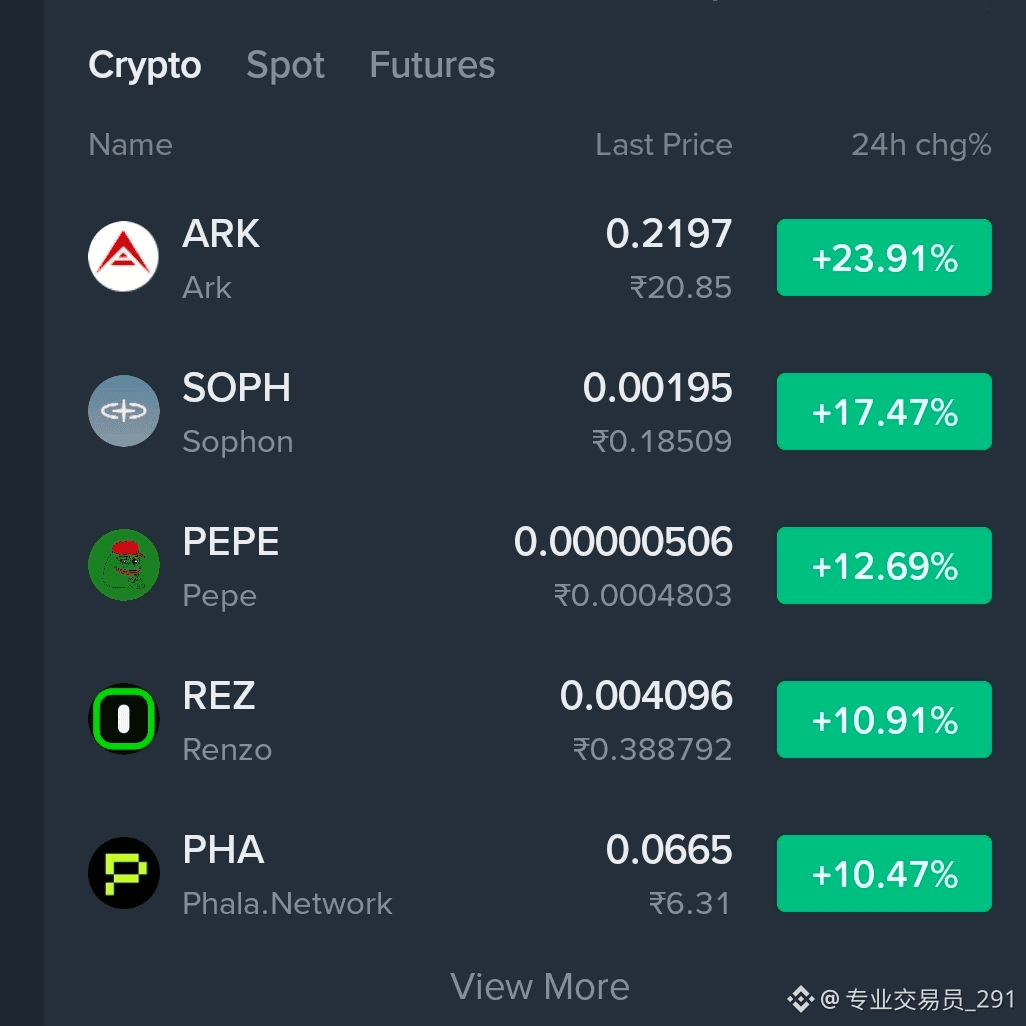
I’m totally breaking down, guys 😭💔 Everyone keeps saying $PEPE, $PHA, and are ready for a massive 50–80% pump 🚀📈 But my balance is literally ZERO 😩💸 How am I supposed to trade when I have no funds? 🥲🔥
$ARK
{future}(ARKUSDT)
$PHA
{future}(PHAUSDT)
$PEPE
{alpha}()
🚀💎
#BinancePick #EarningsSeaso n #BitcoinHashrateHitsSevenMonthHigh #CPI数据 #CPIWatchToo
I’m totally breaking down, guys 😭💔 Everyone keeps saying $PEPE , $PHA , and are ready for a massive 50–80% pump 🚀📈 But my balance is literally ZERO 😩💸 How am I supposed to trade when I have no funds? 🥲🔥
$ARK
$PHA
$PEPE
🚀💎
#BinancePick #EarningsSeaso n #BitcoinHashrateHitsSevenMonthHigh #CPI数据 #CPIWatchToo
$ARK
$PHA
$PEPE
🚀💎
#BinancePick #EarningsSeaso n #BitcoinHashrateHitsSevenMonthHigh #CPI数据 #CPIWatchToo
39
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#UniswapA16zSeekDeFiExemptionFromIllinoisCryptoTax
36,072 views
874 Discussing
2
#HKDollarStablecoinHKDAPToLaunchOnSolana
26,737 views
570 Discussing
3
#$1.5BInLeveragedCryptoBetsLiquidated
54,731 views
267 Discussing
4
#TrezorSaysCryptoBilisSoldWalletMayContainMaliciousComponents
4,773 views
83 Discussing
5
#KOSPIFalls3.53%BackBelow6000
71,731 views
1,163 Discussing
6
#AmazonSharesFallAbout7%InPremarketTrading
34,810 views
640 Discussing
7
#USMidtermElections
279,905 views
2,426 Discussing
8
#StrategySTRCReaches$99.95ForFirstTimeIn165Days
37,120 views
96 Discussing
9
#BinanceWillListPredictPREDICT
110,378 views
1,457 Discussing
10
#SwitzerlandFirstSpotBitcoinETFExpectedToTradeInNovember
3,443 views
115 Discussing