

Jackson Liam
19.5k Posts
Jackson Liam
 Square Verified+
Report
Block User
Blockchain Storyteller • Exposing hidden gems • Riding every wave with precision
Open Trade
Frequent Trader
2 Years
116 Following
43.2K+ Followers
53.6K+ Liked
Posts
Portfolio
All
Quotes
Live
·
--
Bullish
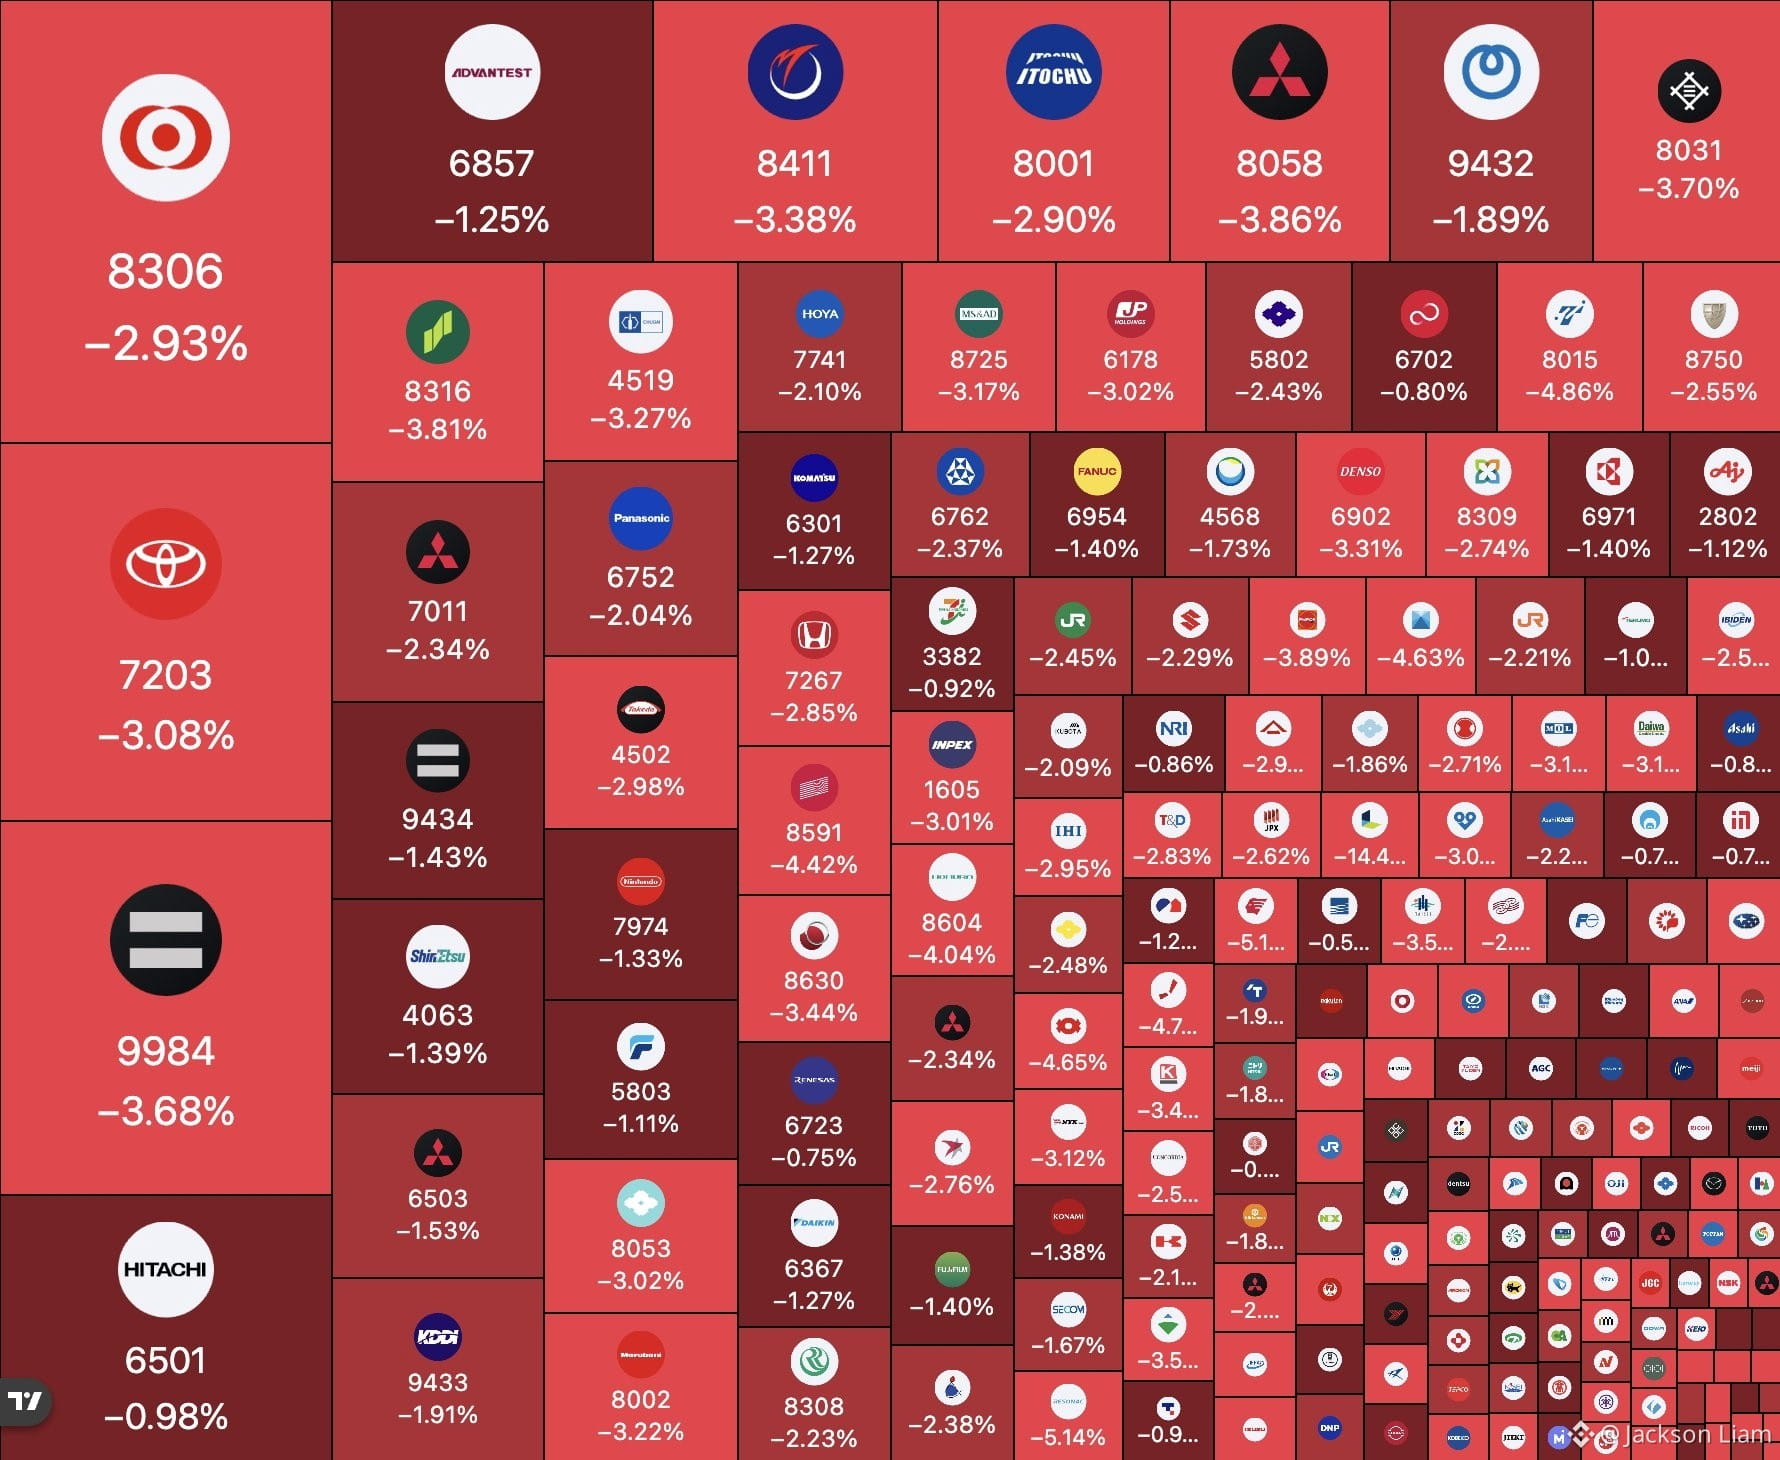
🚨 JAPAN STOCKS ARE GETTING HIT HARD!
More than ¥17.7 TRILLION ($112 BILLION) in market value has been wiped out as the Nikkei drops around 1.5%.
The sell-off comes as global bond yields surge and oil prices climb, raising fresh fears about inflation and higher interest rates.
Japan is feeling the pressure too, with investors dumping shares after the market’s strong recent run.
And this isn’t just a Japan story…
Higher yields + rising oil + geopolitical tension = investors getting nervous across global markets.
Risk-off mode is back.
The big question now: is this just a sharp pullback, or the start of something bigger? 🔥
222
·
--
Bullish
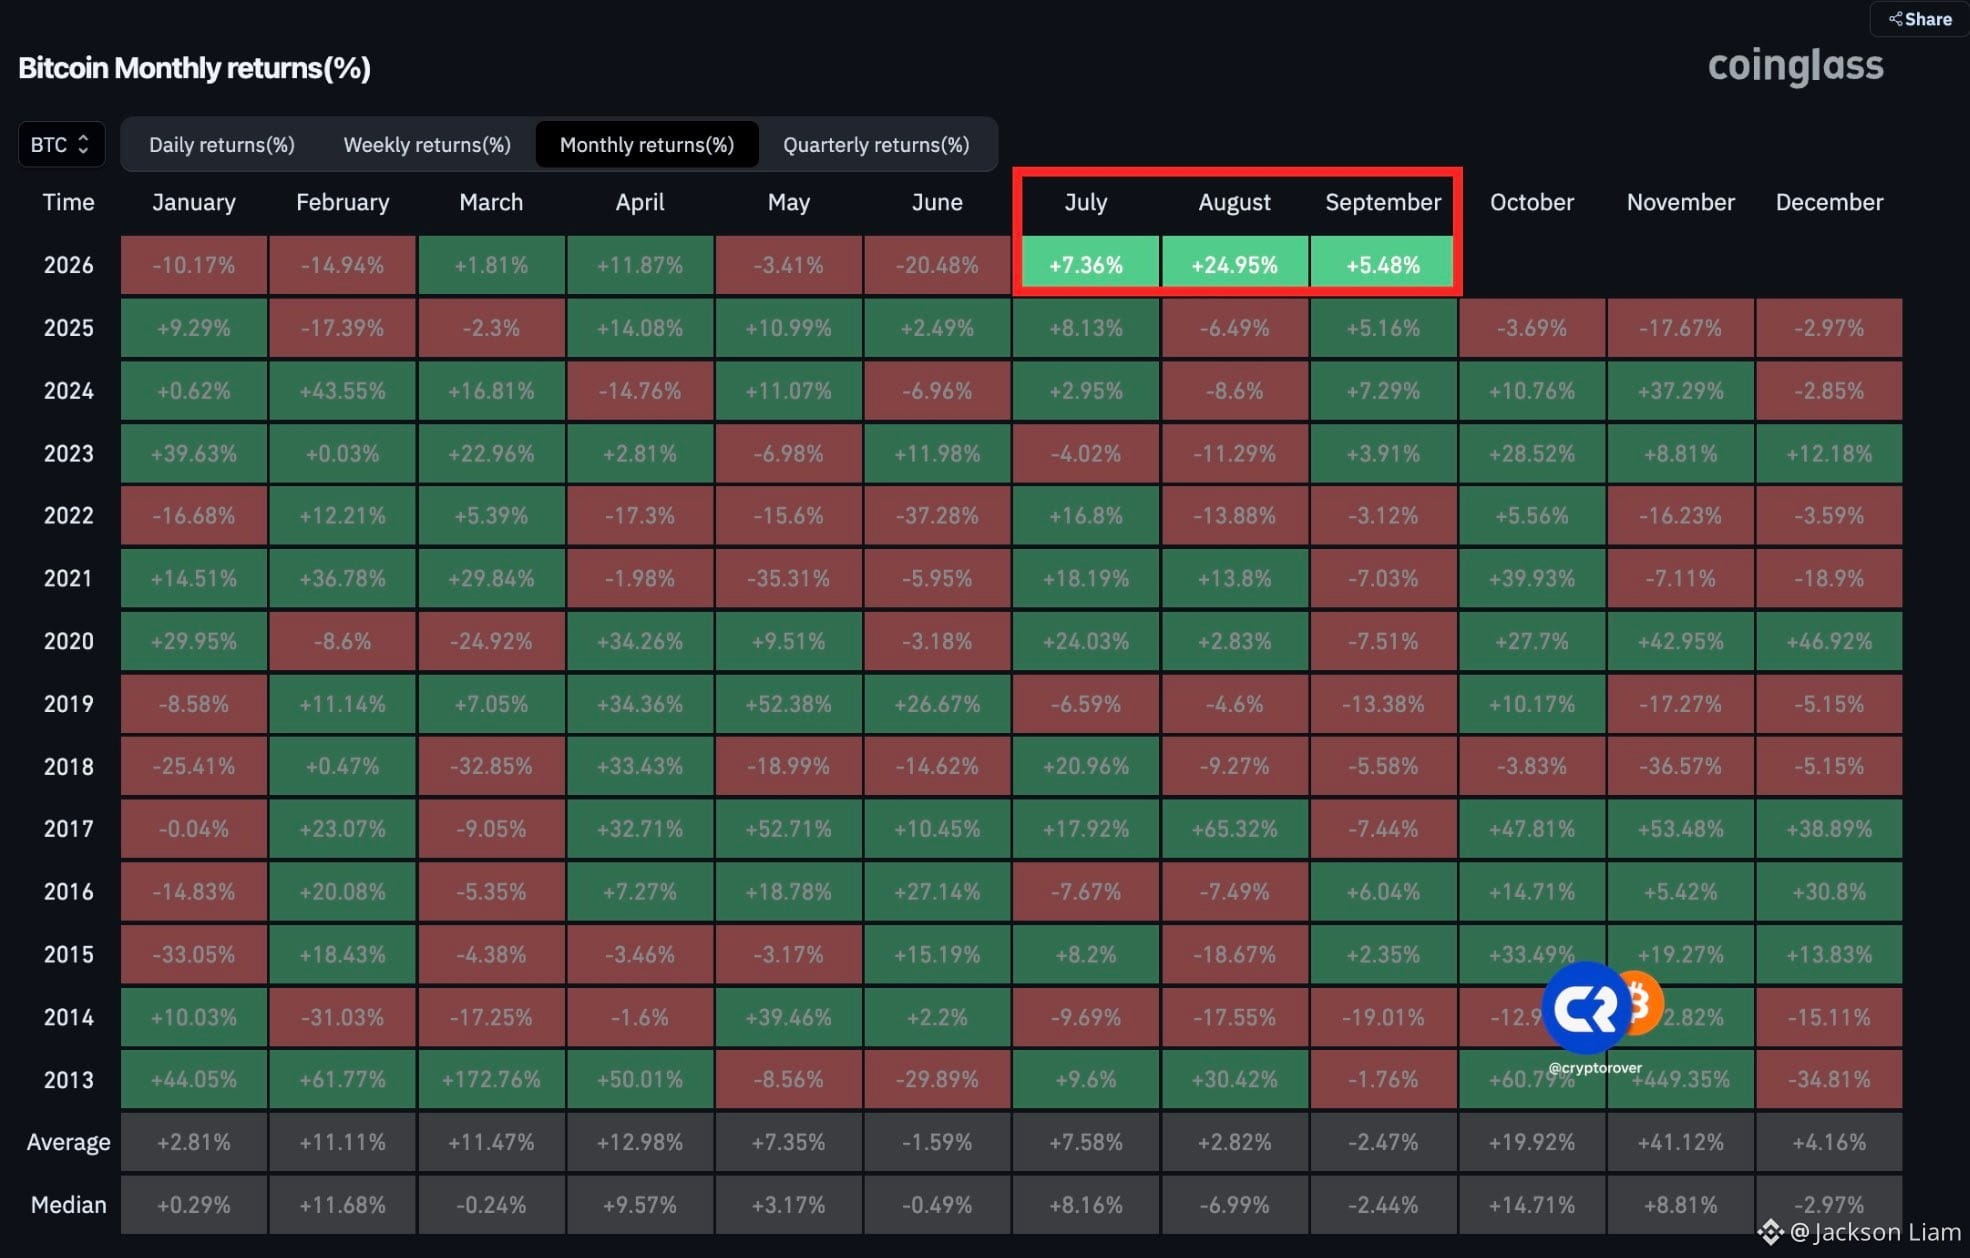
🟢 BITCOIN IS ABOUT TO CLOSE 3 GREEN MONTHS IN A ROW.
And that’s a big deal.
Bitcoin has stayed strong through the last three monthly candles, showing buyers are still stepping in instead of letting the market break down.
Historically, a 3-month green streak is rare during major bear markets.
But here’s the important part:
🚨 It doesn’t mean Bitcoin can’t dump. 🚨 It doesn’t guarantee a new all-time high. 🚨 It does show that the market structure is behaving differently from a typical prolonged bear phase.
Three green monthly candles = momentum is building.
If Bitcoin closes September in green, the real question becomes:
Can the bulls turn this strength into a bigger breakout?
The next monthly candle could be VERY important. 👀
1
288
·
--
Article
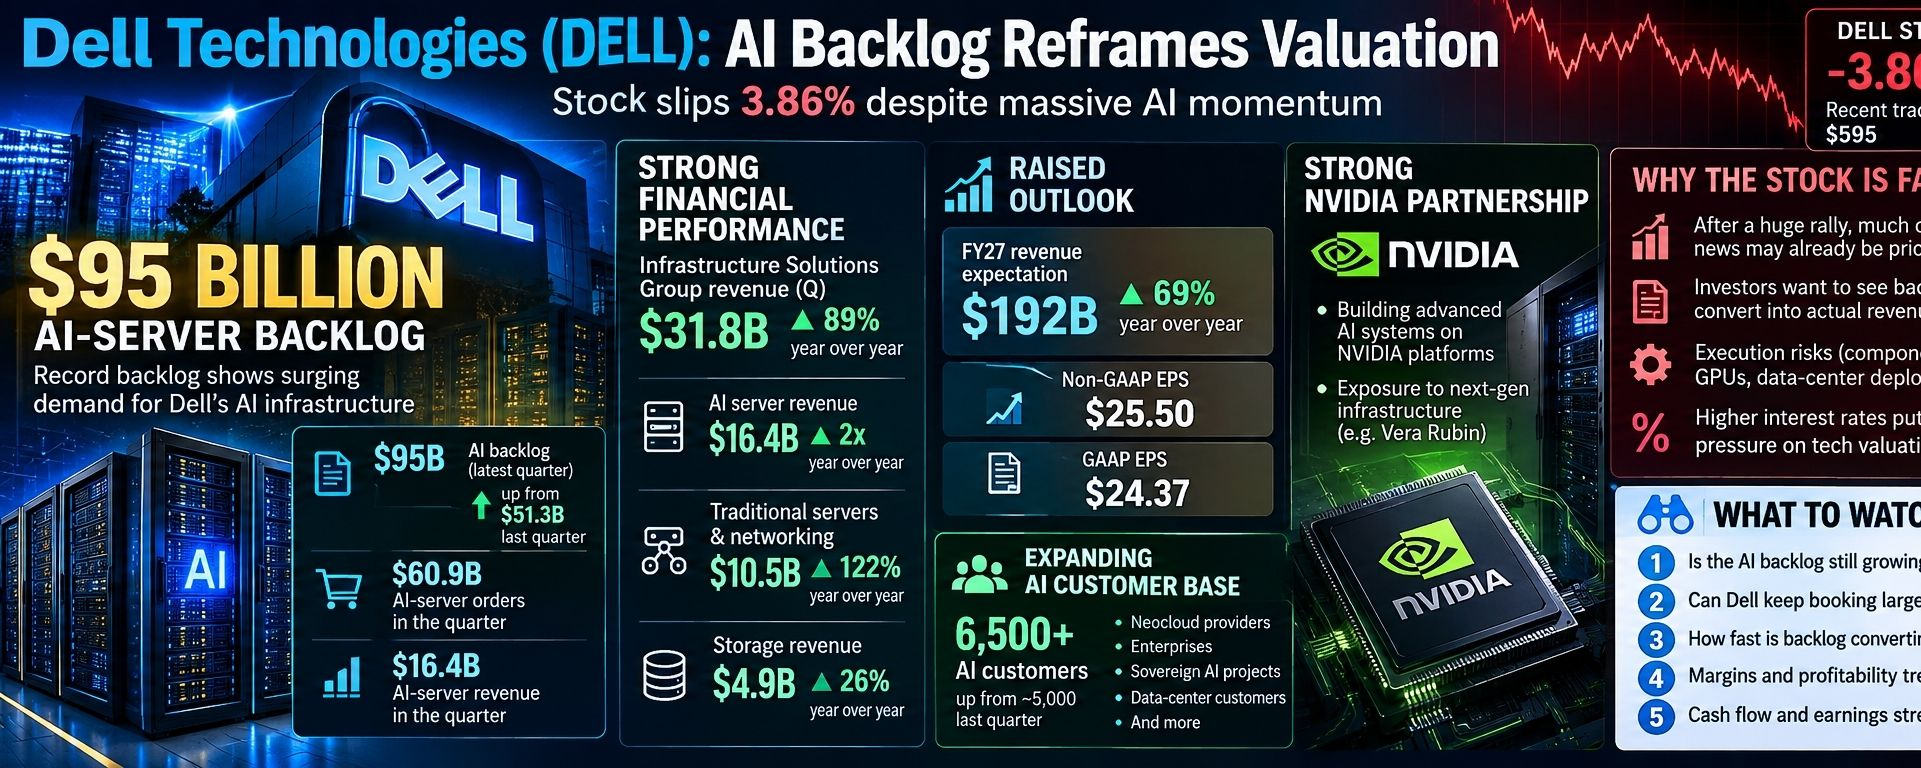
Dell Technologies (DELL): The $95 Billion AI Backlog Is Changing the StoryDell Technologies is no longer just a PC and server company.
That is becoming harder to ignore after the company revealed a massive $95 billion AI-server backlog while its stock recently slipped 3.86%.
The pullback is interesting because Dell's underlying AI business is moving in the opposite direction. Orders are surging, revenue is climbing, and management has raised its full-year outlook.
So why is the stock falling?
Because after a huge rally, investors are no longer asking whether Dell will benefit from AI. They are asking whether the company's future growth is already priced into the stock.
The $95 Billion Number Changes Everything
Dell ended its latest quarter with $95 billion in AI-server backlog, up sharply from $51.3 billion just one quarter earlier.
Even more impressive, Dell booked $60.9 billion of AI-server orders during the quarter and generated $16.4 billion in AI-server revenue.
That gap between orders and revenue is important.
It means customers are placing orders faster than Dell is currently converting them into reported sales.
For investors, the backlog provides a huge amount of visibility into future revenue.
And Dell says its AI pipeline is still several times larger than its existing backlog.
In other words, the $95 billion figure may not represent the end of the opportunity. It could be a snapshot of demand that is still accelerating.
AI Is Already Driving Dell's Numbers
This isn't just a story about future growth.
Dell's Infrastructure Solutions Group generated a record $31.8 billion in quarterly revenue, up 89% year over year.
AI-optimized server revenue reached $16.4 billion, doubling from a year earlier.
Traditional servers and networking were also strong, generating $10.5 billion, up 122%.
Storage revenue increased 26% to $4.9 billion.
That tells us something important: Dell isn't benefiting from only one part of the AI infrastructure stack.
AI data centers need much more than GPUs.
They need servers, networking, storage, CPUs, racks and the infrastructure connecting everything together.
Dell is selling many of those pieces.
Dell Just Raised Its Outlook
The stronger AI demand has pushed Dell to raise its expectations for the year.
The company now expects around $192 billion in FY27 revenue, representing roughly 69% year-over-year growth.
Non-GAAP EPS guidance has been raised to $25.50, while GAAP EPS guidance is around $24.37.
Those numbers show how quickly Dell's earnings profile is changing.
The old question was:
How should investors value a mature hardware company?
The new question is:
What is Dell worth if AI infrastructure remains a major growth engine for several years?
That is a much bigger question.
The Backlog Still Has to Become Revenue
There is an important reality investors shouldn't overlook.
A backlog is not the same as revenue.
Dell still has to build the systems, secure the components and deliver them to customers.
That creates execution risks.
Memory availability, GPU supply, networking components, customer deployment schedules and data-center capacity can all affect how quickly Dell converts orders into sales.
This is why the next few quarters will be important.
Investors will want to see the $95 billion backlog turning into actual revenue and cash flow.
Profitability May Be More Important Than Revenue
Dell's AI growth is impressive, but revenue alone won't determine the long-term valuation.
Margins matter.
Dell's Infrastructure Solutions Group operating income jumped 225% year over year to approximately $4.8 billion.
That is a major improvement and suggests the company is getting meaningful operating leverage as the AI business scales.
If Dell can keep growing rapidly while protecting or improving margins, the earnings story becomes much stronger.
If revenue explodes but margins get squeezed by expensive components and intense competition, the market may become less enthusiastic.
Dell's AI Customer Base Is Growing
Dell says it now serves more than 6,500 AI customers, compared with roughly 5,000 in the previous quarter.
The customer base includes neocloud providers, enterprises and sovereign AI deployments.
That expansion matters.
The AI infrastructure boom is no longer limited to a handful of giant technology companies.
More businesses are building their own AI capacity, while specialized cloud providers are expanding their infrastructure to meet demand.
Dell is trying to capture that spending from multiple directions.
NVIDIA Is a Major Part of the Story
Dell's AI opportunity is closely tied to NVIDIA's technology ecosystem.
The company is building advanced rack-scale AI systems around NVIDIA platforms, including next-generation infrastructure.
That gives Dell a direct connection to one of the biggest technology spending cycles in the world.
But it also creates risk.
Dell doesn't control GPU supply, NVIDIA's product roadmap or the overall pace of AI infrastructure spending.
If customers slow their AI spending, Dell will eventually feel it.
So Why Is DELL Falling?
This is where the stock price becomes more interesting than the headline.
Dell recently traded near $595, after an enormous rally.
At that level, investors are already expecting a lot.
The market knows about the AI backlog.
It knows about the revenue growth.
It knows management is raising guidance.
So the stock doesn't simply need to deliver good results anymore.
It needs to keep delivering results that are better than what investors have already priced in.
That's a much higher bar.
Valuation Is Now the Main Debate
Dell's valuation has changed dramatically as its earnings outlook has improved.
The company is no longer being valued purely as a slow-growing PC and enterprise-hardware business.
But that doesn't mean valuation risk has disappeared.
After such a powerful rally, even a strong company can experience sharp pullbacks.
Investors have to decide how much future AI growth is already reflected in the current share price.
That is probably the biggest debate around Dell right now.
Higher Rates Could Add Pressure
The broader market also matters.
Higher Treasury yields can put pressure on technology valuations because investors typically demand a higher return when interest rates rise.
Dell has strong current earnings, so it isn't purely dependent on distant future profits.
Still, after such a large re-rating, changes in interest rates and investor risk appetite can affect the multiple investors are willing to pay.
What Investors Should Watch Next
The next few earnings reports could be more important than the daily stock move.
Watch the AI backlog first.
Does $95 billion keep growing?
Then watch AI orders.
Can Dell continue booking tens of billions of dollars in new business each quarter?
After that comes AI revenue.
Is Dell converting its backlog quickly enough?
Then comes margins and cash flow.
The strongest version of the Dell story is not simply huge AI orders.
It is huge AI orders turning into revenue, revenue turning into profits, and profits turning into cash.
The Bigger Picture
Dell's transformation is happening quickly.
The company that was once primarily associated with PCs and traditional enterprise hardware is becoming a major supplier to the AI infrastructure buildout.
The $95 billion AI backlog is the clearest evidence of that shift.
But investors shouldn't stop at the backlog number.
The real story is what happens next:
Orders → Backlog → Revenue → Margins → Cash Flow → Earnings
If Dell can successfully move through that chain, the market may continue to view the company differently.
If demand slows, supply problems worsen or margins come under pressure, the valuation could become much harder to defend.
For now, the 3.86% decline looks less like a change in Dell's AI story and more like a reminder that expectations have become extremely high.
Dell has already shown that it can win AI business. Now it has to prove that it can turn that enormous backlog into sustainable earnings.
And that may be the most important part of the Dell story from here.
Dell Technologies (DELL): The $95 Billion AI Backlog Is Changing the Story
Dell Technologies is no longer just a PC and server company.
That is becoming harder to ignore after the company revealed a massive $95 billion AI-server backlog while its stock recently slipped 3.86%.
The pullback is interesting because Dell's underlying AI business is moving in the opposite direction. Orders are surging, revenue is climbing, and management has raised its full-year outlook.
So why is the stock falling?
Because after a huge rally, investors are no longer asking whether Dell will benefit from AI. They are asking whether the company's future growth is already priced into the stock.
The $95 Billion Number Changes Everything
Dell ended its latest quarter with $95 billion in AI-server backlog, up sharply from $51.3 billion just one quarter earlier.
Even more impressive, Dell booked $60.9 billion of AI-server orders during the quarter and generated $16.4 billion in AI-server revenue.
That gap between orders and revenue is important.
It means customers are placing orders faster than Dell is currently converting them into reported sales.
For investors, the backlog provides a huge amount of visibility into future revenue.
And Dell says its AI pipeline is still several times larger than its existing backlog.
In other words, the $95 billion figure may not represent the end of the opportunity. It could be a snapshot of demand that is still accelerating.
AI Is Already Driving Dell's Numbers
This isn't just a story about future growth.
Dell's Infrastructure Solutions Group generated a record $31.8 billion in quarterly revenue, up 89% year over year.
AI-optimized server revenue reached $16.4 billion, doubling from a year earlier.
Traditional servers and networking were also strong, generating $10.5 billion, up 122%.
Storage revenue increased 26% to $4.9 billion.
That tells us something important: Dell isn't benefiting from only one part of the AI infrastructure stack.
AI data centers need much more than GPUs.
They need servers, networking, storage, CPUs, racks and the infrastructure connecting everything together.
Dell is selling many of those pieces.
Dell Just Raised Its Outlook
The stronger AI demand has pushed Dell to raise its expectations for the year.
The company now expects around $192 billion in FY27 revenue, representing roughly 69% year-over-year growth.
Non-GAAP EPS guidance has been raised to $25.50, while GAAP EPS guidance is around $24.37.
Those numbers show how quickly Dell's earnings profile is changing.
The old question was:
How should investors value a mature hardware company?
The new question is:
What is Dell worth if AI infrastructure remains a major growth engine for several years?
That is a much bigger question.
The Backlog Still Has to Become Revenue
There is an important reality investors shouldn't overlook.
A backlog is not the same as revenue.
Dell still has to build the systems, secure the components and deliver them to customers.
That creates execution risks.
Memory availability, GPU supply, networking components, customer deployment schedules and data-center capacity can all affect how quickly Dell converts orders into sales.
This is why the next few quarters will be important.
Investors will want to see the $95 billion backlog turning into actual revenue and cash flow.
Profitability May Be More Important Than Revenue
Dell's AI growth is impressive, but revenue alone won't determine the long-term valuation.
Margins matter.
Dell's Infrastructure Solutions Group operating income jumped 225% year over year to approximately $4.8 billion.
That is a major improvement and suggests the company is getting meaningful operating leverage as the AI business scales.
If Dell can keep growing rapidly while protecting or improving margins, the earnings story becomes much stronger.
If revenue explodes but margins get squeezed by expensive components and intense competition, the market may become less enthusiastic.
Dell's AI Customer Base Is Growing
Dell says it now serves more than 6,500 AI customers, compared with roughly 5,000 in the previous quarter.
The customer base includes neocloud providers, enterprises and sovereign AI deployments.
That expansion matters.
The AI infrastructure boom is no longer limited to a handful of giant technology companies.
More businesses are building their own AI capacity, while specialized cloud providers are expanding their infrastructure to meet demand.
Dell is trying to capture that spending from multiple directions.
NVIDIA Is a Major Part of the Story
Dell's AI opportunity is closely tied to NVIDIA's technology ecosystem.
The company is building advanced rack-scale AI systems around NVIDIA platforms, including next-generation infrastructure.
That gives Dell a direct connection to one of the biggest technology spending cycles in the world.
But it also creates risk.
Dell doesn't control GPU supply, NVIDIA's product roadmap or the overall pace of AI infrastructure spending.
If customers slow their AI spending, Dell will eventually feel it.
So Why Is DELL Falling?
This is where the stock price becomes more interesting than the headline.
Dell recently traded near $595, after an enormous rally.
At that level, investors are already expecting a lot.
The market knows about the AI backlog.
It knows about the revenue growth.
It knows management is raising guidance.
So the stock doesn't simply need to deliver good results anymore.
It needs to keep delivering results that are better than what investors have already priced in.
That's a much higher bar.
Valuation Is Now the Main Debate
Dell's valuation has changed dramatically as its earnings outlook has improved.
The company is no longer being valued purely as a slow-growing PC and enterprise-hardware business.
But that doesn't mean valuation risk has disappeared.
After such a powerful rally, even a strong company can experience sharp pullbacks.
Investors have to decide how much future AI growth is already reflected in the current share price.
That is probably the biggest debate around Dell right now.
Higher Rates Could Add Pressure
The broader market also matters.
Higher Treasury yields can put pressure on technology valuations because investors typically demand a higher return when interest rates rise.
Dell has strong current earnings, so it isn't purely dependent on distant future profits.
Still, after such a large re-rating, changes in interest rates and investor risk appetite can affect the multiple investors are willing to pay.
What Investors Should Watch Next
The next few earnings reports could be more important than the daily stock move.
Watch the AI backlog first.
Does $95 billion keep growing?
Then watch AI orders.
Can Dell continue booking tens of billions of dollars in new business each quarter?
After that comes AI revenue.
Is Dell converting its backlog quickly enough?
Then comes margins and cash flow.
The strongest version of the Dell story is not simply huge AI orders.
It is huge AI orders turning into revenue, revenue turning into profits, and profits turning into cash.
The Bigger Picture
Dell's transformation is happening quickly.
The company that was once primarily associated with PCs and traditional enterprise hardware is becoming a major supplier to the AI infrastructure buildout.
The $95 billion AI backlog is the clearest evidence of that shift.
But investors shouldn't stop at the backlog number.
The real story is what happens next:
Orders → Backlog → Revenue → Margins → Cash Flow → Earnings
If Dell can successfully move through that chain, the market may continue to view the company differently.
If demand slows, supply problems worsen or margins come under pressure, the valuation could become much harder to defend.
For now, the 3.86% decline looks less like a change in Dell's AI story and more like a reminder that expectations have become extremely high.
Dell has already shown that it can win AI business. Now it has to prove that it can turn that enormous backlog into sustainable earnings.
And that may be the most important part of the Dell story from here.
3
298
·
--
NMR — MASSIVE BREAKOUT! LONG SETUP
NMR has exploded over 35%, breaking out of consolidation and hitting $15.50. Momentum is strong, but a pullback could offer a better entry.
LONG SIGNAL
EP (Buy Zone): $13.00 – $13.30
TP1: $14.40 TP2: $15.50 TP3: $16.80
SL: $12.40
A successful retest of $13 could set up another explosive move. Wait for confirmation before entering.
Let's go $NMR
{spot}(NMRUSDT)
$MARSCOIN
{future}(MARSCOINUSDT)
$HBAR
{future}(HBARUSDT)
NMR — MASSIVE BREAKOUT! LONG SETUP
NMR has exploded over 35%, breaking out of consolidation and hitting $15.50. Momentum is strong, but a pullback could offer a better entry.
LONG SIGNAL
EP (Buy Zone): $13.00 – $13.30
TP1: $14.40 TP2: $15.50 TP3: $16.80
SL: $12.40
A successful retest of $13 could set up another explosive move. Wait for confirmation before entering.
Let's go $NMR
$MARSCOIN
$HBAR
$18+ — Breakout continues
$20+ — Full send
Pullback to $13–14 first
Reversal incoming
18 hr(s) left
1
480
·
--
Bullish
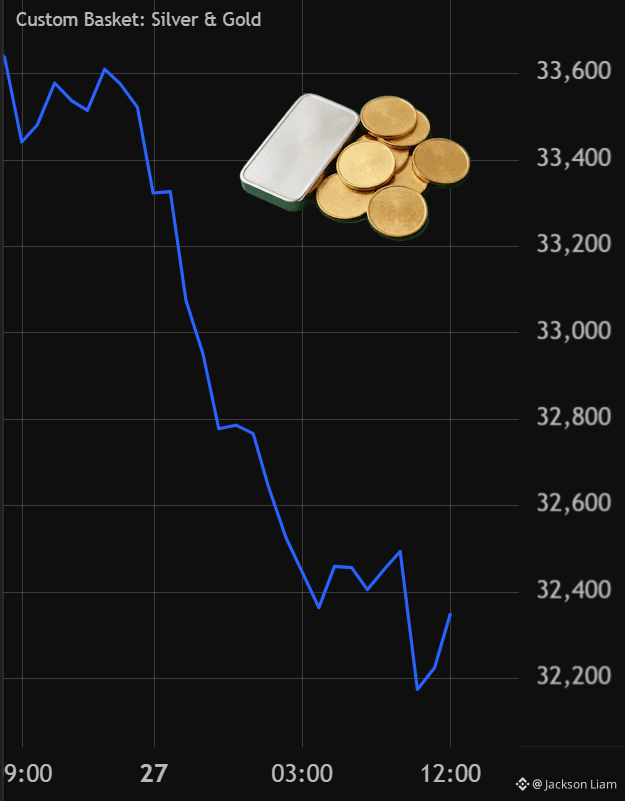
🚨 JUST IN: Gold & silver just took a MASSIVE hit.
$1 TRILLION in combined market cap was wiped out today.
That’s roughly 60% of Bitcoin’s entire market cap.
Think about that.
Markets this big can move hundreds of billions in a single day — and Bitcoin is still relatively tiny compared to traditional stores of value.
We’re still VERY early. 👀
$XAU $XAG
2
1
577
·
--
Bullish
🚨 BREAKING: IRAN SANCTIONS RELIEF COULD BE COMING
Trump is reportedly ready to ease sanctions and unfreeze Iranian assets if Tehran agrees to U.S. nuclear demands.
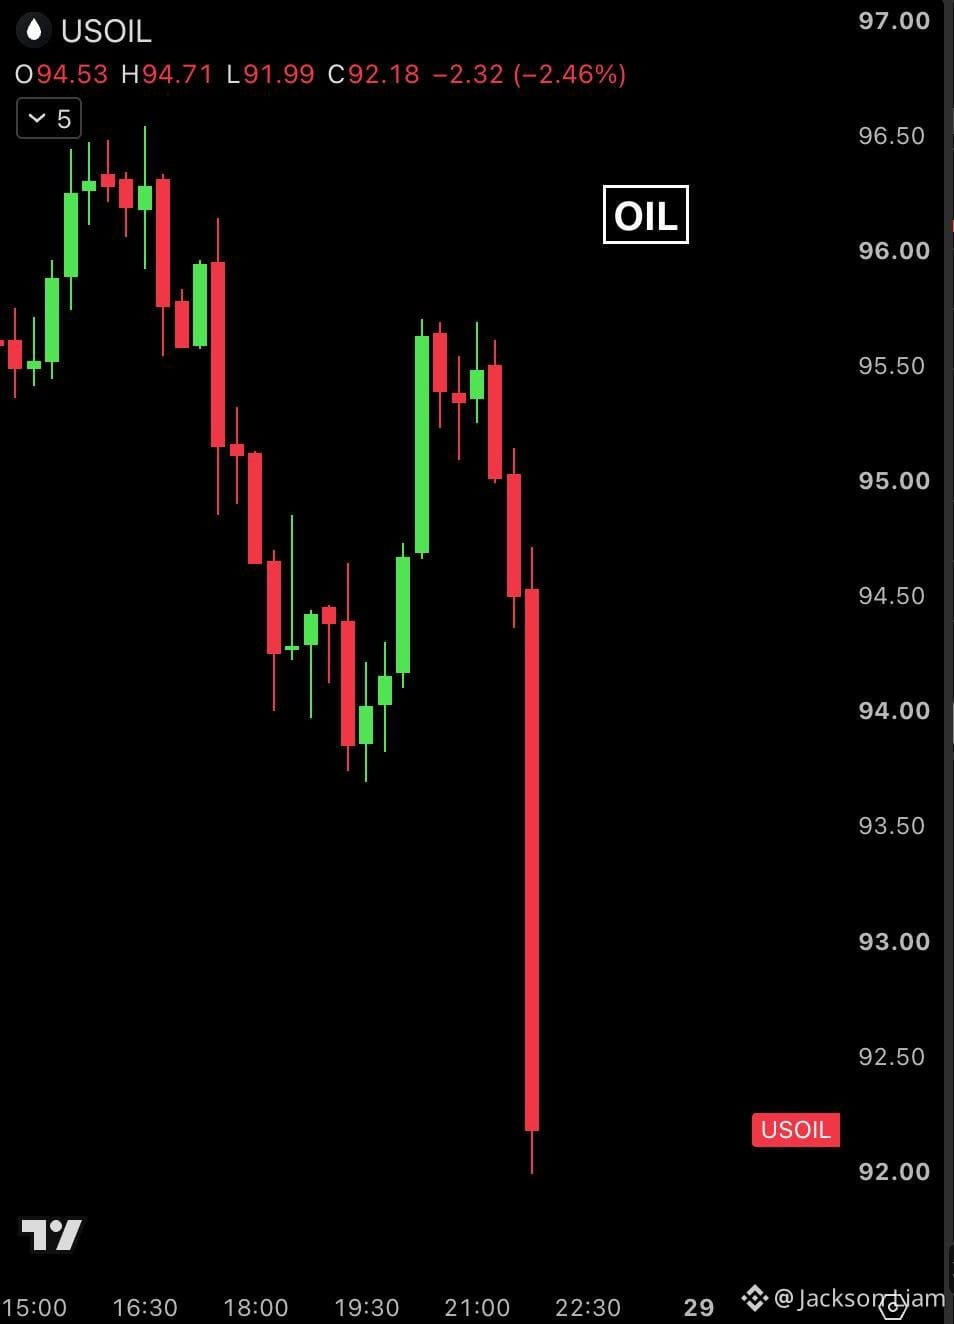
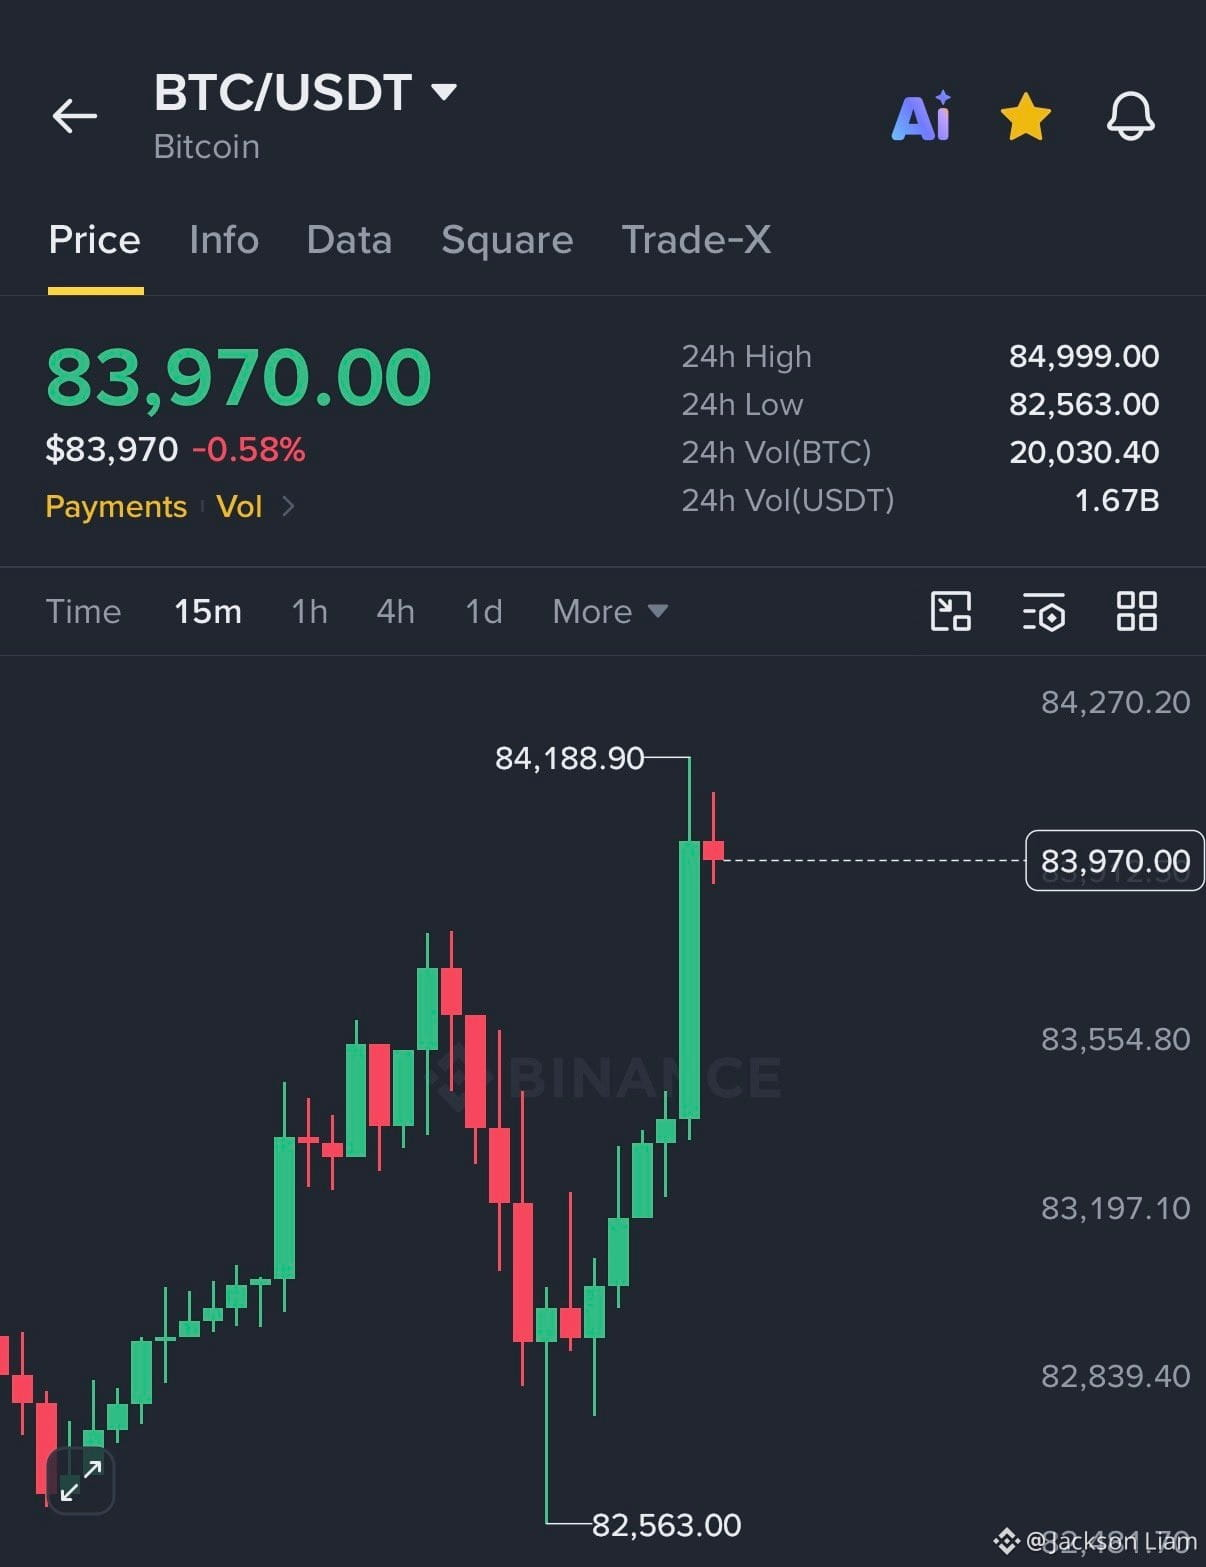
Markets reacted FAST ⚡
🛢️ Oil plunged nearly 4% in just 30 minutes as geopolitical risk premium faded.
₿ Bitcoin also started recovering, as traders priced in a potential de-escalation.
The key now: whether the talks turn into an actual agreement.
1
383
·
--
Bearish
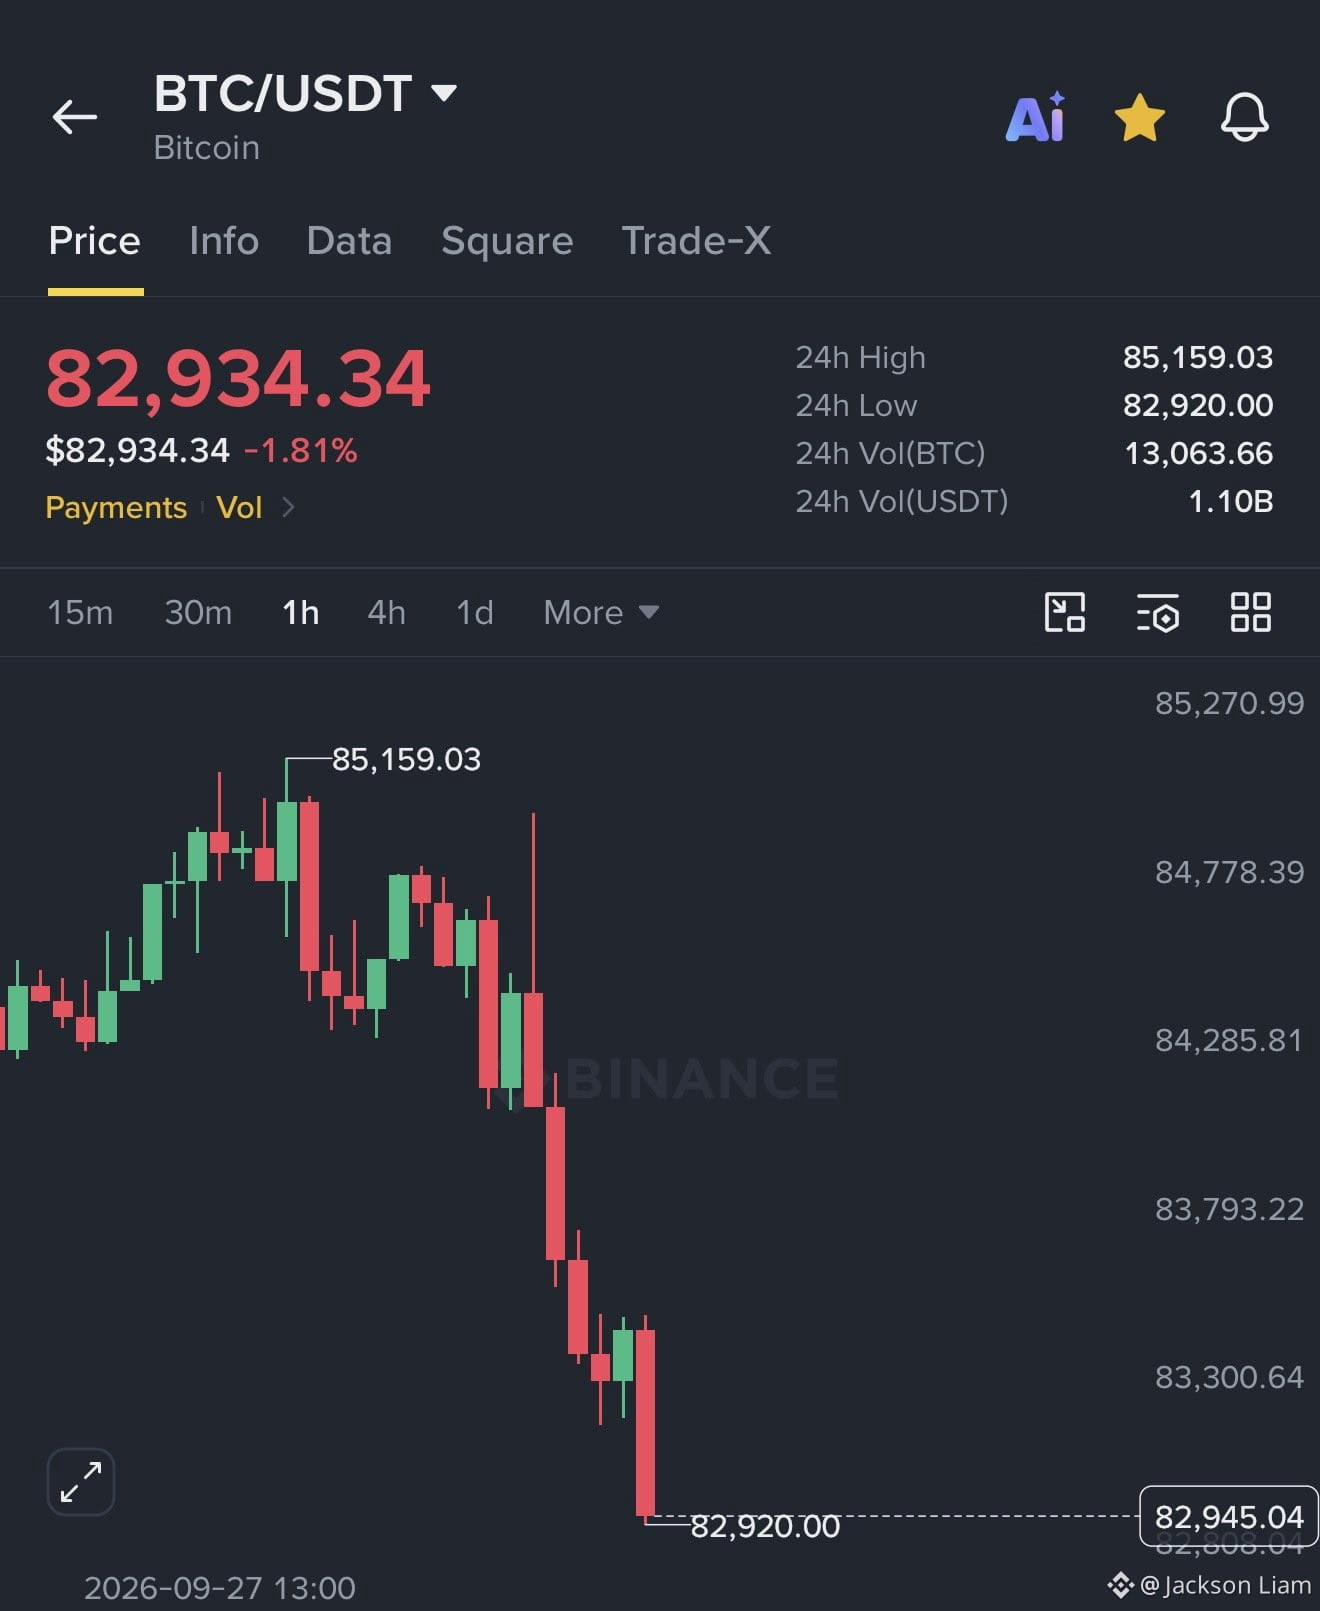
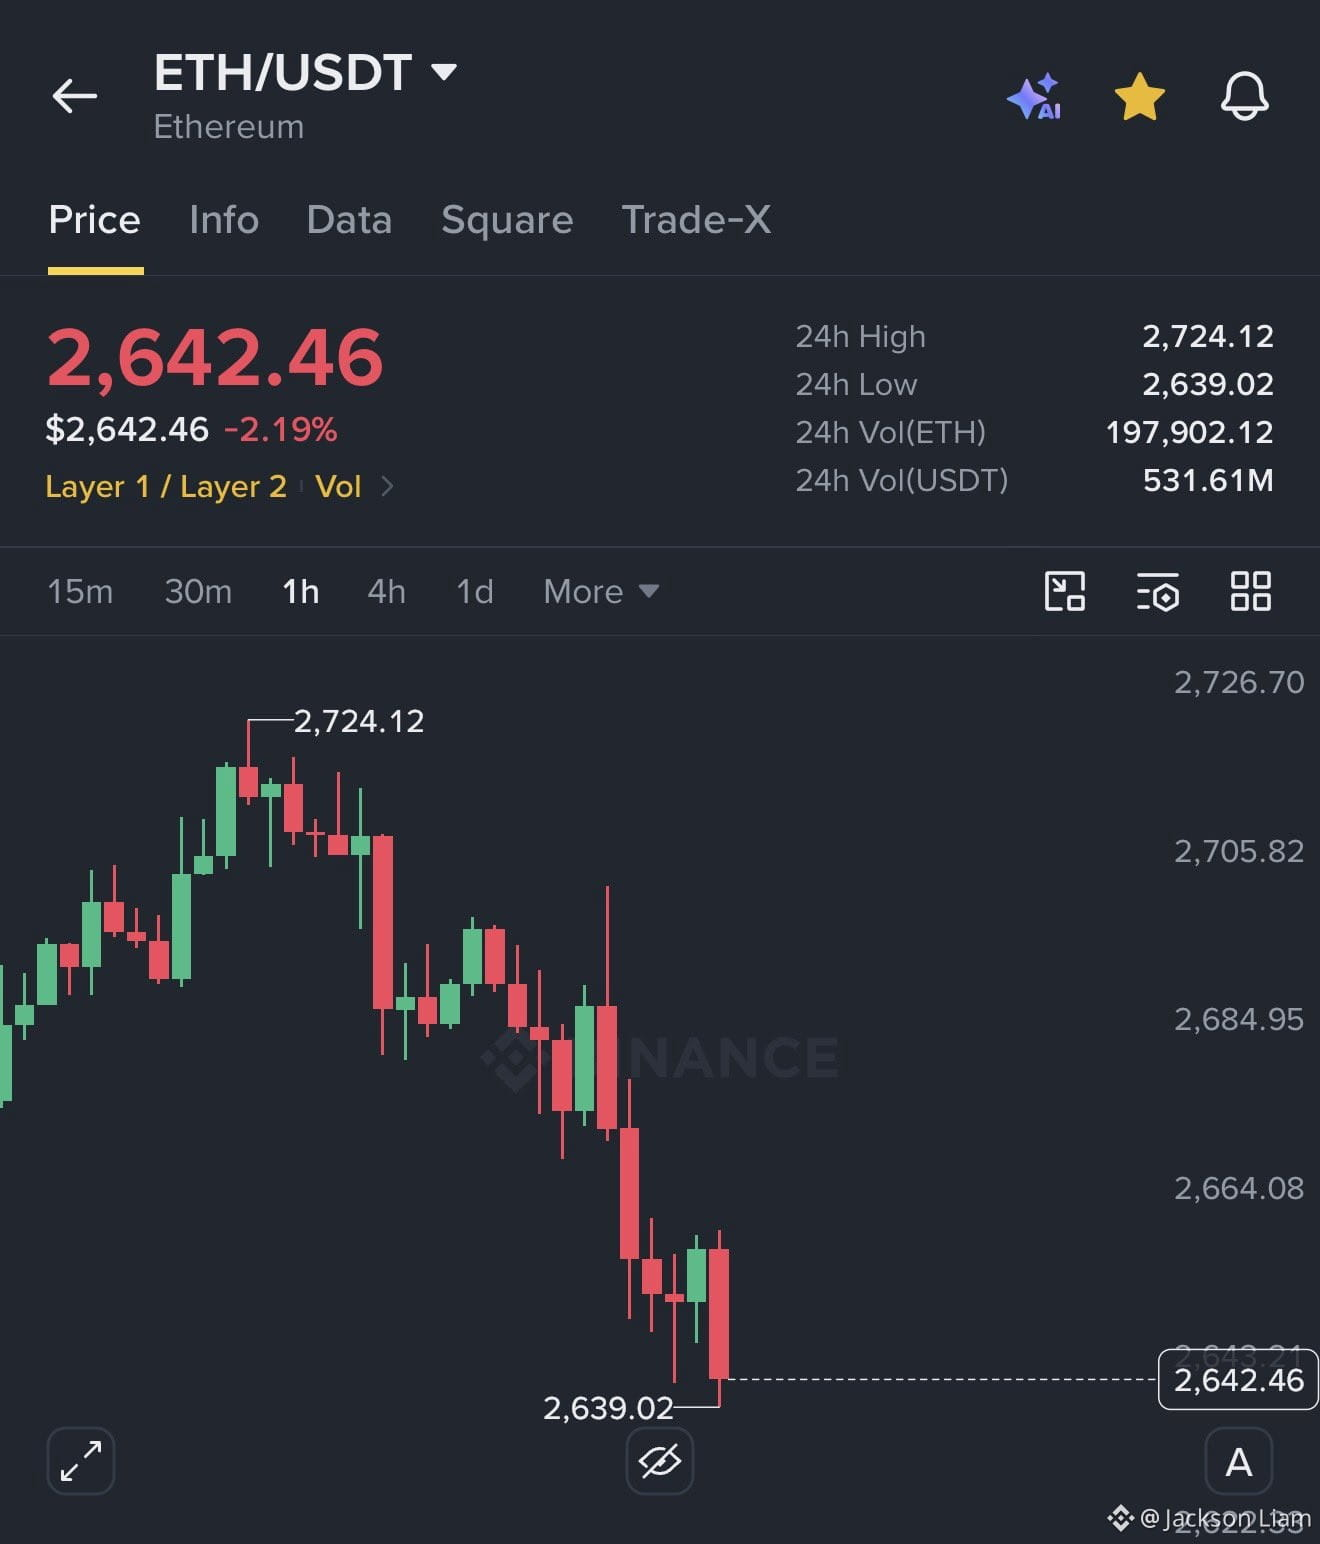
🚨 CRYPTO MARKET FLUSH
Bitcoin just slipped below $83,000 while Ethereum dropped under $2,650.
And the move is already hurting leveraged traders:
💥 $50M+ in longs liquidated in just 60 minutes.
The market is moving fast, and overleveraged positions are getting wiped out as traders rush to cut risk.
$BTC losing $83K and $ETH losing $2.65K puts fresh pressure on the broader crypto market.
One sharp move lower can trigger more liquidations — and that can create even more selling.
Volatility is back. 👀
5
3
439
·
--
Bullish
QNT — explosive breakout is in play.
Price just ripped from the 100s to 195, and now we’re looking for a controlled retest rather than chasing the spike.
Buy Zone: 155–165
EP: 160
TP1: 180
TP2: 195
TP3: 215
SL: 147
Above 195, momentum can accelerate.
If 155–165 holds on the 4H, the setup stays constructive.
Let’s go $QNT
{future}(QNTUSDT)
$Q
{future}(QUSDT)
$SOON
{future}(SOONUSDT)
QNT — explosive breakout is in play.
Price just ripped from the 100s to 195, and now we’re looking for a controlled retest rather than chasing the spike.
Buy Zone: 155–165
EP: 160
TP1: 180
TP2: 195
TP3: 215
SL: 147
Above 195, momentum can accelerate.
If 155–165 holds on the 4H, the setup stays constructive.
Let’s go $QNT
$Q
$SOON
Price just ripped from the 100s to 195, and now we’re looking for a controlled retest rather than chasing the spike.
Buy Zone: 155–165
EP: 160
TP1: 180
TP2: 195
TP3: 215
SL: 147
Above 195, momentum can accelerate.
If 155–165 holds on the 4H, the setup stays constructive.
Let’s go $QNT
$Q
$SOON
Breakout
25%
Pullback
60%
Staying out
15%
20 votes • Voting closed
4
3
2.1k
·
--
Bullish
RARE
Breakout momentum is heating up after a massive expansion from the 0.0130 area. Price is pressing the 0.02244 high, so the key is holding the breakout zone.
Buy Zone: 0.02000–0.02120
TP1: 0.02380
TP2: 0.02650
TP3: 0.03000
SL: 0.01840
EP: 0.02000–0.02120
TP: 0.02380 / 0.02650 / 0.03000
SL: 0.01840
Clean setup: breakout + retest above 0.0200. If 0.0184 breaks, the setup is invalid.
$RARE
{spot}(RAREUSDT)
$ARK
{future}(ARKUSDT)
$PHA
{future}(PHAUSDT)
RARE
Breakout momentum is heating up after a massive expansion from the 0.0130 area. Price is pressing the 0.02244 high, so the key is holding the breakout zone.
Buy Zone: 0.02000–0.02120
TP1: 0.02380
TP2: 0.02650
TP3: 0.03000
SL: 0.01840
EP: 0.02000–0.02120
TP: 0.02380 / 0.02650 / 0.03000
SL: 0.01840
Clean setup: breakout + retest above 0.0200. If 0.0184 breaks, the setup is invalid.
$RARE
$ARK
$PHA
YES — Buying the breakout
40%
NO — Waiting for a pullback
60%
5 votes • Voting closed
4
4
748
·
--
Bullish
🚨 LYNA JUST WENT PARABOLIC!
Evelyn AI’s LYNSDT is moving FAST — and the chart is getting wild.
🔥 Price: $0.06910
📈 24H: +73.92%
💥 24H High: $0.07272
🩸 24H Low: $0.03861
💰 24H Volume: $31.62M
⚡ LYNSDT Volume: 591.28M
The crazy part? LYNSDT spent most of the recent sessions trading around the $0.04 area… then BOOM.
A massive 4H candle sent it straight toward $0.073, with price now holding around $0.069.
And the momentum isn’t just today:
📈 7D: +104.02%
📈 30D: +102.11%
📈 90D: +98.28%
📈 180D: +38.03%
From roughly $0.034 to nearly $0.073 in days.
This is no longer a quiet chart.
The real question now: can LYNSDT hold this breakout, or does the massive move trigger a sharp pullback?
$LYN
{future}(LYNUSDT)
$PHA
{future}(PHAUSDT)
$RARE
{future}(RAREUSDT)
🚨 LYNA JUST WENT PARABOLIC!
Evelyn AI’s LYNSDT is moving FAST — and the chart is getting wild.
🔥 Price: $0.06910
📈 24H: +73.92%
💥 24H High: $0.07272
🩸 24H Low: $0.03861
💰 24H Volume: $31.62M
⚡ LYNSDT Volume: 591.28M
The crazy part? LYNSDT spent most of the recent sessions trading around the $0.04 area… then BOOM.
A massive 4H candle sent it straight toward $0.073, with price now holding around $0.069.
And the momentum isn’t just today:
📈 7D: +104.02%
📈 30D: +102.11%
📈 90D: +98.28%
📈 180D: +38.03%
From roughly $0.034 to nearly $0.073 in days.
This is no longer a quiet chart.
The real question now: can LYNSDT hold this breakout, or does the massive move trigger a sharp pullback?
$LYN
$PHA
$RARE
Breaks $0.073 & runs higher
80%
Consolidates around$0.06–$0.07
20%
Sharp pullback after the pump
0%
⚡ Another explosive move
0%
5 votes • Voting closed
1
938
·
--
Bullish
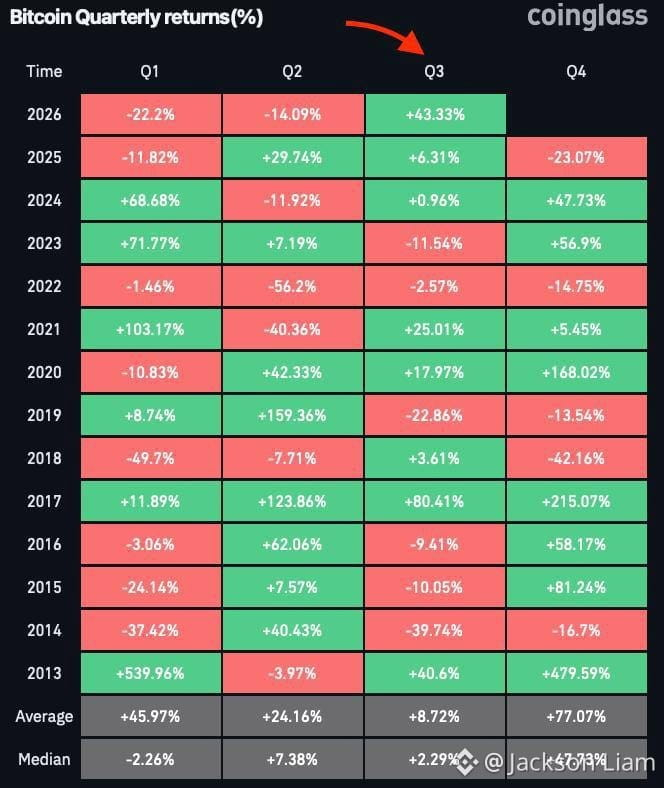
🚨 BITCOIN IS HAVING A MONSTER QUARTER 🔥
$BTC is on track to close Q3 2026 with one of its biggest quarterly gains in history.
Bitcoin started the quarter around $58K and has pushed back toward the $80K–$90K area, putting the quarter’s return around +40% at current levels.
That’s a huge comeback after BTC posted losses in both Q1 and Q2.
The bigger story?
Bitcoin just went from a brutal first half to one of its strongest quarterly rebounds ever.
Q3 isn’t finished yet — but if BTC holds these levels into September 30, this quarter will go down as a major comeback quarter for Bitcoin. 🔥
1
368
·
--
Bullish
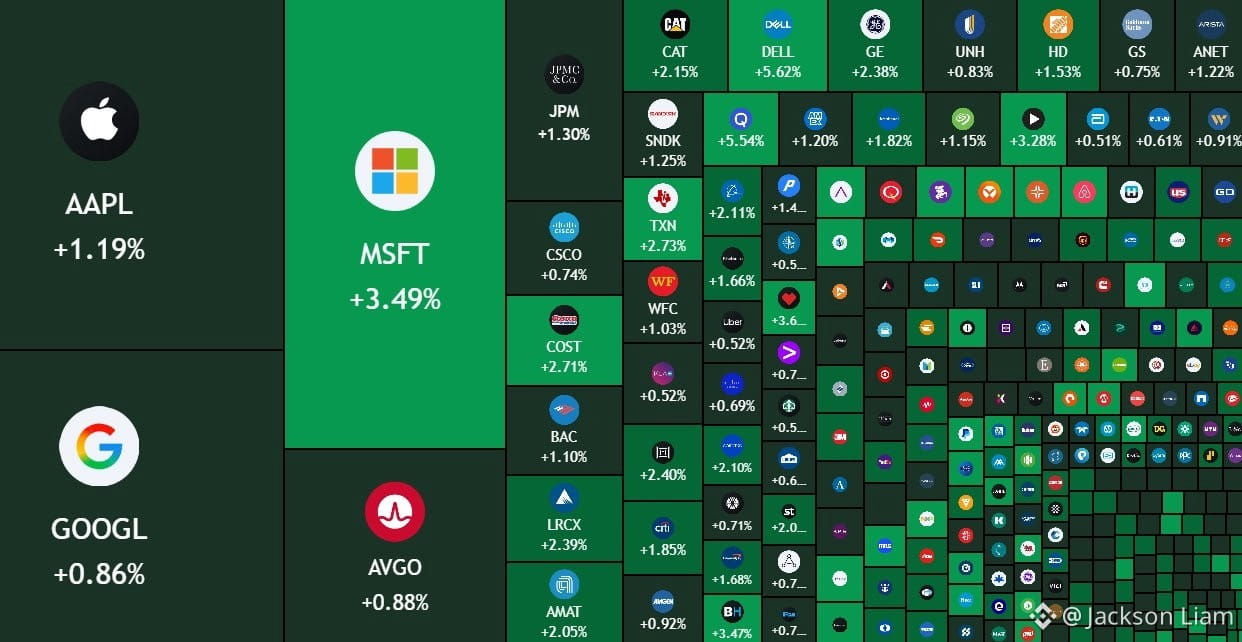
🚨 $450 BILLION ADDED TO US STOCKS IN JUST 30 MINUTES!
Wall Street got a massive boost after reports emerged that US-Iran talks had entered a technical stage.
The headline changed the mood instantly.
Investors started betting that progress toward a deal could reduce fears around the Middle East, especially the Strait of Hormuz and oil supply disruptions.
Stocks quickly bounced as risk sentiment returned.
The bigger picture: markets are watching every headline from the US-Iran negotiations because any progress could ease pressure on oil, inflation and interest rates.
One headline.
30 minutes.
$450 BILLION added to US stocks.
This is how sensitive markets have become to geopolitical news.
1
2
469
·
--
Bullish
🚨 JUST IN: BITGET HIT BY A MASSIVE SECURITY BREACH!
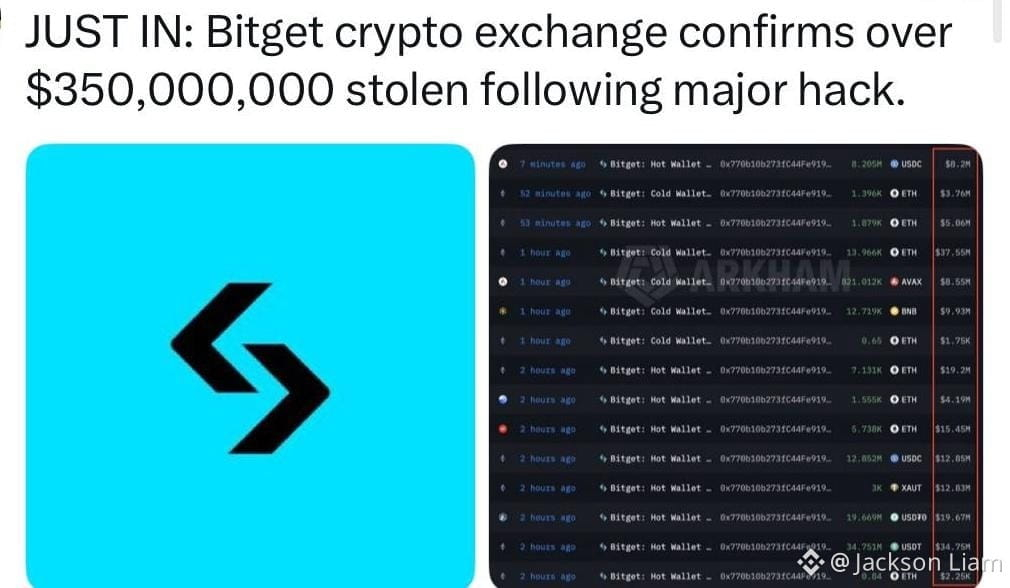
Bitget has reportedly confirmed that more than $350 MILLION worth of crypto was stolen following a major hack.
On-chain activity shows large movements involving assets such as $ETH , USDC, USDT, BNB, $AVAX , $XAUT and USDO from wallets linked to Bitget.
The transactions appear to have happened across multiple wallets within a short period, with some transfers worth tens of millions of dollars.
💥 Over $350M reportedly stolen
💥 Multiple major crypto assets affected
💥 Large wallet movements detected on-chain
💥 Bitget has confirmed the incident
This is a serious hit for the crypto market, and traders will be watching closely for where the stolen funds move next.
2
2
518
·
--
Bullish
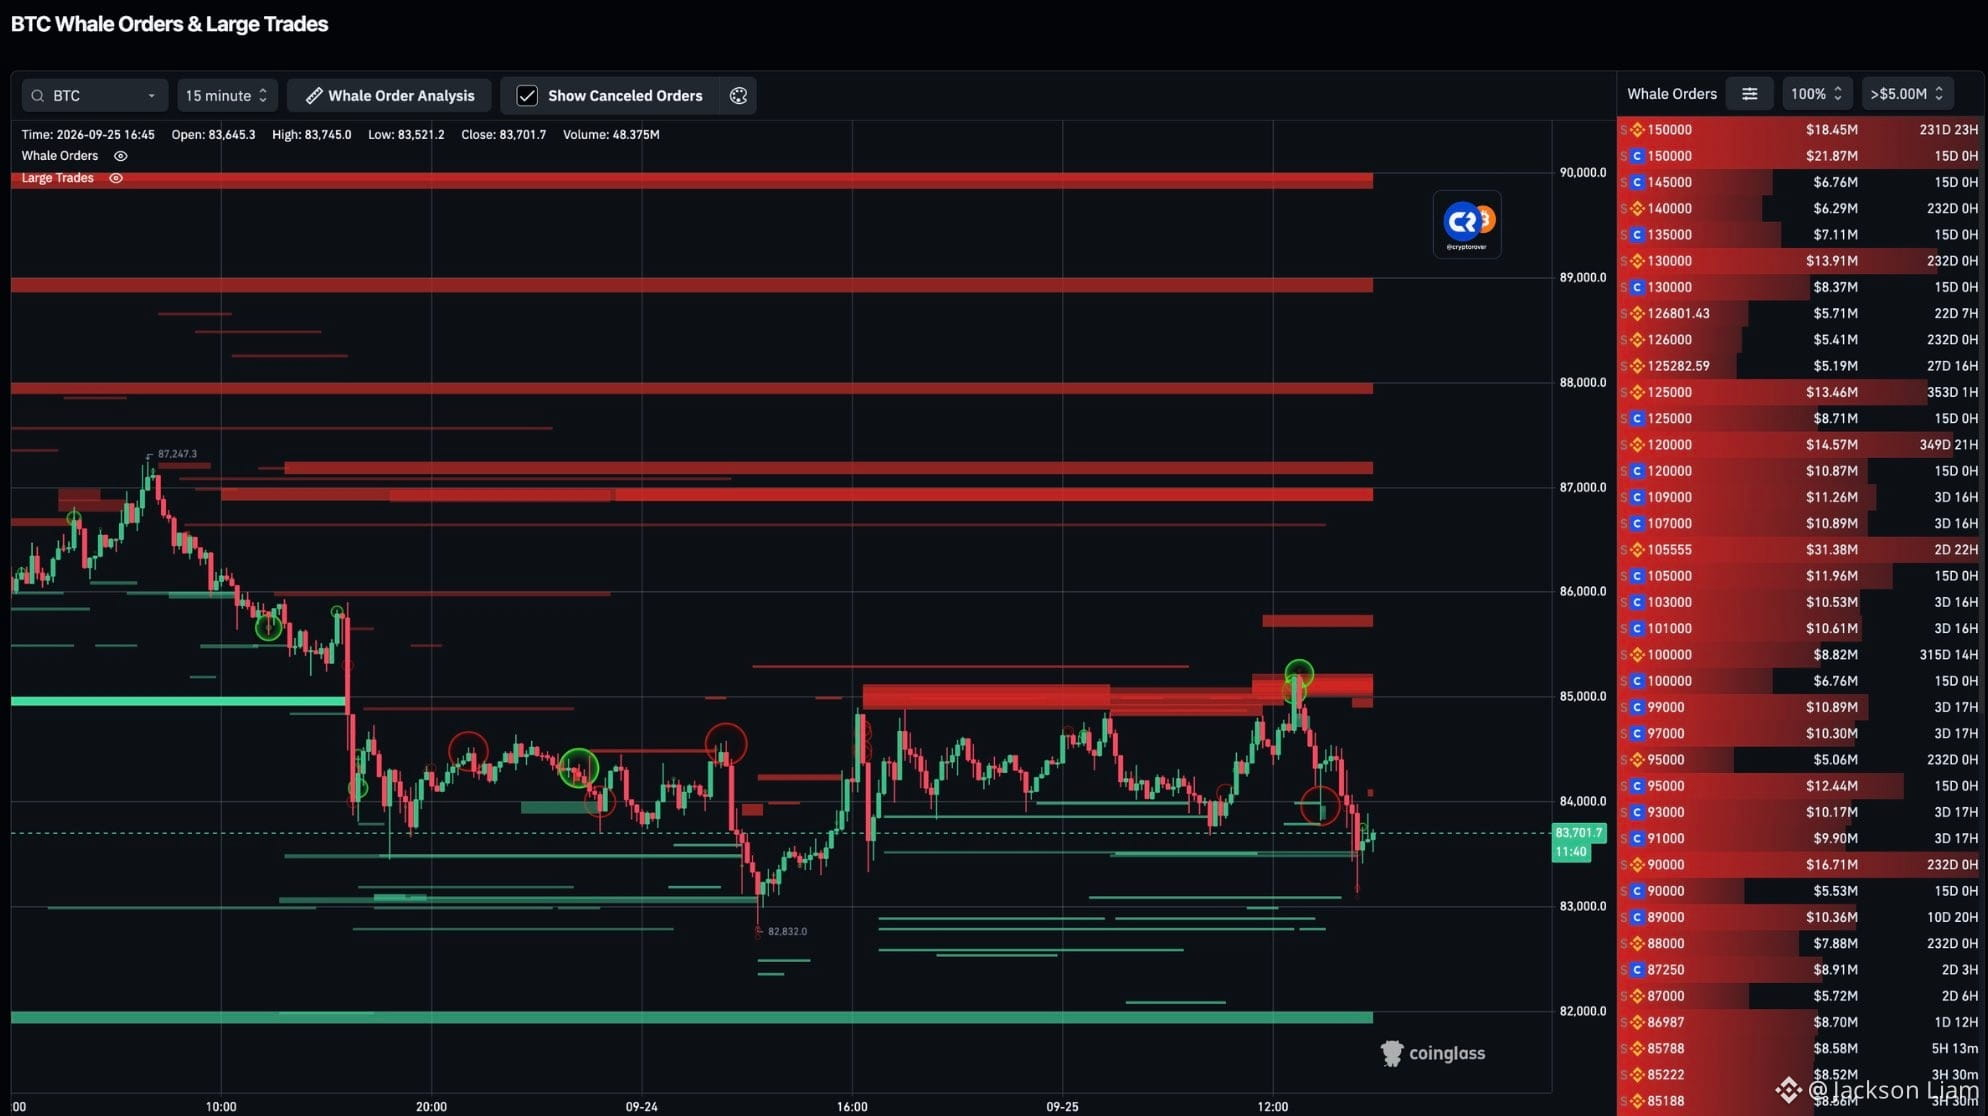
🚨 HUGE BITCOIN SELL WALL ALERT!
Bitcoin is facing heavy sell pressure, with large sell orders stacked all the way down to $90,000.
That means every move higher could run into fresh resistance as sellers look to exit or lock in profits.
If buyers can absorb these orders, $BTC could push higher quickly.
But if the sell wall holds, the market could see another sharp pullback toward $90K.
⚠️ Right now, liquidity is the key. One big wave of buying could clear the wall — or aggressive selling could turn it into a serious rejection.
Bitcoin is at a critical battle zone. 👀
2
1
295
·
--
Bullish
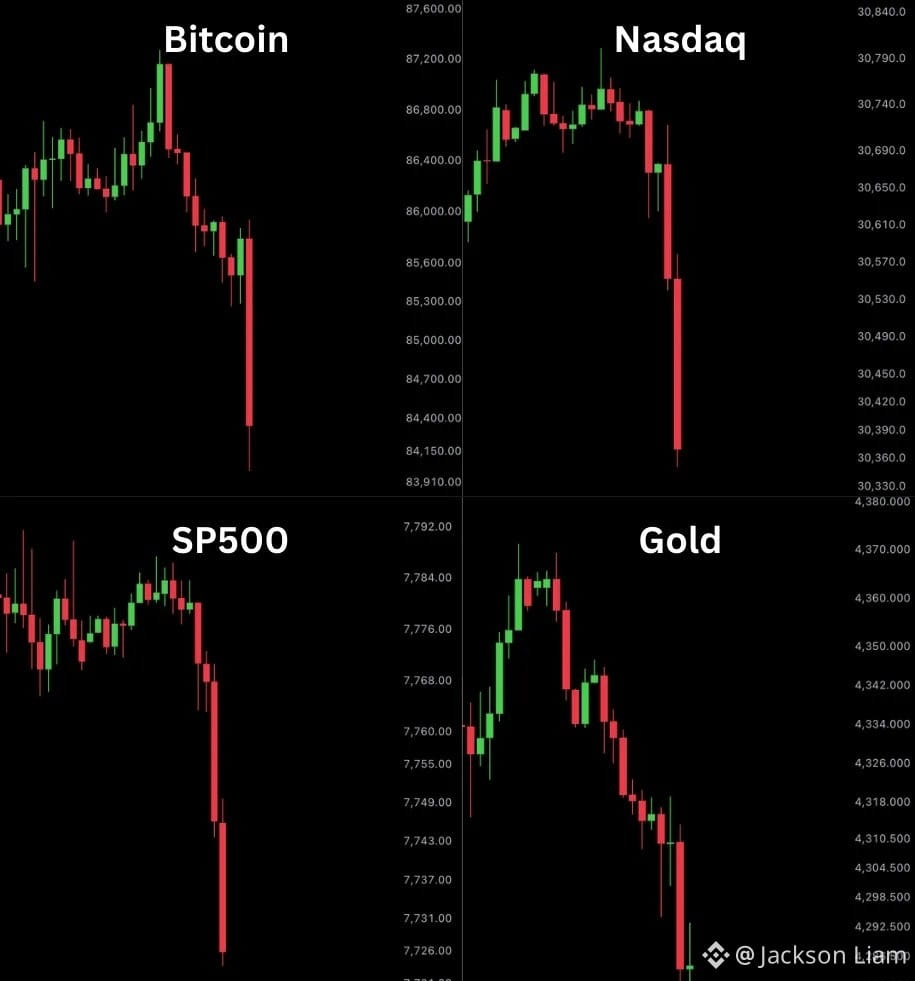
🚨 MASSIVE MARKET SHOCK!
Risk assets are getting slammed as tensions around the U.S.–Iran conflict flare up again. ⚠️
Stocks are under pressure, crypto is volatile, while oil remains near $100/barrel as traders price in geopolitical and inflation risks.
The big question now:
Is this just another panic-driven selloff — or the beginning of a much deeper risk-off move? 👀
Markets are watching every Iran headline. One statement could move stocks, Bitcoin, gold and oil in minutes. 📉🔥
#Bitcoin #Crypto #Stocks #Gold #Iran
5
4
715
·
--
Bearish
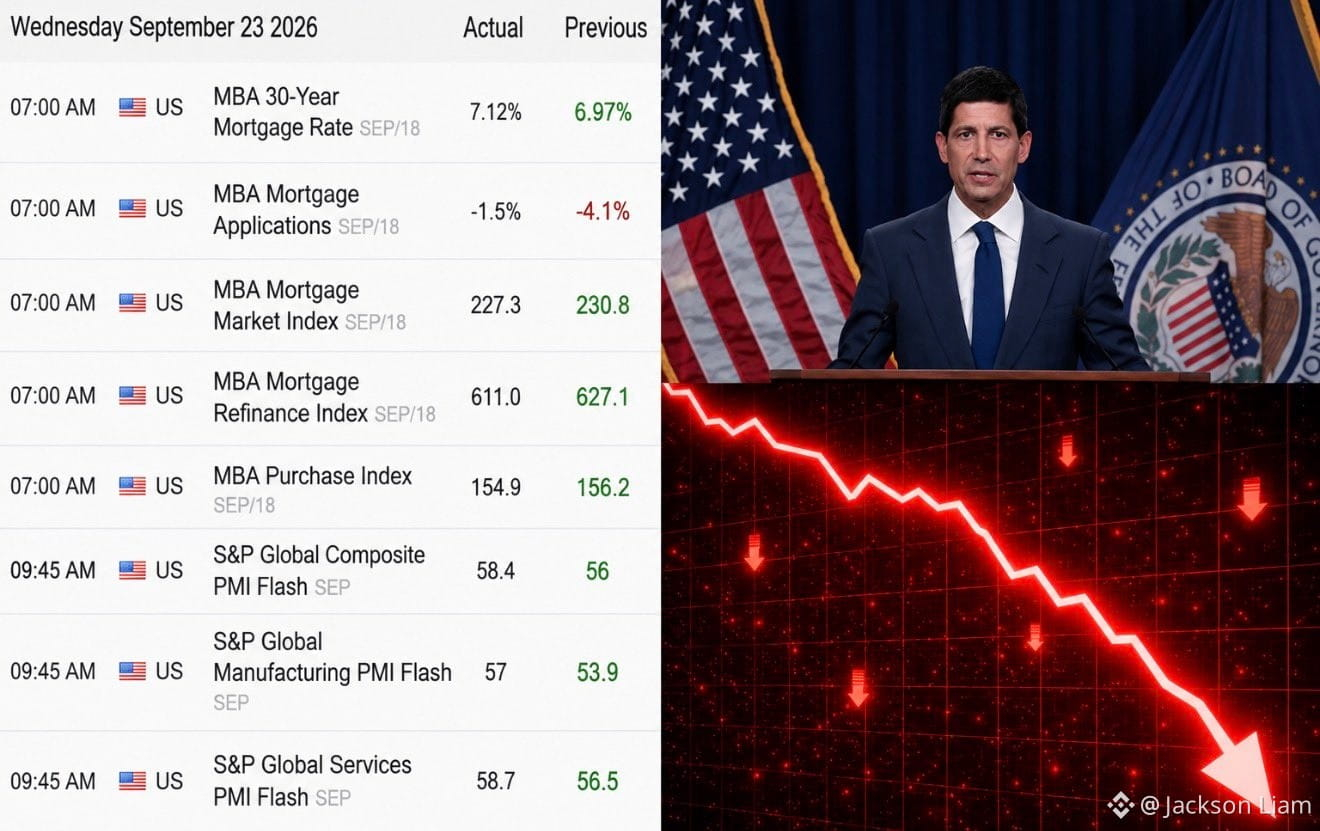
🚨 THE FED JUST GOT ANOTHER REASON TO STAY HAWKISH.
The U.S. economy is showing serious strength — and that could keep pressure on the Federal Reserve.
The latest S&P Global PMI data points to a sharp improvement in economic activity, while inflation remains well above the Fed’s 2% target.
And then there’s oil.
Brent crude has pushed back above $100 a barrel, adding another potential source of inflation pressure. S&P Global says higher energy prices are already forcing inflation forecasts higher.
The message is pretty simple:
📈 Stronger economic activity
🔥 Higher energy prices
💰 Inflation still elevated
🏦 More pressure on the Fed to keep policy tight
The Fed has already delivered a 25-basis-point hike this month, lifting rates to 3.75%–4.00%. Officials also raised their 2026 inflation forecast, with median PCE inflation now projected at 3.7%.
Fed officials are clearly watching inflation closely. Richmond Fed President Tom Barkin said this week that the economy appears to be firming and that inflation remains a major concern.
For markets, this creates a tricky setup.
If growth stays strong while inflation refuses to cool, investors may have to prepare for higher-for-longer rates.
And that matters far beyond stocks.
Higher rates can mean tighter financial conditions for bonds, equities, housing — and risk assets like crypto.
The big question now:
Does the U.S. economy stay strong enough to absorb more tightening, or does the Fed risk pushing growth too far?
1
356
·
--
Bullish
MUBARAK
+57.23% move with price holding near 0.08116 after a sharp breakout. Momentum is strong, but the 0.08781 high is the key breakout level.
BUY ZONE: 0.0775–0.0800
EP: 0.0790
TP1: 0.0845
TP2: 0.0878
TP3: 0.0950
SL: 0.0735
Hold above the buy zone and the breakout structure stays interesting. A clean break above 0.0878 could open the next upside leg.
$MUBARAK
{future}(MUBARAKUSDT)
$NIL
{future}(NILUSDT)
$MARSCOIN
{future}(MARSCOINUSDT)
MUBARAK
+57.23% move with price holding near 0.08116 after a sharp breakout. Momentum is strong, but the 0.08781 high is the key breakout level.
BUY ZONE: 0.0775–0.0800
EP: 0.0790
TP1: 0.0845
TP2: 0.0878
TP3: 0.0950
SL: 0.0735
Hold above the buy zone and the breakout structure stays interesting. A clean break above 0.0878 could open the next upside leg.
$MUBARAK
$NIL
$MARSCOIN
Breaks 0.0878 → New Highs
50%
Pullback → Reclaim & Continue
22%
Range → More Consolidation
7%
Deeper Correction
21%
14 votes • Voting closed
2
2
2.4k
·
--
Bullish
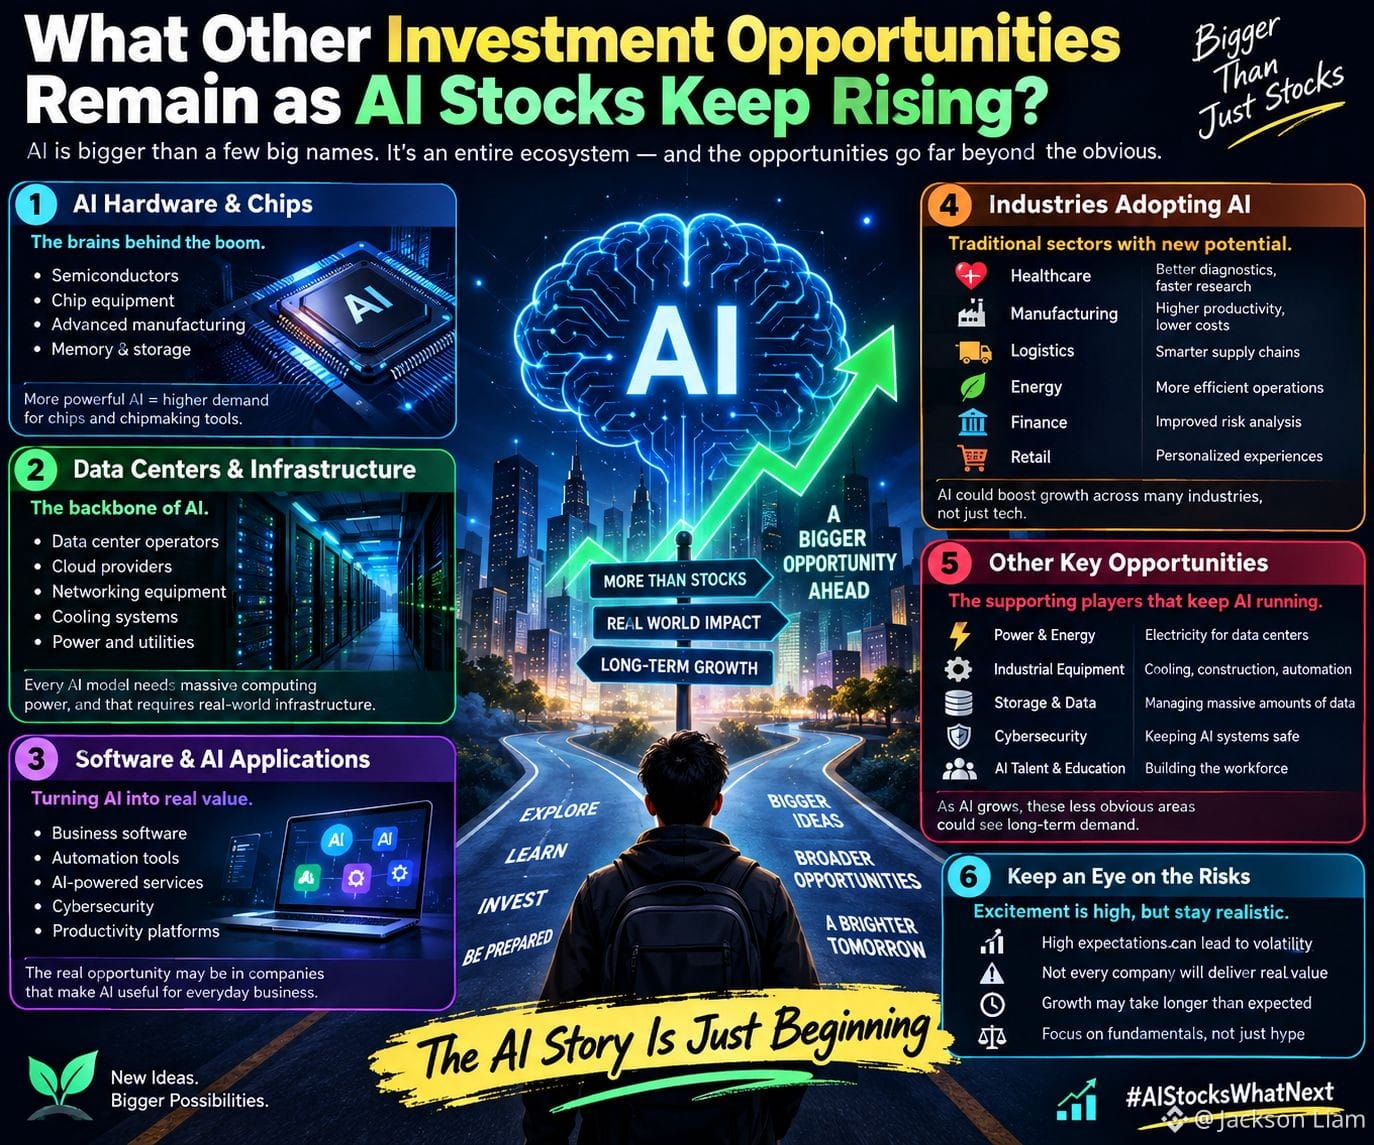
What Other Investment Opportunities Remain as AI Stocks Keep Rising?
AI stocks have been moving fast, and honestly, it’s easy to look at the headlines and think the opportunity is already gone.
But I don’t think the AI story ends with the companies everyone already knows.
Think about what happens every time AI gets bigger. More computing power is needed. More data centers have to be built. Those facilities need electricity, cooling, networking equipment, storage, and security. And once businesses start using AI seriously, they also need software and services that can actually turn all that technology into something useful.
That creates a much wider opportunity than simply chasing the biggest AI names.
I’m also watching what happens outside traditional tech. If AI can genuinely help companies reduce costs, automate repetitive work, improve logistics, analyze information faster, or increase productivity, then industries like manufacturing, healthcare, finance, energy, and retail could become important parts of the next chapter.
But there’s a catch.
When everyone gets excited about the same theme, expectations can become extremely high. A company can have impressive technology and still struggle to meet the growth investors are already expecting. That’s why the real question isn’t just whether AI will keep growing.
It’s who actually captures the value from that growth?
Maybe the next opportunity is in the infrastructure behind AI. Maybe it’s in companies quietly adopting AI to improve their businesses. Or maybe an entirely different sector benefits from the productivity wave.
The AI boom is getting bigger—but the interesting part may be discovering where the money goes after the obvious winners have already been noticed.
What are you watching next?
#AIStocksWhatNext
3
321
·
--
Bullish
🇺🇸 Tom Lee’s BitMine just bought another $75 million of Ethereum.
And the timing is getting interesting.
BitMine continues to stack $ETH aggressively, pushing its total holdings to roughly 5.98 million ETH — around 4.9% of Ethereum’s total supply. The company is now just a step away from its much-discussed goal of controlling 5% of ETH.
But the bigger story is what Tom Lee thinks could happen next.
Lee believes Ethereum’s strong performance in Q3 could force institutions to take another look at crypto exposure. ETH has been one of the strongest macro assets this quarter, according to BitMine’s latest update.
And this is not just about holding ETH.
BitMine says it has already staked more than 5 million ETH, with projected annualized staking revenue now in the hundreds of millions of dollars.
That creates a simple setup:
More ETH accumulation.
More ETH being staked.
Growing institutional attention.
And Q4 approaching.
Tom Lee has made a much bigger call around the coming market environment, suggesting Q4 could mark the beginning of an unusually powerful rally.
That is a prediction, not a guarantee.
But when a company is willing to keep putting tens of millions of dollars into ETH while sitting on nearly 6 million ETH, the market is naturally going to pay attention.
The real question now is:
If institutions start increasing their crypto exposure in Q4, how much demand could Ethereum absorb before the market has to reprice it? 👀
1
2
458
·
--
Bullish
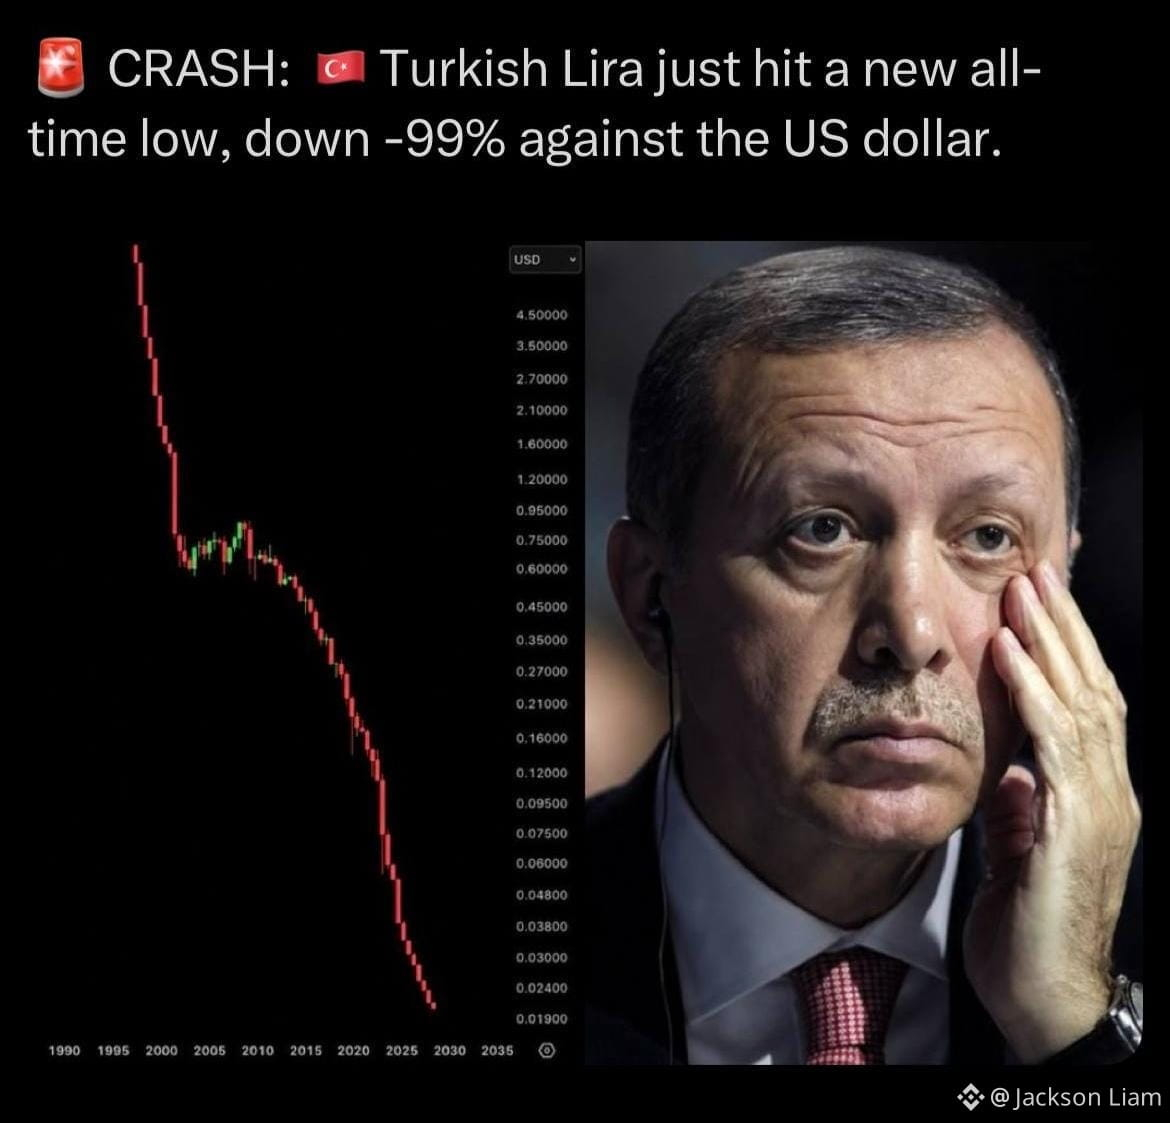
🇹🇷 TURKEY’S CURRENCY HAS LOST ALMOST EVERYTHING 😳
The Turkish lira’s story is one of the most dramatic currency declines of the modern era.
Back around 2000, $1 was worth roughly 0.67 Turkish lira in the old currency system.
Today?
💵 $1 ≈ ₺48.77
That means the lira has been crushed against the US dollar over the long run.
And this wasn’t one sudden 99% crash.
It happened through years of inflation, repeated devaluations and currency pressure.
Turkey has already lived through major currency shocks. During the 2001 crisis, the lira fell sharply after the currency was allowed to float.
Then came another major wave of weakness from 2018 onward.
The result is staggering:
A currency that once had much more value against the dollar now requires nearly 49 lira to buy just $1.
For ordinary people, a weaker currency can mean higher prices for imported goods, travel, energy and other products linked to foreign currencies.
The big question now is simple:
Can Turkey stabilize the lira and bring inflation under control — or will the currency continue losing purchasing power?
The next few years could be very important for the Turkish economy.
449
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number