
StockLite_247
1.5k Posts
StockLite_247
Report
Block User
Free Stock Market News ACCURATE, CONSISTENT, & RELIABLE || https://x.com/Yusty121 || Crypto first commentary with Marco Market Context
Open Trade
Frequent Trader
5.5 Years
7 Following
911 Followers
3.1K+ Liked
Posts
Portfolio
All
Quotes
Videos
PINNED
Elon Musk says “~90% of $SPCX revenue this year will be commercial” with government revenue falling below 5% in Q4.
Starlink has changed the mix so much that SpaceX really looks more like a connectivity platform rather than a government launch business.
Elon Musk says “~90% of $SPCX revenue this year will be commercial” with government revenue falling below 5% in Q4.
Starlink has changed the mix so much that SpaceX really looks more like a connectivity platform rather than a government launch business.
Starlink has changed the mix so much that SpaceX really looks more like a connectivity platform rather than a government launch business.
39
11
191
199k
PINNED
$SPCX just launched USSF-385 on B1100 which is the 100th Falcon 9 Block 5 booster SpaceX has built.
The mission is carrying a classified Space Force payload but the thick fog at Vandenberg made the launch clip look incredible.
$SPCX just launched USSF-385 on B1100 which is the 100th Falcon 9 Block 5 booster SpaceX has built.
The mission is carrying a classified Space Force payload but the thick fog at Vandenberg made the launch clip look incredible.
The mission is carrying a classified Space Force payload but the thick fog at Vandenberg made the launch clip look incredible.
25
15
137
128.1k
·
--
Bullish
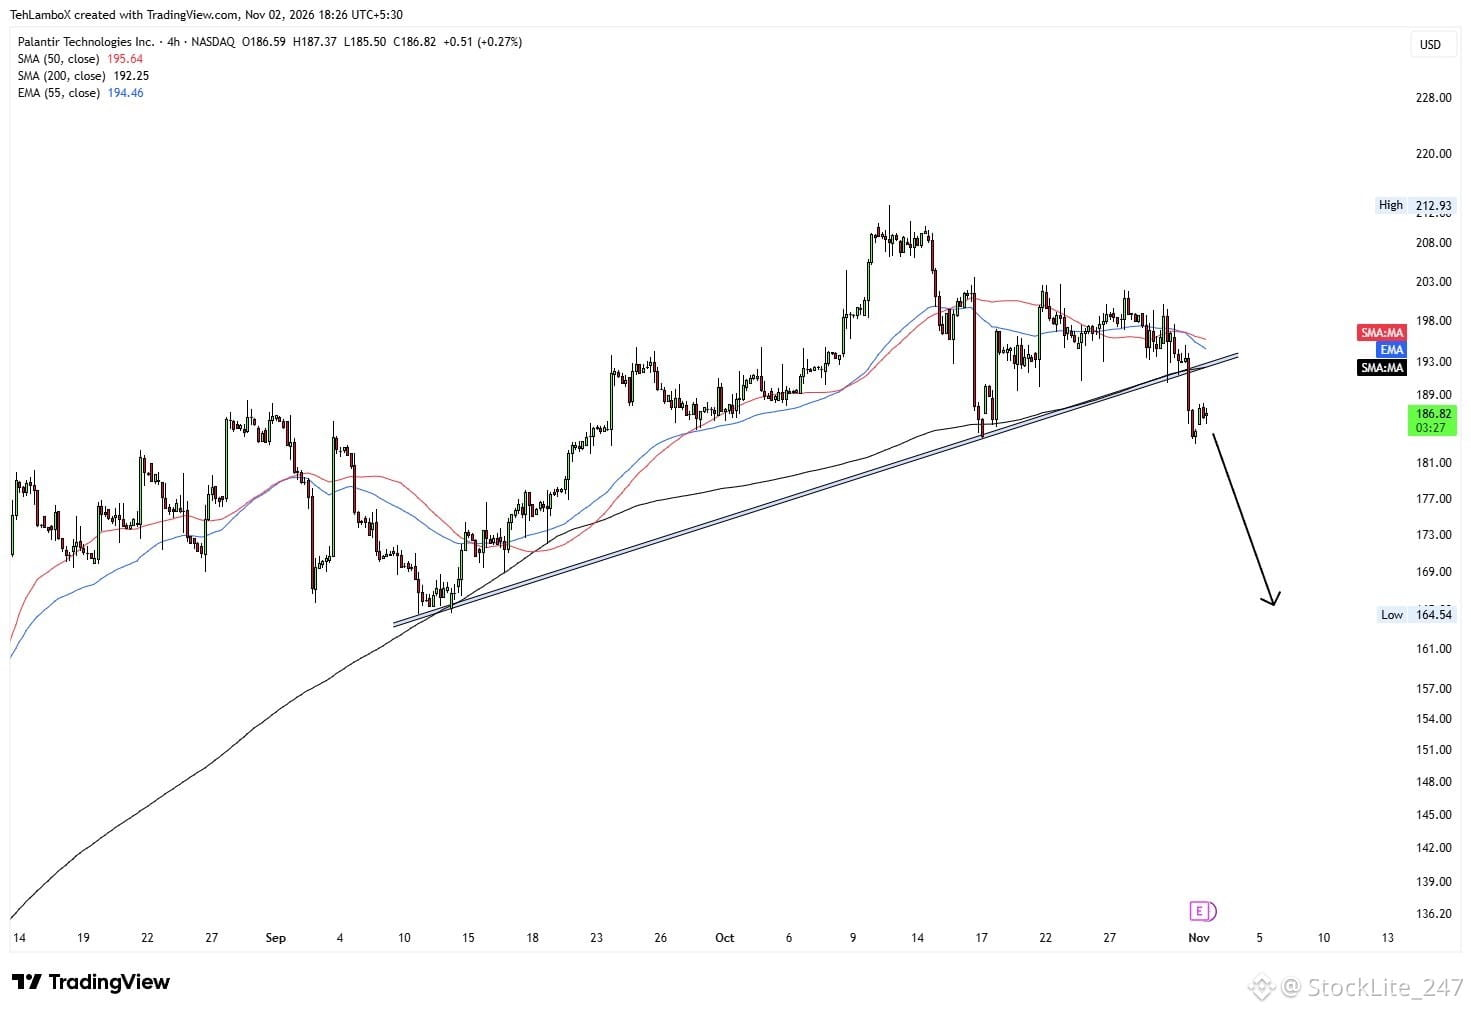
$PLTR on H4 has broken every single support ahead of its ER..
Not looking good but hey, its earnings day and anything can happen. Right??
$PLTR on H4 has broken every single support ahead of its ER..
Not looking good but hey, its earnings day and anything can happen. Right??
Not looking good but hey, its earnings day and anything can happen. Right??
1
62
·
--
Bullish
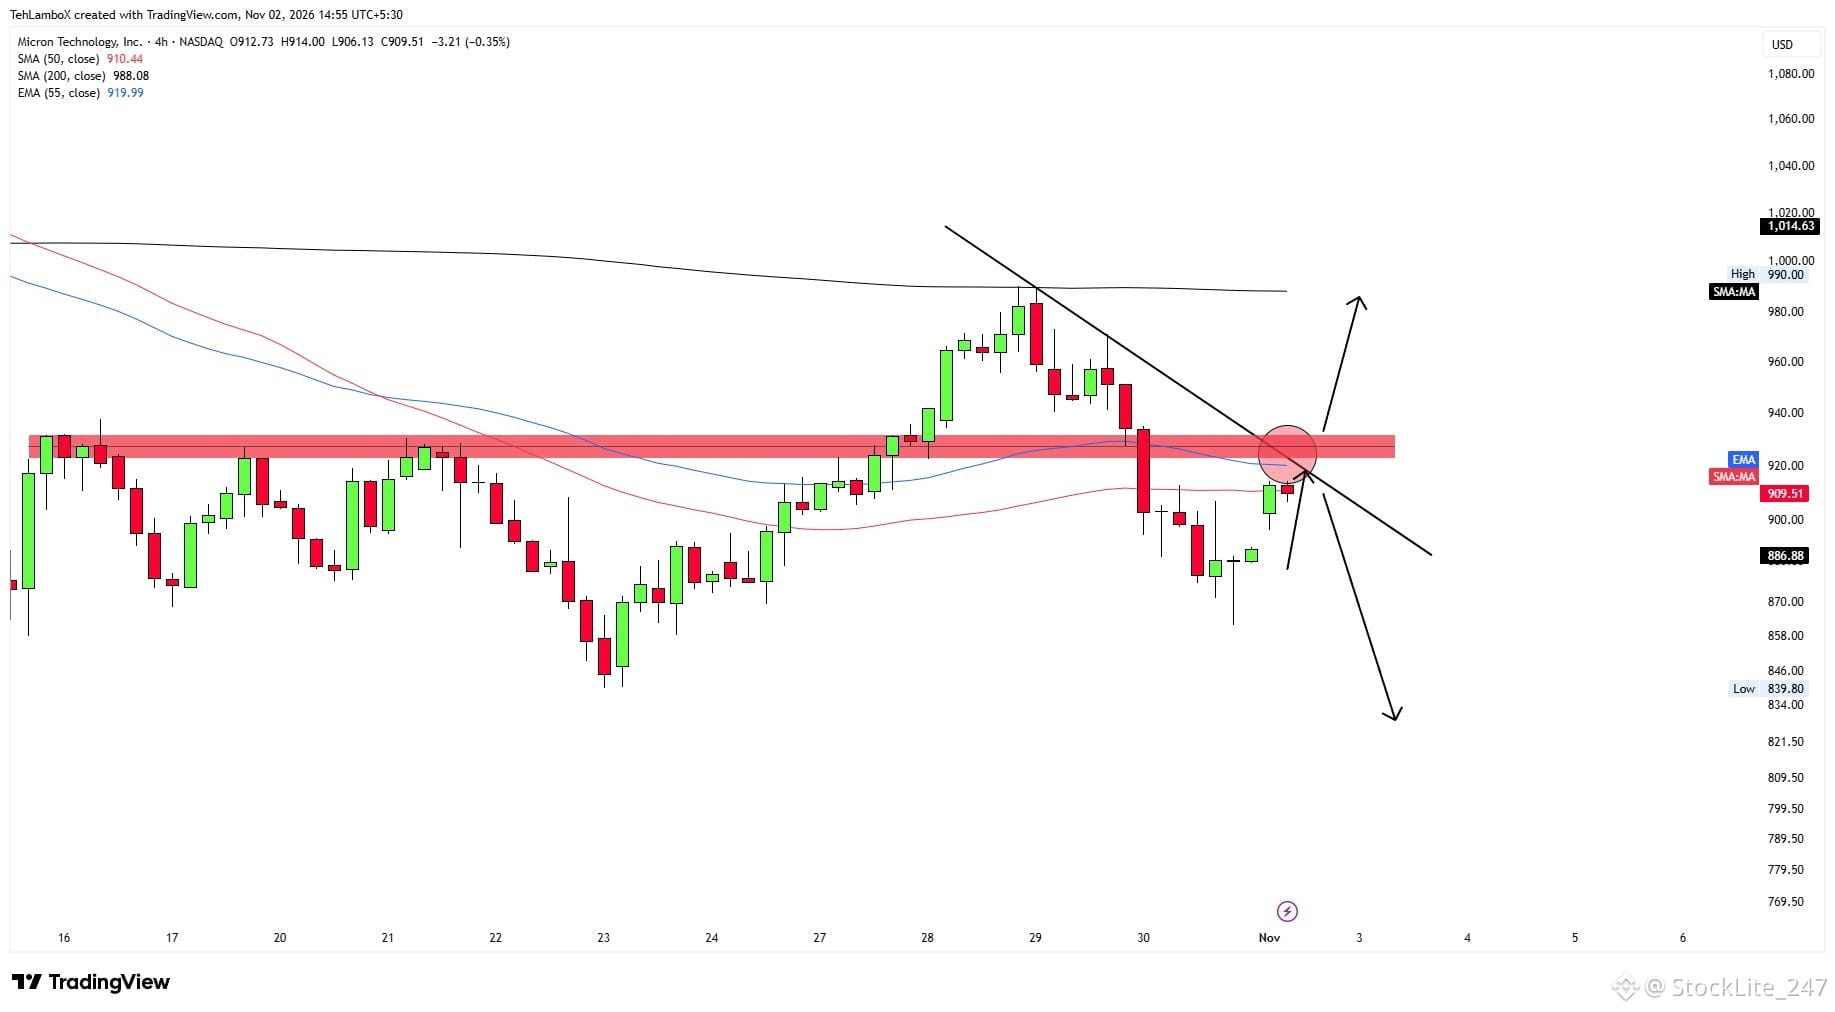
$MU will face a massive resistance again which is confluent with 3 multiple resistances..
If 925 breaks, we might be bullish but until then we will look for a rejection off there only..
$MU will face a massive resistance again which is confluent with 3 multiple resistances..
If 925 breaks, we might be bullish but until then we will look for a rejection off there only..
If 925 breaks, we might be bullish but until then we will look for a rejection off there only..
1
732
·
--
Bullish
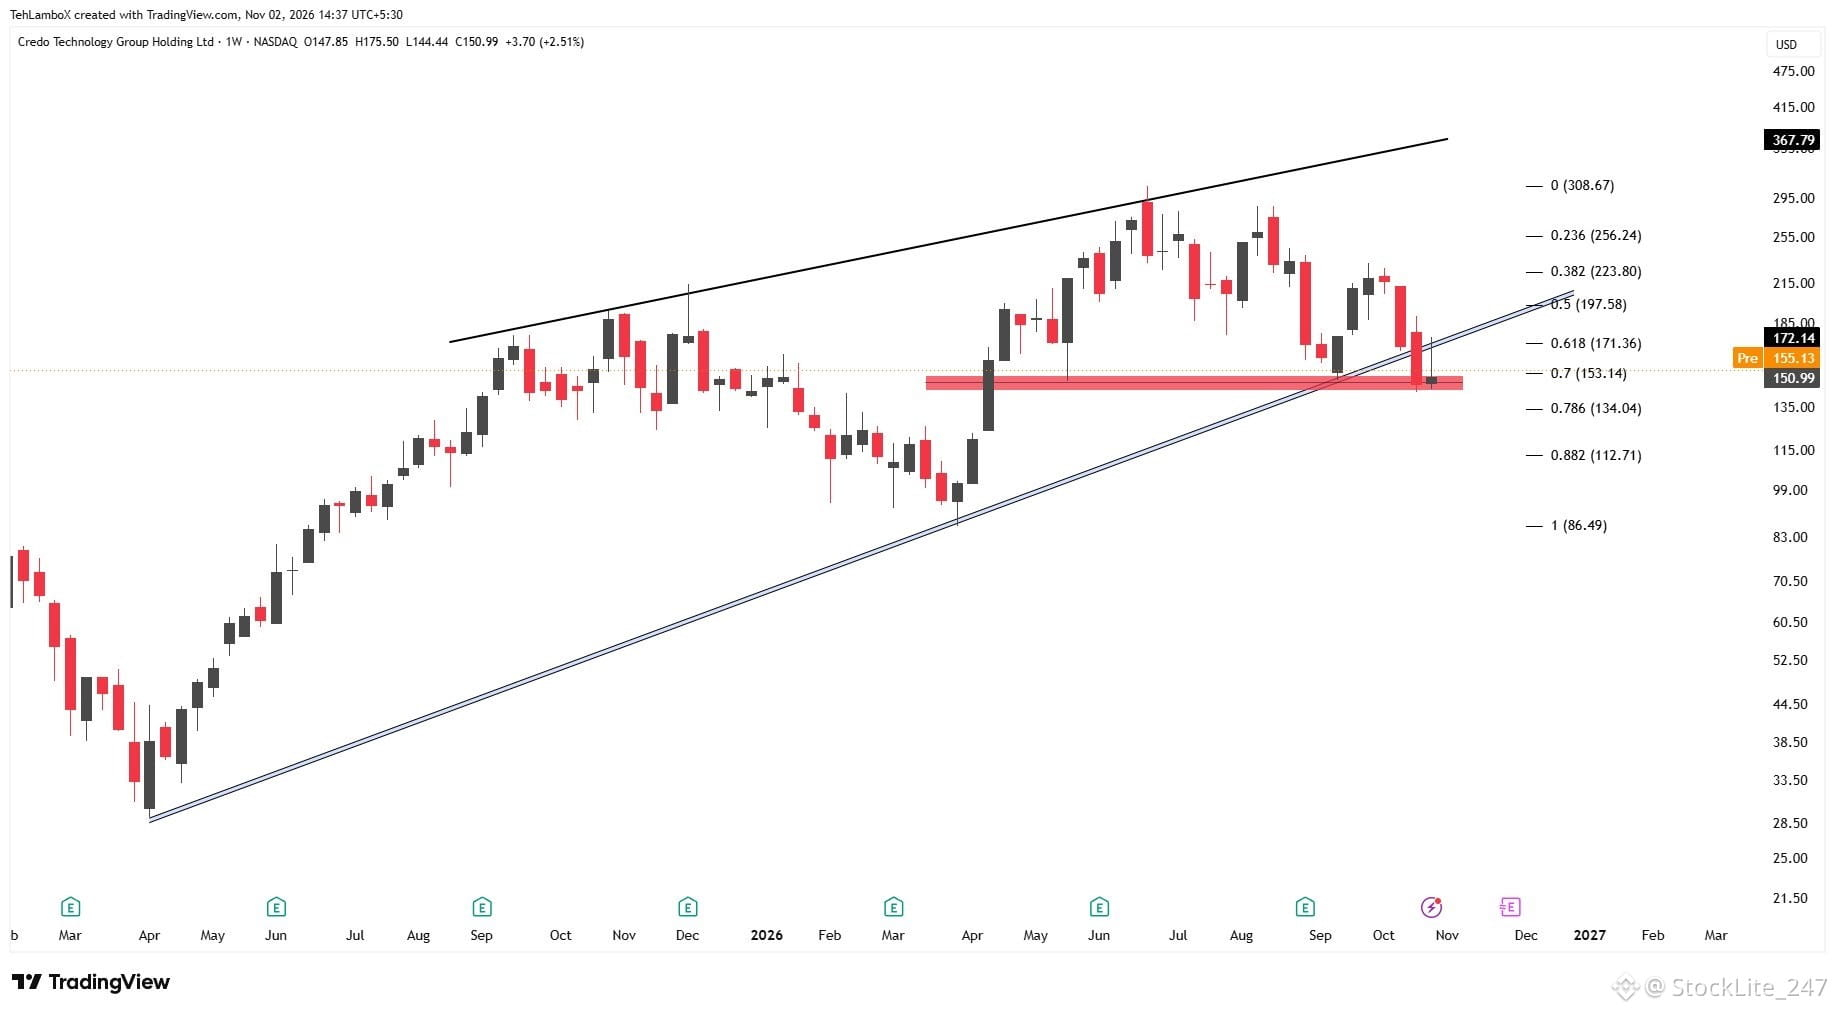
$CRDO is hanging by a thread here..
This has broken below this massive support and got the retest rejection as well..
This support at 140 is the last thing defending this PA here, if it breaks then GOD help this stock..
$CRDO is hanging by a thread here..
This has broken below this massive support and got the retest rejection as well..
This support at 140 is the last thing defending this PA here, if it breaks then GOD help this stock..
This has broken below this massive support and got the retest rejection as well..
This support at 140 is the last thing defending this PA here, if it breaks then GOD help this stock..
1
150
·
--
Bullish
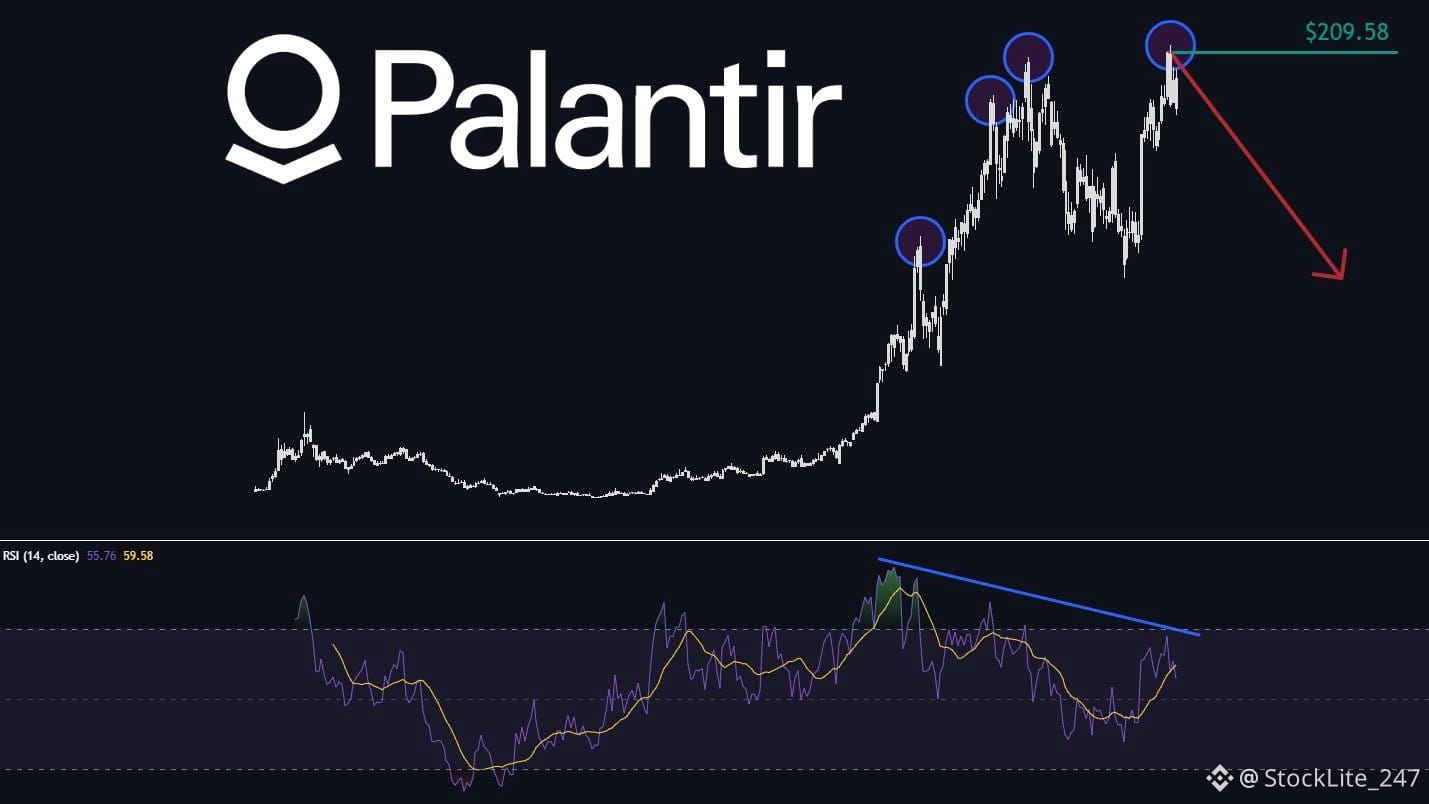
$PLTR REPORTS ITS EARNINGS TODAY, and the technical indicators are raising some serious WARNING signs.
I currently see little evidence supporting another sustained bullish move.
At current levels, $PLTR is a potential sell candidate for me.
Even if the stock manages to reach new ATHs over the coming weeks, I expect the upside to be limited to around $250–$260.
Beyond that, I remain bearish and expect a deeper correction.
What's your outlook on $PLTR?
$PLTR REPORTS ITS EARNINGS TODAY, and the technical indicators are raising some serious WARNING signs.
I currently see little evidence supporting another sustained bullish move.
At current levels, $PLTR is a potential sell candidate for me.
Even if the stock manages to reach new ATHs over the coming weeks, I expect the upside to be limited to around $250–$260.
Beyond that, I remain bearish and expect a deeper correction.
What's your outlook on $PLTR ?
I currently see little evidence supporting another sustained bullish move.
At current levels, $PLTR is a potential sell candidate for me.
Even if the stock manages to reach new ATHs over the coming weeks, I expect the upside to be limited to around $250–$260.
Beyond that, I remain bearish and expect a deeper correction.
What's your outlook on $PLTR ?
1
572
·
--
Bullish
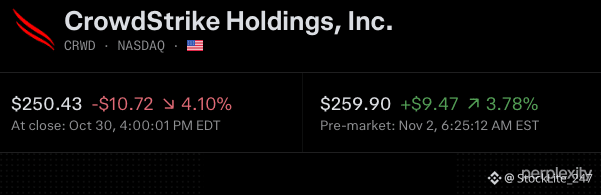
Deutsche Bank upgrades CrowdStrike $CRWD to Buy from Hold, raising its target to $300 from $240.
Brad Zelnick says the market underestimates AI-driven cybersecurity demand.
He sees CrowdStrike's $565B 2034 market estimate as conservative, citing a “tsunami of cyber demand.”
Deutsche Bank upgrades CrowdStrike $CRWD to Buy from Hold, raising its target to $300 from $240.
Brad Zelnick says the market underestimates AI-driven cybersecurity demand.
He sees CrowdStrike's $565B 2034 market estimate as conservative, citing a “tsunami of cyber demand.”
Brad Zelnick says the market underestimates AI-driven cybersecurity demand.
He sees CrowdStrike's $565B 2034 market estimate as conservative, citing a “tsunami of cyber demand.”
1
178
Verified
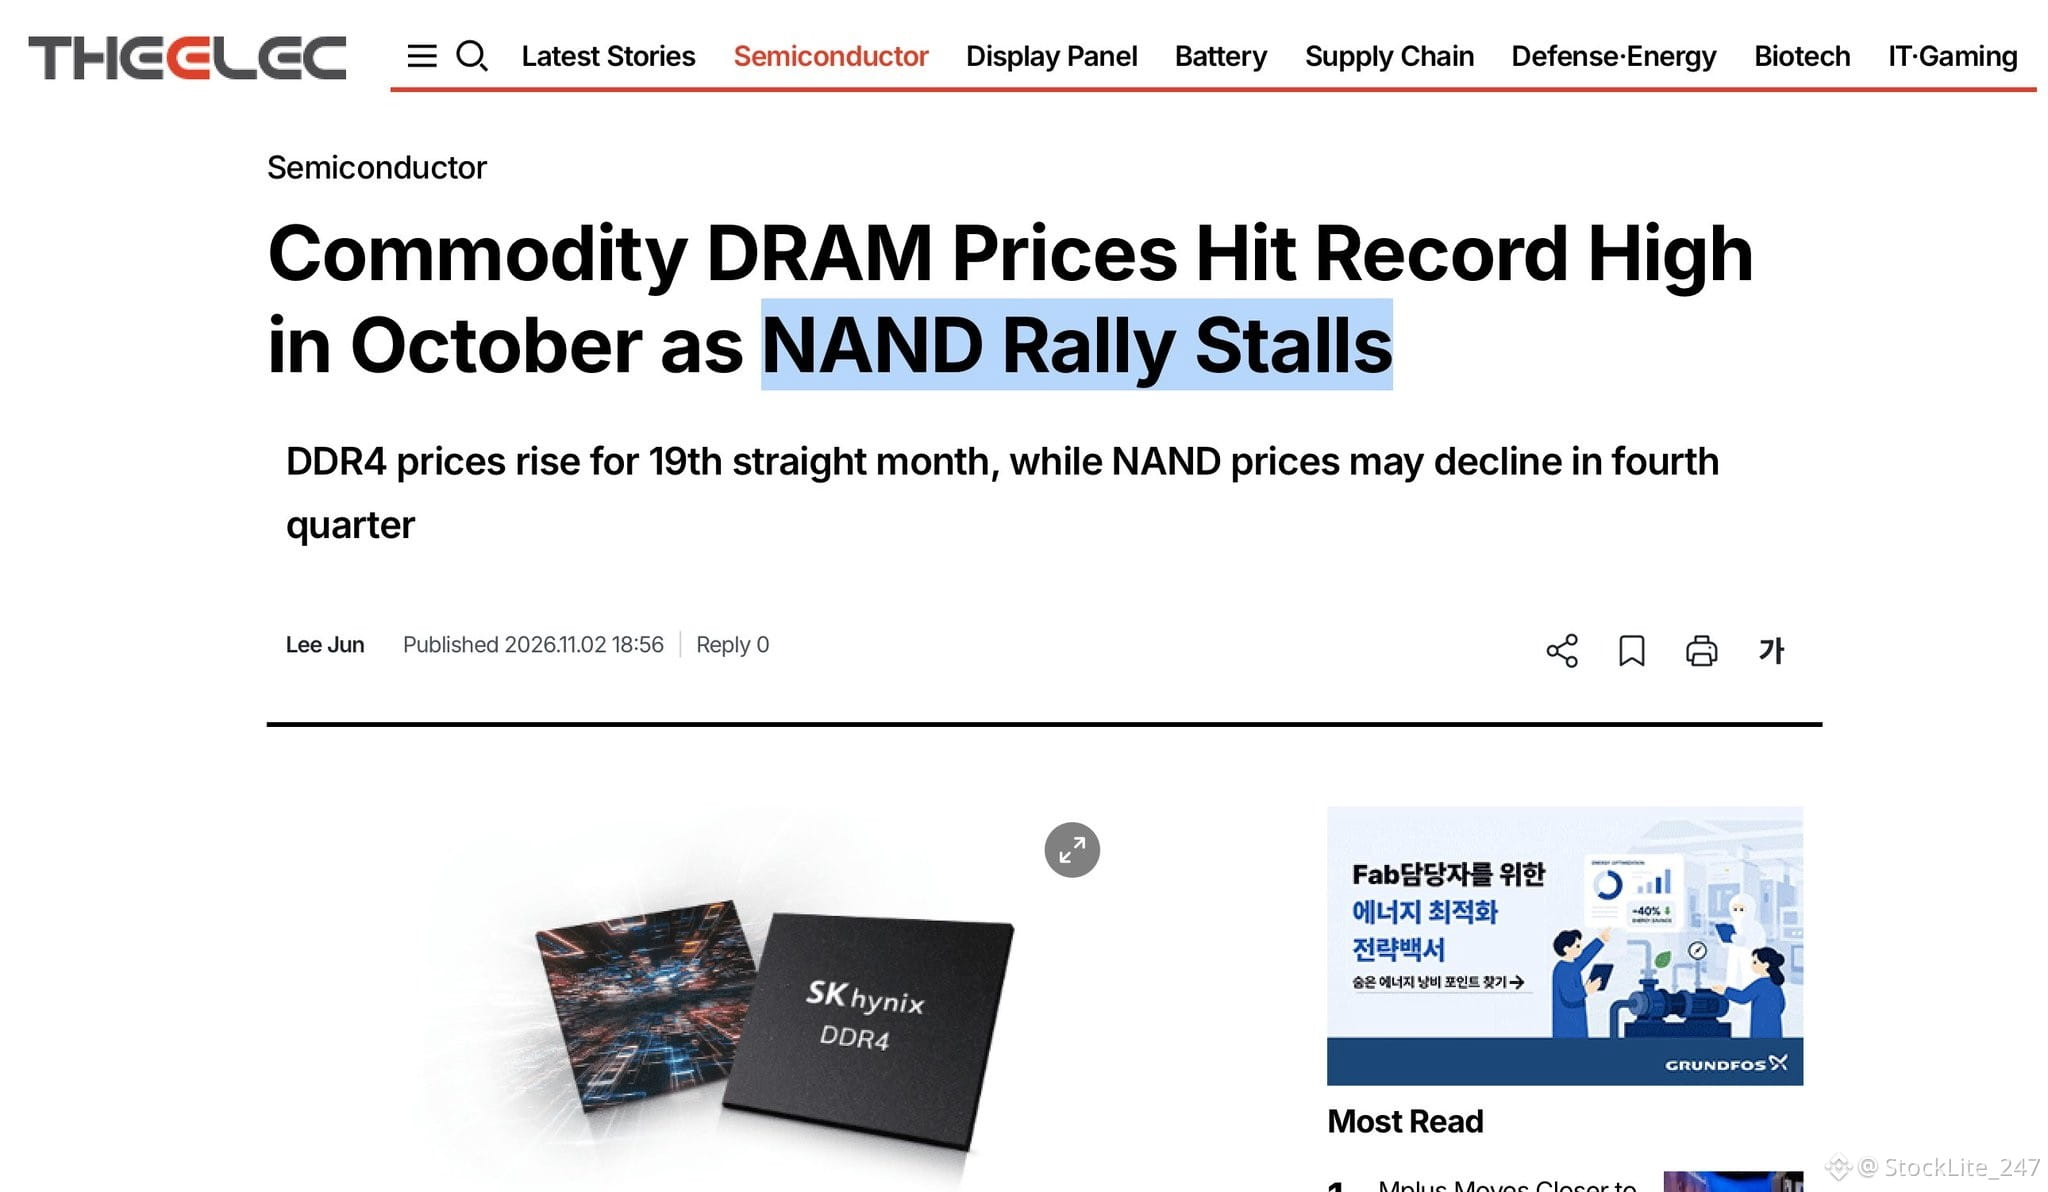
first flat NAND print in ~21 months + the first MoM dip in Korean chip exports, while DRAM keeps rising, points to a DRAM vs NAND split that hits $SNDK before $MU .
What I'm watching is the gap between DRAM-heavy and NAND-heavy names. $MU is mostly DRAM and HBM and guided FQ1 to ~$61.5B. SNDK has no DRAM to lean on.
If NAND rolls over in Q4 while DRAM keeps climbing, those two trades separate.
first flat NAND print in ~21 months + the first MoM dip in Korean chip exports, while DRAM keeps rising, points to a DRAM vs NAND split that hits $SNDK before $MU .
What I'm watching is the gap between DRAM-heavy and NAND-heavy names. $MU is mostly DRAM and HBM and guided FQ1 to ~$61.5B. SNDK has no DRAM to lean on.
If NAND rolls over in Q4 while DRAM keeps climbing, those two trades separate.
What I'm watching is the gap between DRAM-heavy and NAND-heavy names. $MU is mostly DRAM and HBM and guided FQ1 to ~$61.5B. SNDK has no DRAM to lean on.
If NAND rolls over in Q4 while DRAM keeps climbing, those two trades separate.
1
775
·
--
Bullish
$NBIS is trying to make a bounce from the pre-market but I know too well it will be rejected.
As a matter of fact, today and tomorrow might be another hard day (Temporary)
I expect market to start fully recovering from Thursday so if you are willing to add some more position, today and tomorrow might be a great day to add.
$NBIS is trying to make a bounce from the pre-market but I know too well it will be rejected.
As a matter of fact, today and tomorrow might be another hard day (Temporary)
I expect market to start fully recovering from Thursday so if you are willing to add some more position, today and tomorrow might be a great day to add.
As a matter of fact, today and tomorrow might be another hard day (Temporary)
I expect market to start fully recovering from Thursday so if you are willing to add some more position, today and tomorrow might be a great day to add.
1
311
$SPCX is reportedly in talks to acquire Boost Mobile or access its network as Elon Musk looks to launch a full-fledged U.S. wireless service.
The best part isn’t even Boost’s ~7M subscribers but its existing 5G infrastructure and billing systems which could give SpaceX a much faster path into cities where satellites alone can’t handle demand.
The catch is that Boost relies on $TSMB and $TMUS.US for network coverage and transferring those agreements may require their approval so potentially super awkward because Elon’s wireless ambitions in hands of the carriers it wants to disrupt.
$SPCX is reportedly in talks to acquire Boost Mobile or access its network as Elon Musk looks to launch a full-fledged U.S. wireless service.
The best part isn’t even Boost’s ~7M subscribers but its existing 5G infrastructure and billing systems which could give SpaceX a much faster path into cities where satellites alone can’t handle demand.
The catch is that Boost relies on $TSMB and $TMUS.US for network coverage and transferring those agreements may require their approval so potentially super awkward because Elon’s wireless ambitions in hands of the carriers it wants to disrupt.
The best part isn’t even Boost’s ~7M subscribers but its existing 5G infrastructure and billing systems which could give SpaceX a much faster path into cities where satellites alone can’t handle demand.
The catch is that Boost relies on $TSMB and $TMUS.US for network coverage and transferring those agreements may require their approval so potentially super awkward because Elon’s wireless ambitions in hands of the carriers it wants to disrupt.
SPCX+2.42%
TMUSUS+0.22%
1
767
·
--
Bullish
When fundamentally strong companies break below their 200-week moving average, you BET BIG.
$MSFT broke below its 200 WMA twice this year:
• March — for the first time in over 14 years.
• July — since hitting its July low, the stock has surged 50%, reaching a peak gain of 57%.
Now look at $ORCL .
Oracle has broken below its 200 WMA only FOUR times in the past 17 years.
And EVERY SINGLE TIME, it reclaimed that level within weeks.
Now it’s trading below it again.
I’m BUYING AGGRESSIVELY.
If this market correction pushes companies like $AMZN , GOOGL, and META toward or below their 200 WMA, I’ll be deploying serious capital.
When fundamentally strong companies break below their 200-week moving average, you BET BIG.
$MSFT broke below its 200 WMA twice this year:
• March — for the first time in over 14 years.
• July — since hitting its July low, the stock has surged 50%, reaching a peak gain of 57%.
Now look at $ORCL .
Oracle has broken below its 200 WMA only FOUR times in the past 17 years.
And EVERY SINGLE TIME, it reclaimed that level within weeks.
Now it’s trading below it again.
I’m BUYING AGGRESSIVELY.
If this market correction pushes companies like $AMZN , GOOGL, and META toward or below their 200 WMA, I’ll be deploying serious capital.
$MSFT broke below its 200 WMA twice this year:
• March — for the first time in over 14 years.
• July — since hitting its July low, the stock has surged 50%, reaching a peak gain of 57%.
Now look at $ORCL .
Oracle has broken below its 200 WMA only FOUR times in the past 17 years.
And EVERY SINGLE TIME, it reclaimed that level within weeks.
Now it’s trading below it again.
I’m BUYING AGGRESSIVELY.
If this market correction pushes companies like $AMZN , GOOGL, and META toward or below their 200 WMA, I’ll be deploying serious capital.
1
486
·
--
Bullish
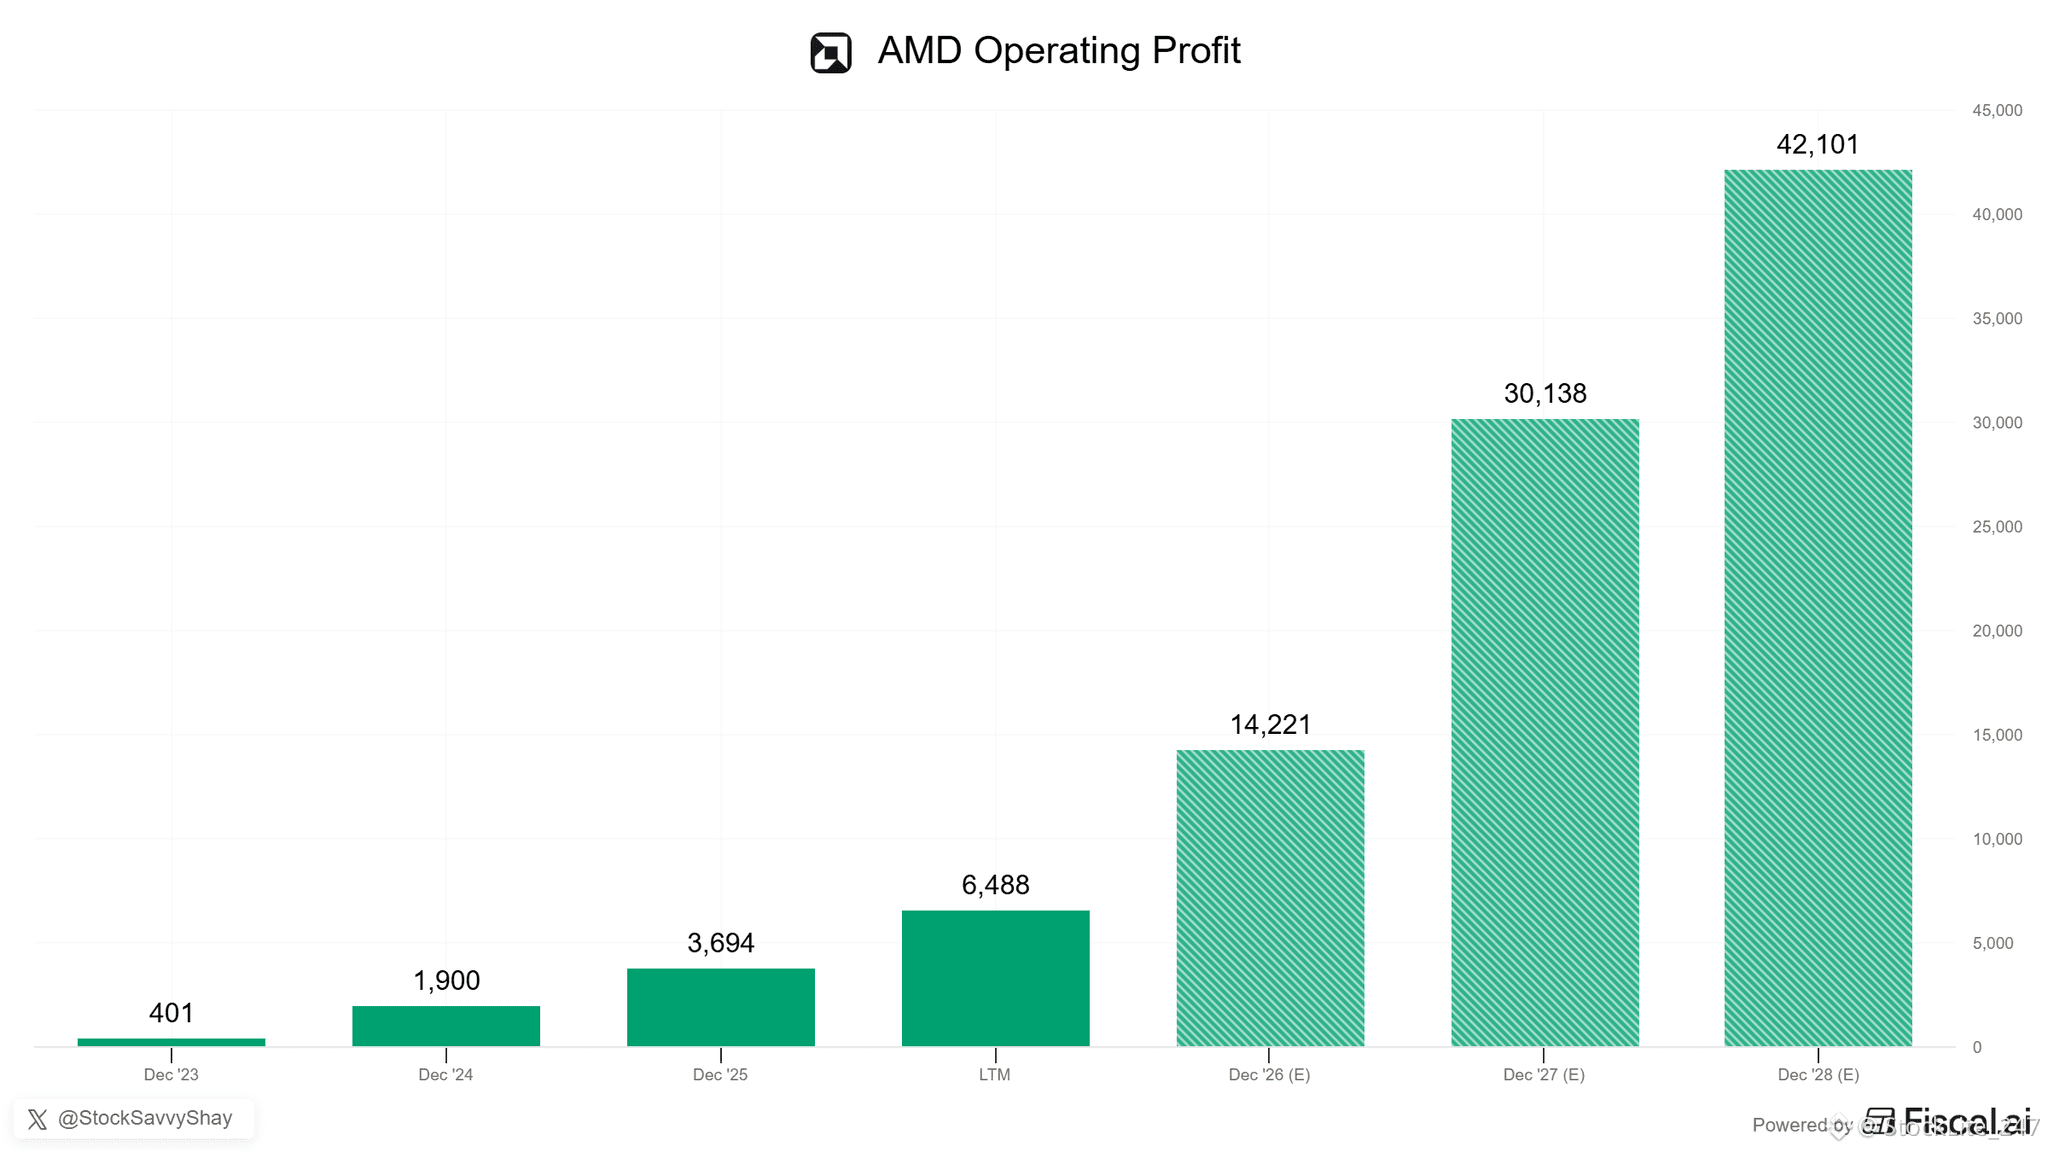
$AMD is on pace to generate ~$86B in profit over the next three years:
• 2026: $14.2B (+285% YoY)
• 2027: $30.1B (+112% YoY)
• 2028: $42.1B (+40% YoY)
AMD is only scaled challenger to both INTC in server CPUs and $NVDA in AI GPUs with its EPYC processors already powering $META Muse agent, Helios systems running at Meta and custom Instinct GPUs on way.
Intel also just told us they expect agentic AI to expand server CPU market 5x to over $200B while admitting supply cannot keep up with demand creating an opportunity for AMD to gain a ton of market share.
$AMD is on pace to generate ~$86B in profit over the next three years:
• 2026: $14.2B (+285% YoY)
• 2027: $30.1B (+112% YoY)
• 2028: $42.1B (+40% YoY)
AMD is only scaled challenger to both INTC in server CPUs and $NVDA in AI GPUs with its EPYC processors already powering $META Muse agent, Helios systems running at Meta and custom Instinct GPUs on way.
Intel also just told us they expect agentic AI to expand server CPU market 5x to over $200B while admitting supply cannot keep up with demand creating an opportunity for AMD to gain a ton of market share.
• 2026: $14.2B (+285% YoY)
• 2027: $30.1B (+112% YoY)
• 2028: $42.1B (+40% YoY)
AMD is only scaled challenger to both INTC in server CPUs and $NVDA in AI GPUs with its EPYC processors already powering $META Muse agent, Helios systems running at Meta and custom Instinct GPUs on way.
Intel also just told us they expect agentic AI to expand server CPU market 5x to over $200B while admitting supply cannot keep up with demand creating an opportunity for AMD to gain a ton of market share.
1
253
·
--
Bullish
$AMZN has secured an $80 BILLION financing facility to fund AI infrastructure purchases.
The financing is backed by the very assets Amazon will acquire with the borrowed money.
• Drawdown period: Q1 2027 through Q3 2028
• Maturity: Up to 5 years for each borrowing
This is exactly the financing model neoclouds like CRWV, $NBIS , and IREN are pursuing: raising debt backed by $NVDA GPUs and data center infrastructure.
But there’s a MASSIVE difference.
AMZN generates enormous operating cash flow from businesses that don’t depend on AI infrastructure.
That makes Amazon a far more attractive borrower in the eyes of lenders.
And here’s the real problem for neoclouds.
As hyperscalers increasingly turn to debt markets to finance their AI expansion, they’re competing for the same pools of capital that neoclouds need to fund their growth.
Why would lenders take on significantly more risk financing a neocloud when they can lend to Amazon?
I expect neoclouds to secure the financing they need. The demand for AI compute and the economics of these investments are simply too compelling.
But as hyperscalers absorb increasingly large amounts of capital, securing financing on attractive terms will become one of the defining challenges for the entire neocloud industry.
$AMZN has secured an $80 BILLION financing facility to fund AI infrastructure purchases.
The financing is backed by the very assets Amazon will acquire with the borrowed money.
• Drawdown period: Q1 2027 through Q3 2028
• Maturity: Up to 5 years for each borrowing
This is exactly the financing model neoclouds like CRWV, $NBIS , and IREN are pursuing: raising debt backed by $NVDA GPUs and data center infrastructure.
But there’s a MASSIVE difference.
AMZN generates enormous operating cash flow from businesses that don’t depend on AI infrastructure.
That makes Amazon a far more attractive borrower in the eyes of lenders.
And here’s the real problem for neoclouds.
As hyperscalers increasingly turn to debt markets to finance their AI expansion, they’re competing for the same pools of capital that neoclouds need to fund their growth.
Why would lenders take on significantly more risk financing a neocloud when they can lend to Amazon?
I expect neoclouds to secure the financing they need. The demand for AI compute and the economics of these investments are simply too compelling.
But as hyperscalers absorb increasingly large amounts of capital, securing financing on attractive terms will become one of the defining challenges for the entire neocloud industry.
The financing is backed by the very assets Amazon will acquire with the borrowed money.
• Drawdown period: Q1 2027 through Q3 2028
• Maturity: Up to 5 years for each borrowing
This is exactly the financing model neoclouds like CRWV, $NBIS , and IREN are pursuing: raising debt backed by $NVDA GPUs and data center infrastructure.
But there’s a MASSIVE difference.
AMZN generates enormous operating cash flow from businesses that don’t depend on AI infrastructure.
That makes Amazon a far more attractive borrower in the eyes of lenders.
And here’s the real problem for neoclouds.
As hyperscalers increasingly turn to debt markets to finance their AI expansion, they’re competing for the same pools of capital that neoclouds need to fund their growth.
Why would lenders take on significantly more risk financing a neocloud when they can lend to Amazon?
I expect neoclouds to secure the financing they need. The demand for AI compute and the economics of these investments are simply too compelling.
But as hyperscalers absorb increasingly large amounts of capital, securing financing on attractive terms will become one of the defining challenges for the entire neocloud industry.
1
404
·
--
Bullish
I can’t tell you whether $150 is the bottom for $NBIS.
The stock could even fall below $100.
But one thing I’m absolutely convinced of:
Buying $NBIS at these prices will look like an incredible decision a few years from now.
$NBIS will trade MUCH higher than it does today.
I can’t tell you whether $150 is the bottom for $NBIS .
The stock could even fall below $100.
But one thing I’m absolutely convinced of:
Buying $NBIS at these prices will look like an incredible decision a few years from now.
$NBIS will trade MUCH higher than it does today.
The stock could even fall below $100.
But one thing I’m absolutely convinced of:
Buying $NBIS at these prices will look like an incredible decision a few years from now.
$NBIS will trade MUCH higher than it does today.
1
3
1.1k
·
--
Bullish
Verified
Tomorrow, $GRAB.US will report its first-ever $1B revenue quarter.
The stock trades at just $2.73, with a forward P/E of 15x.
Meanwhile, its CEO bought $30M worth of shares at $2.89.
$GRAB is one of the biggest opportunities in the entire stock market.
Here’s what I’ll be watching closely in tomorrow’s earnings:
• Financial Services EBITDA breakeven.
The segment reported a $15M adjusted EBITDA loss in Q2, and management guided for adjusted EBITDA breakeven in H2 2026. I want to see it happen in Q3.
• Revenue growth above 23% YoY.
Q2 growth was 22%, but Q3 includes a full quarter of Stash and Superbank consolidation. Anything below 23% would raise serious questions about the strength of underlying organic growth.
At 15x forward earnings, the market is dramatically underestimating what $GRAB is becoming.
Tomorrow, $GRAB.US will report its first-ever $1B revenue quarter.
The stock trades at just $2.73, with a forward P/E of 15x.
Meanwhile, its CEO bought $30M worth of shares at $2.89.
$GRAB is one of the biggest opportunities in the entire stock market.
Here’s what I’ll be watching closely in tomorrow’s earnings:
• Financial Services EBITDA breakeven.
The segment reported a $15M adjusted EBITDA loss in Q2, and management guided for adjusted EBITDA breakeven in H2 2026. I want to see it happen in Q3.
• Revenue growth above 23% YoY.
Q2 growth was 22%, but Q3 includes a full quarter of Stash and Superbank consolidation. Anything below 23% would raise serious questions about the strength of underlying organic growth.
At 15x forward earnings, the market is dramatically underestimating what $GRAB is becoming.
The stock trades at just $2.73, with a forward P/E of 15x.
Meanwhile, its CEO bought $30M worth of shares at $2.89.
$GRAB is one of the biggest opportunities in the entire stock market.
Here’s what I’ll be watching closely in tomorrow’s earnings:
• Financial Services EBITDA breakeven.
The segment reported a $15M adjusted EBITDA loss in Q2, and management guided for adjusted EBITDA breakeven in H2 2026. I want to see it happen in Q3.
• Revenue growth above 23% YoY.
Q2 growth was 22%, but Q3 includes a full quarter of Stash and Superbank consolidation. Anything below 23% would raise serious questions about the strength of underlying organic growth.
At 15x forward earnings, the market is dramatically underestimating what $GRAB is becoming.
GRABUS+5.33%
2
867
·
--
Bullish
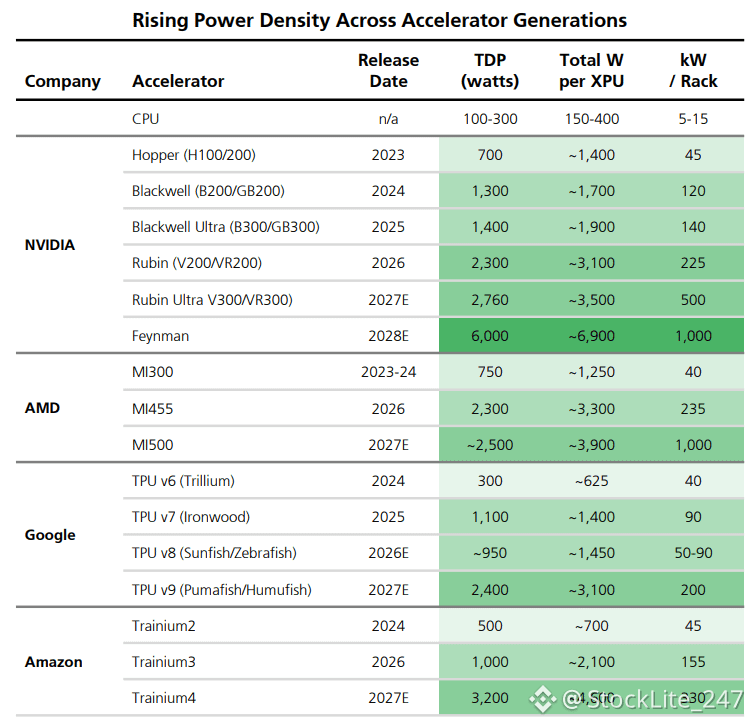
2027 is shaping up to be biggest step change in AI power density yet:
• $NVDA Rubin Ultra ~500kW per rack
• $AMD MI500 ~1,000kW per rack
• $AMZN Trainium4 ~330kW per rack
• GOOGL TPU v9 ~200kW per rack
Traditional data centers were built for CPU racks of just ~10kW so this shift will require a lot of upgrades to existing facilities and fundamentally different electrical and liquid cooling systems in new builds.
2027 is shaping up to be biggest step change in AI power density yet:
• $NVDA Rubin Ultra ~500kW per rack
• $AMD MI500 ~1,000kW per rack
• $AMZN Trainium4 ~330kW per rack
• GOOGL TPU v9 ~200kW per rack
Traditional data centers were built for CPU racks of just ~10kW so this shift will require a lot of upgrades to existing facilities and fundamentally different electrical and liquid cooling systems in new builds.
• $NVDA Rubin Ultra ~500kW per rack
• $AMD MI500 ~1,000kW per rack
• $AMZN Trainium4 ~330kW per rack
• GOOGL TPU v9 ~200kW per rack
Traditional data centers were built for CPU racks of just ~10kW so this shift will require a lot of upgrades to existing facilities and fundamentally different electrical and liquid cooling systems in new builds.
1
585
·
--
Bullish
The three largest cloud platforms are now generating a combined ~$440B in annualized revenue:
• $AMZN AWS ~$184B (+39% YoY)
• $MSFT Azure ~$133B (+48% YoY)
• $GOOGL Cloud ~$123B (+103% YoY)
Agentic AI is becoming a massive tailwind of cloud demand as AWS customers deployed twice as many AgentCore agents in Q3 as previous three quarters combined while Bedrock token volume grew ~17x and Google’s model API usage more than quadrupled YoY and AI agents now start over 40% of GitHub pull requests.
The three largest cloud platforms are now generating a combined ~$440B in annualized revenue:
• $AMZN AWS ~$184B (+39% YoY)
• $MSFT Azure ~$133B (+48% YoY)
• $GOOGL Cloud ~$123B (+103% YoY)
Agentic AI is becoming a massive tailwind of cloud demand as AWS customers deployed twice as many AgentCore agents in Q3 as previous three quarters combined while Bedrock token volume grew ~17x and Google’s model API usage more than quadrupled YoY and AI agents now start over 40% of GitHub pull requests.
• $AMZN AWS ~$184B (+39% YoY)
• $MSFT Azure ~$133B (+48% YoY)
• $GOOGL Cloud ~$123B (+103% YoY)
Agentic AI is becoming a massive tailwind of cloud demand as AWS customers deployed twice as many AgentCore agents in Q3 as previous three quarters combined while Bedrock token volume grew ~17x and Google’s model API usage more than quadrupled YoY and AI agents now start over 40% of GitHub pull requests.
2
1.1k
·
--
Bullish
Verified
Something doesn't add up with $SNDK .
Sandisk dropped 13.5% on Friday, closing around $1,151, despite reporting a monster quarter. The stock is now down roughly 51% from its June high.
Look at these numbers:
• Market cap: ~$164 billion
• Cash and equivalents: $5.14 billion
• Enterprise value: ~$160 billion
• Trailing P/E: ~9.3
• Annual revenue (TTM): $28.97 billion
• Annual net income (TTM): $19.42 billion
• Q1 revenue growth: +378% YoY
• Q1 GAAP net income: $8.1 billion
• Q1 gross margin: 85%
• Q1 free cash flow: $6.31 billion
• Data center revenue growth: +61% QoQ
• Q2 revenue guidance: $12.2B–$12.6B
• Stock buybacks in Q1: $5 billion
The concern is whether these extraordinary profit margins can last, especially in a historically cyclical memory industry.
But does that justify a 13.5% drop immediately after earnings for a company growing revenue nearly 400% and generating billions in free cash flow?
Is this an overreaction, or am I missing something?
Something doesn't add up with $SNDK .
Sandisk dropped 13.5% on Friday, closing around $1,151, despite reporting a monster quarter. The stock is now down roughly 51% from its June high.
Look at these numbers:
• Market cap: ~$164 billion
• Cash and equivalents: $5.14 billion
• Enterprise value: ~$160 billion
• Trailing P/E: ~9.3
• Annual revenue (TTM): $28.97 billion
• Annual net income (TTM): $19.42 billion
• Q1 revenue growth: +378% YoY
• Q1 GAAP net income: $8.1 billion
• Q1 gross margin: 85%
• Q1 free cash flow: $6.31 billion
• Data center revenue growth: +61% QoQ
• Q2 revenue guidance: $12.2B–$12.6B
• Stock buybacks in Q1: $5 billion
The concern is whether these extraordinary profit margins can last, especially in a historically cyclical memory industry.
But does that justify a 13.5% drop immediately after earnings for a company growing revenue nearly 400% and generating billions in free cash flow?
Is this an overreaction, or am I missing something?
Sandisk dropped 13.5% on Friday, closing around $1,151, despite reporting a monster quarter. The stock is now down roughly 51% from its June high.
Look at these numbers:
• Market cap: ~$164 billion
• Cash and equivalents: $5.14 billion
• Enterprise value: ~$160 billion
• Trailing P/E: ~9.3
• Annual revenue (TTM): $28.97 billion
• Annual net income (TTM): $19.42 billion
• Q1 revenue growth: +378% YoY
• Q1 GAAP net income: $8.1 billion
• Q1 gross margin: 85%
• Q1 free cash flow: $6.31 billion
• Data center revenue growth: +61% QoQ
• Q2 revenue guidance: $12.2B–$12.6B
• Stock buybacks in Q1: $5 billion
The concern is whether these extraordinary profit margins can last, especially in a historically cyclical memory industry.
But does that justify a 13.5% drop immediately after earnings for a company growing revenue nearly 400% and generating billions in free cash flow?
Is this an overreaction, or am I missing something?
1
1
972
·
--
Bullish
Partly True
Bloomberg projects AI funding gap will more than double to ~$330B in FY27 with $ORCL and $SPCX accounting for the largest share.
What stands out is that GOOGL, META, $AMZN and MSFT funding gap largely disappears by FY28 while CRWV, NBIS and IREN still need outside capital through FY30.
Bloomberg projects AI funding gap will more than double to ~$330B in FY27 with $ORCL and $SPCX accounting for the largest share.
What stands out is that GOOGL, META, $AMZN and MSFT funding gap largely disappears by FY28 while CRWV, NBIS and IREN still need outside capital through FY30.
What stands out is that GOOGL, META, $AMZN and MSFT funding gap largely disappears by FY28 while CRWV, NBIS and IREN still need outside capital through FY30.
1
653
·
--
Bullish
$NBIS is sitting on a record $28B in total assets against a $35B market cap.
That's equivalent to 80% of its entire market cap.
The market is valuing Nebius at just 1.25x its total assets while Nvidia committed $2B to the company, with plans to help it deploy 5+ GW of Nvidia systems by 2030.
$NBIS is sitting on a record $28B in total assets against a $35B market cap.
That's equivalent to 80% of its entire market cap.
The market is valuing Nebius at just 1.25x its total assets while Nvidia committed $2B to the company, with plans to help it deploy 5+ GW of Nvidia systems by 2030.
That's equivalent to 80% of its entire market cap.
The market is valuing Nebius at just 1.25x its total assets while Nvidia committed $2B to the company, with plans to help it deploy 5+ GW of Nvidia systems by 2030.
1
684
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
BinanceWithdrawalScamWarning
727 views
125 Discussing
Binance Warns Users of Withdrawal Scams as Services Resume: It Will Never Charge Fees, Sell Queue Spots or Ask You to Move Funds to a “Vault”
Binance News
·1 Likes
·1.7k views
USMidtermElections
543,453 views
2,682 Discussing
USOctoberNFP-AreRateCutsStillPossible
6,684 views
232 Discussing