

CHAINLINK RWA
49 Posts
CHAINLINK RWA
Report
Block User
#COIN 💍 | #RWA 🌐 | #AI 📊 | Market Analysis 🚀 | Alpha Seeker & Airdrop Hunter 🔍 | Provice services: Play-2-Earn, METAVERSE, NFT, RWA, Depin
775 Following
175 Followers
95 Liked
Posts
All
Quotes
Corporate actions for all US equities are now available on Pyth.
Splits, dividends, ticker changes, mergers and more, with the data applications need to track them 🧵
$PYTH $LINK $ONDO
Corporate actions for all US equities are now available on Pyth.
Splits, dividends, ticker changes, mergers and more, with the data applications need to track them 🧵
$PYTH $LINK $ONDO
Splits, dividends, ticker changes, mergers and more, with the data applications need to track them 🧵
$PYTH $LINK $ONDO
134
🔥 $LINK HAS ENTERED THE INSTITUTIONAL DERIVATIVES CLUB
CME’s single-asset crypto futures lineup includes Chainlink.
That puts LINK alongside $XRP, $SOL, ADA, AVAX and SUI in CME’s expanding regulated crypto derivatives market.
🔥 $LINK HAS ENTERED THE INSTITUTIONAL DERIVATIVES CLUB
CME’s single-asset crypto futures lineup includes Chainlink.
That puts LINK alongside $XRP, $SOL, ADA, AVAX and SUI in CME’s expanding regulated crypto derivatives market.
CME’s single-asset crypto futures lineup includes Chainlink.
That puts LINK alongside $XRP, $SOL, ADA, AVAX and SUI in CME’s expanding regulated crypto derivatives market.
69
NEW: @PaxosLabs, has launched PAXGy, a gold-backed token built on $1.8B+ PAX Gold (PAXG) issued by @Paxos that accrues in gold terms.
PAXGy is powered by CCIP as its exclusive cross-chain infra & Chainlink Price Feeds for reliable onchain pricing to enable adoption across DeFi. $LINK
{future}(LINKUSDT)
$ETH
{future}(ETHUSDT)
NEW: @PaxosLabs, has launched PAXGy, a gold-backed token built on $1.8B+ PAX Gold (PAXG) issued by @Paxos that accrues in gold terms.
PAXGy is powered by CCIP as its exclusive cross-chain infra & Chainlink Price Feeds for reliable onchain pricing to enable adoption across DeFi. $LINK
$ETH
PAXGy is powered by CCIP as its exclusive cross-chain infra & Chainlink Price Feeds for reliable onchain pricing to enable adoption across DeFi. $LINK
$ETH
42
Vitalik: Ethereum is Becoming More Than a Blockchain
Speaking at the 2026 Shanghai Blockchain International Week, Ethereum co-founder Vitalik Buterin shared a broader vision for where Ethereum is heading.
His main point: Ethereum is evolving from a blockchain that executes everything into a global system focused on computation, privacy and verification.
Here are the key ideas:
1/ ZK is becoming the foundation → Instead of every node doing the same computation, users or other systems can do the work and generate a proof. Ethereum only needs to verify that proof.
2/ Privacy becomes programmable → Vitalik said blockchain is moving beyond simply answering “Who can send what?” The next question is “Who can see what?” This means applications could control which information is visible without exposing everything publicly.
3/ Scaling through proofs → Complex computations can be split, processed in parallel and compressed into proofs before being verified on Ethereum. This could allow much more computation without putting all of it directly on-chain.
4/ Ethereum becomes a full pipeline → Vitalik described a future involving user devices, private transaction pools, multiple participants, block construction, L2s and finally Ethereum for verification. Ethereum does not need to perform every step itself.
5/ AI changes development → AI can help developers write, test and formally verify increasingly complex cryptographic systems. Vitalik believes this can make advanced Ethereum infrastructure both faster to build and more secure.
6/ Quantum resistance matters → Ethereum is also moving toward quantum-safe cryptography, with STARK-based systems playing an important role in the longer-term roadmap.
Ethereum's future may not simply be about making the L1 faster.
It is about building a trust layer where computation can happen anywhere, privacy can be programmed, and complex results can be mathematically proven and verified on-chain.$ETH
{future}(ETHUSDT)
Vitalik: Ethereum is Becoming More Than a Blockchain
Speaking at the 2026 Shanghai Blockchain International Week, Ethereum co-founder Vitalik Buterin shared a broader vision for where Ethereum is heading.
His main point: Ethereum is evolving from a blockchain that executes everything into a global system focused on computation, privacy and verification.
Here are the key ideas:
1/ ZK is becoming the foundation → Instead of every node doing the same computation, users or other systems can do the work and generate a proof. Ethereum only needs to verify that proof.
2/ Privacy becomes programmable → Vitalik said blockchain is moving beyond simply answering “Who can send what?” The next question is “Who can see what?” This means applications could control which information is visible without exposing everything publicly.
3/ Scaling through proofs → Complex computations can be split, processed in parallel and compressed into proofs before being verified on Ethereum. This could allow much more computation without putting all of it directly on-chain.
4/ Ethereum becomes a full pipeline → Vitalik described a future involving user devices, private transaction pools, multiple participants, block construction, L2s and finally Ethereum for verification. Ethereum does not need to perform every step itself.
5/ AI changes development → AI can help developers write, test and formally verify increasingly complex cryptographic systems. Vitalik believes this can make advanced Ethereum infrastructure both faster to build and more secure.
6/ Quantum resistance matters → Ethereum is also moving toward quantum-safe cryptography, with STARK-based systems playing an important role in the longer-term roadmap.
Ethereum's future may not simply be about making the L1 faster.
It is about building a trust layer where computation can happen anywhere, privacy can be programmed, and complex results can be mathematically proven and verified on-chain.$ETH
Speaking at the 2026 Shanghai Blockchain International Week, Ethereum co-founder Vitalik Buterin shared a broader vision for where Ethereum is heading.
His main point: Ethereum is evolving from a blockchain that executes everything into a global system focused on computation, privacy and verification.
Here are the key ideas:
1/ ZK is becoming the foundation → Instead of every node doing the same computation, users or other systems can do the work and generate a proof. Ethereum only needs to verify that proof.
2/ Privacy becomes programmable → Vitalik said blockchain is moving beyond simply answering “Who can send what?” The next question is “Who can see what?” This means applications could control which information is visible without exposing everything publicly.
3/ Scaling through proofs → Complex computations can be split, processed in parallel and compressed into proofs before being verified on Ethereum. This could allow much more computation without putting all of it directly on-chain.
4/ Ethereum becomes a full pipeline → Vitalik described a future involving user devices, private transaction pools, multiple participants, block construction, L2s and finally Ethereum for verification. Ethereum does not need to perform every step itself.
5/ AI changes development → AI can help developers write, test and formally verify increasingly complex cryptographic systems. Vitalik believes this can make advanced Ethereum infrastructure both faster to build and more secure.
6/ Quantum resistance matters → Ethereum is also moving toward quantum-safe cryptography, with STARK-based systems playing an important role in the longer-term roadmap.
Ethereum's future may not simply be about making the L1 faster.
It is about building a trust layer where computation can happen anywhere, privacy can be programmed, and complex results can be mathematically proven and verified on-chain.$ETH
2
220
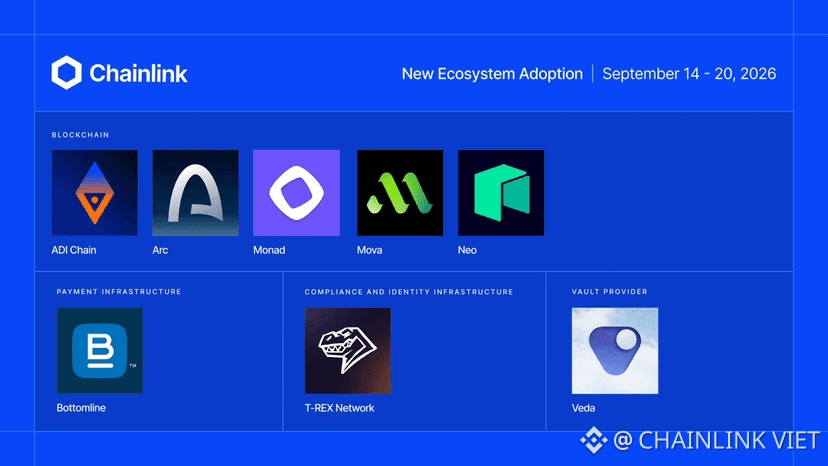
It won't be long before BlackRock announces their exclusive partnership with @chainlink.
Joseph Chalom already talked about the importance of identity, data and interoperability and how chainlink is playing an important role as middle layer.
He also mentioned the importance of staking $LINK to enable reliable data.
Tomorrow @chainlink will talk on a panel with both Joseph Chalom and @BlackRock
Can't wait to hear what they have to share!
It won't be long before BlackRock announces their exclusive partnership with @chainlink.
Joseph Chalom already talked about the importance of identity, data and interoperability and how chainlink is playing an important role as middle layer.
He also mentioned the importance of staking $LINK to enable reliable data.
Tomorrow @chainlink will talk on a panel with both Joseph Chalom and @BlackRock
Can't wait to hear what they have to share!
Joseph Chalom already talked about the importance of identity, data and interoperability and how chainlink is playing an important role as middle layer.
He also mentioned the importance of staking $LINK to enable reliable data.
Tomorrow @chainlink will talk on a panel with both Joseph Chalom and @BlackRock
Can't wait to hear what they have to share!
1
178
Robert kiyosaki said: Your BEST ASSETS are FREE
Unfortunately so are your WORST LIABILITIES
When I was in Sunday School I was taught:
“And the word became flesh…. and dwelt amongst us.”
In other words your words become YOU.
Biggest free liabilities:
“I can’t afford it.”
“l’ll try.”
“The rich are greedy.”
These are the words of poor people.
I am 4th -Generation Japanese-American. I don’t speak Japanese.
If I was going to live or do business in Japan I would learn Japanese.
In the world of the rich….the rich speak the language of money.
For example do you know the difference between these 3-words?
1: Earned
2: Portfolio
3: Passive
Simply said:
The poor work for earned income.
The poor go to school, get a job, and work for a paycheck. Earned income is the worst income, yet that is the type of income…our schools teach student to work hard and study for.
On top of that, Earned income is often the highest taxed income.
The middle class, go to school, get a job, and invest in a 401 k or IRA. They work hard for “portfolio income” often the second highest taxes.
The rich work for “passive income,” income that comes in without working, and is often taxed at zero.
That is why Warren Buffet, a billionaire says he pays less in taxes than his secretary.
Study, learn the words of money, because the best news is, words are FREE.
Lesson: Choose your words carefully….because words do become flesh.
Thank you for following my words.$BTC $ETH
Robert kiyosaki said: Your BEST ASSETS are FREE
Unfortunately so are your WORST LIABILITIES
When I was in Sunday School I was taught:
“And the word became flesh…. and dwelt amongst us.”
In other words your words become YOU.
Biggest free liabilities:
“I can’t afford it.”
“l’ll try.”
“The rich are greedy.”
These are the words of poor people.
I am 4th -Generation Japanese-American. I don’t speak Japanese.
If I was going to live or do business in Japan I would learn Japanese.
In the world of the rich….the rich speak the language of money.
For example do you know the difference between these 3-words?
1: Earned
2: Portfolio
3: Passive
Simply said:
The poor work for earned income.
The poor go to school, get a job, and work for a paycheck. Earned income is the worst income, yet that is the type of income…our schools teach student to work hard and study for.
On top of that, Earned income is often the highest taxed income.
The middle class, go to school, get a job, and invest in a 401 k or IRA. They work hard for “portfolio income” often the second highest taxes.
The rich work for “passive income,” income that comes in without working, and is often taxed at zero.
That is why Warren Buffet, a billionaire says he pays less in taxes than his secretary.
Study, learn the words of money, because the best news is, words are FREE.
Lesson: Choose your words carefully….because words do become flesh.
Thank you for following my words.$BTC $ETH
Unfortunately so are your WORST LIABILITIES
When I was in Sunday School I was taught:
“And the word became flesh…. and dwelt amongst us.”
In other words your words become YOU.
Biggest free liabilities:
“I can’t afford it.”
“l’ll try.”
“The rich are greedy.”
These are the words of poor people.
I am 4th -Generation Japanese-American. I don’t speak Japanese.
If I was going to live or do business in Japan I would learn Japanese.
In the world of the rich….the rich speak the language of money.
For example do you know the difference between these 3-words?
1: Earned
2: Portfolio
3: Passive
Simply said:
The poor work for earned income.
The poor go to school, get a job, and work for a paycheck. Earned income is the worst income, yet that is the type of income…our schools teach student to work hard and study for.
On top of that, Earned income is often the highest taxed income.
The middle class, go to school, get a job, and invest in a 401 k or IRA. They work hard for “portfolio income” often the second highest taxes.
The rich work for “passive income,” income that comes in without working, and is often taxed at zero.
That is why Warren Buffet, a billionaire says he pays less in taxes than his secretary.
Study, learn the words of money, because the best news is, words are FREE.
Lesson: Choose your words carefully….because words do become flesh.
Thank you for following my words.$BTC $ETH
62
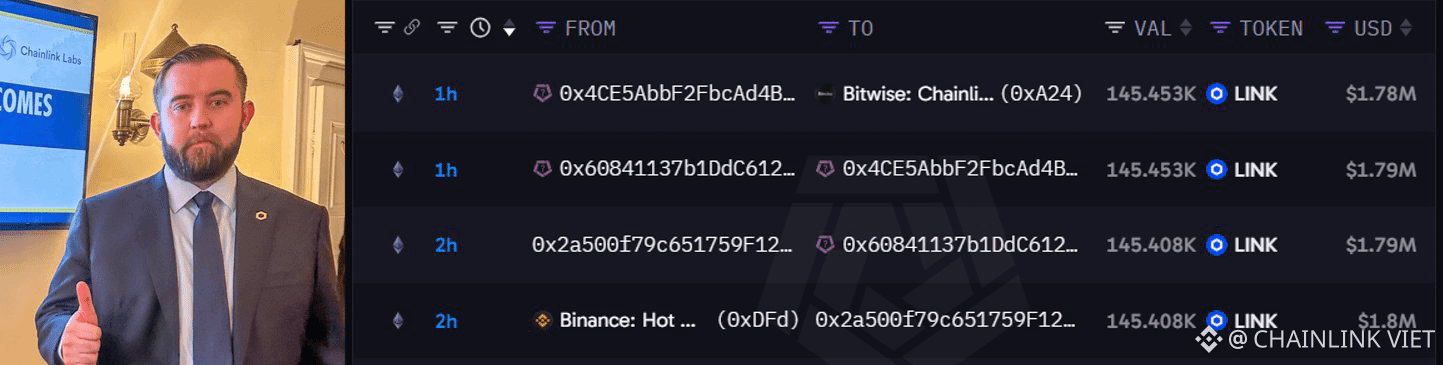
Bitwise just bought another $1.78m of $LINK from Binance 2h ago, bringing its total purchases today to $2.25m.
The institution now holds 4.18m+ $LINK worth nearly $52m.
Sergey Nazarov is probably very happy, while holders’ emotions are all over the place lol!
Bitwise just bought another $1.78m of $LINK from Binance 2h ago, bringing its total purchases today to $2.25m.
The institution now holds 4.18m+ $LINK worth nearly $52m.
Sergey Nazarov is probably very happy, while holders’ emotions are all over the place lol!
The institution now holds 4.18m+ $LINK worth nearly $52m.
Sergey Nazarov is probably very happy, while holders’ emotions are all over the place lol!
352
ALL CHAINLINK
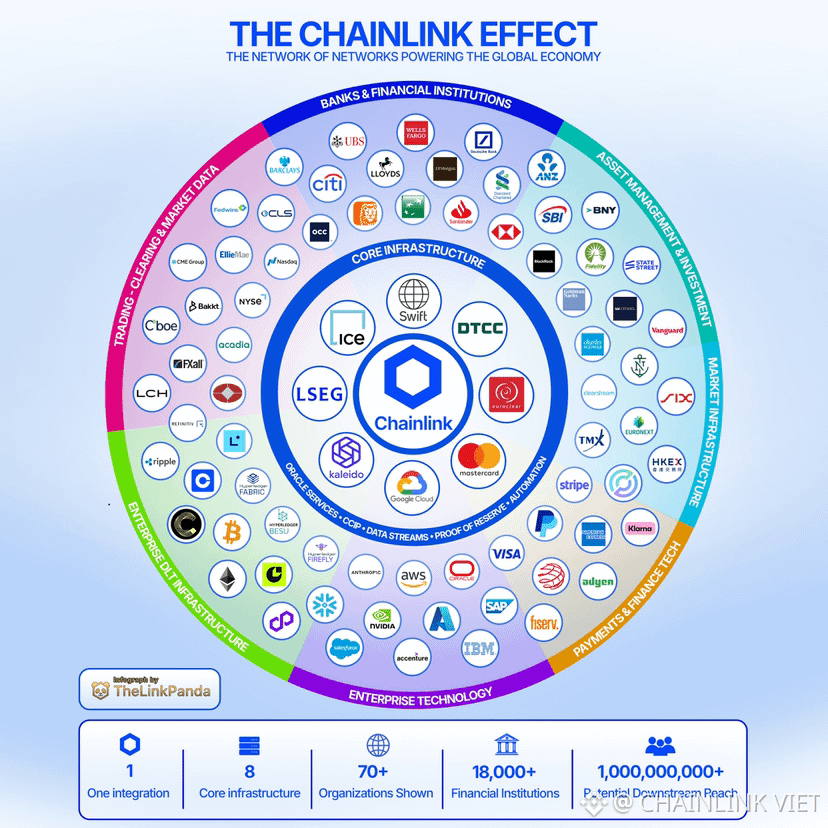
1. Stocks will all be tokenized
2. Bonds will all be tokenized
3. Funds will all be tokenized
4. Real estate will be tokenized
5. Private credit will be tokenized
6. Commodities will be tokenized
7. Treasuries will be tokenized
8. Art will be tokenized
9. Collectibles will be tokenized
10. Infrastructure will be tokenized
11. Insurance will be tokenized
12. Company shares will be issued onchain
13. Stablecoins will become the default rails for moving money
14. Every major financial institution will have an onchain product
15. Every major asset manager will have tokenized products
16. Financial markets will trade 24/7
17. Settlement will move from days to seconds
18. Ownership will become programmable
19. Collateral will become composable
20. Assets will move across borders without traditional financial plumbing
21. The distinction between crypto and finance will keep disappearing
22. Tokenized assets will become normal for the average investor
23. Billions of people will eventually interact with tokenized assets without even thinking about it
24. The majority of financial assets will eventually have an onchain representation
25. Tokenization will become so normal that we stop calling it tokenization
ALL CHAINLINK
1. Stocks will all be tokenized
2. Bonds will all be tokenized
3. Funds will all be tokenized
4. Real estate will be tokenized
5. Private credit will be tokenized
6. Commodities will be tokenized
7. Treasuries will be tokenized
8. Art will be tokenized
9. Collectibles will be tokenized
10. Infrastructure will be tokenized
11. Insurance will be tokenized
12. Company shares will be issued onchain
13. Stablecoins will become the default rails for moving money
14. Every major financial institution will have an onchain product
15. Every major asset manager will have tokenized products
16. Financial markets will trade 24/7
17. Settlement will move from days to seconds
18. Ownership will become programmable
19. Collateral will become composable
20. Assets will move across borders without traditional financial plumbing
21. The distinction between crypto and finance will keep disappearing
22. Tokenized assets will become normal for the average investor
23. Billions of people will eventually interact with tokenized assets without even thinking about it
24. The majority of financial assets will eventually have an onchain representation
25. Tokenization will become so normal that we stop calling it tokenization
1. Stocks will all be tokenized
2. Bonds will all be tokenized
3. Funds will all be tokenized
4. Real estate will be tokenized
5. Private credit will be tokenized
6. Commodities will be tokenized
7. Treasuries will be tokenized
8. Art will be tokenized
9. Collectibles will be tokenized
10. Infrastructure will be tokenized
11. Insurance will be tokenized
12. Company shares will be issued onchain
13. Stablecoins will become the default rails for moving money
14. Every major financial institution will have an onchain product
15. Every major asset manager will have tokenized products
16. Financial markets will trade 24/7
17. Settlement will move from days to seconds
18. Ownership will become programmable
19. Collateral will become composable
20. Assets will move across borders without traditional financial plumbing
21. The distinction between crypto and finance will keep disappearing
22. Tokenized assets will become normal for the average investor
23. Billions of people will eventually interact with tokenized assets without even thinking about it
24. The majority of financial assets will eventually have an onchain representation
25. Tokenization will become so normal that we stop calling it tokenization
37
The stock market, on prediction markets.
Predict the price of top stocks in 15-minute windows with our new category of markets, powered by @Chainlink and querying @Binance Futures’ index prices.
Only on @bnbchain.
Now live: $AMZNB , $NVDAB ,$METAB and more.
The stock market, on prediction markets.
Predict the price of top stocks in 15-minute windows with our new category of markets, powered by @Chainlink and querying @Binance Futures’ index prices.
Only on @bnbchain.
Now live: $AMZNB , $NVDAB ,$METAB and more.
Predict the price of top stocks in 15-minute windows with our new category of markets, powered by @Chainlink and querying @Binance Futures’ index prices.
Only on @bnbchain.
Now live: $AMZNB , $NVDAB ,$METAB and more.
40
Verified
🚨HUGE $HBAR PARTNERSHIP: THE HASHGRAPH GROUP JUST BECAME AN IBM SILVER PARTNER, WITH ITS HEDERA POWERED IDTRUST PLATFORM NOW LISTED ON IBM CLOUD.
That puts technology built on @hedera directly in front of IBM’s global enterprise customers (IBM one of the biggest companies in the world).
$HBAR is moving deeper into the enterprise world. 🔥
{spot}(HBARUSDT)
🚨HUGE $HBAR PARTNERSHIP: THE HASHGRAPH GROUP JUST BECAME AN IBM SILVER PARTNER, WITH ITS HEDERA POWERED IDTRUST PLATFORM NOW LISTED ON IBM CLOUD.
That puts technology built on @hedera directly in front of IBM’s global enterprise customers (IBM one of the biggest companies in the world).
$HBAR is moving deeper into the enterprise world. 🔥
That puts technology built on @hedera directly in front of IBM’s global enterprise customers (IBM one of the biggest companies in the world).
$HBAR is moving deeper into the enterprise world. 🔥
2
186
. @BlackRock has entered the TOKENIZATION building.
Let's try to understand what they are actually saying here.
1. Tokenization is a wrapper: Simply put, it's the digital representation of a real asset. To translate a real asset into digital form, you need data. Lots of data.
This data can then be programmed, automated, used, traded, settled across many chains.
2. Adoption is growing. (still early)
The biggest piece of the puzzle today to achieve that goal is INTEROPERABILITY.
Simply put: the ability to work between chains, as chains are designed to be digital islands.
3. The risks, and the benefits: The benefits are simple.
Automation, 24/7 markets, instant transactions, transparency and access.
The risks: Traditional risks stay the same, but at the moment, regulatory inefficiency is slowing down progress, and infrastructure as of today is still lacking on many chains, and some interoperability layers still have major issues with security, like @LayerZero_Core and @wormhole .
There is however one protocol that effectively has the best track record on both the data side and security side as it has never had a faillure before. That is of course $LINK
. @BlackRock has entered the TOKENIZATION building.
Let's try to understand what they are actually saying here.
1. Tokenization is a wrapper: Simply put, it's the digital representation of a real asset. To translate a real asset into digital form, you need data. Lots of data.
This data can then be programmed, automated, used, traded, settled across many chains.
2. Adoption is growing. (still early)
The biggest piece of the puzzle today to achieve that goal is INTEROPERABILITY.
Simply put: the ability to work between chains, as chains are designed to be digital islands.
3. The risks, and the benefits: The benefits are simple.
Automation, 24/7 markets, instant transactions, transparency and access.
The risks: Traditional risks stay the same, but at the moment, regulatory inefficiency is slowing down progress, and infrastructure as of today is still lacking on many chains, and some interoperability layers still have major issues with security, like @LayerZero_Core and @wormhole .
There is however one protocol that effectively has the best track record on both the data side and security side as it has never had a faillure before. That is of course $LINK
Let's try to understand what they are actually saying here.
1. Tokenization is a wrapper: Simply put, it's the digital representation of a real asset. To translate a real asset into digital form, you need data. Lots of data.
This data can then be programmed, automated, used, traded, settled across many chains.
2. Adoption is growing. (still early)
The biggest piece of the puzzle today to achieve that goal is INTEROPERABILITY.
Simply put: the ability to work between chains, as chains are designed to be digital islands.
3. The risks, and the benefits: The benefits are simple.
Automation, 24/7 markets, instant transactions, transparency and access.
The risks: Traditional risks stay the same, but at the moment, regulatory inefficiency is slowing down progress, and infrastructure as of today is still lacking on many chains, and some interoperability layers still have major issues with security, like @LayerZero_Core and @wormhole .
There is however one protocol that effectively has the best track record on both the data side and security side as it has never had a faillure before. That is of course $LINK
5
1
193
A big moment for $PYTH
@Nasdaq has spent decades building some of the most important market infrastructure in the world. Now Nasdaq Basic is being distributed through the Pyth Data Marketplace.
This is the direction we've believed all market data was heading from day one.
A big moment for $PYTH
@Nasdaq has spent decades building some of the most important market infrastructure in the world. Now Nasdaq Basic is being distributed through the Pyth Data Marketplace.
This is the direction we've believed all market data was heading from day one.
@Nasdaq has spent decades building some of the most important market infrastructure in the world. Now Nasdaq Basic is being distributed through the Pyth Data Marketplace.
This is the direction we've believed all market data was heading from day one.
2
299
In 1981, seven engineers in India started a software company with about 250u borrowed from one founder's wife.
Today that company runs the software under a big chunk of the world's banks.
Yesterday it picked Chainlink.
Most people in crypto have no idea who Infosys is. So let's start there.
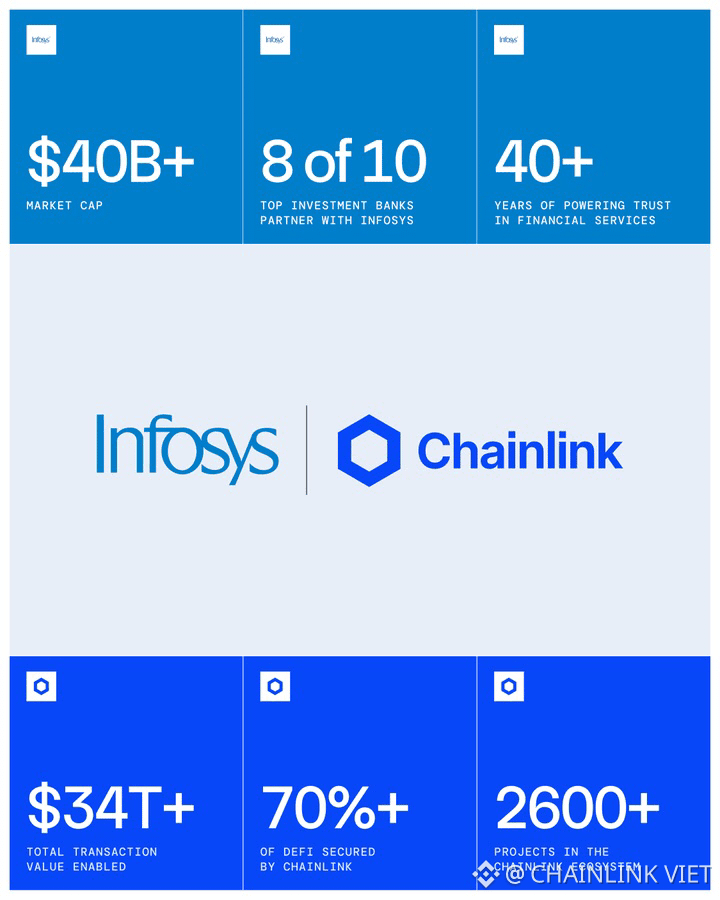
On paper, it's an Indian IT company. 20B in revenue last year. Around 330,000 employees. Listed in New York.
Almost 30% of that revenue comes from one industry: Finance. That's over 5B a year from banks and insurers.
8 of the 10 largest investment banks work with them.
But the part that matters most is a product called Finacle. Finacle is core banking software. It holds your balance, moves your payments, adds your interest every month.
Over 1,000 banks in 100+ countries run on it. DBS. ICICI. Emirates NBD. Standard Bank. India Post runs hundreds of millions of accounts on it.
So when a bank wants to change how its money moves, it doesn't call a crypto startup. It calls the people who built its system.
A lot of the time, that's Infosys. That's who just standardized on @chainlink.
Banks were never stuck on crypto because of the tech. They were stuck on the paperwork. New vendor, new security review, new contracts, two years of meetings. Now the vendor they already trust walks Chainlink in the door.
The word Infosys used was "standardizing." Not "exploring."
So when a bank asks Infosys how to launch tokenized deposits or check what's backing a stablecoin, the answer comes with Chainlink already in it. Nobody gets fired for picking what their vendor recommends.
And it also finishes a pattern.
Swift. Then Bottomline earlier this month, a payments company working with 600+ banks. Now Infosys.
Chainlink isn't chasing banks one by one. It's getting into the pipes banks already use. How they message. How they pay. Now, possibly, the system that holds the accounts.
45 years ago, Infosys started with 250u and a bet that banks would need software.
Now it's betting they'll need onchain rails too. $SOL
They were right the first time.
In 1981, seven engineers in India started a software company with about 250u borrowed from one founder's wife.
Today that company runs the software under a big chunk of the world's banks.
Yesterday it picked Chainlink.
Most people in crypto have no idea who Infosys is. So let's start there.
On paper, it's an Indian IT company. 20B in revenue last year. Around 330,000 employees. Listed in New York.
Almost 30% of that revenue comes from one industry: Finance. That's over 5B a year from banks and insurers.
8 of the 10 largest investment banks work with them.
But the part that matters most is a product called Finacle. Finacle is core banking software. It holds your balance, moves your payments, adds your interest every month.
Over 1,000 banks in 100+ countries run on it. DBS. ICICI. Emirates NBD. Standard Bank. India Post runs hundreds of millions of accounts on it.
So when a bank wants to change how its money moves, it doesn't call a crypto startup. It calls the people who built its system.
A lot of the time, that's Infosys. That's who just standardized on @chainlink.
Banks were never stuck on crypto because of the tech. They were stuck on the paperwork. New vendor, new security review, new contracts, two years of meetings. Now the vendor they already trust walks Chainlink in the door.
The word Infosys used was "standardizing." Not "exploring."
So when a bank asks Infosys how to launch tokenized deposits or check what's backing a stablecoin, the answer comes with Chainlink already in it. Nobody gets fired for picking what their vendor recommends.
And it also finishes a pattern.
Swift. Then Bottomline earlier this month, a payments company working with 600+ banks. Now Infosys.
Chainlink isn't chasing banks one by one. It's getting into the pipes banks already use. How they message. How they pay. Now, possibly, the system that holds the accounts.
45 years ago, Infosys started with 250u and a bet that banks would need software.
Now it's betting they'll need onchain rails too. $SOL
They were right the first time.
Today that company runs the software under a big chunk of the world's banks.
Yesterday it picked Chainlink.
Most people in crypto have no idea who Infosys is. So let's start there.
On paper, it's an Indian IT company. 20B in revenue last year. Around 330,000 employees. Listed in New York.
Almost 30% of that revenue comes from one industry: Finance. That's over 5B a year from banks and insurers.
8 of the 10 largest investment banks work with them.
But the part that matters most is a product called Finacle. Finacle is core banking software. It holds your balance, moves your payments, adds your interest every month.
Over 1,000 banks in 100+ countries run on it. DBS. ICICI. Emirates NBD. Standard Bank. India Post runs hundreds of millions of accounts on it.
So when a bank wants to change how its money moves, it doesn't call a crypto startup. It calls the people who built its system.
A lot of the time, that's Infosys. That's who just standardized on @chainlink.
Banks were never stuck on crypto because of the tech. They were stuck on the paperwork. New vendor, new security review, new contracts, two years of meetings. Now the vendor they already trust walks Chainlink in the door.
The word Infosys used was "standardizing." Not "exploring."
So when a bank asks Infosys how to launch tokenized deposits or check what's backing a stablecoin, the answer comes with Chainlink already in it. Nobody gets fired for picking what their vendor recommends.
And it also finishes a pattern.
Swift. Then Bottomline earlier this month, a payments company working with 600+ banks. Now Infosys.
Chainlink isn't chasing banks one by one. It's getting into the pipes banks already use. How they message. How they pay. Now, possibly, the system that holds the accounts.
45 years ago, Infosys started with 250u and a bet that banks would need software.
Now it's betting they'll need onchain rails too. $SOL
They were right the first time.
2
150
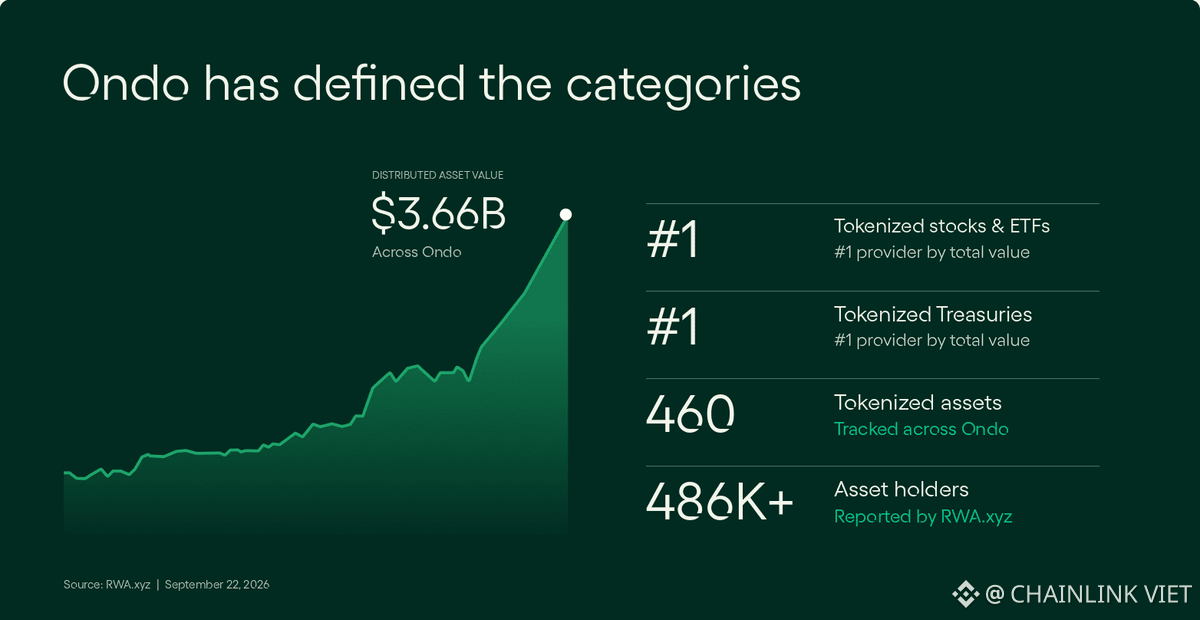
NEW MILESTONE: $ONDO is now the #1 provider of tokenized Treasuries by total value.
Ondo now ranks 1 in both tokenized Treasuries and tokenized stocks & ETFs, per @RWA_xyz:
→ 1 in tokenized Treasuries
→ 1 in tokenized stocks & ETFs
→ 3.66B+ in distributed asset value
$SOL $PYTH
NEW MILESTONE: $ONDO is now the #1 provider of tokenized Treasuries by total value.
Ondo now ranks 1 in both tokenized Treasuries and tokenized stocks & ETFs, per @RWA_xyz:
→ 1 in tokenized Treasuries
→ 1 in tokenized stocks & ETFs
→ 3.66B+ in distributed asset value
$SOL $PYTH
Ondo now ranks 1 in both tokenized Treasuries and tokenized stocks & ETFs, per @RWA_xyz:
→ 1 in tokenized Treasuries
→ 1 in tokenized stocks & ETFs
→ 3.66B+ in distributed asset value
$SOL $PYTH
358
TL;DR
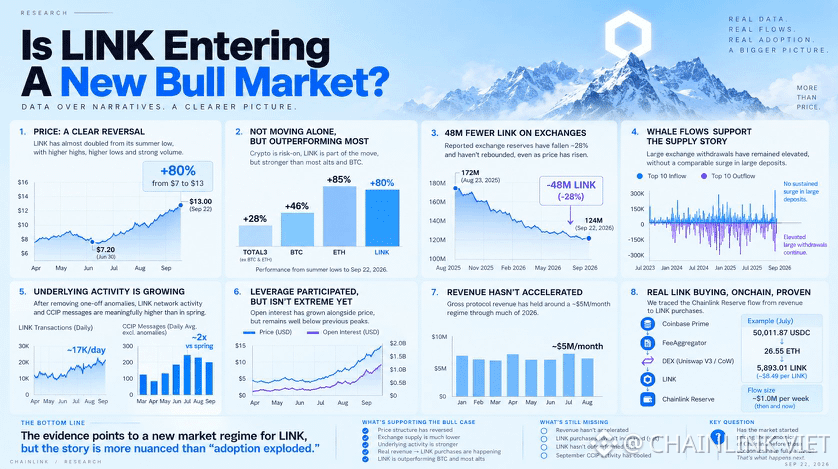
$LINK has moved from ~$7 to ~$13, but I wanted to know whether anything underneath the price actually changed.
So I went through the data and tried to break the bull thesis.
The key findings:
• Reported exchange reserves have fallen by roughly 48M LINK (-28%) since Aug 2025 and stayed low during the rally.
• Large exchange withdrawals remain elevated without a comparable sustained surge in large deposits.
• LINK and underlying CCIP activity have recovered even after removing major one-off anomalies.
• LINK has strongly outperformed $BTC and the broader alt market from the summer lows, although not $ETH.
• Leverage increased with price, but isn't near previous extremes.
• Most importantly, we traced the Reserve mechanism onchain and confirmed real $USDT → $LINK purchases, including a $50K swap around the summer bottom. The broader flow was roughly $1M/week then and remains around that level today.
But there's a catch.
Revenue hasn't accelerated. Neither has the dollar amount being converted into $LINK.
So this isn't a story of Chainlink economics suddenly exploding.
The evidence instead points to a change in market structure: less LINK on exchanges, stronger underlying activity, persistent protocol-linked buying and a broader market that finally turned risk-on.
The next confirmation I'm looking for is simple:
Does adoption now translate into accelerating revenue and larger LINK purchases?
That's where this gets really interesting.
Full investigation below 👇
TL;DR
$LINK has moved from ~$7 to ~$13, but I wanted to know whether anything underneath the price actually changed.
So I went through the data and tried to break the bull thesis.
The key findings:
• Reported exchange reserves have fallen by roughly 48M LINK (-28%) since Aug 2025 and stayed low during the rally.
• Large exchange withdrawals remain elevated without a comparable sustained surge in large deposits.
• LINK and underlying CCIP activity have recovered even after removing major one-off anomalies.
• LINK has strongly outperformed $BTC and the broader alt market from the summer lows, although not $ETH.
• Leverage increased with price, but isn't near previous extremes.
• Most importantly, we traced the Reserve mechanism onchain and confirmed real $USDT → $LINK purchases, including a $50K swap around the summer bottom. The broader flow was roughly $1M/week then and remains around that level today.
But there's a catch.
Revenue hasn't accelerated. Neither has the dollar amount being converted into $LINK .
So this isn't a story of Chainlink economics suddenly exploding.
The evidence instead points to a change in market structure: less LINK on exchanges, stronger underlying activity, persistent protocol-linked buying and a broader market that finally turned risk-on.
The next confirmation I'm looking for is simple:
Does adoption now translate into accelerating revenue and larger LINK purchases?
That's where this gets really interesting.
Full investigation below 👇
$LINK has moved from ~$7 to ~$13, but I wanted to know whether anything underneath the price actually changed.
So I went through the data and tried to break the bull thesis.
The key findings:
• Reported exchange reserves have fallen by roughly 48M LINK (-28%) since Aug 2025 and stayed low during the rally.
• Large exchange withdrawals remain elevated without a comparable sustained surge in large deposits.
• LINK and underlying CCIP activity have recovered even after removing major one-off anomalies.
• LINK has strongly outperformed $BTC and the broader alt market from the summer lows, although not $ETH.
• Leverage increased with price, but isn't near previous extremes.
• Most importantly, we traced the Reserve mechanism onchain and confirmed real $USDT → $LINK purchases, including a $50K swap around the summer bottom. The broader flow was roughly $1M/week then and remains around that level today.
But there's a catch.
Revenue hasn't accelerated. Neither has the dollar amount being converted into $LINK .
So this isn't a story of Chainlink economics suddenly exploding.
The evidence instead points to a change in market structure: less LINK on exchanges, stronger underlying activity, persistent protocol-linked buying and a broader market that finally turned risk-on.
The next confirmation I'm looking for is simple:
Does adoption now translate into accelerating revenue and larger LINK purchases?
That's where this gets really interesting.
Full investigation below 👇
42
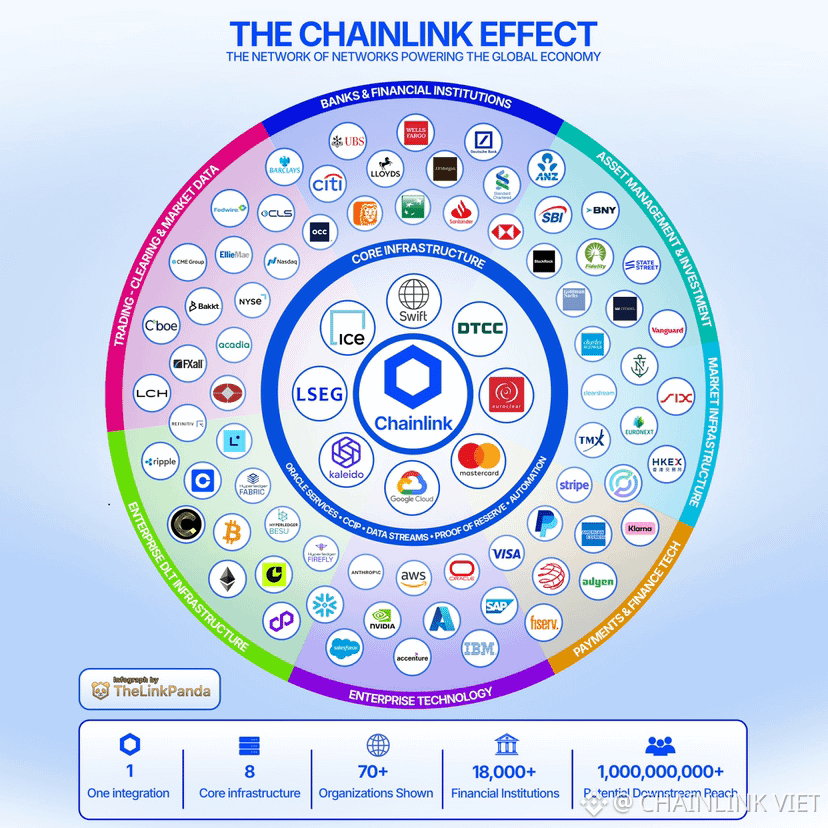
$LINK going 10x is easy. Chainlink is in deep conversations with the largest settlement layers. Institutions are adding LINK etfs. Big firms are publishing reports for clients. 10x is just the start.
When tokenization goes online, trillions of assets in dollars will secured through chainlink $BTC and $ETH will be contested
$LINK going 10x is easy. Chainlink is in deep conversations with the largest settlement layers. Institutions are adding LINK etfs. Big firms are publishing reports for clients. 10x is just the start.
When tokenization goes online, trillions of assets in dollars will secured through chainlink $BTC and $ETH will be contested
When tokenization goes online, trillions of assets in dollars will secured through chainlink $BTC and $ETH will be contested
1
62
Verified
NEWS $NEAR: Every near.com launch removes one more thing you used to do somewhere else.
Today, we're partnering with @Ondo to bring tokenized US stocks and ETFs into near.com, confidentially, with one account 🧵
NEWS $NEAR: Every near.com launch removes one more thing you used to do somewhere else.
Today, we're partnering with @Ondo to bring tokenized US stocks and ETFs into near.com, confidentially, with one account 🧵
Today, we're partnering with @Ondo to bring tokenized US stocks and ETFs into near.com, confidentially, with one account 🧵
5
1.1k
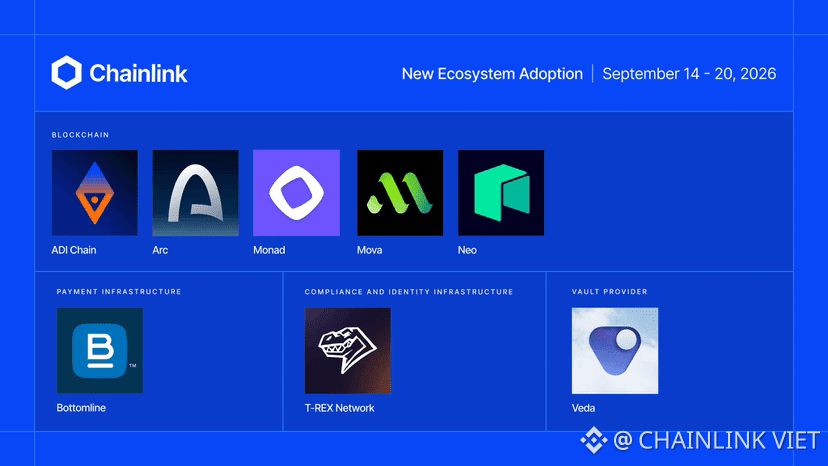
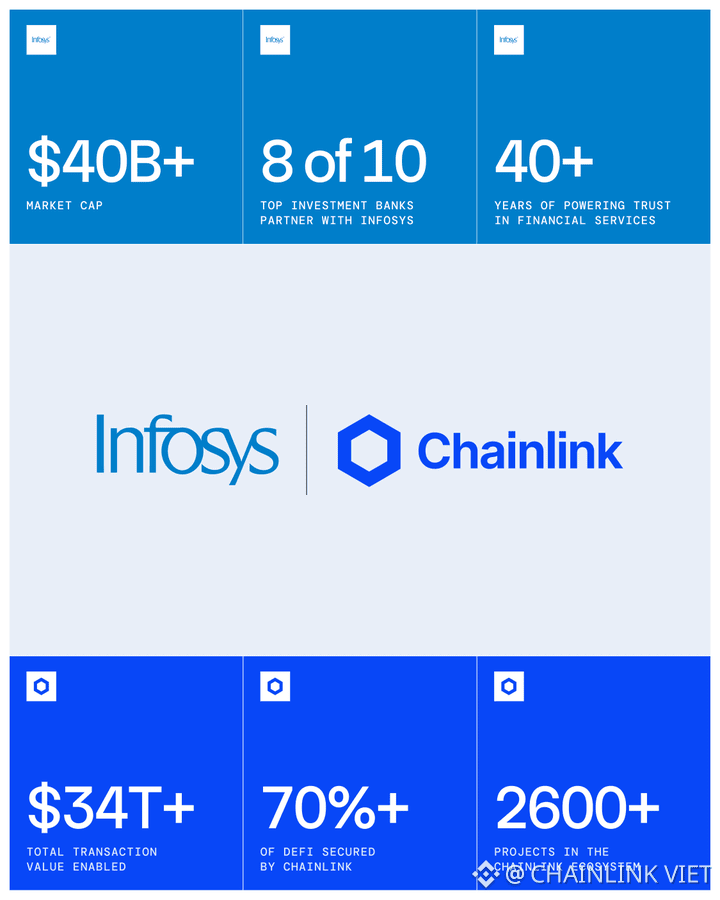
NEW: @Infosys (NYSE: INFY), the $40B+ global IT leader, enters a strategic partnership with Chainlink to accelerate institutional onchain finance.
Infosys supports critical banking and payments infrastructure for more than 1.7 billion customer accounts worldwide and is now standardizing the adoption of the Chainlink platform:
• Cross-Chain Interoperability Protocol (CCIP)
• Chainlink Runtime Environment (CRE)
• Automated Compliance Engine (ACE)
• Proof of Reserve
• Data Streams
• Data Feeds
Together, Infosys and Chainlink are creating a path to connect the world’s largest financial institutions to onchain markets.
Infosys 🤝 Chainlink
NEW: @Infosys (NYSE: INFY), the $40B+ global IT leader, enters a strategic partnership with Chainlink to accelerate institutional onchain finance.
Infosys supports critical banking and payments infrastructure for more than 1.7 billion customer accounts worldwide and is now standardizing the adoption of the Chainlink platform:
• Cross-Chain Interoperability Protocol (CCIP)
• Chainlink Runtime Environment (CRE)
• Automated Compliance Engine (ACE)
• Proof of Reserve
• Data Streams
• Data Feeds
Together, Infosys and Chainlink are creating a path to connect the world’s largest financial institutions to onchain markets.
Infosys 🤝 Chainlink
Infosys supports critical banking and payments infrastructure for more than 1.7 billion customer accounts worldwide and is now standardizing the adoption of the Chainlink platform:
• Cross-Chain Interoperability Protocol (CCIP)
• Chainlink Runtime Environment (CRE)
• Automated Compliance Engine (ACE)
• Proof of Reserve
• Data Streams
• Data Feeds
Together, Infosys and Chainlink are creating a path to connect the world’s largest financial institutions to onchain markets.
Infosys 🤝 Chainlink
7
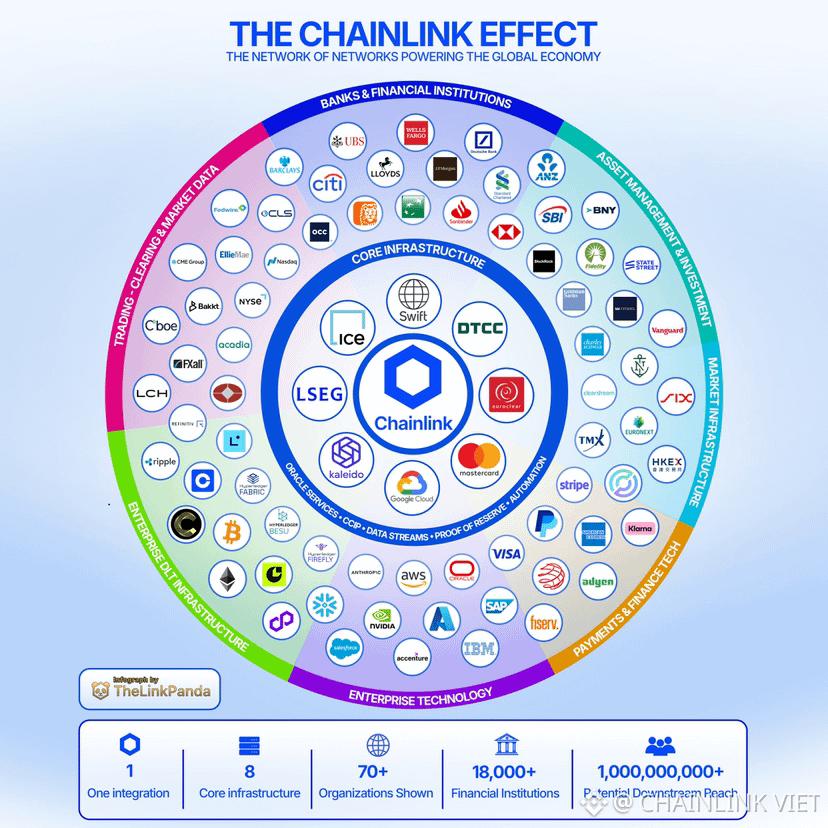
IF the move is stocks going ONCHAIN...
Then you can ONLY assume ONCHAIN will be worth considerably more.
IF you consider ONCHAIN STOCKS need data and orchestration, then $LINK, the token that facilitates the @chainlink network, will be worth considerably more.
That's all you have to take into account.
IF the move is stocks going ONCHAIN...
Then you can ONLY assume ONCHAIN will be worth considerably more.
IF you consider ONCHAIN STOCKS need data and orchestration, then $LINK, the token that facilitates the @chainlink network, will be worth considerably more.
That's all you have to take into account.
Then you can ONLY assume ONCHAIN will be worth considerably more.
IF you consider ONCHAIN STOCKS need data and orchestration, then $LINK, the token that facilitates the @chainlink network, will be worth considerably more.
That's all you have to take into account.
1
1.1k
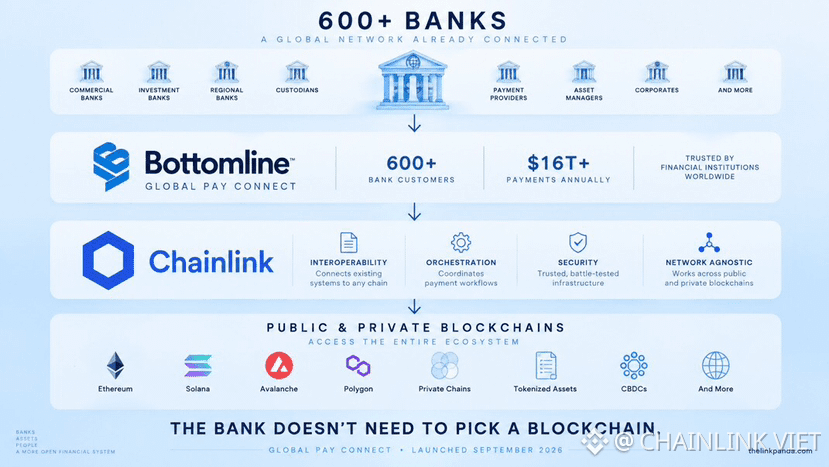
$LINK There's an important difference between a partnership and a product.
Bottomline didn't just announce a partnership with Chainlink.
It has now launched Global Pay Connect, a payment messaging ecosystem for financial institutions that connects existing banking infrastructure with blockchain networks.
Bottomline already connects 600+ banks and processes $16T+ in payments annually.
The interesting part?
Banks don't need to abandon the infrastructure they already use.
They can continue using familiar payment messaging such as ISO 20022, while Chainlink provides the network-agnostic connectivity and orchestration needed to interact with onchain rails.
Legacy banking → Chainlink → public & private blockchains
This is what institutional blockchain adoption was always going to look like.
Not thousands of banks rebuilding their infrastructure around individual blockchains. But infrastructure that connects the systems they already use to any blockchain they need to access. That's the part of the Chainlink thesis I think the market still massively underestimates.
The blockchain may be where settlement happens.
But somebody still has to connect everything before settlement can happen.
$LINK There's an important difference between a partnership and a product.
Bottomline didn't just announce a partnership with Chainlink.
It has now launched Global Pay Connect, a payment messaging ecosystem for financial institutions that connects existing banking infrastructure with blockchain networks.
Bottomline already connects 600+ banks and processes $16T+ in payments annually.
The interesting part?
Banks don't need to abandon the infrastructure they already use.
They can continue using familiar payment messaging such as ISO 20022, while Chainlink provides the network-agnostic connectivity and orchestration needed to interact with onchain rails.
Legacy banking → Chainlink → public & private blockchains
This is what institutional blockchain adoption was always going to look like.
Not thousands of banks rebuilding their infrastructure around individual blockchains. But infrastructure that connects the systems they already use to any blockchain they need to access. That's the part of the Chainlink thesis I think the market still massively underestimates.
The blockchain may be where settlement happens.
But somebody still has to connect everything before settlement can happen.
Bottomline didn't just announce a partnership with Chainlink.
It has now launched Global Pay Connect, a payment messaging ecosystem for financial institutions that connects existing banking infrastructure with blockchain networks.
Bottomline already connects 600+ banks and processes $16T+ in payments annually.
The interesting part?
Banks don't need to abandon the infrastructure they already use.
They can continue using familiar payment messaging such as ISO 20022, while Chainlink provides the network-agnostic connectivity and orchestration needed to interact with onchain rails.
Legacy banking → Chainlink → public & private blockchains
This is what institutional blockchain adoption was always going to look like.
Not thousands of banks rebuilding their infrastructure around individual blockchains. But infrastructure that connects the systems they already use to any blockchain they need to access. That's the part of the Chainlink thesis I think the market still massively underestimates.
The blockchain may be where settlement happens.
But somebody still has to connect everything before settlement can happen.
140
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number