$KMNO Price: $0.03408 | 24h: -0.64% | S: $0.03376 | R: $0.03507
🐂 TL;DR: $KMNO deserves credit for making leadership earn more of its upside. The CEO's November 2 letter ties most of his allocation to sustained valuation milestones. I would still keep the broader insider allocation in the supply model.
Separate two commitments:
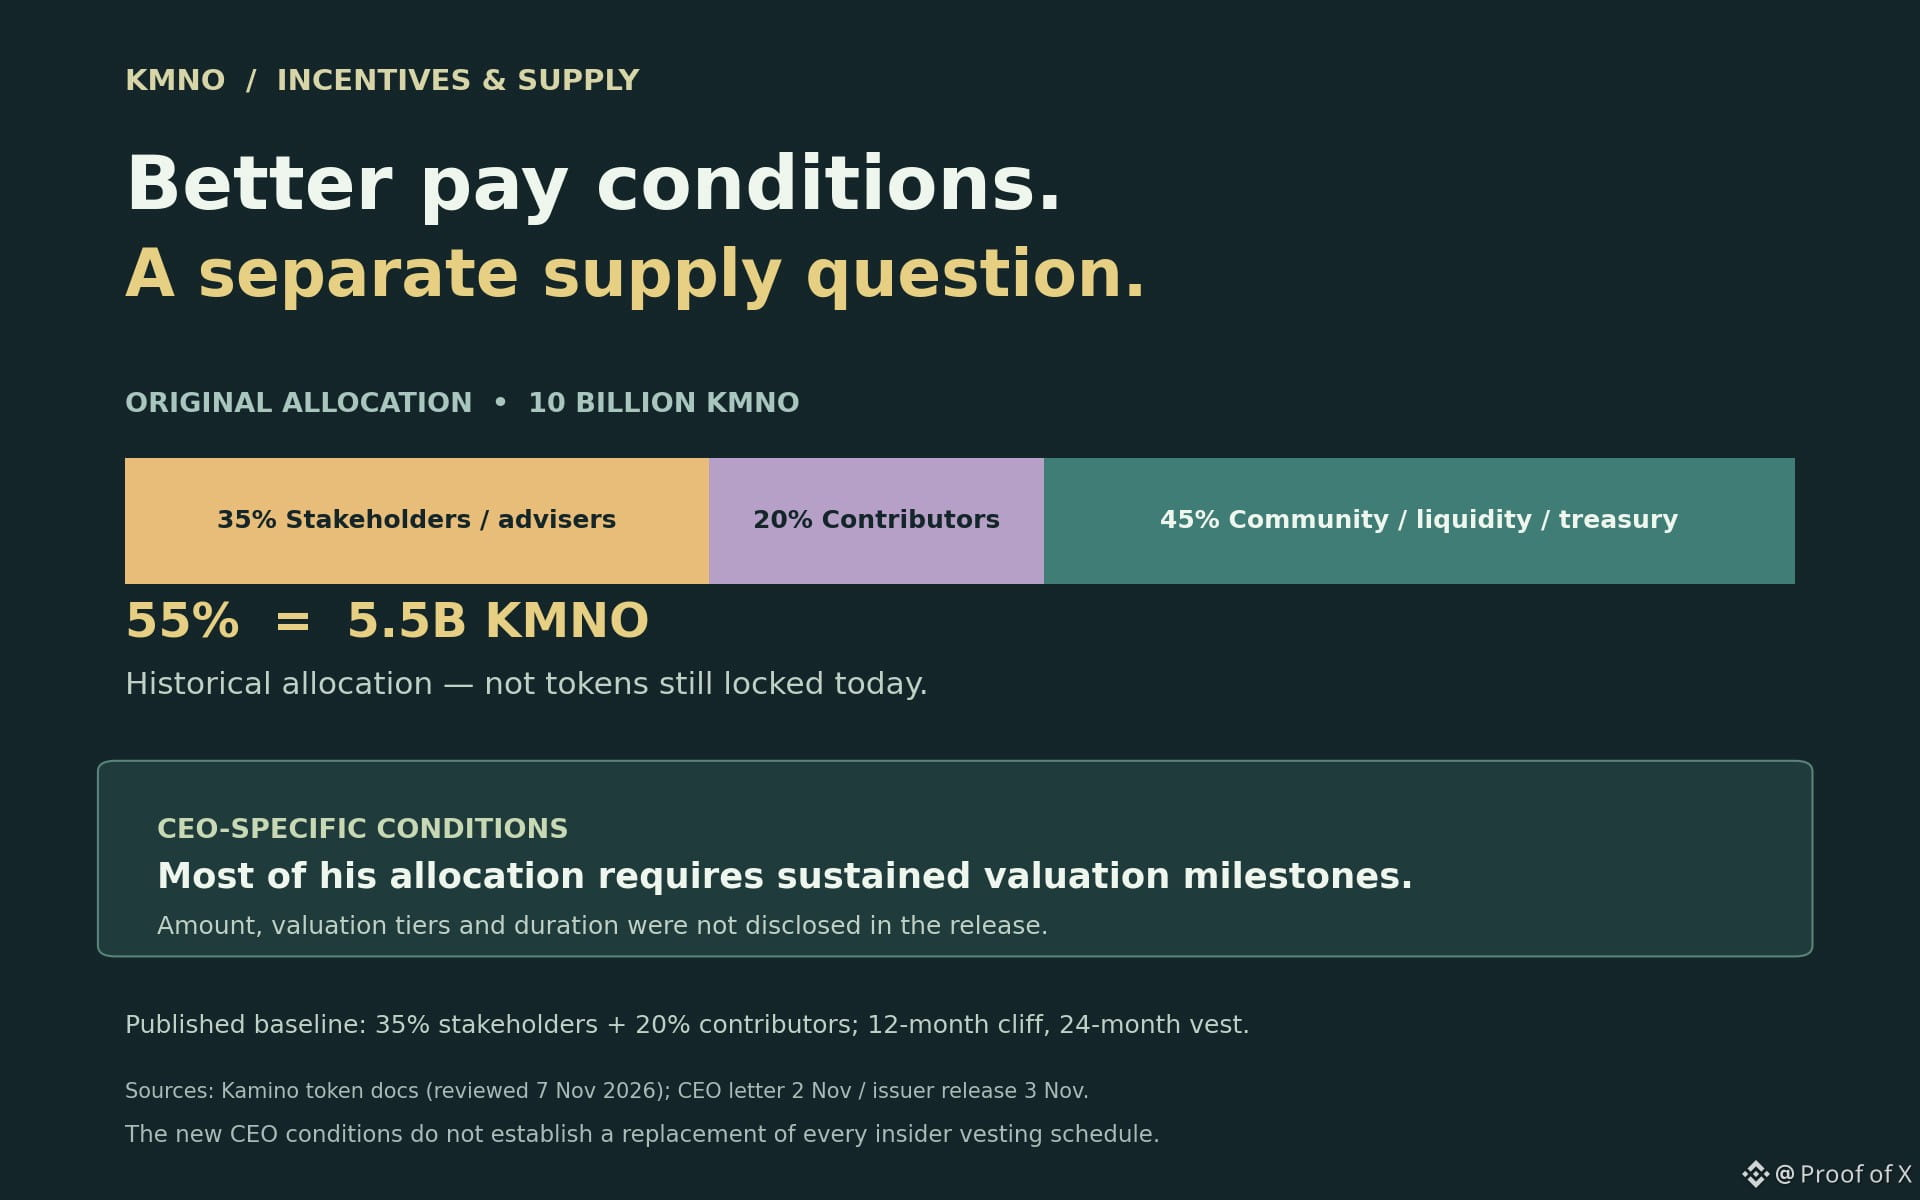
• Published tokenomics: stakeholders/advisors 35%, core contributors 20%—55% of the original 10B supply. Both categories have a 12-month lockup followed by 24-month linear vesting.
• CEO's new conditions: most of his allocation depends on valuation milestones. The release does not disclose its size, thresholds or required holding periods, or replace every insider's schedule.
The business earns a market-specific share of borrower interest; lenders receive a separate share. Kamino says all onchain/offchain revenue and IP accrue to its Foundation, which committed at least $20M over 24 months to expansion. That is a growth commitment, not holder distributions: the release gives KMNO no claim on Foundation revenue or equity.
The economic comparison is Aave: its documented revenue-funded token purchases go to a DAO reserve. Lending growth alone does not establish the same token demand mechanism at Kamino.
My take: This is constructive incentive design, with reinvestment capacity behind the expansion plan. Treat KMNO as exposure to execution and future capital allocation—not an earnings coupon or an end to vesting. The decisive disclosure would be the actual milestone schedule and how much token supply it covers.
Sources: Kamino, One Kamino. One KMNO., November 2; issuer release via Business Wire, November 3, 2026. Kamino KMNO and Borrow Fees docs; Aave AAVE Token docs, undated, reviewed November 7.
As of: 2026-11-07 10:56 UTC | Binance spot KMNOUSDT
S/R basis: Classic S1/R1 from the completed November 6 UTC daily candle.
NFA. DYOR.
🐂 TL;DR: $KMNO deserves credit for making leadership earn more of its upside. The CEO's November 2 letter ties most of his allocation to sustained valuation milestones. I would still keep the broader insider allocation in the supply model.
Separate two commitments:
• Published tokenomics: stakeholders/advisors 35%, core contributors 20%—55% of the original 10B supply. Both categories have a 12-month lockup followed by 24-month linear vesting.
• CEO's new conditions: most of his allocation depends on valuation milestones. The release does not disclose its size, thresholds or required holding periods, or replace every insider's schedule.
The business earns a market-specific share of borrower interest; lenders receive a separate share. Kamino says all onchain/offchain revenue and IP accrue to its Foundation, which committed at least $20M over 24 months to expansion. That is a growth commitment, not holder distributions: the release gives KMNO no claim on Foundation revenue or equity.
The economic comparison is Aave: its documented revenue-funded token purchases go to a DAO reserve. Lending growth alone does not establish the same token demand mechanism at Kamino.
My take: This is constructive incentive design, with reinvestment capacity behind the expansion plan. Treat KMNO as exposure to execution and future capital allocation—not an earnings coupon or an end to vesting. The decisive disclosure would be the actual milestone schedule and how much token supply it covers.
Sources: Kamino, One Kamino. One KMNO., November 2; issuer release via Business Wire, November 3, 2026. Kamino KMNO and Borrow Fees docs; Aave AAVE Token docs, undated, reviewed November 7.
As of: 2026-11-07 10:56 UTC | Binance spot KMNOUSDT
S/R basis: Classic S1/R1 from the completed November 6 UTC daily candle.
NFA. DYOR.