

Well, yesterday we had a hot CPI report, and today they decided to pile on with PPI and retail sales. The results were almost too good for the economy and too bad for the Fed.
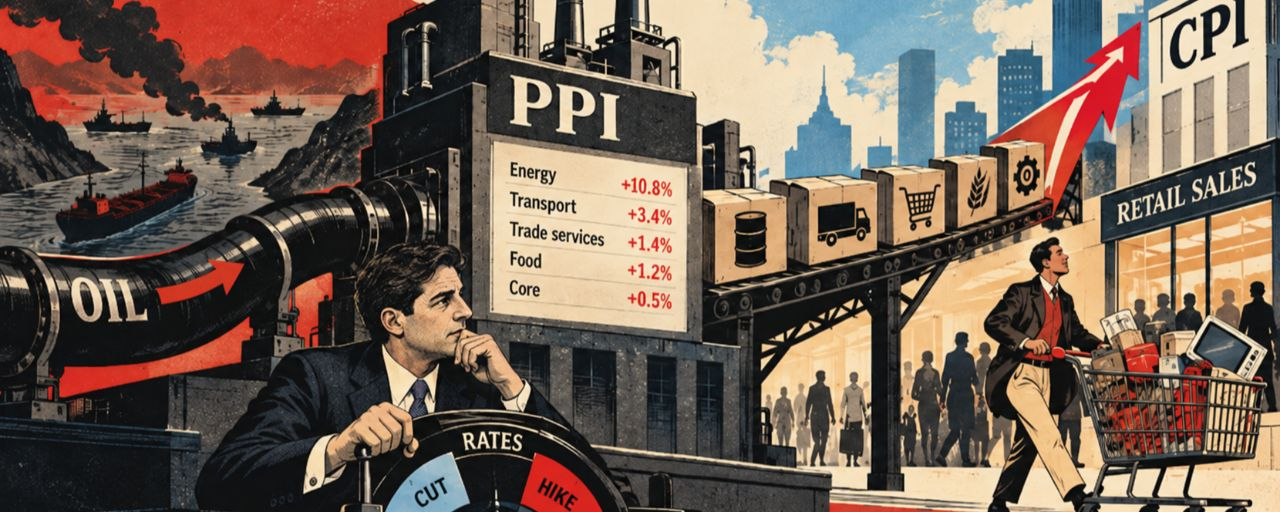
PPI (producer-side inflation) jumped by 1.3% in a single month. Expectations were around +0.5–0.6%. The annual rate rose from 5.6% to 6.3%—its fastest pace since late 2022.
The main reason is familiar to all of us — energy prices, driven by the blockade of the Strait of Hormuz and the war with Iran. Or, according to Trump, Zelenskyy and the Ukrainians are to blame for everything)))
Producers’ energy costs surged 10.8% in a single month, while gasoline prices rose 20.3%. In other words, expensive oil from the Middle East is already feeding through the economy very clearly.
But even without oil, the picture isn’t all that pleasant. Core PPI, excluding food, energy, and trade margins, rose 0.5% m/m, compared with +0.3% in August. Transportation services were up 3.4%, trade margins 1.4%, and food 1.2%. So it’s not just fuel getting more expensive anymore.
And this is exactly what the Fed is watching right now. You could think of PPI as inflation at the input stage: producers are paying more today, and then they try to pass some of those costs on to buyers.
And now for the second part — the American consumer isn’t giving up at all.
Retail sales rose 0.8% m/m in September, versus expectations of +0.3%. August was even revised slightly higher, from +1.2% to +1.3%.
That leaves the Fed with a rather awkward combination: CPI is hot, PPI is even hotter, and consumers keep spending.
So the argument that “the economy is already weak, so it’s better not to touch interest rates” has become a little less convincing today.
But there’s a catch: the market isn’t rushing to price in a rate hike on October 28 just yet. After cautious comments from Fed officials, the probability of an October move is holding at only around 29%. In other words, the data are shouting “tighter,” while the Fed itself is still asking everyone not to rush.
For me, the main picture over the past two days is simple:
Iran = expensive oil = CPI/PPI up = strong consumer = the Fed has fewer and fewer reasons to rush into easing.
And for expensive AI and tech companies, that means one thing — the cost of money is still an issue.
Mykyta Huppal | ProInvestments