

#cryptoadoption
cryptoadoption
13.5M views
16,555 Discussing
Bank of Montreal (BMO), Canada's third-largest bank, has acquired around $150 million in spot Bitcoin ETFs! 🔥📈 Of this investment, $139 million has been allocated to BlackRock's iShares Bitcoin ETF, while the remaining $11 million is spread across three other Bitcoin funds.This is a huge step forward for traditional financial institutions embracing the Bitcoin revolution! 🏦💎What do you think about this major institutional move? Let’s hear your thoughts! 👇
Hot
Latest
People spent $1.2 billion in stablecoins through their cards last month. Triple the amount from a year ago. 💳
Stripe just told CoinDesk it plans to take its stablecoin card programs to more than 100 countries by the end of the year. This is the company that has issued over 400 million cards and processed hundreds of billions in card volume since 2018 — now plugging digital dollars straight into that machine.
The tech stack runs on Bridge, the stablecoin firm Stripe bought for $1.1 billion, and Stripe says it will stay coin-agnostic: many card programs already run on $USDC, but it wants to support any stablecoin on any chain.
Henri Stern, the Privy CEO Stripe acquired last year, now runs all of Stripe's crypto and stablecoin work.
The sharp take: while crypto prices argue with each other, the payments giants are quietly turning stablecoins into everyday money. That is the adoption that actually matters.
Would you pay for your groceries in stablecoins if your card did it automatically?
#Stablecoins #CryptoAdoption #Payments
People spent $1.2 billion in stablecoins through their cards last month. Triple the amount from a year ago. 💳
Stripe just told CoinDesk it plans to take its stablecoin card programs to more than 100 countries by the end of the year. This is the company that has issued over 400 million cards and processed hundreds of billions in card volume since 2018 — now plugging digital dollars straight into that machine.
The tech stack runs on Bridge, the stablecoin firm Stripe bought for $1.1 billion, and Stripe says it will stay coin-agnostic: many card programs already run on $USDC , but it wants to support any stablecoin on any chain.
Henri Stern, the Privy CEO Stripe acquired last year, now runs all of Stripe's crypto and stablecoin work.
The sharp take: while crypto prices argue with each other, the payments giants are quietly turning stablecoins into everyday money. That is the adoption that actually matters.
Would you pay for your groceries in stablecoins if your card did it automatically?
#Stablecoins #CryptoAdoption #Payments

·
--
Corporate Bitcoin Treasury Strategies Are Reaching an Inflection Point
When MicroStrategy started accumulating $BTC in 2020, most CFOs called it reckless. Today, hundreds of public companies hold Bitcoin on their balance sheets and the list is growing.
The logic is simple but powerful: cash loses purchasing power at 3-8% per year depending on your currency. Bitcoin has a mathematically fixed supply of 21 million coins. For treasury managers who have studied this asymmetry, holding zero Bitcoin is increasingly the riskier choice.
What has changed recently is the infrastructure. Bitcoin ETFs give boards a compliant, auditable vehicle without custody headaches. Options markets let treasurers write covered calls to generate yield on existing holdings. Regulated custodians provide the institutional-grade security that risk committees require.
The next wave will not be solo pioneers. It will be industries: energy companies hedging dollar exposure, tech firms parking offshore cash, sovereign wealth funds quietly diversifying reserve baskets. $ETH is following a similar path as institutions discover its dual nature: productive, yield-bearing, and deflationary.
Watch $BNB as institutional-grade staking and settlement infrastructure matures. The pattern is the same: custody first, then allocation, then integration.
Corporate treasuries do not move fast but when they move, they move in size. The accumulation phase is still early.
#Bitcoin #CryptoAdoption #InstitutionalCrypto #CorporateTreasury #BinanceSquare
16

·
--
While most traders are staring blindly at $ETH chopping around 2698, the real signal is happening away from the charts. Account abstraction adoption is quietly surging, finally fixing the onboarding friction that killed past cycles. Consumer dApps are pulling real MAW growth.
#Web3Ecosystem #CryptoAdoption #ETH
#Web3Ecosystem #CryptoAdoption #ETH
1
60
·
--
The Sovereign Reserve Asset Thesis — Why Nations Will Hold $BTC
For decades, nations stored reserves in gold and U.S. Treasuries. Bitcoin is now quietly entering that conversation — not as speculation, but as a censorship-resistant, bearer-asset alternative with a fixed 21 million supply.
Here is why the sovereign reserve narrative is gaining traction:
1. Sanctions exposure. Nations holding USD-denominated reserves can be frozen overnight. Bitcoin balances cannot be confiscated remotely. That is a structural advantage no other asset class offers.
2. Deflationary supply cap. Unlike gold, Bitcoin scarcity is mathematically enforced by protocol. No mining supercycle can dilute the cap. Sovereigns accumulating now lock in a permanent allocation at a known supply ceiling.
3. Verifiable custody. A nation can self-custody $BTC with full on-chain proof of reserves — no custodian counterparty risk, no third-party attestation required.
4. Precedent is accelerating. El Salvador was dismissed as an experiment. Now sovereign wealth discussions in the Gulf, Asia, and Latin America reference Bitcoin as a reserve diversifier alongside $ETH and $BNB for broader digital infrastructure holdings.
The long game: Bitcoin does not need to replace Treasuries. It only needs to capture 1-2% of global reserve portfolios to reprice dramatically. That reallocation has barely begun.
The strongest hands in the next cycle may not be retail — they may carry diplomatic passports.
#Bitcoin #CryptoAdoption #SovereignReserve #MacroCrypto #BinanceSquare
37
Article
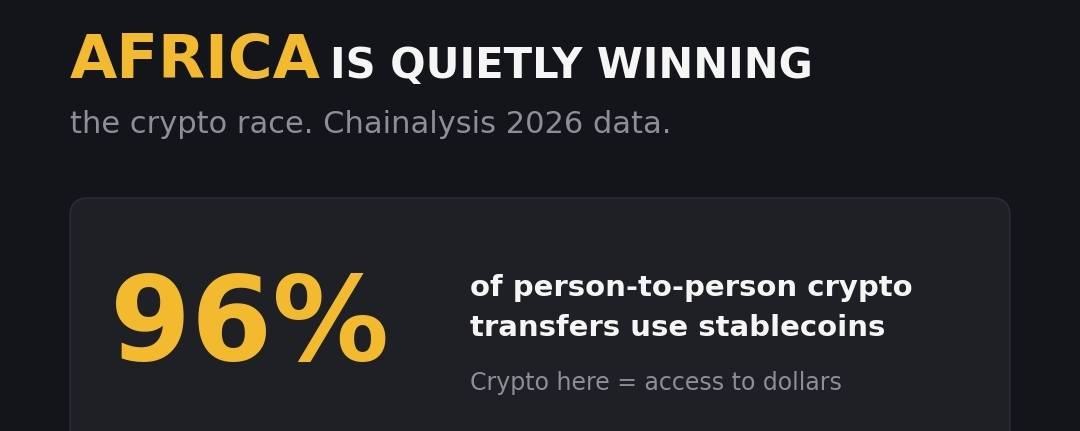
Africa is quietly winning the crypto race 🌍While much of the market struggled this year, Africa kept growing. Writing from Bujumbura 🇧🇮, here's what the data shows:
📈 Fastest growth in the world. Chainalysis's 2026 report found Sub-Saharan Africa had the fastest crypto adoption growth of any region, during one of the toughest markets since 2022.
🇳🇬 Nigeria is #1 globally for both P2P activity and cross-border crypto flows. South Africa ranks in the global top 10.
💵 It's not about speculation. Stablecoins like $USDC and USDT make up 96% of person-to-person crypto transfers. People use crypto to protect savings from inflation, send money across borders, and access dollars.
🤝 Binance is betting on Africa: exploring P2P integration and crypto education with telecom operator Africell, and working with governments across the continent.
What this means:
Western markets trade crypto. Africa uses it. When $BTC drops, people here don't stop sending money home or protecting their savings.
My view: the next wave of crypto users won't come from Wall Street. It will come from Lagos, Nairobi, Kinshasa, and Bujumbura.
Fellow Africans: what do you mainly use crypto for? Savings, sending money, or trading? 👇
#Africa #CryptoAdoption
Africa is quietly winning the crypto race 🌍
While much of the market struggled this year, Africa kept growing. Writing from Bujumbura 🇧🇮, here's what the data shows:
📈 Fastest growth in the world. Chainalysis's 2026 report found Sub-Saharan Africa had the fastest crypto adoption growth of any region, during one of the toughest markets since 2022.
🇳🇬 Nigeria is #1 globally for both P2P activity and cross-border crypto flows. South Africa ranks in the global top 10.
💵 It's not about speculation. Stablecoins like $USDC and USDT make up 96% of person-to-person crypto transfers. People use crypto to protect savings from inflation, send money across borders, and access dollars.
🤝 Binance is betting on Africa: exploring P2P integration and crypto education with telecom operator Africell, and working with governments across the continent.
What this means:
Western markets trade crypto. Africa uses it. When $BTC drops, people here don't stop sending money home or protecting their savings.
My view: the next wave of crypto users won't come from Wall Street. It will come from Lagos, Nairobi, Kinshasa, and Bujumbura.
Fellow Africans: what do you mainly use crypto for? Savings, sending money, or trading? 👇
#Africa #CryptoAdoption
10
·
--
Correspondent banking is one of the most expensive, slowest systems in global finance — yet it moves trillions of dollars every year.
A cross-border wire can take 3–5 business days, cost 25–45 USD in fees, and route through multiple intermediary banks. The real hidden cost is even larger: pre-funded nostro accounts sitting idle in dozens of currencies just to keep the rails alive. The IMF estimates 27 trillion USD in nostro capital is locked globally at any given time. That is an enormous inefficiency waiting to be displaced.
This is the specific problem $XRP and Ripple's network were built to solve. Instead of locking up capital in nostro accounts, a financial institution can source on-demand liquidity, bridge the transaction in seconds, and settle — no pre-positioned capital required.
What makes institutional adoption realistic now is regulatory clarity. Ripple's legal resolution with the SEC removed the primary compliance blocker keeping banks on the sidelines. The post-settlement environment is structurally different from two years ago.
$BTC proved borderless value transfer works. $ETH proved smart contract settlement is programmable. $XRP's thesis is narrower: make the existing correspondent banking infrastructure 60–80% cheaper to run.
Narrower institutional theses with clear counterparties tend to close faster than broad platform bets. Watch actual corridor volumes, not just partnership announcements.
#CrossBorderPayments #CryptoAdoption #RippleEffect #Blockchain
Correspondent banking is one of the most expensive, slowest systems in global finance — yet it moves trillions of dollars every year.
A cross-border wire can take 3–5 business days, cost 25–45 USD in fees, and route through multiple intermediary banks. The real hidden cost is even larger: pre-funded nostro accounts sitting idle in dozens of currencies just to keep the rails alive. The IMF estimates 27 trillion USD in nostro capital is locked globally at any given time. That is an enormous inefficiency waiting to be displaced.
This is the specific problem $XRP and Ripple's network were built to solve. Instead of locking up capital in nostro accounts, a financial institution can source on-demand liquidity, bridge the transaction in seconds, and settle — no pre-positioned capital required.
What makes institutional adoption realistic now is regulatory clarity. Ripple's legal resolution with the SEC removed the primary compliance blocker keeping banks on the sidelines. The post-settlement environment is structurally different from two years ago.
$BTC proved borderless value transfer works. $ETH proved smart contract settlement is programmable. $XRP 's thesis is narrower: make the existing correspondent banking infrastructure 60–80% cheaper to run.
Narrower institutional theses with clear counterparties tend to close faster than broad platform bets. Watch actual corridor volumes, not just partnership announcements.
#CrossBorderPayments #CryptoAdoption #RippleEffect #Blockchain
110
·
--
🚨 Crypto Adoption Is Entering a New Phase
The crypto industry is shifting from building blockchain technology to driving real-world adoption. Companies like Coinbase and WisdomTree are focusing on making crypto products easier, more useful, and accessible, while investors like Kevin O’Leary argue that blockchain networks need to prove real customers, deals, and usage — not just tests. 🔥
#Crypto #Bitcoin #Web3 #ETH #CryptoAdoption
76
·
--
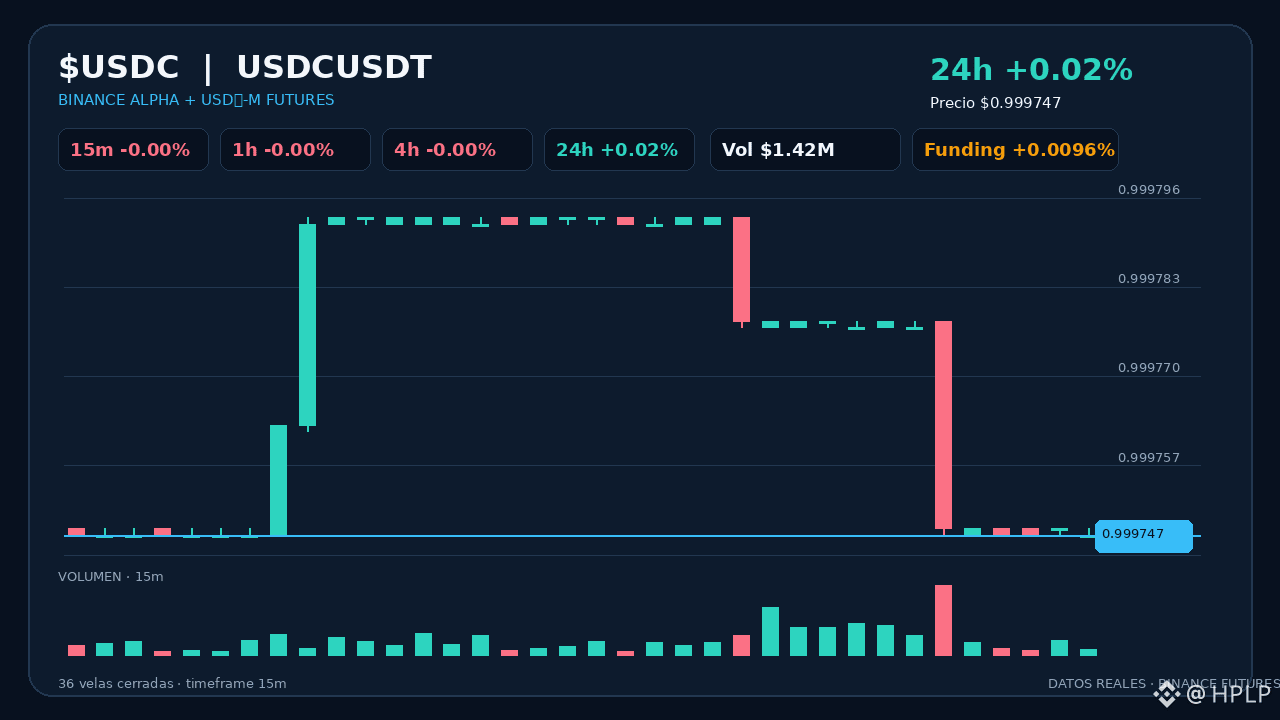
Stripe is accelerating the global adoption of cryptocurrencies by announcing the expansion of its stablecoin cards to more than 100 countries by the end of the year. 🌍
This move reduces long-standing friction between traditional payment rails and on-chain liquidity, making it easier to use digital assets every day at scale.
Why does it matter? Global interoperability boosts the real-world utility of stablecoins beyond exchanges, integrating them into international commerce.
Keep a close eye on how transaction volumes on key networks respond, as well as local regulatory reactions in emerging markets. 📊
#Stablecoins #CryptoAdoption #PagosDigitales $USDC $USDT
6
·
--
Bitcoin as collateral is one of the most underappreciated structural shifts happening in finance right now.
For most of its history, $BTC was seen as a speculative asset — something you buy and hold hoping for price appreciation. That narrative is quietly being replaced by something more powerful: Bitcoin as productive collateral.
Here is how the shift is playing out. Corporations are holding BTC on their balance sheets and using it as collateral for operating credit lines rather than selling to raise cash. Prime brokers are now offering BTC-backed loans to institutional clients at rates that rival traditional securities lending. Sovereign wealth funds exploring crypto exposure are more interested in collateral utility than speculative returns.
This matters structurally because collateral demand creates a different category of buyer. A speculative buyer sells when sentiment turns. A collateral user holds — because liquidating the collateral defeats the purpose of the credit facility. This creates a stickier bid beneath the market.
$ETH is following a parallel path through restaking, where staked ETH becomes collateral for security provisioning across multiple protocols. $BNB plays a similar role within the BNB Chain ecosystem, enabling DeFi credit facilities without requiring asset liquidation.
The long-term implication: as major crypto assets deepen their roles in credit markets, volatility structurally compresses over multi-year cycles — not because of less interest, but because of more sophisticated, longer-duration holders.
The asset class is growing up. Watch the collateral layer, not just the price.
#Bitcoin #CryptoAdoption #DeFi #CryptoInvesting #BlockchainFinance
39

🚨 MAJOR REAL-WORLD LIQUIDITY INTEGRATION BRINGS $USDT PAYMENTS TO MILLIONS OF JAPANESE MERCHANTS! ⚡
A top-tier exchange payment network is connecting directly into Japan's massive PayPay system via the HIVEX interoperability framework. 🌊 International visitors can now spend $USDT across millions of retail locations, vending machines, taxis, and public transit without individual merchant onboarding.
💡 Seamless off-ramping into local merchant JPY settlement represents a major institutional leap forward for real-world crypto utility. 📊 Expanding friction-free transactional velocity across international corridors builds sustained structural demand for stablecoins.
💬 Do you see direct real-world payment rails as the primary driver for stablecoin velocity moving forward? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #USDT #CryptoAdoption #Web3Payments #Stablecoins
⚡ 💎
10

·
--
$BTC - The adoption conversation has moved past "should we own it" to "how do we finance and deploy it."
A new research note highlights institutions now treating bitcoin as a financing foundation rather than just a treasury asset.
The shift spans custody, lending, and collateral frameworks being built by major players.
What comes next depends on how quickly these structures scale and whether regulators engage constructively.
#CryptoAdoption #Adoption
110
·
--
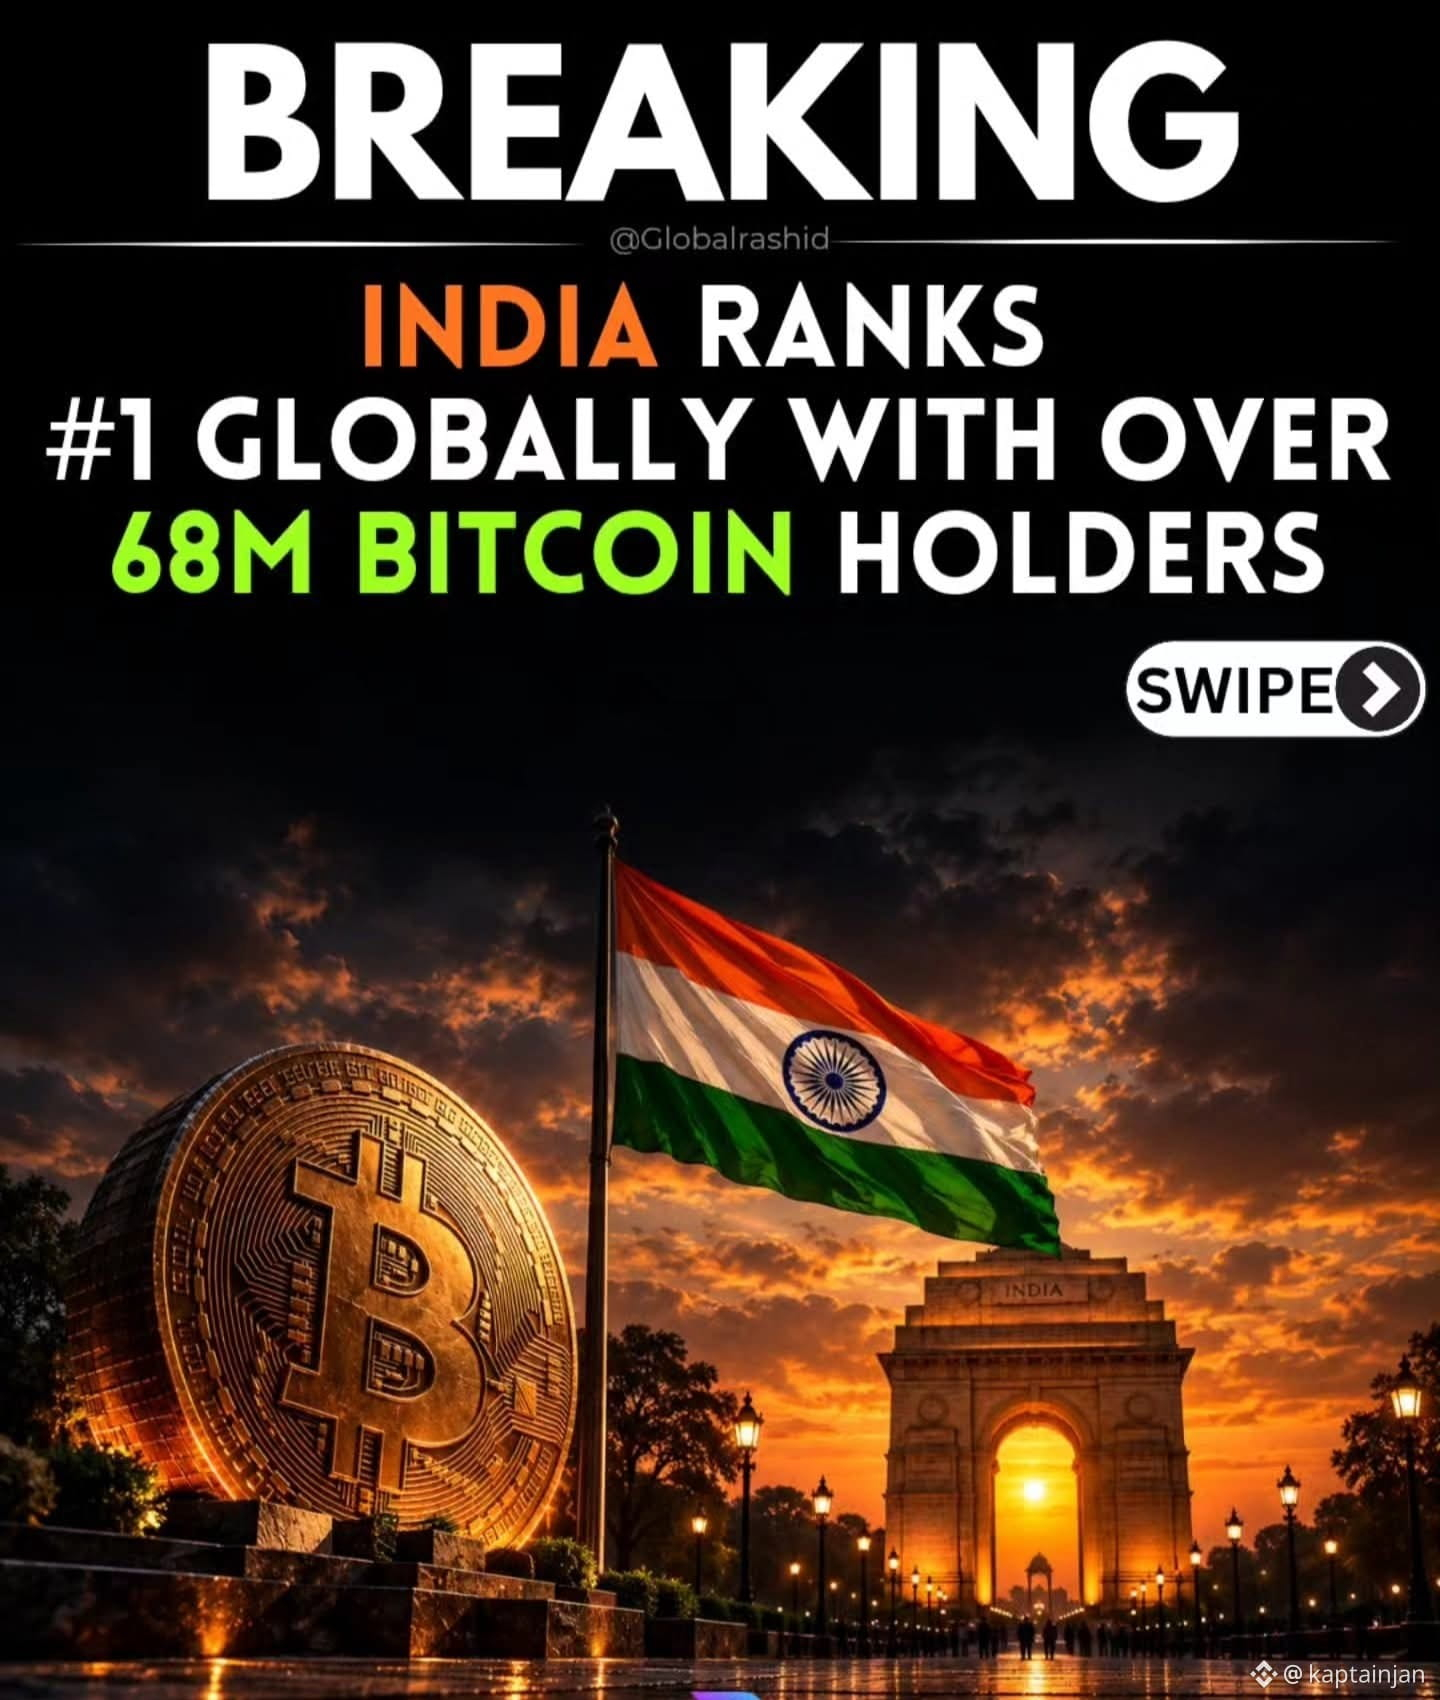
🇮🇳 INDIA RANKS #1 GLOBALLY IN BITCOIN HOLDERS! 🚀
The crypto landscape is evolving faster than ever, and India has officially taken the top spot worldwide, boasting an estimated 68+ million Bitcoin holders!
Even with regulatory curves and economic shifts, the massive surge in digital adoption proves that millions of Indians are looking toward future finance, blockchain innovation, and decentralized assets.
📊 Quick Insights:
Global Rank: #1 by total number of estimated holders
Adoption Drive: Driven by digital payment familiarity and a young, tech-savvy population.
The Shift: Moving rapidly from traditional savings into digital-first economies.
👇 What are your thoughts on this massive milestone? Are you bullish on India's crypto future? Let us know in the comments!
(⚠️ Disclaimer: This post is for informational and educational purposes only and does not constitute financial or investment advice.)
#CryptoAdoption #bitcoin
266

If you're still ignoring enterprise settlement rails to chase speculative memecoins, stop now.
Most retail traders miss the biggest macro moves simply because real institutional adoption happens quietly behind closed doors, leaving them buying the top after the real momentum is already underway.
On September 24, The Clearing House selected Quant to power its new On-Chain Money Initiative. While the market was distracted arguing over short-term charts, one of the most critical payment backbones in the United States quietly locked in $QNT as its primary technology provider.
We saw a similar narrative play out during previous cycles when enterprise pilots pushed networks like $LINK and $XRP into massive structural moves. When traditional financial infrastructure actually integrates decentralized rails rather than just floating vaporware, the resulting liquidity shift tends to catch late rotators completely off guard.
Do you think enterprise-backed settlement rails will outperform retail hype coins as institutional money goes fully live on-chain?
#Quant #CryptoAdoption #RWA
182

·
--
🚨 REVOLUT WINS ARGENTINA BANK APPROVAL TO FUEL LATIN AMERICAN $BTC ADOPTION! 🏦
Institutional fintech appetite across Latin America is reaching fever pitch. 🌐 Revolut just secured approval from Argentina's Central Bank to acquire Banco Cetelem, positioning itself directly in a market with over 150,000 eager waitlist users.
With active banking infrastructure already expanding across Mexico, Brazil, and Colombia, smart money sees the long-term rails being laid for massive retail crypto onboarding. 📊 High-inflation economies are rapidly turning toward digital assets, and early infrastructure builders will capture the bulk of this structural liquidity. 🏦
💬 Will Latin America become the dominant region driving the next global crypto adoption wave? 👇
⚠️ Not financial advice. Always manage your risk. 🛡️
🏷️ #BTC #CryptoAdoption #Fintech #LatinAmerica #Crypto
🔥 💎
28
If you're still measuring real crypto adoption solely by centralized exchange volume, stop now.
Most investors track order books and derivative stats, only to get completely caught off guard when market liquidity vanishes during sudden macro shifts. Relying strictly on platform metrics makes you completely blind to where sticky, real-world capital is actually moving.
There is a running debate over whether institutional infrastructure or grassroots utility drives long-term value. Traditional finance argues that institutional custodial inflows are the only numbers that move the needle for $BTC. Yet in developing economies across Latin America, Africa, and Southeast Asia, millions of people bypass corporate platforms entirely, using $USDT and Bitcoin directly between private wallets for daily trade and capital protection.
While Wall Street controls speculative price swings, direct peer-to-peer settlement builds an unbreakable structural foundation. Speculators trade paper volume back and forth, but everyday users transacting outside platform walls create the genuine liquidity floor that survives every bear market.
Do you think institutional trading or grassroots peer-to-peer usage will drive the next phase of adoption?
#Bitcoin #CryptoAdoption #P2P
If you're still measuring real crypto adoption solely by centralized exchange volume, stop now.
Most investors track order books and derivative stats, only to get completely caught off guard when market liquidity vanishes during sudden macro shifts. Relying strictly on platform metrics makes you completely blind to where sticky, real-world capital is actually moving.
There is a running debate over whether institutional infrastructure or grassroots utility drives long-term value. Traditional finance argues that institutional custodial inflows are the only numbers that move the needle for $BTC . Yet in developing economies across Latin America, Africa, and Southeast Asia, millions of people bypass corporate platforms entirely, using $USDT and Bitcoin directly between private wallets for daily trade and capital protection.
While Wall Street controls speculative price swings, direct peer-to-peer settlement builds an unbreakable structural foundation. Speculators trade paper volume back and forth, but everyday users transacting outside platform walls create the genuine liquidity floor that survives every bear market.
Do you think institutional trading or grassroots peer-to-peer usage will drive the next phase of adoption?
#Bitcoin #CryptoAdoption #P2P
175

·
--
Picture this: you walk into a neighborhood bakery in Buenos Aires or a small electronics shop in Lagos, pay directly from your self-custody wallet, and walk out without a single bank or centralized intermediary touching the transaction.
Most traders get so obsessed with watching exchange order books and hunting quick flips that they completely miss the real structural adoption happening quietly on the ground. When local currencies collapse, holding paper cash or leaving funds trapped behind restrictive banking rails is a fast track to watching your purchasing power evaporate.
Back in 2021, when El Salvador made $BTC legal tender, the world expected adoption to flow top-down through official state apps and corporate infrastructure. Instead, real peer-to-peer usage mirrored what we saw during early local adoption cycles in places like Argentina and Nigeria, where daily volume thrives on decentralized handshake deals rather than custodial exchanges. People in high-inflation economies turned to Bitcoin and dollar-pegged assets like $USDT not for speculative 10x gains, but as practical lifelines for basic commerce and remittance settlement.
While market participants argue over ETF inflows and liquidations on the charts, grassroots users are proving that permissionless settlement matters most when traditional systems fail.
Where do you think real-world adoption will break out next?
#Bitcoin #P2P #CryptoAdoption
132

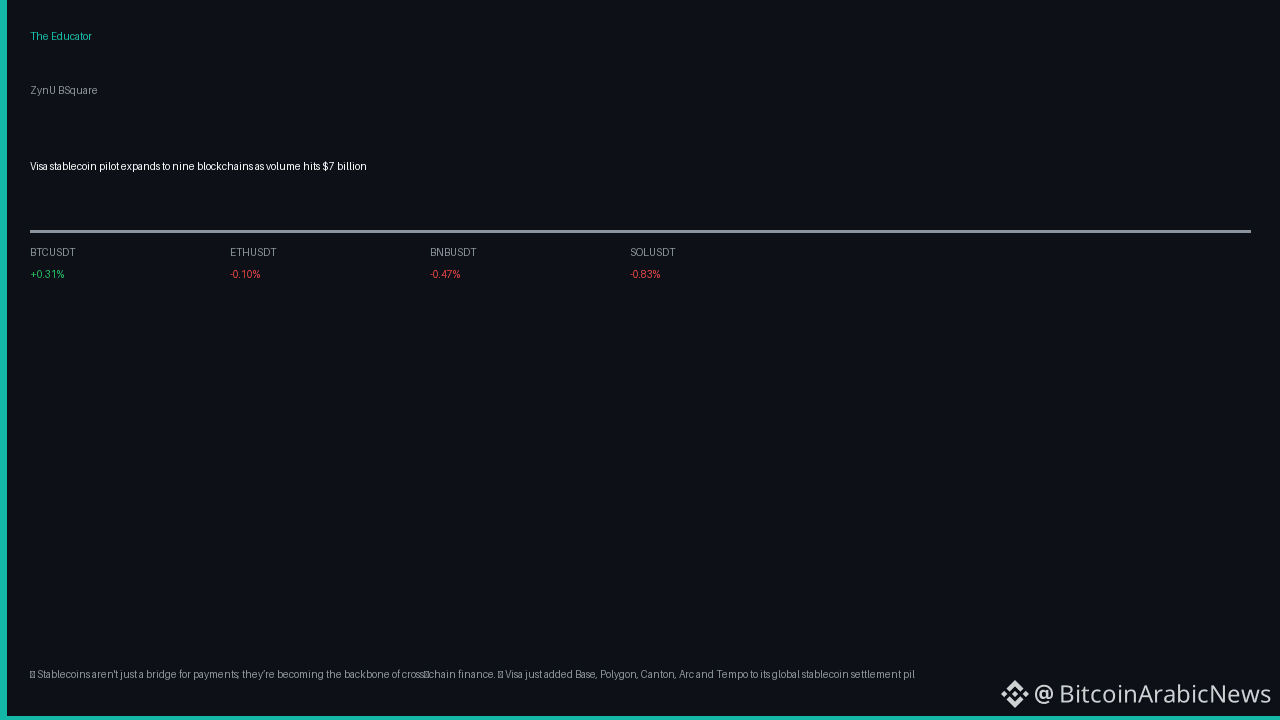
🔥 Stablecoins aren't just a bridge for payments; they’re becoming the backbone of cross‑chain finance.
📊 Visa just added Base, Polygon, Canton, Arc and Tempo to its global stablecoin settlement pilot, pushing the network to nine blockchains and driving the annualized run‑rate to $7 billion – a 50% jump from the previous quarter. #Visa #Stablecoin
💡 This expansion signals that institutional money is finally treating on‑chain liquidity as a core asset class, reinforcing the long‑term #CryptoAdoption narrative as we move deeper into the late‑stage bull cycle where cross‑chain settlement efficiency fuels price discovery. BTC trades at $84,342 (RSI 53) and ETH at $2,691 (RSI 51) while SOL spikes to $121 (RSI 62)
13
Why is nobody talking about how traditional banking giants are quietly building real-world crypto rails while retail investors keep chasing vaporware?
Most market participants lose capital getting caught up in endless narrative rotations and memecoin pumps, completely missing the actual institutional infrastructure shifts happening right in front of them. When mainstream headlines still preach retail caution, the real capital is already setting up operational settlement networks.
Look at Russia right now. While the central bank designs a strict 1% risk-exposure ceiling to keep lenders safe, Sberbank has already launched live crypto-based cross-border settlement for corporate clients. Major financial institutions are not waiting for global regulatory clarity to move value through networks like $BTC and settlement assets like $USDT. They are hedging legacy payment friction with on-chain liquidity because global trade demands speed that traditional wire systems cannot deliver anymore.
When state-backed banking leaders integrate digital asset settlements directly into commercial trade, the macro adoption timeline accelerates faster than most realize.
Where do you think corporate cross-border settlement goes from here?
#CryptoAdoption #CrossBorderPayments #Banking
20
·
--
Institutional rails are expanding as the number of banking services customers grows to 18 million—$BTC customers gain direct access. 🚀
Raiffeisen Bank is directly integrating Bitpanda’s digital asset infrastructure into its European network, opening the door to 18 million banking customers. 📊 While the rollout happens gradually across each market within local regulatory frameworks, the implication for the overall economy is enormous.
Liquidity channels are shifting from independent trading platforms to traditional banking apps. 💡 When individual venture capital is no longer facing friction to allocate it to $BTC , structural demands quietly form ahead of the next big wave.
That’s how long-term adoption accumulates in stealth. 💬 Will the integration of traditional banks drive the next wave of individual investors, or will users stay as they are? 👇
⚠️ Not financial advice. Always manage your risk wisely. 🛡️
🏷️ #BTC #Bitcoin #CryptoAdoption #Macro
🔥 💎
1
139

Verified
STABLECOIN PAYMENTS ARE GAINING SERIOUS INSTITUTIONAL BACKING AGAIN.
Singapore-based payments provider dtcpay just secured $25 million in its Series A funding round, with major support from Japanese financial giant SBI Group. This capital boost will be used to expand its product offerings and upgrade enterprise client infrastructure for seamless crypto transactions.
⚡ SBI Group leads the $25M round to accelerate global crypto payment solutions
⚡ The expansion focuses on scaling merchant networks and enterprise portals
⚡ Focus remains heavily on fiat to stablecoin rails like $USDT and USDC for real-world usage
Traditional finance giants backing stablecoin infrastructure is the clearest bullish sign for adoption we could ask for.
#Stablecoins #CryptoAdoption #Write2Earn #Fintech
2
1.3k
Log in to explore more content
Join global crypto users on Binance Square
⚡️ Get latest and useful information about crypto.
💬 Trusted by the world’s largest crypto exchange.
👍 Discover real insights from verified creators.
Email / Phone number
Trending Topics
1
#FedMinutesFocusOnOctoberPause
165,868 views
1,304 Discussing
2
#BinanceLaunchesBinanceIntelligence
1.1M views
6,504 Discussing
3
#EvernorthDelaysNasdaqDebutToOct12
13,672 views
299 Discussing
4
#RobinhoodAdds$25MInBitcoinToBalanceSheet
3,329 views
73 Discussing
5
#SP500AndNasdaqHitRecordHighs
20,863 views
475 Discussing
6
#USMortgageRatesRiseTo7.49%
25,188 views
386 Discussing
7
#BTCFallsBelow$84K
126,787 views
235 Discussing
8
#DubaiVARAIssuesReserveAssetAuditCircular
46,413 views
953 Discussing
9
#SECApproves3XBitcoinETF
43,869 views
772 Discussing
10
#WinklevossFilesSpotZcashETFApplication
51,734 views
877 Discussing